
 Peak Flow Meters Market | 2026-2036
Peak Flow Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Peak Flow Meters Market Analysis
Homecare patients are rotating toward digital peak flow meters with Bluetooth connectivity, displacing traditional clinic-dependent testing. Omron Healthcare leverages its consumer health electronics heritage to dominate retail pharmacy channels across Asia. Vyaire Medical anchors hospital procurement through integrated respiratory diagnostics portfolios. Microlife competes on price in European homecare segments with mechanical device lines.
Peak flow meters are handheld devices that measure maximum expiratory flow rate, typically calibrated in liters per minute with accuracy tolerances of ±10 percent or ±20 L/min, and serve to monitor airway obstruction in asthma and chronic obstructive pulmonary disease. Digital products with electronic pressure sensors command premium placement as clinicians prioritize data logging and smartphone integration for remote patient monitoring. Mechanical analog variants retain volume in emerging markets where cost sensitivity and battery independence outweigh connectivity demands. Portable formats are displacing desktop units in ambulatory settings as point-of-care testing expands beyond traditional pulmonary function laboratories.
FDA 510(k) premarket notification requirements shape device design cycles and predicate selection strategies for US market entrants, while EU MDR technical documentation demands are extending conformity assessment timelines for European distribution. ISO 26782 standards for spirometry and peak expiratory flow measurement establish international performance benchmarks that manufacturers must validate through clinical testing. Stakeholders must weigh regulatory capital requirements against the margin compression from commoditized mechanical segments when allocating R&D budgets between connected and conventional product architectures.
Market Dynamics
Digital connectivity is fragmenting the peak flow meter value chain, separating hardware manufacturing from data platform ownership and forcing incumbents to choose between device margins and recurring software revenue.
Growth Catalysts
- Homecare Self-Monitoring:Patients with asthma and COPD are adopting Bluetooth-enabled peak flow meters for daily lung function tracking, reducing emergency department visits and enabling proactive medication adjustments.
- FDA 510(k) Pathway Clarity:The US regulator's predicate device framework accelerates clearance timelines for electronic peak flow meters that demonstrate substantial equivalence to established reference products.
- Aging Demographics:Japan, Germany, and the United States exhibit elevated diagnostic rates for chronic respiratory conditions, sustaining procurement volumes across hospital and retail pharmacy channels.
Market Restraints
- EU MDR Compliance Burden:The European Union's Medical Device Regulation extends technical documentation requirements and conformity assessment timelines, elevating capital requirements for market access.
- Mechanical Device Commoditization:Analog peak flow meters face margin compression as manufacturing concentrates in low-cost production clusters, limiting R&D recovery for conventional product lines.
- Sensor Component Concentration:Electronic pressure sensors for digital meters depend on specialized semiconductor foundries concentrated in East Asia, creating supply vulnerability during capacity constraints.
Strategic Opportunities
- Remote Patient Monitoring Integration:Telehealth platforms are incorporating peak flow data streams into chronic disease management workflows, creating subscription revenue potential beyond device sales.
- Underserved Rural Populations:India's tier-2 and tier-3 cities present expansion potential for portable, battery-independent mechanical devices distributed through pharmacy networks.
- ISO 26782 Certification Premium:Manufacturers validating performance against international spirometry standards command preferential placement in institutional procurement tenders across multiple geographies.
Industry Challenges
- Firmware Validation Complexity:Digital peak flow meters require extensive software verification under FDA guidance documents, extending development cycles and elevating quality assurance headcount.
- Interoperability Fragmentation:Proprietary data formats between competing smartphone applications complicate integration with electronic health record systems, frustrating clinician adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peak Flow Meters Market |
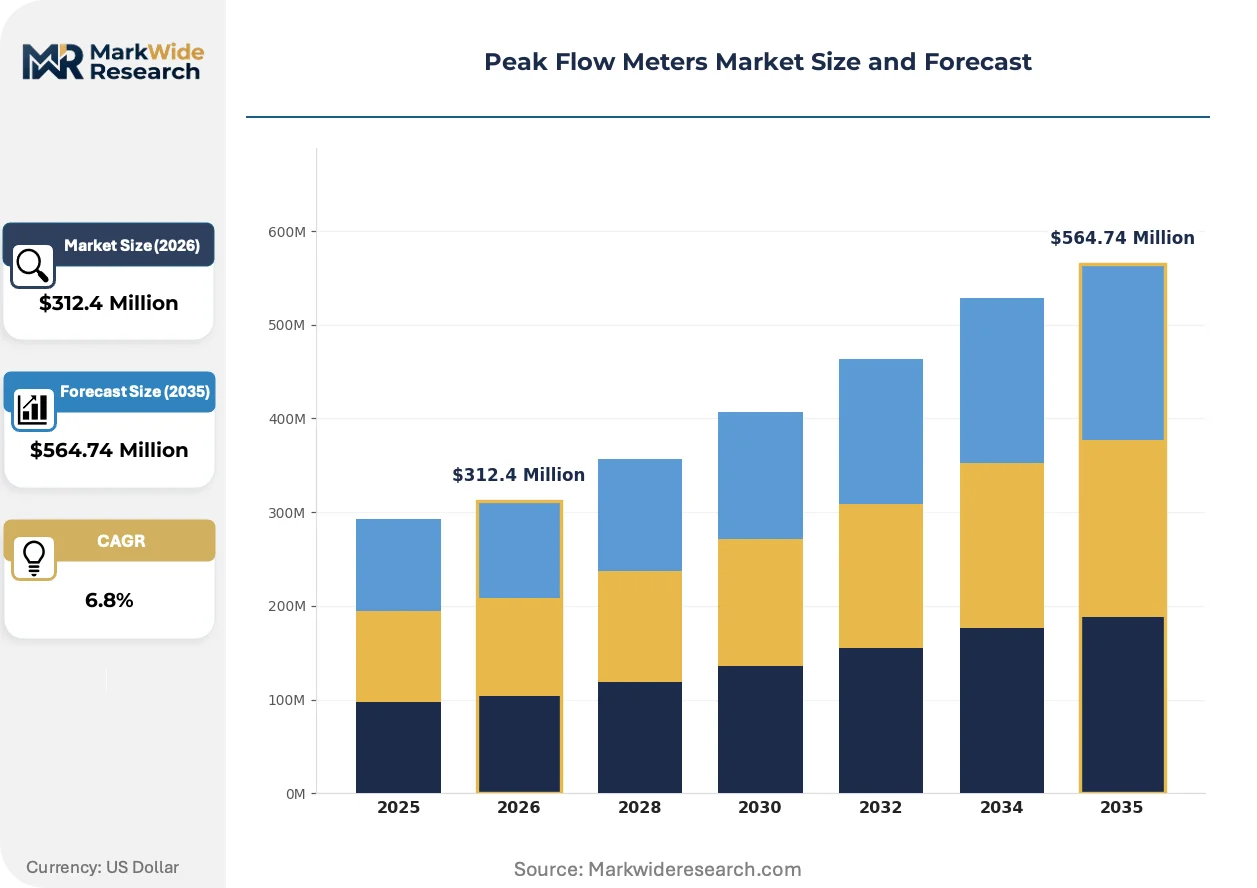
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Analog, Portable, Desktop End User: Hospitals, Clinics, Homecare, Laboratories Technology: Ultrasonic, Mechanical, Electronic, Pressure Sensor Application: Respiratory Monitoring, Asthma Management, Clinical Trials, Research Studies |
| Companies Covered | Vyaire Medical, Microlife, Omron Healthcare, Vitalograph, Trudell Medical International, DeVilbiss Healthcare, Rossmax International, GaleMed Corporation, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peak Flow Meters Market Emerging Trajectories
Connectivity architectures are restructuring how respiratory data flows from patient to provider, separating measurement hardware from analytics platforms and enabling new service-based revenue models.
MEMS pressure sensors are decomposing the traditional peak flow meter into modular components. Homecare patients and clinical trial sponsors are adopting these miniaturized elements for continuous monitoring applications. The technology is decomposing device margins into separate hardware, connectivity, and data licensing revenue streams.
EU MDR technical documentation requirements are reshaping European market entry strategies. Manufacturers must now compile clinical evaluation reports and post-market surveillance systems that satisfy notified body scrutiny. Digital peak flow meter submissions face extended review timelines as regulators assess software lifecycle processes alongside hardware safety.
Hospital procurement departments are unbundling diagnostic device purchases from service contracts. Pulmonary function laboratories now source peak flow meters through group purchasing organizations while negotiating software subscriptions separately. This bifurcation is most pronounced in United States health systems consolidating vendor relationships under value-based care frameworks.
Peak Flow Meters Market Segmentation
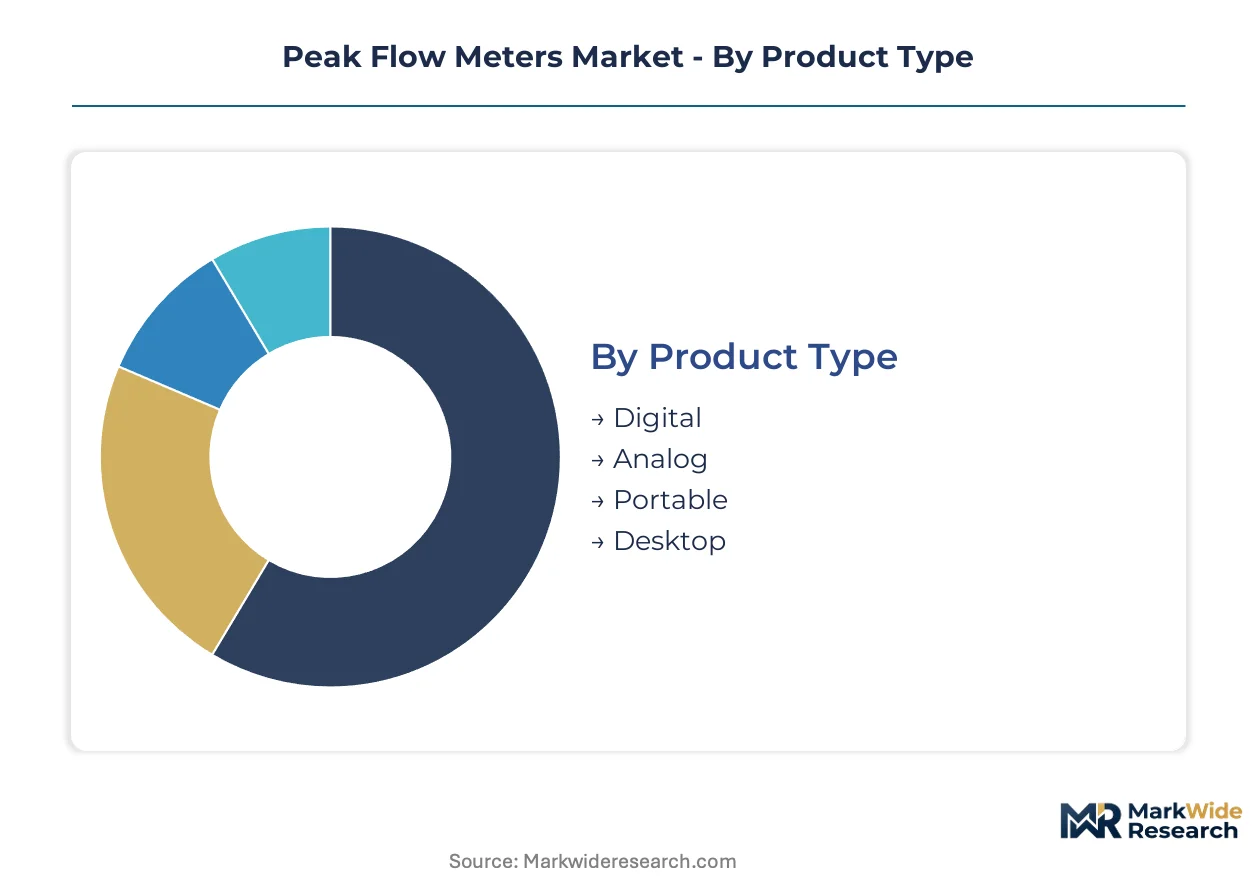
Segmentation in peak flow meters reveals how substitution pressures reshape procurement patterns across healthcare settings. Device categories face divergent fates as digital connectivity displaces analog formats in premium channels while mechanical durability sustains volume in cost-constrained environments.
Product Type:
Digital variants confront the stiffest substitution threat from smartphone-integrated spirometry apps, forcing hardware manufacturers to differentiate through clinical-grade accuracy certifications.
- Digital:Electronic pressure sensors with Bluetooth connectivity enable real-time data transmission to telehealth platforms. Demand concentrates in United States homecare settings where remote patient monitoring reimbursement codes incentivize connected device procurement.
- Analog:Spring-loaded mechanical mechanisms deliver readings without battery dependence. Volume persists in India's tier-2 pharmacy networks where cost sensitivity and infrastructure gaps limit electronic adoption.
- Portable:Handheld form factors prioritize field deployability for asthma patients and traveling clinicians. Compact designs sacrifice some accuracy tolerance for convenience in ambulatory monitoring scenarios.
- Desktop:Stationary units with enhanced stability and precision serve pulmonary function laboratories requiring consistent calibration standards for longitudinal patient tracking.
Digital formats retain volume leadership in institutional procurement; portable configurations hold the steepest expansion curve as point-of-care testing decentralizes beyond hospital walls.
End User:
Cost tier stratification separates capital-intensive hospital installations from recurring homecare purchases, with reimbursement policy acting as the primary allocation mechanism.
- Hospitals:Integrated respiratory diagnostics suites demand ISO 26782-certified devices with electronic health record interoperability. Procurement flows through group purchasing organizations consolidating vendor relationships under value-based care frameworks.
- Homecare:Direct-to-patient distribution channels bypass institutional procurement bottlenecks. Bluetooth-enabled meters dominate United States retail pharmacy shelves as asthma self-management protocols expand insurance coverage for connected monitoring tools.
- Clinics:Intermediate care settings balance accuracy requirements against capital constraints, often selecting mid-tier electronic units with basic data logging capabilities.
- Laboratories:Research-grade calibration and audit trails predominate in clinical trial environments where regulatory documentation requirements exceed standard clinical specifications.
Homecare channels are expanding most quickly as reimbursement shifts toward preventive monitoring; hospitals maintain the highest average transaction values per installation.
Technology:
Supply concentration in East Asian semiconductor foundries creates vulnerability for electronic sensor architectures, elevating the strategic value of mechanical redundancy.
- Electronic:Solid-state pressure transducers convert airflow into digital signals with programmable sampling rates. FDA 510(k) predicate pathways accelerate clearance for devices demonstrating substantial equivalence to established reference products.
- Pressure Sensor:MEMS-based miniaturization enables modular component architectures separating measurement hardware from analytics platforms. Foundry capacity constraints in Taiwan and South Korea periodically disrupt delivery schedules for specialized semiconductor components.
- Ultrasonic:Non-contact flow measurement eliminates moving parts and reduces calibration drift. Niche adoption in research settings where particulate contamination risks compromise mechanical sensor accuracy.
- Mechanical:Proven durability and battery independence sustain deployment in resource-limited settings. Margin compression concentrates manufacturing in low-cost production clusters with limited R&D recovery potential.
Electronic platforms command premium placement in institutional tenders; pressure sensor configurations are gaining share fastest as telehealth integration demands expand.
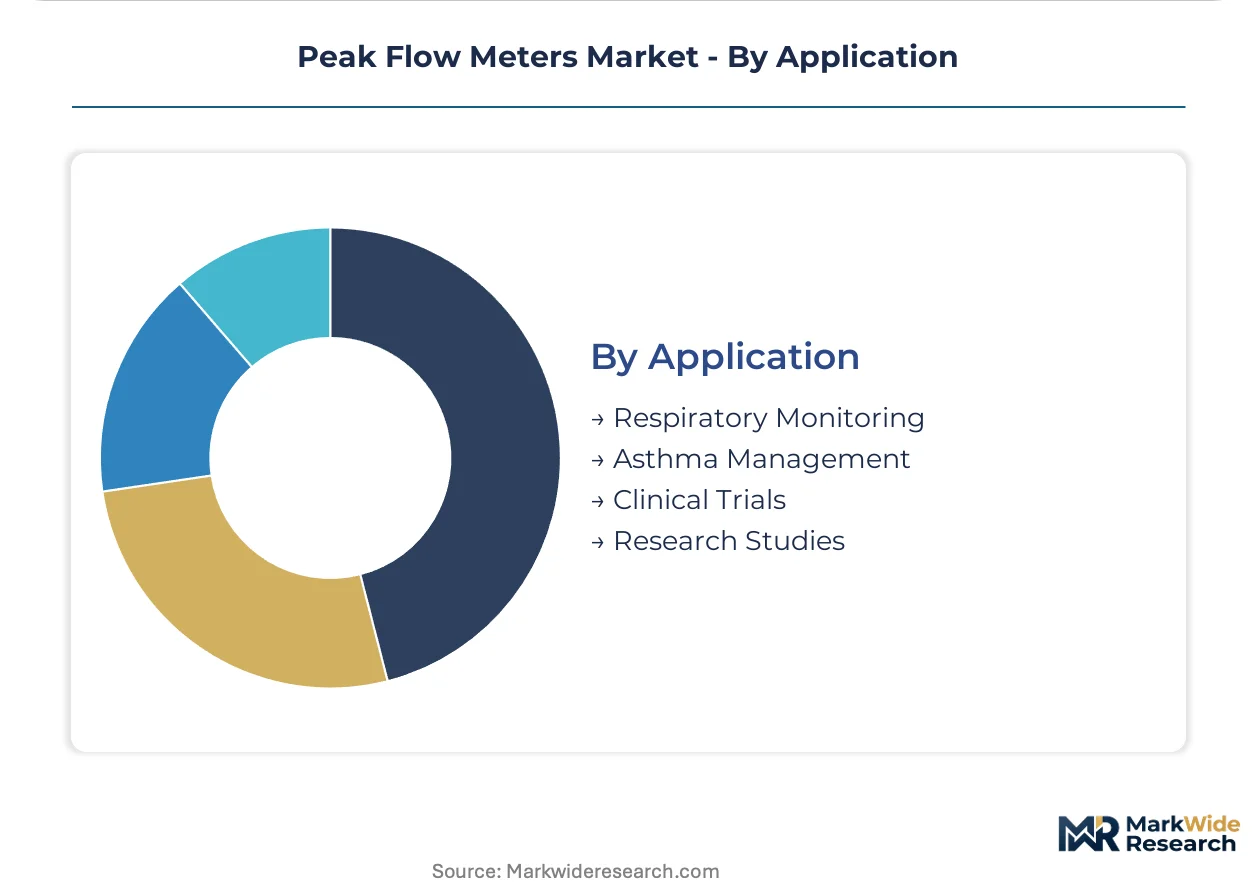
Application:
Maturity differentiation separates established therapeutic monitoring from emerging research instrumentation, with regulatory validation requirements determining market entry barriers.
- Asthma Management:Daily peak expiratory flow tracking enables proactive medication adjustment and exacerbation prevention. Patient adherence programs in Germany and Japan drive replacement cycles for home-use devices.
- Respiratory Monitoring:Broad-spectrum COPD and post-surgical surveillance applications span acute and chronic care settings. Reimbursement codes in the United States increasingly cover remote monitoring for chronic respiratory conditions.
- Clinical Trials:Regulatory-grade documentation and audit trails satisfy FDA and EMA data integrity requirements for pharmaceutical development programs. Device validation protocols exceed standard clinical specifications.
- Research Studies:Academic and epidemiological investigations prioritize cost efficiency and standardization across multi-site data collection networks.
Asthma management retains the largest installed base; clinical trial instrumentation carries the steepest expansion trajectory as respiratory drug pipelines accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision respiratory diagnostics to United States hospital systems, while Japanese electronics producers supply sensor components to digital meter assemblers across Asia-Pacific homecare channels.
United States
CMS reimbursement codes for remote patient monitoring accelerate Bluetooth-enabled meter adoption among Medicare-enrolled COPD patients. FDA 510(k) predicate pathways compress clearance timelines for electronic devices demonstrating substantial equivalence. Minneapolis-St. Paul hosts respiratory device development clusters serving group purchasing organizations consolidating hospital procurement.
Germany
DiagnostikNetz-BB federated research networks generate clinical evidence supporting peak flow meter integration into chronic disease management protocols. BfArM post-market surveillance requirements elevate documentation burdens for digital health devices entering German distribution. Berlin-Brandenburg medical technology clusters specialize in ISO 26782-compliant calibration systems for clinical trial instrumentation.
Japan
PMDA streamlined review pathways for designated medical devices accelerate market entry for smartphone-connected respiratory monitors. METI healthcare technology export promotion programs support domestic manufacturers expanding into Southeast Asian pharmacy retail. Osaka-Kobe industrial corridors concentrate MEMS pressure sensor fabrication for miniaturized flow measurement components.
India
CDSCO medical device rules mandate registration for all peak flow meters regardless of risk classification, extending import timelines for foreign manufacturers. Ayushman Bharat health insurance expansion creates reimbursement infrastructure for asthma diagnostic tools in tier-2 cities. Gujarat pharmaceutical manufacturing zones incubate low-cost mechanical device production for domestic pharmacy distribution.
United Kingdom
NHS Long Term Plan respiratory disease commitments sustain procurement volumes for home-use monitoring devices across integrated care systems. MHRA post-EU MDR transition maintains stringent conformity assessment requirements for electronic health devices. Cambridge-Oxford-London life science corridor concentrates digital health startups developing AI-enhanced spirometry analytics platforms.
Peak Flow Meters Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and regulatory sophistication dimensions. The vendor base stratifies into three tiers: diversified medical technology conglomerates with respiratory portfolios, dedicated respiratory device specialists, and regional mechanical device fabricators. Strategic archetypes include telehealth-integrated platform builders, cost-optimized emerging market suppliers, and clinical-grade calibration specialists. Competitive moves concentrate on M&A for digital health capabilities and strategic partnerships with telemedicine platforms.
Among diversified health technology conglomerates, Koninklijke Philips occupies a position exemplifying integrated respiratory diagnostics portfolios spanning hospital and homecare channels. Omron Healthcare represents the consumer health electronics archetype leveraging retail pharmacy distribution density across Asia-Pacific markets. Vyaire Medical anchors the dedicated respiratory specialist tier with positioning reflecting pure-play focus on pulmonary function measurement systems.
| Leading Market Players |
|---|
| Vyaire Medical |
| Microlife |
| Omron Healthcare |
| Vitalograph |
| Trudell Medical International |
| DeVilbiss Healthcare |
| Rossmax International |
| GaleMed Corporation |
| Koninklijke Philips |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day semiconductor lead times for MEMS pressure sensors concentrate pricing power with Taiwanese and South Korean foundries, while mechanical device assemblers in India and China respond with stripped-down BOM strategies that compress margins across analog product tiers.
Pricing Analysis
Digital-to-analog pricing gaps of three-to-five times separate Bluetooth-enabled meters from spring-loaded mechanical units. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification status, ISO 26782 compliance grade, and bundled software subscription terms. Cost compression in mechanical segments is intensifying because Indian and Chinese manufacturers are scaling pharmacy-direct distribution. Homecare patients in tier-2 Indian cities exhibit the highest price sensitivity; United States hospital systems purchasing through group purchasing organizations show the lowest.
Supply Chain Analysis
Taiwan Strait shipping lanes anchor global MEMS sensor supply for digital peak flow meters, creating vulnerability during geopolitical friction or foundry capacity crunches. Component sourcing draws from Taiwan and South Korea for pressure transducers, Japan for precision plastics, and India for mechanical springs and molded housings. Single-source vulnerability concentrates in 200-millimeter wafer capacity for specialized biomedical sensors. Distribution runs through hospital group purchasing organizations in the United States, pharmacy retail chains in Germany and Japan, and direct-to-patient e-commerce in India's urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peak flow meters sit in early-cycle expansion as remote patient monitoring reimbursement codes in the United States and Germany unlock homecare adoption beyond traditional clinical settings.
For Market Incumbents: Compound data platform ownership advantages by integrating Bluetooth meters with telehealth subscription services before smartphone spirometry apps achieve clinical-grade accuracy certification. Defend against MEMS foundry concentration risk by qualifying secondary sensor suppliers in Japan. Secure backward integration into pressure sensor packaging to protect margin structure during semiconductor capacity crunches. For New Entrants and Emerging Players: Interoperability gaps in electronic health record integration present white-space opportunity for middleware developers bridging proprietary smartphone formats with hospital information systems. India's tier-2 pharmacy networks remain the most penetrable geography for battery-independent mechanical devices. Pursue CDSCO registration partnerships with established Indian distributors to compress market entry timelines. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease management infrastructure play because respiratory monitoring hardware anchors recurring data revenue streams in value-based care contracts. Acquisition targets should display FDA 510(k) clearance pipelines or ISO 26782 calibration capabilities. Watch for CMS reimbursement code expansions covering pediatric asthma monitoring as the signal for inflection in homecare penetration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device pathways accelerate clearance timelines for electronic meters in United States distribution. |
| CE Marking Pathway | EU MDR technical documentation demands extend conformity assessments for European market access. |
| Hospital System Partnership | GPO contracts in United States health systems consolidate vendor relationships under value-based frameworks. |
| Software Companion Development | Telehealth platforms in Germany and Japan integrate peak flow data into chronic disease management workflows. |
| Reimbursement Strategy | CMS remote monitoring codes in the United States incentivize connected device procurement among Medicare enrollees. |
Methodological Framework
A spread of perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and homecare respiratory therapists converged on the working assumptions underpinning volume and value estimates. Primary fieldwork with device manufacturers and pharmacy distribution partners combined with secondary validation against FDA 510(k) databases, EU MDR notified body registers, CMS reimbursement code filings, and hospital procurement contract repositories. Bottom-up unit economics triangulated against top-down epidemiological modeling of asthma and COPD prevalence across the analysis window.
Segmentation dimensions modeled span product type, end user, technology architecture, and application use case, with geographic regulatory clusters treated as a cross-cutting analytical layer. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns in connected medical devices and respiratory diagnostics. Forecast inputs incorporated MEMS sensor foundry capacity expansion schedules and telehealth platform partnership announcements without assigning specific weighting coefficients.
Forecasts assume regulatory continuity in FDA 510(k) predicate frameworks and EU MDR conformity assessment timelines; material policy shifts would require re-modeling market entry trajectories and capital recovery periods. Practitioners should keep alternative scenarios live as reimbursement code expansions and semiconductor supply constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Repositioning and Offloading Devices Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Spinal Traction Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Global Cast Saw Devices Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Carotid Artery Stents Market
Medical Devices
Pulmonary Function Testing System Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Urometer Market
Medical Devices
Spain Respiratory Devices Market
Medical Devices
Surgical Robot Accessories Market
Medical Devices
Peripheral Interventions Market