
 Endorectal Balloon Market | 2026-2036
Endorectal Balloon Market Size, Share, and Industry Trends Forecast 2026-2036
Endorectal Balloon Market Foresight
MDR is pivoting the European cost-of-entry calculus for endorectal balloon manufacturers toward expanded clinical documentation and notified body scrutiny. Bionix Radiation Therapy anchors its position through deep specialization in radiation oncology accessories. Qfix leverages proprietary immobilization expertise to extend its balloon portfolio into integrated prostate positioning systems. CIVCO Medical Solutions dominates hospital contracting channels across North American academic medical centers.
An endorectal balloon is a deformable, inflatable device inserted into the rectum to displace prostatic tissue from the radiation beam path during external beam radiotherapy, typically fabricated from medical-grade silicone or latex with inflation volumes calibrated to individual anatomy. Single-use balloon configurations lead procedural volumes in radiation therapy applications due to infection control protocols, while silicone material grades command premium positioning against latex alternatives for hypersensitive patient populations. Customized and patient-specific balloon designs represent the fastest-growing product category as clinics adopt 3D-printed molds and anthropometric databases.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development timelines and commercial access across the two largest addressable markets. Japan's PMDA enforces JIS-standard biocompatibility testing that adds a distinct regulatory layer for Asian market entry. Stakeholders must monitor evolving reimbursement coding for image-guided radiation therapy accessories as payers recalibrate coverage for precision prostate interventions.
Market Dynamics
Precision prostate radiotherapy programs are consolidating purchasing authority within hospital system supply chains, compressing vendor negotiation cycles and elevating clinical evidence requirements for balloon selection committees.
Growth Catalysts
- EU MDR clinical documentation mandates:Stricter notified body scrutiny is filtering marginal competitors from European markets, creating shelf space for compliant manufacturers with robust quality management systems.
- Silicone material biocompatibility:Hypersensitive patient populations in academic medical centers are driving preference for medical-grade silicone configurations over latex alternatives in radiation therapy departments.
- Japan precision oncology scaling:PMDA's streamlined review pathways for radiation accessories are accelerating commercial access as Japanese hospital systems expand image-guided radiotherapy capacity.
Market Restraints
- Medical-grade silicone feedstock volatility:Specialized elastomer supply concentrates among Asian chemical processors, exposing balloon manufacturers to input cost swings and extended lead times.
- Single-use infection control protocols:Mandatory disposable configurations eliminate reprocessing revenue streams and inflate per-procedure costs for radiation therapy departments.
- Latex hypersensitivity liability exposure:Patient adverse event risk constrains latex balloon distribution in North American and European institutional settings despite cost advantages.
Strategic Opportunities
- 3D-printed patient-specific molds:Anthropometric database integration enables customized balloon geometries that improve rectal displacement precision and reduce planning margins.
- Integrated prostate positioning systems:Convergence of balloon immobilization with real-time tracking technology creates bundled procurement opportunities in academic medical centers.
- Germany hospital system consolidation:Centralized purchasing within large Krankenhausverbände favors vendors with comprehensive radiation oncology accessory portfolios and established GPO relationships.
Industry Challenges
- FDA 510(k) predicate device navigation:Substantial equivalence determinations for novel balloon geometries require extensive biocompatibility and mechanical testing documentation.
- Cross-platform compatibility engineering:Balloon inflation systems must interface with diverse linear accelerator vendor ecosystems, complicating product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endorectal Balloon Market |
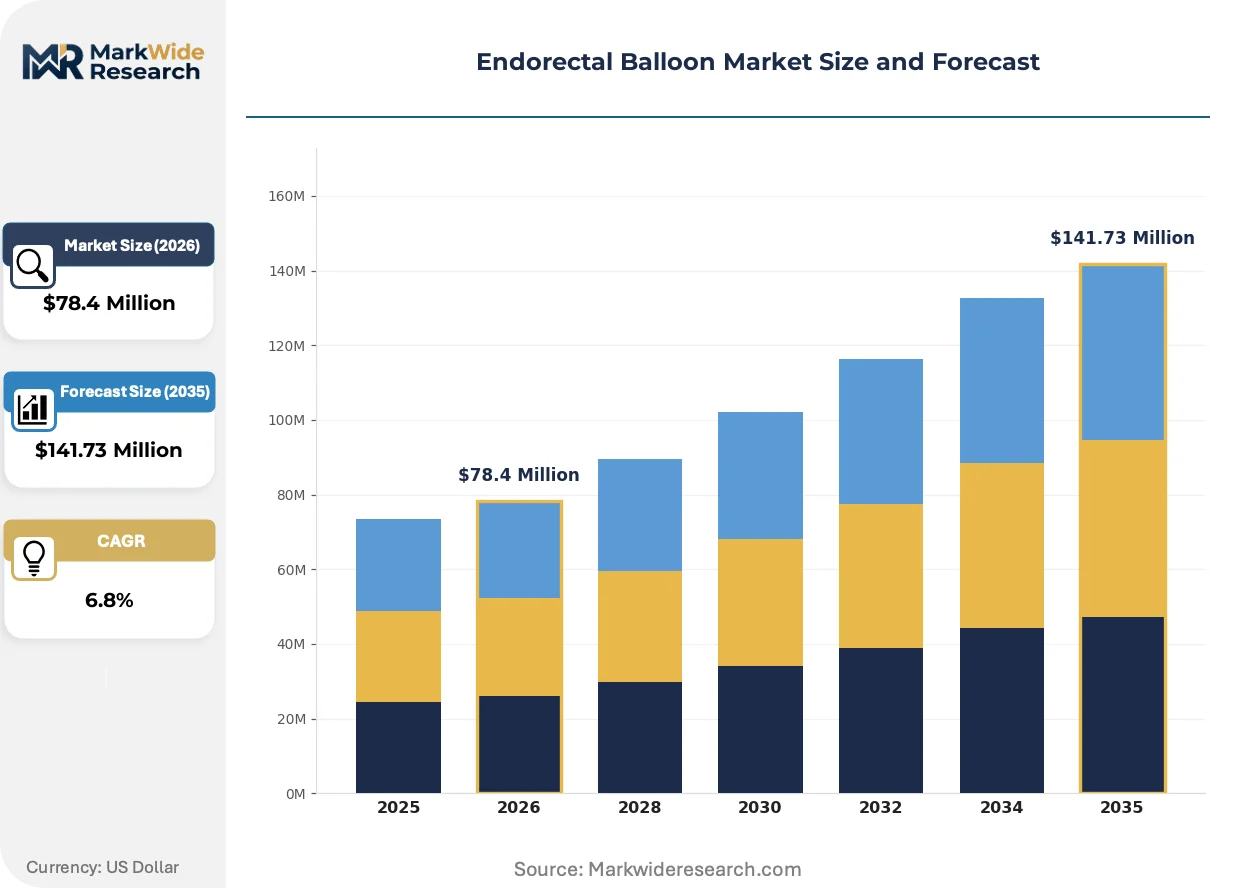
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Balloon, Reusable Balloon, Customized Balloon, Patient-Specific Balloon Application: Radiation Therapy, Medical Imaging, Endoscopy, Surgical Procedures Material: Latex, Silicone, Polyurethane, PVC End User: Hospitals, Clinics, Research Institutions, Outpatient Facilities |
| Companies Covered | QLRAD, Bionix Radiation Therapy, AngioDynamics, Qfix, BioProtect, CIVCO Medical Solutions, Coloplast, Boston Scientific, Becton Dickinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endorectal Balloon Market Shifts & Advancements
Computational modeling and additive manufacturing are converging to transform endorectal balloon from standardized commodities into anatomy-matched therapeutic instruments.
Patient-specific 3D-printed balloon molds derived from pelvic MRI atlases are rewriting treatment planning workflows. Radiation oncology departments at major academic centers are adopting these customized configurations for complex prostate anatomies. The technology is compressing planning margins and enabling dose escalation protocols previously constrained by rectal toxicity risk.
FDA's updated 510(k) pathway for Class II urological devices is tightening quality benchmarks for balloon manufacturers seeking US commercial access. The revised guidance demands expanded mechanical testing and biocompatibility documentation. Latex balloon suppliers face particular scrutiny as the agency elevates hypersensitivity risk assessment requirements.
Hospital system value analysis committees are consolidating radiation accessory purchasing decisions under centralized supply chain governance. Independent radiation therapy clinics are losing direct vendor negotiation autonomy as purchasing migrates to corporate procurement offices. The United States exhibits the most pronounced concentration, with major health systems standardizing balloon specifications across multi-state facility networks.
Endorectal Balloon Market Segmentation
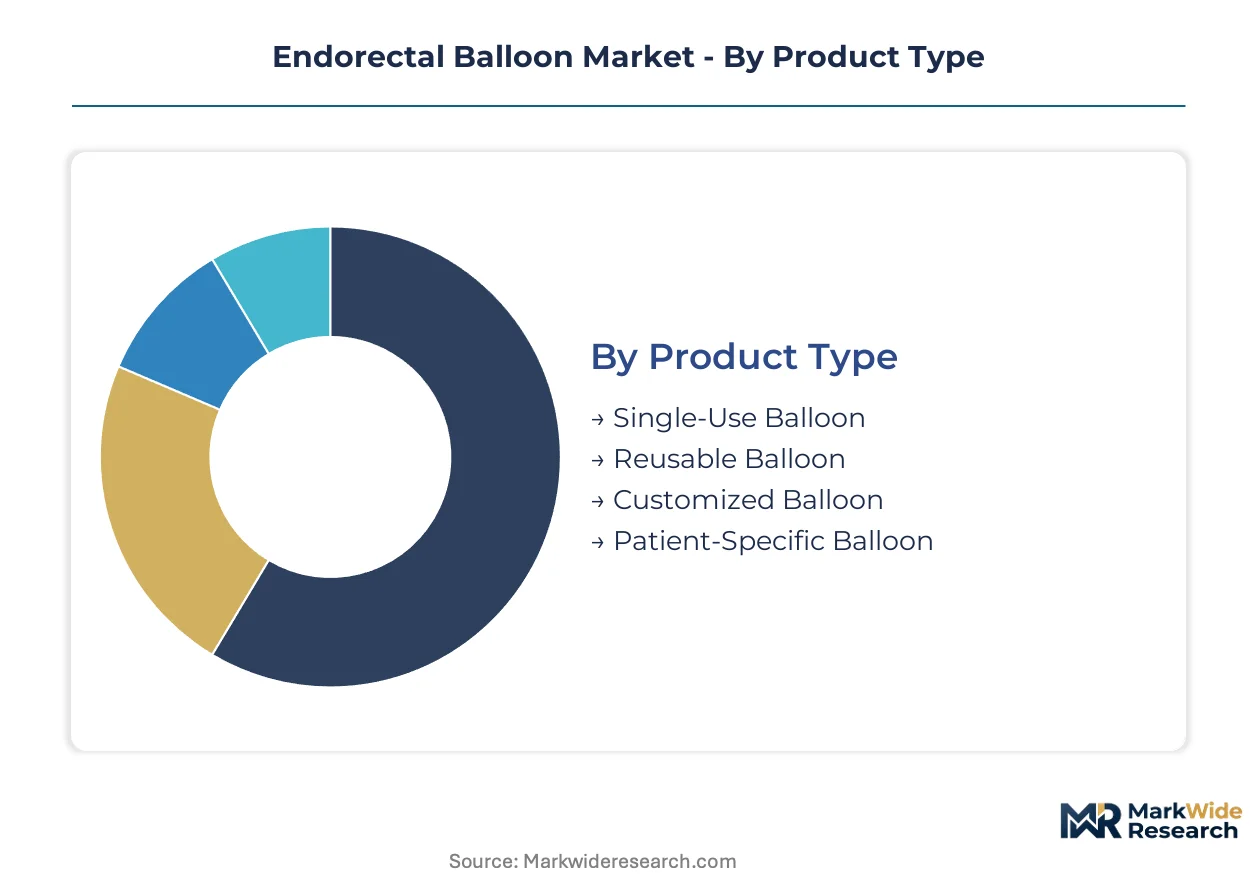
Endorectal balloon procurement patterns diverge sharply across clinical settings, with infection control protocols and precision radiotherapy requirements driving specification choices. Material biocompatibility and procedural volume economics further stratify vendor positioning across hospital system supply chains.
Product Type:
Disposable configurations dominate procedural economics while additive manufacturing opens patient-matched geometries.
- Single-Use Balloon:Sterile, pre-packaged latex or silicone configurations eliminate cross-contamination risk in radiation therapy departments. United States hospital systems mandate disposable protocols under Joint Commission infection control standards, compressing reprocessing revenue for alternative formats.
- Customized Balloon:3D-printed molds derived from pelvic MRI atlases enable anatomy-matched inflation geometries. Academic medical centers in Germany and Japan are piloting these configurations to compress planning margins and enable dose escalation protocols.
- Reusable Balloon:Autoclavable silicone designs persist in cost-constrained outpatient settings despite declining institutional preference.
- Patient-Specific Balloon:Anthropometric database integration enables individualized displacement precision for complex prostate anatomies.
Mature deployment sits with single-use configurations. Newer deployment is concentrated in patient-specific and customized balloon formats.
Application:
Clinical utility spans diagnostic imaging through therapeutic intervention, with radiation oncology commanding specification development.
- Radiation Therapy:External beam prostate radiotherapy remains the core indication, with balloons displacing rectal tissue from high-dose beam paths. Linear accelerator vendor ecosystems in the United States and Japan drive inflation system compatibility requirements.
- Medical Imaging:MRI and CT-compatible silicone configurations enable diagnostic rectal wall distension for pelvic floor assessment.
- Endoscopy:Low-pressure inflation assists colonoscopic visualization of rectosigmoid junction pathologies.
- Surgical Procedures:Transanal minimally invasive surgery applications utilize balloons for operative field exposure.
Volume concentration rests with radiation therapy. Imaging compatibility requirements are expanding fastest as MRI-guided radiotherapy platforms proliferate.
Material:
Biocompatibility grades and hypersensitivity liability exposure stratify raw material selection across regulatory jurisdictions.
- Silicone:Medical-grade platinum-cured elastomers command premium positioning in academic medical centers. PMDA's JIS-standard biocompatibility testing and FDA's elevated hypersensitivity risk assessments favor silicone adoption in Japan and the United States.
- Latex:Natural rubber configurations retain cost advantage in emerging markets but face distribution constraints in North American and European institutional settings due to adverse event liability exposure.
- Polyurethane:Thermoplastic alternatives offer intermediate compliance characteristics for specialized inflation profiles.
- PVC:Phthalate-free formulations serve cost-sensitive diagnostic applications with limited therapeutic exposure duration.
Silicone dominates precision oncology procurement. Latex persists where reimbursement compression outweighs hypersensitivity risk management priorities.
End User:
Purchasing authority consolidation reshapes vendor access patterns across facility types.
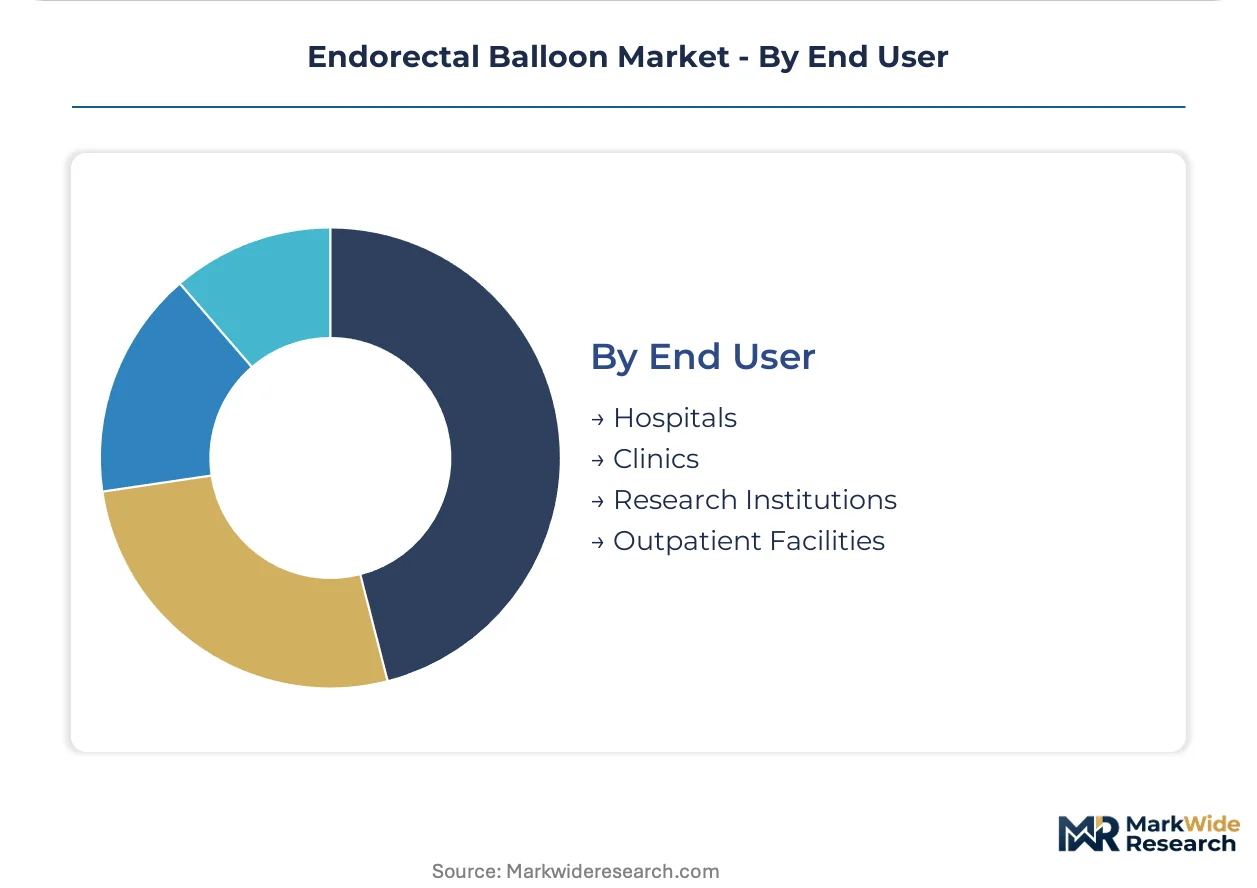
- Hospitals:Major health systems in the United States standardize balloon specifications across multi-state facility networks, concentrating negotiation leverage within corporate procurement offices.
- Clinics:Independent radiation therapy centers are losing direct vendor autonomy as purchasing migrates to hospital system supply chains.
- Research Institutions:Academic medical centers pilot patient-specific configurations and drive clinical evidence generation for regulatory submissions.
- Outpatient Facilities:Ambulatory surgery centers prioritize single-use disposables to minimize reprocessing infrastructure investment.
Hospital system contracting commands procurement volume. Research institutions are expanding fastest as customized balloon development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for endorectal balloons concentrates in health systems scaling precision prostate radiotherapy. The United States, Germany, and Japan anchor procurement volume through expanded image-guided radiotherapy programs and centralized hospital contracting.
United States
Major health systems standardize balloon specifications across multi-state networks, compressing vendor negotiation cycles. FDA's updated 510(k) pathway for Class II urological devices tightens quality benchmarks and elevates biocompatibility documentation requirements. The Greater Boston and Houston medical corridors host academic centers piloting patient-specific 3D-printed balloon configurations.
Germany
Krankenhausverbände consolidate purchasing authority within large hospital associations, favoring vendors with comprehensive radiation oncology portfolios. EU MDR conformity assessments filter marginal competitors through expanded clinical documentation mandates. The North Rhine-Westphalia cluster anchors manufacturing and distribution infrastructure for European markets.
Japan
PMDA's streamlined review pathways for radiation accessories accelerate commercial access as hospital systems expand image-guided radiotherapy capacity. JIS-standard biocompatibility testing creates a distinct regulatory layer for market entry. The Kanto region surrounding Tokyo concentrates precision oncology program development and academic medical center procurement.
United Kingdom
NHS England's specialized commissioning frameworks shape radiation therapy accessory procurement through centralized value analysis committees. MHRA post-Brexit regulatory alignment with EU MDR maintains conformity assessment stringency. The London-Southeast corridor dominates hospital system consolidation and academic center pilot programs.
Australia
TGA's medical device regulations enforce ISO 13485 quality management system certification for balloon manufacturers seeking commercial access. Public hospital procurement through state health departments concentrates negotiation leverage within centralized supply chains. New South Wales and Victoria anchor radiotherapy department expansion and precision oncology investment.
Endorectal Balloon Market Competitive Landscape
United States producers anchor the premium-tier segment through FDA-cleared silicone configurations; European specialists hold position via MDR-compliant documentation and academic center relationships. The vendor base stratifies across three tiers: diversified medical device conglomerates with radiation oncology divisions, dedicated radiation therapy accessory specialists, and regional contract manufacturers serving cost-sensitive markets. Dominant competitive moves include portfolio diversification into integrated prostate positioning systems and strategic partnerships with linear accelerator vendors for inflation system compatibility.
Among radiation therapy specialists, Bionix Radiation Therapy, Qfix, and CIVCO Medical Solutions occupy positions representing distinct strategic archetypes. Bionix exemplifies deep specialization in radiation oncology accessories with concentrated product development focus. Qfix represents the immobilization expertise extension model, leveraging core positioning technology into adjacent balloon applications. CIVCO anchors the hospital contracting channel dominance archetype, particularly across North American academic medical centers where GPO relationships and multi-product portfolio breadth create procurement stickiness. These three specialists collectively illustrate how vendor positioning in this market derives from either technology origin, channel control, or clinical workflow integration rather than scale economies alone.
| Leading Market Players |
|---|
| QLRAD |
| Bionix Radiation Therapy |
| AngioDynamics |
| Qfix |
| BioProtect |
| CIVCO Medical Solutions |
| Coloplast |
| Boston Scientific |
| Becton Dickinson |
| Others |
Supply & Pricing Matrix
Captive production of medical-grade silicone elastomers anchors supply positioning and pricing power for balloon manufacturers serving FDA and EU MDR jurisdictions. Asian chemical processors control specialized platinum-cured silicone feedstock, tethering input costs to regional polymer capacity and elevating margin pressure for Western device makers.
Pricing Analysis
High-volume single-use latex configurations trade at compressed margins while low-volume patient-specific silicone balloons command substantial premiums. Price differentiation rests on FDA 510(k) clearance tier and JIS-standard biocompatibility certification, with academic medical centers absorbing premium positioning for hypersensitive populations. Pricing pressure stems from hospital system GPO consolidation compressing vendor negotiation leverage. Independent radiation clinics exhibit acute price sensitivity; major health systems with standardized specifications demonstrate reduced elasticity.
Supply Chain Analysis
Reverse-logistics flows for reusable balloon configurations have contracted as infection control protocols mandate single-use disposables, eliminating refurbishment revenue streams. Raw material supply concentrates in China, Japan, and South Korea for platinum-cured silicone elastomers and precision inflation valves. Feedstock sourcing draws from Asian chemical processors, exposing manufacturers to commodity price volatility and extended lead times. Distribution runs through hospital system procurement offices and radiation oncology GPOs in the United States, Germany, and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The endorectal balloon market is becoming a vertical-integration race as manufacturers pursue captive control over medical-grade silicone compounding to defend margin structures against Asian feedstock volatility.
For Market Incumbents: Deepen backward integration into platinum-cured silicone compounding to reduce exposure to Asian chemical processor pricing cycles. Fortify hospital system GPO relationships through bundled prostate positioning system offerings that complicate vendor switching. CIVCO's contracting channel dominance and Qfix's immobilization technology extension illustrate defensive postures against emerging 3D-printed patient-specific entrants.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in patient-specific balloon configurations offers white-space opportunity for additive manufacturing specialists with anthropometric database capabilities. Target academic medical centers in Germany and Japan piloting customized rectal displacement geometries. Pursue regulatory sandbox pathways through PMDA's streamlined radiation accessory review to accelerate commercial proof points.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified radiation oncology device conglomerates seeking balloon portfolio fill-ins. Long-term viability hinges on MDR documentation depth and FDA 510(k) predicate navigation capability. Monitor EU notified body backlog resolution as inflection signal for European market access timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Clinical Documentation Investment | Expanded notified body scrutiny filters marginal competitors from European hospital contracting. |
| 3D-Printed Patient-Specific Mold Development | Anthropometric database integration enables anatomy-matched geometries for complex prostate anatomies. |
| Silicone Compounding Backward Integration | Captive elastomer production reduces exposure to Asian chemical processor price volatility. |
| Linear Accelerator Vendor Partnership | Inflation system compatibility engineering secures procurement stickiness in radiation therapy departments. |
| Hospital System GPO Consolidation | Multi-product portfolio breadth creates negotiation leverage against independent radiation clinics. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, PMDA radiation accessory submissions, and hospital procurement databases, complemented by interviews with radiation oncology department heads, biomedical engineers, GPO contracts managers, and silicone elastomer procurement leads. Secondary validation drew from CMS Medicare reimbursement data, academic medical center purchasing records, and JIS-standard biocompatibility testing protocols. Bottom-up procedure volume estimates and top-down radiation therapy department capacity assessments were triangulated against manufacturer shipment data.
Segment-level value outputs were generated across product type, material grade, application, and end-user facility categories throughout the forecast period. CAGRs were derived from procedure volume elasticity models calibrated to precision oncology program expansion rates and linear accelerator installation data. Forecast inputs incorporated EU MDR transition timelines, PMDA review pathway efficiency, and hospital system consolidation trajectories in the United States and Germany.
Inputs from FDA pre-submission meetings and notified body technical documentation reviews were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around price-point estimates. Forecasts reflect documented assumptions regarding MDR compliance cost pass-through and silicone feedstock price normalization. Practitioners should monitor EU notified body capacity expansion and Japanese image-guided radiotherapy reimbursement decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
China Endoscopy Devices Market
Endoscopy
Endoscopic Stricture Management Market
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
Veterinary Video Endoscopy Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Dermatology Endoscopy Devices Market
Endoscopy
Brazil Endoscopy Devices Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
UAE Endoscopy Devices Market
Endoscopy
Duodenoscope Market
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
Argentina Endoscopy Devices Market
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Mexico Endoscopy Devices Market