
 Nasal Irrigation Market | 2026-2036
Nasal Irrigation Market Size, Share, and Industry Trends Forecast 2026-2036
Nasal Irrigation Market Outlook
The capital-intensity gap between established device manufacturers and commodity saline suppliers is collapsing as automated production lines lower entry barriers for precision-molded nasal wash systems. NeilMed Pharmaceuticals leverages its direct-to-consumer channel infrastructure to sustain margin capture across retail pharmacy networks. Medtronic differentiates through clinical-grade device portfolios that anchor hospital procurement contracts. Heal Force Bio-meditech Holdings competes on manufacturing scale, occupying cost-advantaged positions in bulk saline production for emerging markets.
Nasal irrigation encompasses the therapeutic rinsing of nasal passages with saline formulations to clear mucus, allergens, and irritants, typically employing isotonic or hypertonic solutions delivered via squeeze bottles, neti pots, or pulsatile devices. The practice functions primarily to reduce sinus inflammation, improve mucociliary clearance, and mitigate rhinitis symptoms in both clinical and home settings. Nasal Sprays and Devices command the dominant revenue share due to convenience-driven patient preference and pharmacy shelf placement, while Home Care represents the fastest-expanding end user channel as post-pandemic hygiene habits normalize self-administered routines. Saline Solutions retain mature, high-volume positioning with thinner margins, whereas Automatic delivery modes concentrate premium pricing among chronic sinusitis patients seeking consistent flow control.
FDA 510(k) clearance requirements for powered irrigation devices shape product development timelines and clinical validation burdens for manufacturers seeking US market access. EPA oversight of medical device sterilization processes and ISO 13485 quality management standards further constrain supply chain qualification for international exporters. Stakeholders must monitor evolving FDA guidance on software-enabled dosing features and antimicrobial claims, as these regulatory boundaries will determine which product architectures secure reimbursement eligibility and retail distribution priority.
Market Dynamics
Automated manufacturing lines are collapsing the capital-intensity gap between precision-molded nasal wash systems and commodity saline production, redistributing competitive advantage toward scale-efficient producers with FDA 510(k) clearance capabilities.
Growth Catalysts
- Home Care Channel Expansion:Post-pandemic hygiene normalization is cementing self-administered nasal irrigation routines among chronic rhinitis patients, pulling volume through retail pharmacy networks and direct-to-consumer platforms.
- ISO 13485 Quality Standardization:International quality management certification is streamlining supply chain qualification for exporters, reducing market entry friction for automated production facilities.
- EPA Sterilization Oversight:Medical device sterilization process regulations are elevating quality benchmarks, filtering out subscale competitors and consolidating procurement contracts around compliant manufacturers.
Market Restraints
- Petroleum-Based Polymer Cost Volatility:Squeeze bottles and neti pots depend on medical-grade plastics whose input costs fluctuate with crude oil markets, compressing margins for molded device producers.
- FDA 510(k) Validation Burden:Powered irrigation devices face extended clinical validation timelines and software documentation requirements that delay US market access by 12-18 months for new entrants.
- Hypertonic Saline Substitution:Over-the-counter decongestant sprays and oral antihistamines compete for allergy symptom relief, particularly among episodic users with low treatment adherence.
Strategic Opportunities
- Software-Enabled Dosing Features:Bluetooth-connected pulsatile devices with flow monitoring and usage tracking are opening premium positioning among tech-adherent chronic sinusitis patients seeking adherence data.
- Emerging Market Bulk Saline:Cost-advantaged manufacturing positions in Asia-Pacific and Latin America offer white space for high-volume, lower-margin saline production serving price-sensitive healthcare systems.
- Antimicrobial Device Claims Pathway:Evolving FDA guidance on antimicrobial surface coatings creates first-mover advantage for manufacturers investing in copper-alloy or silver-ion molded components.
Industry Challenges
- Biocompatibility Testing Talent Scarcity:ISO 10993 biological evaluation expertise is concentrated among specialized contract research organizations, creating bottlenecks for manufacturers accelerating 510(k) submissions.
- Legacy Pharmacy Distribution Integration:Automated replenishment systems and EDI compliance requirements demand IT infrastructure investments that strain mid-tier device manufacturers without captive retail technology teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasal Irrigation Market |
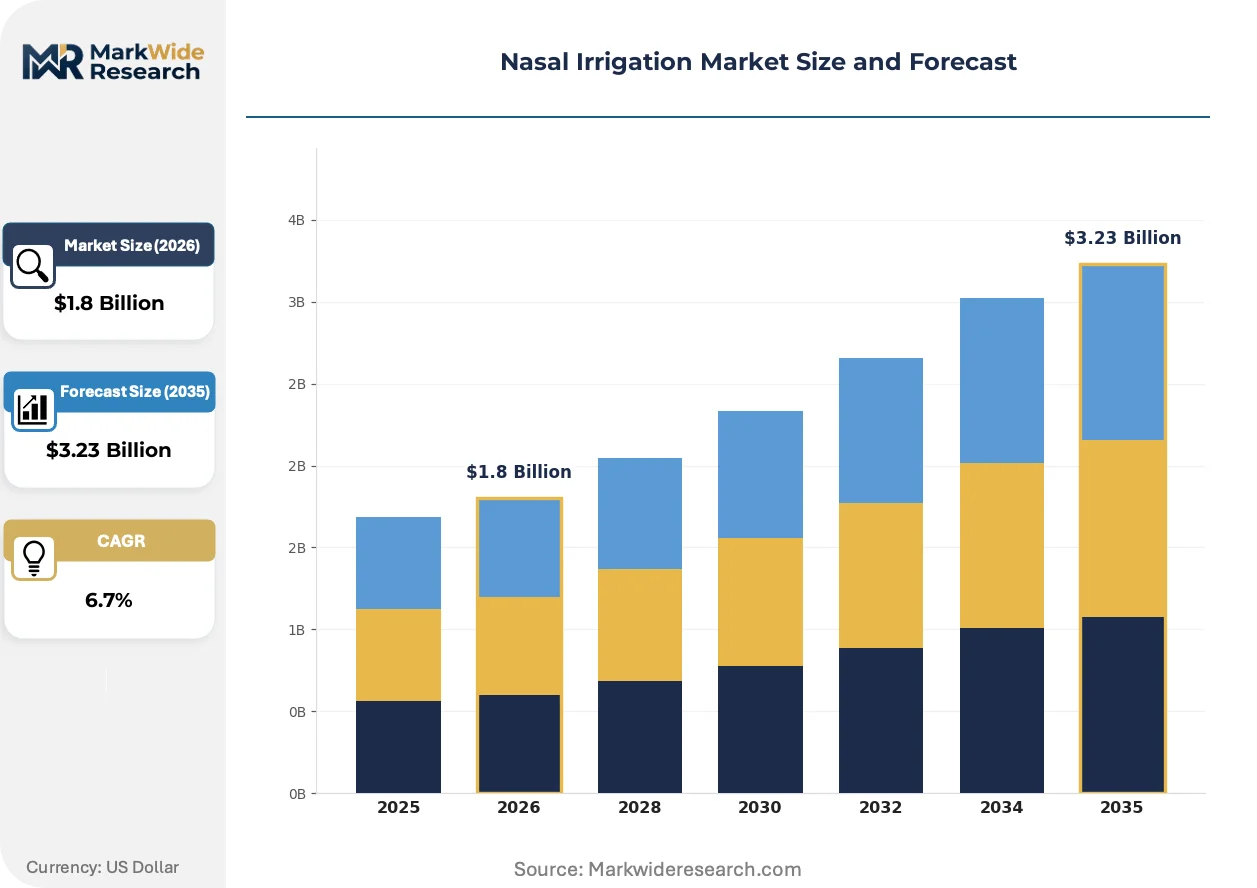
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nasal Sprays, Saline Solutions, Neti Pots, Devices End User: Patients, Healthcare Providers, Pharmacies, Home Care Delivery Mode: Manual, Automatic, Pre-filled, Bulk Application: Allergy Relief, Sinus Relief, Cold Treatment, Others |
| Companies Covered | Stryker Corporation, Heal Force Bio-meditech Holdings, NeilMed Pharmaceuticals, Bayer Pharma, RhinoSystems, Medtronic, Flaem Nuova, SinuPulse, Air Liquide Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasal Irrigation Market Strategic Shifts
Pulsatile delivery technology and connected health features are resegmenting the nasal irrigation market, compressing the traditional divide between clinical-grade and consumer-oriented products while tightening regulatory scrutiny on software-enabled claims.
Smart irrigation systems with pressure-sensing feedback and mobile app integration are supplanting mechanical squeeze bottles among chronic sinusitis patients requiring consistent flow control. Allergy specialists and ENT clinics are prescribing these devices at accelerating rates. The technology is compressing pricing power for basic neti pots while enabling subscription revenue models for consumable saline pods.
FDA guidance evolution on software-as-medical-device functionality is reshaping product architecture decisions for powered irrigation manufacturers. Developers must now document algorithm validation for dosing recommendations and antimicrobial surface claims. The powered device segment is responding by segregating R&D teams into hardware engineering and regulatory software compliance units.
Direct-to-consumer subscription models are disrupting traditional pharmacy shelf-dependent distribution for saline consumables. Chronic users are bypassing retail intermediaries for auto-ship programs bundled with device purchases. This pattern is most visible in the United States, where allergy prevalence and self-treatment culture support higher customer lifetime value economics.
Nasal Irrigation Market Segmentation
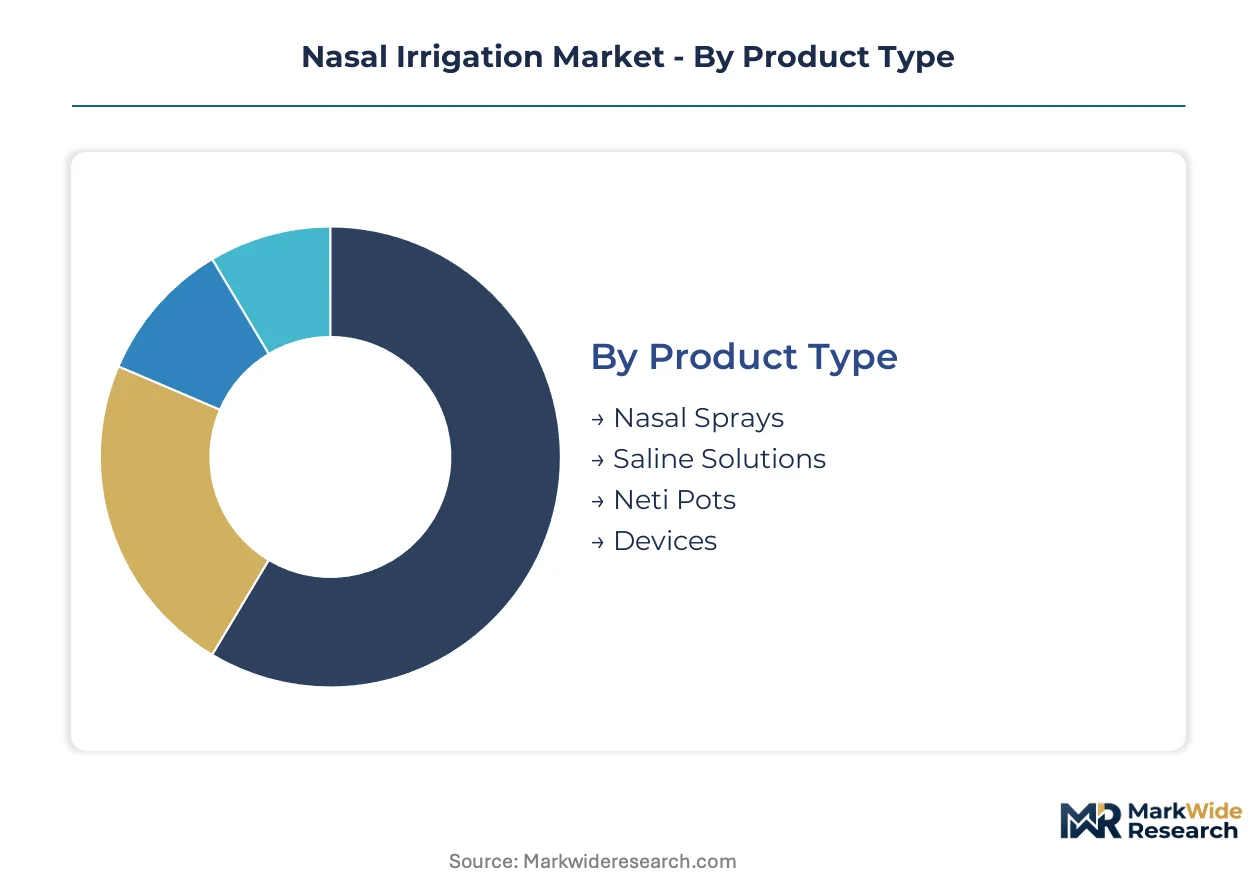
Segmentation in nasal irrigation reveals how margin capture concentrates around convenience-driven formats and self-administered care channels. Understanding these divides helps manufacturers allocate R&D resources between premium device innovation and high-volume saline production.
Product Type:
Premium margins cluster around precision-engineered delivery systems with regulatory clearance, while commodity saline competes on manufacturing scale.
- Nasal Sprays:Pressurized or pump-actuated systems delivering metered saline doses through proprietary nozzle geometries. Demand concentrates in US retail pharmacy networks where allergy sufferers prioritize portability and discrete use. Shelf placement fees and brand recognition create defensive moats for incumbent manufacturers.
- Devices:Powered pulsatile irrigators with pressure modulation and FDA 510(k) clearance. ENT clinics in Germany and Japan prescribe these for chronic sinusitis patients requiring consistent flow control. Software-enabled dosing features command subscription revenue for consumable pods.
- Saline Solutions:Isotonic and hypertonic formulations in squeeze bottles or refill containers. Bulk production in India and China serves price-sensitive healthcare systems with thinner margins.
- Neti Pots:Ceramic or plastic gravity-fed vessels for traditional irrigation. Ayurvedic wellness channels in India and alternative medicine practitioners in California sustain niche demand.
The dominant share belongs to Nasal Sprays, while Devices are closing the gap fastest.
End User:
Volume pull-through varies sharply by purchasing authority and reimbursement access.
- Home Care:Self-paying consumers managing chronic rhinitis through direct-to-consumer platforms and retail pharmacy networks. Post-pandemic hygiene normalization in the United States and United Kingdom has cemented daily irrigation routines among allergy sufferers.
- Healthcare Providers:ENT specialists and allergy clinics prescribing clinical-grade devices with documented outcomes. Reimbursement eligibility under Medicare and private insurers in the US determines procurement volume.
- Patients:Individual purchasers responding to physician recommendations or self-diagnosing allergy symptoms. Price sensitivity segments this group between premium devices and basic saline bottles.
- Pharmacies:Retail intermediaries controlling shelf placement and generic substitution for saline consumables. Consolidation among US pharmacy chains concentrates bargaining power.
Home Care commands the steepest expansion trajectory, though Healthcare Providers retain the highest per-unit margins.
Delivery Mode:
Technology intensity separates premium positioning from commodity supply.
- Automatic:Battery-powered or electric systems with pressure sensing and flow modulation. Chronic sinusitis patients in Japan and South Korea adopt these for adherence tracking.
- Pre-filled:Single-use saline pods eliminating mixing errors and contamination risk. Travel-oriented consumers in the United States and Germany pay premium per-dose pricing.
- Manual:Squeeze bottles and neti pots requiring user-controlled pressure. Lowest cost entry point for episodic users with limited treatment adherence.
- Bulk:Multi-liter saline containers for clinical settings or heavy home users. Hospital procurement in India and Brazil prioritizes cost per treatment.
Manual delivery still moves the most units, though Automatic systems are gaining share fastest among chronic patients.
Application:
Clinical validation depth determines reimbursement and prescribing behavior.
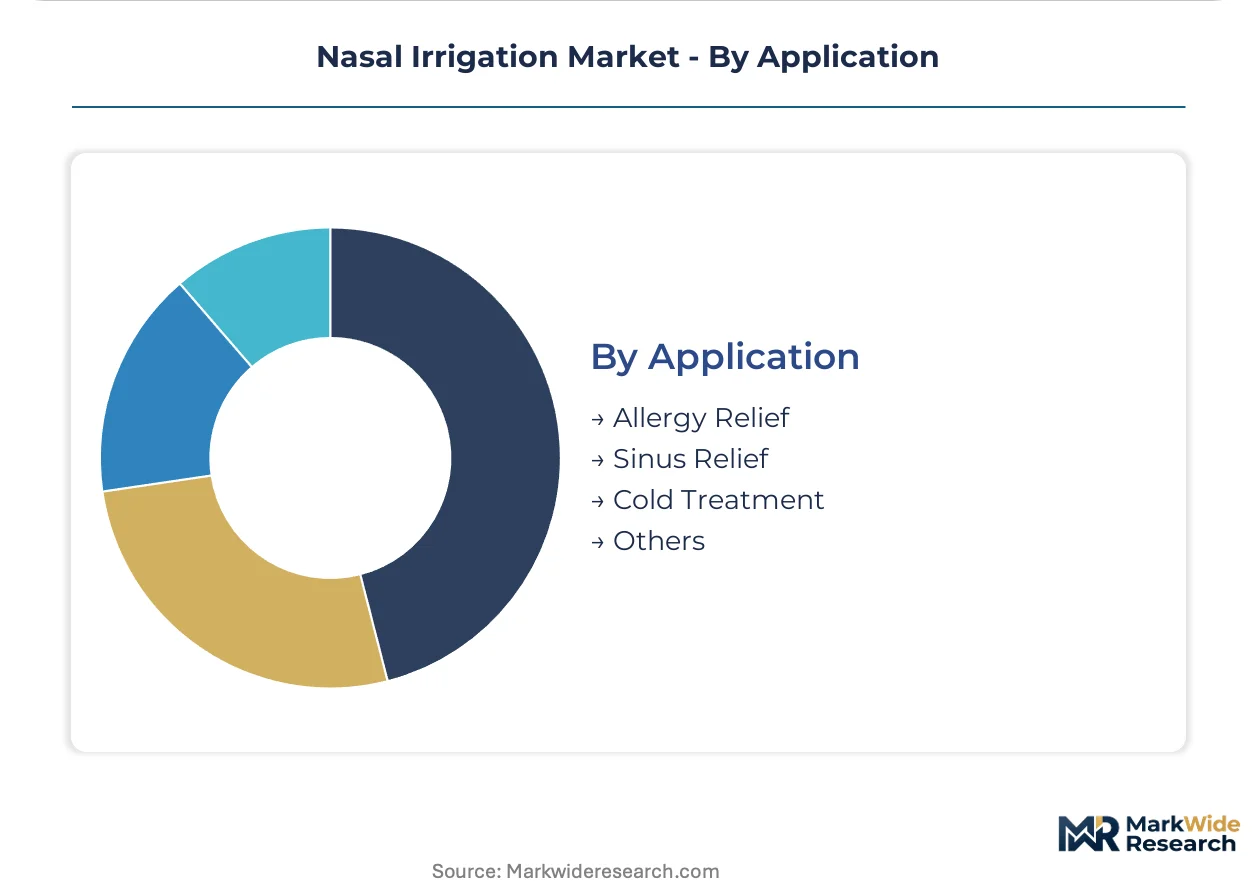
- Allergy Relief:Seasonal and perennial rhinitis management with documented efficacy in pollen-heavy regions. Demand spikes correlate with spring pollen counts in the US Midwest and Japanese cedar season.
- Sinus Relief:Chronic sinusitis and post-surgical care requiring physician oversight. FDA-cleared devices with clinical trial data secure hospital contracts.
- Cold Treatment:Symptomatic relief for viral upper respiratory infections. Over-the-counter positioning limits pricing power.
- Others:Post-operative care, pregnancy-related congestion, and occupational irritant exposure. Fragmented demand across specialized patient populations.
Allergy Relief holds the largest addressable population, while Sinus Relief delivers the highest revenue per patient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of precision-molded nasal wash systems concentrate in automated manufacturing corridors, while saline solution imports satisfy price-sensitive healthcare systems lacking domestic production scale. Trade balances tilt toward deficit in emerging markets and surplus in automated production hubs.
United States
Allergy prevalence in the Midwest and self-treatment culture in California sustain retail pharmacy volume. FDA 510(k) clearance requirements filter device imports, privileging domestic manufacturers with established regulatory infrastructure. Minneapolis and Boston anchor clinical-grade device production clusters serving hospital procurement networks.
Germany
ENT clinic density and chronic sinusitis diagnosis rates drive prescription-grade device demand. EMA medical device regulations and ISO 13485 certification requirements constrain non-European exporters. Stuttgart and Munich host precision engineering clusters producing pulsatile irrigators with pressure modulation technology.
Japan
Adherence-tracking technology adoption among chronic patients accelerates automatic device penetration. PMDA software-as-medical-device guidance shapes product architecture decisions for connected health features. Osaka and Nagoya concentrate manufacturing of battery-powered systems with flow monitoring capabilities.
India
Price-sensitive healthcare procurement and Ayurvedic wellness channels sustain bulk saline and neti pot demand. CDSCO medical device regulations are tightening quality benchmarks for imported powered systems. Gujarat and Maharashtra host cost-advantaged production facilities serving domestic hospital networks and export markets.
Brazil
Seasonal allergy patterns and expanding pharmacy retail chains pull volume through over-the-counter channels. ANVISA medical device registration timelines delay market access for new powered irrigation entrants. São Paulo anchors distribution infrastructure connecting imported devices to southeastern healthcare networks.
Nasal Irrigation Market Competitive Environment
Concentration sits with diversified medical device conglomerates and specialized saline manufacturers. The market structure divides between premium device producers with regulatory clearance and commodity saline suppliers competing on manufacturing scale. Two strategic archetypes dominate: clinical-grade device specialists with hospital procurement relationships, and direct-to-consumer platforms with captive retail pharmacy networks. Competitive moves center on automated production line investments and software-enabled dosing feature development.
Among diversified medical technology conglomerates, Stryker Corporation and Medtronic exemplify the hospital-contract archetype with clinical-grade device portfolios. NeilMed Pharmaceuticals occupies a position within the direct-to-consumer channel infrastructure, representing retail pharmacy network penetration strategies. Heal Force Bio-meditech Holdings anchors the manufacturing-scale archetype for bulk saline production serving emerging market price sensitivity.
| Leading Market Players |
|---|
| Stryker Corporation |
| Heal Force Bio-meditech Holdings |
| NeilMed Pharmaceuticals |
| Bayer Pharma |
| RhinoSystems |
| Medtronic |
| Flaem Nuova |
| SinuPulse |
| Air Liquide Medical Systems |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for medical-grade polymer feedstock expose device manufacturers to crude oil volatility while compressing margin buffers for precision-molded nasal wash systems against commodity saline producers. This lead-time structure concentrates pricing power among automated production facilities with FDA 510(k) clearance capabilities.
Pricing Analysis
The customization-premium spread between software-enabled pulsatile devices and basic squeeze bottles reaches three-to-one, with Bluetooth-connected systems commanding subscription-bundled pricing while manual delivery modes compete on per-unit transactional models. Price differentiation rests on FDA clearance tier and manufacturing scale, with ISO 13485-certified facilities capturing brand premiums against uncertified imports. Pricing pressure intensifies in the saline solutions tier as Asian bulk producers expand capacity, squeezing margins for Western molded device specialists. Home care consumers exhibit highest price sensitivity, whereas ENT clinic procurement committees prioritize clinical validation over unit cost.
Supply Chain Analysis
Inventory compression to sixty-day cycles for lithium-ion battery cells in Japanese automatic devices reflects just-in-time pressures from pulsatile technology adoption. Supply concentrates in China for medical-grade polypropylene resin, India for bulk saline formulation, and Germany for precision pressure-modulation components. Raw material dependencies include petroleum-derived polymers, pharmaceutical-grade sodium chloride, and electronic sensor modules. Single-source vulnerability for FDA-registered sterilization services creates bottlenecks during submission surges. Distribution runs through consolidated US pharmacy chains and direct-to-consumer platforms bypassing retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to seasonal allergy prevalence patterns, with spring pollen indices in the US Midwest and Japanese cedar season driving predictable demand spikes that normalize inventory positioning.
For Market Incumbents: Compound defensive moats by deepening backward integration into pharmaceutical-grade sodium chloride production and securing exclusive GPO contracts with hospital procurement networks. Software-enabled dosing features represent the critical lever against emerging Asian device manufacturers lacking FDA software documentation capabilities. Automated replenishment system investments cement pharmacy shelf control against direct-to-consumer disruptors. For New Entrants and Emerging Players: Anchor in the emerging market bulk saline segment serving price-sensitive healthcare systems in India and Brazil, where CDSCO and ANVISA registration timelines favor domestic producers. White space concentrates in pre-filled single-use pods for travel-oriented consumers, with white-label supply agreements to European pharmacy chains offering the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates seeking to divest non-core consumer health portfolios, particularly those with dormant FDA 510(k) clearances and underutilized automated production lines. Long-term viability hinges on recurring revenue attachment rates for consumable pods. The signal to watch is ENT clinic prescription velocity for connected devices as reimbursement eligibility expands.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software Documentation | Algorithm validation for dosing recommendations secures premium device positioning against mechanical competitors. |
| Hospital System Partnership | GPO contract anchoring with Minneapolis and Boston procurement networks locks in clinical-grade volume. |
| Direct-to-Consumer Platform Launch | Auto-ship subscription models bypass retail pharmacy intermediaries and capture higher customer lifetime value. |
| Backward Integration into Saline | In-house pharmaceutical-grade sodium chloride production insulates margin from commodity price swings. |
| Antimicrobial Surface Certification | Copper-alloy or silver-ion coating claims open first-mover advantage under evolving FDA guidance. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) submissions, EPA sterilization registration databases, and ISO certification registries. Interviews with ENT specialists, hospital GPO contract managers, biomedical engineers, and retail pharmacy category buyers inform demand-side validation. Secondary sources include hospital procurement databases, CMS Medicare durable medical equipment claims, and customs trade data for saline solution imports. Bottom-up patient population modeling triangulates against top-down manufacturer revenue aggregation.
Segmentation dimensions modeled span product type, delivery mode, end user channel, and application severity across the projection horizon. CAGRs derive from patient population growth, allergy prevalence indices, and technology substitution curves for manual versus automatic devices. Forecast inputs incorporate pollen count correlation models, reimbursement eligibility expansion timelines, and regulatory clearance backlog estimates for software-enabled features.
Material uncertainties — FDA guidance evolution on software-as-medical-device functionality, petroleum price volatility, and seasonal allergy severity variation — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
Medical Coatings Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Heart Failure POC and LOC Devices Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market
Medical Devices
Australia Aesthetic Devices Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Memory Implants Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Digital Orthodontics Market
Medical Devices
Cranial Closure and Fixation Devices Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Motorized Prosthesis Market
Medical Devices
Active Wheelchair Market
Medical Devices
Digital X-Ray Devices Market