
 Pneumatic Nebulizers Market | 2026-2036
Pneumatic Nebulizers Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Nebulizers Market Analysis
Respiratory therapist staffing shortages across US hospital networks is collapsing inpatient nebulization capacity and pushing therapy into outpatient channels. Koninklijke Philips N.V. leverages its home-care respiratory portfolio to capture this migration, while OMRON Corporation anchors the Asia-Pacific market through compact compressor designs optimized for domestic use. PARI GmbH differentiates via specialized aerosol delivery systems for cystic fibrosis patients requiring precise particle size control.
Pneumatic nebulizers are medical devices that convert liquid medication into respirable aerosol droplets through compressed gas or mechanical force, typically producing particles in the one-to-five micrometer range for optimal deep-lung deposition. These systems serve as foundational therapy delivery platforms for chronic obstructive pulmonary disease, asthma, and cystic fibrosis management across clinical and domestic environments. Portable nebulizers now command the fastest expansion trajectory within product type segmentation, driven by patient mobility demands and reimbursement shifts favoring ambulatory care. Home care settings represent the dominant end-user channel for value capture, though hospitals retain volume leadership in acute exacerbation scenarios where supervised administration remains protocol.
FDA medical device regulations govern 510(k) clearance pathways for nebulizer systems, while ISO 27427 standards define performance benchmarks for pneumatically powered respiratory equipment. The European Union Medical Device Regulation imposes additional clinical evidence requirements on manufacturers seeking CE marking for active therapeutic devices. Stakeholders must monitor evolving reimbursement codes for home nebulization across Medicare and private payers, as coverage determinations will shape patient access economics and manufacturer channel investments.
Market Dynamics
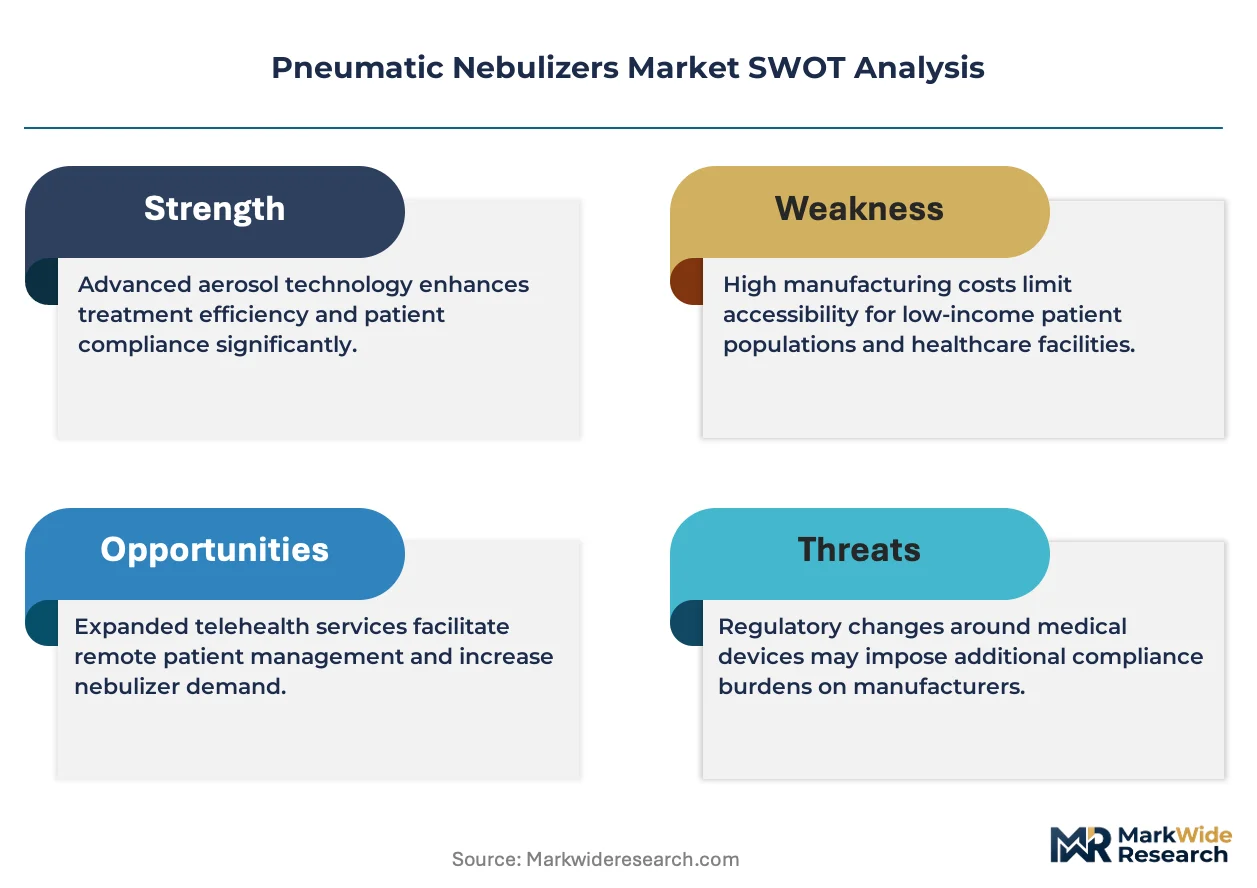
Respiratory therapist workforce attrition across United States hospital networks is collapsing inpatient nebulization capacity and forcing therapy migration into outpatient and domestic channels, fundamentally restructuring distribution economics and manufacturer channel investments.
Growth Catalysts
- Medicare reimbursement expansion:CMS coverage determinations for home nebulization under durable medical equipment provisions are accelerating patient access economics and manufacturer channel prioritization toward domestic settings.
- COPD prevalence demographics:Aging populations in the United States and Japan are sustaining clinical demand for chronic respiratory management platforms that pneumatic systems reliably deliver.
- Mesh-to-pneumatic substitution resistance:Compressor-based systems retain protocol preference among cystic fibrosis specialists requiring precise particle size distribution control that vibrating mesh alternatives struggle to replicate.
Market Restraints
- Compressor motor supply concentration:Precision motor manufacturing for portable units clusters in East Asian supplier networks, exposing procurement to geopolitical friction and logistics disruption.
- EU MDR clinical evidence burden:The European Union Medical Device Regulation imposes costly post-market surveillance and clinical performance documentation requirements that compress margins for mid-tier manufacturers.
- Ultrasonic nebulizer substitution:Silent operation and reduced treatment time in battery-powered ultrasonic systems threaten pneumatic unit adoption among noise-sensitive pediatric and geriatric patient segments.
Strategic Opportunities
- Rural India penetration gap:Underdeveloped respiratory care infrastructure in tier-3 and tier-4 Indian cities creates white space for ruggedized compressor systems optimized for unreliable electrical supply.
- Telehealth integration protocols:Remote patient monitoring reimbursement codes in the United States are creating incentive alignment for connected nebulizers that transmit adherence data to pulmonology practices.
- Green propellant transition:EPA hydrofluorocarbon phase-down mandates are forcing metered-dose inhaler reformulation, potentially redirecting asthma maintenance therapy toward nebulized alternatives with lower environmental compliance burden.
Industry Challenges
- Respiratory therapy talent pipeline collapse:Training program enrollment declines in the United States are constraining clinical support capacity needed to train patients on proper nebulizer technique and maintenance protocols.
- 510(k) clearance timeline volatility:FDA medical device review backlogs for aerosol delivery systems are extending time-to-market for next-generation compressor designs and compressing competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Nebulizers Market |
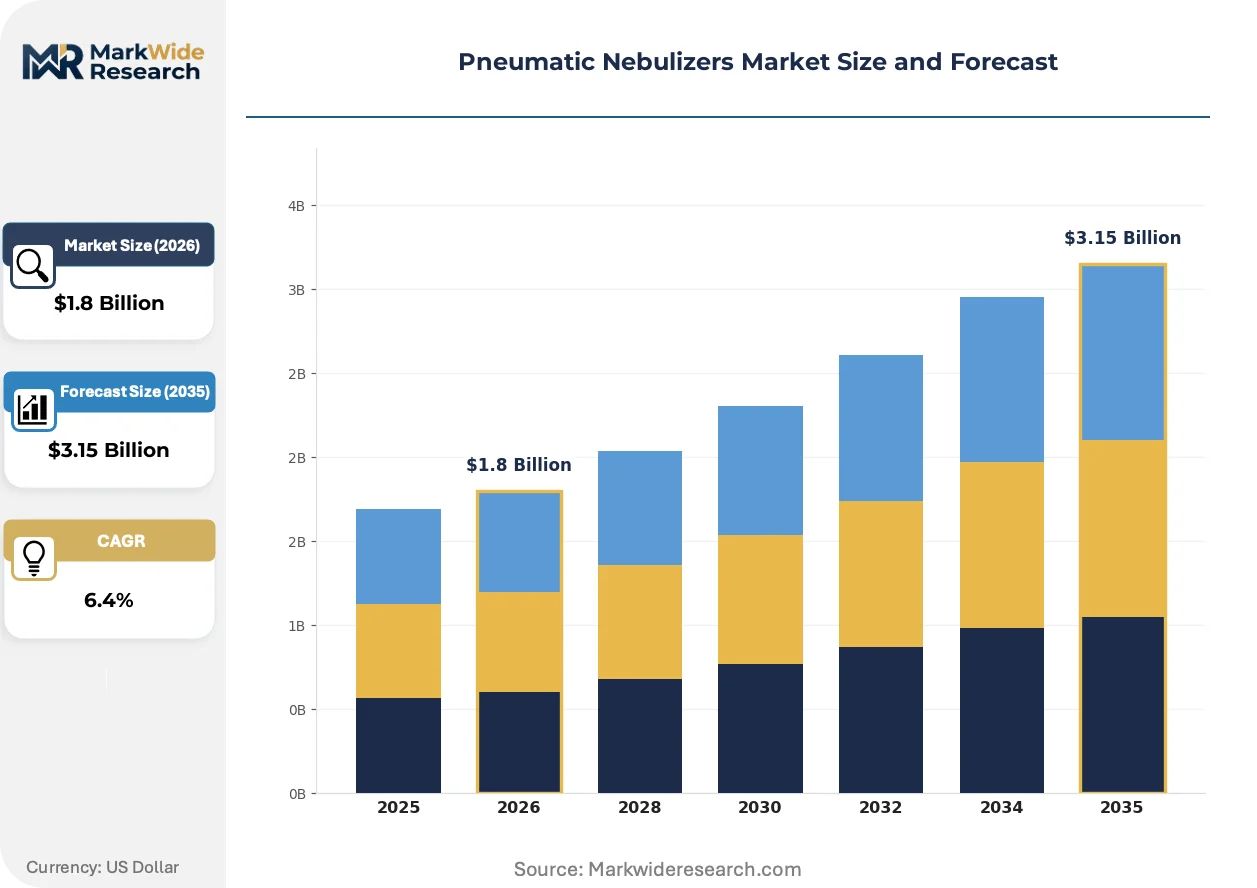
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop Nebulizers, Portable Nebulizers, Battery-operated Nebulizers, Electric Nebulizers End User: Hospitals, Clinics, Home Care Settings, Emergency Rooms Technology: Compressor Technology, Mesh Technology, Ultrasonic Technology, Manual Technology Application: Asthma Treatment, COPD Management, Cystic Fibrosis, Respiratory Infections |
| Companies Covered | Koninklijke Philips N.V., OMRON Corporation, PARI GmbH, General Electric, Allied Healthcare Products, Inc., BD (Becton, Dickinson & Company), GF Health Products, Inc., Medline Industries, LP, Briggs Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Nebulizers Market Emerging Trajectories
Pneumatic nebulizer engineering is converging with consumer electronics miniaturization and connectivity architectures, compressing device footprints while expanding therapeutic monitoring capabilities beyond traditional clinical boundaries.
Compressor technology is miniaturizing through piezoelectric pump innovations that replace conventional piston-driven mechanisms with silent, battery-efficient alternatives. Home care patients and traveling professionals are adopting these pocket-sized units at accelerating rates, displacing bedside compressor systems that tether users to electrical outlets. The structural consequence is miniaturizing the addressable market toward ambulatory patient segments previously excluded from nebulizer therapy by portability constraints.
ISO 27427 performance benchmarking revisions are tightening particle size distribution tolerances for pneumatic respiratory equipment, forcing manufacturers to recalibrate atomization chamber geometries and gas flow algorithms. Industrial consequence includes elevated R&D expenditure for compliance validation and accelerated obsolescence of legacy compressor platforms that fail tightened efficacy thresholds. Pediatric cystic fibrosis centers in Germany and the United States are responding by consolidating procurement around devices with documented sub-three-micrometer mass median aerodynamic diameter performance.
Hospital procurement committees are unbundling device acquisition from maintenance service contracts, compressing vendor margins on aftermarket revenue streams and shifting profitability toward consumable medication partnerships. The channel disruption is most visible in United States integrated delivery networks where GPO-negotiated device pricing now excludes technical support provisions that manufacturers previously bundled. Pulmonology practices in Texas and Florida are responding by establishing direct relationships with compressor suppliers for patient home deployment, bypassing traditional durable medical equipment intermediaries.
Pneumatic Nebulizers Market Segmentation
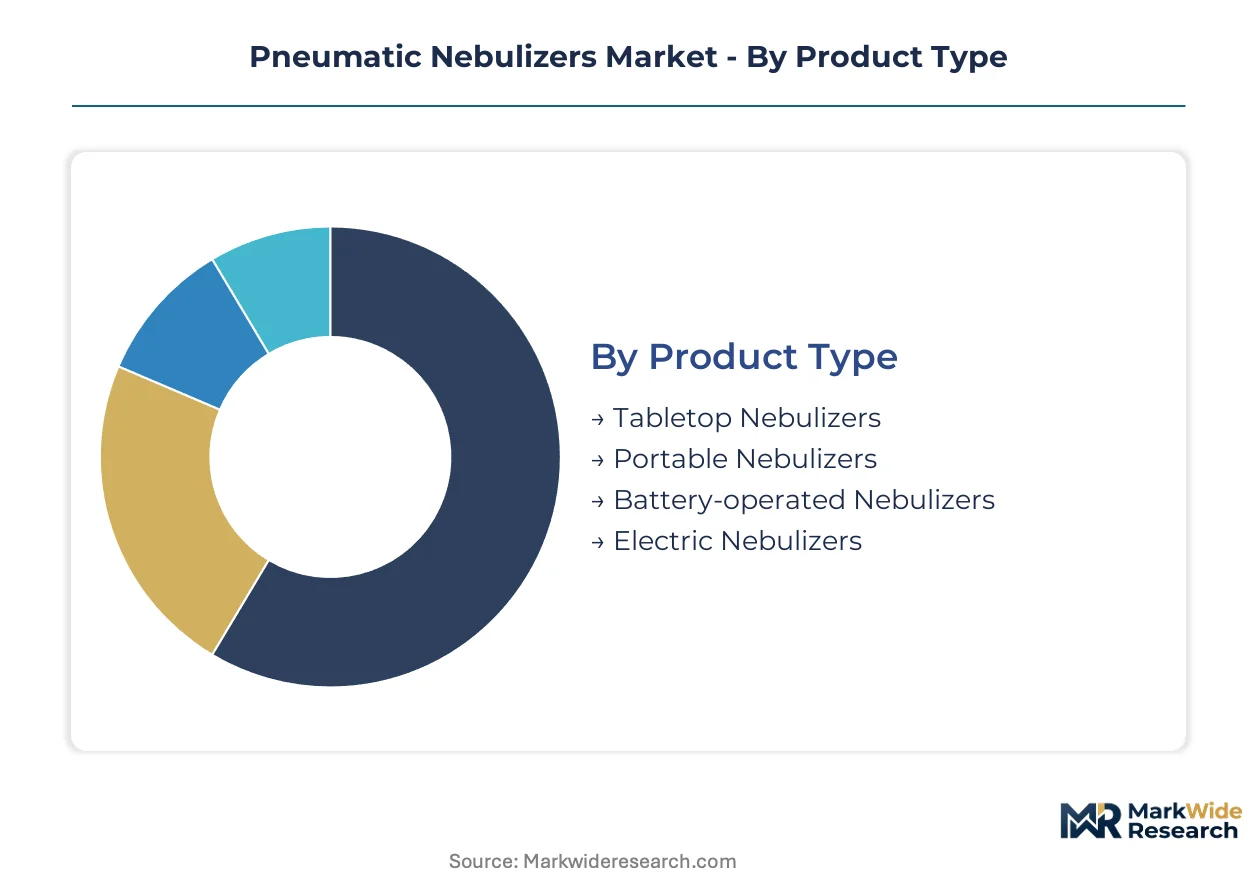
Pneumatic nebulizer segmentation reveals distinct margin architectures across product form factors and clinical deployment settings. Manufacturers optimize channel strategies by aligning compressor specifications with reimbursement pathways and patient mobility requirements.
Product Type:
Margin concentration tilts toward portable and battery-operated configurations as home care reimbursement expands and hospital procurement shifts toward patient-owned devices.
- Portable Nebulizers:Compact compressor units weighing under 500 grams deliver therapeutic aerosol through miniaturized piston or piezoelectric pump mechanisms. Demand concentrates among traveling professionals and mobile patients in the United States where Medicare durable medical equipment coverage supports ambulatory therapy. FDA 510(k) clearance timelines for these devices have lengthened as the agency tightens electrical safety validation for battery-powered medical equipment.
- Battery-operated Nebulizers:Cordless lithium-ion powered systems enable therapy delivery without electrical outlet dependency, critical for rural India and other regions with unreliable grid infrastructure. Japanese manufacturers lead cell efficiency optimization, extending treatment cycles per charge to support full medication compliance.
- Tabletop Nebulizers:Stationary compressor systems dominate pediatric cystic fibrosis centers requiring consistent particle size distribution for complex medication regimens.
- Electric Nebulizers:AC-powered bedside units retain hospital volume leadership in acute exacerbation scenarios where supervised administration remains protocol.
The dominant share belongs to tabletop nebulizers, while portable nebulizers are closing the gap fastest.
End User:
Channel economics diverge sharply between institutional procurement committees and direct-to-patient durable medical equipment suppliers.
- Home Care Settings:Patient-directed therapy delivery captures expanding reimbursement under CMS durable medical equipment provisions, with pulmonology practices in Texas and Florida establishing direct supplier relationships to bypass traditional intermediaries. ISO 27427 compliance documentation requirements elevate vendor selection criteria beyond price alone.
- Hospitals:Inpatient nebulization capacity faces structural constraint from respiratory therapist workforce attrition across United States networks, forcing therapy migration toward outpatient channels and compressing device procurement volumes.
- Clinics:Outpatient pulmonary practices serve as transition points between acute hospital discharge and long-term home management.
- Emergency Rooms:Acute presentation sites require rapid-deployment compressor systems for bronchodilator delivery during respiratory distress episodes.
Home care settings command the steepest expansion trajectory, though hospitals retain volume leadership in acute scenarios.
Technology:
Intellectual property concentration and manufacturing complexity determine margin durability across atomization mechanisms.
- Compressor Technology:Pneumatic gas-driven systems utilizing jet nebulization principles achieve consistent one-to-five micrometer particle size distribution through Bernoulli effect atomization. Cystic fibrosis specialists in Germany and the United States maintain protocol preference for these systems over vibrating mesh alternatives due to precise aerosol characterization.
- Mesh Technology:Vibrating aperture plate systems generate aerosol through mechanical oscillation of micromachined membranes, offering silent operation that threatens pneumatic adoption among noise-sensitive pediatric segments.
- Ultrasonic Technology:Piezoelectric crystal-driven nebulization produces high-output aerosol without compressor noise, gaining traction in geriatric home care applications.
- Manual Technology:Hand-powered squeeze-bulb systems serve emergency backup and resource-limited settings where electrical supply is unavailable.
Compressor technology holds the installed base majority, while mesh technology is gaining share fastest in noise-sensitive segments.
Application:
Therapeutic protocol requirements and medication formulation compatibility shape device specification demand.
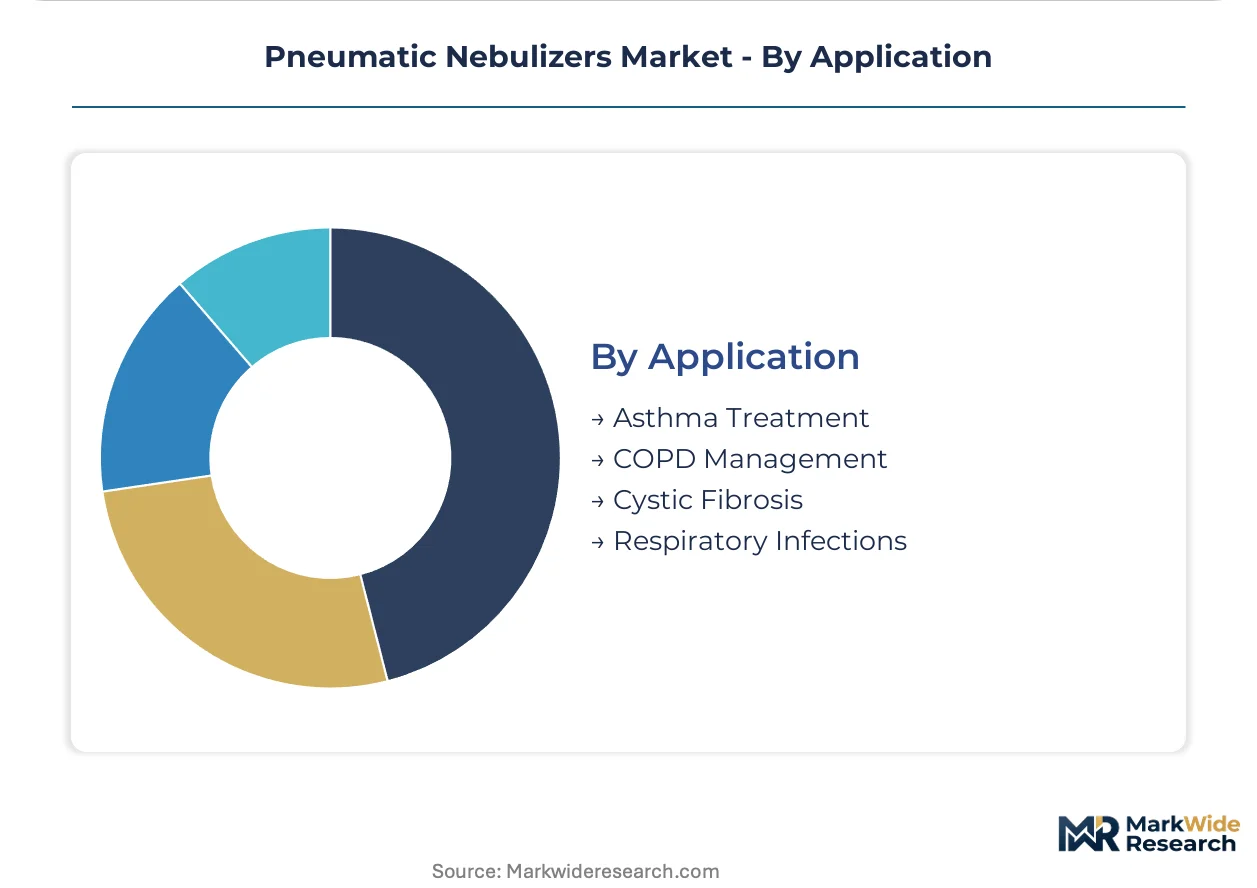
- COPD Management:Chronic obstructive pulmonary disease maintenance therapy drives the largest addressable patient population, with aging demographics in the United States and Japan sustaining clinical need for reliable bronchodilator delivery platforms that pneumatic systems reliably provide.
- Asthma Treatment:Maintenance and rescue therapy applications face potential redirection from metered-dose inhalers as EPA hydrofluorocarbon phase-down mandates force propellant reformulation, potentially elevating nebulized alternatives with lower environmental compliance burden.
- Cystic Fibrosis:Complex multi-drug regimens requiring precise sub-three-micrometer mass median aerodynamic diameter performance consolidate procurement around validated compressor platforms.
- Respiratory Infections:Acute bronchitis and pneumonia adjunct therapy represents episodic demand concentrated in hospital and emergency settings.
COPD management generates the dominant procedure volume, while cystic fibrosis commands the highest per-patient device investment intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States patients deploy pneumatic nebulizers predominantly in home care settings under Medicare durable medical equipment coverage, while Japanese and German markets retain stronger institutional procurement patterns tied to cystic fibrosis center protocols.
United States
COPD prevalence among aging populations and respiratory therapist workforce attrition are accelerating outpatient therapy migration. FDA 510(k) clearance pathways govern device approvals, with review timelines extending for battery-powered equipment. Texas and Florida pulmonology practices are establishing direct supplier relationships to bypass traditional durable medical equipment intermediaries.
Germany
Pediatric cystic fibrosis centers demand precise sub-three-micrometer particle size distribution performance that compressor systems reliably deliver. EU MDR clinical evidence requirements impose costly post-market surveillance obligations on manufacturers seeking CE marking. Industrial concentration in Baden-Württemberg hosts precision aerosol engineering clusters serving European hospital procurement networks.
Japan
Aging demographics sustain chronic respiratory management demand, with METI industrial policy supporting domestic medical device manufacturing competitiveness. PMDA regulatory frameworks align with international ISO 27427 performance benchmarks. Tokyo-based manufacturers lead lithium-ion cell efficiency optimization for battery-operated nebulizer designs.
India
Tier-3 and tier-4 cities present white space for ruggedized compressor systems optimized for unreliable electrical supply. CDSCO medical device regulations govern import and domestic manufacturing compliance. Maharashtra industrial corridors are emerging as assembly locations for cost-optimized portable units targeting rural penetration.
China
Expanding respiratory disease burden and domestic healthcare infrastructure investment are elevating nebulizer procurement volumes. NMPA medical device classification frameworks govern registration requirements for active therapeutic equipment. Yangtze River Delta manufacturing clusters concentrate precision motor component supply for portable compressor units.
Pneumatic Nebulizers Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure reflecting divergent channel strategies between hospital procurement committees and direct-to-patient durable medical equipment suppliers. The competitive terrain separates into three archetypes: diversified healthcare conglomerates with home-care respiratory portfolios, dedicated aerosol delivery specialists with cystic fibrosis clinical validation, and diversified industrial manufacturers with medical device divisions. Consolidation activity concentrates on consumable medication partnerships that recapture margins lost to unbundled service contracts, while geographic expansion targets reimbursement-favorable ambulatory care markets.
Within the diversified healthcare conglomerate tier, Koninklijke Philips N.V. exemplifies integrated home-care respiratory positioning, while OMRON Corporation anchors Japanese domestic market presence through compact compressor designs. PARI GmbH occupies a specialist position validated by cystic fibrosis center procurement consolidation. These three represent distinct strategic postures: Philips leverages portfolio breadth across patient monitoring and sleep therapy, OMRON exemplifies consumer health device miniaturization capabilities, and PARI embodies clinical specialty focus with precise aerosol characterization requirements.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| OMRON Corporation |
| PARI GmbH |
| General Electric |
| Allied Healthcare Products, Inc. |
| BD (Becton, Dickinson & Company) |
| GF Health Products, Inc. |
| Medline Industries, LP |
| Briggs Healthcare |
| Others |
Supply Flow & Price Mechanics
Compressor motor manufacturing scale economies in East Asian supplier networks establish minimum efficient scale thresholds that price out regional assemblers and compress margin structures for mid-tier brands competing on unit economics alone. This concentration simultaneously elevates procurement leverage for volume buyers and fragments pricing power among device assemblers lacking captive motor production.
Pricing Analysis
Contract-based long-term offtake agreements dominate hospital procurement through GPO-negotiated frameworks, while spot purchasing persists in direct-to-patient durable medical equipment channels. Price differentiation separates FDA-cleared premium tiers from economy units lacking ISO 27427 documentation, with brand premium and after-sales service bundling widening spreads. Cost compression in the mid-tier intensifies as unbundled maintenance contracts shift profitability toward consumable partnerships. Home care patients exhibit highest price sensitivity, while pediatric cystic fibrosis centers prioritize particle size validation over acquisition cost.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for precision motor components sourced from China, South Korea, and Japan. Device assembly draws from lithium-ion cell suppliers in Japan, precision pumps from Germany, and injection-molded housings from China. Single-source vulnerability concentrates in piezoelectric pump suppliers serving portable unit manufacturers. Distribution runs through durable medical equipment intermediaries in the United States and direct hospital procurement committees in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as respiratory therapist workforce attrition collapses centralized clinical capacity and disperses demand across outpatient pulmonology practices and direct-to-patient channels, creating service and logistics niches that national brands under-serve.
For Market Incumbents: Secure cystic fibrosis center procurement consolidation through sub-three-micrometer MMAD performance documentation and ISO 27427 compliance investment. Defend against vibrating mesh substitution by embedding compressor systems into multi-drug adherence protocols. Backward integration into precision motor production reduces East Asian supplier concentration risk and stabilizes margin capture in portable segments. For New Entrants and Emerging Players: Remote patient monitoring integration gaps expose white space for connected nebulizers transmitting adherence data to Texas and Florida pulmonology practices bypassing traditional intermediaries. Target tier-3 Indian cities with ruggedized compressor designs optimized for unreliable grid infrastructure. Pursue CDSCO registration pathways for cost-optimized portable units assembled in Maharashtra corridors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clinical specialty firms with validated aerosol characterization over diversified conglomerates competing on home-care portfolio breadth. Five-to-ten year viability hinges on consumable medication partnership structures that recapture margins lost to unbundled service contracts. Monitor EPA hydrofluorocarbon phase-down enforcement as inflection signal for metered-dose inhaler-to-nebulizer substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathways for battery-powered designs face extended electrical safety validation timelines. |
| CE Marking Pathway | EU MDR clinical evidence requirements impose costly post-market surveillance on active therapeutic devices. |
| Hospital System Partnership | GPO-negotiated device pricing now excludes technical support provisions previously bundled. |
| Software Companion Development | Telehealth reimbursement codes create incentive alignment for connected nebulizers transmitting adherence data. |
| Reimbursement Strategy | Medicare durable medical equipment coverage determinations shape patient access economics and channel investments. |
Methodological Framework
Desk research of FDA 510(k) filings, CMS reimbursement code databases, and ISO 27427 performance benchmarking revisions preceded structured interviews with respiratory therapy directors, hospital GPO contracts managers, biomedical engineers, and durable medical equipment suppliers. Secondary validation drew from hospital procurement databases, Medicare claims data, and EU MDR clinical evidence documentation. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored volume and value estimates.
Variance decomposition across product type, end-user channel, technology mechanism, and therapeutic application dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro demand drivers including COPD prevalence demographics and respiratory therapist workforce trends. Modeled inputs incorporated EPA hydrofluorocarbon phase-down enforcement schedules and CMS coverage determination timelines.
Material uncertainties — regulatory review backlogs, supply chain disruption severity, and reimbursement policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions documented in base-case parameterization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Intrauterine Devices Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Canada Minimally Invasive Surgery Devices Market
Medical Devices
TMJ Implants Market
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
Electrosurgery Devices Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Ultrasonic Medical Nebulizer Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Global Portable Oxygen Concentrators Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Pulse Lavage Market