
 Middle Ear Implants Market | 2026-2036
Middle Ear Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle Ear Implants Market Intelligence
The shift towards outcome-based reimbursement models from healthcare payors is reconfiguring market access for high-cost devices. This structure favors established players with strong clinical evidence portfolios. Cochlear Limited leverages its global distribution network to maintain a dominant market position. MED-EL Medical Electronics differentiates through its focus on broad implant candidacy and diverse electrode designs. Sonova Holding AG competes by integrating its hearing aid and implant technologies across its portfolio.
Middle ear implants are surgically placed devices that treat moderate to severe hearing loss by directly stimulating the ossicles or the round window. These systems often utilize an external audio processor and an internal component with a piezoelectric or electromechanical transducer. Active Middle Ear Implants, which use powered transducers, are gaining share over older passive implant technologies due to superior performance. The treatment of sensorineural hearing loss represents a significant growth area, expanding beyond traditional conductive loss cases.
Device approval and market access are governed by stringent regulatory frameworks. In the United States, the FDA mandates rigorous pre-market approval for these Class III devices, while in Europe, the CE marking process under the Medical Device Regulation (MDR) sets high standards. These regulations require extensive clinical data to prove both safety and efficacy. The key strategic decision for manufacturers involves navigating these divergent regulatory pathways while managing innovation pipelines.
Market Dynamics
The central dynamic in the middle ear implants market is the tension between rapid technological advancements in transducer and processing technologies and the increasingly stringent, divergent regulatory frameworks of bodies like the FDA and EMA, which govern market access.
Growth Catalysts
- Digital Signal Processing:Advances in DSP algorithms enhance sound clarity and speech recognition, broadening the patient candidacy for implants beyond what traditional hearing aids can offer.
- Sensorineural Loss Application:The expanding use of middle ear implants to treat certain types of sensorineural hearing loss, not just conductive loss, is opening a significant new patient population within specialized audiology centers.
- Aging Demographics:Developed healthcare markets, particularly in Germany and Japan, face a growing elderly population with age-related hearing loss, creating a sustained demand base for advanced hearing solutions.
Market Restraints
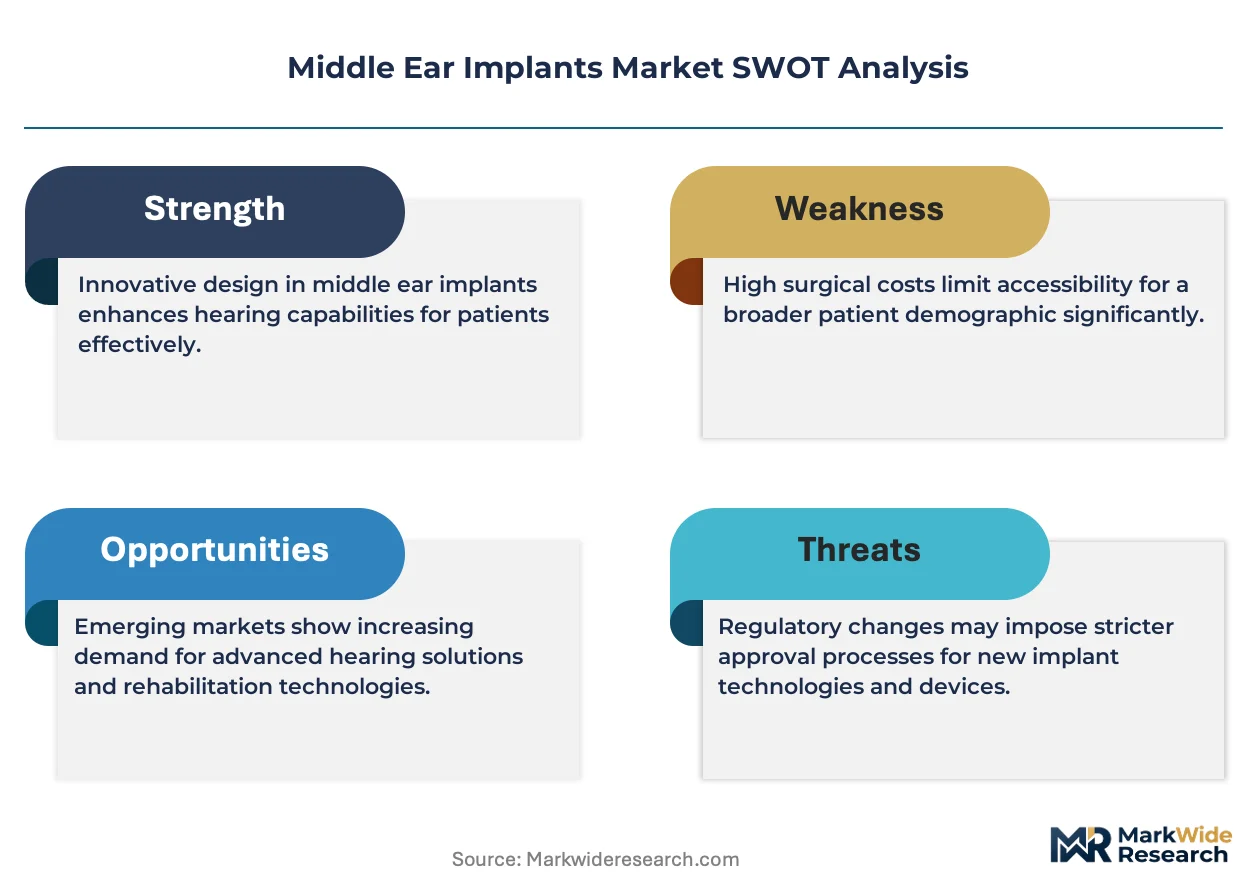
- High Procedure Cost:The substantial cost of the implant device, combined with specialized surgical fees, restricts patient access in healthcare systems with limited reimbursement policies for high-cost prosthetic devices.
- Stringent Regulatory Hurdles:The FDA's rigorous pre-market approval (PMA) pathway and Europe's Medical Device Regulation (MDR) create long development timelines and high compliance costs, acting as significant barriers for new entrants.
- Conventional Hearing Aid Efficacy:The performance of high-power, behind-the-ear digital hearing aids continues to improve, presenting a powerful, non-invasive, and lower-cost substitution threat for many potential implant candidates.
Strategic Opportunities
- Fully Implantable Systems:Developing devices where all components, including the microphone and power source, are placed under the skin addresses a primary user desire for cosmetic invisibility and lifestyle convenience.
- Wireless Connectivity Integration:Incorporating Bluetooth and other wireless protocols allows for direct audio streaming from smartphones and other devices, a key feature differentiator that enhances user experience.
- Emerging Market Penetration:Targeting countries with expanding private healthcare infrastructure and a growing middle class, such as Brazil and South Korea, offers new avenues for market growth beyond saturated developed nations.
Industry Challenges
- Surgical Training Gaps:A limited number of otologic surgeons possess the specialized training required for the precise placement of middle ear implant transducers, constraining the geographic availability of the procedure.
- Post-Market Surveillance Demands:Meeting the extensive post-market clinical follow-up (PMCF) requirements under regulations like the EU's MDR is a resource-intensive challenge for manufacturers.
- Interoperability with Diagnostics:Ensuring seamless compatibility of implant programming software with the diverse range of audiometric and diagnostic equipment used in clinics worldwide remains a persistent technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle Ear Implants Market |
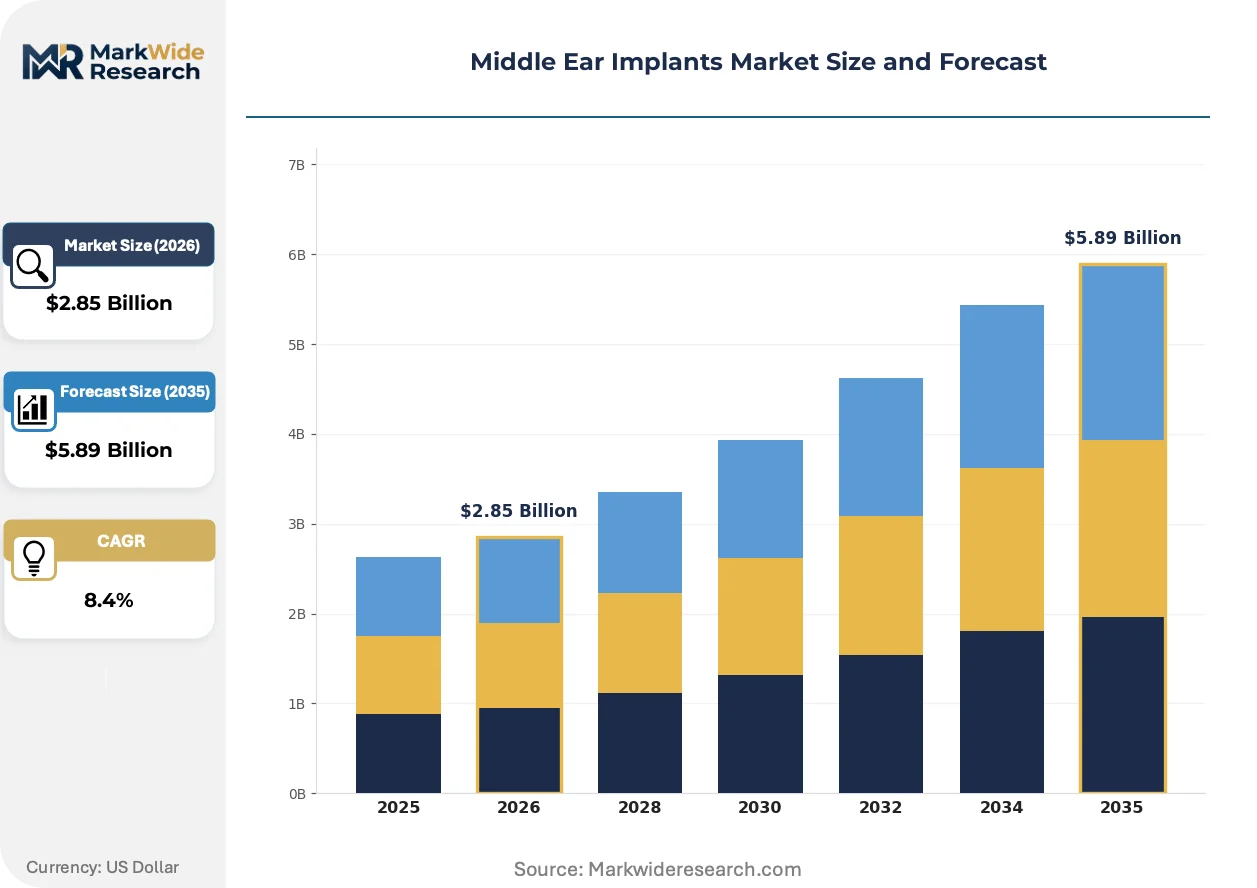
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ossicular Replacement Prosthesis, Cochlear Implants, Middle Ear Prosthesis, Bone Conduction Implants, Active Middle Ear Implants Application: Chronic Otitis Media, Otosclerosis, Conductive Hearing Loss, Mixed Hearing Loss, Sensorineural Hearing Loss End User: ENT Clinics, Audiology Centers, Specialized Hearing Institutes, Ambulatory Surgical Centers Technology: Electromechanical Implants, Hydraulic Systems, Piezoelectric Devices, Passive Implants, Digital Signal Processing |
| Companies Covered | Cochlear Limited, MED-EL Medical Electronics, Advanced Bionics, Envoy Medical, Sonova Holding AG, Demant A/S, Oticon Medical, Nurotron Biotechnology, Ototronix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle Ear Implants Market Strategic Shifts & Innovations
The market's evolution is defined by the dual pressures of miniaturization in electronics and a clinical evidence mandate from regulators. This combination is accelerating the development of more sophisticated, data-backed, and less obtrusive implantable hearing solutions for an expanding patient base.
Piezoelectric transducers provide the core mechanism for converting electrical signals into precise mechanical vibrations to stimulate the middle ear structures. Active Middle Ear Implant systems are rapidly adopting this technology for its power efficiency and high-fidelity sound reproduction. This innovation is rendering obsolete older, bulkier electromagnetic designs that offered inferior performance and had greater power consumption requirements.
Europe's Medical Device Regulation (MDR) has significantly elevated the requirements for placing and maintaining devices on the market. The regulation compels manufacturers of Class III devices, such as middle ear implants, to provide more robust clinical evidence of safety and performance. Device makers targeting the EU are most affected, being forced to increase investment in long-term clinical follow-up studies to retain their CE marking.
Patient expectations are shifting toward greater discretion and integration with personal technology. This demand for less conspicuous external components and direct connectivity to smartphones is disrupting the traditional device design paradigm, which prioritized functional restoration above all else. This trend is most visible in the competitive United States and German markets, where lifestyle and aesthetic factors heavily influence patient and clinician choice.
Middle Ear Implants Market Segmentation
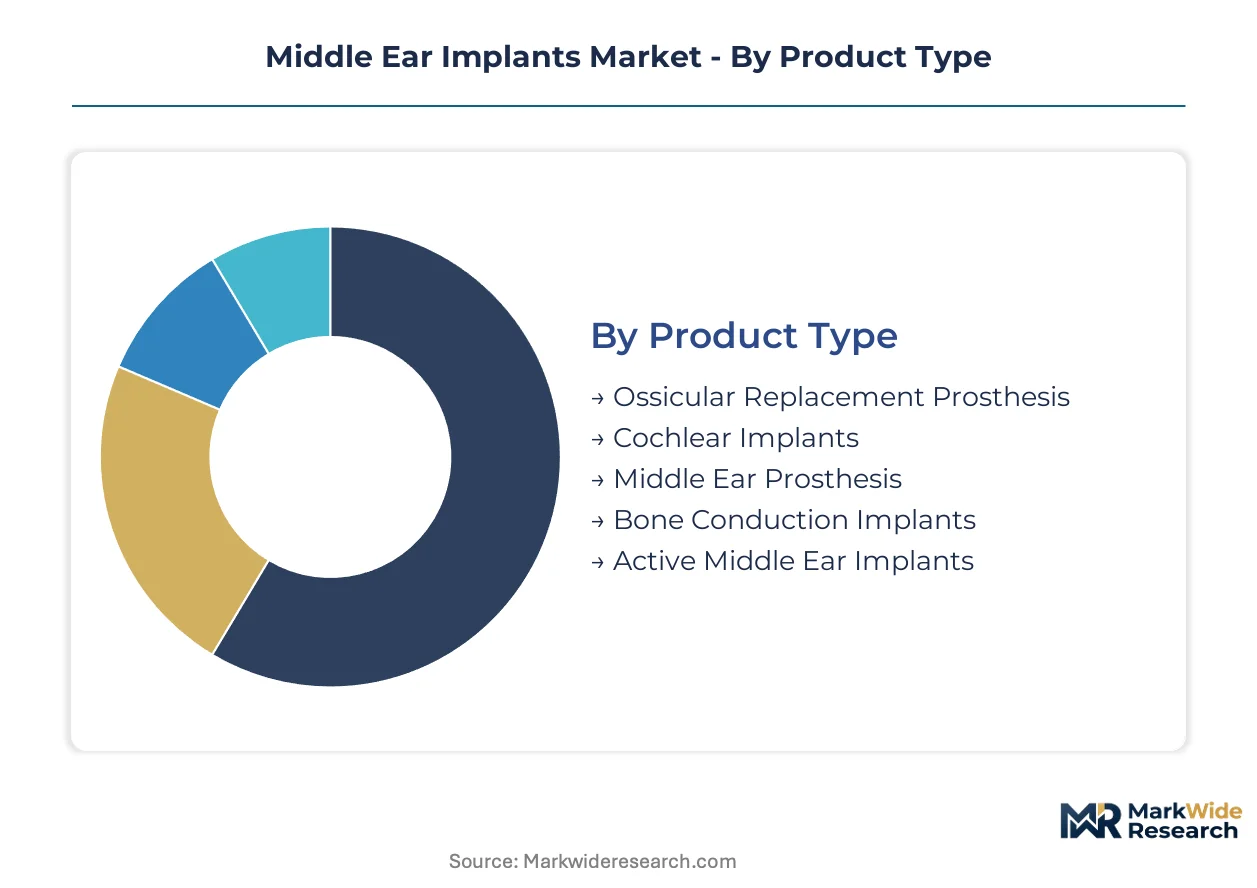
Understanding the segmentation of the middle ear implants market reveals the specific product innovations, clinical applications, and end-user environments driving market evolution. This granular view helps identify areas of concentrated demand and technological advancement across diverse patient needs.
Product Type:
The product type dimension delineates the various implantable devices available for hearing restoration.
- Active Middle Ear Implants:These devices employ powered transducers, often piezoelectric, to directly stimulate ossicles or the round window, offering superior performance and gaining share in developed healthcare markets like the United States.
- Cochlear Implants:Surgically implanted electronic devices bypass damaged parts of the inner ear, directly stimulating the auditory nerve; demand concentrates in specialized audiology centers for severe to profound sensorineural hearing loss.
- Ossicular Replacement Prosthesis:These prostheses replace damaged or diseased ossicles, restoring sound conduction to the inner ear.
- Bone Conduction Implants:These systems transmit sound vibrations through the bone to the inner ear, suitable for conductive or mixed hearing loss.
- Middle Ear Prosthesis:This category encompasses a range of devices designed to reconstruct or replace middle ear structures.
Ossicular Replacement Prosthesis holds installed capacity. Active Middle Ear Implants is rotating up the share rankings.
Application:
The application scope details the specific audiologic conditions addressed by these implant technologies.
- Sensorineural Hearing Loss:This application involves damage to the inner ear or auditory nerve, representing a significant growth area as implants expand beyond traditional conductive loss cases, particularly in Germany.
- Conductive Hearing Loss:This condition results from problems with the outer or middle ear, where implants directly stimulate the ossicles, maintaining a foundational patient population.
- Chronic Otitis Media:Middle ear implants can address hearing loss resulting from long-term inflammation or infection of the middle ear.
- Otosclerosis:This condition involves abnormal bone growth in the middle ear, which can be treated with ossicular replacement or other implants.
- Mixed Hearing Loss:This category involves a combination of both conductive and sensorineural components, requiring versatile implant solutions.
Sensorineural Hearing Loss treatment is expanding most quickly. Conductive Hearing Loss applications remain foundational.
End User:
Customer type differentiation highlights the primary healthcare facilities administering middle ear implant procedures.
- Specialized Hearing Institutes:These institutions offer comprehensive audiological services and specialized surgical expertise, driving demand for advanced implants in regions like the United States.
- Audiology Centers:These centers focus on diagnosing hearing loss and fitting devices, serving as primary points of patient referral and post-implant care.
- ENT Clinics:Ear, Nose, and Throat clinics provide initial diagnosis and surgical consultations for various ear conditions, including implant candidacy.
- Ambulatory Surgical Centers:These facilities perform outpatient surgical procedures, offering a cost-effective setting for less complex implant surgeries.
Specialized Hearing Institutes are central to complex implant procedures. Ambulatory Surgical Centers are gaining share for less complex interventions.
Technology:
The underlying technology classification reflects the diverse engineering principles powering modern middle ear implants.
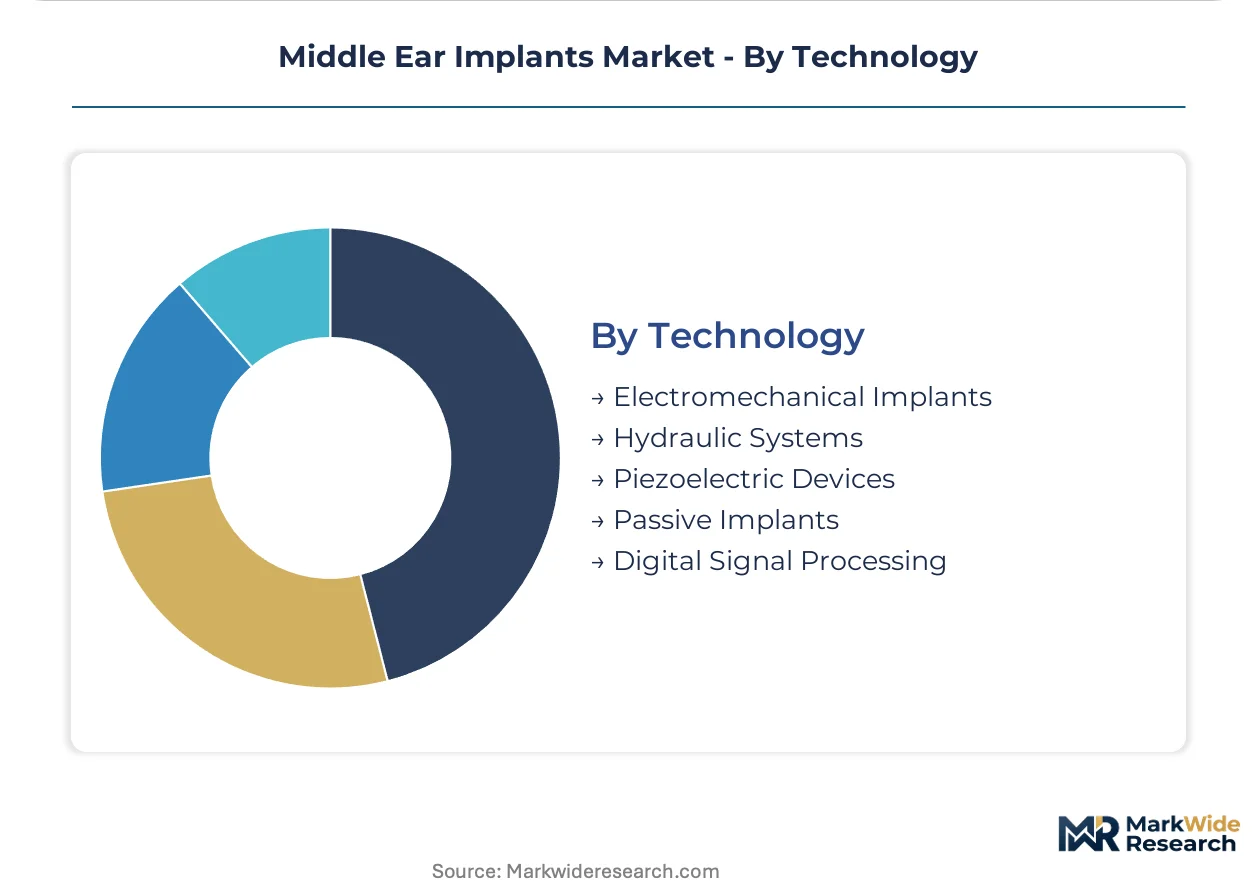
- Piezoelectric Devices:These transducers convert electrical signals into precise mechanical vibrations, representing a core mechanism for active middle ear implants due to their power efficiency and high-fidelity sound reproduction, particularly in advanced devices.
- Digital Signal Processing:Advances in DSP algorithms enhance sound clarity and speech recognition, broadening patient candidacy and improving user experience across all implant types.
- Electromechanical Implants:These systems use electromagnetic forces to vibrate middle ear structures, representing an earlier generation of active implant technology.
- Passive Implants:These devices do not contain active electronic components and rely on sound transmission through mechanical means.
- Hydraulic Systems:Some experimental or niche implant designs incorporate hydraulic principles for sound transmission.
Piezoelectric Devices are rapidly displacing older technologies. Digital Signal Processing capabilities are continuously advancing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global middle ear implants market exhibits varying dynamics based on each region's capacity for advanced medical device manufacturing versus its reliance on imports. Developed nations often lead in both innovation and procurement, whereas emerging economies prioritize expanding access and building local infrastructure. This balance significantly influences market penetration and technological adoption rates across diverse healthcare systems.
United States
Demand for middle ear implants in the United States stems from a robust healthcare infrastructure and a high prevalence of age-related hearing loss. The FDA's rigorous pre-market approval (PMA) pathway ensures high safety and efficacy standards for these Class III devices. Specialized audiology centers within major metropolitan areas like Boston continue to drive innovation and clinical adoption of advanced implant technologies.
Germany
Germany's market for middle ear implants is propelled by an aging demographic and strong demand for advanced solutions to sensorineural hearing loss. The CE marking process under the Medical Device Regulation (MDR) sets stringent requirements for device market access and ongoing post-market surveillance. Munich's medical technology cluster supports both research and manufacturing, fostering continuous advancements in implant design.
Japan
Japan experiences sustained demand for middle ear implants due to its rapidly aging population and a cultural emphasis on high-quality medical care. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees strict approval processes for new medical technologies, ensuring patient safety. Tokyo's numerous specialized clinics and research institutions contribute to the development and deployment of innovative hearing solutions.
Brazil
Brazil represents a significant opportunity for middle ear implant market expansion, driven by an expanding private healthcare sector and a growing middle class. ANVISA's device registration requirements are critical for manufacturers seeking to enter this burgeoning market. São Paulo's developing medical device industry is attracting investment, aiming to enhance local production and distribution capabilities for advanced implants.
Middle Ear Implants Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical sub-assemblies and advanced materials. The middle ear implants market is characterized by a tiered structure, with a few established global players dominating the full-system solutions segment. Strategic archetypes include comprehensive solution providers, specialized technology innovators, and regional distribution networks. Geographic expansion into high-growth emerging markets and continuous portfolio diversification represent dominant competitive moves.
Global leaders such as Cochlear Limited leverage extensive distribution networks to maintain their market presence across developed healthcare systems. MED-EL Medical Electronics exemplifies a focus on broad implant candidacy and diverse electrode designs, differentiating its offerings through clinical versatility. Sonova Holding AG occupies a position as a diversified hearing care company, integrating its hearing aid and implant technologies for a comprehensive portfolio approach.
| Leading Market Players |
|---|
| Cochlear Limited |
| MED-EL Medical Electronics |
| Advanced Bionics |
| Envoy Medical |
| Sonova Holding AG |
| Demant A/S |
| Oticon Medical |
| Nurotron Biotechnology |
| Ototronix |
| Others |
Cost & Logistics Intelligence
High capacity utilization in specialized piezoelectric component manufacturing facilities drives supplier behavior and pricing posture for advanced middle ear implants. This utilization directly impacts the cost structure for device manufacturers.
Pricing Analysis
Industrial OEM buyers anchor a value-based pricing structure in the middle ear implants market. Price differentiation stems from demonstrated clinical efficacy, particularly FDA and CE marking, along with comprehensive after-sales support and surgeon training programs. Pricing pressure exhibits an upward trend, driven by intensive R&D investments and stringent regulatory compliance costs. Healthcare payors demonstrate high price sensitivity, balancing cost against long-term patient outcomes, while specialized hearing institutes prioritize device performance.
Supply Chain Analysis
Single-source vulnerability for specialized micro-components and piezoelectric materials presents a significant supply chain risk. Geographic supply concentration for high-precision manufacturing resides primarily in Germany, the United States, and Japan. The supply chain draws from a limited pool of highly specialized suppliers for piezoelectric ceramics and advanced micro-electronics. Distribution runs through a hybrid model, combining direct sales forces targeting specialized hearing institutes with regional distribution partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The middle ear implants market represents a high-growth disruption, driven by the rapid advancements in piezoelectric device technology and sophisticated digital signal processing. These innovations are expanding clinical applications and improving patient outcomes.
For Market Incumbents:Harden existing market positions by accelerating R&D into fully implantable systems, mitigating the threat from increasingly effective conventional hearing aids. Invest in robust clinical evidence portfolios to navigate stringent regulatory hurdles like Europe's MDR and FDA's PMA pathway. Deepen partnerships with specialized audiology centers to ensure continuous feedback and strong clinical adoption. Focus on miniaturization and power efficiency in next-generation device designs.
For New Entrants and Emerging Players:Establish a beachhead in emerging markets like Brazil and South Korea, where private healthcare infrastructure is expanding. Target niche applications within specific sensorineural hearing loss types, leveraging advanced piezoelectric transducer designs. A viable go-to-market angle involves offering cost-effective, high-performance solutions for less complex interventions in Ambulatory Surgical Centers. This approach allows for focused resource deployment.
For Investors and Strategic Acquirers:Capital is best deployed toward specialized technology innovators possessing strong intellectual property in piezoelectric devices or advanced digital signal processing. The market demonstrates long-term viability, driven by aging demographics and expanding clinical applications over the next decade. Monitor regulatory approvals for fully implantable systems as a key inflection indicator. Prioritize companies with established clinical data and clear pathways to market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Expansion | Broaden patient candidacy for sensorineural hearing loss, expanding market reach. |
| Regulatory Pathway Optimization | Accelerate FDA PMA and EU MDR compliance for faster market access. |
| Wireless Connectivity Integration | Enhance user experience and device differentiation with direct smartphone streaming. |
| Emerging Market Entry | Capture new patient populations in Brazil and South Korea, diversifying revenue streams. |
| Miniaturization R&D | Develop cosmetically invisible, fully implantable devices addressing patient aesthetic demands. |
Research Approach
A standing panel of otologic surgeons, audiologists, biomedical engineers, and healthcare payor representatives provided ongoing calibration for market sizing and trend validation. This approach combined in-depth primary interviews with extensive secondary validation from sources such as FDA filings, EMA submissions, and medical device registries. Bottom-up and top-down triangulation ensured data integrity and consistency across all segments.
Scenario-bracketing across optimistic, baseline, and conservative trajectories informed the quantitative forecasting framework. The analytical framework modeled market dynamics across the analysis window, segmenting by product type, application, end user, technology, and regional regulatory frameworks. Compound annual growth rates were derived from regression analysis of historical data and projected impact of identified growth catalysts. Key inputs included age-related hearing loss prevalence and healthcare expenditure growth.
Stress conditions across regulatory policy shifts, technological breakthroughs, and reimbursement policy changes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding these variables, acknowledging potential revisions from unforeseen global economic downturns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Nebulizer Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Italy Aesthetic Devices Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Surgical Display Market
Medical Devices
Spine Surgery Robots Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Bedwetting Alarm Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Neuro Medical Devices Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
Drug Delivery Solutions Market