
 Nephrostomy Catheters Market | 2026-2036
Nephrostomy Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Nephrostomy Catheters Market Intelligence
A widening capability gap between vertically integrated manufacturers and assembly-only suppliers is reorganizing competitive tiers in nephrostomy catheter supply. Cook Medical leverages in-house polymer extrusion to control material consistency across its percutaneous portfolio. Becton Dickinson and Company anchors its position through sterilization infrastructure that smaller competitors cannot replicate at scale.
Nephrostomy catheters are silicone or polyurethane drainage tubes inserted percutaneously into the renal pelvis to decompress obstructed urinary systems, typically ranging 8-14 French in diameter with pigtail retention curves. Percutaneous designs dominate procedural volume due to established interventional radiologist familiarity and lower complication profiles in stone obstruction cases. Double-J configurations command premium positioning in urine obstruction applications where internal stenting replaces external drainage. Thin-walled variants are gaining fastest in outpatient clinic settings where smaller access tracts reduce recovery time.
The FDA's 510(k) clearance framework and ISO 13485 quality management standards govern device safety and manufacturing consistency, while the EU MDR's clinical evidence requirements are extending certification timelines for European market entry. The EPA regulates ethylene oxide sterilization emissions that most catheter manufacturers depend upon, pressuring facility upgrades or alternative sterilization adoption. Stakeholders must monitor how CMS reimbursement adjustments for interventional nephrology procedures reshape site-of-service economics between hospitals and ambulatory surgery centers.
Market Dynamics
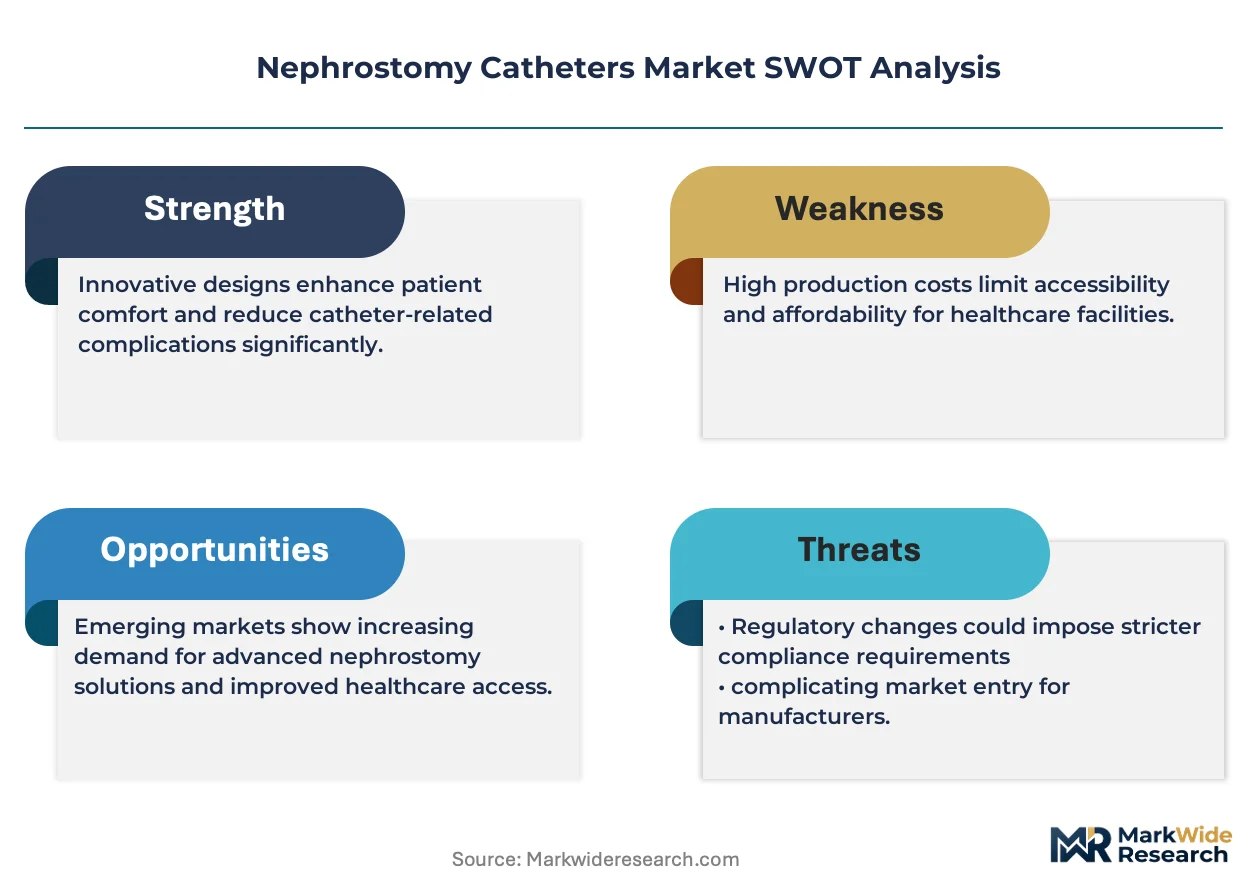
Site-of-service migration from inpatient to ambulatory settings is compressing reimbursement rates and forcing manufacturers to engineer catheter systems compatible with lower-acuity environments without sacrificing clinical performance.
Growth Catalysts
- Stone Disease Prevalence:Rising incidence of kidney stones among aging populations in the United States sustains procedural volume expansion in hospital interventional suites.
- FDA 510(k) Modernization:Streamlined clearance pathways for urological devices accelerate time-to-market for iterative catheter designs with enhanced retention mechanisms.
- Silicone Material Advances:Improved biocompatibility and reduced encrustation rates in next-generation silicone formulations extend indwelling duration and lower revision frequency.
Market Restraints
- Ethylene Oxide Dependency:EPA emissions regulations constrain sterilization capacity, creating bottlenecks for manufacturers lacking alternative validation infrastructure.
- Polymer Supply Concentration:Medical-grade silicone and polyurethane feedstock sourcing clusters in East Asian chemical manufacturing zones, exposing supply chains to geopolitical friction.
- Double-J Stent Substitution:Internal drainage systems eliminate external catheter dependency in select ureteral obstruction cases, capping addressable procedure growth.
Strategic Opportunities
- Ambulatory Surgery Center Penetration:CMS reimbursement parity expansion creates procurement openings for catheter kits optimized for same-day discharge protocols.
- Antimicrobial Coating Convergence:Integration of silver-ion and antibiotic-eluting technologies with standard catheter platforms commands premium positioning in infection-prevention contracts.
- Outpatient Clinic Channel:Thin-walled percutaneous designs sized for office-based ultrasound guidance unlock volume in urology group practices seeking procedural autonomy.
Industry Challenges
- Interventional Radiology Training Pipeline:Fellowship program capacity constraints limit operator availability to support procedural volume targets in secondary markets.
- EU MDR Clinical Evidence Burden:Extended certification timelines for European market entry delay revenue recognition and strain regulatory affairs staffing.
- Legacy EHR Integration:Catheter tracking and outcome documentation systems require costly interface development with hospital information technology architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nephrostomy Catheters Market |
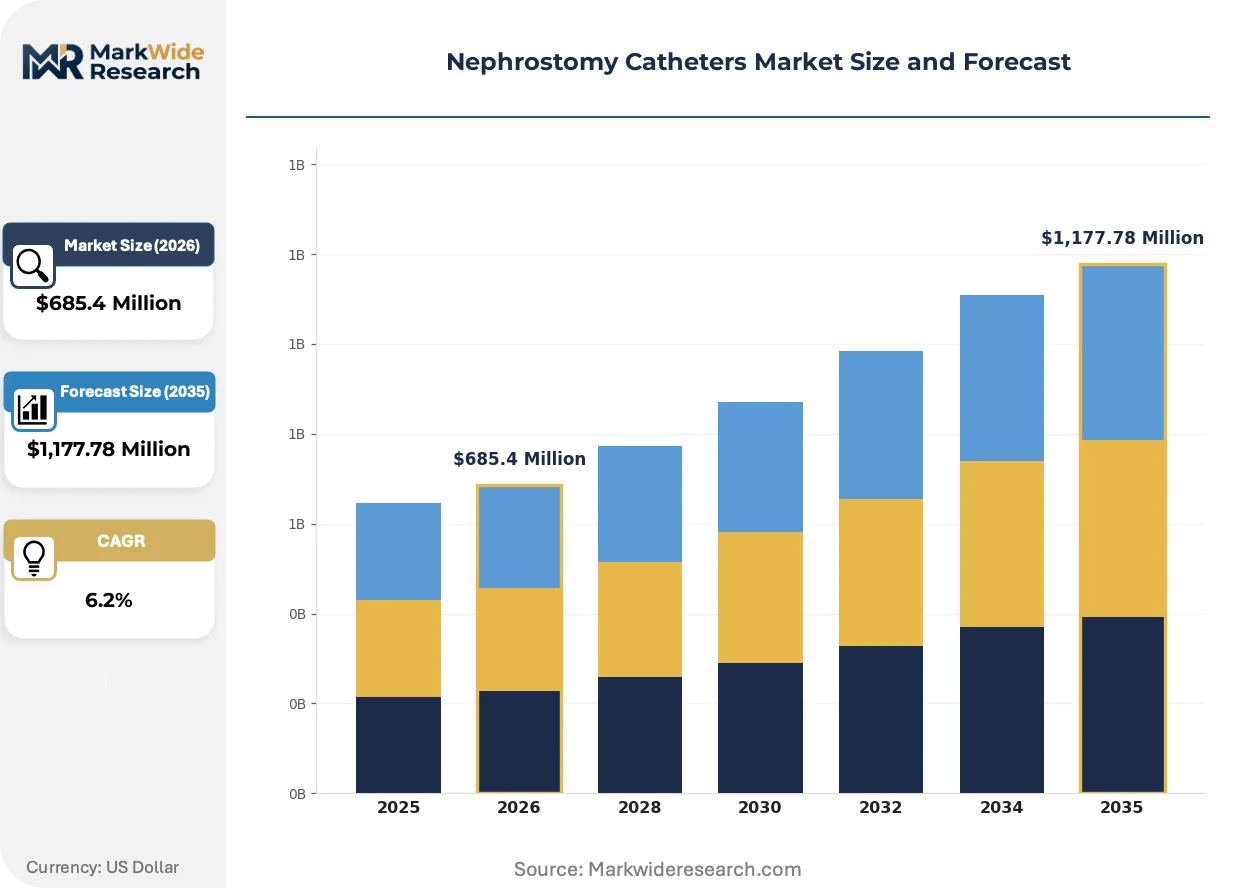
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Percutaneous, Double-J, Ureteral, Thin-Walled Application: Kidney Stones, Urine Obstruction, Pyonephrosis, Renal Failure End User: Hospitals, Clinics, Dialysis Centers, Home Care Delivery Mode: Traditional, Mobile Delivery, Telemedicine, Self-Management |
| Companies Covered | Cook Medical, Boston Scientific Corporation, Becton Dickinson and Company, Teleflex Incorporated, B. Braun SE, Coloplast Group, Cardinal Health, ARGON MEDICAL, Envaste Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nephrostomy Catheters Market Strategic Shifts & Innovations
Material science breakthroughs and sterilization technology pivots are redefining performance benchmarks while regulatory frameworks on both sides of the Atlantic force evidence-generation investments that reshape competitive economics.
Antimicrobial-impregnated catheter substrates are decomposing the traditional infection-risk calculus that governed product selection. Hospital infection control committees now specify silver-alloy or antibiotic-coated platforms for immunocompromised patient cohorts. This shift is compressing commodity pricing power for uncoated alternatives and rewarding manufacturers with validated elution profiles.
EU MDR clinical evidence requirements are extending certification timelines and forcing retrospective data collection from legacy device portfolios. European notified bodies now demand post-market surveillance infrastructure that smaller manufacturers cannot resource. Catheter suppliers with established European registries capture accelerated market access while competitors face 18-24 month approval delays.
Bundle purchasing agreements are consolidating procurement authority within integrated delivery networks. Urology service line managers now negotiate multi-year catheter supply contracts spanning percutaneous, internal, and accessory categories. This concentration is most visible in United States health systems exceeding 50 hospitals, where standardization mandates override individual physician preference.
Nephrostomy Catheters Market Segmentation
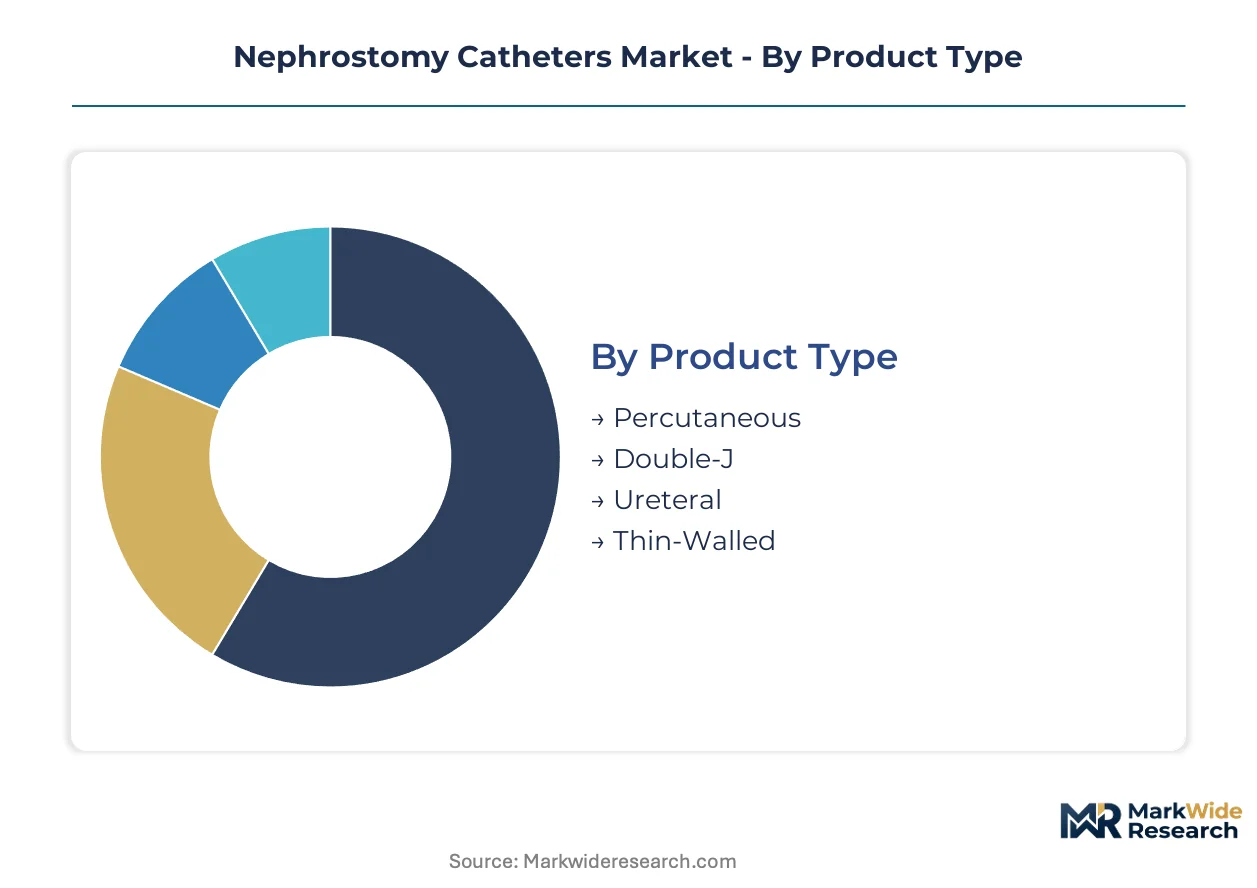
Catheter selection in nephrostomy procedures hinges on obstruction etiology, anatomical access constraints, and care setting capabilities. Segmentation reveals where double-J internal stents displace external drainage systems, reshaping volume allocation across product categories.
Product Type:
Double-J stents exert the strongest substitution pressure on percutaneous designs, particularly in distal ureteral obstruction cases where internal drainage eliminates external catheter dependency.
- Percutaneous:Silicone or polyurethane tubes inserted through the flank into the renal pelvis, typically 8-14 French with pigtail retention curves. Hospital interventional radiology suites in the United States generate the highest procedural volumes, driven by stone disease prevalence and established operator training pathways.
- Double-J:Internal stents spanning renal pelvis to bladder that eliminate external drainage apparatus. Urology group practices in Florida and Texas are expanding same-day stent placement, compressing external catheter demand in select obstruction presentations.
- Ureteral:Specialized configurations for ureter-specific anatomical challenges.
- Thin-Walled:Reduced-diameter variants optimized for ultrasound-guided office placement.
Percutaneous designs anchor the volume base while thin-walled variants gain share at the steepest rate.
Application:
Cost tier differentiation separates acute stone intervention from chronic renal failure management, with reimbursement intensity varying across clinical presentations.
- Kidney Stones:Acute decompression following failed expulsive therapy or obstructing calculus. United States ambulatory surgery centers are capturing migration from inpatient settings, demanding catheter kits compatible with same-day discharge protocols.
- Urine Obstruction:Malignant or benign ureteral stricture management. Academic medical centers in California and New York drive technology evaluation for complex obstruction cases.
- Pyonephrosis:Infected hydronephrosis requiring urgent drainage.
- Renal Failure:Chronic decompression in progressive kidney disease.
Kidney stone applications anchor the volume base while urine obstruction management climbs the fastest as internal stent technology advances.
End User:
Site-of-service economics restructure procurement authority, with integrated delivery networks consolidating purchasing across hospital and non-hospital settings.
- Hospitals:Inpatient and emergency department placement with full interventional radiology support. Major health systems exceeding 50 facilities negotiate multi-year supply agreements spanning catheter categories, overriding individual physician preference.
- Clinics:Office-based ultrasound-guided placement in urology practices. Large group practices in Arizona and Nevada pursue procedural autonomy through thin-walled catheter adoption.
- Dialysis Centers:Chronic access management in end-stage renal disease populations.
- Home Care:Long-term external drainage with nursing support.
Hospitals anchor the volume base while clinics expand most quickly as reimbursement parity enables site-of-service migration.
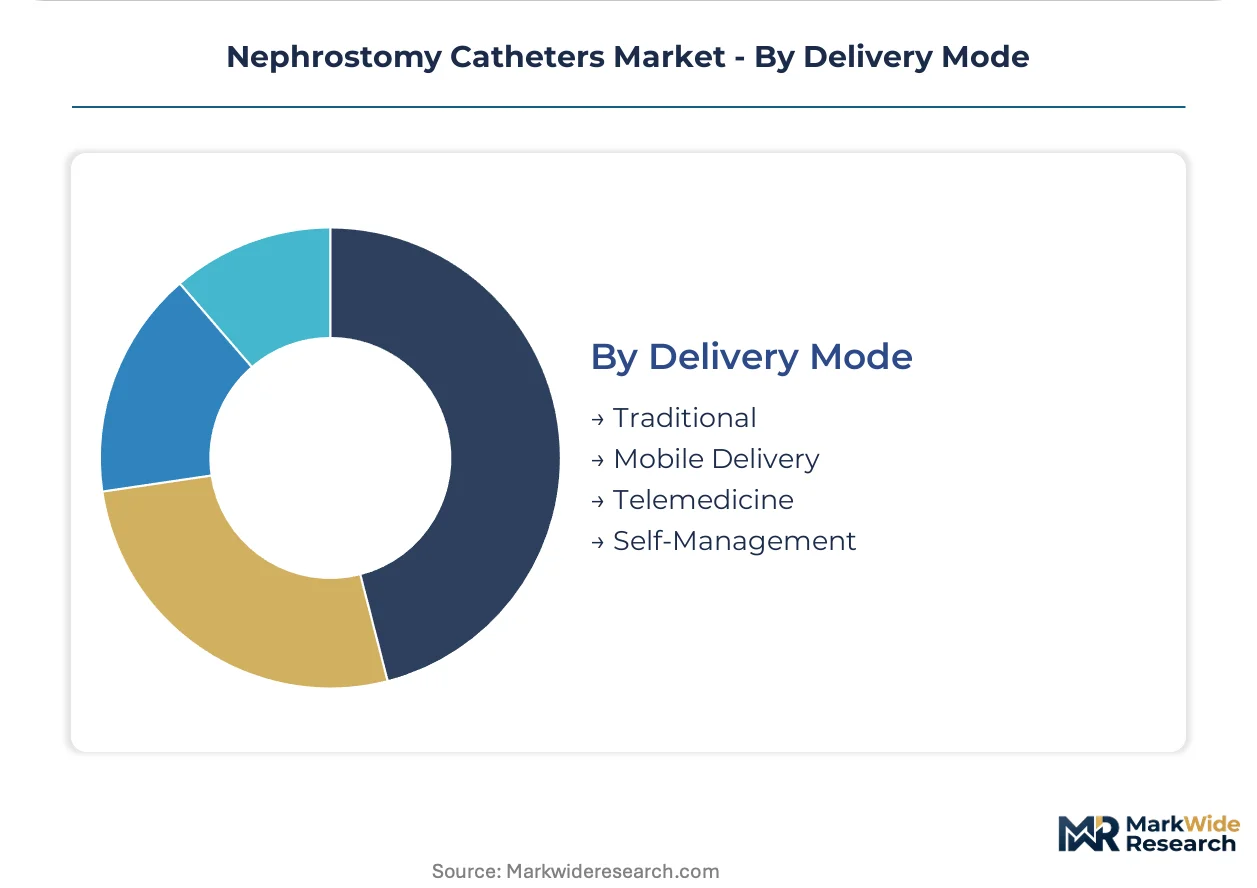
Delivery Mode:
Maturity gradients separate established procedural workflows from emerging remote care models, with regulatory validation lagging technology availability.
- Traditional:In-person placement with fluoroscopic or ultrasound guidance. Hospital-based interventional radiology departments maintain dominant procedural share, constrained by fellowship training pipeline capacity.
- Mobile Delivery:Portable imaging systems enabling bedside or nursing facility placement. Rural health systems in Montana and Wyoming deploy mobile units to extend geographic coverage.
- Telemedicine:Remote consultation and procedural planning.
- Self-Management:Patient-directed catheter maintenance education.
Traditional delivery anchors the volume base while mobile delivery gains share at the steepest rate as rural access expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds European benchmarks by margins exceeding thirty percent, reflecting reimbursement intensity and site-of-service economics that compress procurement budgets in Germany and France.
United States
Stone disease prevalence among aging populations drives procedural volume expansion in Florida and Texas ambulatory surgery centers. The FDA's 510(k) modernization for urological devices accelerates clearance timelines for iterative catheter designs. Academic medical clusters in California and New York evaluate complex obstruction technologies before broader adoption.
Germany
EU MDR clinical evidence requirements extend certification timelines and strain regulatory affairs staffing for manufacturers seeking European market entry. The country's national pharmaceutical regulator enforces post-market surveillance infrastructure that smaller suppliers cannot resource. Industrial concentration in Baden-Württemberg hosts sterilization facilities adapting to ethylene oxide emission constraints.
Japan
Aging demographics sustain interventional nephrology procedure growth in Tokyo and Osaka metropolitan hospitals. The PMDA maintains stringent quality management standards for imported medical devices. Kansai region medical device distributors consolidate procurement authority across prefectural health systems.
United Kingdom
NHS procurement frameworks standardize catheter specifications across integrated care systems, overriding individual physician preference. The MHRA operates post-Brexit regulatory pathways parallel to EU MDR requirements. London and Southeast England academic centers drive technology evaluation for malignant obstruction management protocols.
India
Domestic manufacturing incentives under the PLI scheme attract catheter assembly operations to Maharashtra and Gujarat medical device zones. The CDSCO streamlines import licensing for critical urological devices while strengthening local quality audits. Tamil Nadu hospital procurement is shifting toward value-engineered kits compatible with resource-constrained settings.
Nephrostomy Catheters Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated manufacturers commanding material consistency premiums while assembly-focused suppliers compete on kit pricing. The market structures around three tiers: premium innovators with captive polymer extrusion, mid-scale specialists with sterilization infrastructure advantages, and regional fabricators serving price-sensitive procurement. Consolidation pressures concentrate among mid-tier players lacking either R&D depth or geographic scale. Dominant competitive moves include backward integration into polymer feedstock and multi-year supply agreements with integrated delivery networks exceeding fifty facilities.
Among North American-based manufacturers, Cook Medical and Boston Scientific Corporation exemplify the technology leadership archetype through in-house production capabilities, while Becton Dickinson and Company anchors the sterilization infrastructure tier that smaller competitors cannot replicate at scale. These three entities represent distinct competitive positions: one emphasizing material science control, another clinical evidence generation, and the third regulatory compliance scale.
| Leading Market Players |
|---|
| Cook Medical |
| Boston Scientific Corporation |
| Becton Dickinson and Company |
| Teleflex Incorporated |
| B. Braun SE |
| Coloplast Group |
| Cardinal Health |
| ARGON MEDICAL |
| Envaste Limited |
| Others |
Cost & Logistics Intelligence
FDA 510(k) clearance tiers and ISO 13485 certification grades simultaneously gate supplier qualification and stratify price positioning in nephrostomy catheter procurement. Manufacturers bearing validated sterilization infrastructure and polymer extrusion capabilities capture premium positioning against assembly-only competitors.
Pricing Analysis
Configured-to-order pricing for antimicrobial-coated and patient-specific catheter configurations commands spreads exceeding standard percutaneous designs by substantial margins. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from integrated delivery networks. Cost compression in economy tiers intensifies as Asian assembly specialists penetrate procurement contracts. Ambulatory surgery centers exhibit highest price sensitivity while academic medical centers prioritize clinical performance over unit economics.
Supply Chain Analysis
Inventory cycles for medical-grade silicone and polyurethane feedstock extend lead times when geopolitical friction disrupts East Asian chemical manufacturing zones. Production gravity centers on China, Germany, and the United States for polymer extrusion and catheter finishing. Raw material dependencies encompass silicone elastomers, radiopaque barium sulfate, and antimicrobial silver-ion formulations. Single-source vulnerability concentrates in sterilization capacity constrained by EPA ethylene oxide emission regulations. Distribution runs through group purchasing organizations and integrated delivery network central procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as site-of-service migration from hospitals to ambulatory clinics creates procurement niches underserved by legacy supply structures. Thin-walled catheter demand from urology group practices rewards agile manufacturers with rapid configuration capabilities.
For Market Incumbents: Shield market position through backward integration into medical-grade polymer feedstock and sterilization infrastructure that smaller competitors cannot replicate. Double-J stent substitution threat demands accelerated antimicrobial coating R&D investment. Captive polymer extrusion capabilities defend margin structure against Asian assembly specialists.
For New Entrants and Emerging Players: Anchor in thin-walled percutaneous catheter segments where ultrasound-guided office placement protocols unlock urology group practice procurement. Arizona and Nevada clinics represent most penetrable geographic clusters. Reimbursement parity expansion enables direct-to-practice distribution models bypassing hospital GPO contracts.
For Investors and Strategic Acquirers: Carve-out targets emerge from mid-tier manufacturers lacking European MDR post-market surveillance infrastructure yet possessing validated catheter platforms. Long-term viability hinges on sterilization technology pivots and ambulatory-compatible product pipelines. EU MDR certification delays signal acquisition timing inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Validation | FDA 510(k) submissions for silver-ion platforms secure infection-prevention contract specifications. |
| Sterilization Infrastructure Expansion | Ethylene oxide alternative validation addresses EPA emission constraints limiting competitor capacity. |
| Ambulatory Surgery Center Partnership | CMS reimbursement parity creates procurement openings for same-day discharge catheter kits. |
| European MDR Registry Investment | Post-market surveillance infrastructure accelerates notified body approval timelines against delayed competitors. |
| Polymer Extrusion Backward Integration | In-house silicone production controls material consistency across percutaneous portfolio specifications. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with interventional radiologists, urology practice administrators, hospital purchasing committee members, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Across the analysis window, forecasts incorporate segmentation by product type, application, end user, and delivery mode alongside geographic regulatory cluster differentiation. CAGRs derive from procedural volume trajectories, reimbursement intensity shifts, and technology substitution rates. Silicone material advance curves and interventional radiology fellowship pipeline constraints feed directly into modeling assumptions.
Material uncertainties — EPA sterilization regulation amendments, EU MDR certification timeline extensions, polymer feedstock supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these structural factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Ablation Devices Market
Medical Devices
Batteries for Skin Patches Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Animal Ultrasound Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Prosthetic Liners Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Bone Conduction Hearing Devices Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
Global Foley Catheters Market