
 Asia-Pacific Ultrasound Probe Disinfection Market | 2026-2036
Asia-Pacific Ultrasound Probe Disinfection Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ultrasound Probe Disinfection Market Outlook
Modular subscription bundles pairing automated disinfection hardware with per-cycle consumables is repositioning procurement economics for Asia-Pacific hospitals. Ecolab Inc leverages its regional chemical supply chain to anchor recurring revenue streams across Southeast Asian hospital networks. Nanosonics Ltd specializes in ultraviolet-based trophon systems that dominate Australia's obstetrics and gynecology departments. Tristel Plc competes through chlorine dioxide wipe formats that occupy premium manual-disinfection niches in Japan's diagnostic imaging centers.
Asia-Pacific ultrasound probe disinfection encompasses technologies and protocols designed to eliminate microbial contamination on transducer surfaces between patient examinations, employing ultraviolet irradiation at 254 nanometers, hydrogen peroxide vapor at 30-35% concentration, or peracetic acid solutions achieving high-level disinfection within 7-10 minute cycles. The primary purpose centers on preventing cross-contamination during semi-critical ultrasound procedures involving mucous membrane or non-intact skin contact. Automated systems lead product-type revenue due to capital-intensive hospital installations and regulatory preference for validated, repeatable disinfection parameters. Chemical disinfectants sustain the broadest technology footprint across manual and semi-automated workflows, while ultraviolet platforms represent the fastest-growing technology segment driven by Japan's PMDA-cleared trophon deployments and Australia's stringent AS/NZS 4187 reprocessing standards.
Japan's PMDA and Australia's Therapeutic Goods Administration (TGA) enforce divergent validation requirements for high-level disinfection claims, compelling manufacturers to maintain separate clinical data packages for each national market. India's CDSCO and China's NMPA are tightening pre-market scrutiny of automated disinfection systems through amended medical device rules that now classify probe reprocessors as Class B or Class C instruments. Stakeholders must monitor harmonization gaps between ASEAN medical device directives and national pharmacopeial standards to anticipate compliance cost shifts and distribution pathway changes.
Market Dynamics
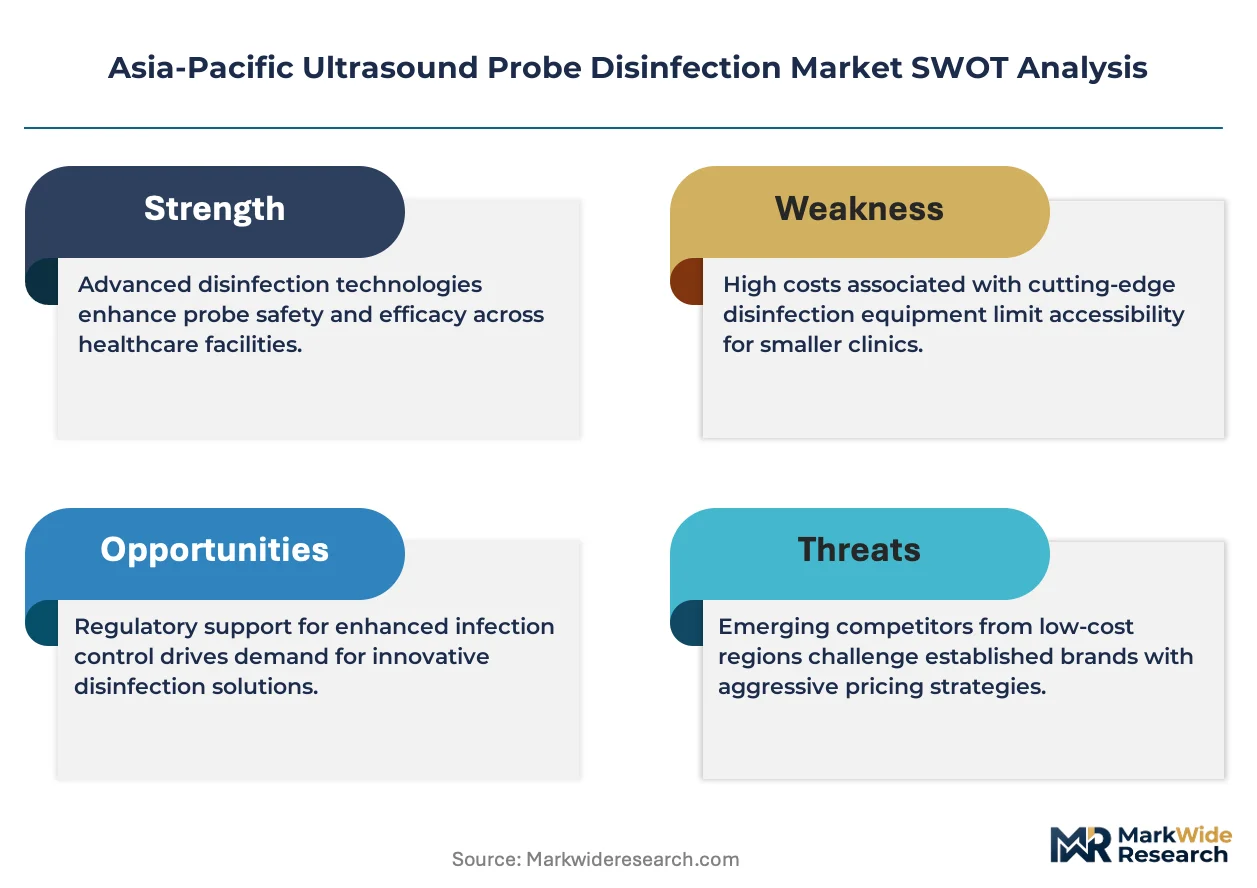
Japan's PMDA and Australia's TGA are tightening validation requirements for high-level disinfection claims, forcing manufacturers to maintain separate clinical data packages and accelerating capital migration toward automated ultraviolet platforms that satisfy divergent national standards.
Growth Catalysts
- Semi-critical device mandates:Japan's Ministry of Health, Labour and Welfare guidelines now require validated reprocessing protocols for intracavitary probes, compelling tertiary hospitals to replace manual wipe methods with traceable automated systems.
- Accreditation pressure:Australia's AS/NZS 4187 standards mandate documented high-level disinfection cycles for endocavitary transducers, driving replacement demand across obstetrics and gynecology departments in Queensland and New South Wales.
- Ultraviolet-C irradiation:PMDA-cleared trophon systems at 254 nanometers are displacing hydrogen peroxide vapor in Japanese diagnostic imaging centers due to shorter cycle times and reduced ventilation requirements.
Market Restraints
- Capital intensity barriers:Automated disinfection hardware requires upfront investment exceeding manual workflows by an order of magnitude, limiting penetration to tier-1 hospitals in India and Southeast Asia.
- Consumables supply concentration:Peracetic acid cartridges and proprietary hydrogen peroxide formulations concentrate supply among three chemical manufacturers, creating vulnerability to input cost volatility and import dependency.
- Technical compatibility limits:Existing ultraviolet chambers cannot accommodate linear array transducers exceeding 40 millimeters in width, restricting adoption in cardiology and vascular imaging segments.
Strategic Opportunities
- Vietnam and Indonesia hospital expansion:Greenfield tertiary facilities in Ho Chi Minh City and Jakarta lack legacy disinfection infrastructure, enabling direct-to-automated deployment without replacement cycle friction.
- Subscription bundling models:Hardware-plus-consumables contracts are penetrating Southeast Asian private hospital chains, converting capital expenditure into operational budgets and extending vendor lock-in duration.
- ASEAN harmonization momentum:The ASEAN Medical Device Directive's convergence pathway promises unified technical documentation requirements, potentially collapsing compliance cost duplication across Singapore, Thailand, and Malaysia.
Industry Challenges
- Biomedical engineering talent scarcity:Validation specialists capable of interpreting TGA and PMDA disinfection efficacy data concentrate in Sydney, Melbourne, and Tokyo, creating recruitment bottlenecks for regional distributors.
- Legacy probe incompatibility:Older transducer models from major ultrasound manufacturers lack standardized electrical connectors, requiring custom adapter development that extends automated system integration timelines.
- Dual certification burden:Separate clinical studies for ultraviolet dose validation must satisfy both Japan's PMDA and Australia's TGA, doubling time-to-market for new platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ultrasound Probe Disinfection Market |
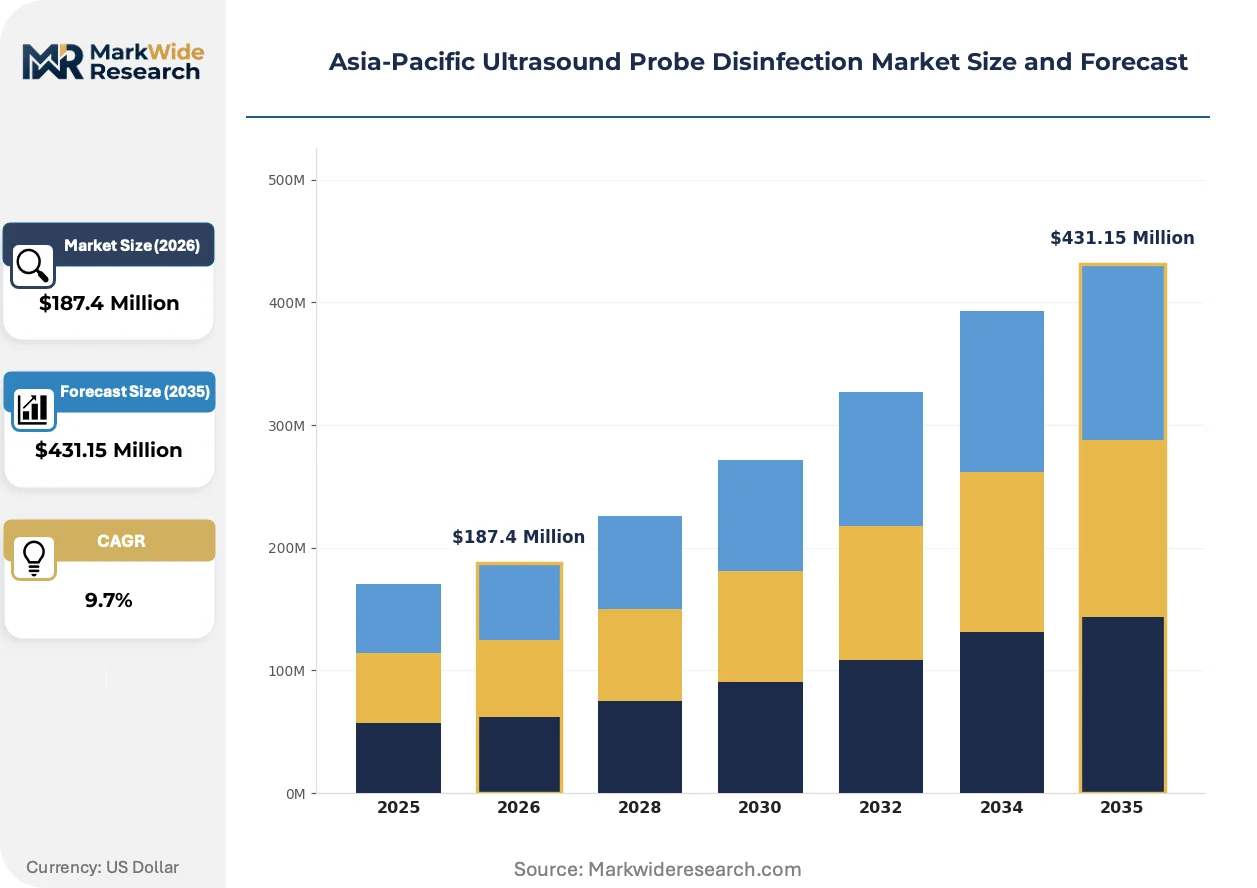
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Systems, Wipes, Solutions End User: Hospitals, Diagnostic Centers, Research Labs, Clinics Technology: Ultraviolet, Chemical Disinfectants, Heat Sterilization, Ozone Treatment Application: General Practice, Cardiology, Gynecology, Urology |
| Companies Covered | Ecolab Inc, Tristel Plc, CIVCO Medical Solutions, Germitec SAS, CS Medical LLC, Nanosonics Ltd, ASP (Fortive), STERIS, Steelco S.p.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ultrasound Probe Disinfection Market Strategic Shifts
Ultraviolet-C irradiation systems are compressing disinfection cycle durations while regulatory divergence between Japan and Australia is fragmenting product development roadmaps. These forces are reshaping competitive positioning around compliance agility rather than pure technical performance.
Ultraviolet-C systems operating at 254 nanometers deliver high-level disinfection within seven-minute cycles without residual chemical handling. Australian obstetrics departments in Sydney and Melbourne are adopting these platforms fastest due to AS/NZS 4187 documentation requirements. This technology is absorbing service revenue from chemical supply contracts by embedding consumables into closed-loop cartridge systems.
Japan's PMDA amended its medical device rules to classify automated probe reprocessors as Class C instruments requiring clinical efficacy studies. Manufacturers now face eighteen-month validation timelines versus six months under previous interpretations. Southeast Asian distributors are responding by prioritizing PMDA-cleared platforms for regional rollout, anticipating that ASEAN regulators will reference Japanese standards.
Hospital procurement departments are unbundling after-sales service from hardware contracts and tendering disinfection cycle validation separately. Australian tertiary networks in Queensland and Western Australia now engage third-party biomedical engineering firms for annual efficacy audits. This pattern is most visible in public hospital systems where budget accountability rules mandate competitive tendering for recurring services.
Asia-Pacific Ultrasound Probe Disinfection Market Segmentation
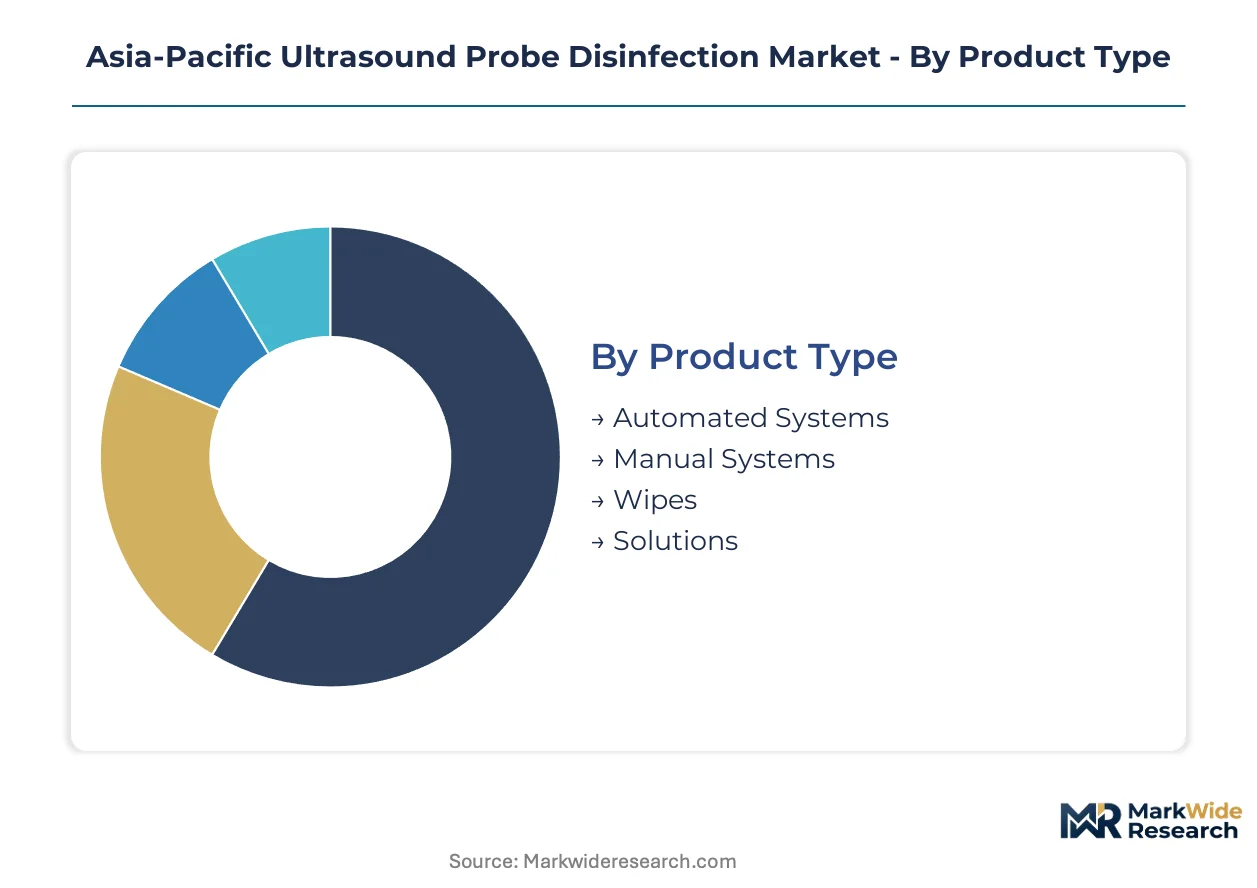
Segmentation in ultrasound probe disinfection reveals how capital intensity, clinical workflow integration, and regulatory validation requirements create distinct procurement pathways across Asia-Pacific healthcare networks. Understanding these divides enables targeted positioning against Japan's PMDA mandates, Australia's AS/NZS 4187 standards, and Southeast Asia's emerging accreditation frameworks.
Product Type:
Standardization dominates high-volume installations while customization persists in retrofit scenarios and specialty probe configurations.
- Automated Systems:Closed-loop disinfection chambers with validated cycle documentation and traceability logging. Australian tertiary hospitals in Queensland and New South Wales deploy these platforms to satisfy AS/NZS 4187 audit requirements for endocavitary probe reprocessing.
- Manual Systems:Semi-automated soak stations requiring operator intervention for chemical preparation and contact time verification. India's tier-1 hospitals in Mumbai and Delhi favor these units as interim upgrades ahead of full automation mandates from the national pharmaceutical regulator.
- Wipes:Pre-saturated chlorine dioxide or quaternary ammonium formulations for surface disinfection between patients.
- Solutions:Bulk peracetic acid or hydrogen peroxide concentrates requiring manual dilution and neutralization protocols.
Most installed capacity flows through Automated Systems. Expansion is steepest in Manual Systems as Southeast Asian hospitals bridge compliance gaps.
End User:
Procurement authority concentrates in centralized supply chains for large networks while fragmented purchasing characterizes standalone facilities.
- Hospitals:Multi-departmental procurement committees governing capital equipment and consumables contracts. Japan's Ministry of Health, Labour and Welfare guidelines are compelling tertiary centers in Tokyo and Osaka to replace manual workflows with traceable automated platforms.
- Diagnostic Centers:High-throughput imaging facilities prioritizing rapid cycle turnaround and minimal probe downtime. Independent operators in Bangkok and Kuala Lumpur favor ultraviolet systems with seven-minute disinfection cycles to maintain patient scheduling density.
- Research Labs:Academic medical centers requiring documented sterility assurance for clinical trial protocols.
- Clinics:Small-volume practices with limited capital budgets and space constraints for dedicated reprocessing rooms.
Revenue concentration sits with Hospitals. Volume expansion is climbing fastest in Diagnostic Centers as private imaging chains proliferate.
Technology:
Capital deployment favors platforms with regulatory pre-clearance while emerging modalities face extended validation timelines.
- Ultraviolet:254-nanometer irradiation chambers delivering high-level disinfection without chemical residuals or ventilation infrastructure. PMDA-cleared trophon deployments are accelerating across Japanese diagnostic imaging centers due to shorter cycle times and reduced facility modification requirements.
- Chemical Disinfectants:Peracetic acid, hydrogen peroxide vapor, and chlorine dioxide formulations achieving sporicidal efficacy. Australia's hospital networks maintain these systems for linear array transducers exceeding ultraviolet chamber dimensional limits.
- Heat Sterilization:Pressurized steam or dry-heat protocols restricted to non-electronic probe components and accessories.
- Ozone Treatment:Aqueous ozone generators with limited commercial penetration pending efficacy validation against mycobacteria and spores.
Technology adoption concentrates in Ultraviolet platforms. Investment momentum is building fastest in Chemical Disinfectants as compatibility solutions for oversized probes advance.
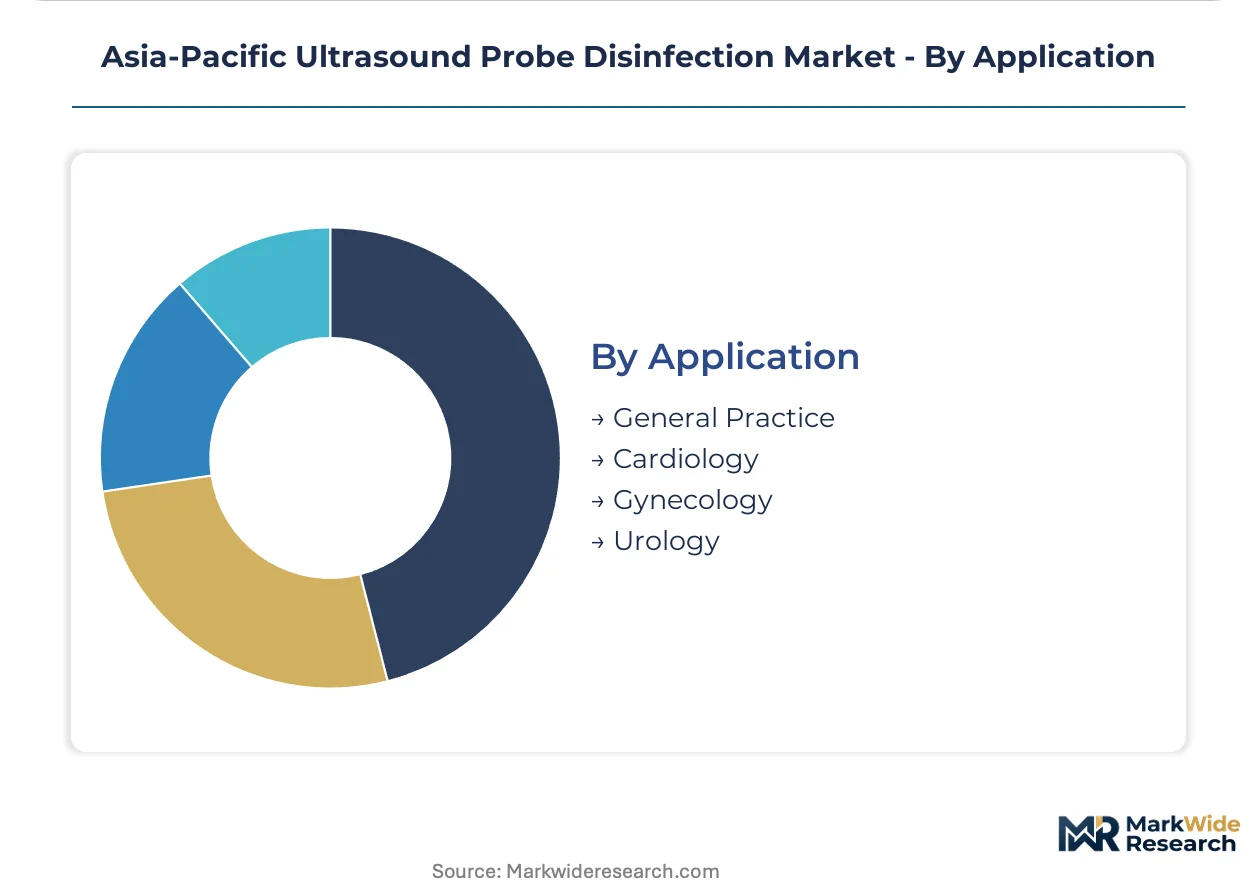
Application:
Regulatory scrutiny intensity varies by procedural invasiveness, with intracavitary applications commanding the strictest reprocessing standards.
- Gynecology:Transvaginal probe disinfection with documented high-level disinfection for semi-critical device classification. Australian obstetrics departments in Sydney and Melbourne are deploying automated ultraviolet systems to satisfy accreditation mandates for traceable reprocessing records.
- Urology:Transrectal probe protocols for prostate imaging and biopsy guidance. Japanese urology clinics are prioritizing PMDA-cleared platforms with printed cycle validation receipts for liability documentation.
- Cardiology:External transthoracic imaging with lower reprocessing requirements than intracavitary applications.
- General Practice:Surface and vascular imaging with intermediate disinfection protocols for non-critical device contact.
Compliance expenditure concentrates in Gynecology. Regulatory tightening is accelerating fastest in Urology as prostate screening programs expand across Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultrasound probe disinfection protocols first achieved regulatory codification in Japan during the 1990s, with Australian tertiary hospitals subsequently adopting automated systems in the 2000s. This historical lineage established the Asia-Pacific region as the testing ground for high-level disinfection validation standards now spreading across Southeast Asia.
Japan
PMDA-cleared ultraviolet platforms now dominate procurement in Tokyo and Osaka tertiary centers. The Ministry of Health, Labour and Welfare guidelines mandate validated reprocessing for semi-critical devices, compelling replacement of manual wipe workflows. Kansai region hospitals in Osaka Prefecture are deploying trophon systems with printed cycle validation receipts for liability documentation.
Australia
AS/NZS 4187 standards mandate documented high-level disinfection cycles for endocavitary transducers across Queensland and New South Wales. The Therapeutic Goods Administration enforces separate clinical data packages from Japanese regulators, fragmenting product development roadmaps. Sydney and Melbourne obstetrics departments are absorbing the fastest ultraviolet system deployments to satisfy accreditation audit requirements.
China
NMPA amended medical device rules now classify automated probe reprocessors as Class B or Class C instruments, tightening pre-market scrutiny. Tier-1 hospitals in Beijing and Shanghai are bridging compliance gaps with semi-automated soak stations ahead of full automation mandates. Yangtze River Delta imaging centers are prioritizing systems with traceable cycle documentation for liability protection.
India
CDSCO regulatory amendments are accelerating capital migration toward validated automated platforms in Mumbai and Delhi tertiary networks. Manual disinfection workflows persist in tier-2 cities due to capital intensity barriers exceeding tenfold cost differentials. Karnataka and Maharashtra state hospital procurement committees are unbundling after-sales service from hardware contracts for competitive tendering.
Vietnam
Greenfield tertiary facilities in Ho Chi Minh City lack legacy disinfection infrastructure, enabling direct-to-automated deployment without replacement friction. The national pharmaceutical regulator is referencing Japanese PMDA standards for emerging accreditation frameworks. Private hospital chains in the Mekong Delta region are adopting subscription bundling models converting capital expenditure into operational budgets.
Asia-Pacific Ultrasound Probe Disinfection Market Competitive Environment
Premium-margin players sit above commodity-margin players across compliance agility and regulatory pre-clearance capabilities. The vendor base stratifies between multinational chemical suppliers with regional supply chains and specialized ultraviolet platform manufacturers with PMDA-cleared portfolios. Three archetypes dominate: integrated hygiene conglomerates leveraging consumables recurring revenue, ultraviolet technology specialists with closed-loop cartridge systems, and manual disinfection providers occupying premium wipe niches. Competitive moves concentrate on strategic partnerships with Southeast Asian hospital chains and geographic expansion through distributor networks in Vietnam and Indonesia.
Among Australia-based specialists, Nanosonics Ltd exemplifies the ultraviolet technology archetype with trophon system deployments across obstetrics departments. Ecolab Inc anchors the integrated hygiene conglomerate tier, leveraging regional chemical supply chains for consumables bundling. Tristel Plc occupies a position within premium manual disinfection niches, representing the wipe-format specialist archetype in Japanese diagnostic imaging centers.
| Leading Market Players |
|---|
| Ecolab Inc |
| Tristel Plc |
| CIVCO Medical Solutions |
| Germitec SAS |
| CS Medical LLC |
| Nanosonics Ltd |
| ASP (Fortive) |
| STERIS |
| Steelco S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Japan's PMDA Class C device reclassification and Australia's AS/NZS 4187 accreditation mandates gate qualified supply access and premium-tier pricing power for automated ultraviolet platforms. Manufacturers lacking dual-market regulatory clearance face exclusion from tertiary hospital procurement committees across Tokyo, Osaka, Sydney, and Melbourne.
Pricing Analysis
Hardware-plus-consumables subscription contracts dominate procurement across Southeast Asian private hospital chains, converting capital expenditure into operational budgets and extending vendor lock-in duration. Price differentiation rests on PMDA clearance status and TGA validation documentation, with dual-certified platforms commanding threefold premiums over single-market alternatives. Cost compression in manual disinfection tiers is intensifying because India's CDSCO amendments are accelerating capital migration toward validated automated systems. Tier-2 hospitals in Mumbai and Delhi remain most price-sensitive, while Australian tertiary networks in Queensland and New South Wales prioritize compliance documentation over unit economics.
Supply Chain Analysis
Regional distribution centers in Singapore and Sydney anchor hub-and-spoke patterns serving Southeast Asian and Oceania markets respectively. Manufacturing concentration centers on Germany, Japan, and the United States for ultraviolet irradiation chambers, while peracetic acid and hydrogen peroxide formulations draw from domestic chemical producers in China and India. Single-source vulnerability persists for proprietary hydrogen peroxide cartridges, with three chemical manufacturers controlling global output. Distribution runs through authorized medical device distributors with biomedical engineering validation capabilities, particularly in Vietnam and Indonesia where direct manufacturer presence remains limited.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific ultrasound probe disinfection market functions as a regulatory compounder, with Japan's Ministry of Health, Labour and Welfare semi-critical device mandates driving replacement demand across tertiary hospital networks.
For Market Incumbents: Hedge against PMDA-TGA regulatory divergence by maintaining parallel clinical data packages for ultraviolet dose validation studies. Prioritize certification investment in ASEAN harmonization pathways to collapse compliance cost duplication across Singapore, Thailand, and Malaysia. Channel control through exclusive distributor agreements with biomedical engineering capabilities in Sydney, Melbourne, and Tokyo protects against emerging ultraviolet platform specialists. For New Entrants and Emerging Players: Begin with greenfield tertiary facilities in Ho Chi Minh City and Jakarta, where absence of legacy disinfection infrastructure enables direct-to-automated deployment without replacement cycle friction. Vietnam's private hospital chains in the Mekong Delta region present the most penetrable segment, with subscription bundling models converting capital expenditure into operational budgets. A go-to-market angle anchored to PMDA-cleared platform distribution anticipates ASEAN regulators referencing Japanese standards. For Investors and Strategic Acquirers: Roll-up economics work for specialized ultraviolet platform manufacturers with PMDA-cleared portfolios because dual-certification burdens create acquisition scarcity and extend competitive moats. Long-term viability over the coming decade hinges on compliance agility rather than pure technical performance. The signal to watch is CDSCO regulatory amendment timing for automated probe reprocessor classification in India, which would trigger capital migration acceleration across Mumbai and Delhi tertiary networks.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Dual-Certification Investment | Accelerates market access across Japanese and Australian tertiary hospital networks simultaneously. |
| ASEAN Harmonization Pathway Engagement | Collapses compliance cost duplication for Singapore, Thailand, and Malaysia distribution expansion. |
| Subscription Bundling Model Deployment | Converts capital expenditure to operational budgets across Southeast Asian private hospital chains. |
| Biomedical Engineering Capability Acquisition | Secures validation specialist talent concentrated in Sydney, Melbourne, and Tokyo recruitment markets. |
| Legacy Probe Adapter Development Program | Resolves compatibility limits for linear array transducers exceeding ultraviolet chamber dimensional constraints. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement committee members, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists at ultraviolet platform manufacturers with secondary validation against PMDA medical device filings, TGA therapeutic goods registers, CDSCO amended device rules, and hospital procurement database records. Bottom-up installation tracking across Queensland, New South Wales, Tokyo, and Osaka tertiary networks was triangulated with top-down market sizing.
The forecast window anchored historical reference periods to documented ultraviolet system deployment cycles across Australian obstetrics departments and Japanese diagnostic imaging centers. Segmentation dimensions modeled include product type automation level, end-user procurement authority concentration, technology regulatory clearance status, and application invasiveness classification. CAGRs were derived from installation run-rate analysis and consumables recurring revenue trajectories, with probe reprocessor replacement cycles and accreditation audit timing as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential NMPA reclassification of automated systems in China and unforeseen supply disruptions in peracetic acid cartridge manufacturing. Forecasts reflect documented assumptions around regulatory harmonization momentum and hospital capital expenditure recovery patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Global Microcatheter Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Global Disposable Medical Sensors Market
Medical Devices
North America Vagus Nerve Stimulation Market
Medical Devices
Tourniquet Systems Market
Medical Devices
Memory Implants Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Global Microscopy Device Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
Mucus Clearance Devices Market
Medical Devices
Breast Pump Flange Market