
 Global Cranial Implants Market | 2026-2036
Global Cranial Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cranial Implants Market Foresight
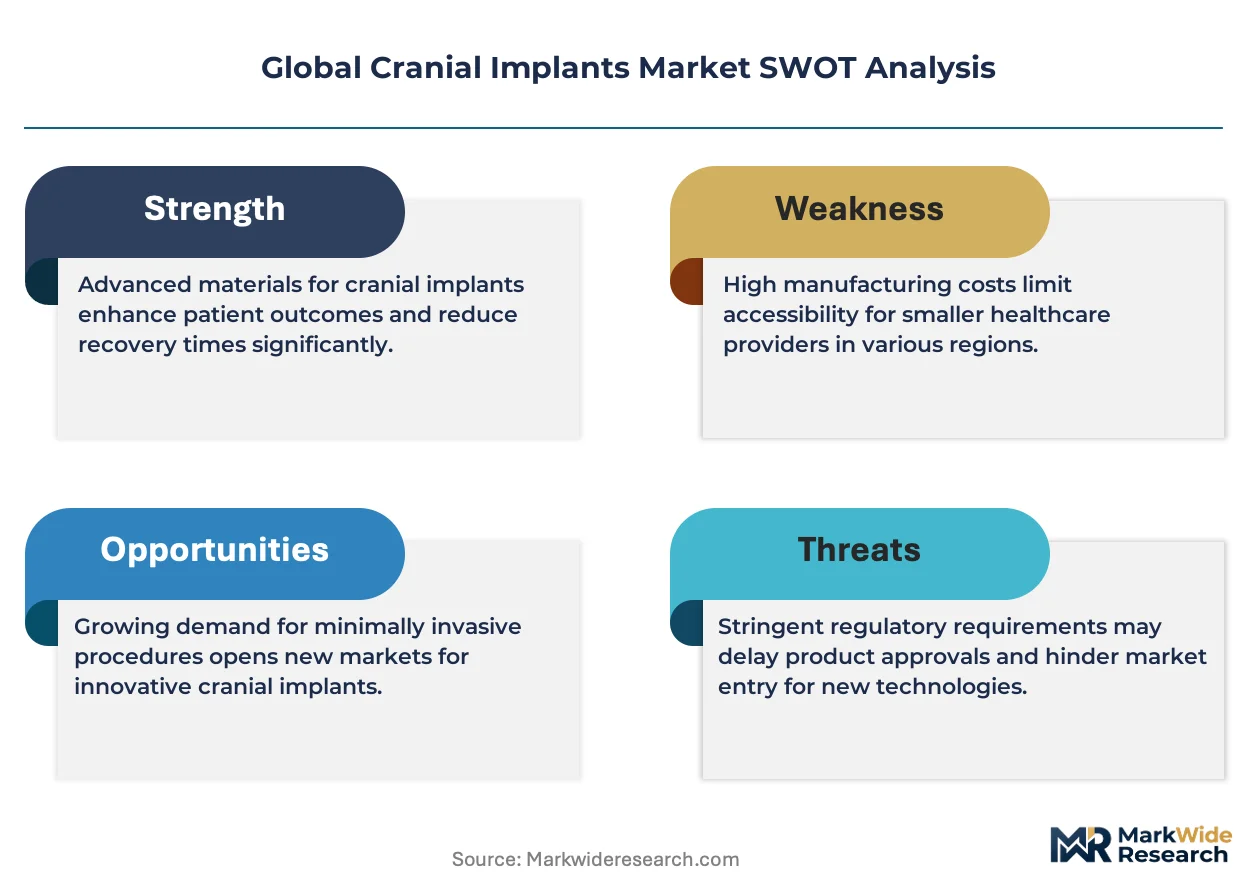
North American titanium forging capacity is reconfiguring supply availability for cranial implant manufacturers. Stryker Corporation leverages its orthopedic manufacturing scale to anchor polymer-to-metal hybrid production. Zimmer Biomet Holdings, Inc. sustains R&D intensity across patient-matched implant workflows. DePuy Synthes differentiates through vertical control over titanium powder supply chains.
Cranial implants are biocompatible constructs engineered to restore skull integrity following trauma, tumor resection, or congenital deformity, typically manufactured from titanium alloys, polyetheretherketone, or polymethyl methacrylate with thickness tolerances below 0.5 millimeters to ensure anatomical conformity. These devices function primarily to protect intracranial structures, restore cerebral hemodynamics, and provide aesthetic reconstruction. Polyetheretherketone leads product type margins due to its radiolucency and thermal stability, while ceramic composites represent the fastest-growing material class driven by osseointegration performance. Traumatic brain repair dominates application volumes, though neuro-oncology reconstruction generates premium pricing through custom morphological complexity.
The FDA's 510(k) framework governs US market entry, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements through notified body oversight. ISO 5832 standards for metallic surgical implants establish baseline biocompatibility and fatigue resistance benchmarks that manufacturers must satisfy across jurisdictions. Stakeholders must monitor evolving reimbursement coding for patient-specific implants and assess ceramic composite validation data against emerging MDR Annex XIV clinical evaluation criteria.
Market Dynamics
Patient-matched additive manufacturing is compressing production timelines for cranial reconstructive devices while simultaneously fragmenting traditional supply relationships between hospitals and implant fabricators.
Growth Catalysts
- EU MDR Annex XIV:Enhanced clinical evidence requirements for patient-specific implants are accelerating investment in automated quality systems among European manufacturers seeking notified body certification.
- Trauma center consolidation:High-volume neurosurgery hubs in the United States are centralizing complex cranial reconstruction referrals, concentrating procurement authority among fewer institutional buyers.
- PEEK radiolucency:Polyetheretherketone's compatibility with post-operative MRI surveillance is displacing titanium alloys in neuro-oncology applications where longitudinal imaging dominates patient management.
Market Restraints
- Titanium sponge volatility:Raw material costs for implant-grade titanium alloys fluctuate with aerospace demand cycles, squeezing margin stability for mid-tier manufacturers lacking long-term supply contracts.
- Notified body capacity:EU MDR implementation has thinned the pool of certifying organizations, extending time-to-market for novel ceramic composite formulations awaiting clinical evaluation.
- Autologous bone grafts:Patient-derived reconstruction remains clinically preferred for pediatric cases and contaminated trauma, capping addressable market expansion for synthetic alternatives.
Strategic Opportunities
- Brazil ANVISA pathway:Streamlined registration for FDA-cleared devices creates expedited access to Latin America's largest trauma surgery market with underdeveloped domestic manufacturing.
- AI-driven morphological prediction:Machine learning integration with preoperative planning software is converging with 3D printing workflows to enable same-week implant delivery.
- India PLI scheme:Production-linked incentives for medical device manufacturing are attracting contract fabrication investment to serve cost-sensitive Asian markets.
Industry Challenges
- Bioengineer scarcity:Specialized talent bridging computational anatomy, biomaterials science, and regulatory affairs commands premium compensation, constraining R&D team scaling.
- ISO 5832 fatigue validation:Extended mechanical testing protocols for novel porous titanium architectures delay product launches despite accelerated design capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cranial Implants Market |
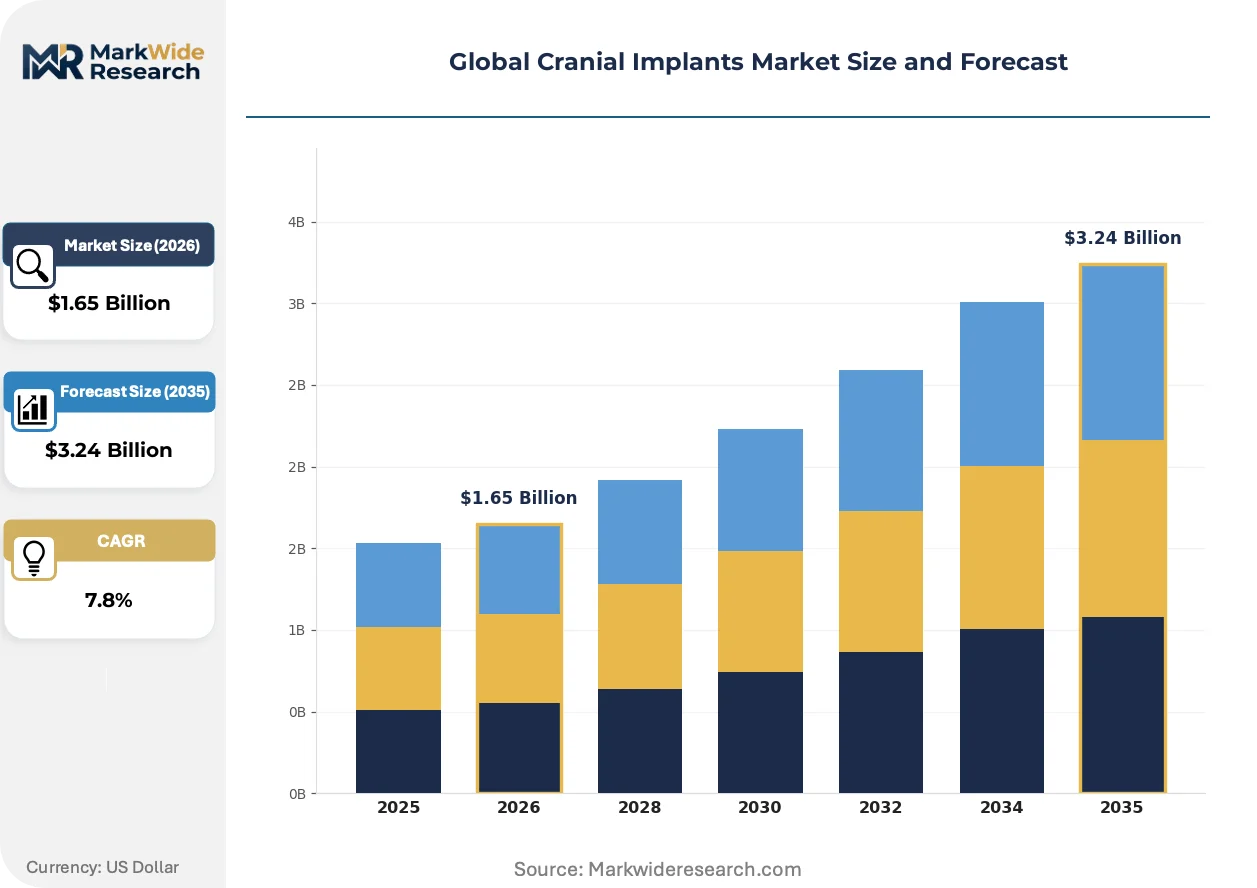
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.24 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous Bone, Titanium Mesh, Polymethyl Methacrylate, Polyetheretherketone, Ceramic Composites Application: Traumatic Brain Repair, Neuro-oncology Reconstruction, Cranial Deformity Correction, Skull Base Surgery End User: Neurosurgery Centers, Specialty Clinics, Ambulatory Surgical Facilities, Rehabilitation Institutes Deployment: Intraoperative Custom Molding, Pre-fabricated Implants, Injectable Systems, Modular Constructs |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Inc., DePuy Synthes, Medtronic Plc, KLS Martin Group, B. Braun Melsungen AG, Integra LifeSciences Holdings Corporation, Medartis AG, OsteoMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cranial Implants Market Shifts & Advancements
Digital surgical planning ecosystems are collapsing the traditional boundary between diagnostic imaging and implant fabrication, enabling same-patient specificity at production scales previously reserved for standardized inventory.
Additive manufacturing of titanium lattice structures is hybridizing the structural properties of solid metal with the osseointegration characteristics of porous ceramics. Neurosurgery departments at academic medical centers in Germany and the United States are adopting these hybrid constructs for complex orbital-frontal reconstructions. The technology is hybridizing procurement patterns by enabling hospital-based point-of-care fabrication that bypasses traditional distributor relationships.
EU MDR's enhanced post-market surveillance requirements are mandating systematic implant registry participation across member states. Manufacturers must now fund longitudinal outcome tracking as a condition of continued market authorization. High-complexity patient-specific devices face disproportionate compliance burden relative to commodity titanium mesh, tilting portfolio investment toward platforms with scalable data collection infrastructure.
Institutional procurement committees are consolidating vendor relationships around full-service reconstructive solution providers rather than discrete implant suppliers. Hospital systems in the United States are displacing standalone product purchasing with integrated contracts bundling preoperative planning software, implant fabrication, and revision warranty coverage. This behavioral shift concentrates most visibly among integrated delivery networks managing Level I trauma center networks across multiple states.
Global Cranial Implants Market Segmentation
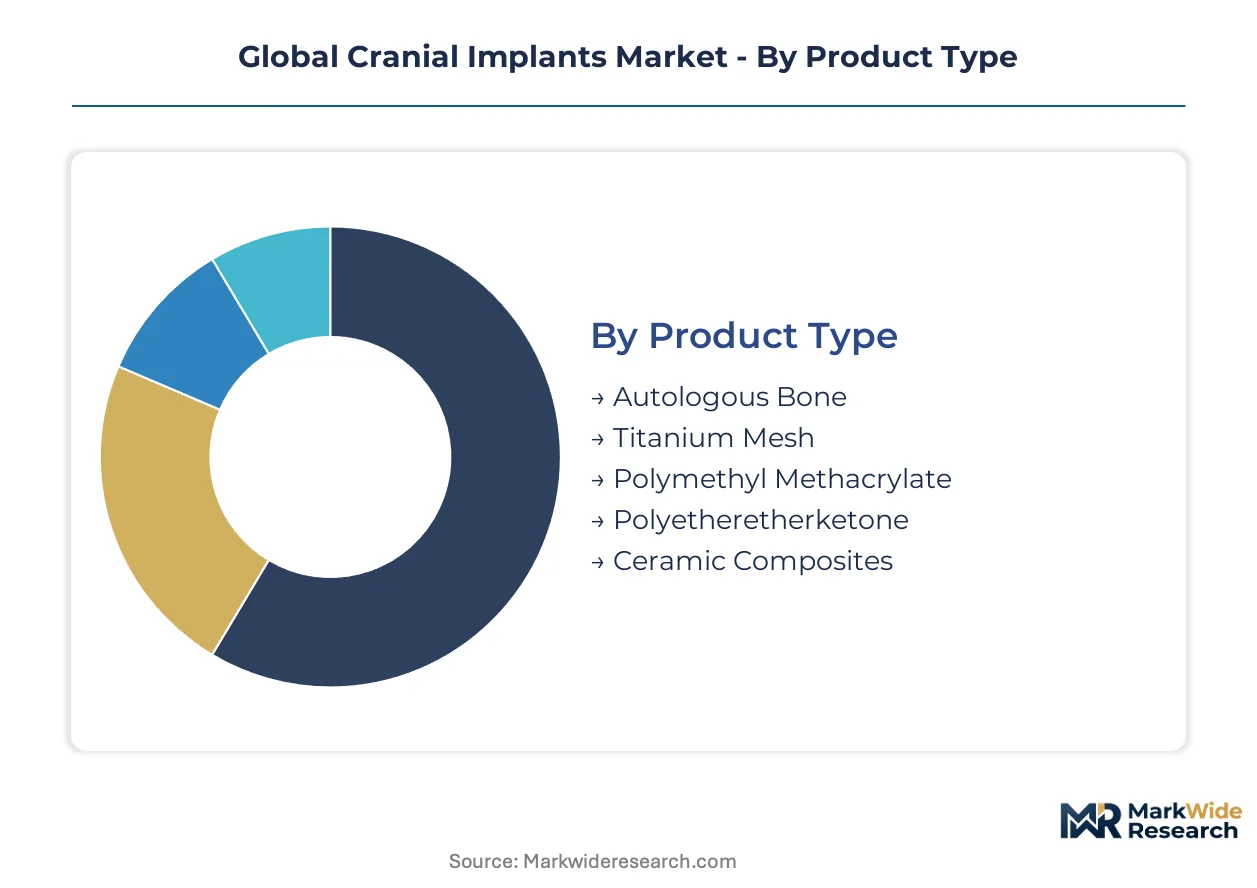
Segmentation in cranial implants determines procurement workflows, regulatory pathways, and after-sales service intensity. Manufacturers configure support infrastructure differently across product tiers, with patient-specific devices demanding dedicated bioengineering liaison teams while standardized inventory relies on distributor technical support.
Product Type:
After-sales service intensity varies sharply across material categories, with ceramic composites requiring specialized handling protocols and PEEK implants demanding MRI compatibility verification at implantation.
- Polyetheretherketone:This radiolucent thermoplastic withstands sterilization cycles exceeding 134°C without thermal degradation. Neuro-oncology centers in Germany and the United States specify PEEK for patients requiring longitudinal MRI surveillance, displacing titanium alloys in resection cases where post-operative imaging dominates follow-up protocols.
- Ceramic Composites:Hydroxyapatite-reinforced matrices achieve direct bone bonding through biomimetic surface architecture. Academic medical centers in Heidelberg and Boston are adopting these constructs for pediatric cranial reconstruction where osseointegration performance outweighs cost considerations.
- Titanium Mesh:Implant-grade Ti-6Al-4V alloys deliver fatigue resistance exceeding 800 MPa with thickness tolerances below 0.3 millimeters. Trauma centers in Texas and Florida maintain substantial inventory for emergency cranioplasty.
- Polymethyl Methacrylate:Intraoperative malleability permits manual contouring during open procedures. Cost-sensitive procurement in India and Brazil favors PMMA for deferred reconstruction cases.
- Autologous Bone:Patient-derived grafts harvested from calvarial or rib sources eliminate foreign body response. Pediatric neurosurgery protocols in Paris and Toronto specify autograft as first-line for contaminated trauma.
By volume, titanium mesh leads procurement across emergency trauma applications. By growth pace, ceramic composites are climbing the fastest as osseointegration data accumulates in European implant registries.
Application:
Cost tier stratification separates emergency trauma repair from elective reconstructive procedures, with neuro-oncology cases commanding premium pricing through morphological complexity and preoperative planning software integration.
- Traumatic Brain Repair:Emergency decompressive craniectomy generates immediate implant demand with limited preoperative customization. Level I trauma centers in Chicago and Los Angeles centralize high-volume procurement through integrated delivery networks.
- Neuro-oncology Reconstruction:Tumor resection cases require patient-matched implants addressing complex orbital-frontal defects. University hospitals in Munich and New York are expanding additive manufacturing partnerships for same-week implant delivery.
- Cranial Deformity Correction:Craniosynostosis and positional plagiocephaly procedures in pediatric populations favor resorbable materials. Toronto's Hospital for Sick Children and Paris Necker Hospital specialize in these reconstructions.
- Skull Base Surgery:Combined neurosurgical-otolaryngology approaches demand implants addressing anterior and middle cranial fossa defects. Pittsburgh and Zurich academic centers lead procedural volume.
Traumatic brain repair dominates absolute procedure counts. Neuro-oncology reconstruction shows the steepest expansion trajectory as preoperative planning software penetrates community hospital settings.
End User:
Customer type determines technical support expectations, with neurosurgery centers requiring embedded bioengineering liaison while ambulatory facilities depend on remote technical assistance.
- Neurosurgery Centers:High-complexity academic institutions in Germany and the United States maintain direct manufacturer relationships for patient-specific implant workflows. These facilities generate disproportionate revenue per procedure through premium device categories.
- Specialty Clinics:Focused craniofacial practices in São Paulo and Mumbai concentrate elective reconstruction volumes. Their procurement emphasizes preoperative planning software integration over implant inventory breadth.
- Ambulatory Surgical Facilities:Same-day discharge protocols in Florida and Arizona drive demand for streamlined implant systems with reduced operative time. These settings favor pre-fabricated titanium mesh over custom-manufactured alternatives.
- Rehabilitation Institutes:Secondary cranioplasty for stroke and anoxic brain injury patients occurs in post-acute settings. Cleveland Clinic and Johns Hopkins rehabilitation networks coordinate delayed reconstruction scheduling.
Neurosurgery centers capture the highest revenue per implant. Ambulatory surgical facilities are gaining share fastest as minimally invasive approaches expand eligible patient populations.
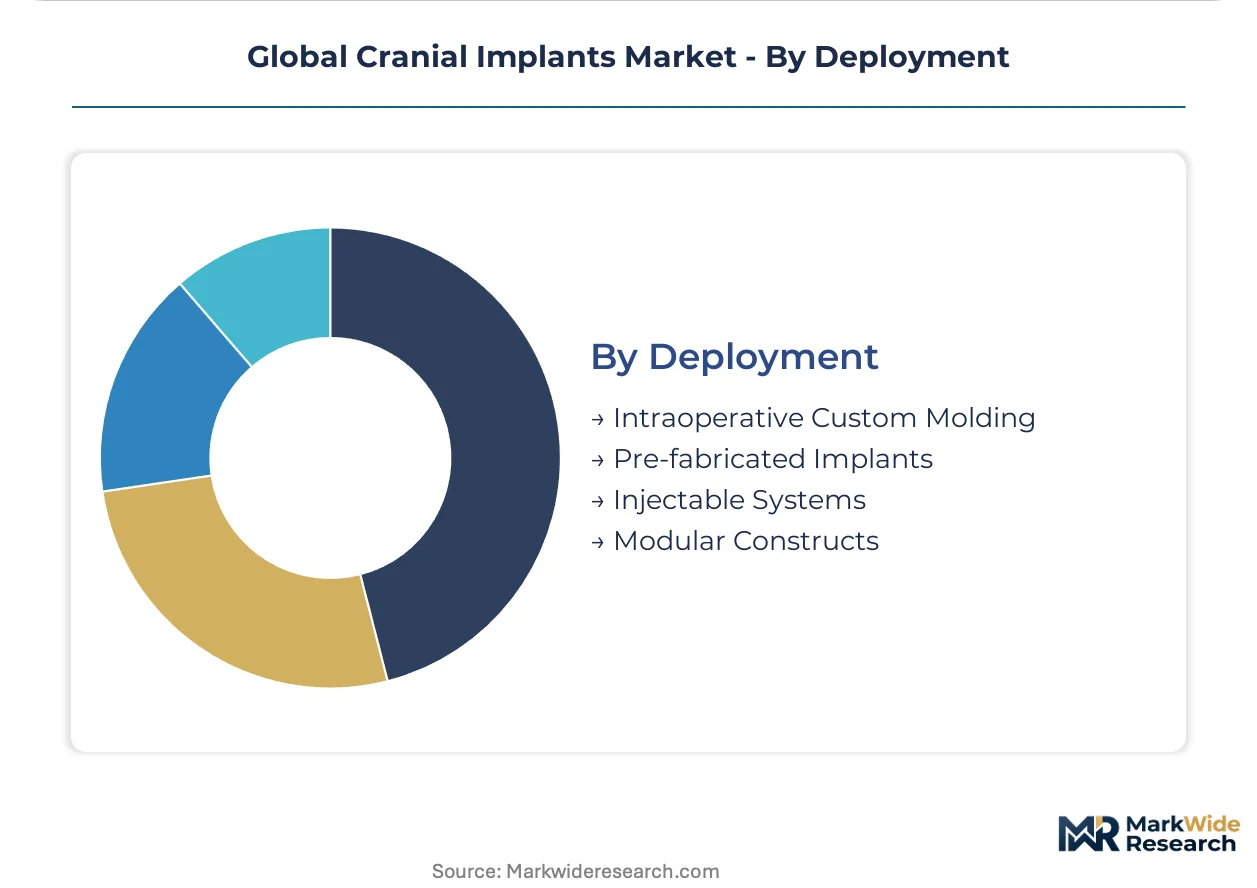
Deployment:
Supply concentration distinguishes centralized fabrication facilities from point-of-care manufacturing, with intraoperative molding requiring minimal capital investment while additive manufacturing demands substantial equipment deployment.
- Pre-fabricated Implants:Standardized titanium mesh and PMMA plates ship from regional distribution centers with 24-hour availability. Stryker and Zimmer Biomet maintain North American fulfillment networks serving emergency trauma.
- Intraoperative Custom Molding:Thermoplastic devices shaped during open procedures eliminate manufacturing lead times. Community hospitals in Texas and Georgia rely on this approach for cost containment.
- Modular Constructs:Interlocking plate systems permit intraoperative assembly for complex defects. DePuy Synthes promotes these platforms across European trauma networks.
- Injectable Systems:Calcium phosphate cements harden in situ for small cranial defects. Limited structural capacity restricts application to burr hole coverage and minor contour irregularities.
Pre-fabricated implants dominate emergency procurement volumes. Modular constructs are expanding most quickly as surgical training programs emphasize intraoperative adaptability over custom manufacturing delays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States dominate cranial implant consumption through divergent procurement models: German neurosurgery centers emphasize patient-specific additive manufacturing workflows, while American trauma networks prioritize standardized inventory availability for emergency decompressive procedures.
United States
Level I trauma centers in Chicago and Los Angeles centralize high-volume procurement through integrated delivery networks, concentrating purchasing authority among fewer institutional buyers. The FDA's 510(k) clearance pathway accelerates commercialization timelines for titanium mesh and polyetheretherketone devices. Academic medical centers in Boston and New York are expanding additive manufacturing partnerships for same-week implant delivery in neuro-oncology reconstruction.
Germany
Neurosurgery centers in Heidelberg and Munich are expanding adoption of patient-specific cranial implants through direct manufacturer relationships. The EU Medical Device Regulation imposes enhanced clinical evidence requirements through notified body oversight, accelerating investment in automated quality systems. The Heidelberg-Berlin corridor anchors European production of ceramic composite constructs for pediatric cranial reconstruction.
China
Domestic trauma surgery volumes in Shanghai and Beijing sustain demand for cost-effective polymethyl methacrylate implants in deferred reconstruction cases. The National Medical Products Administration governs market entry through Class III medical device registration requirements. Yangtze River Delta manufacturing clusters are attracting contract fabrication investment to serve cost-sensitive Asian markets.
Brazil
Specialty craniofacial practices in São Paulo concentrate elective reconstruction volumes, emphasizing preoperative planning software integration over implant inventory breadth. ANVISA maintains streamlined registration pathways for FDA-cleared devices, creating expedited access to Latin America's largest trauma surgery market. Domestic manufacturing remains underdeveloped, sustaining import dependence for premium patient-specific devices.
India
Cost-sensitive procurement in Mumbai and Delhi favors polymethyl methacrylate for deferred reconstruction cases, while academic centers explore ceramic composites for pediatric applications. The Production-Linked Incentive scheme for medical device manufacturing attracts contract fabrication investment. Maharashtra and Gujarat industrial corridors are emerging as fabrication hubs for standardized titanium mesh serving domestic and export markets.
Global Cranial Implants Market Competitive Landscape
Capability concentration sits with patient-specific additive manufacturing specialists; scale advantage sits with diversified orthopedic conglomerates. The market structures around three tiers: full-service reconstructive solution providers bundling software and fabrication, mid-tier manufacturers dependent on distributor relationships, and emerging point-of-care fabricators bypassing traditional supply chains. Dominant competitive moves include portfolio diversification into ceramic composites and strategic partnerships with academic medical centers for clinical validation data.
Among diversified orthopedic conglomerates, Stryker Corporation and Zimmer Biomet Holdings, Inc. occupy positions anchoring polymer-to-metal hybrid production at scale. DePuy Synthes exemplifies upstream supply chain control through in-house titanium powder sourcing. These three entities represent the tier consolidating procurement relationships around integrated contracts bundling preoperative planning, implant fabrication, and revision warranty coverage.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| DePuy Synthes |
| Medtronic Plc |
| KLS Martin Group |
| B. Braun Melsungen AG |
| Integra LifeSciences Holdings Corporation |
| Medartis AG |
| OsteoMed |
| Others |
Supply & Pricing Matrix
Titanium sponge price volatility originating from aerospace demand cycles compresses margin stability for mid-tier cranial implant manufacturers lacking long-term supply contracts, forcing a pricing structure that separates premium patient-specific additive manufacturing from standardized titanium mesh and economy-grade polymethyl methacrylate tiers while simultaneously reshaping procurement relationships toward vertically integrated conglomerates with captive raw material sourcing.
Pricing Analysis
Price spreads between German neurosurgery centers and Indian deferred reconstruction cases exceed threefold across equivalent defect sizes. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification tier, customization depth, and after-sales bioengineering support bundling. Cost compression in mid-tier titanium mesh intensifies because aerospace demand spikes absorb implant-grade alloy capacity. Ambulatory surgical facilities in Florida and Arizona exhibit highest price sensitivity, while academic medical centers in Boston and Munich prioritize radiolucency performance over unit cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for implant-grade titanium alloy procurement. Manufacturing gravity centers on Germany, United States, and China, with Yangtze River Delta clusters serving cost-sensitive Asian markets. Raw material dependencies rest on titanium sponge from aerospace suppliers, PEEK resin from European chemical conglomerates, and hydroxyapatite ceramic precursors from Japanese specialty manufacturers. Single-source vulnerability concentrates in implant-grade powder supply for additive manufacturing. Distribution runs through integrated delivery networks consolidating procurement authority among Level I trauma center systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient-matched additive manufacturing penetration in neuro-oncology reconstruction signals early-cycle expansion with substantial runway before saturation, as same-week implant delivery workflows currently serve fewer than fifteen percent of eligible tumor resection cases globally.
For Market Incumbents: Insulate margin position through backward integration into titanium powder supply chains and captive PEEK resin sourcing, while accelerating automated quality system deployment to satisfy EU MDR Annex XIV post-market surveillance obligations that threaten market authorization continuity for manufacturers lacking scalable data infrastructure. For New Entrants and Emerging Players: Build out point-of-care fabrication partnerships with academic medical centers in São Paulo and Mumbai, where streamlined ANVISA and CDSCO pathways for FDA-cleared devices create expedited market access without domestic manufacturing investment, targeting cost-sensitive trauma reconstruction with pre-fabricated titanium mesh before advancing to patient-specific workflows. For Investors and Strategic Acquirers: The market sits at a technology-adoption phase that favors additive manufacturing specialists with embedded clinical validation partnerships over diversified orthopedic conglomerates, with long-term viability hinging on ceramic composite osseointegration data accumulation in European implant registries; the signal to watch is notified body capacity expansion permitting accelerated novel material certification.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated contracts bundling software, fabrication, and warranty displace standalone purchasing at Level I trauma networks. |
| CE Marking Pathway | EU MDR Annex XIV compliance investment separates viable European competitors from regulatory casualties. |
| Software Companion Development | AI-driven morphological prediction integration with preoperative planning enables same-week implant delivery workflows. |
| FDA Submission | 510(k) clearance pathway for titanium lattice structures accelerates commercialization timelines relative to PMA devices. |
| Reimbursement Strategy | Patient-specific implant coding evolution determines addressable market expansion beyond emergency trauma repair. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with neurosurgeons, biomedical engineers, hospital purchasing committees, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement records. Bottom-up segmentation modeling triangulated with top-down macroeconomic anchoring across product type, application, end user, and deployment configuration dimensions.
Forecast inputs considered trauma surgery volume trajectories, additive manufacturing adoption curves in neuro-oncology, and regulatory pathway evolution across the analysis window. Segmentation dimensions modeled include material category, procedural indication, facility type, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity constraints. Industry-specific inputs incorporated titanium sponge price forecasting and notified body certification queue dynamics.
Stress conditions across titanium raw material availability, EU MDR implementation pace, and point-of-care fabrication regulatory clarity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from ceramic composite clinical validation surprises or autologous bone graft protocol shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
South Korea Respiratory Devices Market
Medical Devices
Appendage Management Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Arthroscopy Procedures and Products Market
Medical Devices
Surgical Integration Systems Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Dose Monitoring Devices Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Latin America Insulin Delivery Devices Market
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
Phoropters Market
Medical Devices
Spain Artificial Organs and Bionic Implants Market
Medical Devices
Sleep Apnea Implants Market
Medical Devices
Digital Migraine Treatment Device Market
Medical Devices
Argentina Ultrasound Devices Market