
 Balloon Catheters Market | 2026-2036
Balloon Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Balloon Catheters Market Analysis
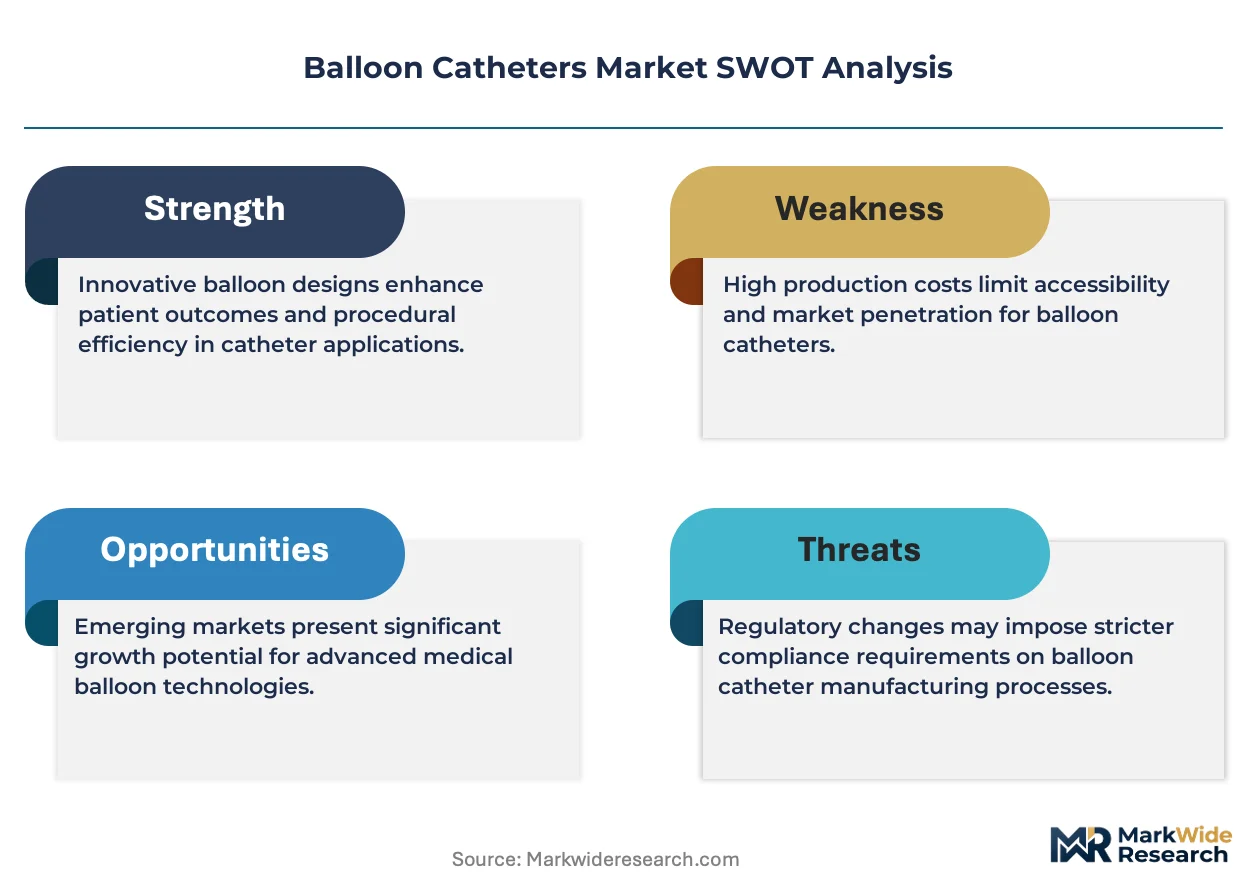
Software-defined pressure-sensing and connected-procedure analytics is broadening what catheter vendors monetize beyond the physical device. Boston Scientific Corporation leverages integrated hemodynamic monitoring platforms to sustain premium positioning in coronary workflows. Medtronic plc anchors its vascular portfolio through catheter-electronics convergence that extends into cath lab informatics.
A balloon catheter is a flexible, inflatable-tipped tube manufactured from polyamide, polyethylene terephthalate, or polyurethane composites, designed to dilate stenotic vessels, deploy stents, or occlude blood flow during minimally invasive procedures. Coronary procedures occupy the largest application segment due to sustained procedural volumes in interventional cardiology, while drug-eluting balloons represent the fastest-expanding product category as restenosis-reduction protocols gain clinical traction. Peripheral procedures command growing attention where chronic limb ischemia prevalence outpaces surgical bypass capacity.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and sterilization validation standards for balloon catheter manufacturers. Japan's PMDA and China's NMPA impose supplementary biocompatibility and local clinical testing obligations that condition market entry sequencing. Stakeholders must monitor how real-world evidence mandates and value-based procurement criteria in Germany and France restructure purchasing authority away from individual physicians toward hospital-system formulary committees.
Market Dynamics
Software-defined pressure-sensing architectures are redefining catheter value capture, enabling vendors to monetize real-time hemodynamic analytics alongside physical devices. This convergence of electronics and disposable instrumentation is restructuring R&D priorities across interventional cardiology portfolios.
Growth Catalysts
- EU MDR technical documentation mandates:Sterility validation requirements are accelerating consolidation among manufacturers with in-house sterilization capabilities, favoring scaled producers over contract assemblers.
- Drug-eluting balloon protocols:Restenosis-reduction clinical pathways in German and Japanese hospital systems are expanding procedural indications beyond standard angioplasty.
- Aging demographics in Japan:Chronic limb ischemia prevalence is outpacing surgical bypass capacity, redirecting patient volumes toward catheter-based peripheral interventions.
Market Restraints
- Polymer feedstock concentration:Medical-grade polyurethane and polyamide supply concentrates among three European chemical suppliers, exposing margins to petrochemical volatility.
- FDA 510(k) pathway friction:Predicate device requirements for novel balloon geometries are extending clearance timelines for innovative catheter designs.
- Surgical bypass substitution:Improved endovascular techniques in aortic and femoral segments are compressing addressable volumes for coronary balloon applications.
Strategic Opportunities
- Connected-procedure platforms:Integration of catheter pressure sensors with cath lab informatics systems creates recurring revenue streams beyond device sales.
- Peripheral artery disease expansion:Underpenetrated below-the-knee procedures in the United States represent white space as drug-coated balloon protocols mature.
- Japan PMDA real-world evidence pathways:Post-market surveillance data requirements are creating first-mover advantages for manufacturers with established Japanese clinical infrastructure.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization studies face bottlenecks at contracted laboratories, delaying EU MDR conformity assessments.
- Electronics-sterilization compatibility:Pressure-sensor integration requires novel ethylene oxide or vaporized hydrogen peroxide protocols that legacy catheter facilities cannot accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Balloon Catheters Market |
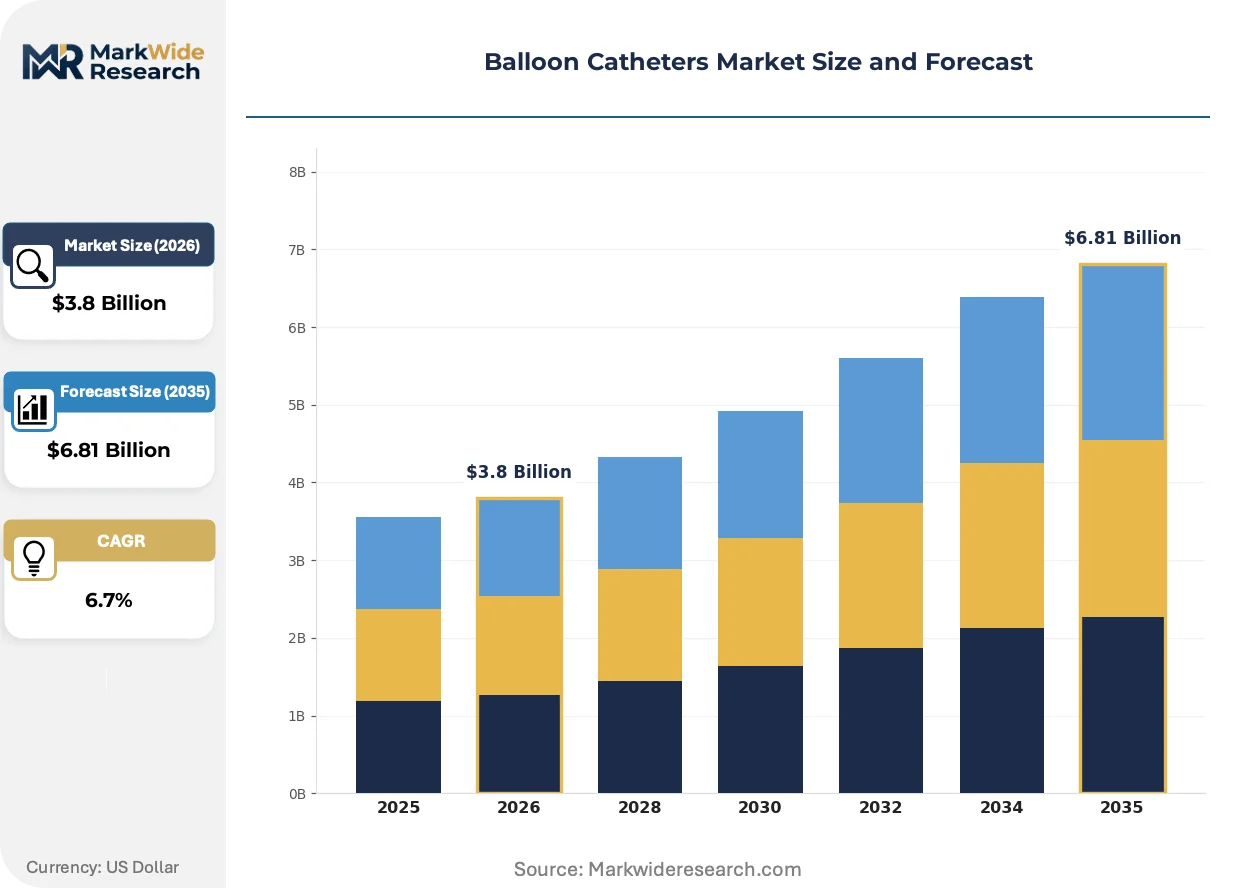
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTCA Balloons, Non-Compliant Balloons, Cutting Balloons, Drug-Eluting Balloons Application: Coronary Procedures, Peripheral Procedures, Urological Applications, Gastrointestinal Applications End User: Hospitals, Specialized Clinics, Ambulatory Surgical Centers, Cardiology Departments Delivery Mode: Manual Delivery, Mechanical Delivery, Electrode-Powered Delivery, Vascular Access Delivery |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Medtronic plc, Becton Dickinson and Company, B. Braun Melsungen AG, Terumo Corporation, Johnson & Johnson, Cardinal Health, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Balloon Catheters Market Emerging Trajectories
Catheter-electronics convergence is dismantling traditional boundaries between disposable devices and capital equipment, forcing vendors to build software competencies alongside polymer engineering. This recomposition of technical requirements is filtering the competitive field toward systems-level players.
Microelectromechanical pressure sensors embedded in balloon walls are modularizing catheter architecture, separating sensing electronics from disposable inflatable components. Interventional cardiology suites in the United States and Germany are piloting these platforms to enable procedure-to-procedure data continuity. This modularity is compressing replacement cycles for sensing hardware while extending service contracts for analytics subscriptions.
EU MDR post-market surveillance obligations are tightening clinical evidence requirements for Class III cardiovascular devices, mandating systematic collection of real-world performance data. Manufacturers must now maintain post-authorization safety studies and periodic safety update reports across their European portfolios. Drug-eluting balloon categories face the steepest compliance burden, as novel coating chemistries lack long-term implant registries.
Hospital-system formulary committees in France and Germany are consolidating purchasing authority over individual physician preference items, including coronary balloon selections. Cardiovascular service line directors now negotiate multi-year supply agreements that bundle catheters with contrast media and guidewire commitments. This concentration is most visible in German university hospital networks, where procurement centralization has compressed vendor counts by half within three years.
Balloon Catheters Market Segmentation
Balloon catheter purchasing decisions fragment across clinical workflow requirements, reimbursement tier alignment, and cath lab infrastructure compatibility. Manufacturers must architect portfolio breadth that spans high-volume coronary interventions through specialized peripheral and non-vascular applications.
Product Type:
Material compliance properties and coating chemistries differentiate price positioning and clinical indication breadth.
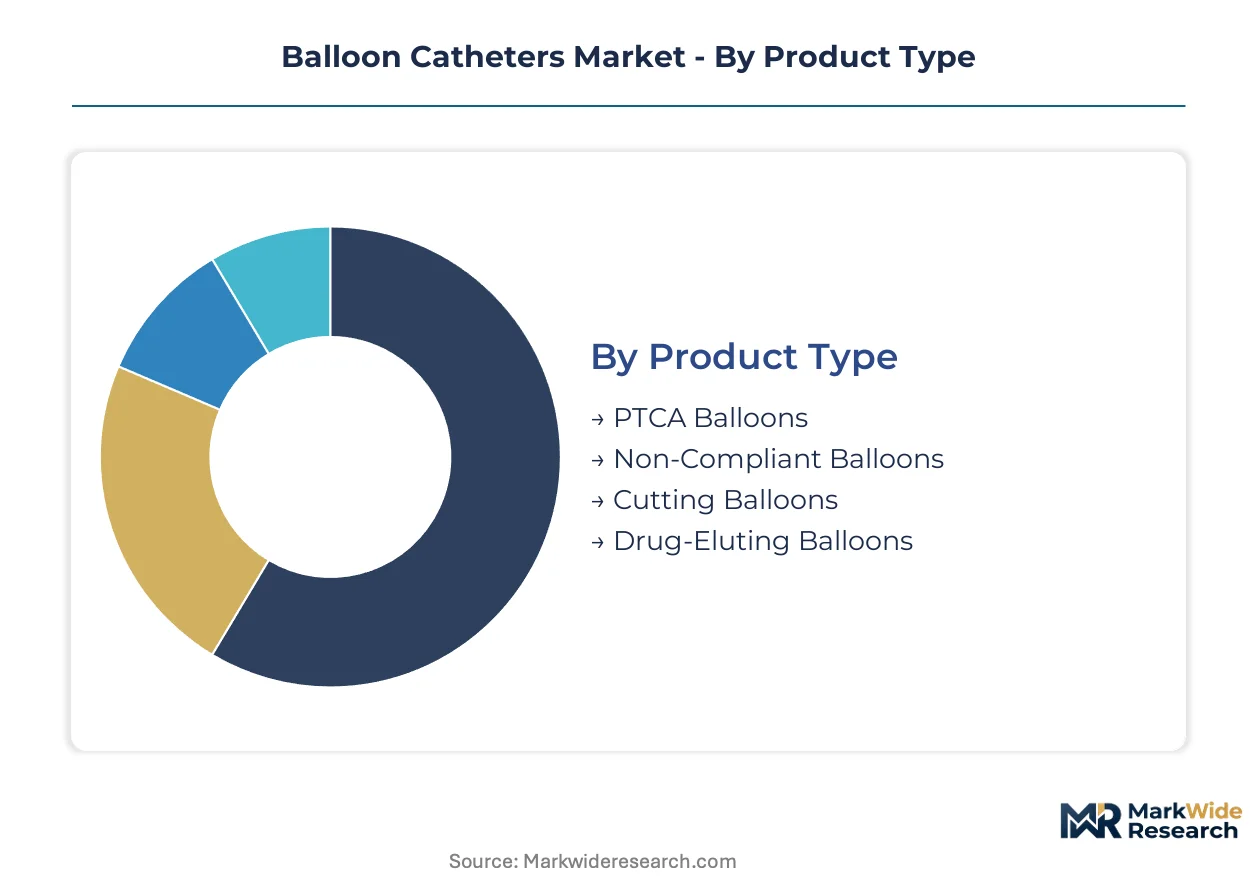
- PTCA Balloons:Semi-compliant polyethylene terephthalate construction permits controlled radial expansion during coronary dilatation. Hospital systems in the United States and Germany standardize on these platforms for routine percutaneous coronary intervention workflows, with procurement committees favoring established sterilization-validated supply chains.
- Drug-Eluting Balloons:Paclitaxel- or sirolimus-coated surfaces deliver antiproliferative agents directly to vessel walls. Japanese and German hospital networks are expanding indications for these devices in in-stent restenosis protocols where stent reimplantation carries elevated bleeding risk.
- Non-Compliant Balloons:High-pressure nylon or polyamide composites resist deformation at rated burst pressures above 20 atmospheres.
- Cutting Balloons:Microsurgical atherotomes mounted on balloon surfaces score calcified lesions prior to dilatation.
PTCA balloons lead volumes today; drug-eluting balloons are gaining share fastest.
Application:
Procedure reimbursement intensity and complication risk profiles shape vendor selection criteria across clinical domains.
- Coronary Procedures:Stenotic lesion dilatation and stent deployment in epicardial vessels. Interventional cardiology suites in the United States generate concentrated demand for rapid-exchange catheter platforms compatible with existing guidewire inventories.
- Peripheral Procedures:Femoropopliteal and infrapopliteal interventions for chronic limb ischemia. Below-the-knee applications in Japanese tertiary centers are outpacing surgical bypass volumes as diabetes-related vascular disease prevalence climbs.
- Urological Applications:Ureteral stricture dilatation and prostatic hyperplasia management.
- Gastrointestinal Applications:Esophageal and biliary stricture palliation.
Coronary applications dominate revenue; peripheral procedures show the steepest expansion trajectory.
End User:
Capital equipment integration requirements and case volume thresholds determine distribution channel economics.
- Hospitals:Comprehensive cardiovascular service lines with integrated cath lab informatics. German university hospital networks are consolidating purchasing authority through multi-year supply agreements that bundle catheters with contrast media commitments.
- Cardiology Departments:Subspecialized interventional units within larger hospital systems. These departments in the United States pilot connected-procedure platforms integrating pressure-sensing catheters with hemodynamic monitoring infrastructure.
- Specialized Clinics:Freestanding vascular intervention facilities.
- Ambulatory Surgical Centers:Lower-acuity peripheral procedures with same-day discharge protocols.
Hospitals anchor procurement volumes; cardiology departments are expanding fastest as service lines unbundle from general surgical suites.
Delivery Mode:
Operator training requirements and procedure automation potential differentiate adoption barriers across cath lab settings.
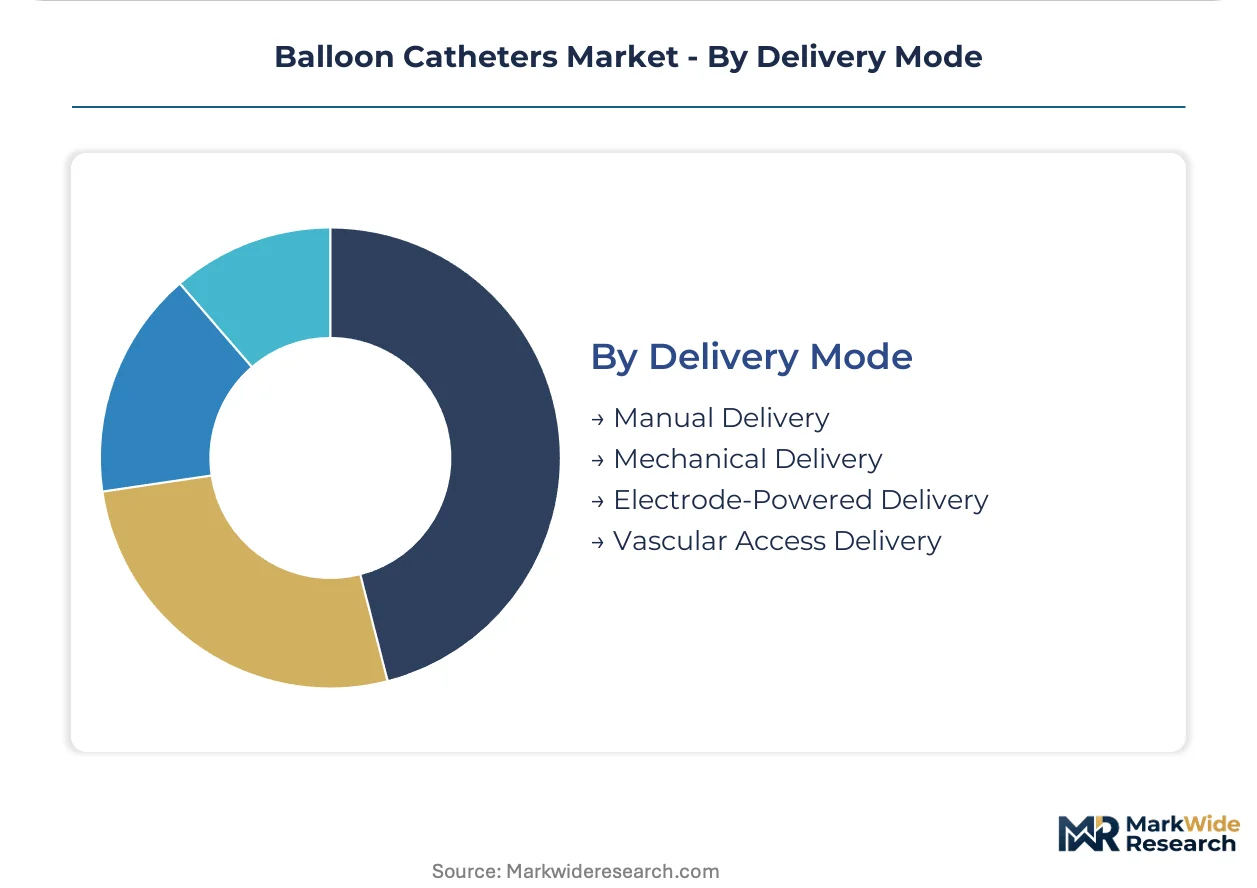
- Manual Delivery:Physician-controlled inflation via syringe-based indeflators with tactile pressure feedback. United States interventionalists favor these platforms for complex bifurcation lesions requiring real-time tactile adjustment.
- Mechanical Delivery:Automated inflation systems with programmable pressure ramp protocols. German hospital systems deploy these for standardized procedural workflows that reduce operator variability and support training standardization.
- Electrode-Powered Delivery:Integrated electrosurgical capabilities for lesion modification.
- Vascular Access Delivery:Sheath-compatible rapid-exchange systems for radial artery approaches.
Manual delivery systems retain volume leadership; mechanical delivery platforms are climbing the fastest as cath labs prioritize procedure standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between jurisdictions are redirecting balloon catheter manufacturing investments toward locations with streamlined sterilization validation pathways. Manufacturers balance EU MDR compliance depth against FDA 510(k) timeline predictability when siting production capacity.
United States
Interventional cardiology suites in Cleveland Clinic and Mayo Clinic networks drive concentrated demand for rapid-exchange catheter platforms. FDA 510(k) predicate device requirements shape product development sequencing for novel balloon geometries. Minneapolis-St. Paul anchors domestic manufacturing with established ethylene oxide sterilization infrastructure serving cardiovascular device clusters.
Germany
University hospital networks in Berlin and Munich consolidate purchasing authority through multi-year supply agreements bundling catheters with contrast media. EU MDR technical documentation mandates accelerate consolidation among manufacturers with captive sterilization capabilities. Baden-Württemberg hosts specialized polymer processing facilities supplying medical-grade polyurethane feedstocks.
Japan
PMDA real-world evidence pathways for Class III cardiovascular devices create first-mover advantages for manufacturers with established domestic clinical infrastructure. Chronic limb ischemia prevalence in Tokyo and Osaka tertiary centers outpaces surgical bypass capacity. Kansai region medical device clusters specialize in catheter-electronics convergence for pressure-sensing platforms.
China
NMPA biocompatibility testing obligations and local clinical trial requirements condition market entry sequencing for multinational manufacturers. Shanghai and Beijing hospital systems expand catheter-based peripheral intervention volumes as diabetes-related vascular disease prevalence climbs. Yangtze River Delta contract manufacturers scale polymer extrusion capacity for domestic and export markets.
Switzerland
Swissmedic conformity assessment procedures align with EU MDR standards while offering streamlined timelines for innovative coating chemistries. Basel and Zurich medical technology clusters concentrate R&D-intensive catheter development alongside pharmaceutical coating expertise. Alpine region sterilization facilities serve niche high-value balloon categories requiring specialized vaporized hydrogen peroxide protocols.
Balloon Catheters Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device-electronics platforms commanding premium positioning against commodity balloon suppliers. The vendor base stratifies into three tiers: multinational cardiovascular conglomerates with cath lab informatics integration, mid-scale regional manufacturers with sterilization captive supply, and specialized coating technology licensors. Consolidation accelerates through sterilization asset acquisitions and polymer feedstock backward integration. Portfolio diversification into drug-eluting balloon categories and geographic expansion into Japanese real-world evidence pathways represent dominant competitive vectors.
Among US-based cardiovascular conglomerates, Abbott Laboratories and Boston Scientific Corporation exemplify integrated platform strategies spanning catheter hardware through procedure analytics. Medtronic plc anchors the systems-tier with vascular portfolio breadth extending into cath lab informatics infrastructure. Becton Dickinson and Company represents the diversified medical technology archetype with sterilization validation depth across multiple device categories. These three structures—integrated platform, systems-tier breadth, and diversified validation—capture distinct procurement committee preferences across German hospital networks and US integrated delivery systems.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Medtronic plc |
| Becton Dickinson and Company |
| B. Braun Melsungen AG |
| Terumo Corporation |
| Johnson & Johnson |
| Cardinal Health |
| Cook Medical |
| Others |
Supply Flow & Price Mechanics
Three-tier pricing structure across premium, standard, and economy levels bifurcates the balloon catheter landscape, with integrated pressure-sensing platforms commanding hospital system formulary premiums while commodity PTCA balloons face procurement committee compression. This divergence manifests in supply chain configurations where EU MDR-validated sterilization assets anchor premium tiers and contract assemblers populate economy segments.
Pricing Analysis
Distributor margins compress most acutely in standard-tier PTCA balloons where German hospital networks negotiate multi-year bundled contracts. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) predicate validation status and integrated hemodynamic analytics capability. Cost compression in economy segments intensifies as Asian contract manufacturers scale polymer extrusion capacity. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery systems with captive cath lab informatics show lowest.
Supply Chain Analysis
ISO 10993 cytotoxicity validation and EU MDR technical documentation gating concentrate qualified supply among Germany, Switzerland, and United States sterilization facilities. Medical-grade polyurethane feedstocks draw from Baden-Württemberg chemical clusters and Minneapolis-St. Paul medical device corridors. Single-source vulnerability concentrates in vaporized hydrogen peroxide sterilization protocols required for pressure-sensor integration. Distribution runs through hospital-system GPO contracts and specialized cardiovascular device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Balloon catheter demand compounds through regulatory ratchet effects, with EU MDR post-market surveillance mandates accelerating replacement cycles for non-compliant legacy portfolios.
For Market Incumbents: Acquire captive sterilization assets in EU MDR-validated geographies to defend margin position against contract assembler price erosion. Backward integration into medical-grade polyurethane feedstocks mitigates petrochemical volatility exposure from European chemical suppliers. Priority investment in Japan PMDA real-world evidence infrastructure secures first-mover positioning in chronic limb ischemia protocols. For New Entrants and Emerging Players: Begin with below-the-knee peripheral applications in United States ambulatory surgical centers where drug-coated balloon protocols remain underpenetrated. White space concentrates in mechanical delivery platforms for German hospital systems standardizing procedural workflows. Go-to-market leverage rests on cath lab informatics partnerships rather than device-only distribution. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale regional manufacturers possessing sterilization captive supply and drug-eluting balloon coating licenses. Long-term viability hinges on electronics-sterilization compatibility capabilities across the 5-10 year technology convergence horizon. Signal to monitor: FDA 510(k) clearance timeline extensions for novel balloon geometries indicating regulatory friction arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Sterilization Validation | Captive ethylene oxide capacity in Germany and Switzerland secures premium tier access. |
| Pressure-Sensor Platform Integration | Cath lab informatics convergence with Boston Scientific and Medtronic systems creates recurring revenue. |
| Japan PMDA Real-World Evidence Pathway | Domestic clinical infrastructure investment unlocks Class III cardiovascular device approvals. |
| Drug-Eluting Balloon Coating Licensing | Paclitaxel and sirolimus chemistry partnerships expand indication breadth in German networks. |
| Peripheral Procedure Portfolio Expansion | Below-the-knee applications in United States ASCs capture fastest-growing procedural segment. |
Methodological Framework
Bottom-up cath lab procedure modeling reconciled against top-down catheter production tracking forms the analytical core of this study. Primary interviews with interventional cardiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers cross-validated against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Triangulation between demand-side procedural volume estimates and supply-side manufacturing capacity assessments resolves measurement gaps.
Historical trendline analysis of PTCA and drug-eluting balloon adoption curves informed projection frameworks across the analysis window. Segmentation dimensions span product type, application, end user, and delivery mode, with additional modeling of regulatory pathway clustering by geography. CAGRs derive from fitted growth curves applied to procedural volume trajectories and ASP erosion patterns. Forecast inputs incorporate EU MDR compliance cost pass-through assumptions and Japan PMDA real-world evidence pathway adoption rates.
Several conditions sit outside the modeled scope, including novel antithrombotic coating chemistries lacking predicate devices, and disruptive endovascular robotic platforms displacing manual catheter manipulation. Forecasts reflect documented assumptions about reimbursement stability and sterilization capacity expansion timelines. A model refresh is warranted upon material change in FDA 510(k) predicate requirements or EU MDR post-market surveillance enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
Blood Pressure Transducers Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
Global Artificial Heart Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
Aortic Stents Grafts Market
Cardiovascular Devices
UAE Cardiovascular Devices Market
Cardiovascular Devices
North America Vascular Stents Market
Cardiovascular Devices
Peripheral Vascular Devices Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Lung Stent Market
Cardiovascular Devices
Vena Cava Clips and Filters Market