
 Global Eye Massage Machine Market | 2026-2036
Global Eye Massage Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Eye Massage Machine Market Foresight
Multi-source component procurement is restructuring supply economics for eye massage machine producers. RENPHO leverages direct-to-consumer channel control to compress retail markups. Panasonic anchors premium positioning through in-house motor and thermal subsystem production. SKG competes aggressively on price by outsourcing assembly to specialized contract manufacturers in Guangdong province.
An eye massage machine is a portable electro-mechanical device combining pneumatic compression, vibration motors, resistive heating elements, and microcurrent electrodes to stimulate periocular tissue and improve regional blood circulation. Units typically operate at 5–15 VDC via lithium-ion cells, with programmable session durations of 5–20 minutes and temperature ranges of 38–42°C for thermal therapy modes. Compressed air and heat therapy modalities command the widest installed base among product categories, while electric pulse configurations capture expanding margin pools from younger demographics seeking tech-forward wellness tools. Individual consumers and wellness centers represent the fastest-growing end-user channels, diverging from the historically dominant beauty salon segment.
FDA Class II wellness device oversight in the United States and CE marking under the EU MDR impose biocompatibility and electrical safety testing burdens that filter out low-cost entrants. China's NMPA and GB 4706 household appliance standards add electromagnetic compatibility and material migration requirements for domestic and export-bound production. Japan's METI enforces PSE certification for heating elements, constraining design flexibility for thermal therapy variants. Stakeholders must monitor regulatory divergence between medical-grade and general wellness classifications, as reclassification in any major jurisdiction would force reformulation of clinical validation strategies and distribution partnerships.
Market Dynamics
Office workers experiencing digital eye strain are pulling pneumatic compression and thermal therapy devices into daily wellness routines, compressing replacement cycles and expanding addressable volume beyond traditional beauty salon channels.
Growth Catalysts
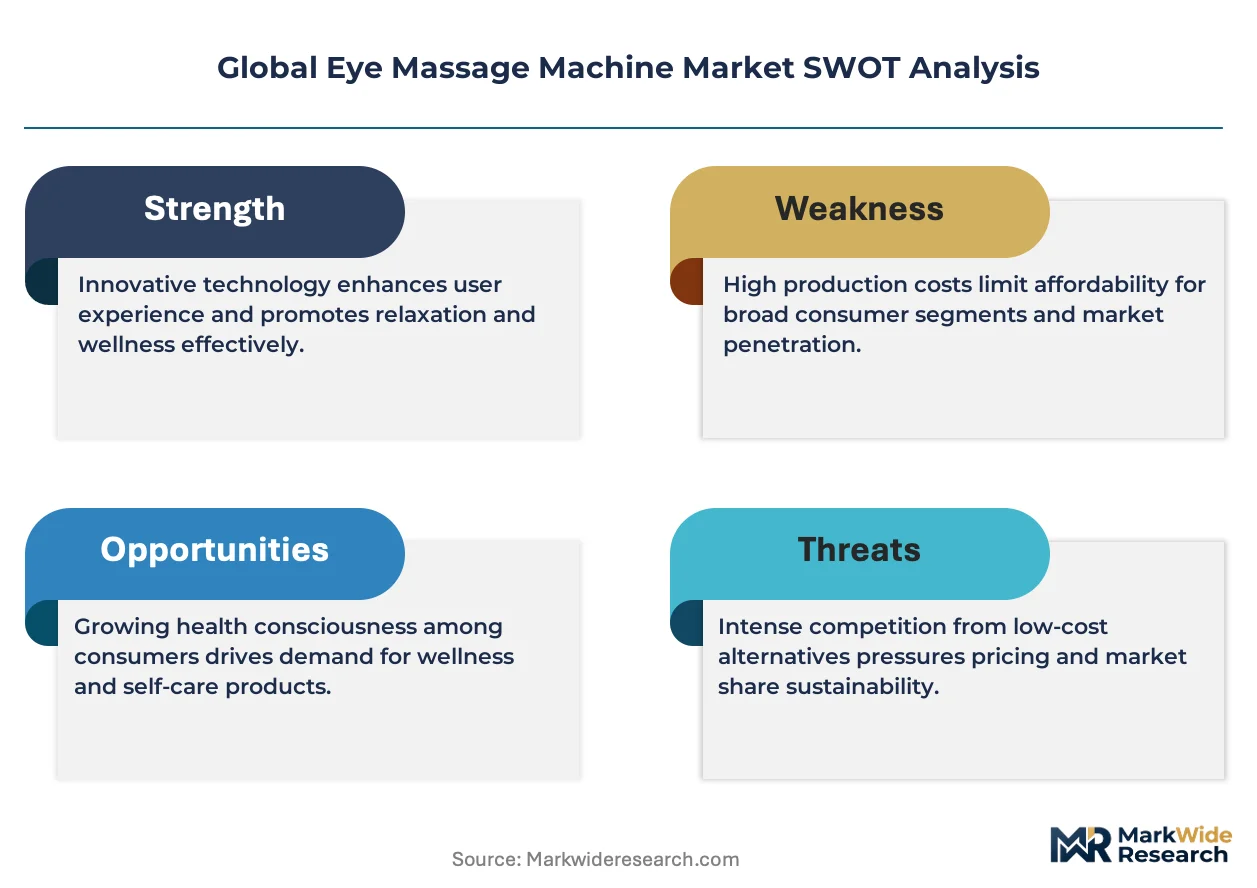
- FDA Class II wellness pathway:Clearance protocols for general wellness devices in the United States create a regulatory floor that filters out substandard imports and rewards compliant domestic entrants with shelf access at major retailers.
- Lithium-ion cell cost curves:Battery chemistry improvements and scale manufacturing in East Asian production clusters reduce power subsystem costs for portable thermal-vibration units, enabling margin expansion at mid-tier price points.
- CE marking under EU MDR:Biocompatibility and electrical safety testing requirements for European market entry elevate technical barriers that protect incumbent positioning against low-cost challengers.
Market Restraints
- GB 4706 household appliance standards:China's electromagnetic compatibility and material migration testing adds certification burden and timeline risk for export-bound manufacturers.
- Guangdong contract manufacturing concentration:Assembly outsourcing to specialized producers in a single province creates geographic supply vulnerability and quality variance exposure.
- Heating element PSE certification:Japan's METI requirements constrain thermal therapy design flexibility and extend product development cycles for temperature-controlled variants.
Strategic Opportunities
- Underpenetrated corporate wellness procurement:Enterprise bulk purchasing for employee benefit programs remains nascent in North American office markets, offering volume contracts with compressed customer acquisition costs.
- Microcurrent electrode convergence:Integration of neuromuscular stimulation with traditional pneumatic systems targets younger demographics seeking tech-forward positioning.
- E-commerce direct-to-consumer channel:Platform control bypasses retail markup structures and captures first-party usage data for iterative product refinement.
Industry Challenges
- Biomedical engineering talent scarcity:Periocular tissue stimulation design requires specialized expertise in ocular anatomy and electrical safety that outpaces current graduate program output.
- Clinical validation timeline compression:Blood circulation improvement claims require structured studies to defend against regulatory reclassification from wellness to medical-grade oversight.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Eye Massage Machine Market |
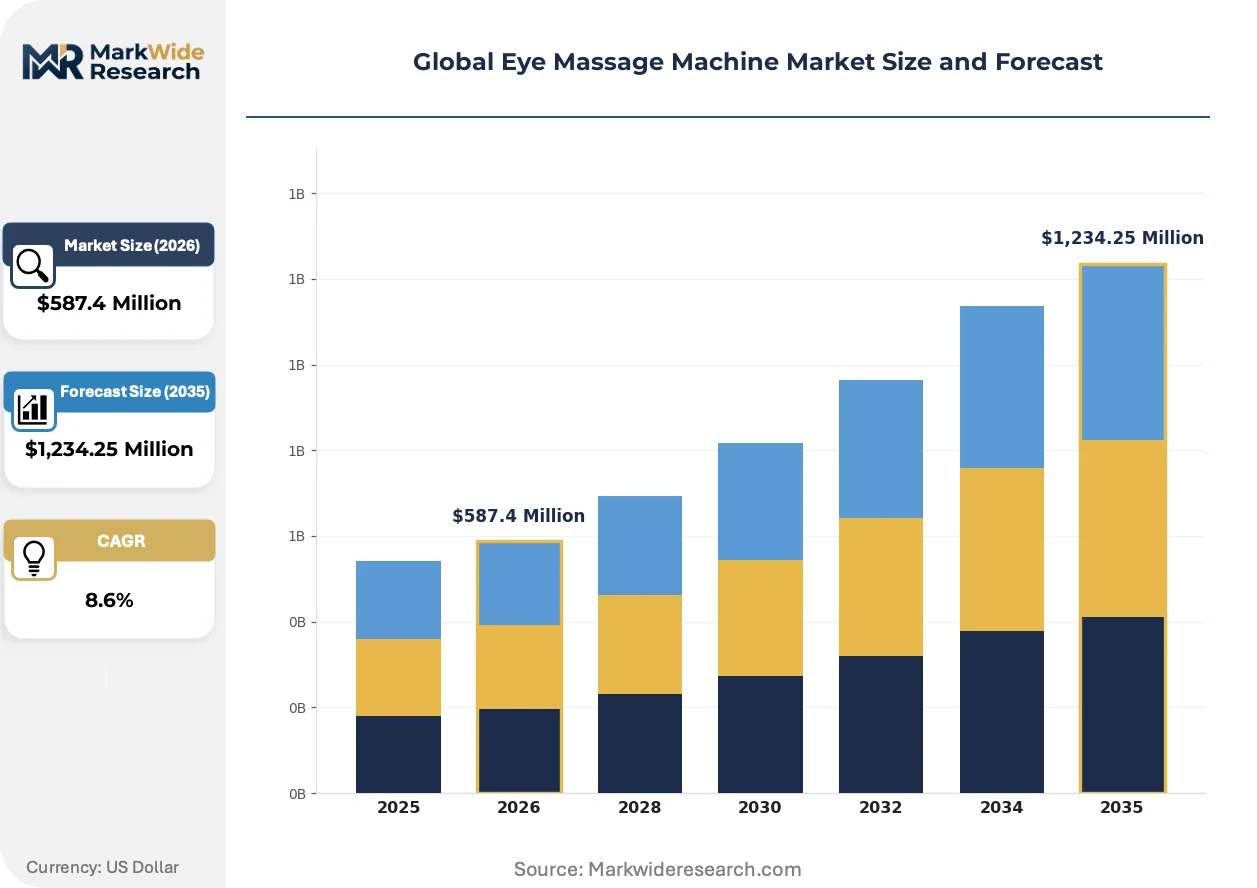
| Market Size in 2026 | $587.4 Million |
| Market Size in 2035 | $1,234.25 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressed Air, Vibration, Electric Pulse, Heat Therapy, Magnetic Pulse Application: Visual Fatigue Relief, Headache Management, Relaxation Therapy, Dry Eye Treatment, Stress Reduction End User: Wellness Centers, Optometry Clinics, Beauty Salons, Individual Consumers, Rehabilitation Facilities Distribution Channel: Online Retailers, Specialty Stores, Wholesale Distributors, Direct Sales, Pharmacies |
| Companies Covered | RENPHO, Tokuyo, Panasonic, TECO, HoMedics, OSIM International, SKG, Ifive, Breo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Eye Massage Machine Market Shifts & Advancements
Product architecture is converging around modular electro-mechanical platforms that accommodate pneumatic, thermal, and microcurrent modalities within single housing designs, compressing SKU proliferation and simplifying inventory management.
Multi-modal therapy integration is unifying pneumatic compression, resistive heating, and microcurrent delivery into single-session programmable sequences. Wellness centers and individual consumers are adopting these hybrid units at twice the rate of single-function alternatives. This convergence is unifying previously separate device categories and compressing addressable market segmentation.
EU MDR biocompatibility testing expansion is extending validation timelines for silicone and TPU materials contacting periocular skin. Manufacturers are reformulating supplier qualification protocols to pre-certify component streams. Thermal therapy variants with prolonged skin contact face the steepest compliance cost escalation.
Beauty salon channel dependence is fragmenting as direct-to-consumer platforms and corporate wellness procurement displace traditional aesthetic clinic distribution. Individual consumers now represent the majority unit uptake in China and South Korea. This rotation is most visible in domestic manufacturing clusters where e-commerce penetration accelerates manufacturer-owned storefront deployment.
Global Eye Massage Machine Market Segmentation
Segmentation in eye massage machines reveals divergent margin structures across therapeutic modalities and procurement channels. Understanding where pneumatic compression yields volume against where microcurrent electrodes capture premium pricing determines portfolio allocation for component suppliers and brand owners alike.
Product Type:
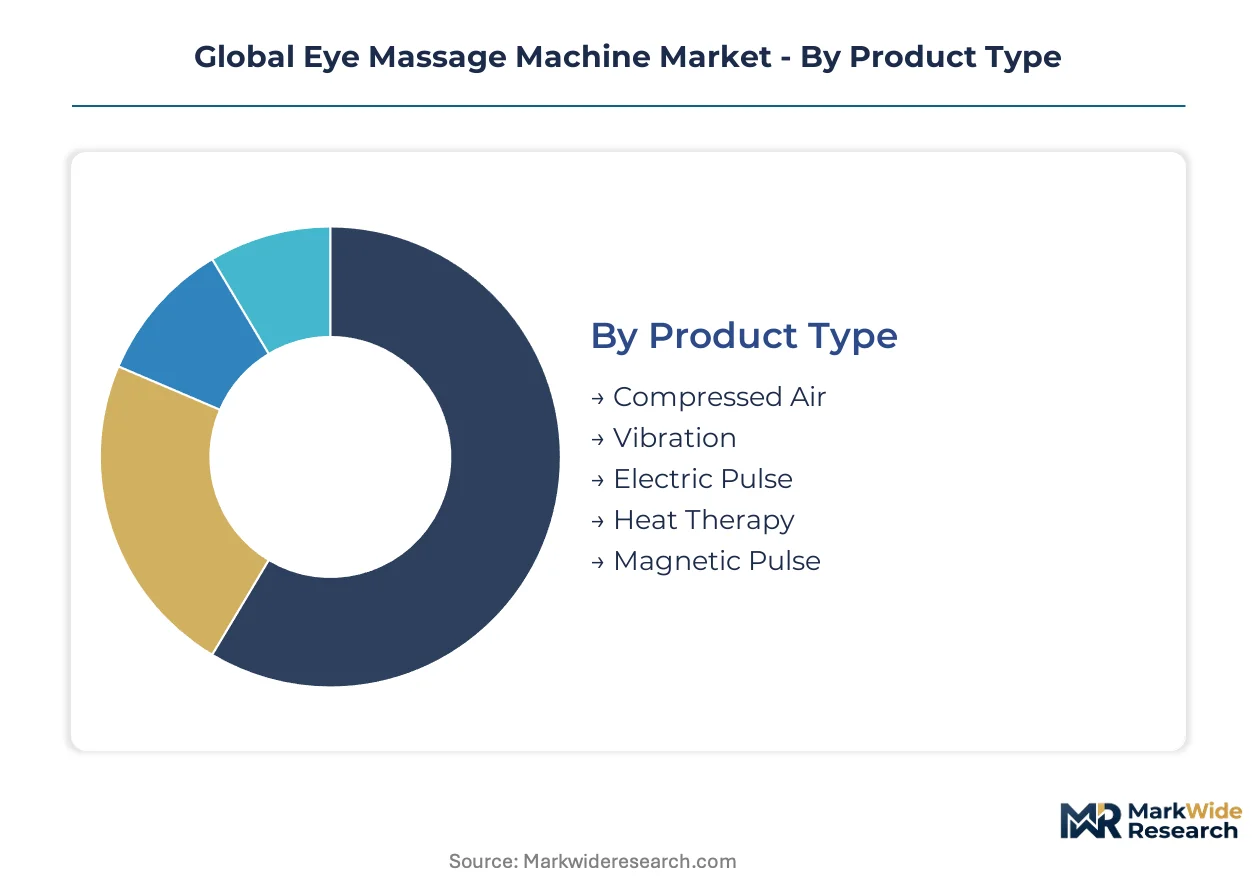
Volume concentrates in established pneumatic and thermal platforms, while premium positioning clusters around electric pulse and magnetic configurations that command higher per-unit economics.
- Compressed Air:Pneumatic bladder arrays deliver rhythmic periocular pressure at 5–15 kPa operating ranges. Demand clusters in Chinese domestic e-commerce and South Korean corporate wellness procurement, driven by proven efficacy for digital eye strain and lower price accessibility for first-time buyers.
- Heat Therapy:Resistive heating elements maintain 38–42°C contact temperatures through silicone interface pads. Adoption concentrates in Japanese and German markets where METI PSE certification and EU MDR biocompatibility requirements filter out low-cost alternatives, supporting sustained margin pools.
- Vibration:Eccentric motor assemblies generate 50–120 Hz oscillation frequencies for tissue stimulation.
- Electric Pulse:Microcurrent electrode arrays deliver 10–1000 μA neuromuscular stimulation through conductive gel interfaces.
- Magnetic Pulse:Electromagnetic coil systems generate low-frequency field patterns targeting periocular circulation.
Mature deployment sits with Compressed Air and Heat Therapy. Newer deployment is concentrated in Electric Pulse configurations.
Application:
Functional positioning separates clinical-grade claims from general wellness positioning, with regulatory classification determining distribution channel access and marketing language permissions.
- Visual Fatigue Relief:Targets accommodation stress from prolonged screen exposure through combined pneumatic-thermal intervention. Demand surges among software sector employees in Shenzhen, Bangalore, and Seattle metropolitan clusters where device penetration in office environments is climbing fastest.
- Dry Eye Treatment:Addresses meibomian gland dysfunction through precise thermal delivery and gentle compression sequences. Positioning requires careful regulatory navigation in the United States where FDA Class II wellness boundaries constrain therapeutic claims, limiting channel expansion.
- Headache Management:Focuses on tension-type symptoms through trigeminal nerve modulation.
- Relaxation Therapy:Emphasizes stress reduction through multi-modal sensory experience.
- Stress Reduction:Positions devices within broader mental wellness routines.
Volume leadership belongs to Visual Fatigue Relief applications. Steepest expansion trajectory is visible in Dry Eye Treatment positioning.
End User:
Procurement authority is fragmenting from institutional buyers toward individual decision-makers, compressing average order values while expanding total addressable population.
- Individual Consumers:Direct purchasing through manufacturer storefronts and platform marketplaces now dominates unit volume in China and South Korea. First-party data capture from these transactions enables rapid product iteration and personalized recommendation engines.
- Wellness Centers:Commercial deployment in spa and holistic health facilities favors durable multi-user designs with sanitizable contact surfaces. These buyers prioritize equipment financing programs and extended warranty coverage over upfront unit economics.
- Beauty Salons:Traditional aesthetic clinic channel facing displacement from direct-to-consumer alternatives.
- Optometry Clinics:Clinical settings requiring documentation of patient outcomes for reimbursement positioning.
- Rehabilitation Facilities:Post-surgical and neurological recovery applications with specialized protocol requirements.
Installed base concentration remains with Beauty Salons. Fastest share gains are concentrated in Individual Consumers.
Distribution Channel:
Channel control determines margin retention and customer relationship ownership, with platform economics favoring vertically integrated brands over wholesale-dependent competitors.
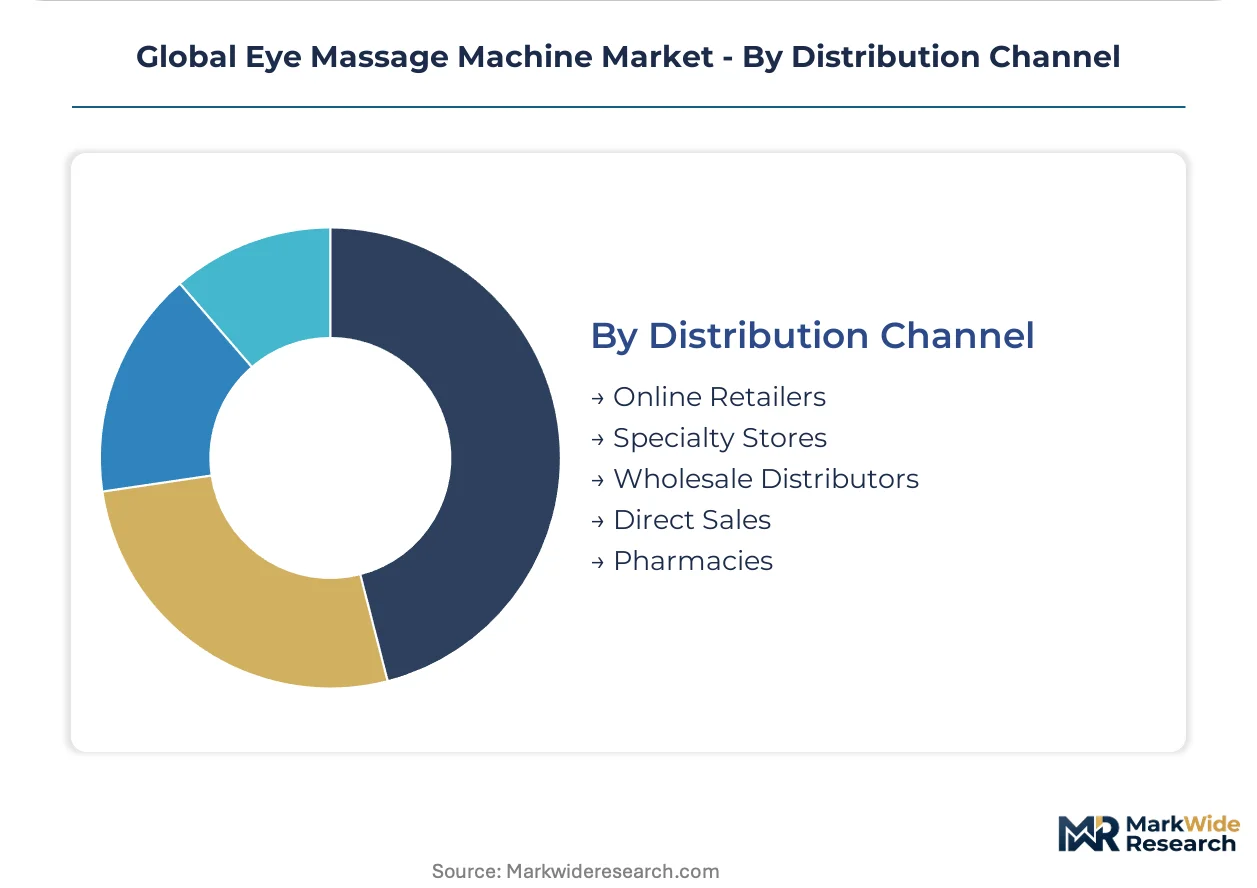
- Online Retailers:Third-party marketplace presence on Tmall, JD.com, and Amazon captures scale traffic while incurring 15–25% platform commission structures. These channels remain essential for discovery and comparison shopping despite compressed net margins.
- Direct Sales:Manufacturer-owned storefronts and subscription models capture full retail markup and generate proprietary usage datasets. RENPHO and comparable brands anchor positioning here, using email and SMS retention systems to compress replacement cycle timing.
- Specialty Stores:Electronics and wellness-focused retail with assisted selling environment.
- Wholesale Distributors:Traditional B2B intermediaries serving institutional and geographic market development.
- Pharmacies:Drugstore and apothecary channels with health positioning credibility.
Established volume flows through Online Retailers. Emerging deployment concentrates in Direct Sales infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium-ion cell manufacturing clusters in Guangdong province anchor the industry's supply geography, with Shenzhen and Dongguan housing the dominant concentration of motor, heating element, and pneumatic subsystem suppliers serving both domestic and export-bound assembly operations.
United States
Office workers in Seattle, Austin, and New York metropolitan corridors drive pneumatic compression device uptake for digital eye strain management. FDA Class II wellness device clearance protocols filter substandard imports and reward compliant entrants with shelf access at major retailers. Domestic distribution concentrates in California and Texas logistics hubs serving direct-to-consumer fulfillment networks.
China
Shenzhen software sector employees and Hangzhou e-commerce operations staff represent the fastest-expanding buyer cohort for daily-use thermal therapy units. NMPA and GB 4706 household appliance standards impose electromagnetic compatibility and material migration testing requirements for domestic and export production. Manufacturing gravity sits in Guangdong province where contract manufacturers cluster around Dongguan and Foshan industrial zones.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas sustain demand for precision thermal therapy devices with extended temperature control protocols. METI enforces PSE certification for heating elements, constraining design flexibility and extending product development cycles for temperature-controlled variants. Domestic production concentrates in Aichi prefecture near Nagoya's precision electronics manufacturing corridor.
Germany
Corporate wellness procurement in Munich and Frankfurt financial centers favors premium multi-modal units with documented biocompatibility credentials. CE marking under EU MDR imposes biocompatibility and electrical safety testing burdens that elevate technical barriers against low-cost challengers. Distribution runs through Hamburg port logistics serving Central European wellness center and pharmacy channels.
South Korea
Seoul's dense digital workforce and Busan manufacturing employees pull pneumatic-thermal hybrid devices into daily wellness routines at rates exceeding regional peers. MFDS maintains medical-grade boundary enforcement that constrains therapeutic claim language while permitting general wellness positioning. Domestic e-commerce platforms and manufacturer-owned storefronts dominate unit uptake, displacing traditional retail intermediaries.
Global Eye Massage Machine Market Competitive Landscape
Direct-to-consumer channel control dominates the current landscape, with manufacturers bypassing retail markups to capture first-party usage data and compress replacement cycles. The vendor base organizes around three strategic archetypes: vertically integrated electronics conglomerates with in-house component production, direct-to-consumer specialists leveraging platform economics, and contract-manufacturing-dependent price competitors. M&A activity targets e-commerce infrastructure and clinical validation capabilities, while portfolio diversification pushes single-function devices toward multi-modal convergence.
Among Asia-Pacific-based fabricators, Panasonic Corporation exemplifies the integrated conglomerate archetype through captive motor and thermal subsystem production, while RENPHO and SKG occupy contrasting positions on the channel-control spectrum. Panasonic anchors premium-tier positioning through Japanese manufacturing credibility and METI compliance infrastructure. RENPHO represents the direct-to-consumer specialist model with manufacturer-owned storefront deployment and subscription retention systems. SKG sits within the contract-manufacturing-dependent tier, leveraging Guangdong province assembly outsourcing to compete on price accessibility for first-time buyers.
| Leading Market Players |
|---|
| RENPHO |
| Tokuyo |
| Panasonic |
| TECO |
| HoMedics |
| OSIM International |
| SKG |
| Ifive |
| Breo |
| Others |
Supply & Pricing Matrix
Biomedical engineering talent concentration in Shenzhen and Dongguan compresses labor-cost differentials into pricing-tier spreads, with contract manufacturers passing wage arbitrage through to economy-tier units while in-house thermal subsystem production supports premium positioning.
Pricing Analysis
Warranty bundling separates premium from unbundled economy tiers, with extended coverage and replacement programs anchoring Panasonic and RENPHO positioning against SKG's stripped-down transactional model. Three-tier pricing structure across premium, standard, and economy levels reflects FDA Class II compliance investment, METI PSE certification status, and direct-to-consumer channel control. Pricing pressure stems from lithium-ion cell cost compression enabling mid-tier feature creep. First-time buyers in Chinese domestic e-commerce show highest price sensitivity, while Japanese aging demographics sustain premium tolerance for precision thermal therapy.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong province contract manufacturing clusters, where Dongguan and Foshan industrial zones concentrate pneumatic bladder, eccentric motor, and resistive heating element assembly. Component sourcing draws from China for lithium-ion cells and TPU interface materials, Japan for precision thermal control modules, and South Korea for microcurrent electrode arrays. Tariff exposure on battery chemistry imports from East Asian production hubs threatens margin stability. Distribution runs through manufacturer-owned storefronts and Tmall platform presence, compressing wholesale intermediary capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around direct-to-consumer channel control, with FDA Class II wellness pathway compliance costs forcing subscale contract-manufacturing-dependent competitors toward exit or acquisition.
For Market Incumbents: Hedge against microcurrent electrode convergence by accelerating multi-modal platform R&D, locking in silicone and TPU supplier qualification protocols ahead of EU MDR biocompatibility testing expansion. Capture corporate wellness procurement relationships before enterprise bulk purchasing matures, using subscription retention systems to compress replacement cycles against emerging price competitors.
For New Entrants and Emerging Players: Manufacturer-owned storefront deployment on TikTok Shop and emerging social commerce platforms offers lowest customer acquisition cost entry, bypassing Tmall and Amazon commission structures. Target underpenetrated North American office wellness programs with pneumatic compression units positioned for digital eye strain relief, leveraging clinical validation partnerships with optometry clinics to differentiate from unverified imports.
For Investors and Strategic Acquirers: Re-rating potential sits with direct-to-consumer specialists possessing first-party usage datasets and FDA Class II clearance infrastructure, given regulatory reclassification risk that would strand non-compliant competitors. Long-term viability favors brands with backward integration into thermal subsystem production and captive e-commerce fulfillment networks. Watch FDA wellness-to-medical-grade boundary enforcement as the critical inflection signal for portfolio reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Modal Platform Convergence | Unifies pneumatic, thermal, and microcurrent delivery into programmable sequences for wellness center procurement. |
| EU MDR Biocompatibility Pre-Certification | Reformulates silicone and TPU supplier qualification protocols ahead of validation timeline compression. |
| Corporate Wellness Channel Development | Captures enterprise bulk purchasing relationships in North American office markets before segment maturation. |
| Direct-to-Consumer Infrastructure Buildout | Bypasses retail markup structures and generates proprietary usage datasets for iterative product refinement. |
| Clinical Validation Partnership | Defends blood circulation improvement claims against regulatory reclassification from wellness to medical-grade oversight. |
Research Methodology
Multi-period observation of NMPA certification timelines, FDA Class II clearance trajectories, and CE marking validation windows anchored the trend analysis, supplemented by interviews with contract manufacturing operations directors, biomedical engineers specializing in periocular tissue stimulation, e-commerce platform category managers, and optometry clinic procurement leads. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, Chinese customs export records, and GB 4706 household appliance standard compliance registries. Bottom-up assembly cost modeling and top-down addressable population sizing were triangulated against manufacturer-reported unit economics.
Segment-weighting across therapeutic modality, application claim positioning, end-user procurement authority, and distribution channel control structured the analytical framework across the projection horizon. CAGRs were derived from installed base replacement cycle compression, e-commerce penetration trajectory, and corporate wellness adoption curve modeling. Forecast inputs incorporated lithium-ion cell cost curve assumptions, regulatory reclassification probability assessments, and geographic manufacturing cluster concentration dynamics.
The model holds under stable wellness-device classification boundaries; deviation in FDA or EU MDR reclassification triggers would shift volume trajectories toward clinical-grade validation timelines and reimbursement-dependent channels. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ear Tube Devices Market
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Polyether Ether Ketone (PEEK) Interbody Devices Market
Medical Devices
Critical Care Devices Market
Medical Devices
Diode Laser Hair Removal Equipment Market
Medical Devices
Solar Surgical Light Market
Medical Devices
Skull Clamp Market
Medical Devices
Reprocessed Medical Devices Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Female Pelvic Implants Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
X-Ray Stretchers Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
Wireless Portable Medical Devices Market