
 Mexico Aesthetic Devices Market | 2026-2036
Mexico Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Aesthetic Devices Market Foresight
Mexican dermatology equipment distributors is restructuring procurement relationships as import logistics for energy-based systems grow more complex. Sisram Medical Ltd leverages its Alma Lasers portfolio to sustain service density across private clinic networks in Mexico City. AbbVie, through its Allergan aesthetic franchise, anchors injectable product availability via direct specialist-channel relationships. Cynosure LLC competes on laser platform specialization, particularly in hair removal and fractional resurfacing configurations.
Aesthetic devices comprise electromechanical and optical systems engineered to deliver controlled thermal, acoustic, or light energy to cutaneous or subcutaneous tissue, typically operating at wavelengths between 532 nm and 10,600 nm or radiofrequencies in the 0.3–40 MHz range for tissue coagulation, collagen remodeling, or adipocyte disruption. These systems serve commercial purposes across dermatology, plastic surgery, and medical spa settings where non-surgical cosmetic outcomes replace or delay invasive procedures. Laser devices occupy the dominant revenue position due to established reimbursement adjacent-coding and versatile platform economics across multiple applications. Non-invasive technology leads volume growth as patient downtime intolerance shifts preference toward fractional and cooling-assisted modalities that reduce erythema duration. Radiofrequency devices concentrate margin pools in body contouring, where higher device ASPs and consumable attachment cycles sustain recurring revenue structures.
COFEPRIS registration requirements for Class II and III energy-based devices shape market access timelines, favoring manufacturers with established Mexican regulatory dossiers over new entrants lacking local clinical validation. NOM standards for electrical safety and electromagnetic compatibility further constrain product eligibility, filtering distributor portfolios toward ISO 13485-certified supply chains. The Federal Commission for the Protection against Sanitary Risk additionally monitors advertising claims for aesthetic outcomes, limiting direct-to-consumer positioning for certain device categories. Stakeholders must monitor whether COFEPRIS accelerates alignment with FDA 510(k) recognition pathways, which would reshape competitive entry costs for US-origin manufacturers.
Market Dynamics
COFEPRIS registration bottlenecks for Class II and III energy-based devices are compressing distributor portfolios toward manufacturers with complete technical dossiers, restructuring competitive access timelines across Mexican metropolitan clinic networks.
Growth Catalysts
- Out-of-pocket payment willingness:Patients in Mexico City and Guadalajara now finance aesthetic procedures directly, bypassing insurance constraints and accelerating clinic equipment upgrade cycles.
- NOM electrical safety standards:Harmonized certification requirements with ISO 13485 supply chains reduce technical validation friction for established distributors expanding service density.
- Fractional laser platforms:Dermatology chains deploy versatile multi-wavelength systems that address skin rejuvenation, hair removal, and resurfacing through single capital investments.
Market Restraints
- Import logistics complexity:Energy-based device shipments face extended customs clearance timelines at Mexican ports, inflating working capital requirements for distributor inventory positioning.
- Consumable attachment dependency:Radiofrequency body contouring systems require proprietary handpiece replacements, locking clinics into single-source supply relationships with limited price negotiation leverage.
- COFEPRIS clinical validation gaps:New device entrants lacking Mexican-specific efficacy data face 18-24 month registration delays versus established competitors with dossier precedent.
Strategic Opportunities
- Monterrey clinic network expansion:Private dermatology groups in Nuevo León remain underpenetrated relative to capital-region saturation, offering first-mover platform placement potential.
- Cooling-assisted modality convergence:Integration of cryogenic skin cooling with fractional laser delivery reduces erythema duration, addressing patient downtime intolerance in medical spa segments.
- Direct specialist-channel relationships:Bypassing distributor intermediaries for injectable product lines captures margin pools currently fragmented across multi-tier logistics structures.
Industry Challenges
- Laser technician certification scarcity:Qualified operators for 1,064 nm and 1,540 nm wavelength platforms command wage premiums that compress clinic operating margins in secondary cities.
- Legacy device integration friction:Radiofrequency systems purchased under prior NOM standards require electrical retrofitting to meet updated electromagnetic compatibility protocols, straining capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Aesthetic Devices Market |
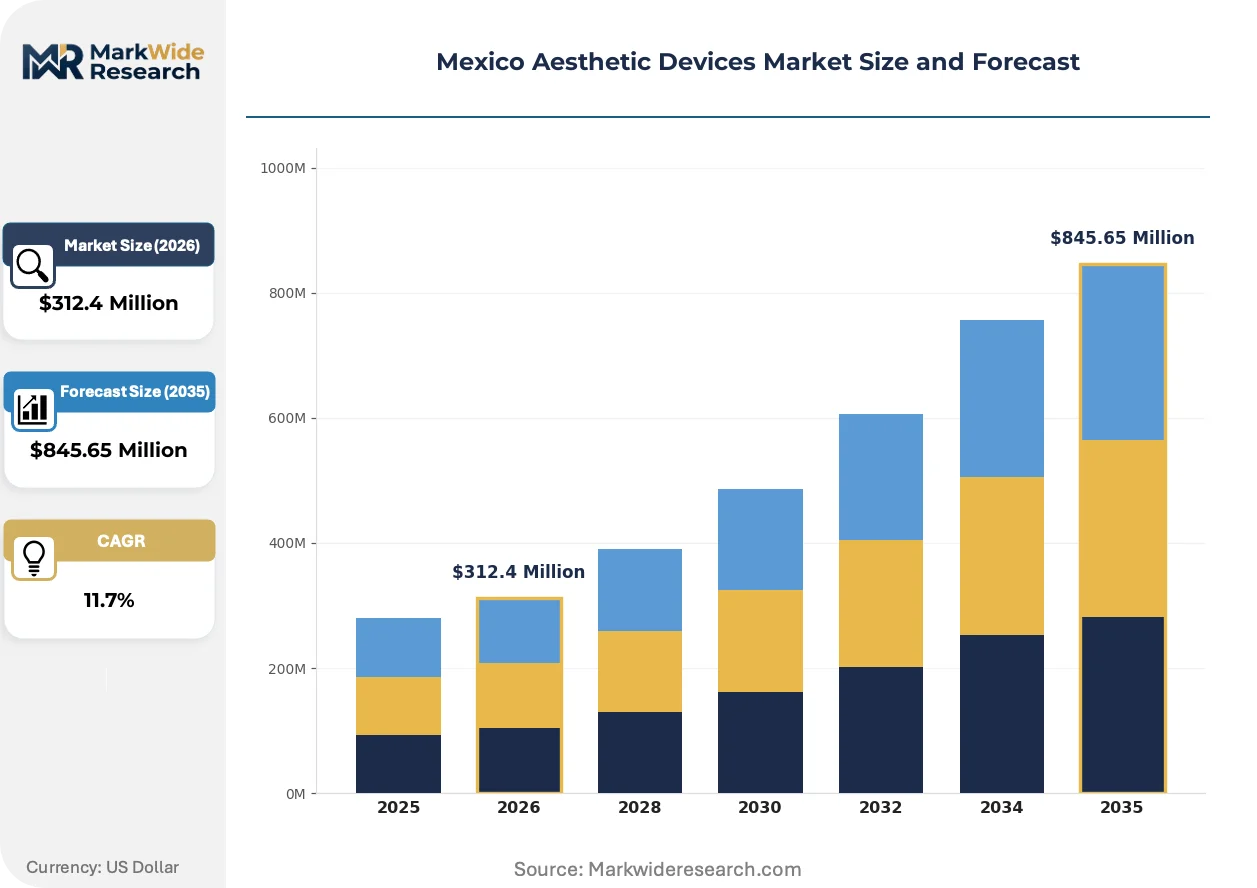
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser Devices, Ultrasound Devices, Light Therapy Devices, Radiofrequency Devices End User: Clinics, Hospitals, Home Care, Spas Technology: Non-Invasive, Minimally Invasive, Invasive, Hybrid Application: Skin Rejuvenation, Body Contouring, Hair Removal, Acne Treatment |
| Companies Covered | Sisram Medical Ltd (Alma Lasers Ltd), Venus Concept Ltd, Galderma SA, Hologic Inc, Bausch Health Companies Inc (Solta Medical Inc), AbbVie (Allergan Inc), Merz Pharma GmbH & Co KGaA, Cynosure LLC, Johnson & Johnson Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Aesthetic Devices Market Shifts & Advancements
Energy delivery precision and patient throughput economics are converging to reshape platform specifications across Mexican aesthetic service providers, with technology vendors racing to compress treatment duration without sacrificing safety margins.
Intelligent skin-cooling modules paired with fractional laser arrays are automating temperature regulation during resurfacing procedures, eliminating operator-dependent manual adjustment. High-volume dermatology chains in Mexico City deploy these systems to standardize 15-minute treatment protocols across multiple clinic locations. This automation is compressing training requirements for new technicians while reducing adverse event liability exposure for clinic operators.
COFEPRIS has tightened advertising claim scrutiny for energy-based aesthetic outcomes, requiring clinical evidence substantiation before device marketing approval. Manufacturers now submit Mexican-specific patient cohort data rather than relying solely on foreign registration dossiers. Laser platform distributors serving medical spa segments face the steepest compliance recalibration, as direct-to-consumer promotional channels face expanded prohibition.
Clinic procurement committees now unbundle device acquisition from mandatory service contracts, demanding competitive maintenance pricing after warranty expiration. Metropolitan dermatology groups negotiate three-year total cost of ownership comparisons rather than upfront capital expenditure alone. This behavioral shift concentrates purchasing authority within centralized procurement functions, displacing individual physician-driven equipment decisions prevalent through 2022.
Mexico Aesthetic Devices Market Segmentation
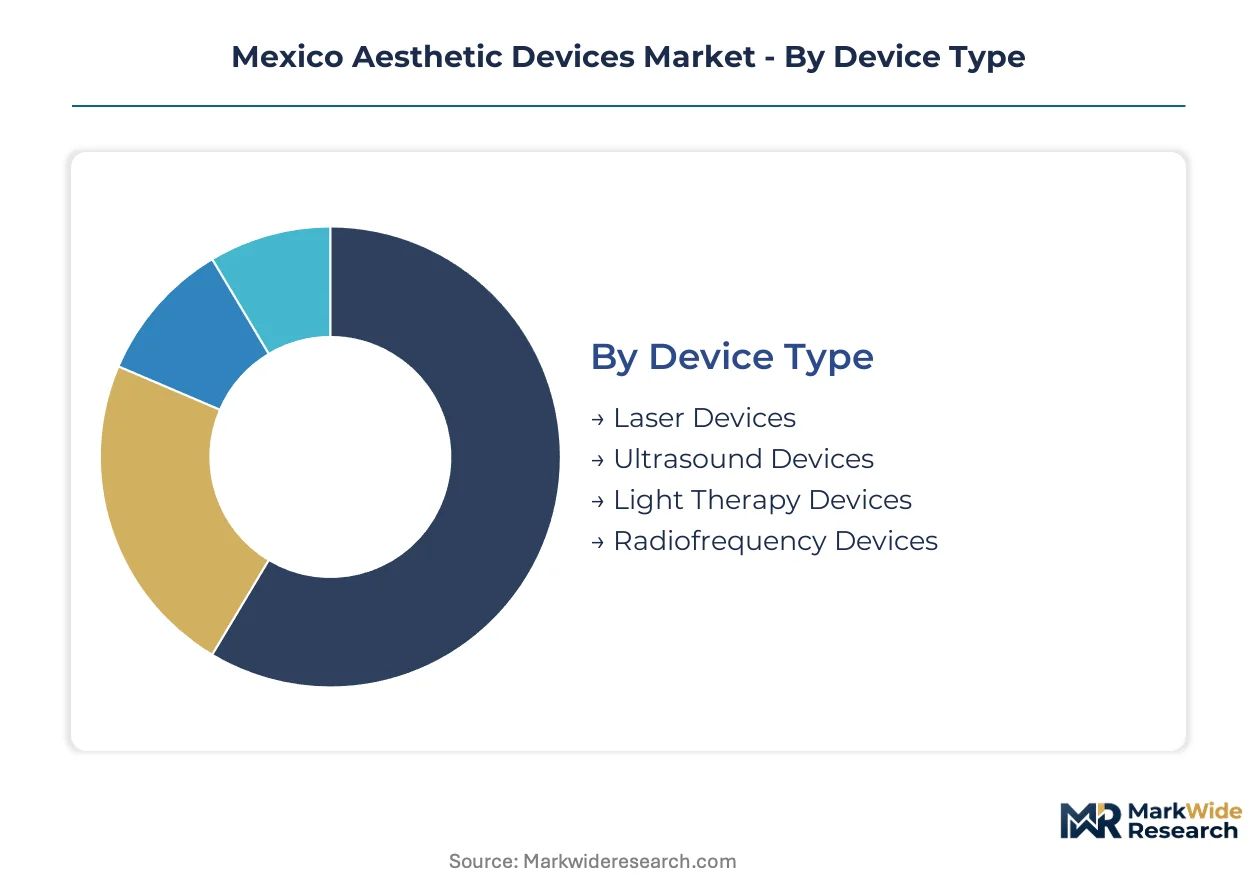
Device specifications and end-use requirements fragment procurement priorities across Mexican metropolitan clinic networks. COFEPRIS registration pathways and NOM electrical standards create divergent compliance burdens that reshape segment-level competitive dynamics.
Device Type:
Supply concentration for energy-based platforms clusters around manufacturers with complete COFEPRIS technical dossiers, compressing distributor portfolios toward established laser and radiofrequency suppliers.
- Laser Devices:Optical systems operating at 532 nm to 10,600 nm wavelengths deliver controlled thermal energy for tissue coagulation and collagen remodeling. Demand concentrates in Mexico City dermatology chains where fractional resurfacing and hair removal applications command premium placement. COFEPRIS Class III registration requirements favor established manufacturers with Mexican-specific clinical validation over new market entrants.
- Radiofrequency Devices:Electromagnetic systems at 0.3–40 MHz frequencies generate subcutaneous heating for adipocyte disruption and skin tightening. Metropolitan medical spas in Guadalajara deploy these platforms for body contouring, though proprietary handpiece dependencies lock clinics into single-source consumable relationships with limited price negotiation leverage.
- Ultrasound Devices:High-frequency acoustic energy systems target subcutaneous fat layers through non-thermal mechanical disruption.
- Light Therapy Devices:LED and IPL platforms address superficial skin conditions through selective photothermolysis at lower energy densities.
Laser devices absorb the bulk of installed capacity; radiofrequency devices are expanding most quickly.
End User:
Procurement authority is shifting from individual physicians toward centralized purchasing functions as clinic networks consolidate equipment standardization across multiple locations.
- Clinics:Private dermatology and plastic surgery practices constitute the primary deployment setting for capital-intensive laser and radiofrequency platforms. Mexico City and Guadalajara chains now finance equipment through direct patient out-of-pocket revenue, bypassing insurance constraints and accelerating upgrade cycles.
- Spas:Medical spa segments favor cooling-assisted fractional modalities that reduce erythema duration and address patient downtime intolerance. COFEPRIS advertising claim scrutiny has tightened most severely for this channel, requiring clinical evidence substantiation before device marketing approval.
- Hospitals:Institutional procurement committees demand three-year total cost of ownership comparisons rather than upfront capital expenditure alone.
- Home Care:Lower-energy LED and microcurrent devices target consumer self-treatment with reduced regulatory oversight.
Clinics command the dominant share of capital equipment deployment; spas are gaining share fastest.
Technology:
Patient throughput economics and technician certification requirements create divergent operational constraints across technology categories.
- Non-Invasive:Cooling-assisted fractional laser and external radiofrequency platforms eliminate recovery periods and expand addressable patient populations. Mexico City high-volume chains deploy intelligent skin-cooling modules to standardize 15-minute treatment protocols across multiple locations.
- Minimally Invasive:Microneedle radiofrequency and laser-assisted lipolysis systems penetrate dermal or subcutaneous tissue with reduced trauma versus surgical alternatives.
- Invasive:Surgical laser and radiofrequency-assisted procedures require operating room infrastructure and specialized credentialing.
- Hybrid:Combined modality platforms integrate multiple energy delivery mechanisms within single capital investments.
Non-invasive technology carries the heaviest installed base; hybrid configurations are climbing the fastest.
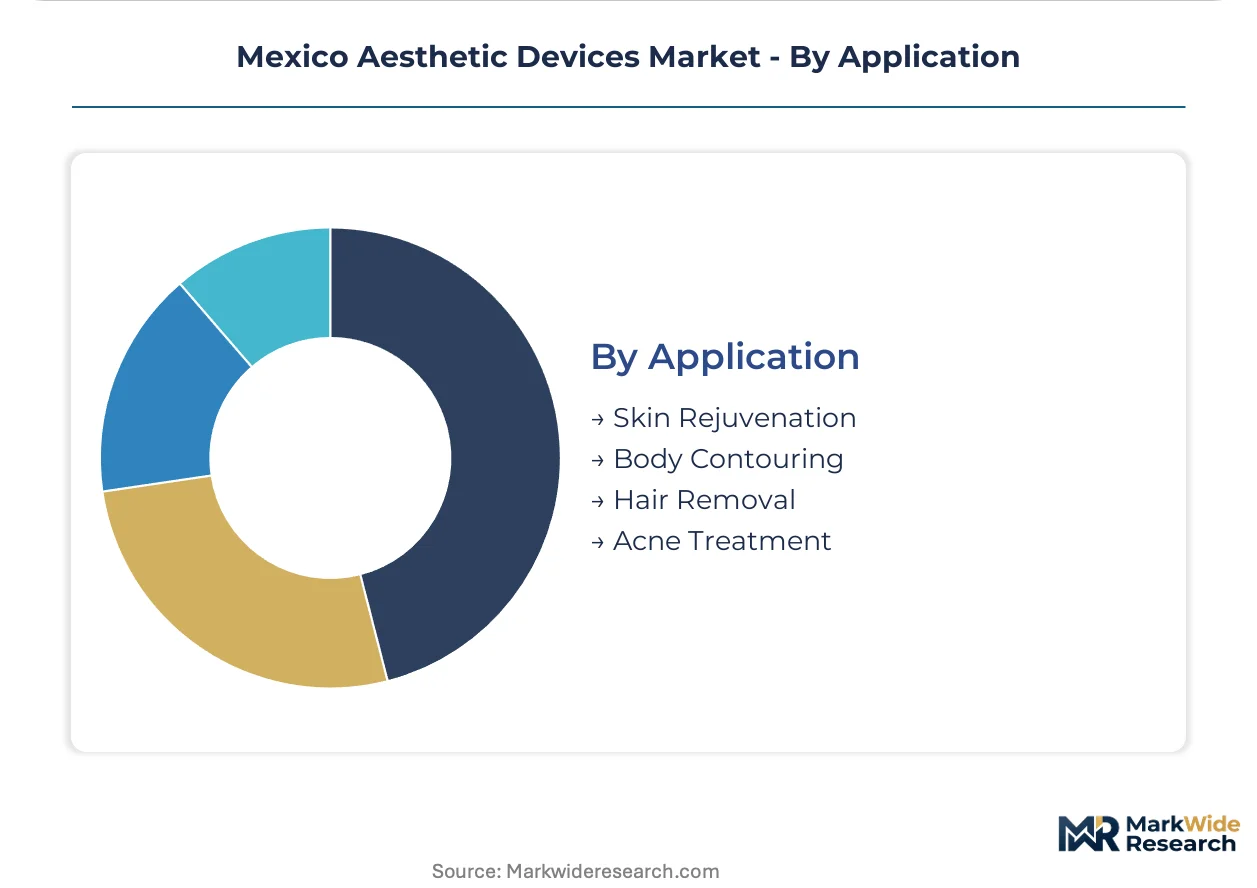
Application:
Reimbursement-adjacent coding and consumable attachment economics concentrate margin pools in specific treatment categories.
- Skin Rejuvenation:Fractional resurfacing, photorejuvenation, and collagen remodeling procedures generate recurring patient visits across age demographics. Guadalajara dermatology groups prioritize multi-wavelength platforms addressing pigmentation, texture, and laxity through single capital investments.
- Body Contouring:Non-surgical fat reduction and skin tightening applications command premium device ASPs and proprietary consumable cycles. Radiofrequency systems in this category lock clinics into single-source supply relationships that sustain recurring revenue structures for manufacturers.
- Hair Removal:755 nm and 1,064 nm laser platforms serve large addressable markets but face price compression from platform commoditization.
- Acne Treatment:Blue light and photodynamic therapy systems target younger patient demographics with lower per-procedure revenue.
Skin rejuvenation dominates procedure volume; body contouring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan medical infrastructure and COFEPRIS regulatory density anchor the Mexico Aesthetic Devices Market across distinct sub-regional clusters.
Mexico City Metro
Dermatology chains and private plastic surgery groups concentrate capital equipment procurement in the capital region, driven by affluent patient out-of-pocket payment capacity. COFEPRIS maintains its headquarters and primary technical review capacity here, accelerating registration timelines for dossier-complete manufacturers. Polanco and Santa Fe districts host the densest clinic network deployments of fractional laser and radiofrequency platforms.
Nuevo León
Monterrey's medical tourism corridor and cross-border patient flows from Texas generate sustained demand for premium aesthetic service tiers. The state's economic development agency promotes healthcare infrastructure investment through targeted fiscal incentives for private clinic expansion. San Pedro Garza García anchors high-end dermatology group consolidation, with equipment upgrade cycles running 18-24 months.
Jalisco
Guadalajara's medical spa segment leads adoption of cooling-assisted non-invasive modalities addressing patient downtime intolerance. COFEPRIS regional offices coordinate advertising claim enforcement for energy-based device marketing across western Mexico. The city's Providencia and Chapultepec corridors concentrate mid-tier clinic networks pursuing platform standardization across multiple locations.
Bajío Region
Querétaro and León manufacturing zones generate industrial workforce demand for aesthetic services alongside medical device production clusters. NOM electrical safety certification laboratories in the region reduce technical validation friction for distributor inventory positioning. León's leather and footwear industry executives drive discretionary spending on body contouring and skin rejuvenation procedures.
Northern Border States
Tijuana and Ciudad Juárez aesthetic clinics serve dual patient populations from both sides of the US-Mexico border, with pricing arbitrage driving volume. Extended customs clearance timelines at Laredo and Otay Mesa ports inflate working capital requirements for energy-based device shipments. Tijuana's Zona Río medical district specializes in same-day aesthetic procedures for California-based patients.
Mexico Aesthetic Devices Market Competitive Landscape
Global majors compete with regional champions across regulatory dossier completeness and service network density. COFEPRIS registration bottlenecks compress distributor portfolios toward manufacturers with established Mexican technical dossiers, creating tiered access timelines. Three archetypes dominate: diversified healthcare conglomerates with aesthetic divisions, laser platform specialists with full regulatory precedent, and injectable product houses with direct specialist-channel relationships. Competitive moves concentrate on distributor exclusivity negotiations and centralized procurement committee penetration.
Among Israel-based energy-based device manufacturers, Sisram Medical Ltd occupies a position exemplifying laser platform specialization with established COFEPRIS dossiers. AbbVie, through its Allergan aesthetic franchise, anchors the injectable product archetype with direct specialist-channel relationships bypassing distributor intermediaries. Cynosure LLC represents the US-origin laser specialist tier competing on platform configuration breadth. These three entities illustrate how regulatory precedent and channel control structure competitive positioning across Mexican metropolitan clinic networks.
| Leading Market Players |
|---|
| Sisram Medical Ltd (Alma Lasers Ltd) |
| Venus Concept Ltd |
| Galderma SA |
| Hologic Inc |
| Bausch Health Companies Inc (Solta Medical Inc) |
| AbbVie (Allergan Inc) |
| Merz Pharma GmbH & Co KGaA |
| Cynosure LLC |
| Johnson & Johnson Inc |
| Others |
Supply & Pricing Matrix
Centralized procurement committees at Mexico City dermatology chains now demand unbundled device acquisition from mandatory service contracts, forcing distributors to restructure pricing architectures around three-year total cost of ownership comparisons rather than upfront capital expenditure alone. This buyer consolidation compresses margin pools for manufacturers lacking competitive maintenance pricing post-warranty.
Pricing Analysis
Warranty and service contract unbundling now dominates procurement negotiations across Mexican metropolitan clinic networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification grade and COFEPRIS dossier completeness, with established manufacturers commanding brand premiums for Class III energy-based platforms. Pricing pressure stems from consumable attachment dependencies in radiofrequency body contouring systems that lock clinics into single-source relationships. Medical spa segments exhibit highest price sensitivity due to advertising claim scrutiny limiting direct-to-consumer positioning, while hospital procurement committees demonstrate lowest sensitivity given institutional budget cycles.
Supply Chain Analysis
ISO 13485 certification and NOM electrical safety compliance function as non-negotiable gating criteria for distributor portfolio inclusion across Mexican energy-based device markets. Manufacturing concentration centers on Israel, the United States, and Germany for laser platform core components, with optical resonators and cooling modules drawing from specialized semiconductor foundries. Supply chain risk concentrates in extended customs clearance timelines at Laredo and Otay Mesa ports, inflating working capital requirements for inventory positioning. Distribution runs through authorized distributor networks with exclusive territorial agreements, though direct specialist-channel relationships are displacing multi-tier logistics for injectable product lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where control over consumable attachment cycles and regulatory dossier completeness determines margin capture. Manufacturers pursuing backward integration into optical component production secure supply security while distributors building direct clinician relationships bypass intermediaries.
For Market Incumbents: Lock in distributor exclusivity agreements across Monterrey and Guadalajara clinic networks before COFEPRIS registration bottlenecks ease for new entrants. Invest in Mexican-specific clinical validation cohorts to accelerate dossier approval timelines versus competitors relying solely on foreign data. Defensive consolidation through service contract repricing captures maintenance revenue streams currently fragmented post-warranty. For New Entrants and Emerging Players: Launch via hybrid direct-to-clinic partnerships in Nuevo León's underpenetrated dermatology corridor, bypassing established distributor intermediaries that favor incumbent manufacturers with complete technical dossiers. Target medical spa segments in Guadalajara with cooling-assisted fractional modalities addressing patient downtime intolerance, leveraging faster regulatory pathways for lower-risk device classifications. White-space penetration depends on proprietary handpiece economics that break single-source lock-in dynamics. For Investors and Strategic Acquirers: Re-rating potential sits with laser platform specialists possessing established COFEPRIS precedents given regulatory acceleration as a catalyst for geographic expansion. Long-term viability over the projection horizon favors manufacturers with vertical integration into consumable production and software companion development. Acquisition target archetypes include regional distributors with dense Mexico City service networks. Monitor COFEPRIS alignment with FDA 510(k) recognition pathways as the signal to watch for competitive entry cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Dossier Acceleration | Established Mexican clinical validation compresses registration timelines versus foreign-data reliance. |
| Consumable Attachment Development | Proprietary handpiece cycles sustain recurring revenue structures in radiofrequency body contouring. |
| Direct Specialist-Channel Relationships | Bypassing distributor intermediaries captures margin pools fragmented across multi-tier logistics. |
| Intelligent Cooling Module Integration | Automated temperature regulation standardizes 15-minute protocols across high-volume clinic chains. |
| Monterrey Network Expansion | Nuevo León's medical tourism corridor offers first-mover placement in underpenetrated premium segments. |
Research Methodology
COFEPRIS registration databases, NOM electrical safety certification records, and Mexican customs import declarations formed the secondary backbone for supply-side validation. Primary interviews with biomedical engineers at dermatology chains, GPO contracts managers at hospital systems, regulatory affairs leads at energy-based device manufacturers, and distributor procurement heads combined with secondary triangulation. Bottom-up and top-down approaches cross-validated installed base estimates against capital expenditure disclosures and clinic network expansion announcements.
Bottom-up modeling segmented the market by device type, end user, technology, and application across the analysis window. CAGRs derived from procedure volume growth, equipment replacement cycles, and patient out-of-pocket payment capacity expansion. Industry-specific inputs included COFEPRIS registration timeline data, NOM standard revision schedules, and metropolitan clinic network consolidation patterns.
Regulatory pathway shifts, import logistics disruptions, and technician certification scarcity are the dominant revision risks to modeled projections. Forecasts reflect assumptions about COFEPRIS processing efficiency and distributor portfolio concentration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spain Aesthetic Devices Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
Infusion Management Market
Medical Devices
Scoliosis Traction Chairs Market
Medical Devices
Global Brain Implants Market
Medical Devices
Centrifugation-Free Sperm Separation Systems Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
United Kingdom Contraceptive Devices Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
MRI Safe Defibrillator Market
Medical Devices
3D-Printed Prosthetic Implants Market
Medical Devices
Global Artificial Kidney Market
Medical Devices
Cystic Fibrosis Devices Market
Medical Devices
Lower Limb Prosthetics Market