
 Asia-Pacific Ostomy Drainage Bags Market | 2026-2036
Asia-Pacific Ostomy Drainage Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ostomy Drainage Bags Market Analytics
Aftermarket service revenue is rewriting profit architecture across the Asia-Pacific ostomy landscape. Coloplast A/S anchors its regional position through specialized stoma care nurse training programs that lock in patient loyalty. Hollister Inc. leverages direct-to-patient subscription models to sustain recurring revenue streams in Australia and Japan.
Asia-Pacific ostomy drainage bags are medical collection devices, typically constructed from multilayer odor-barrier films combining polyethylene with activated carbon filters, designed to receive and contain effluent from surgically created stomas following colorectal, urological, or ileal procedures. Two-piece systems dominate hospital procurement due to their modularity and reduced per-change costs, while silicone-based materials are gaining fastest in homecare channels where skin sensitivity and extended wear time command premium positioning. Closed systems retain mature share in pediatric and bedridden segments where controlled disposal protocols prevail.
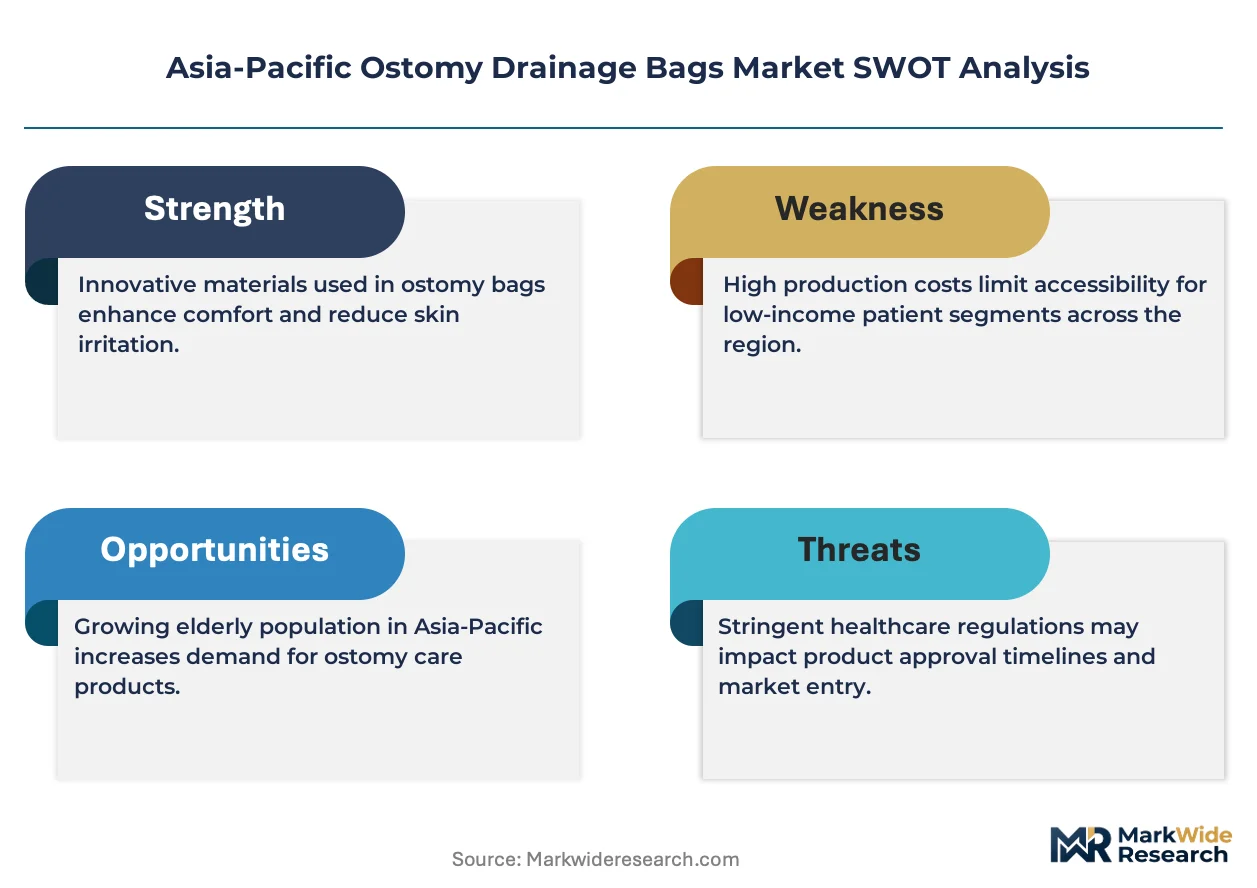
Japan's PMDA and Australia's TGA enforce biocompatibility and sterility standards that shape product registration timelines and clinical evidence requirements for bag adhesives and barrier films. China's NMPA medical device classification rules are tightening quality system audits, filtering lower-tier domestic suppliers from tertiary hospital tenders. Stakeholders must monitor how India's CDSCO pending medical device rules will reshape import licensing and local testing obligations for ostomy accessories.
Market Dynamics
Japan's Ministry of Health, Labour and Welfare reimbursement expansion for ostomy supplies is restructuring patient access economics across the Asia-Pacific region, shifting procurement power from hospitals toward homecare channels.
Growth Catalysts
- Aging Demographics:China's expanding geriatric population and rising colorectal cancer incidence are enlarging the addressable patient pool for surgical stoma procedures.
- Reimbursement Policy:Japan's MHLW coverage expansion for ostomy accessories reduces out-of-pocket burdens and accelerates product uptake in community settings.
- Silicone Material Advancement:Skin-friendly silicone-based barrier films enable extended wear times, commanding premium positioning in Australia's homecare segment.
Market Restraints
- Input Cost Volatility:Medical-grade polyethylene and activated carbon filter supply fluctuations compress margins for multilayer odor-barrier film manufacturers.
- Regulatory Friction:China's NMPA quality system audit tightening filters lower-tier domestic suppliers from tertiary hospital procurement tenders.
- Technical Limitation:Adhesive biocompatibility requirements under Japan's PMDA standards extend clinical evidence timelines for new barrier formulations.
Strategic Opportunities
- Rural Penetration:India's tier-2 and tier-3 cities present underpenetrated demand for ostomy care products as surgical infrastructure expands.
- Subscription Commerce:Direct-to-patient recurring delivery models in Australia and Japan bypass traditional distributor markups and capture lifetime value.
- Telehealth Integration:Remote stoma nurse consultation platforms combined with automated reorder systems reduce patient leakage and improve adherence.
Industry Challenges
- Specialized Nursing Shortage:Certified stoma care nurse scarcity across Southeast Asia limits post-operative patient education and product conversion rates.
- Certification Timeline Compression:Australia's TGA biocompatibility and sterility validation requirements delay product registration for novel adhesive technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ostomy Drainage Bags Market |
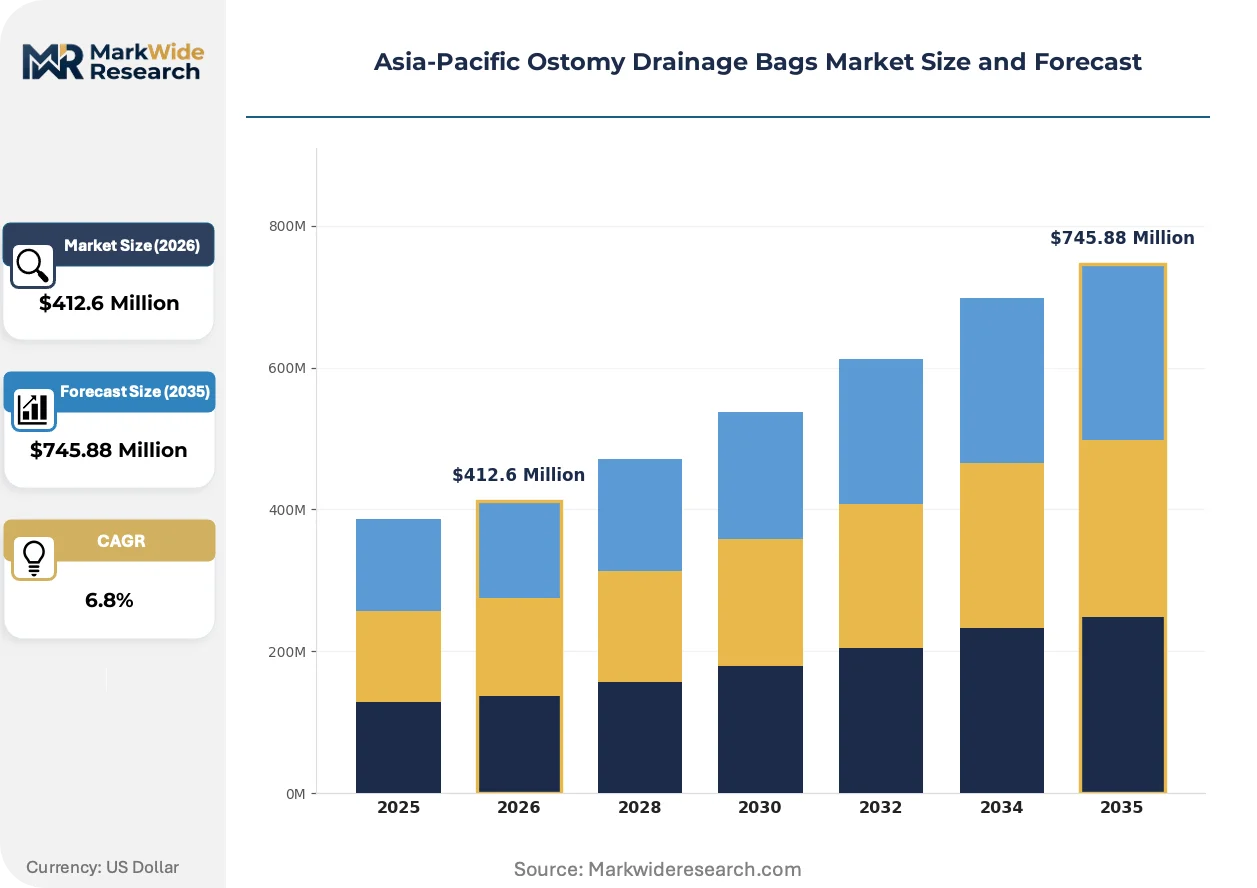
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: One-Piece, Two-Piece, Closed System, Open System Material: PVC, Silicone, Polyurethane, Latex End User: Hospitals, Homecare, Long-Term Care Facilities, Ambulatory Surgical Centers Distribution Channel: Retail Pharmacies, Online Stores, Direct Sales, Wholesalers |
| Companies Covered | B. Braun Melsungen AG, Salts Healthcare Ltd, Coloplast A/S, Pelcin Healthcare Ltd, Flexicare Medical Ltd, ConvaTec Inc., Alcare Co. Ltd, Dansac, Hollister Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ostomy Drainage Bags Market Evolving Landscape
Digital health infrastructure and material science advances are converging to transform how ostomy patients manage care outside institutional settings across Asia-Pacific markets.
Smart ostomy systems incorporating Bluetooth-enabled fill-level sensors and mobile application connectivity are virtualizing traditional manual inspection routines. Homecare patients in Japan and Australia are adopting these connected devices fastest, reducing emergency leakage incidents and unscheduled clinical visits. This sensor-to-cloud architecture is virtualizing the role of district nurses, compressing face-to-face consultation frequency while maintaining outcome accountability.
China's NMPA medical device classification rules are tightening quality system audits and clinical evidence standards for ostomy bag adhesives and barrier films. Domestic manufacturers face elevated compliance costs, forcing portfolio rationalization toward higher-margin two-piece systems. Tertiary hospital procurement committees in Beijing and Shanghai are responding by consolidating supplier lists around ISO 13485-certified producers with established biocompatibility dossiers.
Patients across the region are consolidating purchase decisions through hospital discharge coordinators and stoma care nurse recommendations rather than independent retail selection. This channel concentration is displacing pharmacy-centric distribution in favor of institutional referral networks with embedded education protocols. South Korea's MFDS-registered homecare service providers are capturing this shift through bundled product-and-training packages delivered at point of surgical recovery.
Asia-Pacific Ostomy Drainage Bags Market Segmentation
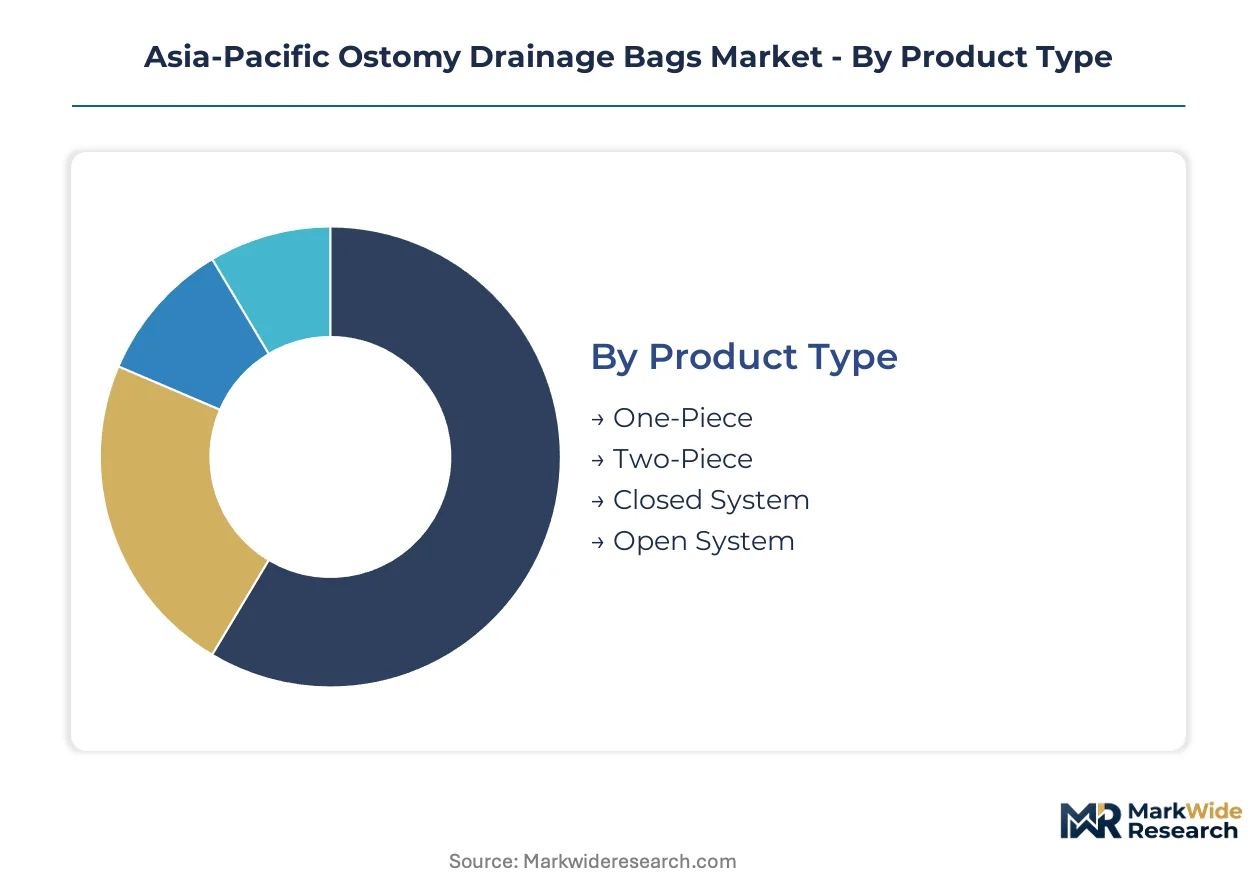
Product architecture across Asia-Pacific ostomy drainage bags determines service attachment rates and patient lifetime value. Material selection and channel configuration directly shape reimbursement eligibility and clinical outcomes in this regulated medical device category.
Product Type:
After-sales service intensity varies sharply across system architectures, with modularity driving replacement part revenue and skin barrier consumables.
- Two-Piece:Modular flange-and-bag separation allows independent barrier replacement, reducing per-change costs for hospital procurement committees. China's tertiary hospitals favor this configuration for colorectal surgery wards where nursing staff turnover demands standardized, trainable procedures.
- One-Piece:Integrated adhesive-barrier construction suits homecare patients seeking simplified application without flange alignment. Australia's stoma care nurses recommend these for elderly patients with limited dexterity, though higher disposal frequency elevates long-term supply costs.
- Closed System:Sealed, drain-free design serves pediatric and bedridden segments where controlled disposal protocols prevent contamination.
- Open System:Drainable tail closure enables multiple uses per bag, preferred by mobile adults managing high-output ileostomies.
Two-Piece holds the largest share; momentum sits with One-Piece as homecare channels expand.
Material:
Cost tier stratification separates premium silicone formulations from commodity PVC in procurement tenders and patient out-of-pocket decisions.
- Silicone:Hypoallergenic barrier films with extended wear properties command premium positioning in Japan's reimbursed homecare segment. PMDA biocompatibility dossiers for silicone adhesives require lengthier clinical validation than synthetic alternatives.
- Polyurethane:Breathable, flexible membranes balance durability with skin conformity, gaining traction in Australia's humid coastal regions where moisture management dominates patient complaints.
- PVC:Cost-optimized multilayer construction dominates volume tenders in India's price-sensitive institutional market.
- Latex:Natural rubber barriers retain niche use where elasticity and conformability outweigh allergy concerns.
Silicone captures premium value; polyurethane is expanding most quickly on skin sensitivity positioning.
End User:
Application setting dictates regulatory pathway, with institutional procurement governed by NMPA and TGA quality system audits versus homecare reimbursement codes.
- Hospitals:Surgical wards and stoma clinics drive initial patient conversion through discharge coordinator product selection. China's NMPA tightening filters supplier lists to ISO 13485-certified manufacturers with established biocompatibility documentation.
- Homecare:Self-managed patients generate recurring revenue through subscription replenishment models in Japan and Australia. Japan's MHLW reimbursement expansion for community-based ostomy supplies accelerates this channel's expansion.
- Long-Term Care Facilities:Nursing home procurement prioritizes staff efficiency and infection control in bulk purchasing decisions.
- Ambulatory Surgical Centers:Same-day discharge protocols concentrate initial product education and starter kit distribution.
Hospitals anchor volume; homecare is gaining share fastest on reimbursement policy tailwinds.
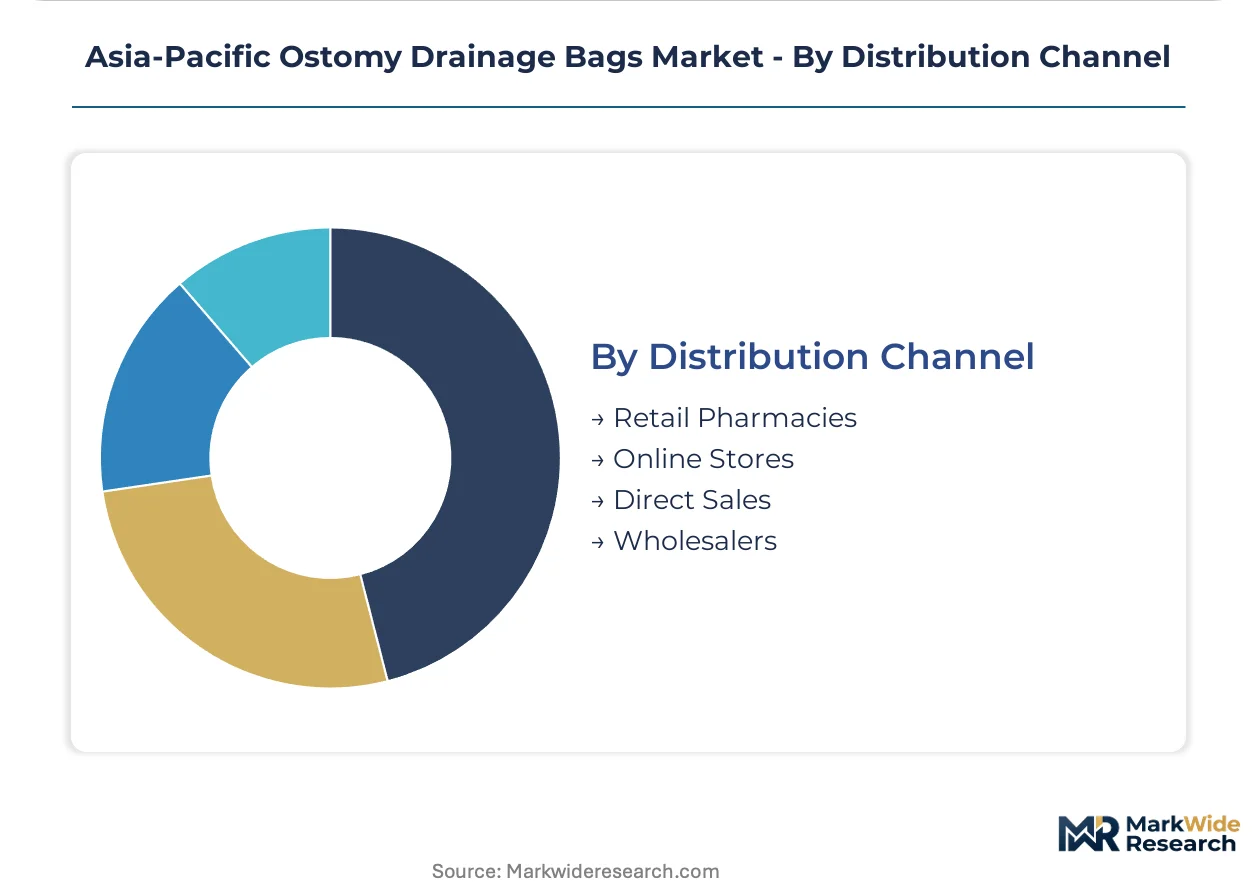
Distribution Channel:
Customer type concentration shifts purchase influence from retail pharmacists toward institutional discharge planners and direct manufacturer relationships.
- Direct Sales:Manufacturer-to-patient subscription models bypass distributor markups and capture lifetime value through automated replenishment. Hollister Inc. deploys this channel in Australia and Japan with embedded stoma nurse telehealth support.
- Online Stores:E-commerce platforms aggregate patient reviews and comparison tools, displacing pharmacy-centric selection in South Korea's digitally native patient population.
- Retail Pharmacies:Community pharmacy networks retain relevance for emergency replacement purchases and rural access.
- Wholesalers:Institutional distributors serve hospital procurement committees with consolidated medical-surgical supply contracts.
Direct Sales commands margin leadership; Online Stores show steepest expansion trajectory on digital health infrastructure convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for medical-grade ostomy drainage systems concentrates in East Asian polymer processing clusters and European-owned regional facilities. Japan's reimbursement infrastructure and China's surgical volume expansion are redrawing procurement gravity across the Asia-Pacific region.
China
Aging demographics and rising colorectal cancer incidence are enlarging the surgical stoma patient pool in tier-1 cities. NMPA quality system audits are filtering lower-tier domestic suppliers from Beijing and Shanghai tertiary hospital tenders. The Yangtze River Delta polymer processing corridor supplies multilayer odor-barrier films to ISO 13485-certified converters serving hospital procurement committees.
Japan
Homecare channel expansion is accelerating as MHLW reimbursement policies reduce out-of-pocket burdens for community-based ostomy supplies. PMDA biocompatibility standards for silicone adhesives extend clinical evidence timelines for new barrier formulations. The Kanto region anchors specialist stoma care nurse training infrastructure that locks in patient product loyalty post-discharge.
India
Surgical infrastructure expansion in tier-2 and tier-3 cities is opening underpenetrated demand for ostomy care products. CDSCO pending medical device rules are reshaping import licensing and local testing obligations for ostomy accessories. Maharashtra's medical device manufacturing clusters are developing domestic barrier film capabilities to serve price-sensitive institutional procurement.
Australia
Direct-to-patient subscription models are capturing lifetime value through automated replenishment systems bypassing traditional distributor markups. TGA biocompatibility and sterility validation requirements delay registration timelines for novel adhesive technologies. Sydney and Melbourne homecare service networks are integrating telehealth stoma nurse consultation with product delivery platforms.
South Korea
Digital health infrastructure convergence is displacing pharmacy-centric distribution through bundled product-and-training packages delivered at surgical recovery points. MFDS-registered homecare service providers are consolidating purchase influence through hospital discharge coordinator relationships. The Seoul Capital Area dominates connected ostomy device pilot programs linking fill-level sensors to mobile application platforms.
Asia-Pacific Ostomy Drainage Bags Market Competitive Landscape
Full-spectrum multinationals and specialized regional fabricators split the market between premium reimbursed segments and price-optimized institutional tenders. Vendor concentration remains moderate with tiered positioning across material technology sophistication and channel reach. Two strategic archetypes dominate: integrated stoma care solution providers combining hardware with nurse education infrastructure, and component-focused manufacturers supplying barrier films and adhesives to third-party assemblers. Competitive moves center on backward integration into medical-grade polymer supply and direct-to-patient subscription platform deployment.
Within the integrated solution tier, Coloplast A/S and Hollister Inc. exemplify archetypes anchoring premium positioning through service attachment. Among regional specialists, Alcare Co. Ltd and Pelcin Healthcare Ltd occupy positions bridging domestic regulatory compliance with cost-optimized manufacturing. Dansac represents the European-origin specialist archetype maintaining regional presence through distributor partnerships rather than direct infrastructure investment.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Salts Healthcare Ltd |
| Coloplast A/S |
| Pelcin Healthcare Ltd |
| Flexicare Medical Ltd |
| ConvaTec Inc. |
| Alcare Co. Ltd |
| Dansac |
| Hollister Inc. |
| Others |
Value Network & Pricing Analysis
Single-source dependency on medical-grade polyethylene resin from the Yangtze River Delta determines both pricing tier spreads and supply chain shape across Asia-Pacific ostomy drainage bag manufacturing. NMPA quality system audit tightening filters lower-tier suppliers from tertiary hospital tenders, compressing margins for domestic converters while elevating certified producers to premium positioning.
Pricing Analysis
Japan's MHLW reimbursement expansion dictates the pricing tier structure across Asia-Pacific ostomy care markets. Three-tier pricing separates silicone-based premium systems with extended wear properties from standard polyurethane configurations and economy PVC tenders serving India's price-sensitive institutional procurement. Price differentiation rests on PMDA biocompatibility certification status and ISO 13485 quality system documentation. Cost compression in the PVC tier intensifies because NMPA audit requirements force portfolio rationalization toward higher-margin configurations. Hospital procurement committees in China demonstrate highest price sensitivity, while Australia's homecare subscription patients accept premium positioning for skin-friendly silicone formulations.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate procurement relationships between multilayer film converters and tertiary hospital systems across China, Japan, and Australia. Medical-grade polyethylene resin, activated carbon filter substrates, and silicone adhesive formulations anchor raw material dependencies. Geographic supply concentration centers on the Yangtze River Delta polymer processing corridor, Osaka medical device clusters, and Maharashtra emerging barrier film capabilities. Single-source vulnerability from activated carbon filter supply constrains odor-barrier film production during commodity volatility spikes. Distribution runs through institutional wholesalers serving hospital procurement committees, direct-to-patient subscription platforms in reimbursed markets, and online aggregators displacing pharmacy-centric selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific ostomy drainage bags are approaching a platform-economics inflection where telehealth-integrated subscription models and sensor-to-cloud architectures reshape patient retention and lifetime value capture.
For Market Incumbents: Insulate recurring revenue streams by deepening backward integration into medical-grade polymer supply and deploying captive stoma care nurse training infrastructure that locks in post-discharge product loyalty. Coloplast A/S exemplifies this archetype through specialized education programs. Counter direct-to-patient subscription entrants by embedding automated replenishment with telehealth consultation platforms that reduce patient leakage to competitor ecosystems. For New Entrants and Emerging Players: Pursue India's tier-2 and tier-3 city surgical infrastructure expansion where CDSCO pending device rules have delayed multinational penetration and created temporary white-space for compliant domestic assemblers. Target China's secondary hospital tier below NMPA audit-filtered tertiary procurement committees, where ISO 13485 certification requirements remain less stringent. Anchor go-to-market through bundled product-and-training packages delivered at surgical discharge points, mirroring South Korea's MFDS-registered homecare service provider model. For Investors and Strategic Acquirers: The market sits at a reimbursement-policy acceleration phase that favors integrated solution providers combining hardware with nurse education infrastructure over component-focused barrier film suppliers. Long-term viability favors acquirers of telehealth-enabled subscription platforms with demonstrated patient adherence metrics. Watch Japan's MHLW reimbursement expansion velocity as the signal indicating whether homecare channel shift sustains premium pricing or triggers competitive compression.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | MHLW policy expansion in Japan unlocks community-based ostomy supply access. |
| Hospital System Partnership | Discharge coordinator relationships concentrate purchase influence at surgical recovery. |
| Software Companion Development | Bluetooth-enabled fill-level sensors reduce emergency leakage incidents. |
| Backward Integration | Captive medical-grade polymer supply insulates margin from resin volatility. |
| Regulatory Certification Pathway | PMDA biocompatibility dossiers extend clinical evidence timelines for silicone adhesives. |
Research Methodology
Cross-validation between primary interviews with stoma care nurses, hospital procurement managers, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from NMPA device registration databases, PMDA approval filings, MHLW reimbursement bulletins, and hospital procurement tender records. Bottom-up patient population estimates by surgical procedure volume triangulate with top-down medical device trade flow analysis across the analysis window.
Calibration against historical reimbursement policy implementation timelines and surgical infrastructure expansion patterns shapes the analytical framework. Segmentation dimensions modeled include product system architecture, material technology tier, end-user setting, and distribution channel configuration. CAGRs derive from procedure volume elasticity to reimbursement access and homecare channel penetration rates across the projection horizon. Input assumptions incorporate colorectal cancer incidence trajectories, aging demographic shifts, and regulatory audit intensity evolution.
The forecast holds incumbent behavior within observed patterns; aggressive direct-to-patient subscription expansion by multinational device manufacturers or accelerated NMPA quality system enforcement would shift outcomes. Macroeconomic deviation, regulatory timeline compression, or smart ostomy system technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Suture Sleeve Kit Market
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
Western Europe Sterile Gloves Market
Medical Supplies
Finger Splint Market
Medical Supplies
Petri Dishes Market
Medical Supplies
Human Acellular Dermis Market
Medical Supplies
Catgut Sutures Market
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
Safety Lancet Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Americas Safety Lancet Market
Medical Supplies
Single-Use Sterilization Wraps Market
Medical Supplies
Abdominal Compression Garments Market