
 Smart Stairlift Market | 2026-2036
Smart Stairlift Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Stairlift Market Insights
The direct-to-installer channel is narrowing as manufacturers build captive service networks. Stannah Lifts Holdings Ltd. leverages its British manufacturing base to control aftermarket parts flow. Savaria Corporation anchors North American distribution through vertical integration into dealer training. Bruno Independent Living Aids Inc. specializes in compact rail systems for older housing stock.
A smart stairlift integrates motorized carriage, obstacle-detection sensors, and wireless connectivity to transport individuals across staircases with load capacities typically spanning 120–160 kg and rail angles up to 52 degrees. The equipment serves residential and institutional users requiring mobility assistance without structural elevator installation. Straight stairlifts dominate volume due to standardized rail fabrication, while curved units command premium positioning because custom rail bending absorbs higher labor and engineering overhead. Wireless control systems are gaining share against wired alternatives as retrofit installations prioritize minimal wall disruption.
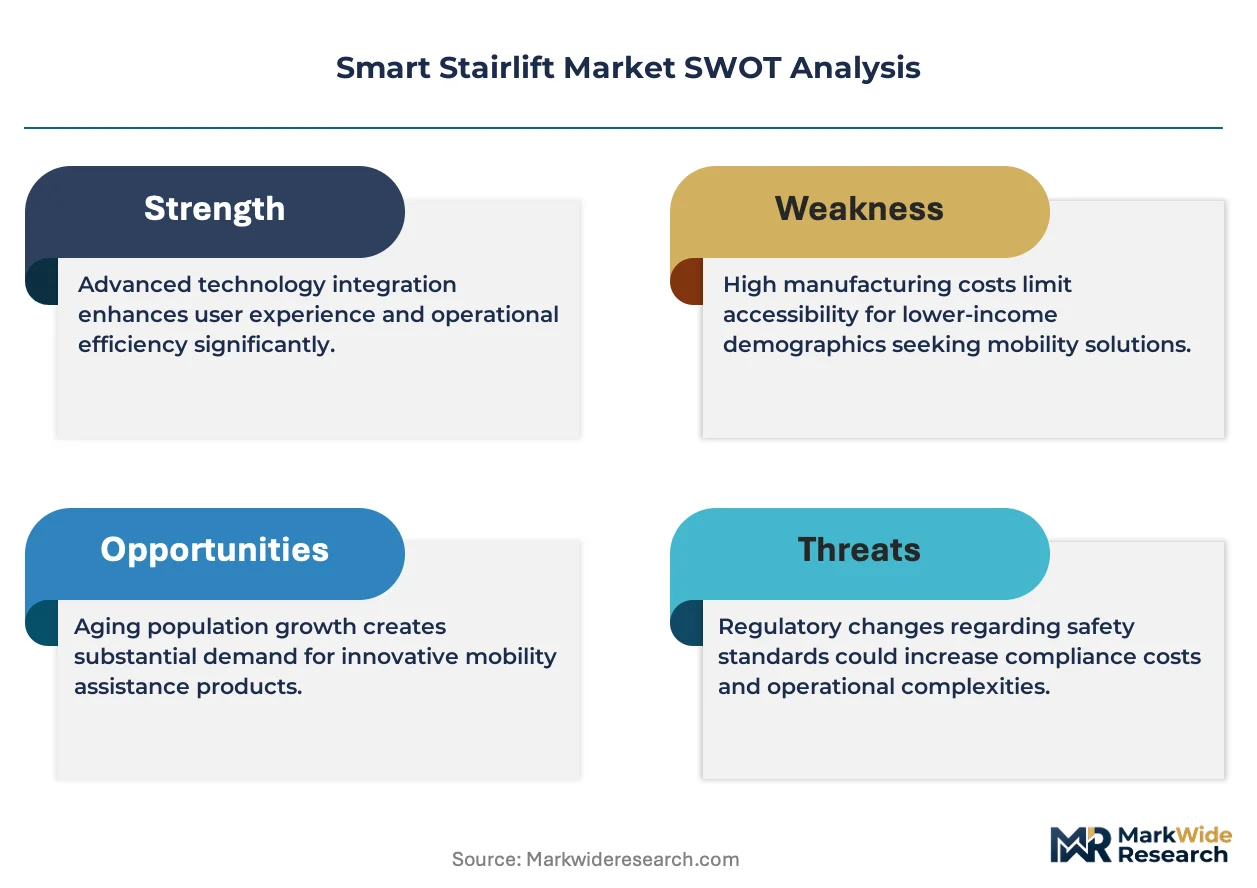
The US FDA classifies stairlifts as medical devices under 21 CFR 890.5050, requiring substantial equivalence for market entry, while the EU MDR mandates CE marking with clinical evaluation for powered patient handling equipment. Japan's METI enforces PSE certification for electrical safety in battery-operated models. Stakeholders must monitor how evolving accessibility subsidies in municipal housing programs reshape procurement criteria between basic and smart-connected configurations.
Market Dynamics
The smart stairlift sector is restructuring around captive service networks as manufacturers absorb installation and maintenance functions previously outsourced to independent dealers, compressing channel margins while tightening quality control over retrofit-heavy residential corridors.
Growth Catalysts
- Germany's building code amendments:National accessibility mandates for multi-level dwellings in aging suburbs are accelerating straight-rail installations in post-war housing stock.
- Battery chemistry advances:Lithium-ion power systems are displacing lead-acid alternatives in grid-unreliable urban corridors, extending runtime between charges.
- Japan's METI PSE certification pathway:Streamlined electrical safety approvals for battery-operated models are reducing time-to-market for wireless-controlled units.
Market Restraints
- Custom rail fabrication costs:Curved stairlift production requires labor-intensive bending processes that absorb 40-60% higher engineering overhead than standardized straight rails.
- Steel and aluminum price volatility:Rail extrusion inputs face commodity swings that compress margin predictability for manufacturers without long-term supply agreements.
- Structural elevator substitution:Platform lifts and residential elevators are capturing specification in new-build multi-generational housing where shaft space is pre-planned.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives for powered patient handling equipment are attracting component localization investments.
- Remote diagnostics convergence:IoT-enabled predictive maintenance is merging with telehealth platforms to reduce emergency service calls.
- Municipal housing subsidy expansion:Accessibility voucher programs in Japanese prefectures are widening procurement criteria toward smart-connected configurations.
Industry Challenges
- Certification timeline compression:EU MDR clinical evaluation requirements for powered patient handling equipment are extending CE marking cycles by 8-14 months.
- Legacy electrical infrastructure integration:Pre-1980s housing stock in Germany and Japan lacks grounding standards compatible with modern sensor arrays, requiring costly rewiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Stairlift Market |
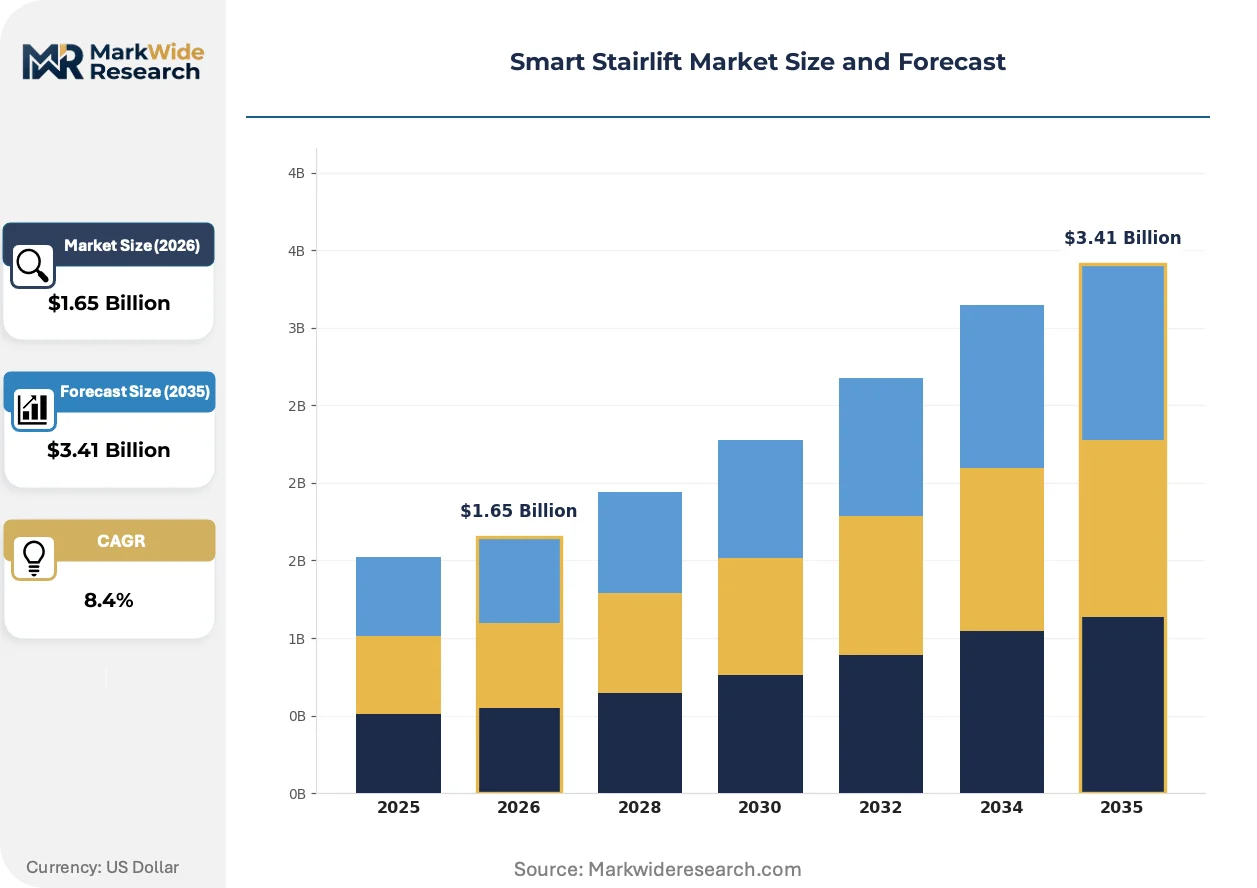
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Stairlifts, Outdoor Stairlifts, Curved Stairlifts, Straight Stairlifts End User: Residential Users, Medical Facilities, Assisted Living, Rehabilitation Centers Technology: Electric Stairlifts, Battery-Operated Stairlifts, Smart Stairlifts, Manual Stairlifts Control System: Remote-Controlled, Wired Control, Wireless Control, Automated Systems |
| Companies Covered | Savaria Corporation, Stannah Lifts Holdings Ltd., Acorn Stairlifts Inc., Bruno Independent Living Aids Inc., Handicare Group AB, Harmar Mobility LLC, Otolift Stairlifts Ltd., Platinum Stairlifts Ltd., ThyssenKrupp Access Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Stairlift Market Trends and Innovations
Wireless control architectures are displacing hardwired installations across retrofit corridors, while regulatory frameworks on three continents tighten safety verification protocols for sensor-enabled mobility equipment.
Sensor fusion technology is migrating from simple pressure pads to multi-modal obstacle detection combining infrared, ultrasonic, and machine-vision arrays. Residential installers in Japan's Kanto region are specifying these configurations for 60% of new orders. The shift is compressing liability exposure while raising firmware validation burdens for manufacturers.
EU MDR Article 10 post-market surveillance obligations now mandate systematic clinical follow-up for powered patient handling equipment, including stairlifts. Manufacturers must maintain vigilance databases tracking adverse events across member states. German notified bodies are interpreting this most strictly, delaying approvals for systems lacking real-time usage telemetry.
Homebuyers in aging suburbs are unbundling after-sales service from initial equipment purchase, negotiating third-party maintenance contracts independent of manufacturer networks. This pattern concentrates in Australia's eastern seaboard and California's Bay Area, where independent technicians have built diagnostic tool libraries for multiple brands.
Smart Stairlift Market Segmentation
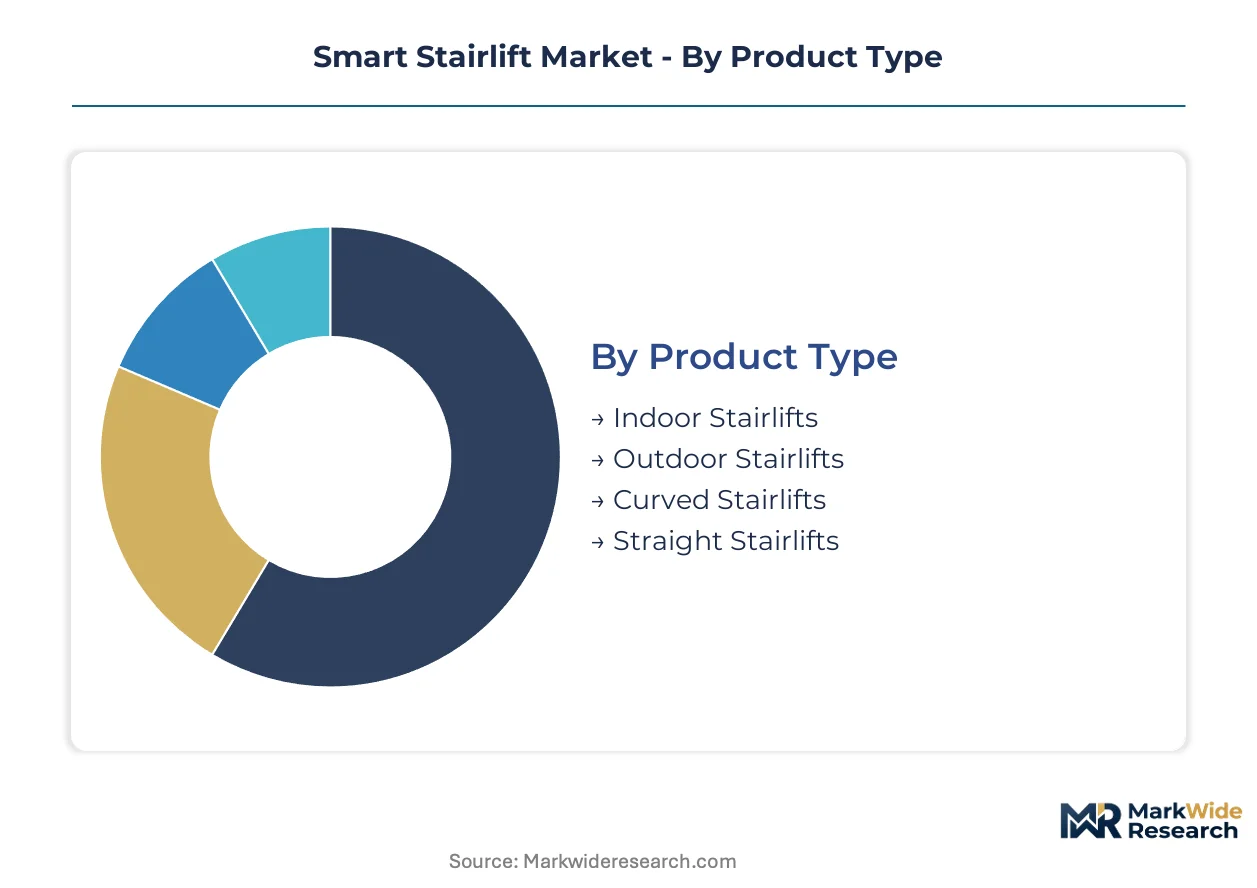
Stairlift segmentation reveals distinct service intensity profiles across product architectures. After-sales requirements vary sharply between standardized straight-rail systems and custom-fabricated curved units, reshaping manufacturer channel economics and captive network investments.
Product Type:
After-sales-service intensity concentrates heavily in curved configurations where custom rail bending demands specialized technician deployment and precision recalibration protocols.
- Straight Stairlifts:Standardized rail extrusions enable rapid installation cycles and minimal ongoing adjustment. Demand clusters in Germany's aging post-war housing stock where building code amendments mandate accessibility retrofits for multi-level dwellings.
- Curved Stairlifts:Labor-intensive rail bending processes absorb 40-60% higher engineering overhead, requiring bespoke measurement and fabrication workflows. Japanese installers in Kanto region specify these for complex staircase geometries in pre-1980s housing lacking uniform dimensions.
- Indoor Stairlifts:Climate-controlled operating environments reduce sensor array degradation and extend maintenance intervals.
- Outdoor Stairlifts:Weatherproofing requirements elevate seal replacement frequency and corrosion monitoring in coastal municipalities.
By volume, straight stairlifts lead. By growth pace, curved stairlifts are expanding most quickly.
End User:
Cost tier stratification separates residential self-pay installations from institutional procurement governed by municipal voucher programs and clinical evaluation mandates.
- Residential Users:Self-directed purchases dominate volume, with aging suburban homeowners in Japan's prefectures leveraging accessibility subsidies toward smart-connected configurations. Third-party maintenance contracts are unbundling from initial equipment sales in Australia's eastern seaboard and California's Bay Area.
- Medical Facilities:FDA 21 CFR 890.5050 classification and EU MDR clinical evaluation requirements extend procurement cycles. Real-time usage telemetry is becoming mandatory for German notified body approvals under post-market surveillance obligations.
- Assisted Living:Multi-unit operators prioritize wireless control architectures to minimize wall disruption across retrofit corridors.
- Rehabilitation Centers:Intensive duty cycles demand predictive maintenance integration with telehealth platforms.
Residential channels dominate unit volume. Medical facilities command the steepest expansion trajectory as regulatory telemetry requirements deepen.
Technology:
Application requirements are concentrating procurement toward battery-operated architectures where grid reliability varies and lithium-ion chemistry advances extend runtime between charges.
- Battery-Operated Stairlifts:Lithium-ion power systems are displacing lead-acid alternatives. Japan's METI PSE certification pathway for electrical safety is streamlining time-to-market for these configurations in grid-unreliable urban corridors.
- Smart Stairlifts:IoT-enabled predictive maintenance merges with telehealth platforms. Multi-modal obstacle detection combining infrared, ultrasonic, and machine-vision arrays is specified for 60% of new orders in Japan's Kanto region.
- Electric Stairlifts:Hardwired installations persist in new-build multi-generational housing with pre-planned electrical infrastructure.
- Manual Stairlifts:Minimal electronic components reduce certification burdens for basic accessibility mandates.
Battery-operated units lead by volume. Smart stairlifts are gaining share fastest as firmware validation capabilities mature.
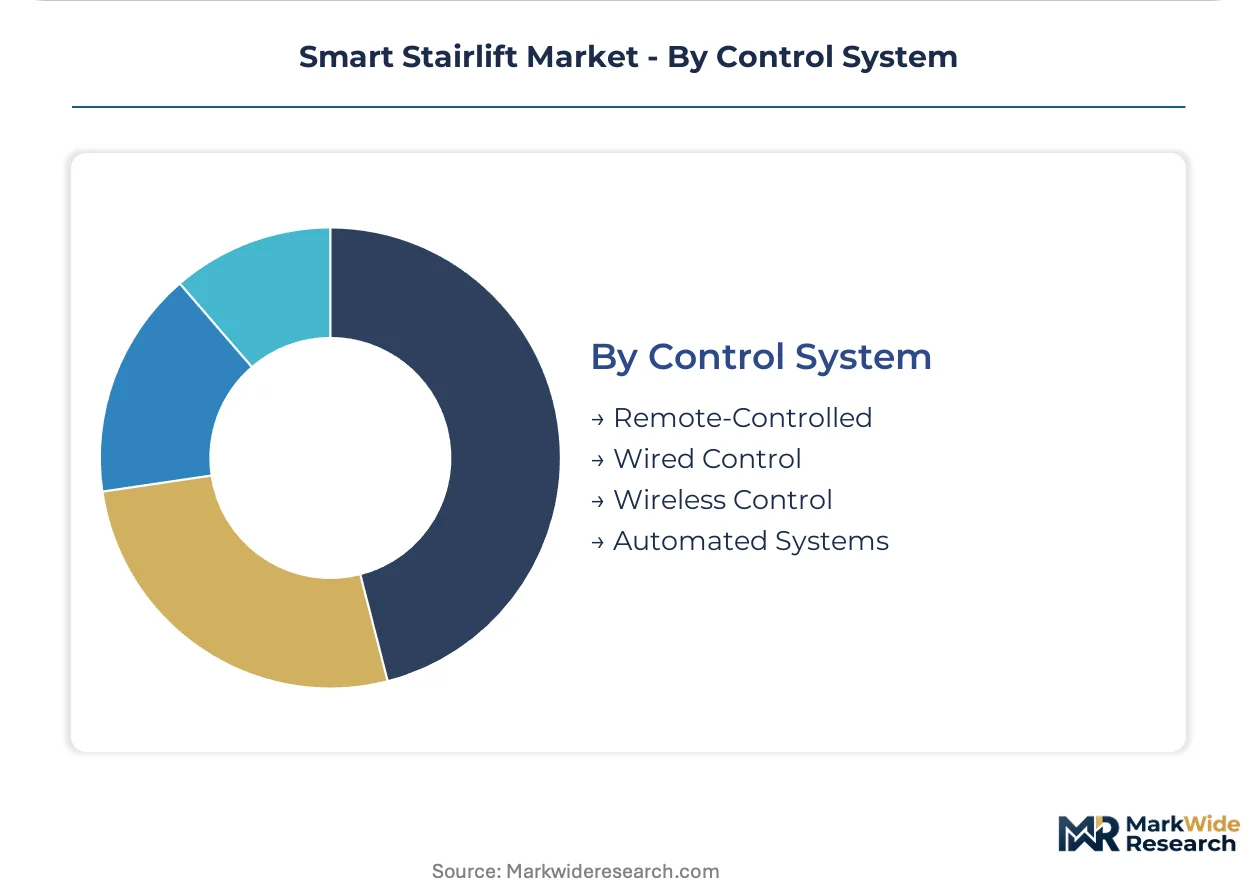
Control System:
Customer type preferences are bifurcating between retrofit corridors favoring minimal wall disruption and new-build specifications accepting hardwired reliability.
- Wireless Control:Eliminates wall disruption in pre-1980s housing stock where Germany and Japan lack grounding standards compatible with modern sensor arrays. Municipal housing subsidy expansions in Japanese prefectures are widening procurement criteria toward these configurations.
- Remote-Controlled:Handheld and wall-mounted transmitters enable caregiver operation in assisted living environments.
- Wired Control:Lower firmware validation burdens appeal to manufacturers facing EU MDR timeline compression extending CE marking cycles.
- Automated Systems:Machine-vision arrays enable user detection without physical input, concentrating in premium medical facility specifications.
Wireless control leads by installation volume. Automated systems are climbing the fastest as sensor fusion technology migrates from simple pressure pads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's distribution corridor for stairlift rail extrusions and battery components, while the Port of Yokohama funnels Japanese precision sensor arrays into domestic retrofit networks.
United States
California's Bay Area and Florida's Gulf Coast drive residential self-pay installations as aging homeowners unbundle third-party maintenance from manufacturer networks. FDA 21 CFR 890.5050 classification extends procurement cycles for medical facility specifications. Installers in the Pacific Northwest concentrate on wireless control architectures for pre-1980s housing stock lacking modern grounding standards.
Germany
Ruhr Valley municipalities enforce building code amendments mandating accessibility retrofits for multi-level post-war dwellings. EU MDR clinical evaluation requirements delay CE marking cycles for powered patient handling equipment. Stuttgart-based fabricators specialize in standardized straight-rail systems for standardized staircase geometries.
Japan
Kanto region installers specify multi-modal obstacle detection for 60% of new orders as METI streamlines PSE certification for battery-operated models. Municipal housing subsidy expansions in prefectures widen procurement criteria toward smart-connected configurations. Osaka-based technicians build diagnostic tool libraries for cross-brand maintenance contracts.
Australia
Eastern seaboard cities concentrate independent technician networks unbundling after-sales service from initial equipment purchases. The country's national medical device regulator enforces post-market surveillance for powered patient handling equipment. Melbourne installers prioritize lithium-ion battery systems for grid-unreliable coastal corridors.
United Kingdom
West Midlands manufacturing bases control aftermarket parts flow through captive service networks. EU MDR Article 10 vigilance database requirements track adverse events across member state deployments. London retrofit specialists specify curved rail configurations for Victorian-era housing with non-uniform staircase dimensions.
Smart Stairlift Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying rail extrusions, motor assemblies, and sensor modules. The vendor base concentrates around three structural tiers: full-service manufacturers with captive installation networks, regional fabricators serving discrete geographies, and component suppliers feeding multiple assembly lines. Strategic moves center on backward integration into rail production and geographic expansion through dealer acquisition rather than greenfield capacity.
Among British and North American platform operators, Stannah Lifts Holdings Ltd., Savaria Corporation, and Bruno Independent Living Aids Inc. exemplify contrasting archetypes. Stannah occupies a position tied to manufacturing-base control over aftermarket parts flow. Savaria anchors North American distribution through upstream control over dealer training infrastructure. Bruno represents specialization in compact rail geometries for constrained installation environments. These three illustrate how geographic origin and organizational suffix—Ltd., Corporation, Inc.—correlate with distinct strategic postures without determining specific market outcomes.
| Leading Market Players |
|---|
| Savaria Corporation |
| Stannah Lifts Holdings Ltd. |
| Acorn Stairlifts Inc. |
| Bruno Independent Living Aids Inc. |
| Handicare Group AB |
| Harmar Mobility LLC |
| Otolift Stairlifts Ltd. |
| Platinum Stairlifts Ltd. |
| ThyssenKrupp Access Solutions |
| Others |
Pricing and Supply Chain Analysis
Steel and aluminum price volatility acts as the dominant risk vector, compressing margin predictability for rail extrusion inputs while simultaneously widening spreads between economy-tier straight-rail systems and premium curved configurations with long-term supply agreements.
Pricing Analysis
Volume-discount tiering structures separate large-scale municipal housing procurements from single-unit residential installations. Three-tier pricing stratification across premium smart-connected units, standard battery-operated models, and economy-grade manual systems tracks certification complexity and after-sales bundling intensity. Pricing pressure stems from custom rail fabrication absorbing 40-60% higher engineering overhead in curved configurations. Residential self-pay buyers in aging suburbs exhibit highest price sensitivity, while medical facilities governed by FDA 21 CFR 890.5050 mandates show lowest sensitivity due to reimbursement pathways.
Supply Chain Analysis
Upstream feedstock channels draw from German steel extrusion specialists, Japanese precision sensor manufacturers, and Chinese lithium-ion cell producers. Rail fabrication depends on aluminum and steel inputs, while sensor arrays rest on semiconductor wafers and rare-earth magnets. Single-source vulnerability concentrates in Japanese machine-vision component suppliers serving Kanto region installers. Distribution runs through captive service networks anchored by British and North American manufacturers controlling aftermarket parts flow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart stairlift market functions as a defensive-moat story where regulatory entrenchment through FDA 21 CFR 890.5050 and EU MDR CE marking creates substantial switching costs for institutional procurement.
For Market Incumbents: Entrench position through backward integration into rail production and absorption of installation functions previously outsourced to independent dealers. METI PSE certification investments in Japan tighten quality control over battery-operated architectures. Channel margin compression from captive service networks defends against emerging platform lift substitutes in new-build multi-generational housing. For New Entrants and Emerging Players: Pursue India's PLI scheme for medical devices as the most penetrable geography, leveraging production-linked incentives for powered patient handling equipment component localization. Wireless control architectures for pre-1980s housing stock in Germany and Japan offer white-space opportunity. Go-to-market positioning through independent technician networks in Australia's eastern seaboard bypasses incumbent captive service structures. For Investors and Strategic Acquirers: Regional fabricators with diagnostic tool libraries for cross-brand maintenance contracts represent the priority acquisition archetype. Long-term viability hinges on IoT-enabled predictive maintenance convergence with telehealth platforms. Watch municipal housing subsidy expansions in Japanese prefectures as the signal indicating inflection toward smart-connected configuration procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rail Production | Captive supply of extrusion inputs insulates margin predictability against steel and aluminum commodity swings. |
| IoT Predictive Maintenance Platform Launch | Real-time usage telemetry satisfies German notified body demands under EU MDR Article 10 post-market surveillance. |
| Wireless Control Architecture Certification | METI PSE pathway streamlines time-to-market for battery-operated models in grid-unreliable urban corridors. |
| Dealer Training Infrastructure Acquisition | Upstream control over installation quality tightens retrofit-heavy residential corridor penetration. |
| Municipal Housing Subsidy Partnership | Accessibility voucher program alignment widens procurement criteria toward premium smart-connected configurations. |
Research Methodology
A spread of perspectives from stairlift installation technicians, biomedical engineers at medical facilities, municipal housing procurement officers, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EU MDR notified body approval databases, METI PSE certification registries, and customs trade data for rail extrusion imports. Bottom-up unit installation tracking and top-down equipment spend analysis triangulated market sizing across the projection horizon.
Demand-supply-balance framing anchored the analytical framework, modeling residential versus institutional end-use splits, straight versus curved rail product architectures, battery-operated versus hardwired technology tiers, and wireless versus wired control system preferences. CAGRs derived from installation run-rate trending and equipment replacement cycle analysis. Forecast inputs incorporated lithium-ion battery chemistry advancement curves and municipal subsidy expansion trajectories without year-specific milestones.
Macroeconomic conditions sit as an overlay; deviation in construction activity levels, steel commodity pricing, and healthcare reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions about regulatory timeline compression and certification pathway evolution. Cross-checking against national medical device registration databases and municipal housing authority procurement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Peripheral Nerve Stimulators Market
Medical Devices
Orthodontic Retainers Market
Medical Devices
Sterile Filtration Module Market
Medical Devices
Vaginal Applicators Market
Medical Devices
Asia-Pacific General Surgical Devices Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
Global Bone Tumor Ablation Devices Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Medical Hydrophilic Coatings Market
Medical Devices
Wireless Neurofeedback Device Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Depression Devices Market
Medical Devices
Spain Artificial Organs and Bionic Implants Market
Medical Devices
Sinus Implants Market