
 Bioimpedance Devices Market | 2026-2036
Bioimpedance Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Bioimpedance Devices Market Analysis
Multi-frequency measurement precision is reorganizing competitive expectations across the bioimpedance devices landscape. Tanita Corporation leverages its decades-long calibration databases to sustain brand authority in consumer body composition scales. InBody Co. Ltd. dominates professional-grade segmental analysis systems through direct channel control in fitness and clinical verticals. Omron Healthcare Inc. competes on portable form-factor reliability, extending its reach into home monitoring environments where ease-of-use dictates purchase decisions.
Bioimpedance devices measure electrical resistance and reactance across biological tissues to quantify body composition, hydration status, and cellular integrity, typically operating at frequencies between 1 kHz and 1000 kHz with electrode configurations varying from four-point to eight-point contact systems. These instruments serve clinical nutrition, nephrology, sports medicine, and pharmaceutical research by delivering non-invasive, repeatable metrics that substitute for more invasive or costly reference methods. Handheld devices lead volume shipments due to their deployment flexibility in point-of-care and fitness settings, though stationary systems capture disproportionate margin pools in hospital accounts where accuracy certifications drive procurement. Wearable devices represent the fastest-expanding category as continuous monitoring protocols migrate from episodic clinic visits to ambulatory and remote patient management frameworks.
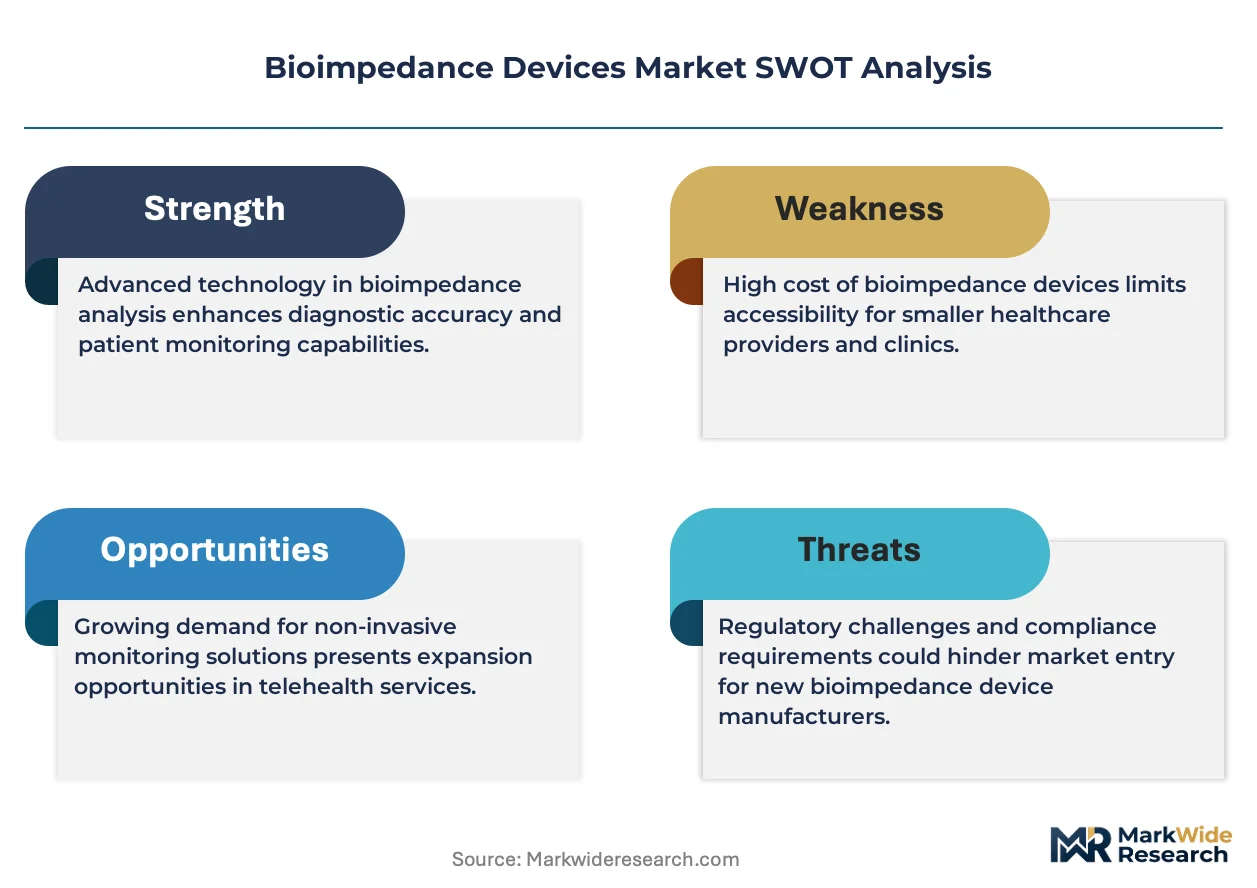
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development timelines and clinical validation burdens for manufacturers seeking market access in the United States and European Economic Area. Japan's PMDA and South Korea's MFDS impose additional electrical safety and software validation standards that filter out lower-capability entrants. Stakeholders must monitor evolving reimbursement codes for body composition assessment and fluid status monitoring to align R&D portfolios with payor willingness.
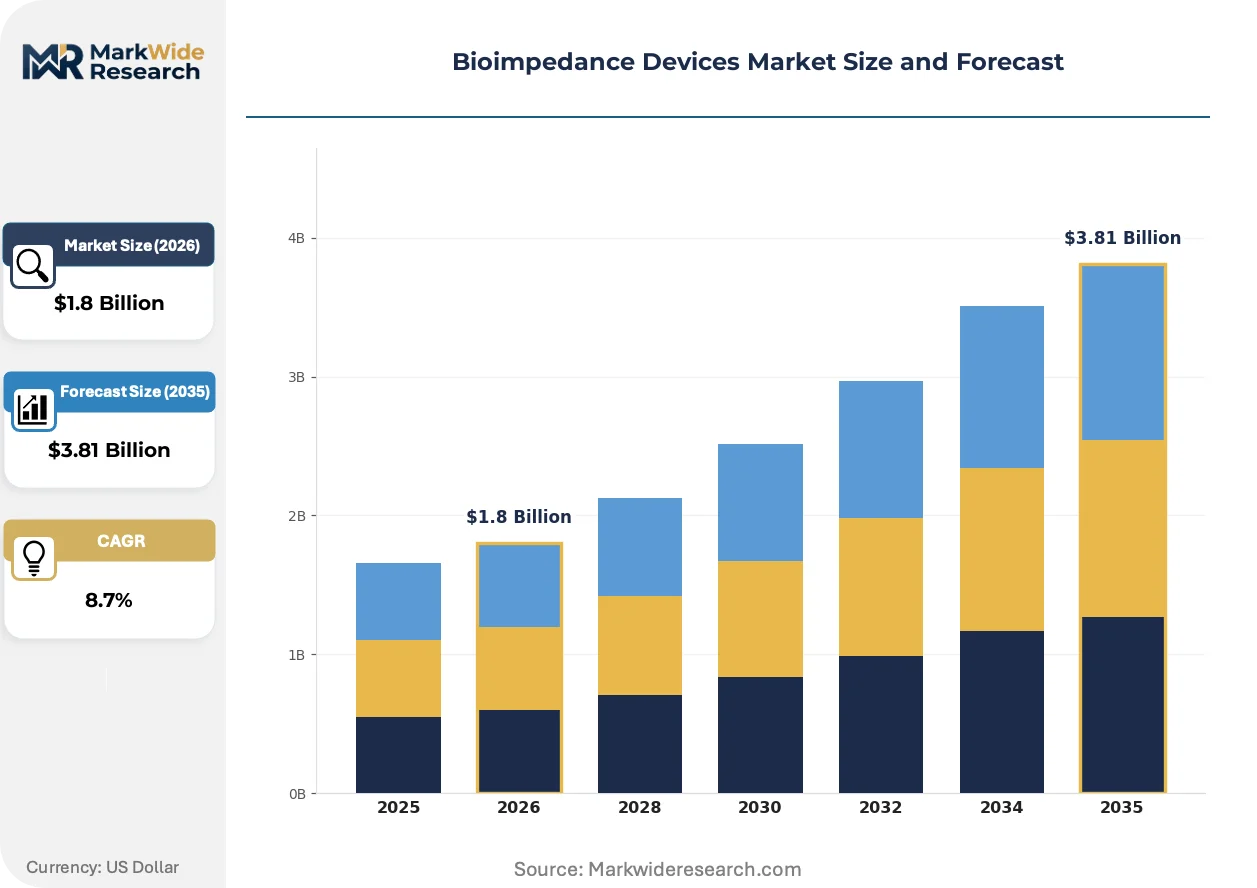
Market Dynamics
Multi-frequency bioimpedance analyzers are compressing the performance gap between portable devices and laboratory-grade reference systems, forcing incumbents to recalibrate R&D roadmaps around measurement precision rather than form-factor differentiation alone.
Growth Catalysts
- Preventive care reimbursement alignment:Medicare Advantage plans in the United States now cover body composition assessment for chronic disease management, expanding addressable patient populations beyond cash-pay wellness segments.
- EU MDR performance documentation:Stricter clinical validation requirements for Class IIa medical devices are filtering out low-accuracy competitors and consolidating procurement authority around certified manufacturers.
- Continuous monitoring protocols:Wearable bioimpedance sensors enable ambulatory fluid status tracking for heart failure patients, creating new prescription channels distinct from episodic clinic-based testing.
Market Restraints
- Electrode material cost volatility:Silver-silver chloride sensor prices fluctuate with precious metals markets, compressing gross margins on disposable consumable business models.
- Reference method substitution:Dual-energy X-ray absorptiometry retains diagnostic authority in osteoporosis and sarcopenia protocols, limiting bioimpedance penetration in geriatric specialist practices.
- Calibration infrastructure concentration:Validated impedance phantom production centers in Germany and Japan create supply bottlenecks for manufacturers seeking ISO 13485 certification.
Strategic Opportunities
- Remote patient management expansion:Telehealth reimbursement permanence in the United States enables direct-to-patient distribution models bypassing traditional hospital procurement committees.
- Pharmaceutical trial endpoints:Bioimpedance-derived cellular integrity metrics are qualifying as surrogate endpoints in oncology and nephrology drug development, opening research institution demand.
- AI-assisted interpretation integration:Machine learning algorithms trained on population-specific impedance databases are enabling point-of-care diagnostic support without specialist oversight.
Industry Challenges
- 510(k) predicate device scarcity:FDA clearance pathways for novel multi-frequency architectures face predicate identification delays when existing devices lack equivalent technical characteristics.
- Interoperability protocol fragmentation:Absence of universal data exchange standards between bioimpedance devices and electronic health record systems forces costly custom integration development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioimpedance Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Stationary Devices, Wearable Devices, Software Solutions Technology: Single Frequency, Multi-Frequency, Spectrum Analysis, Time-Domain Application: Body Composition Analysis, Medical Diagnostics, Fitness Monitoring, Research & Development End User: Hospitals, Clinics, Fitness Centers, Research Institutions |
| Companies Covered | ImpediMed Ltd., Omron Healthcare Inc., Seca GmbH & Co. KG, Tanita Corporation, InBody Co. Ltd., RJL Systems Inc., Bodystat Ltd., General Electric Company, Hologic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioimpedance Devices Market Emerging Trajectories
Spectral bioimpedance analysis is extending measurement bandwidth beyond traditional single-frequency limitations, enabling simultaneous assessment of intracellular and extracellular fluid compartments without invasive tracer methods.
Phase-sensitive detection circuitry operating across 5 kHz to 500 kHz is displacing conventional magnitude-only measurement approaches in nephrology and critical care settings. Hospital dialysis units in Germany and Japan are adopting these systems for real-time dry weight assessment during hemodialysis sessions. The technology is compressing calibration cycle requirements from quarterly to annual intervals while maintaining equivalent accuracy against isotope dilution reference methods.
EU Medical Device Regulation Article 10 clinical evaluation requirements are extending validation timelines for new bioimpedance submissions by 12-18 months compared to predecessor directives. Manufacturers must now demonstrate equivalence to existing approved devices through head-to-head studies rather than literature-based justification alone. Stationary clinical systems face the heaviest documentation burden, prompting some firms to prioritize handheld device portfolios where predicate pathways remain more established.
Hospital procurement committees are unbundelling device acquisition from long-term service contracts, shifting toward capital purchase models with separate software subscription tiers. This pattern is most visible in United States health system consolidation, where centralized supply chain offices negotiate enterprise pricing across multiple facility sites. Independent service organizations are capturing maintenance revenue previously retained by original equipment manufacturers, compressing aftermarket profit pools for device vendors.
Bioimpedance Devices Market Segmentation
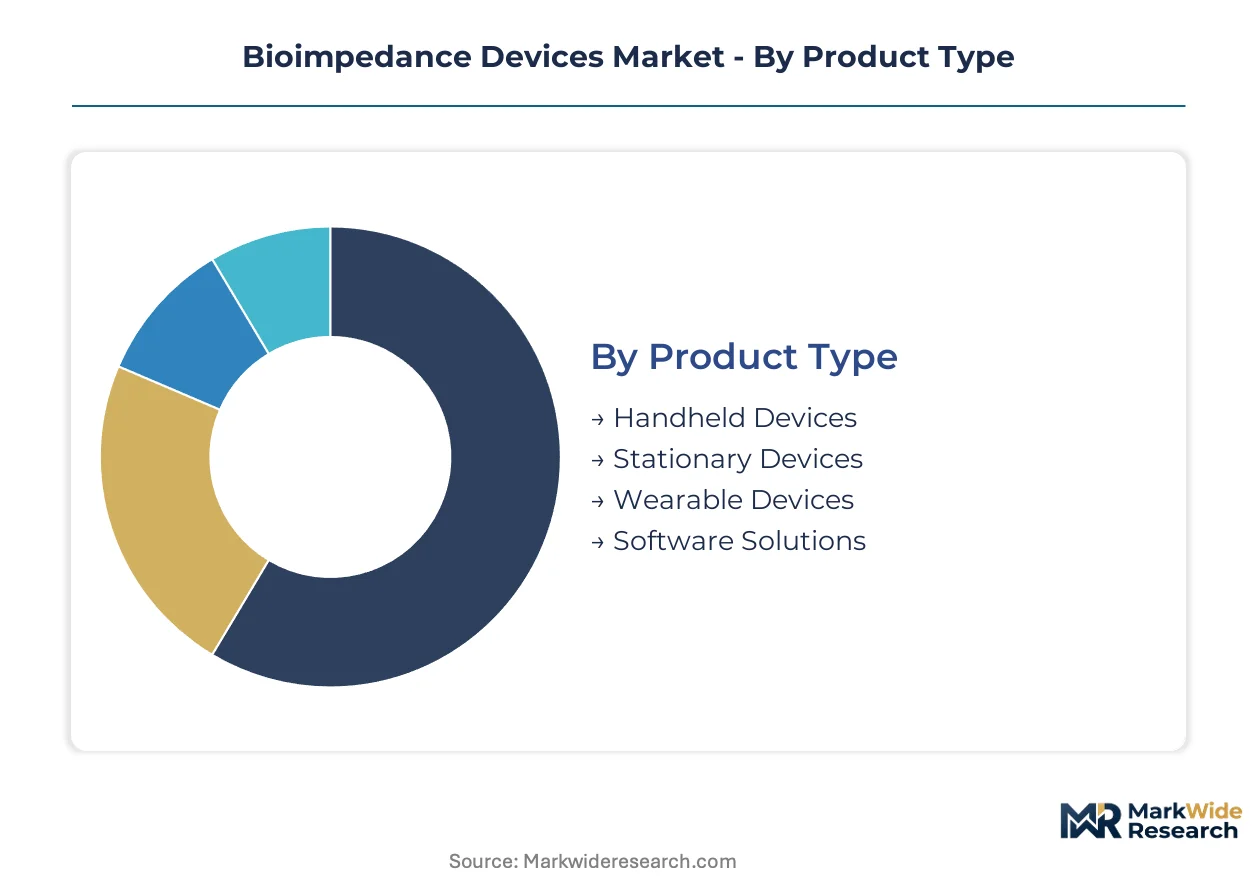
Segmentation in bioimpedance devices reveals distinct channel economics: hospital procurement committees favor certified stationary systems, while fitness centers and direct-to-consumer platforms drive volume in portable categories. Understanding these flow patterns helps manufacturers align certification investments with margin capture potential.
Product Type:
Channel concentration varies sharply across form factors, with hospital supply chains filtering for stationary systems and e-commerce platforms accelerating wearable adoption.
- Handheld Devices:Battery-operated units with four-point electrode configurations deliver point-of-care body composition screening. Demand clusters in United States Medicare Advantage preventive care protocols and Japanese corporate wellness programs, where reimbursement alignment favors portable diagnostic tools.
- Stationary Devices:Eight-point contact platforms with segmental analysis capabilities serve hospital accounts requiring ISO 13485 certification. German dialysis centers and United States health system consolidations concentrate procurement authority around these high-accuracy systems for fluid management protocols.
- Wearable Devices:Continuous monitoring patches and smartwatch-integrated sensors enable ambulatory fluid tracking. The category is expanding most quickly as United States telehealth reimbursement permanence enables prescription channel development.
- Software Solutions:Cloud-based analytics platforms interpret raw impedance data for clinical decision support.
By volume, Handheld Devices leads. By growth pace, Wearable Devices is ahead.
Technology:
Cost tier stratification separates premium multi-frequency architectures from economy single-frequency alternatives, with spectrum analysis commanding research institution budgets.
- Single Frequency:Fixed-frequency circuits operating at 50 kHz estimate total body water through simplified resistance measurements. Fitness centers in Germany and consumer wellness markets in Japan absorb these lower-cost units where absolute precision matters less than trend tracking.
- Multi-Frequency:Variable frequency sweep from 5 kHz to 500 kHz distinguishes intracellular from extracellular fluid compartments. United States hospital accounts and South Korean MFDS-certified manufacturers concentrate demand here for nephrology and critical care applications.
- Spectrum Analysis:Broadband impedance spectroscopy across 1 kHz to 1000 kHz enables cellular integrity assessment.
- Time-Domain:Impulse response measurement techniques offer rapid assessment capabilities for high-throughput screening environments.
By installed base, Single Frequency dominates. By margin expansion, Multi-Frequency outperforms.
Application:
Customer type fragmentation splits demand between clinical reimbursement codes and cash-pay wellness segments, with research procurement following distinct funding cycles.
- Body Composition Analysis:Athlete monitoring and weight management programs drive recurring assessment protocols. United States fitness chains and Japanese sports medicine clinics concentrate volume, though DEXA substitution limits penetration in geriatric specialist practices.
- Medical Diagnostics:Lymphedema detection and fluid overload monitoring qualify for procedure codes in United States Medicare and German statutory health insurance. FDA 510(k) clearance requirements filter competitors in this highest-margin segment.
- Fitness Monitoring:Consumer-facing wellness tracking applications.
- Research & Development:Pharmaceutical trial endpoints and academic physiology studies.
By revenue concentration, Medical Diagnostics leads. By volume velocity, Fitness Monitoring is climbing the fastest.
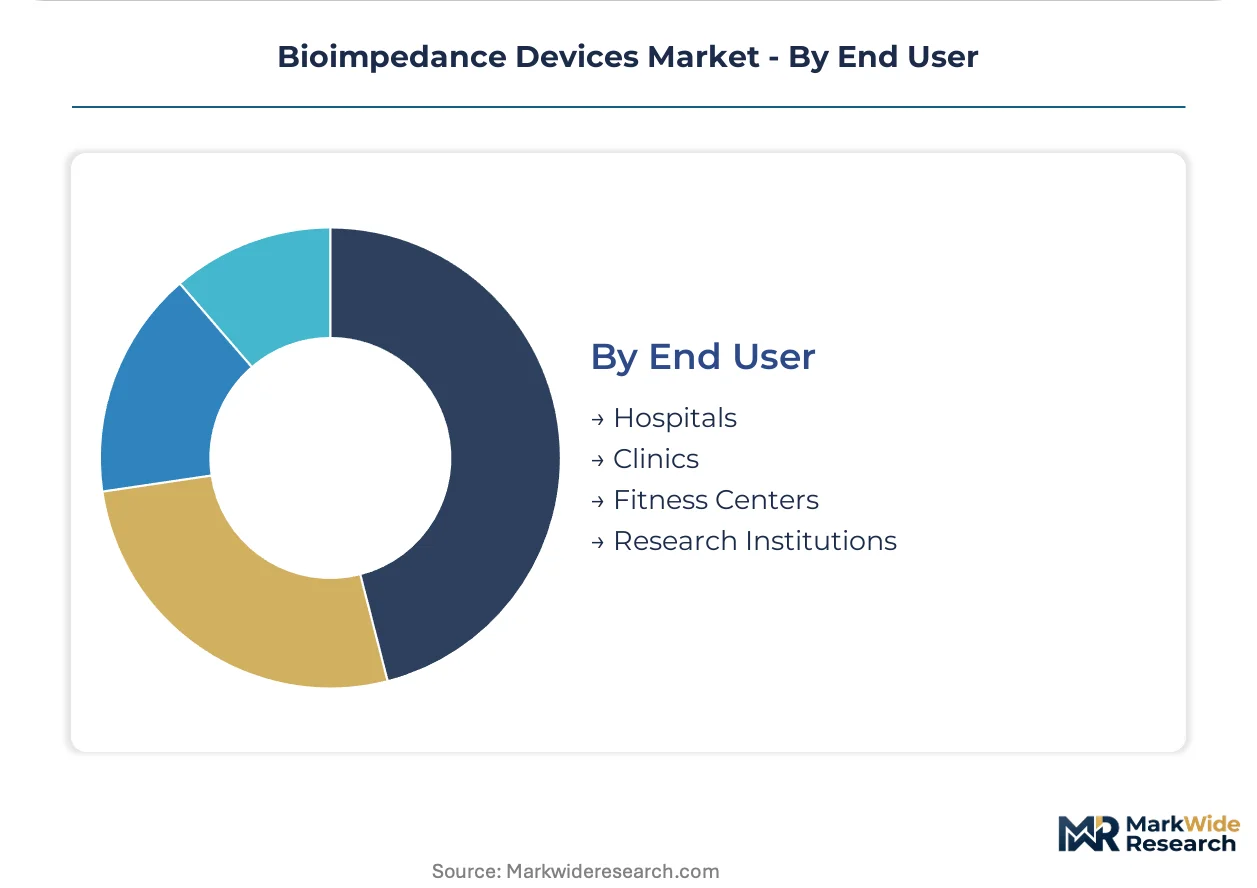
End User:
Supply concentration in certified manufacturing clusters shapes geographic availability, with hospital procurement committees in consolidated United States health systems exercising disproportionate pricing leverage.
- Hospitals:Enterprise purchasing agreements across multi-site health systems in the United States and university hospital networks in Germany concentrate demand for stationary multi-frequency systems. EU MDR Article 10 documentation requirements extend sales cycles but protect incumbent positions.
- Clinics:Independent nephrology and nutrition practices favor handheld devices for patient throughput efficiency. Japanese clinic chains and South Korean primary care networks represent concentrated demand pockets.
- Fitness Centers:Commercial gym chains and corporate wellness facilities.
- Research Institutions:Academic medical centers and pharmaceutical contract research organizations.
By average selling price, Hospitals leads. By unit expansion, Clinics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing clusters in Germany and Japan, while the United States absorbs premium device volumes through consolidated health system procurement. Trade flows concentrate calibrated impedance phantoms and precision electrode assemblies from these centers into clinical markets worldwide.
United States
Medicare Advantage preventive care protocols and telehealth reimbursement permanence drive demand for portable body composition devices. FDA 510(k) clearance requirements filter market access, concentrating procurement authority around certified manufacturers. Hospital supply chain consolidation in Texas and the Midwest enables enterprise pricing negotiations across multi-site health systems.
Germany
Statutory health insurance coverage for fluid management assessment and dialysis dry weight monitoring sustains hospital demand for multi-frequency systems. EU MDR Article 10 clinical evaluation requirements extend validation timelines but protect incumbent manufacturers. The Baden-Württemberg medical technology cluster anchors precision electrode and calibration phantom production for European distribution.
Japan
Corporate wellness programs and PMDA electrical safety standards shape adoption of handheld devices in clinic chains. METI industrial policy supports domestic manufacturing of segmental analysis systems. The Kanto region around Tokyo concentrates R&D facilities for impedance spectroscopy applications in sports medicine and nephrology.
South Korea
MFDS software validation standards and primary care network expansion drive handheld device deployment. Domestic manufacturers leverage semiconductor supply chain proximity for phase-sensitive detection circuitry development. The Seoul Capital Area hosts validation laboratories serving regional export markets.
United Kingdom
NHS long-term plan integration of body composition assessment for chronic disease management creates procurement opportunities. MHRA post-Brexit regulatory alignment with EU MDR maintains certification requirements for continental market access. The Oxford-Cambridge corridor concentrates research institution demand for pharmaceutical trial endpoint applications.
Bioimpedance Devices Market Vendor Landscape
Concentration sits with calibration-anchored specialists and direct-channel controllers. The vendor base stratifies across three tiers: premium-grade stationary systems for hospital accounts, portable devices for clinic throughput, and consumer-facing wearables for remote monitoring. Two dominant competitive moves define current positioning: backward integration into electrode material supply chains to buffer precious metals volatility, and AI-assisted interpretation licensing to capture recurring software revenue streams.
Within the calibration-anchored tier, Tanita Corporation and InBody Co. Ltd. exemplify divergent channel strategies. Tanita leverages decades-long impedance databases to sustain authority in consumer and clinical body composition measurement. InBody occupies a position in professional-grade segmental analysis through controlled distribution in fitness and medical verticals. Omron Healthcare Inc. sits within the portable reliability archetype, extending reach into home monitoring environments where form-factor and ease-of-use drive purchase decisions.
| Leading Market Players |
|---|
| ImpediMed Ltd. |
| Omron Healthcare Inc. |
| Seca GmbH & Co. KG |
| Tanita Corporation |
| InBody Co. Ltd. |
| RJL Systems Inc. |
| Bodystat Ltd. |
| General Electric Company |
| Hologic Inc. |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance requirements and EU MDR Article 10 clinical evaluation standards gate both supply qualification and price differentiation in bioimpedance devices, concentrating procurement authority around certified manufacturers while filtering out lower-accuracy competitors from premium tier access.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium, standard, and economy tiers, with ISO 13485 certification and multi-frequency precision commanding 40-60% premiums over single-frequency alternatives. Price differentiation rests on calibration database depth and after-sales service bundling. Cost compression in handheld segments intensifies as Medicare Advantage reimbursement alignment expands addressable volumes. Fitness center buyers exhibit highest price sensitivity, while German dialysis centers and United States health system consolidations prioritize accuracy over unit cost.
Supply Chain Analysis
Germany and Japan anchor precision electrode and validated impedance phantom production, with the Baden-Württemberg cluster and Kanto region feeding global clinical certification pipelines. Silver-silver chloride sensor supply draws from precious metals markets, while phase-sensitive detection circuitry sources from South Korean semiconductor foundries. Single-source vulnerability concentrates in calibration phantom production, where ISO 17025-accredited facilities face 12-18 month qualification backlogs. Distribution runs through hospital supply chain consolidators in the United States and statutory health insurance procurement frameworks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability protocol fragmentation is forcing a platform-economics inflection in bioimpedance devices, with AI-assisted interpretation layers and cloud analytics subscriptions emerging as the decisive ecosystem control points.
For Market Incumbents: Consolidate calibration database moats through backward integration into electrode material supply chains, buffering silver price volatility while denying rivals access to validated phantom infrastructure. Deepen hospital system partnerships in United States consolidated health networks before independent service organizations capture maintenance revenue pools. Prioritize FDA 510(k) predicate device accumulation to delay novel multi-frequency architecture entrants. For New Entrants and Emerging Players: AI-assisted interpretation software licensing represents the most penetrable service layer, where incumbents under-serve independent nephrology clinics lacking specialist oversight capacity. Target South Korean primary care networks and Japanese clinic chains for handheld device deployment, leveraging MFDS and PMDA pathway efficiencies. Pursue direct-to-patient distribution models enabled by United States telehealth reimbursement permanence, bypassing hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across wearable sensor sub-segments as semiconductor integration reduces discrete component counts. Long-term viability favors acquisition targets combining proprietary impedance databases with cloud-native analytics platforms rather than hardware-only manufacturers. Watch for FDA breakthrough device designation signals in continuous monitoring protocols as inflection indicators for prescription channel development.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Clearance accumulation creates predicate device barriers for multi-frequency architecture competitors. |
| CE Marking Pathway under EU MDR | Article 10 clinical evaluation requirements extend validation timelines but protect incumbent market positions. |
| Hospital System Partnership | Enterprise pricing agreements across United States consolidated health networks lock out rival device vendors. |
| Software Companion Development | AI-assisted interpretation layers capture recurring subscription revenue from impedance data analytics. |
| Reimbursement Strategy | Medicare Advantage preventive care protocol alignment expands addressable patient populations beyond cash-pay segments. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers, nephrology clinic directors, GPO contracts managers, and fitness center operations heads, then refined through secondary validation against FDA 510(k) filings, EU MDR submission databases, CMS Medicare reimbursement codes, and hospital procurement contract records. Bottom-up device shipment estimates and top-down addressable market sizing were triangulated to resolve variance.
Variance decomposition across product type, technology tier, application segment, and end-user channel shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated reimbursement code evolution timelines, calibration infrastructure capacity constraints, and precious metals price trajectory assumptions.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR Article 10 enforcement; material policy shifts in Medicare Advantage coverage or PMDA electrical safety standards would require re-modeling. Recalibration cycles align with material shifts in reimbursement alignment, MDR implementation case law, and wearable sensor battery chemistry breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electrosurgery Accessories Market
Medical Devices
Global Subdermal Contraceptive Implants Market
Medical Devices
Cholesterol Management Devices Market
Medical Devices
Artificial Eye Lenses Market
Medical Devices
Global Medical Device Security Market
Medical Devices
Arthroscopy Procedures and Products Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Heart Closure Devices Market
Medical Devices
Bunion Correction Systems Market
Medical Devices
Neurotechnology Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Wearable Medical Technology Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Cytology Brush Market