
 Intrauterine Insemination Devices Market | 2026-2036
Intrauterine Insemination Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Intrauterine Insemination Devices Market Foresight
Asset-light leasing models for precision manufacturing equipment is reconfiguring capital requirements for mid-sized IUI device entrants. Cook Medical leverages captive polymer extrusion capacity to control catheter quality from raw material to finished sterile product. CooperSurgical sustains broad geographic coverage through direct distribution in North America and tiered distributor networks across Europe and Asia. Kitazato Corporation anchors its competitive position through specialized expertise in Japan's JIS-compliant reproductive device segment.
Intrauterine insemination devices comprise sterile, single-use catheters, cannulas, syringes, and needles engineered from medical-grade polyurethane, silicone, or polyethylene, typically 10–14 French diameter with rounded atraumatic tips designed to deposit washed sperm 1–2 cm from the uterine fundus. These instruments serve the primary commercial purpose of facilitating timed, low-invasive sperm delivery in assisted reproductive technology protocols. Catheters manufactured from soft polyurethane dominate procedure volumes in fertility clinics due to reduced cervical trauma and patient discomfort, while silicone variants command premium positioning for complex cervical anatomy cases. Stainless steel cannulas retain utility in hospital settings where rigid instrumentation supports training protocols and research applications.
The FDA's 510(k) premarket notification framework governs device clearance in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for reproductive device manufacturers seeking CE marking access. Japan's PMDA maintains distinct biocompatibility testing standards that shape product development priorities for Asia-Pacific market participants. Stakeholders must monitor evolving notified body capacity constraints in Europe and alignment of sterilization validation protocols across FDA, EMA, and PMDA jurisdictions to sustain multi-regional commercialization timelines.
Market Dynamics
Single-use catheter adoption is compressing reusable instrument maintenance revenue streams while expanding per-procedure consumable throughput across fertility clinic networks.
Growth Catalysts
- Polyurethane catheter materials:Soft, atraumatic tips reduce cervical trauma complaints and support higher patient throughput per clinical session. Fertility networks in the United States standardize on these variants for routine IUI protocols.
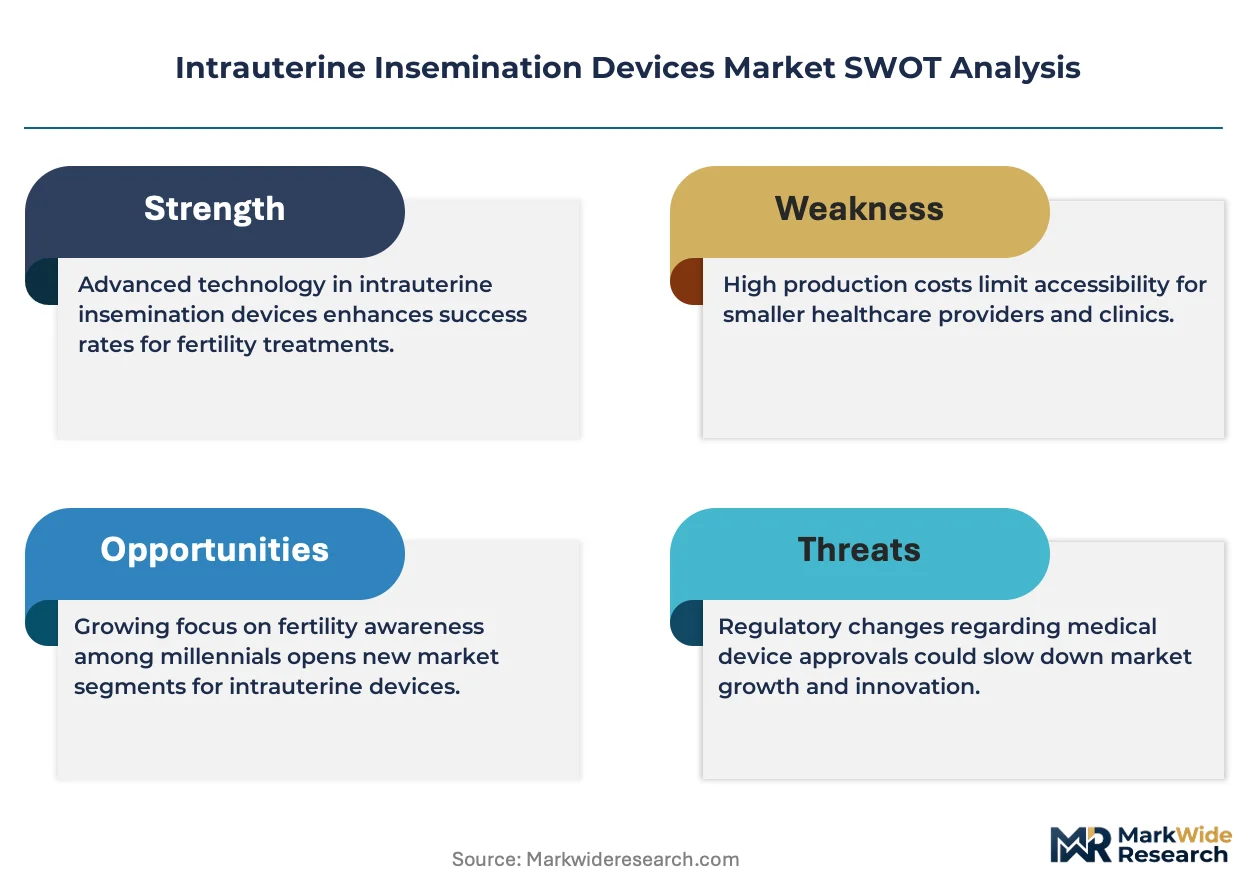
- FDA 510(k) pathway streamlining:Expedited premarket notification reviews for class II reproductive devices shorten manufacturer time-to-revenue cycles. Device sponsors leverage predicate device strategies to accelerate clearance timelines.
- Japan's PMDA biocompatibility frameworks:Specialized JIS-compliant testing standards create defensible market positions for manufacturers achieving local certification. Domestic clinic procurement preferences favor PMDA-cleared devices.
Market Restraints
- Medical-grade polymer input volatility:Polyurethane and silicone resin prices fluctuate with petrochemical feedstock markets. Manufacturers lack pricing power to pass through raw material spikes.
- European notified body capacity constraints:EU MDR implementation bottlenecks delay CE marking timelines for reproductive device categories. Sterilization validation backlogs extend commercialization schedules by quarters.
- Stainless steel cannula substitution:Rigid instrumentation retains hospital-based training and research utility. Academic medical centers sustain demand for reusable alternatives despite single-use trends.
Strategic Opportunities
- India's CDSCO registration pathways:Underpenetrated assisted reproductive technology infrastructure creates first-mover positioning for catheter manufacturers achieving import license clearance. Private fertility clinic chains expand metro presence.
- Asset-light precision manufacturing leasing:Polymer extrusion equipment rental models reduce capital barriers for mid-sized entrants. Contract manufacturers absorb sterilization infrastructure costs.
- EMA-MDR clinical evidence harmonization:Streamlined biocompatibility documentation requirements reduce redundant testing burdens. Multi-regional sponsors consolidate regulatory dossier preparation.
Industry Challenges
- Sterilization validation expertise scarcity:Ethylene oxide and gamma irradiation protocol specialists command premium compensation. Smaller manufacturers outsource to contract sterilizers with limited capacity.
- Multi-jurisdiction quality management system complexity:FDA 21 CFR Part 820, EU MDR Annex IX, and PMDA QMS ministerial ordinance requirements demand parallel compliance architectures. Audit fatigue strains regulatory affairs teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intrauterine Insemination Devices Market |
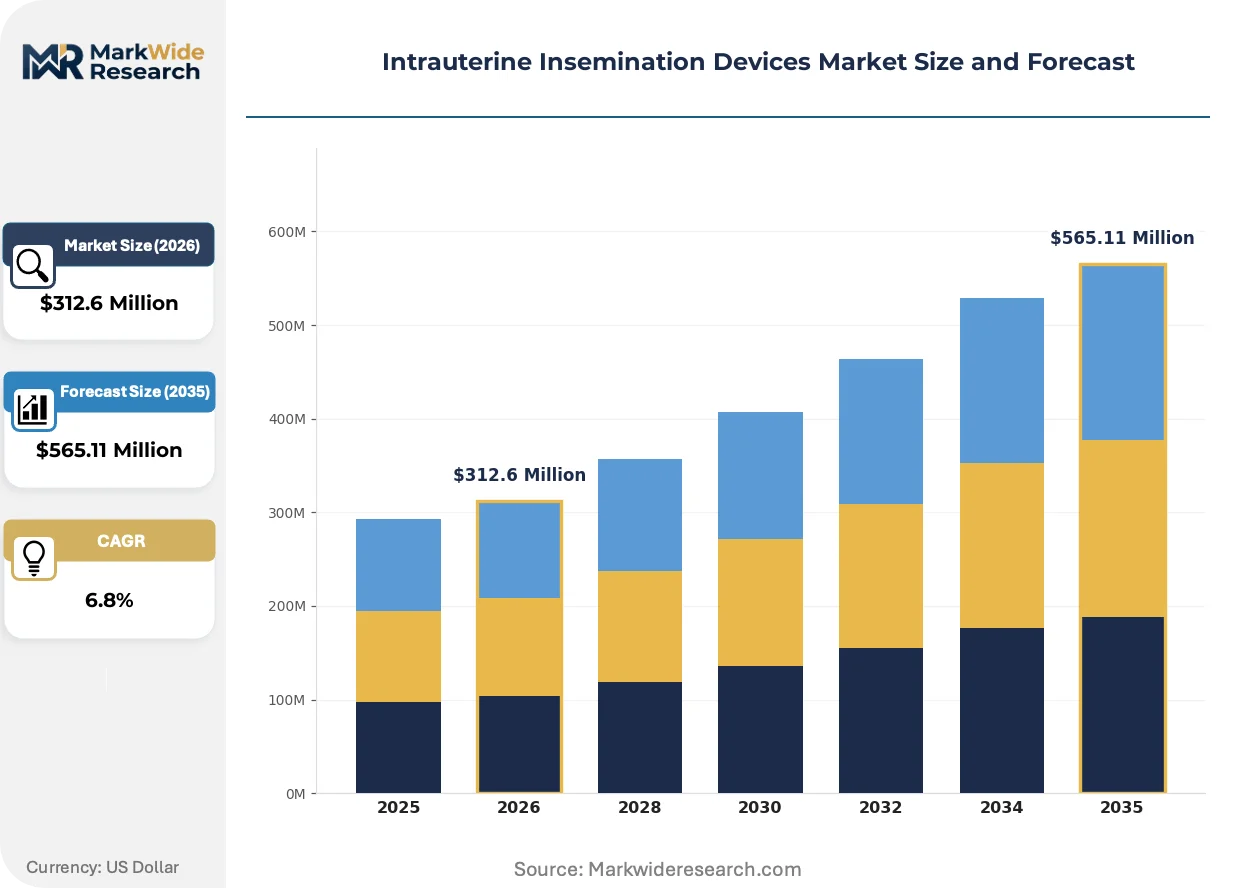
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Catheters, Cannulas, Syringes, Needles End User: Fertility Clinics, Hospitals, Research Institutions, Home Care Material: Polyurethane, Silicone, Stainless Steel, Polyethylene Application: Infertility Treatment, Sperm Preservation, Genetic Screening, Assisted Reproductive Technology |
| Companies Covered | Cook Medical, CooperSurgical, MedGyn Products, Kitazato Corporation, Rocket Medical, Prince Medical, Gynotec B.V., Hamilton Thorne, SURGIMEDIK Healthcare India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intrauterine Insemination Devices Market Shifts & Advancements
Catheter design is converging with precision polymer processing and automated assembly to compress unit costs while elevating atraumatic performance benchmarks.
Soft polyurethane formulations are migrating from premium positioning to standard-of-care across fertility clinic networks. High-volume clinic operators specify rounded-tip catheters for routine IUI procedures. This material transition is compressing silicone variant market share in uncomplicated cervical anatomy cases.
EU MDR Annex XVI reproductive device classification rules are expanding clinical evidence requirements for CE marking. Manufacturers must generate post-market surveillance data beyond predicate device equivalence. Small-cap sponsors face documentation burdens previously managed through 510(k) cross-recognition strategies.
Direct procurement contracts between fertility clinic networks and catheter manufacturers are displacing traditional distributor intermediaries. Large United States fertility platforms negotiate volume pricing through centralized supply chain functions. This channel consolidation is visible most acutely in multi-state clinic systems with standardized protocol requirements.
Intrauterine Insemination Devices Market Segmentation
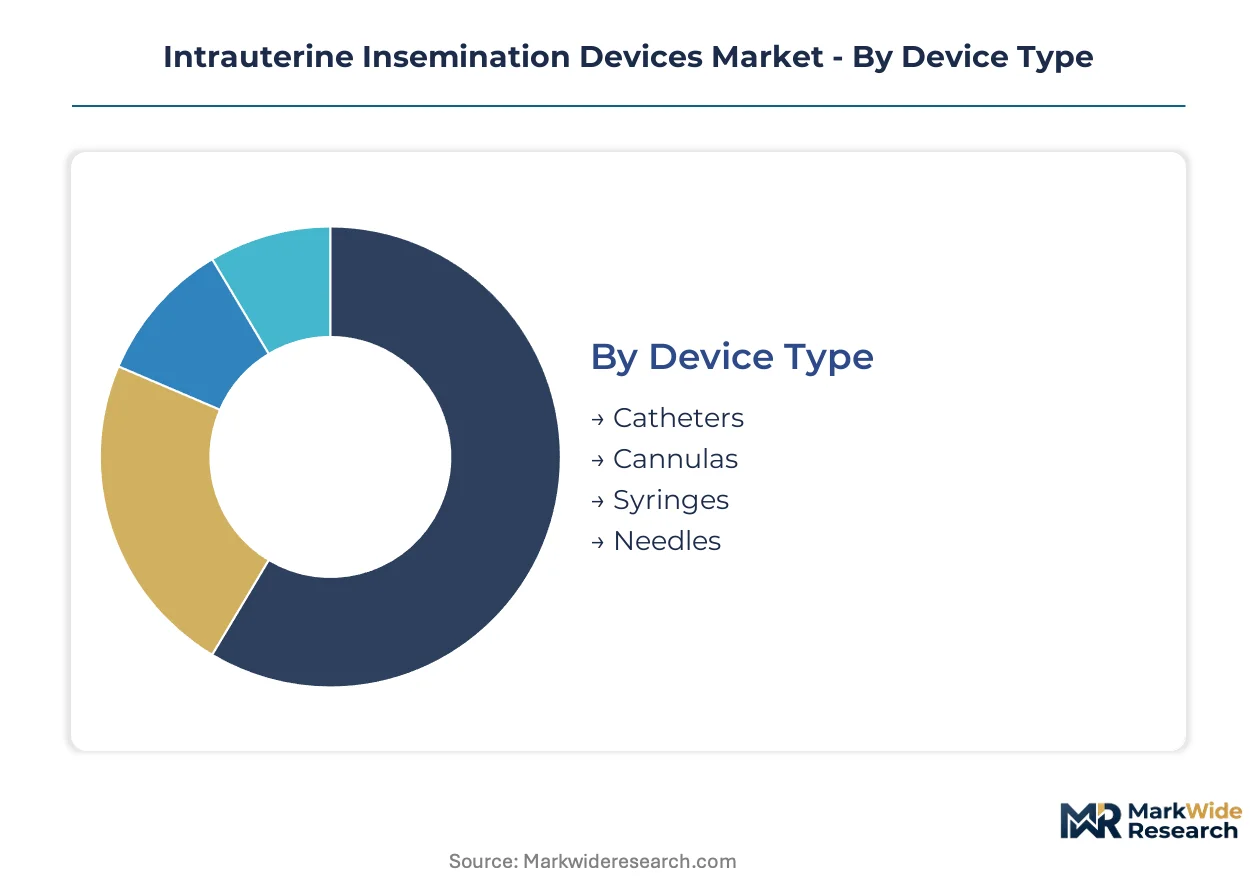
Segmentation in the intrauterine insemination devices market reveals how material science, clinical setting economics, and procedure complexity drive purchasing behavior. Manufacturers calibrate product portfolios across these dimensions to capture volume in high-throughput fertility networks while defending margin in specialized applications.
Device Type:
Application complexity and reimbursement rates determine which instrument formats dominate procurement budgets across clinical settings.
- Catheters:Engineered from soft polymers with rounded atraumatic tips, these instruments deposit washed sperm at precise fundal distances. Fertility clinics in the United States specify single-use polyurethane variants for routine IUI protocols, compressing procedure time and reducing patient discomfort complaints.
- Cannulas:Rigid stainless steel construction supports training applications and research protocols requiring instrument durability. Academic medical centers sustain procurement of reusable cannulas despite single-use trends, particularly for resident education programs.
- Syringes:Luer-lock compatible barrels ensure controlled sperm suspension delivery pressure.
- Needles:Precision-gauge designs facilitate semen aspiration in cryopreservation workflows.
Catheters command the established base. The steepest expansion runs through single-use cannula alternatives for outpatient settings.
End User:
Procurement authority and volume scale separate institutional buyers, with network consolidation reshaping supplier relationships.
- Fertility Clinics:Specialized reproductive medicine centers generate concentrated demand for high-throughput, single-use catheter formats. Large United States fertility platforms negotiate direct manufacturer contracts, bypassing traditional distributor markups through centralized supply chain functions.
- Hospitals:Integrated health systems balance IUI procedure volume against broader obstetrics-gynecology service lines. Reusable instrument maintenance programs retain budget share in hospital settings where sterilization infrastructure is already captive.
- Research Institutions:Protocol standardization requirements drive demand for documented batch consistency and material traceability.
- Home Care:Regulatory constraints limit penetration, though telemedicine-enabled protocols are expanding supervised self-administration models.
Fertility clinics command the established base. The steepest expansion runs through hospital outpatient departments adding IUI capacity.
Material:
Biocompatibility certification tiers and manufacturing cost structures stratify competitive positioning across price-sensitive and premium segments.
- Polyurethane:Soft, thermoplastic formulations enable thin-wall catheter construction with superior flexibility and kink resistance. The material has migrated from premium positioning to standard-of-care across United States fertility networks, displacing silicone in uncomplicated cervical anatomy cases.
- Silicone:Hydrophobic surface properties and exceptional biocompatibility sustain premium positioning for complex cervical stenosis or retroverted uterus cases where instrument navigation demands maximum tissue conformance.
- Stainless Steel:Rigid cannula applications in training and research preserve demand despite polymer dominance in clinical practice.
- Polyethylene:Lower-cost alternative for price-constrained markets, though stiffness limitations restrict application scope.
Polyurethane commands the established base. The steepest expansion runs through next-generation silicone-polyurethane blends.
Application:
Clinical indication severity and reimbursement coding precision determine which procedure categories absorb device innovation investment.
- Infertility Treatment:Primary indication driving IUI device volume, encompassing unexplained infertility, mild male factor, and cervical factor cases. Fertility clinics in the United States standardize catheter protocols across this broad indication category, with procedure coding supporting favorable reimbursement.
- Assisted Reproductive Technology:IUI serves as first-line intervention before IVF escalation, with device specifications calibrated to ovarian stimulation protocols. Timing precision requirements in stimulated cycles elevate demand for consistent catheter performance.
- Sperm Preservation:Cryobanking workflows require specialized cannulas for semen sample extraction and processing.
- Genetic Screening:Preimplantation genetic testing companion procedures utilize modified catheter designs for embryo transfer after screening.
Infertility treatment commands the established base. The steepest expansion runs through ART-integrated IUI protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fertility clinic networks concentrate procurement authority in the United States, while manufacturer certification strategies target Japan's specialized biocompatibility standards and India's underpenetrated assisted reproductive technology infrastructure.
United States
Large multi-state fertility platforms drive catheter volume through centralized direct procurement contracts, bypassing traditional distributor intermediaries. The FDA's streamlined 510(k) premarket notification framework accelerates clearance timelines for class II reproductive devices. Major fertility networks in California and Texas standardize single-use polyurethane catheter protocols across their clinic systems.
Japan
Domestic clinic procurement preferences favor devices achieving PMDA clearance under specialized JIS-compliant biocompatibility testing standards. The country's national pharmaceutical regulator maintains distinct validation protocols that shape product development priorities for Asia-Pacific market participants. Tokyo and Osaka metropolitan areas host concentrated fertility clinic density supporting premium catheter positioning.
Germany
Hospital-based obstetrics-gynecology departments sustain demand for reusable instrument maintenance programs alongside single-use adoption. The EU Medical Device Regulation imposes strengthened clinical evidence requirements through notified body capacity-constrained CE marking pathways. The Rhine-Ruhr and Bavarian medical device clusters concentrate sterilization validation expertise serving reproductive device manufacturers.
India
Private fertility clinic chains expand metro presence in underpenetrated assisted reproductive technology markets. CDSCO import license registration pathways create first-mover positioning for catheter manufacturers achieving regulatory clearance. Mumbai and Delhi-NCR fertility hubs absorb rising procedure volumes as patient awareness of IUI protocols spreads.
United Kingdom
NHS fertility service commissioning frameworks shape procurement specifications across hospital and clinic settings. MHRA alignment with EU MDR transitional provisions extends CE marking recognition timelines for reproductive device categories. London and Southeast England fertility networks negotiate volume contracts with manufacturer direct sales operations.
Intrauterine Insemination Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into three archetypes: large integrated reproductive health corporations with direct distribution infrastructure, mid-sized polymer processing specialists with captive extrusion capacity, and regional contract manufacturers serving price-constrained markets. Dominant competitive moves include direct procurement contract negotiations with fertility clinic networks and sterilization validation capability investments to compress regulatory timelines.
Among United States-based reproductive health corporations, Cook Medical and CooperSurgical occupy positions exemplifying integrated channel control through direct distribution networks and polymer processing specialization. Kitazato Corporation represents the Asia-Pacific specialist archetype, anchoring competitive positioning through Japan's JIS-compliant device segment expertise. These three entities illustrate how geographic certification advantages and manufacturing integration separate tier positions in catheter supply.
| Leading Market Players |
|---|
| Cook Medical |
| CooperSurgical |
| MedGyn Products |
| Kitazato Corporation |
| Rocket Medical |
| Prince Medical |
| Gynotec B.V. |
| Hamilton Thorne |
| SURGIMEDIK Healthcare India |
| Others |
Supply & Pricing Matrix
Polymer resin price volatility tied to petrochemical feedstock markets determines both the spread between premium silicone and standard polyurethane catheter tiers and the geographic distribution of extrusion capacity. Manufacturers absorbing raw material spikes without pricing power compress margins at the economy tier while defending premium positioning through JIS-compliant certification premiums.
Pricing Analysis
Cost-plus contracts with polyurethane resin indexation dominate procurement between catheter manufacturers and fertility clinic networks in the United States. Pricing stratifies across premium, standard, and economy tiers based on material grade and FDA 510(k) clearance status, with silicone variants commanding substantial premiums for complex cervical anatomy cases. Cost compression in the polyethylene economy tier is intensifying as Indian contract manufacturers expand CDSCO-cleared import volumes. Hospital outpatient departments exhibit the highest price sensitivity, while specialized fertility clinics prioritize atraumatic performance over unit cost.
Supply Chain Analysis
Contract manufacturing for sterile catheter assembly concentrates in Malaysia, Costa Rica, and selected Eastern European medical device zones serving EU and US markets. Medical-grade polyurethane pellets, silicone elastomers, and ethylene oxide sterilization services feed from petrochemical hubs in Texas, Singapore, and Rotterdam. Single-source vulnerability in gamma irradiation capacity creates bottlenecks during sterilization validation surges. Distribution runs through direct procurement contracts with large fertility networks displacing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intrauterine insemination devices market represents a high-growth disruption anchored by FDA 510(k) pathway streamlining that compresses manufacturer time-to-revenue cycles. This regulatory inflection enables rapid predicate device strategies while EU MDR implementation creates temporary competitive shelter for US-cleared products.
For Market Incumbents: Entrench polymer extrusion capacity through backward integration into medical-grade resin compounding to defend against commodity volatility. Expand sterilization validation infrastructure in Malaysia and Costa Rica to compress regulatory timelines threatened by European notified body capacity constraints. Direct procurement contract penetration with multi-state fertility networks remains the priority lever against distributor disintermediation.
For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated assisted reproductive technology infrastructure by securing CDSCO import licenses before metro clinic chain expansion accelerates. Target hospital outpatient departments adding IUI capacity as the most penetrable segment, where reusable instrument maintenance programs create switching cost vulnerability. Pursue asset-light precision manufacturing leasing models to bypass capital barriers.
For Investors and Strategic Acquirers: EU MDR Annex XVI implementation reshapes the acquisition landscape by elevating clinical evidence requirements that strain small-cap sponsor resources. Long-term viability favors mid-sized polymer processing specialists with captive extrusion capacity and multi-regional certification portfolios. Monitor notified body capacity expansion timelines as the critical inflection signal for CE marking timeline normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Expedited premarket notification reviews compress time-to-revenue for class II reproductive device sponsors. |
| Direct Procurement Contracting | Centralized supply chain functions at large US fertility networks displace traditional distributor intermediaries. |
| Sterilization Validation Investment | Ethylene oxide and gamma irradiation capability expansion addresses expertise scarcity constraining smaller manufacturers. |
| CDSCO Registration Pathway Execution | Import license clearance in India creates first-mover positioning in underpenetrated metro fertility markets. |
| Polymer Extrusion Backward Integration | Captive resin compounding capacity insulates margin compression from petrochemical feedstock volatility. |
Research Methodology
A standing panel of reproductive endocrinologists, fertility clinic supply chain directors, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation through FDA 510(k) premarket notification databases, EU MDR notified body guidance documents, PMDA ministerial ordinances, and hospital procurement contract records. Bottom-up catheter volume estimates from fertility clinic procedure data triangulated with top-down medical device trade flow analysis across the analysis window.
Scenario-bracketing around polymer resin price volatility, notified body capacity constraints, and fertility clinic network consolidation generated bounded projections across device type, material grade, end-user setting, and regional regulatory cluster dimensions. CAGRs derived from procedure volume elasticity to reimbursement rate changes and catheter replacement cycle analysis. Forecast inputs incorporated sterilization validation queue lengths and CDSCO registration timeline distributions without year-specific anchoring.
Stress conditions across polyurethane resin indexation bands, EU MDR implementation delays, and fertility clinic network M&A velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding predicate device equivalence strategies and JIS-compliant certification penetration. Quarterly review of notified body capacity indicators, CDSCO clearance volumes, and fertility clinic direct procurement contract announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intracranial Stents Total Addressable Market
Medical Devices
Middle East and Africa Aligner Sheet Market
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Non-Invasive Ventilators Market
Medical Devices
Portable Medical Devices Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
North America Medical Devices Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Electrophysiology Ablation Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Netherlands Artificial Organs and Bionic Implants Market
Medical Devices
Intubation Tubes Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
Electroencephalogram (EEG) Caps Market