
 Saudi Arabia Anesthesia Devices Market | 2026-2036
Saudi Arabia Anesthesia Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Anesthesia Devices Market Analytics
The Saudi Arabia anesthesia devices landscape is recalibrating around a widening split between premium integrated workstations and commodity-level delivery systems. GE Healthcare leverages its installed base of advanced anesthesia machines to sustain service-contract revenue across Ministry of Health hospitals. Mindray Medical International Limited anchors its position through cost-competitive monitors that compete aggressively in mid-tier surgical centers. Drägerwerk AG & Co. KGaA differentiates via German-engineered ventilation safety protocols that dominate high-acuity cardiac and pediatric settings.
Anesthesia devices encompass mechanical systems for controlled gas delivery, respiratory monitoring, and patient ventilation during surgical or diagnostic procedures, typically integrating vaporizers, breathing circuits, and multi-parameter sensors within a single workstation. Their primary purpose is to maintain precise depth of unconsciousness while safeguarding airway patency and hemodynamic stability. Anesthesia machines command the largest installed base among device types, though monitors capture disproportionate margin pools through recurring sensor and software upgrade cycles. Among applications, cardiac procedures and pediatric surgery represent structurally faster-growing demand verticals due to specialized ventilation requirements and smaller patient physiology constraints.
The Saudi Food and Drug Authority (SFDA) enforces medical device registration and post-market surveillance protocols that shape import timelines and clinical evidence requirements for anesthesia equipment manufacturers. Ministry of Health procurement frameworks increasingly mandate ISO 13485 quality system certification and IEC 60601 electrical safety compliance as baseline market access conditions. Stakeholders must monitor how SFDA alignment with Global Harmonization Task Force standards reshapes technical documentation burdens and competitive entry thresholds.
Market Dynamics
Vision 2030 healthcare privatization is restructuring purchasing authority from centralized Ministry of Health procurement toward hospital-level decision-making, fragmenting vendor relationships and accelerating workstation replacement cycles at tertiary facilities.
Growth Catalysts
- SFDA Registration Harmonization:Alignment with Global Harmonization Task Force standards is streamlining technical documentation for imported anesthesia workstations, reducing market entry timelines for international manufacturers.
- Tertiary Hospital Expansion:New cardiac and pediatric surgical centers in Riyadh and Jeddah are generating concentrated demand for high-acuity ventilation systems with specialized safety protocols.
- Integrated Monitoring Convergence:Multi-parameter sensors combining respiratory, hemodynamic, and depth-of-anesthesia data are displacing standalone monitors in flagship Ministry of Health facilities.
Market Restraints
- Import Dependency Concentration:European and Asian original equipment manufacturers control vaporizer and ventilator component supply, exposing procurement to currency fluctuation and shipping volatility.
- SFDA Clinical Evidence Requirements:Post-market surveillance protocols mandate local adverse event reporting infrastructure that smaller distributors struggle to maintain.
- Specialized Technical Labor Scarcity:Biomedical engineering programs in Saudi Arabia produce insufficient certified anesthesia equipment technicians for preventive maintenance demands.
Strategic Opportunities
- Eastern Province Penetration:Dammam and Khobar surgical centers remain under-supplied with advanced workstations relative to Riyadh-Jeddah concentration.
- Remote Monitoring Integration:Cloud-connected anesthesia data platforms are opening recurring software revenue streams independent of hardware replacement cycles.
- Public-Private Partnership Frameworks:Ministry of Health leasing arrangements for anesthesia equipment are transferring capital burden to vendors while locking long-term service contracts.
Industry Challenges
- Biomedical Certification Bottlenecks:IEC 60601 electrical safety testing capacity at SFDA-accredited laboratories creates six-to-nine month approval queues for new workstation models.
- Legacy System Interoperability:Hospital information system fragmentation forces anesthesia vendors to maintain multiple data interface protocols, elevating software development overhead.
- Preventive Maintenance Workforce Gaps:Field service engineer turnover exceeds training pipeline output, degrading uptime guarantees at mid-tier surgical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Anesthesia Devices Market |
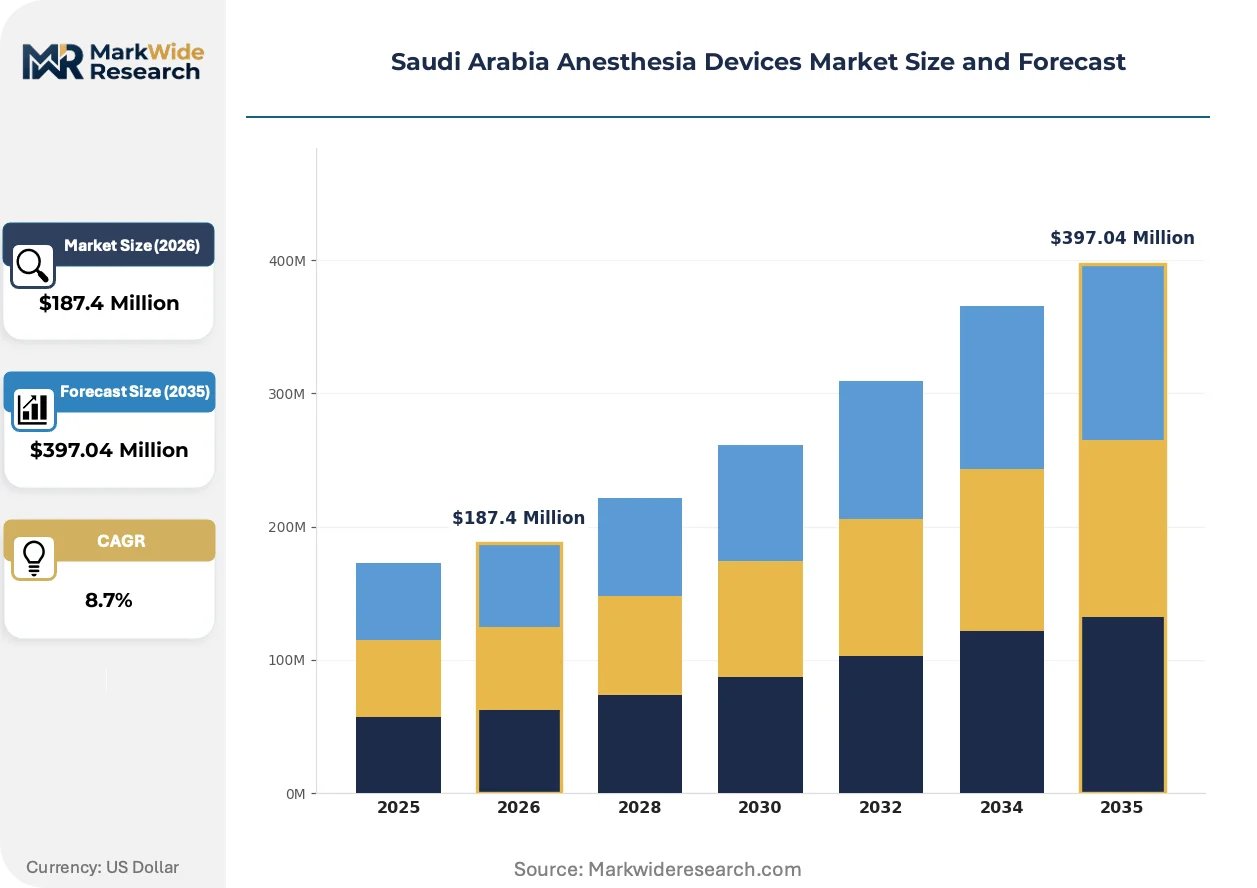
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Anesthesia Machines, Monitors, Delivery Systems, Ventilators Application: Pediatric Surgery, Cardiac Procedures, Pain Management, Emergency Medicine End User: Hospitals, Surgical Centers, Ambulatory Care, Clinics Technology: MAC, TIVA, Closed Circuit, Open Circuit |
| Companies Covered | GE Healthcare, Mindray Medical International Limited, Drägerwerk AG & Co. KGaA, Koninklijke Philips N.V., Medtronic PLC, Cardinal Health, Inc, Nihon Kohden Corporation, Schiller AG, Al-Amin Medical Instruments Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Anesthesia Devices Market Evolving Landscape
Digital anesthesia workstations are embedding predictive algorithms and closed-loop control systems that reduce anesthesiologist cognitive load while tightening ventilation precision. These advances are compressing the functional gap between premium and mid-tier equipment categories.
Closed-loop target-controlled infusion systems are integrating pharmacokinetic modeling with real-time depth-of-anesthesia monitoring to automate propofol and remifentanil delivery. Tertiary cardiac centers in Riyadh are piloting these platforms for long-duration procedures. The technology is integrating anesthesiologist decision support with mechanical execution, reducing variability in emergence times and post-operative recovery metrics.
SFDA alignment with IEC 60601-1 third edition and collateral standards for alarm systems is mandating prioritized audible alerts and alarm pause functionality across all new anesthesia workstation registrations. Manufacturers must redesign user interfaces and conduct human factors validation studies to maintain market access. High-acuity pediatric settings face the steepest compliance burden due to specialized low-flow ventilation alarm thresholds.
Hospital procurement departments are consolidating anesthesia device purchasing under five-year managed equipment service agreements that bundle hardware, consumables, and preventive maintenance into per-procedure fees. Ministry of Health flagship facilities pioneered this model; mid-tier surgical centers in Jeddah are now adopting similar structures. The shift transfers obsolescence risk to vendors while binding customers to single-source relationships through embedded software ecosystems.
Saudi Arabia Anesthesia Devices Market Segmentation
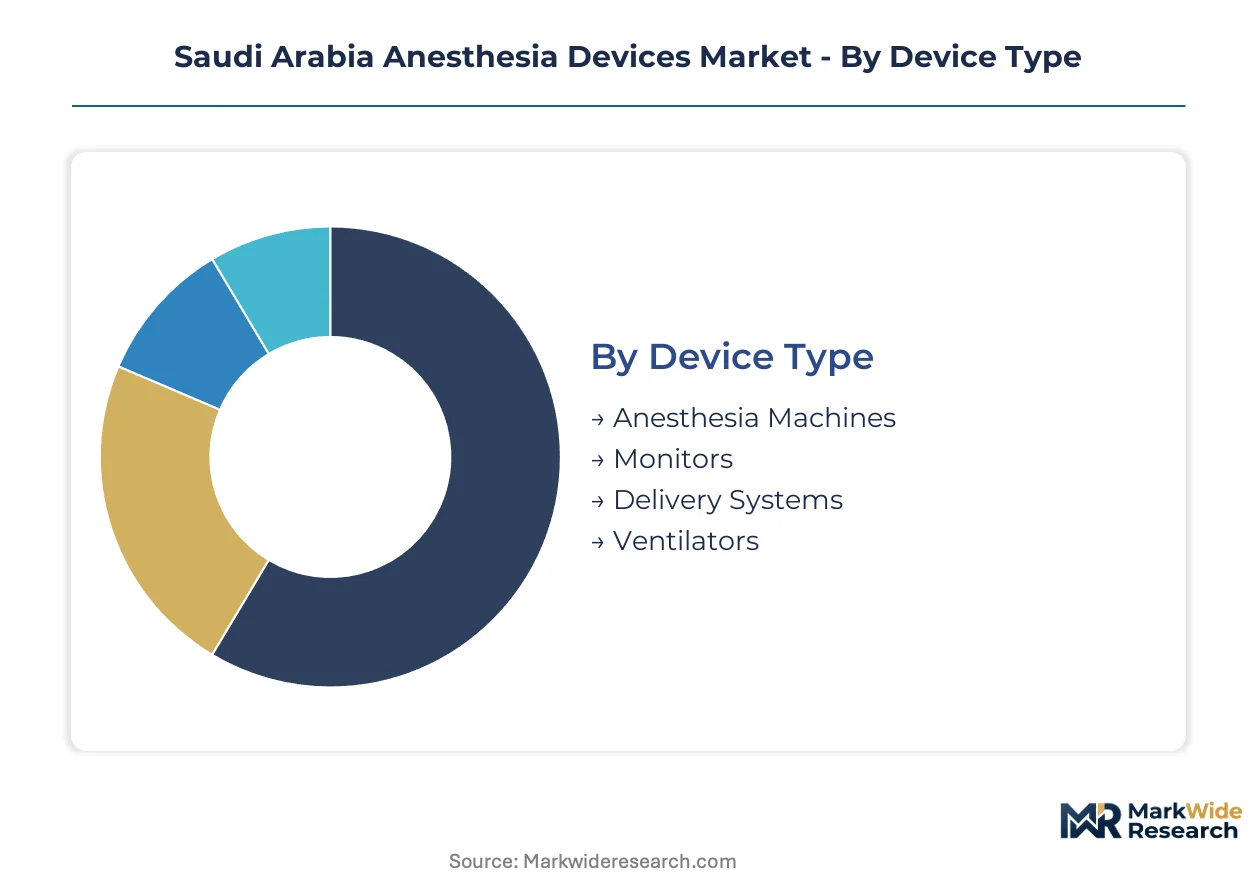
Saudi Arabia's anesthesia devices market fragments across four critical dimensions that shape procurement decisions at Ministry of Health facilities and emerging private surgical centers. Understanding these segment boundaries clarifies how Vision 2030 privatization redirects purchasing authority and technology preferences.
Device Type:
Hospital procurement committees weigh capital intensity against service revenue potential when selecting anesthesia equipment categories.
- Anesthesia Machines:Integrated workstations combining vaporizers, breathing circuits, and gas delivery systems form the core infrastructure for tertiary surgical suites. Riyadh's flagship cardiac centers prioritize German-engineered units with advanced ventilation safety protocols.
- Monitors:Multi-parameter sensors tracking respiratory, hemodynamic, and depth-of-anesthesia metrics generate recurring revenue through disposable components and software upgrades. Jeddah's mid-tier surgical centers favor cost-competitive Asian alternatives.
- Delivery Systems:Standalone vaporizers and gas mixing modules serve as replacement components within existing workstation ecosystems.
- Ventilators:High-frequency and low-flow ventilation units address specialized pediatric and cardiac physiology requirements.
Anesthesia machines lead on scale; monitors lead on momentum.
Application:
Procedure complexity and patient physiology constraints create divergent equipment specifications across surgical specialties.
- Cardiac Procedures:Long-duration surgeries demand closed-loop target-controlled infusion systems with precise hemodynamic monitoring. Riyadh's new cardiac centers pilot automated propofol delivery platforms.
- Pediatric Surgery:Smaller patient volumes and specialized low-flow ventilation requirements command premium safety protocols and alarm threshold configurations.
- Pain Management:Regional anesthesia and nerve block procedures utilize portable delivery systems with simplified user interfaces.
- Emergency Medicine:Rapid-sequence induction capabilities prioritize reliability and minimal setup time over advanced monitoring integration.
Cardiac procedures anchor revenue concentration; pediatric surgery claims the steepest expansion trajectory.
End User:
Facility scale and case volume determine whether procurement favors premium integrated workstations or modular component systems.
- Hospitals:Ministry of Health tertiary facilities command centralized purchasing power for advanced anesthesia workstations with comprehensive service contracts.
- Surgical Centers:Mid-tier private facilities in Jeddah adopt managed equipment service agreements bundling hardware, consumables, and preventive maintenance.
- Ambulatory Care:Same-day surgery units prioritize compact, transportable delivery systems with rapid turnover capabilities.
- Clinics:Diagnostic and minor procedure settings utilize basic monitors and standalone delivery modules.
Hospitals dominate absolute spend; surgical centers gain share fastest.
Technology:
Anesthesia delivery methodology selection reflects anesthesiologist training backgrounds and procedure-specific pharmacokinetic requirements.
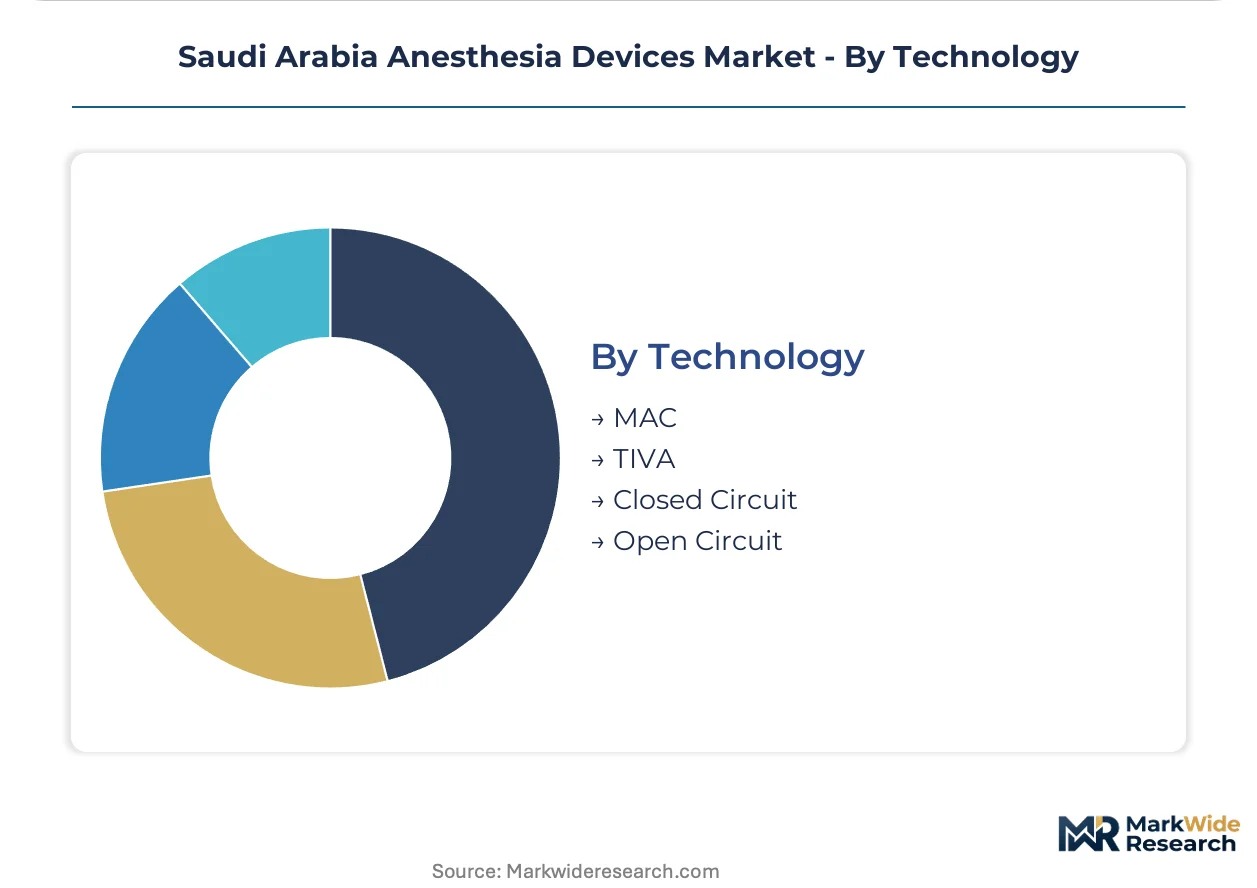
- MAC:Minimum alveolar concentration-based inhalational anesthesia remains the dominant protocol for general surgery across Saudi tertiary facilities.
- TIVA:Total intravenous anesthesia with target-controlled infusion systems expands in cardiac and neurosurgical settings requiring precise emergence control.
- Closed Circuit:Low-flow rebreathing systems reduce anesthetic gas consumption and environmental exposure in high-volume surgical centers.
- Open Circuit:Non-rebreathing configurations serve pediatric and emergency applications requiring rapid gas exchange.
MAC retains installed base dominance; TIVA climbs fastest among advanced surgical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified biomedical engineers concentrate in Riyadh and Jeddah, creating localized maintenance capacity that shapes equipment procurement patterns across Saudi Arabia's anesthesia devices landscape.
Riyadh
Flagship Ministry of Health cardiac centers and pediatric surgical institutes drive demand for high-acuity ventilation systems with advanced safety protocols. SFDA registration requirements for new workstation models create six-to-nine month approval queues at accredited testing laboratories. King Faisal Specialist Hospital anchors centralized purchasing authority for integrated anesthesia workstations across the capital region.
Jeddah
Mid-tier private surgical centers adopt managed equipment service agreements bundling hardware, consumables, and preventive maintenance into per-procedure fees. Ministry of Health procurement frameworks mandate ISO 13485 certification and IEC 60601 compliance as baseline market access conditions. King Abdulaziz Medical City and adjacent private facilities concentrate demand for cost-competitive monitors from Asian manufacturers.
Eastern Province
Dammam and Khobar surgical centers remain under-supplied with advanced workstations relative to Riyadh-Jeddah concentration, creating penetration opportunities for vendors with established service networks. SFDA post-market surveillance protocols require local adverse event reporting infrastructure that filters distributor participation. Johns Hopkins Aramco Healthcare and Dammam Medical Complex anchor procurement clusters in the region's largest metropolitan zone.
Western Region
Makkah and Madinah pilgrimage healthcare infrastructure generates seasonal demand spikes for portable anesthesia delivery systems with rapid setup capabilities. Ministry of Health leasing arrangements transfer capital burden to vendors while locking long-term service contracts. The Two Holy Mosques' medical cities prioritize equipment redundancy for high-volume surgical throughput during Hajj and Umrah periods.
NEOM Northwest
Emerging healthcare zone development under Vision 2030 mandates cloud-connected anesthesia data platforms from inception rather than retrofitting legacy systems. Public-private partnership frameworks for medical city construction specify integrated monitoring convergence requirements. The linear city's planned surgical institutes represent greenfield procurement opportunities unconstrained by existing vendor relationships.
Saudi Arabia Anesthesia Devices Market Competitive Landscape
Top-tier vendors anchor high-acuity integrated workstation segments, while mid-tier specialists compete on monitor cost positioning and regional service coverage. The vendor base stratifies across three archetypes: German-engineered safety protocol specialists, Asian cost-competitive monitor suppliers, and diversified healthcare conglomerates with installed base leverage. Dominant competitive moves include five-year managed equipment service agreements that bundle hardware and consumables, plus cloud-connected software ecosystems that lock recurring revenue streams.
Among German-engineered specialists, Drägerwerk AG & Co. KGaA exemplifies the premium-tier archetype through its ventilation safety positioning in cardiac and pediatric settings. GE Healthcare represents the diversified conglomerate model, leveraging broad healthcare portfolios to sustain service-contract relationships across Ministry of Health facilities. Mindray Medical International Limited anchors the cost-competitive tier, occupying a position that challenges mid-tier surgical center procurement with monitor-focused alternatives.
| Leading Market Players |
|---|
| GE Healthcare |
| Mindray Medical International Limited |
| Drägerwerk AG & Co. KGaA |
| Koninklijke Philips N.V. |
| Medtronic PLC |
| Cardinal Health, Inc |
| Nihon Kohden Corporation |
| Schiller AG |
| Al-Amin Medical Instruments Co. Ltd |
| Others |
Value Network & Pricing Analysis
Closed-loop target-controlled infusion systems are compressing cost economics across anesthesia workstation tiers while simultaneously redistributing supply influence toward manufacturers with integrated software ecosystems. This technological shift rewards vendors bundling predictive algorithms with hardware, squeezing margins for standalone equipment suppliers.
Pricing Analysis
Managed equipment service agreements now dominate procurement, bundling hardware, consumables, and preventive maintenance into per-procedure fees that transfer obsolescence risk to vendors. Price differentiation rests on ISO 13485 certification tier and depth of after-sales service integration. Cost compression in mid-tier monitors intensifies as Asian manufacturers compete aggressively on sensor replacement cycles. Ministry of Health tertiary facilities show lowest price sensitivity, while private surgical centers in Jeddah negotiate hardest on upfront capital outlays.
Supply Chain Analysis
Regional distribution centers in Riyadh and Jeddah anchor hub-and-spoke patterns serving Ministry of Health facilities across the Kingdom. Component supply draws from Germany, China, and South Korea for vaporizers, ventilator assemblies, and multi-parameter sensors. Single-source vulnerability concentrates in precision gas flow controllers and specialized pediatric breathing circuits. Distribution runs through authorized distributor networks with SFDA import licensing, creating bottleneck risk at customs clearance and electrical safety testing queues.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Saudi Arabia's anesthesia devices market stems from software-anchored recurring revenue displacing transactional hardware sales. Cloud-connected data platforms and predictive maintenance contracts capture value previously lost to third-party service providers.
For Market Incumbents: Acquire field service engineering capabilities to lock preventive maintenance relationships before hospital privatization fragments purchasing authority. Defend against Asian monitor manufacturers by embedding proprietary sensor ecosystems that raise switching costs. Prioritize IEC 60601-1 third edition compliance investment to clear SFDA approval queues faster than competitors.
For New Entrants and Emerging Players: Capture Eastern Province surgical centers in Dammam and Khobar where advanced workstation penetration lags Riyadh-Jeddah concentration. Target pediatric and cardiac ventilation segments requiring specialized safety protocols that filter out commodity competitors. Enter through public-private partnership leasing frameworks that bypass upfront capital barriers at mid-tier facilities.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors lacking SFDA adverse event reporting infrastructure. Long-term viability favors vendors with cloud-connected software platforms generating recurring revenue independent of hardware replacement cycles. Monitor SFDA alignment with Global Harmonization Task Force standards as signal for technical documentation burden shifts that favor scaled manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Harmonization | Streamlined technical documentation reduces market entry timelines for international manufacturers seeking Saudi access. |
| Managed Equipment Service Agreements | Five-year bundled contracts transfer obsolescence risk to vendors while locking customers through embedded software ecosystems. |
| Cloud-Connected Data Platform Development | Remote monitoring integration opens recurring software revenue streams independent of hardware replacement cycles at tertiary facilities. |
| Eastern Province Service Network Expansion | Dammam and Khobar penetration addresses supply gap relative to Riyadh-Jeddah concentration with established maintenance capacity. |
| Pediatric Ventilation Safety Certification | Specialized low-flow alarm threshold compliance captures premium positioning in high-acuity settings with steepest regulatory barriers. |
Research Methodology
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers, plus secondary validation against SFDA registration databases, Ministry of Health procurement records, and IEC standards documentation — were reconciled through bottom-up equipment shipment analysis and top-down healthcare expenditure triangulation.
Historical trend analysis cross-referenced with panel input from anesthesia device manufacturers and distributor networks shaped the projection framework across device type, application, end user, and technology segmentation dimensions. CAGRs were derived from installed base replacement cycles, surgical volume growth assumptions, and Vision 2030 privatization timelines. Modeled inputs incorporated tertiary hospital expansion pipelines, SFDA regulatory alignment schedules, and regional biomedical engineer concentration patterns.
Currency fluctuation, shipping volatility, and SFDA approval queue extensions are the dominant revision risks to forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Tear Duct Plugs Market
Medical Devices
United States Minimally Invasive Surgery Device Market
Medical Devices
Ankle Mobile Bearing System Market
Medical Devices
Microcurrent Facial Market
Medical Devices
Foot Suction Unit Market
Medical Devices
Hemodynamic Flow Alteration Devices Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Global Keratometers Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market
Medical Devices
Percutaneous Nephrostomy Catheters Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market
Medical Devices
Intradermal Injections Market