
 Latin America Insulin Delivery Devices Market | 2026-2036
Latin America Insulin Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Insulin Delivery Devices Market Foresight
Aftermarket service revenue for connected insulin delivery ecosystems is reshaping margin distribution across the Latin America Insulin Delivery Devices Market. Medtronic leverages its sensor-integrated pump platforms to sustain recurring calibration and software update income. Novo Nordisk anchors its position through pre-filled pen dominance and direct-to-patient digital coaching programs. Becton Dickinson and Company competes in the syringe and pen needle segment with high-volume manufacturing scale across multiple Latin American production sites.
Insulin delivery devices comprise engineered systems for subcutaneous hormone administration, incorporating precision dosing mechanisms, sterile fluid pathways, and biocompatible materials such as medical-grade polycarbonate and stainless steel cannulae designed to maintain insulin stability at 2-8°C storage and room-temperature operation. These devices serve the therapeutic requirement for controlled glycemic management in Type 1 and Type 2 diabetes patients across clinical and ambulatory settings. Smart Devices within the technology dimension command premium positioning through Bluetooth-enabled dose logging and clinician dashboard integration, while Conventional Devices retain volume leadership in price-sensitive public procurement channels. Pens dominate the device type category due to patient convenience and reduced dosing error rates, whereas Pumps capture faster expansion among pediatric and intensive insulin therapy populations with reimbursement support.
ANVISA in Brazil enforces post-market surveillance and Good Manufacturing Practice compliance for imported and domestically produced insulin delivery systems, directly conditioning market entry timelines and product registration costs. Mexico's Federal Commission for the Protection against Sanitary Risk applies NOM standards for medical device biocompatibility and sterility assurance, shaping supplier qualification requirements. The EU MDR equivalency pathways and ISO 11608 needle-based injection system standards further influence design verification protocols for multinational manufacturers serving Latin America. Stakeholders must monitor evolving reimbursement classifications for continuous glucose monitor-integrated pump systems as health technology assessment bodies in São Paulo, Mexico City, and Buenos Aires evaluate cost-effectiveness thresholds.
Market Dynamics
ANVISA's tightened post-market surveillance protocols for imported insulin delivery systems are compressing product registration timelines and elevating compliance costs, forcing manufacturers to restructure Latin American market entry strategies around domestic production partnerships and accelerated local clinical validation programs.
Growth Catalysts
- Reimbursement Expansion:Brazil's Sistema Único de Saúde has broadened coverage for continuous glucose monitor-integrated pump systems, reducing out-of-pocket burdens for Type 1 diabetes patients in São Paulo and Rio de Janeiro metropolitan zones.
- Home Care Migration:Mexican public health institutions are decentralizing diabetes management to ambulatory settings, creating pull-through demand for pre-filled pen devices with simplified dosing interfaces.
- Sensor-Pump Convergence:Bluetooth-enabled dose logging technology is penetrating pediatric and intensive insulin therapy populations as Argentine private insurers expand prior authorization pathways for closed-loop systems.
Market Restraints
- Import Dependency:Concentrated manufacturing of precision dosing mechanisms in North American and European facilities exposes Latin American supply chains to extended lead times and currency fluctuation risk.
- Biocompatibility Compliance:Mexico's NOM standards for medical device sterility assurance impose substantial laboratory certification costs on regional distributors lacking in-house testing infrastructure.
- Substitution Pressure:Oral GLP-1 receptor agonists are capturing select Type 2 diabetes patient segments, constraining volume growth for conventional syringe and pen needle categories in price-sensitive public procurement channels.
Strategic Opportunities
- Colombian Market Development:Underpenetrated diabetes management infrastructure in Bogotá and Medellín creates first-mover positioning for connected pen platforms with integrated dose-tracking applications.
- Direct-to-Patient Channels:Digital coaching programs linked to device ecosystems are bypassing traditional hospital-based distribution, capturing margin previously allocated to institutional procurement intermediaries.
- Local Production Incentives:Brazilian industrial policy frameworks for medical device manufacturing are attracting assembly operations for pen needle and syringe components, reducing import tariff exposure.
Industry Challenges
- Regulatory Divergence:Non-harmonized registration requirements across ANVISA, COFEPRIS, and Argentina's national pharmaceutical regulator force redundant clinical documentation and extended product launch timelines.
- Technical Workforce Scarcity:Specialized training for connected device calibration and maintenance remains concentrated in São Paulo and Mexico City, limiting service network expansion into secondary metropolitan areas.
- Legacy System Integration:Hospital information systems in Argentine public institutions lack standardized interoperability protocols for Bluetooth-enabled dose data transmission, complicating clinician dashboard deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Insulin Delivery Devices Market |
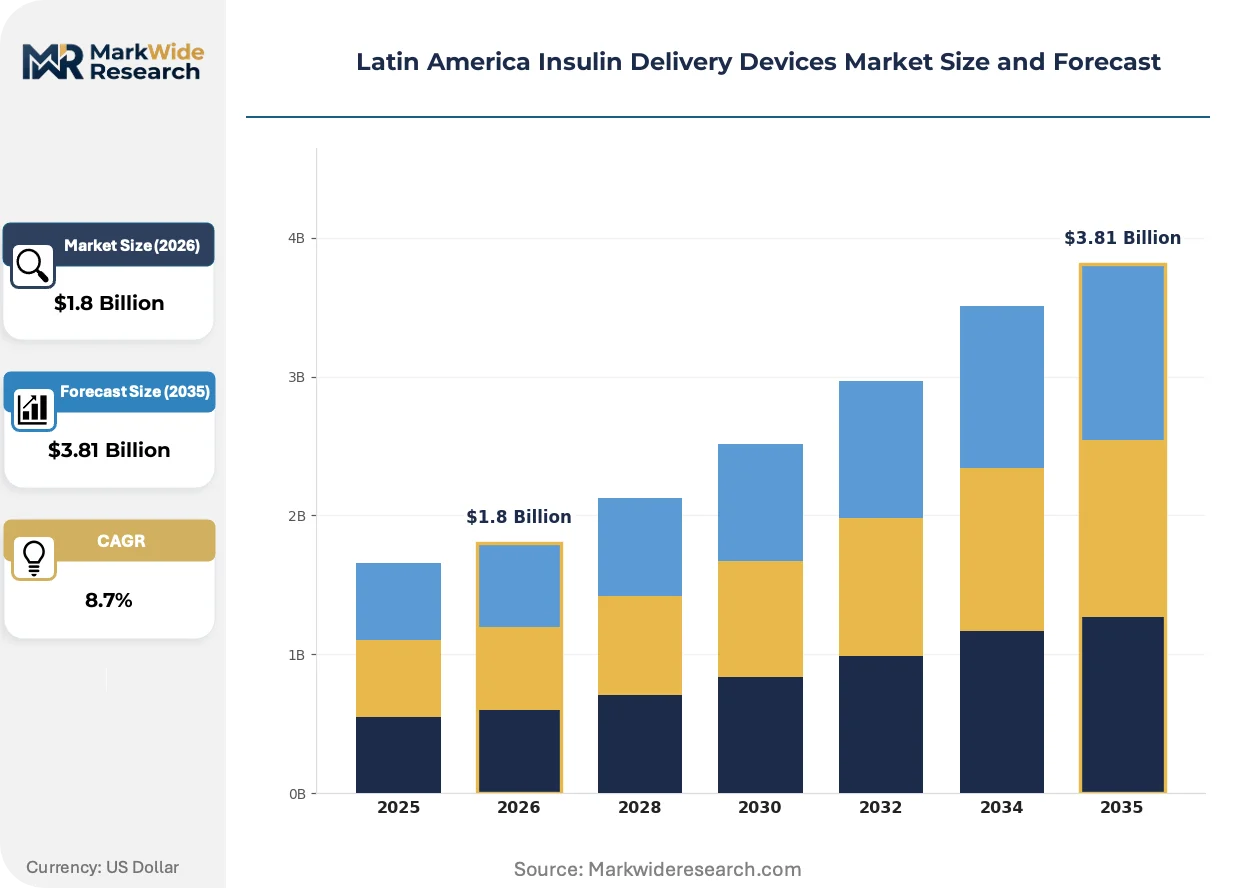
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Pens, Pumps, Syringes, Jet Injectors End User: Hospitals, Clinics, Home Care, Diagnostic Centers Technology: Smart Devices, Conventional Devices, Wearable Devices, Disposable Devices Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Medtronic, Becton Dickinson and Company, Novo Nordisk, Embecta Corp., Ypsomed, Sanofi, Insulet Corporation, Tandem Diabetes Care, Eli Lilly and Company, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Insulin Delivery Devices Market Shifts & Advancements
Device architecture is converging around closed-loop ecosystems that merge continuous glucose monitoring with automated insulin modulation, compressing the traditional separation between sensing and delivery functions into single-platform therapeutic management.
Closed-loop artificial pancreas systems are hybridizing discrete hardware categories into unified therapeutic platforms. Pediatric endocrinology centers in São Paulo are piloting these integrated systems at accelerated rates compared to adult populations. This convergence is compressing standalone pump and continuous monitor markets into subscription-based ecosystem contracts with recurring software and sensor revenue components.
ANVISA's updated Good Manufacturing Practice requirements for sterile fluid pathway validation are extending product registration review cycles for imported devices. Domestic manufacturers with established quality management systems are capturing accelerated approval pathways. Smart pen and pump categories face disproportionate compliance burden increases relative to conventional syringe segments.
Patient self-administration preferences are displacing hospital-centric procurement as the dominant demand signal. Home care settings in Mexico City and Buenos Aires are negotiating direct purchasing arrangements with manufacturers, bypassing traditional distributor markups. This channel disintermediation is most visible among privately insured Type 1 diabetes populations with established digital literacy profiles.
Latin America Insulin Delivery Devices Market Segmentation
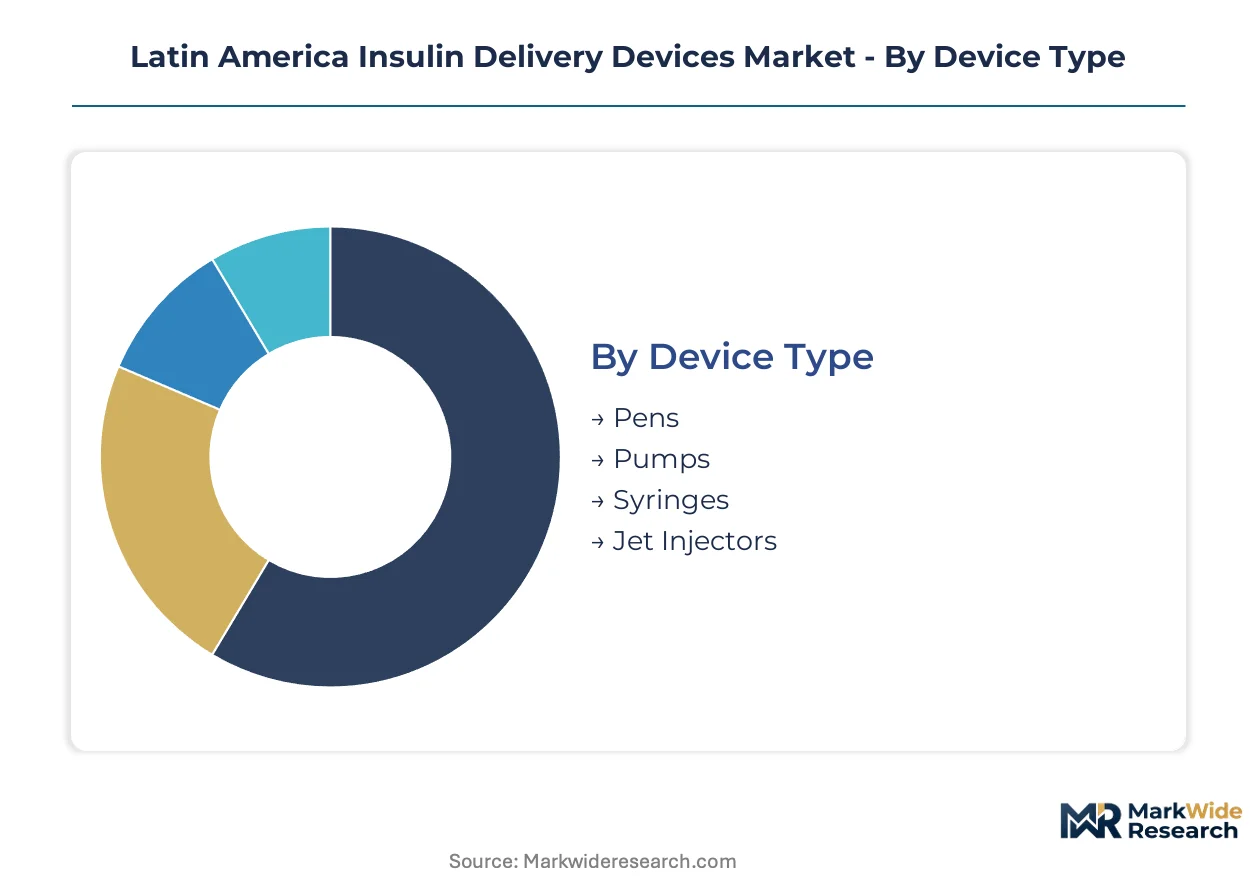
Segmentation in Latin America insulin delivery devices determines service revenue models and regulatory compliance pathways. Device architecture, care setting, and connectivity level each create distinct margin profiles and aftermarket attachment rates across Brazilian, Mexican, and Argentine markets.
Device Type:
After-sales service intensity varies sharply across device categories, with sensor-integrated platforms generating recurring calibration revenue while disposable segments rely on volume throughput.
- Pens:Pre-filled and reusable pen systems incorporate precision dosing mechanisms with medical-grade polycarbonate barrels and stainless steel needles. Demand concentrates in Mexican ambulatory settings where public health decentralization programs favor simplified self-administration interfaces for Type 2 diabetes populations.
- Pumps:Motorized reservoir systems with subcutaneous infusion sets enable continuous basal delivery and bolus programming. São Paulo pediatric endocrinology centers drive adoption as ANVISA reimbursement pathways expand for closed-loop configurations integrated with continuous glucose monitors.
- Syringes:Conventional glass-barrel or plastic disposable systems with fixed or detachable needles serve price-sensitive public procurement channels.
- Jet Injectors:Needle-free pressure delivery systems using high-velocity liquid streams penetrate needle-phobic patient segments.
Pens holds the largest share; momentum sits with Pumps.
End User:
Procurement authority and reimbursement structure diverge across care settings, with institutional buyers negotiating volume contracts while home care channels capture direct-to-patient margin.
- Hospitals:Inpatient and outpatient departments with centralized pharmacy operations and endocrinology specialist oversight. Argentine public institutions in Buenos Aires face legacy system integration barriers for Bluetooth-enabled dose data transmission.
- Clinics:Specialized diabetes centers and primary care facilities with nurse educator staffing. Colombian underpenetrated markets in Bogotá create positioning opportunities for connected pen platforms with dose-tracking applications.
- Home Care:Patient-directed administration settings with family caregiver involvement.
- Diagnostic Centers:Facilities focused on glycemic monitoring and diabetes screening with limited therapeutic device dispensing.
Home Care is expanding most quickly; Hospitals retain the volume base.
Technology:
Connectivity tier determines regulatory burden and pricing power, with Bluetooth-enabled systems commanding premium positioning against commodity conventional alternatives.
- Smart Devices:Bluetooth-enabled pens and pumps with dose logging, clinician dashboard integration, and mobile application synchronization. Brazilian ANVISA post-market surveillance protocols compress registration timelines and elevate compliance costs for imported systems.
- Conventional Devices:Mechanical dosing systems without data connectivity or software components. Mexican NOM biocompatibility standards impose laboratory certification costs on regional distributors lacking in-house testing infrastructure.
- Wearable Devices:Patch pumps and adhesive delivery systems designed for body-worn continuous infusion.
- Disposable Devices:Single-use pre-filled systems with no maintenance or calibration requirements.
Conventional Devices dominates procurement volume; Smart Devices shows the steepest expansion trajectory.
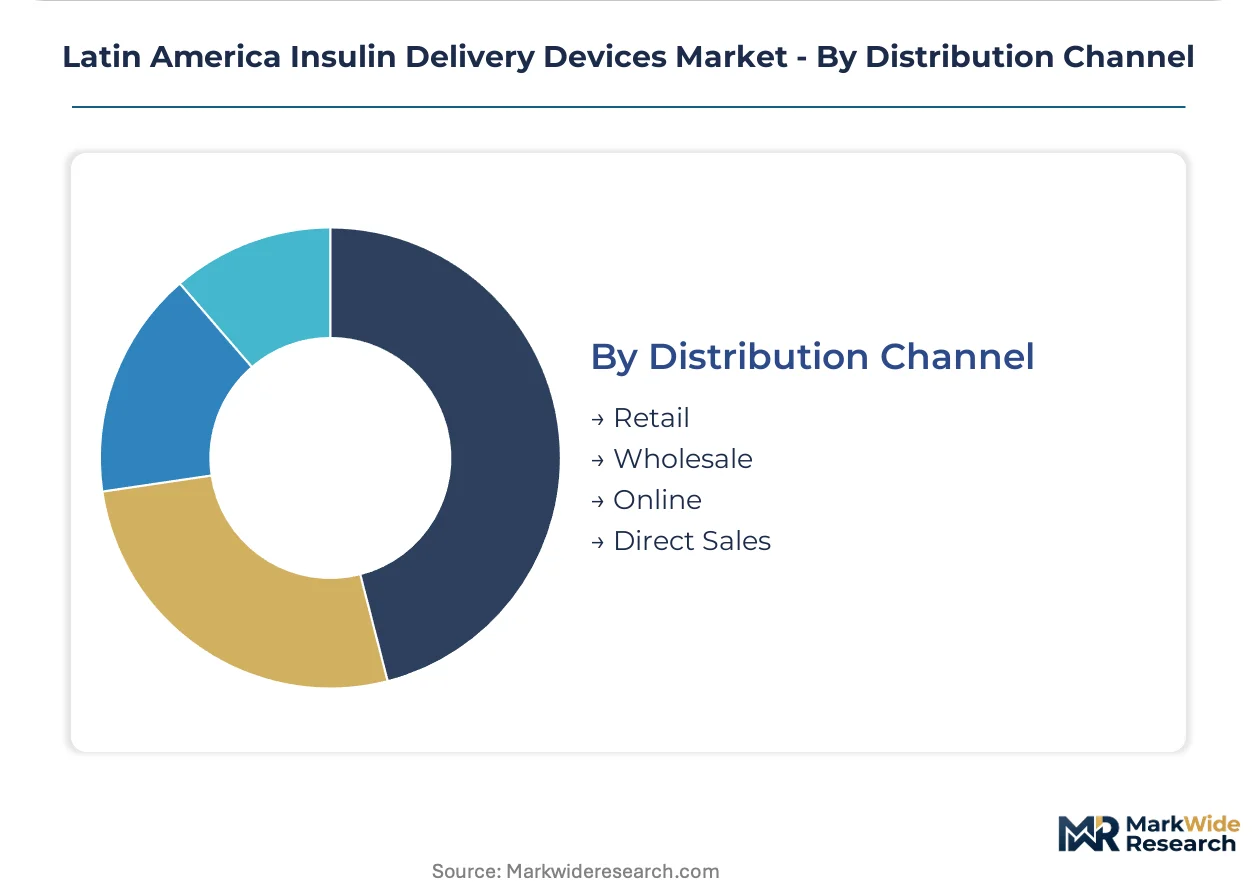
Distribution Channel:
Channel structure determines margin capture and patient access speed, with traditional wholesale-retail networks competing against emerging direct manufacturer relationships.
- Retail:Pharmacy chains and independent drugstores with counter-based dispensing and patient counseling. Mexico City and Buenos Aires home care settings increasingly negotiate direct purchasing arrangements, bypassing traditional distributor markups.
- Wholesale:Regional distributors with warehousing infrastructure and institutional salesforces serving hospital and clinic procurement departments.
- Online:E-commerce platforms and manufacturer-direct portals with home delivery logistics.
- Direct Sales:Manufacturer field forces engaging specialty endocrinology practices and diabetes education centers.
Retail holds the largest share; momentum sits with Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision dosing mechanism manufacturing concentrates in São Paulo industrial corridors and Mexico City medical device clusters, with Brazilian and Mexican facilities supplying syringe and pen needle components across the Southern Cone. Distribution networks radiate from these hubs into secondary metropolitan zones.
Brazil
São Paulo pediatric endocrinology centers drive closed-loop pump adoption as ANVISA reimbursement pathways expand. ANVISA enforces post-market surveillance and Good Manufacturing Practice compliance, extending registration review cycles for imported devices. Domestic manufacturers with established quality management systems in São Paulo industrial parks capture accelerated approval pathways for pen needle assembly operations.
Mexico
Mexico City home care settings negotiate direct purchasing arrangements with manufacturers, bypassing traditional distributor markups. COFEPRIS applies NOM standards for medical device biocompatibility and sterility assurance, imposing laboratory certification costs on regional distributors. Jalisco manufacturing corridors host high-volume syringe production serving public procurement channels across Central America.
Argentina
Buenos Aires private insurers expand prior authorization pathways for Bluetooth-enabled closed-loop systems among pediatric populations. The national pharmaceutical regulator maintains non-harmonized registration requirements that force redundant clinical documentation. Argentine public institutions face legacy system integration barriers for clinician dashboard deployment in metropolitan diabetes centers.
Colombia
Bogotá and Medellín present underpenetrated diabetes management infrastructure creating first-mover positioning for connected pen platforms. The national health regulator evaluates cost-effectiveness thresholds for continuous glucose monitor-integrated systems. Caribbean coastal clinics pull simplified dosing interfaces for Type 2 populations from emerging distribution partnerships.
Chile
Santiago private healthcare networks pilot sensor-pump convergence among intensive insulin therapy patients with established digital literacy. The national pharmaceutical regulator aligns with ISO 11608 needle-based injection system standards for design verification. Valparaíso medical device import corridors face currency fluctuation exposure from concentrated North American supply origins.
Latin America Insulin Delivery Devices Market Competitive Landscape
Sensor-integrated platform specialists and high-volume disposable manufacturers split the market into divergent margin architectures. The competitive structure concentrates around three strategic archetypes: multinational medtech conglomerates with recurring software revenue models, regional manufacturing specialists with tariff-advantaged production scale, and emerging connectivity players with direct-to-patient digital channels. Consolidation pressures favor backward integration into sterile component manufacturing and exclusive distribution partnerships with private insurer networks.
Within the multinational medtech tier, Medtronic and Novo Nordisk exemplify divergent ecosystem strategies. Medtronic anchors its position through sensor-integrated pump platforms that generate recurring calibration and software update income streams. Novo Nordisk occupies a position through pre-filled pen dominance and direct-to-patient digital coaching programs that bypass traditional hospital procurement intermediaries. Becton Dickinson and Company represents the high-volume manufacturing archetype with production scale across multiple Latin American sites serving commodity syringe and pen needle segments.
| Leading Market Players |
|---|
| Medtronic |
| Becton Dickinson and Company |
| Novo Nordisk |
| Embecta Corp. |
| Ypsomed |
| Sanofi |
| Insulet Corporation |
| Tandem Diabetes Care |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Single-source dependency on North American and European precision dosing mechanism manufacturers compresses pricing tier spreads while extending lead times for Brazilian and Mexican assembly operations. ANVISA's post-market surveillance protocols elevate compliance costs for imported smart devices, forcing domestic production partnerships that reshape supply chain geometry and pricing power distribution across the region.
Pricing Analysis
ANVISA's Good Manufacturing Practice requirements dictate the pricing tier structure across the Latin America insulin delivery devices market. Three-tier pricing stratifies across premium sensor-integrated pump systems, standard pre-filled pen platforms, and economy syringe segments serving public procurement channels. Price differentiation hinges on certification grade under ISO 11608 standards and after-sales service bundling for calibration-dependent devices. Cost compression in the conventional syringe tier intensifies because oral GLP-1 receptor agonists capture select Type 2 diabetes segments. Public procurement channels in Mexico and Brazil exhibit the highest price sensitivity, while privately insured pediatric populations in São Paulo demonstrate the lowest.
Supply Chain Analysis
Tariff exposure between North American component suppliers and Brazilian assembly operations dominates supply chain risk calculations for multinational manufacturers. Precision dosing mechanism production concentrates in the United States, Germany, and Switzerland, with medical-grade polycarbonate and stainless steel cannulae drawing from specialized polymer and metallurgical suppliers. Single-source vulnerability persists for Bluetooth-enabled sensor modules tethered to concentrated semiconductor fabrication. Distribution runs through São Paulo and Mexico City medical device clusters, with secondary metropolitan zones in Buenos Aires, Bogotá, and Santiago served through regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America insulin delivery devices market rewards specialized calibration expertise and regulatory navigation capabilities that remain scarce outside São Paulo and Mexico City metropolitan zones. Manufacturers and investors must anchor strategies around this capability concentration while monitoring substitution threats from oral glucose-lowering therapies.
For Market Incumbents: Harden market position through backward integration into sterile pen needle component manufacturing within Brazilian industrial parks, capturing accelerated ANVISA approval pathways and reducing import tariff exposure. Deepen software companion development for clinician dashboard integration to defend against emerging connectivity players with direct-to-patient digital channels. Prioritize exclusive distribution partnerships with private insurer networks in Buenos Aires and Santiago to lock in closed-loop system reimbursement pathways before regulatory harmonization pressures intensify. For New Entrants and Emerging Players: Underpenetrated diabetes management infrastructure in Colombian metropolitan zones represents the most penetrable entry point for connected pen platforms with integrated dose-tracking applications. Direct-to-patient digital coaching programs linked to device ecosystems offer a go-to-market angle that bypasses traditional hospital procurement intermediaries and captures margin previously allocated to institutional distribution channels. Target ambulatory settings in Mexican public health decentralization programs where simplified dosing interfaces for Type 2 populations face limited incumbent saturation. For Investors and Strategic Acquirers: The market sits at a reimbursement expansion phase that favors sensor-pump convergence specialists with established software revenue models and regulatory clearance momentum. Long-term viability across the projection horizon depends on capturing recurring calibration and subscription income rather than transactional device sales. Watch for health technology assessment body decisions in São Paulo, Mexico City, and Buenos Aires regarding continuous glucose monitor-integrated pump system cost-effectiveness thresholds as the primary inflection indicator for ecosystem adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Securing ANVISA and COFEPRIS coverage pathways for closed-loop systems determines pediatric and intensive therapy market access. |
| Software Companion Development | Bluetooth-enabled dose logging and clinician dashboard integration command premium positioning against conventional mechanical alternatives. |
| Local Production Incentives | Brazilian industrial policy frameworks attract pen needle assembly operations, reducing import tariff exposure and compressing registration timelines. |
| Hospital System Partnership | Direct purchasing arrangements with Mexico City and Buenos Aires home care settings bypass traditional distributor markups. |
| CE Marking Pathway | EU MDR equivalency protocols influence design verification standards for multinational manufacturers serving Latin American markets. |
Research Methodology
The analysis maps insulin delivery device categories including pens, pumps, syringes, and jet injectors, each validated through endocrinologists, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Primary interviews with device manufacturers, regional distributors, and private insurer formulary directors combined with secondary validation against ANVISA registration databases, COFEPRIS NOM standards documentation, ISO 11608 technical specifications, and hospital procurement records. Bottom-up demand modeling across device type, technology tier, and care setting segments triangulated with top-down market sizing from trade flow analysis.
Forecast assumptions held regulatory approval timelines and reimbursement classification frameworks fixed while varying sensor-pump convergence adoption curves and oral GLP-1 substitution pressure intensity across the analysis window. Segmentation dimensions modeled include device architecture, connectivity level, end-user care setting, and distribution channel structure. CAGRs derived from patient population growth projections, therapy intensity shifts, and pricing trajectory analysis for smart versus conventional device categories. Industry-specific inputs incorporated ANVISA post-market surveillance protocol evolution and Mexican public health decentralization program implementation pace.
Practitioners should monitor regulatory harmonization progress across ANVISA, COFEPRIS, and Argentina's national pharmaceutical regulator for early signals of accelerated product launch timelines or elevated compliance burdens. Forecasts reflect assumptions regarding sustained reimbursement expansion for continuous glucose monitor-integrated systems and stable currency conditions for import-dependent supply chains. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Brachytherapy Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Global Robotic Nurse Assistant Market
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Manual Resuscitators Market
Medical Devices
Non-Invasive Brain Stimulation System Market
Medical Devices
Rectal Catheters Market