
 Pleural Catheters Market | 2026-2036
Pleural Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Pleural Catheters Market Outlook
Consolidation among hospital procurement networks is realigning how pleural catheter vendors secure long-term supply agreements. Smiths Medical leverages its integrated manufacturing footprint to sustain direct hospital contracts across North America. Teleflex Incorporated anchors its position through specialized interventional pulmonology portfolios that dominate teaching hospital purchasing committees.
Pleural catheters are flexible drainage tubes inserted into the pleural space to evacuate air, fluid, or blood, typically constructed from silicone or polyurethane with multiple side holes and radiopaque markers for placement verification; they serve as essential devices in managing pneumothorax, malignant effusions, and postoperative drainage. Small bore catheters lead volume due to their compatibility with ultrasound-guided insertion protocols that reduce iatrogenic complications, while tunneled systems command premium positioning through extended indwelling durations that shift care toward home settings. The delivery mode dimension shows ultrasound-guided placement growing fastest as point-of-care imaging becomes standard in emergency departments and ambulatory surgical centers.
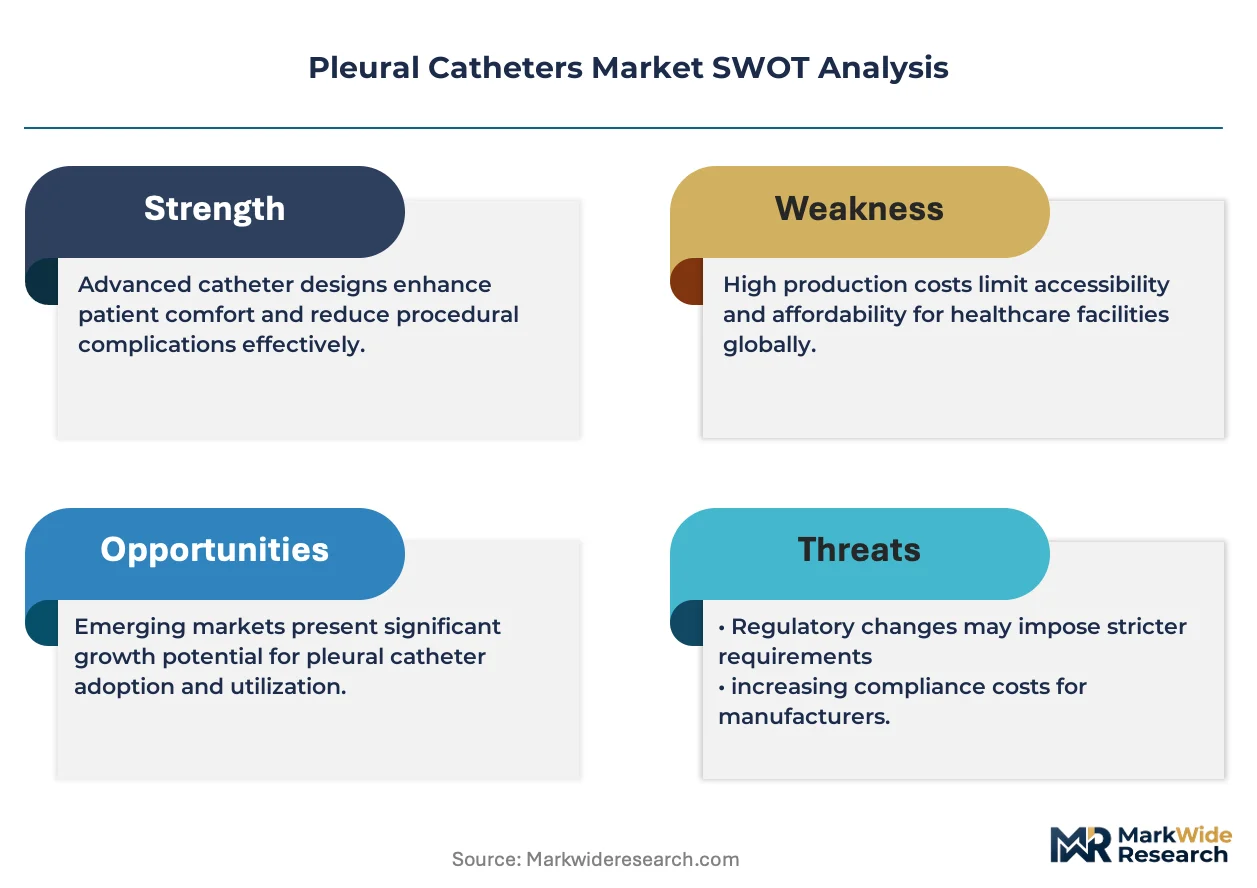
The FDA's Class II medical device framework governs 510(k) clearance pathways for pleural catheters, while ISO 13485 quality management standards shape supplier audit requirements across OEM partnerships. BIS certification in India and CE marking under the EU MDR create parallel compliance tracks for manufacturers seeking multi-regional distribution. Stakeholders must monitor how evolving sterile barrier requirements and single-use device mandates reshape material selection and packaging economics across their supplier base.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while simultaneously raising barriers to entry for pleural catheter manufacturers seeking long-term supply contracts with integrated delivery networks.
Growth Catalysts
- EU MDR implementation:Stricter CE marking requirements under the Medical Device Regulation are filtering out subscale competitors and concentrating market share among quality-certified manufacturers.
- Ambulatory surgical centers:These facilities are expanding interventional pulmonology services and driving demand for small-bore catheters compatible with ultrasound-guided protocols.
- Silicone material advances:Improved biocompatibility and kink-resistance in silicone formulations are extending indwelling durations and enabling home-based drainage management.
Market Restraints
- Medical-grade silicone supply:Concentrated sourcing from specialty chemical suppliers creates input cost volatility and single-source vulnerability for catheter manufacturers.
- FDA 510(k) pathway complexity:Tightened premarket notification requirements for Class II thoracic drainage devices are extending regulatory timelines and raising compliance costs.
- Peritoneal dialysis catheters:These devices serve overlapping drainage applications in certain malignant effusion cases, creating substitution pressure at price-sensitive hospital accounts.
Strategic Opportunities
- Home healthcare transition:Tunneled pleural catheter systems enable extended outpatient management, opening reimbursement pathways in United States Medicare Advantage plans.
- India BIS certification expansion:Domestic manufacturing incentives and streamlined medical device registration create low-cost production bases for export-oriented suppliers.
- Ultrasound-integrated placement kits:Convergence of point-of-care imaging with single-use catheter delivery systems reduces training barriers and procedural complication rates.
Industry Challenges
- Interventional pulmonology training pipelines:Shortage of specialists proficient in ultrasound-guided thoracentesis limits adoption velocity at community hospitals.
- Sterile barrier validation:Evolving ISO 11607 requirements for packaging integrity demand capital-intensive testing infrastructure that strains mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pleural Catheters Market |
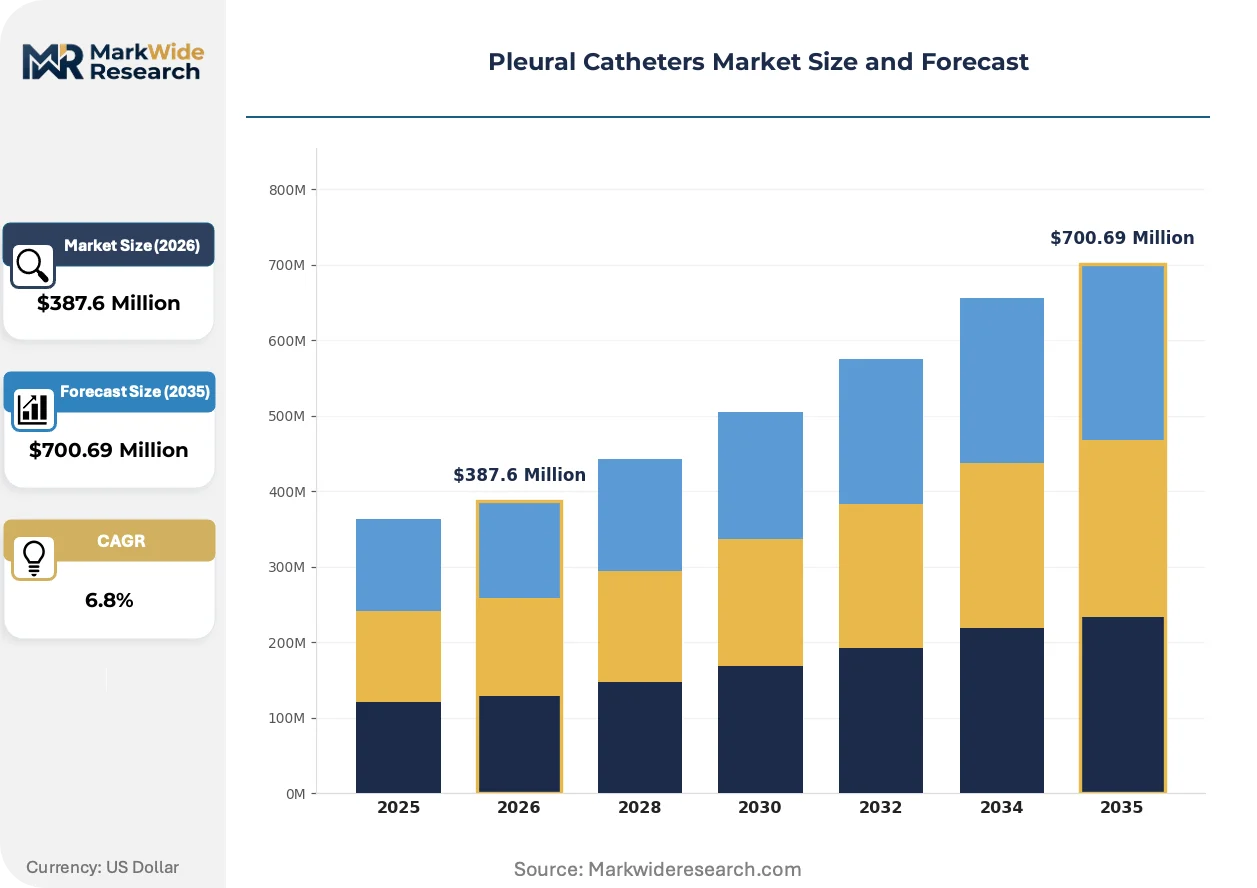
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Bore, Large Bore, Tunneled, Non-Tunneled Application: Pneumothorax, Pleural Effusion, Thoracentesis, Chest Tube Removal End User: Hospitals, Ambulatory Surgical Centers, Home Care, Clinics Delivery Mode: Surgical, Ultrasound-Guided, CT-Guided, Manual Insertion |
| Companies Covered | Smiths Medical, Rocket Medical, Teleflex Incorporated, Argon Medical Devices, REDAX, Becton, Dickinson and Company, B. Braun Melsungen AG, ICU Medical, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pleural Catheters Market Strategic Shifts
Active material science development and procedural technique standardization are converging to redefine performance benchmarks across pleural drainage systems.
Antimicrobial-impregnated catheter surfaces are absorbing sustained investment from manufacturers seeking to differentiate on infection prevention metrics. Teaching hospitals and tertiary care centers are piloting these coated devices in high-risk malignant effusion cases. The technology is absorbing premium pricing power that was previously concentrated in tunneled system categories.
REACH restrictions on certain phthalate plasticizers are compelling polyurethane formulation changes across European supply chains. Manufacturers serving EU markets must reformulate catheter materials or source compliant alternatives, raising production complexity. Small-bore catheter segments face the steepest reformulation costs due to thinner wall specifications and flexibility requirements.
Direct contracting between catheter vendors and ambulatory surgical centers is displacing traditional distributor intermediaries in United States metropolitan markets. These facilities demand consolidated supply agreements spanning multiple drainage product lines. The pattern is most visible in Texas and Florida, where ASC networks have achieved sufficient scale to negotiate manufacturer-direct pricing.
Pleural Catheters Market Segmentation
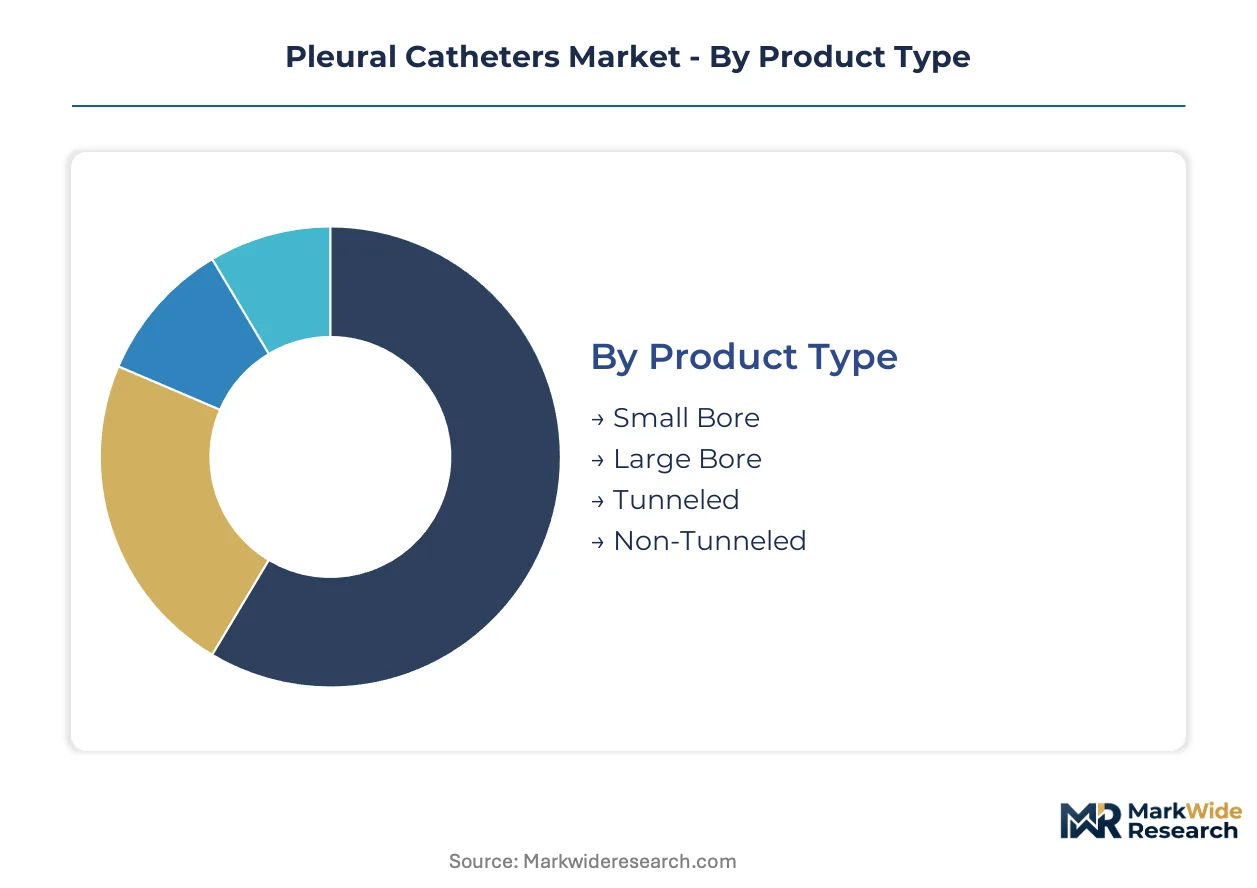
Pleural catheter purchasing decisions fragment across procedural setting, patient acuity, and reimbursement pathway. Manufacturers must align product portfolios with distinct clinical workflows rather than pursuing undifferentiated distribution.
Product Type:
Standardization dominates high-volume acute care lines while customization governs extended-dwelling and specialty configurations.
- Small Bore:Silicone or polyurethane tubes under 14 French diameter enable ultrasound-guided placement with reduced tissue trauma. Demand concentrates in United States ambulatory surgical centers where interventional pulmonologists perform same-day thoracentesis procedures.
- Tunneled:Subcutaneously anchored catheters with Dacron cuffs permit weeks-long indwelling periods for malignant effusion management. Home healthcare agencies in Medicare Advantage networks drive procurement volume for outpatient drainage protocols.
- Large Bore:Rigid drainage tubes exceeding 20 French diameter address hemothorax and postoperative air leaks requiring high-volume evacuation.
- Non-Tunneled:Percutaneous insertion devices for short-term drainage in emergency department pneumothorax cases.
Leading the category by volume: Small Bore. Growing fastest: Tunneled.
Application:
Reimbursement intensity and procedure complexity create tiered margin profiles across clinical indications.
- Pleural Effusion:Transudative and exudative fluid accumulation drives the highest catheter consumption volume globally. United States hospital procurement networks consolidate contracts around effusion drainage systems that span diagnostic and therapeutic applications.
- Pneumothorax:Air evacuation procedures command premium pricing in trauma and iatrogenic complication settings. European emergency departments favor small-bore systems compatible with rapid bedside insertion protocols.
- Thoracentesis:Diagnostic fluid sampling creates demand for catheters with integrated one-way valves and collection chambers.
- Chest Tube Removal:Specialized occlusion devices and gradual weaning accessories support postoperative recovery pathways.
Dominant by procedure frequency: Pleural Effusion. Steepest expansion trajectory: Pneumothorax.
End User:
Site-of-care migration from inpatient to outpatient settings reshapes packaging, training support, and pricing structures.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements spanning emergency, surgical, and critical care departments. FDA 510(k) clearance status and ISO 13485 certification serve as mandatory qualification thresholds for vendor selection.
- Ambulatory Surgical Centers:These facilities demand compact procedure kits with integrated ultrasound compatibility and single-use sterile barriers. Direct manufacturer contracting is displacing traditional distributor relationships in Texas and Florida metropolitan markets.
- Home Care:Extended-dwelling tunneled catheter systems require patient training infrastructure and 24/7 clinical support hotlines.
- Clinics:Community-based pulmonary practices source small-bore devices for outpatient thoracentesis with local anesthesia.
Highest absolute consumption: Hospitals. Most rapid volume shift: Ambulatory Surgical Centers.
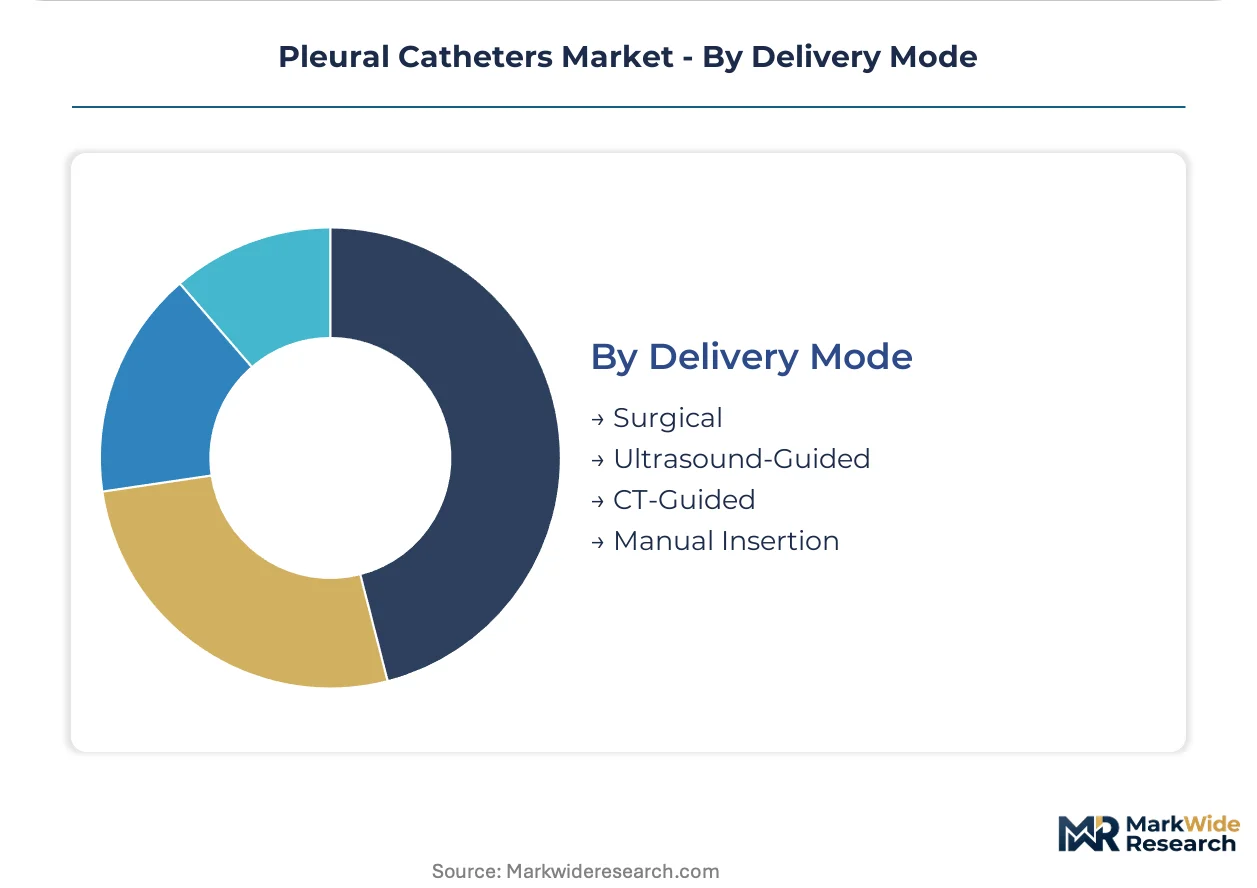
Delivery Mode:
Imaging integration intensity separates premium positioning from commodity supply tiers.
- Ultrasound-Guided:Real-time visualization protocols reduce pneumothorax and vascular puncture complications. Point-of-care ultrasound adoption in United States emergency departments and ASCs accelerates demand for compatible catheter insertion kits.
- Surgical:Open thoracotomy placement persists in trauma centers and cardiothoracic services requiring large-bore drainage.
- CT-Guided:Computed tomography navigation serves loculated effusions and complex pleural anatomies in tertiary referral centers.
- Manual Insertion:Landmark-based placement without imaging guidance remains confined to resource-limited settings and emergency rescue scenarios.
Widest installed base: Surgical. Fastest protocol adoption: Ultrasound-Guided.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital procurement networks concentrate demand for pleural drainage systems, with ambulatory surgical centers in Texas and Florida accelerating volume shifts toward outpatient settings. Medicare Advantage reimbursement pathways for tunneled catheter home management reinforce this geographic concentration.
United States
Ambulatory surgical centers in Houston, Dallas, and Miami metropolitan areas are expanding interventional pulmonology services and demanding ultrasound-compatible catheter kits. FDA's tightened 510(k) premarket notification requirements for Class II thoracic drainage devices filter vendor qualification. Smiths Medical maintains direct hospital contracts across North America through integrated manufacturing infrastructure.
Germany
Tertiary care centers in Berlin and Munich pilot antimicrobial-impregnated catheter surfaces for high-risk malignant effusion cases. REACH restrictions on phthalate plasticizers compel polyurethane formulation changes across domestic supply chains. Baden-Württemberg's medical technology cluster houses specialized thoracic drainage device engineering capabilities serving EU markets.
India
Domestic manufacturing incentives under the PLI scheme attract catheter producers seeking low-cost export bases for silicone and polyurethane devices. BIS certification requirements streamline medical device registration while raising quality barriers. Gujarat's pharmaceutical and medical device manufacturing corridor hosts emerging suppliers targeting Middle East and African distribution.
Japan
Aging demographics and rising malignant pleural effusion incidence drive catheter consumption in Tokyo and Osaka metropolitan hospital networks. PMDA regulatory pathways emphasize post-market surveillance for extended-dwelling tunneled systems. Kansai region's precision polymer processing industry supplies high-grade silicone materials for domestic catheter manufacturers.
United Kingdom
NHS procurement consolidation favors vendors with ISO 13485 certification and multi-product drainage portfolios. Teaching hospitals in London and Manchester evaluate ultrasound-integrated placement kits to reduce iatrogenic complication rates. Midlands manufacturing bases supply standard catheter configurations for national tender contracts.
Pleural Catheters Market Competitive Environment
United States producers anchor one tier; European specialists hold differentiated positioning through regulatory-certified manufacturing. Hospital procurement consolidation compresses margins while raising qualification barriers for integrated delivery network contracts. Three archetypes dominate: diversified medical device conglomerates with thoracic portfolios, interventional pulmonology-focused specialists, and regional manufacturers leveraging domestic certification advantages. Competitive moves center on direct ASC contracting displacement of distributors and antimicrobial surface technology licensing.
Within the diversified conglomerate tier, Smiths Medical and Teleflex Incorporated exemplify scale-driven positioning across North American hospital networks. Becton, Dickinson and Company occupies a position bridging acute care and ambulatory settings through multi-line supply agreements. These three entities represent how integrated manufacturing footprints and regulatory certification depth translate into procurement committee influence.
| Leading Market Players |
|---|
| Smiths Medical |
| Rocket Medical |
| Teleflex Incorporated |
| Argon Medical Devices |
| REDAX |
| Becton, Dickinson and Company |
| B. Braun Melsungen AG |
| ICU Medical |
| Cook Medical |
| Others |
Value Chain & Pricing Dynamics
Medical-grade silicone price indices cascade through pleural catheter manufacturing tiers, compressing margins on standard small-bore lines while preserving premium positioning for tunneled systems with extended-dwelling protocols. Procurement consolidation among United States integrated delivery networks amplifies this bifurcation, as hospital committees leverage volume scale to extract concessions on commodity configurations while accepting elevated pricing for home-care-compatible platforms.
Pricing Analysis
Volume-margin splits separate high-turnover small-bore catheters from premium tunneled systems. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, ISO 13485 certification depth, and bundled training support. Pricing pressure stems from GPO-negotiated multi-year supply agreements that commoditize standard configurations. Ambulatory surgical centers exhibit highest price sensitivity due to direct manufacturer contracting displacement of distributor markups.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing strategies for export-oriented manufacturers seeking BIS-certified production bases. Medical-grade silicone feedstock draws from Japan's Kansai polymer processors and German specialty chemical suppliers, while finished device assembly concentrates in India, Malaysia, and Costa Rica. Single-source vulnerability pervades silicone precursor supply. Distribution runs through integrated delivery network direct contracts and ambulatory surgical center consolidated procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum intensifies as manufacturers pursue captive control over medical-grade silicone compounding to defend margin structures against raw material volatility. Backward integration into polymer processing represents the decisive upstream lever separating sustainable competitors from margin-compressed assemblers.
For Market Incumbents: Anchor market position through ISO 11607 sterile barrier validation infrastructure that mid-tier competitors cannot replicate. Deepen direct contracting relationships with Texas and Florida ambulatory surgical center networks before regional scale enables distributor displacement. Peritoneal dialysis catheter substitution threats demand defensive R&D investment in tunneled system differentiation. For New Entrants and Emerging Players: E-commerce-enabled direct procurement platforms offer lowest-friction entry into price-sensitive clinic segments underserved by incumbent field sales organizations. Target India's Gujarat manufacturing corridor for BIS-certified export production serving Middle East and African distribution. Ultrasound-integrated placement kits represent the most penetrable white-space configuration for technology-focused entrants. For Investors and Strategic Acquirers: The window for entry favors antimicrobial surface technology licensors with patent-protected coating platforms and established teaching hospital validation. Long-term viability hinges on reimbursement pathway capture within Medicare Advantage home-care frameworks. Monitor FDA 510(k) clearance velocity for tunneled systems as inflection indicator for competitive positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Surface Licensing | Teaching hospital pilot programs validate infection prevention metrics that command premium pricing power. |
| CE Marking Pathway Investment | EU MDR compliance filters subscale competitors and concentrates share among quality-certified manufacturers. |
| Hospital System Partnership | Direct ASC contracting in Texas and Florida displaces distributor intermediaries and secures volume commitments. |
| Reimbursement Strategy Development | Medicare Advantage home-care coding capture enables extended-dwelling tunneled system adoption. |
| Software Companion Development | Patient drainage tracking applications support home-care transition and reduce clinical support hotline burden. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this pleural catheter market assessment. Primary interviews with interventional pulmonologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with FDA 510(k) databases, EU MDR notified body submissions, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation validated segmentation outputs.
Data-stream reconciliation across shipment records, procurement database extracts, and clinical registry reports informed the analytical framework. Segmentation dimensions spanned product type, application indication, end-user facility class, delivery mode, and regional regulatory cluster. CAGRs derived from fitted trend extrapolation with elasticity adjustments for reimbursement pathway shifts. Silicone material cost trajectories and ambulatory surgical center expansion rates served as industry-specific forecast inputs across the projection horizon.
The model holds under stable FDA Class II device classification and continued Medicare Advantage home-care reimbursement; deviation in EU MDR enforcement intensity or medical-grade silicone supply disruption would shift volume and value trajectories. Forecasts reflect documented assumptions regarding procedural adoption curves and procurement consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Dual Chamber Prefilled Syringes Market
Medical Devices
Global Joint Replacement Device Market
Medical Devices
Carotid Stents Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
Self-Destructing Syringe Market
Medical Devices
Asthma Inhaler Device Market
Medical Devices
Power Smart Bed Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Human Enhancement Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Global Laparoscopy Devices Market
Medical Devices
Ventricle Assist Device Market