
 Blood Collection Vacuum Devices Market | 2026-2036
Blood Collection Vacuum Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Collection Vacuum Devices Market Intelligence
Subscription-based inventory management software integrated with device sales is broadening the value proposition beyond the physical product. Becton, Dickinson and Company leverages its extensive global distribution network to maintain market leadership. Greiner Bio-One International GmbH specializes in preanalytical systems for complex diagnostic workflows. Terumo Corporation differentiates through its expertise in proprietary needle designs and advanced material science, enhancing patient comfort and sample integrity.
Blood collection vacuum devices are sterile glass or plastic tubes containing a pre-set vacuum for drawing a predetermined volume of blood. This calibrated vacuum is critical for ensuring the correct blood-to-additive ratio for accurate downstream analysis. Vacuum tubes constitute the largest product segment, driven by high-volume use in diagnostic testing applications. The safety-enhanced technology segment shows the highest growth, propelled by global regulations aimed at preventing needlestick injuries in clinical settings.
Device approval and market access are governed by stringent regulatory frameworks, including the FDA's 510(k) clearance process in the United States and CE marking under the Medical Device Regulation (MDR) in Europe. International standards like ISO 6710 specify material and performance requirements for single-use venous blood specimen containers. The strategic selection between shatter-resistant PET for safety and inert glass for specific assays will continue to shape manufacturing and procurement decisions.
Market Dynamics
The structural shift toward safety-engineered devices, mandated by occupational health regulations in developed markets and mimicked by best-practice adoption in emerging ones, is the central force defining product development, procurement standards, and competitive differentiation in the market.
Growth Catalysts
- Chronic Disease Management:The rising global incidence of chronic conditions necessitates frequent diagnostic monitoring, directly increasing the volume of blood collection procedures performed in hospitals and standalone diagnostic centers.
- Infrastructure Expansion:Governments in countries like India and Brazil are investing heavily in national public health infrastructure, including the establishment of new diagnostic laboratories, which creates sustained demand for blood collection consumables.
- Regulatory Mandates:Worker safety regulations, such as OSHA's Bloodborne Pathogens standard in the US, compel healthcare facilities to adopt safety-enhanced devices, acting as a powerful, non-cyclical demand driver for premium products.
Market Restraints
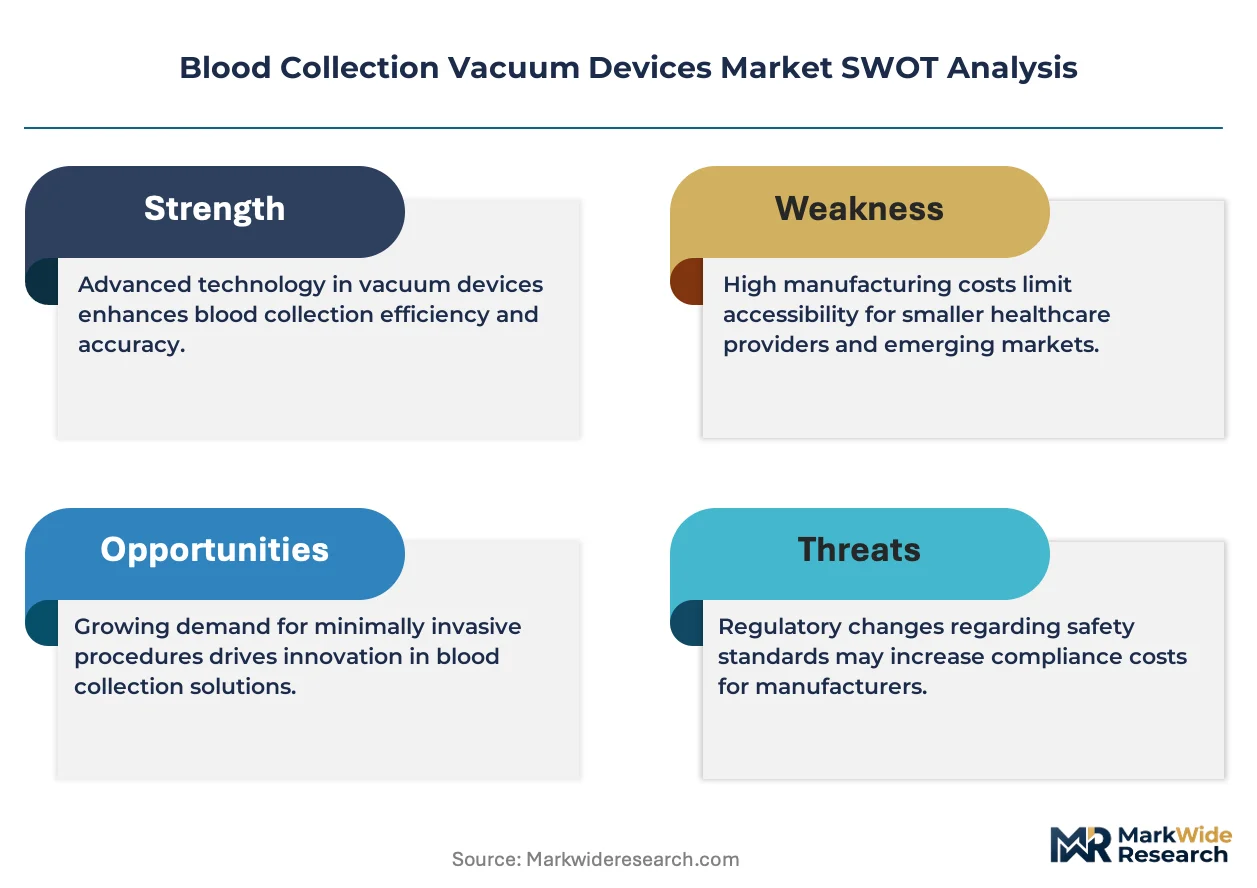
- Material Cost Volatility:Manufacturing costs are sensitive to price fluctuations in medical-grade polymers like PET, which can compress margins for device makers, particularly in the high-volume, price-sensitive standard tube segment.
- Glass-to-Plastic Conversion Barriers:Certain sensitive diagnostic assays still require the inert properties of glass tubes, creating a technical barrier to the complete market conversion to safer, shatter-resistant plastic alternatives.
- Sterilization Logistics:The requirement for validated sterilization processes, such as gamma or E-beam irradiation, adds significant cost, complexity, and logistical challenges to the supply chain, particularly for new entrants.
Strategic Opportunities
- Digital Integration:Embedding RFID tags or scannable codes on tubes to integrate with laboratory information systems and automated pre-analytical sorters presents a significant value-add opportunity beyond the physical device.
- Specialized Assay Tubes:Development of collection devices tailored for emerging fields like liquid biopsy, proteomics, and cell-free DNA analysis offers a pathway to high-margin, specialized product lines.
- Underpenetrated Markets:Expanding distribution and educational initiatives in regions across Africa and Southeast Asia, where diagnostic infrastructure is nascent, represents a long-term volume growth opportunity.
Industry Challenges
- Regulatory Compliance Burden:Navigating divergent and increasingly stringent regulatory pathways, such as the FDA's 510(k) process and the EU's MDR, requires substantial, ongoing investment in clinical data generation and quality management systems.
- Training and Adoption Friction:Ensuring correct usage of safety-engineered features by healthcare personnel requires continuous training to prevent activation errors, which can negate safety benefits or compromise sample quality.
- Supply Chain Resilience:Maintaining an uninterrupted supply of sterile, single-use devices on a global scale demands complex logistical networks that are vulnerable to disruption from geopolitical events or public health crises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Collection Vacuum Devices Market |
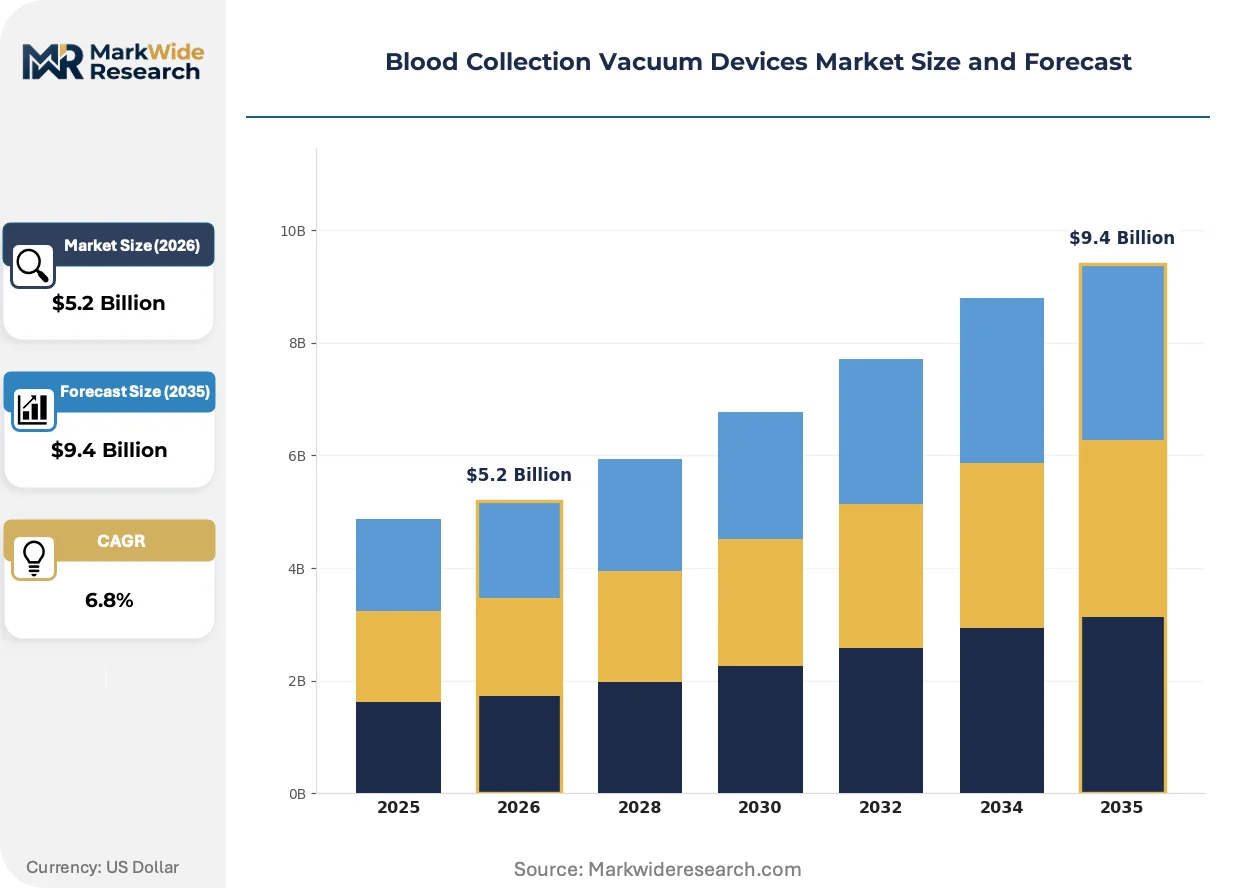
| Market Size in 2026 | $5.2 Billion |
| Market Size in 2035 | $9.4 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Tubes, Accessories, Needle Holders, Tube Holders Application: Diagnostic Testing, Clinical Research, Blood Banks, Therapeutic Drug Monitoring End User: Pathology Laboratories, Diagnostic Centers, Blood Donation Camps, Specialty Clinics Technology: Fully Automated, Semi-Automated, Manual, Safety Enhanced |
| Companies Covered | Becton, Dickinson and Company, Greiner Bio-One International GmbH, Cardinal Health, Terumo Corporation, Fresenius Kabi AG, SARSTEDT AG & Co. KG, Sekisui Chemical, Nipro Corporation, Vacutest Kima S.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Collection Vacuum Devices Market Strategic Shifts & Innovations
The market's evolution is being shaped by the convergence of material science, digital tracking, and pre-analytical automation. This integration aims to enhance sample integrity from the point of collection to analysis, while simultaneously improving clinician safety and workflow efficiency.
Micro-volume collection technology is gaining traction for pediatric and geriatric applications. These devices are designed to draw smaller, yet sufficient, quantities of blood, minimizing patient discomfort and iatrogenic anemia risk in vulnerable populations. Major diagnostic centers are adopting these specialized tubes for specific patient demographics, and this technology is automating the process of obtaining viable samples with minimal patient impact.
The European Union's Medical Device Regulation (MDR) imposes more rigorous requirements for clinical evidence and post-market surveillance. This policy shift elevates the cost and complexity of achieving and maintaining CE marking for all medical devices. The safety-enhanced product segment is particularly impacted, as manufacturers must now provide more extensive data to substantiate performance and safety claims for continued market access in Europe.
A notable shift in purchasing behavior involves large healthcare networks moving toward vendor-managed inventory programs. This model displaces traditional, transactional bulk ordering with a more integrated service that includes just-in-time delivery and stock monitoring via software. The trend is most pronounced in the United States and Western Europe, where hospital systems prioritize supply chain optimization and cost-of-ownership reduction over simple unit price.
Blood Collection Vacuum Devices Market Segmentation
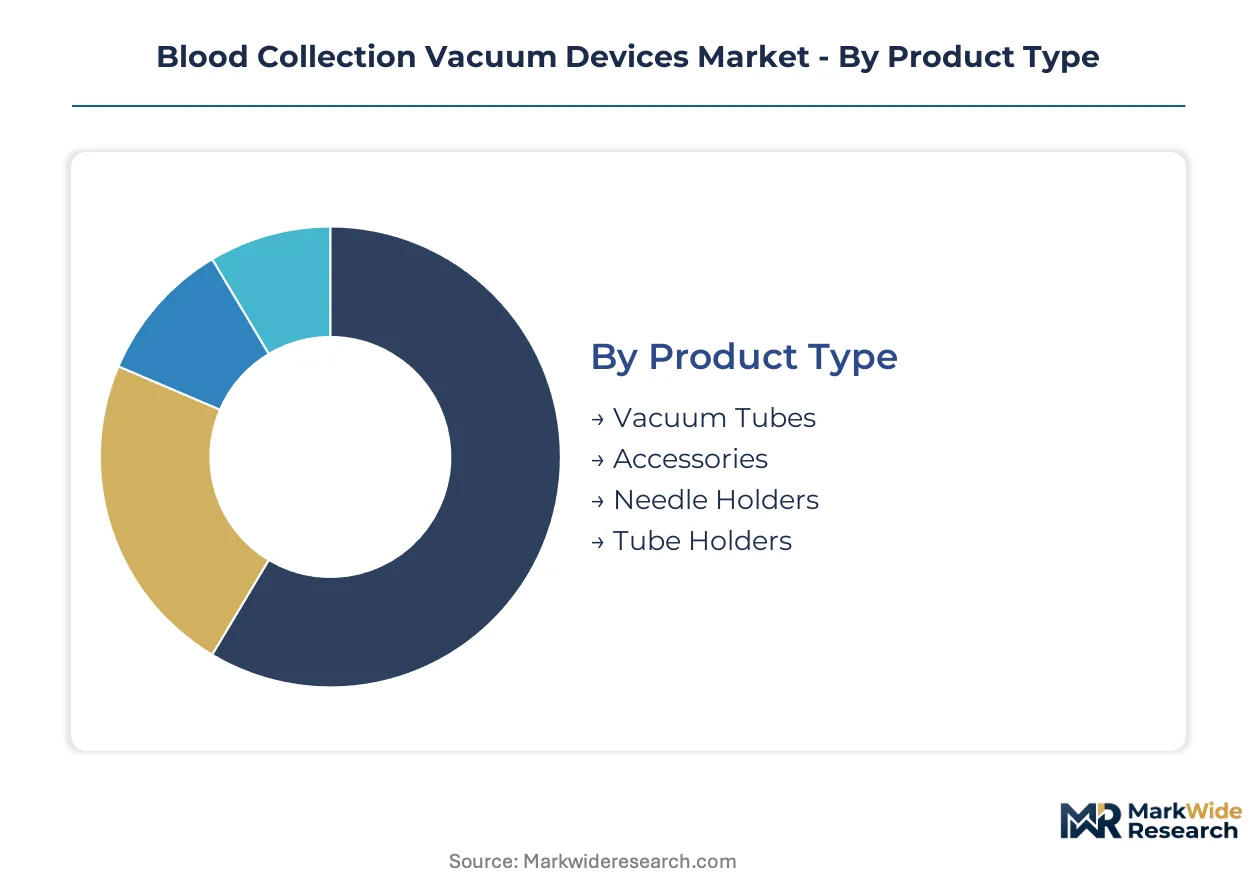
The Blood Collection Vacuum Devices market categorizes products and services to reflect distinct functional requirements and end-user needs. Understanding these segments helps manufacturers tailor offerings and allows healthcare providers to optimize procurement for specific clinical applications and operational workflows.
Product Type:
The market for blood collection devices stratifies by the volume of product consumed versus the specialized features that command premium pricing.
- Vacuum Tubes:These sterile glass or plastic tubes contain a pre-set vacuum, ensuring precise blood collection volumes and correct additive ratios for accurate diagnostic analysis. Demand for these tubes is consistently high in diagnostic centers globally for routine health screenings and chronic disease monitoring.
- Accessories:This segment includes a range of supplementary items like tourniquets, alcohol wipes, and gauze, essential for maintaining sterile collection procedures and ensuring patient comfort. Hospitals and clinics procure these items in conjunction with primary collection devices to complete phlebotomy kits.
- Needle Holders:Reusable or single-use devices, needle holders securely connect venipuncture needles to vacuum tubes, facilitating safe and efficient blood draw.
- Tube Holders:These devices provide a stable platform for holding multiple vacuum tubes during the collection process, improving workflow efficiency in busy phlebotomy stations.
Mature deployment sits with Vacuum Tubes. Newer deployment is concentrated in Accessories, reflecting a broader focus on comprehensive phlebotomy kits.
Application:
Market segmentation by application highlights the diverse clinical contexts where blood collection vacuum devices are indispensable.
- Diagnostic Testing:Devices used for a wide array of laboratory tests, including hematology, chemistry, and coagulation, form the core of this segment. The increasing global incidence of chronic diseases drives consistent demand for frequent diagnostic monitoring in this area.
- Clinical Research:Specialized tubes and collection systems are crucial for clinical trials and scientific studies, often requiring precise sample handling for novel biomarkers or genetic analyses. This application segment requires high-integrity samples for research outcomes.
- Blood Banks:These facilities utilize vacuum devices for collecting, processing, and storing blood for transfusions and other therapeutic uses.
- Therapeutic Drug Monitoring:Specific vacuum tubes with appropriate additives are used to measure drug levels in a patient's bloodstream, ensuring efficacy and preventing toxicity.
Diagnostic Testing represents the largest volume segment. Clinical Research shows a strong growth trajectory due to expanding pharmaceutical development.
End User:
The end-user segmentation illustrates the primary institutional purchasers and consumers of blood collection vacuum devices.
- Pathology Laboratories:These facilities conduct a vast range of diagnostic tests on blood samples, making them high-volume consumers of vacuum tubes and associated collection supplies. Their operations depend on reliable, standardized collection devices for accurate results.
- Diagnostic Centers:Standalone diagnostic centers, often offering routine health check-ups and specialized testing, constitute a significant end-user segment. Infrastructure expansion in countries like India and Brazil directly increases demand from these centers.
- Blood Donation Camps:Temporary or mobile blood collection sites rely on these devices for efficient and safe donor blood acquisition.
- Specialty Clinics:Focused medical practices, such as oncology or endocrinology clinics, use blood collection devices for disease-specific diagnostic and monitoring purposes.
Pathology Laboratories anchor the largest share of consumption. Diagnostic Centers are expanding their procurement patterns due to infrastructure investments.
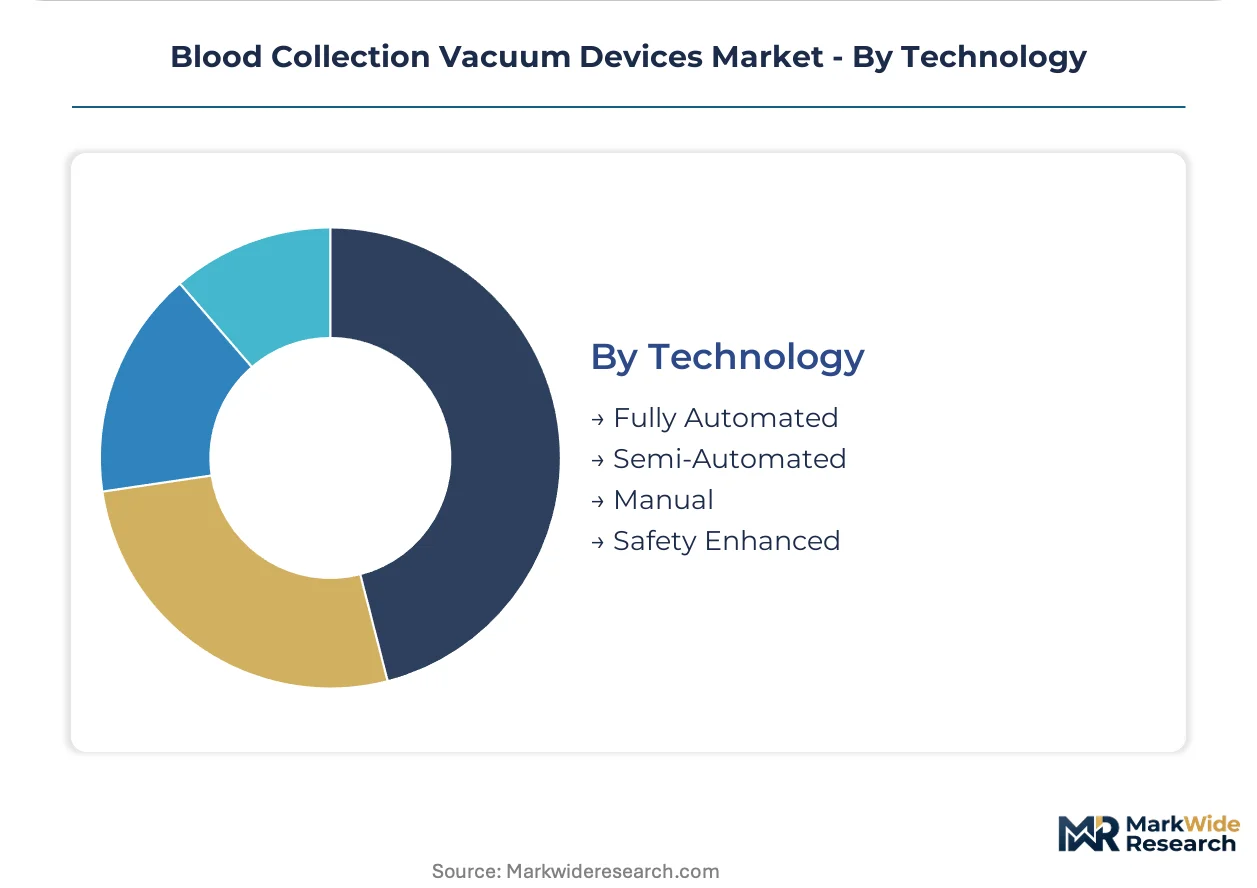
Technology:
Segmentation by technology reflects the evolving landscape of automation and safety features integrated into blood collection devices.
- Safety Enhanced:This category includes devices designed with features to prevent needlestick injuries and bloodborne pathogen exposure, such as retractable needles and shielded systems. Regulatory mandates like OSHA's Bloodborne Pathogens standard in the US compel healthcare facilities to adopt these premium products.
- Fully Automated:These systems integrate blood collection with automated processing, minimizing human intervention and improving workflow efficiency in high-throughput laboratories. Advanced diagnostic centers are increasingly adopting fully automated solutions to streamline operations.
- Semi-Automated:These devices combine manual steps with some automated features, offering a balance between cost and efficiency for various laboratory settings.
- Manual:Traditional collection methods, while still used in certain settings, require direct human handling throughout the entire phlebotomy process.
Safety Enhanced technology is gaining share fastest, driven by worker safety regulations. Fully Automated solutions are critical for maximizing throughput in large diagnostic networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of blood collection vacuum devices often centers in established manufacturing hubs, while consumption is rapidly expanding in developing healthcare markets. This dynamic creates distinct regional procurement and supply chain challenges. Global demand for these essential diagnostic tools continues to rise with chronic disease monitoring.
United States
Demand for advanced safety-enhanced blood collection devices is strong due to a mature healthcare system and high diagnostic testing volumes. OSHA's Bloodborne Pathogens standard mandates the use of safety features in clinical settings. Major diagnostic laboratories in states like California and New York consistently invest in high-throughput automated systems.
Germany
A robust healthcare infrastructure and a focus on precision diagnostics drive demand for high-quality preanalytical systems. CE marking under the Medical Device Regulation (MDR) sets stringent requirements for device approval and market access. Manufacturing clusters in regions like Baden-Württemberg specialize in medical technology innovation and export.
India
Infrastructure expansion and a rising burden of chronic diseases necessitate increased volumes of blood collection procedures. The national PLI scheme supports domestic manufacturing and healthcare infrastructure development. Metropolitan areas such as Mumbai and Delhi are seeing significant investment in new diagnostic centers.
Brazil
Government investments in public health and a growing population requiring diagnostic services fuel the demand for blood collection devices. ANVISA regulations govern the approval and distribution of medical devices within the country. Healthcare networks in São Paulo and Rio de Janeiro are expanding their procurement of essential medical consumables.
China
The vast patient base and expanding diagnostic testing capabilities contribute to substantial demand for blood collection devices. The NMPA regulates medical device registration and quality control within the Chinese market. Large-scale diagnostic facilities in the Yangtze River Delta actively integrate automated collection and processing solutions.
Blood Collection Vacuum Devices Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the blood collection vacuum devices market, which exhibits a tiered structure. This landscape includes global diversified medical device conglomerates alongside specialized preanalytical system providers. Strategic archetypes encompass large-scale manufacturers leveraging extensive global distribution and niche players focusing on advanced material science and digital integration. Companies actively pursue portfolio diversification and geographic expansion to maintain and grow market share amidst evolving regulatory demands.
Global medical technology leaders, such as Becton, Dickinson and Company, leverage their extensive distribution networks and broad product portfolios to maintain significant market presence across various segments. German-based Greiner Bio-One International GmbH exemplifies specialization as a key archetype, focusing on comprehensive preanalytical systems for complex diagnostic workflows. Japanese-headquartered Terumo Corporation occupies a position focused on proprietary needle designs and advanced material science, differentiating its offerings by enhancing patient comfort and ensuring sample integrity. These players represent distinct strategies in a competitive landscape.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Greiner Bio-One International GmbH |
| Cardinal Health |
| Terumo Corporation |
| Fresenius Kabi AG |
| SARSTEDT AG & Co. KG |
| Sekisui Chemical |
| Nipro Corporation |
| Vacutest Kima S.r.l. |
| Others |
Cost & Logistics Intelligence
Vertical integration into specialized material science anchors the supply position for premium blood collection devices, influencing pricing power through proprietary technology and enhanced product features.
Pricing Analysis
Cost compression in the high-volume standard tube segment intensifies due to aggregated purchasing power from large diagnostic networks. The market employs a hybrid pricing model, combining per-unit transactional sales for basic vacuum tubes with subscription-based software for inventory management. Price differentiation stems from safety-enhanced features for worker protection and specialized material science, such as inert glass for sensitive assays. Large diagnostic centers exhibit high price sensitivity for routine consumables, while specialty clinics prioritize performance for niche applications.
Supply Chain Analysis
Dual-sourcing requirements for critical components enhance supply chain resilience, particularly for medical-grade polymers and specialized additives. Production concentrates in established manufacturing hubs like Germany and the United States, with increasing output from China. The industry relies on medical-grade PET plastic, inert glass, and specific chemical additives for anticoagulant formulations. Material cost volatility for polymers poses a significant structural risk. Distribution runs through global medical distributors and direct sales to large healthcare networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood collection vacuum devices market is in a technology-transition phase, with safety-enhanced devices displacing traditional manual collection methods. This shift redefines product development and procurement standards across healthcare systems.
For Market Incumbents: Anticipate continued regulatory pressure from the EU's MDR and OSHA standards by proactive investment in safety-enhanced product lines. Deepen vertical integration into specialized material science to control critical inputs and maintain differentiation. Expand digital integration with laboratory information systems, offering value-added services beyond physical products. Becton, Dickinson and Company leverages its extensive global distribution network for market leadership.
For New Entrants and Emerging Players: Group purchasing organizations offer a critical channel for market entry, particularly for innovative, cost-effective solutions. White-space opportunities exist in specialized assay tubes for emerging fields like liquid biopsy and proteomics. Target underpenetrated markets in Africa and Southeast Asia, where diagnostic infrastructure is nascent. A go-to-market angle should emphasize superior sample integrity for novel biomarker analysis.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized medical technology firms offering unique preanalytical solutions or advanced material science. The market demonstrates long-term viability over a 5-10 year window, driven by chronic disease management and stringent safety regulations. Target acquisition archetypes include niche players in micro-volume collection technology or digital integration for laboratory information systems. Watch for increased adoption of vendor-managed inventory programs as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Integration with LIS | Enhances workflow efficiency and data accuracy for diagnostic centers. |
| CE Marking Pathway Acceleration | Ensures market access in Europe under the rigorous Medical Device Regulation. |
| Micro-volume Collection R&D | Addresses patient comfort and iatrogenic anemia risk in vulnerable populations. |
| Hospital System Partnership | Secures large-volume procurement contracts and optimizes supply chain for healthcare networks. |
| Advanced Material Science Investment | Improves sample integrity and patient safety through proprietary needle designs. |
Research Approach
FDA 510(k) clearances, CE marking databases, and ISO 6710 standards formed the secondary backbone for this analysis. This was complemented by primary interviews with diagnostic center procurement managers, phlebotomy specialists, medical device engineers, and regulatory affairs leads. A robust bottom-up and top-down triangulation approach ensured data validity, integrating insights from both supply and demand sides of the market.
Historical trendline analysis established foundational growth parameters across the analysis window. The analytical framework modeled market dynamics across product type, application, end-user, technology, and regional healthcare spending. Compound Annual Growth Rates were derived from historical growth patterns. Forecast inputs included chronic disease incidence rates and national diagnostic infrastructure investments.
Caveats apply where geopolitical events or public health crises could materially shift the outlook. Forecasts reflect assumptions regarding regulatory stability and raw material supply chain resilience. Deviation in these factors would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Minimally Invasive Deformity Correction System Market
Medical Devices
Wireless Handheld Ultrasound Devices Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
Mucus Clearance Devices Market
Medical Devices
Artificial Respirator Market
Medical Devices
Global Trauma Devices Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Flexible Spinal Implants Market
Medical Devices
Trocars Market
Medical Devices
IV Equipment Market
Medical Devices
ADA Substitute Market
Medical Devices
Non-Rebreathing Oxygen Mask Market