
 Endoscopic Retrograde Cholangiopancreatography/ERCP Market | 2026-2036
Endoscopic Retrograde Cholangiopancreatography/ERCP Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopic Retrograde Cholangiopancreatography/ERCP Market Foresight
ISO 13485 certification is bifurcating the competitive landscape into qualified manufacturers and excluded aspirants. Olympus Corporation leverages its vertically integrated endoscope manufacturing to sustain pricing power across premium visualization platforms. Boston Scientific Corporation competes through specialized stent and dilation portfolios tailored to complex biliary anatomy. Cook Medical anchors its position via deep catheter expertise and direct hospital contracting networks.
Endoscopic retrograde cholangiopancreatography denotes a fluoroscopy-guided endoscopic technique where a side-viewing duodenoscope accesses the ampulla of Vater to inject contrast into the biliary and pancreatic ducts, enabling diagnostic imaging and therapeutic intervention. The procedure requires high-resolution C-arm fluoroscopy systems capable of real-time digital subtraction angiography to visualize ductal architecture and guide instrument deployment. Among product categories, endoscopes command the largest installed base revenue pool while accessories generate the highest replacement frequency and recurring margin contribution. Within applications, bile duct stone management represents the mature volume leader whereas cholangiocarcinoma interventions are expanding fastest due to rising incidence and procedural complexity.
FDA duodenoscope reprocessing guidance and EU MDR Class IIa device classification impose stringent validation burdens that favor established manufacturers with regulatory infrastructure. The EPA and OSHA jointly influence sterile processing department workflows through disinfection chemical exposure limits and reprocessing environment standards. Stakeholders must monitor evolving single-use endoscope substitution economics against capital-intensive reusable system refurbishment cycles.
Market Dynamics
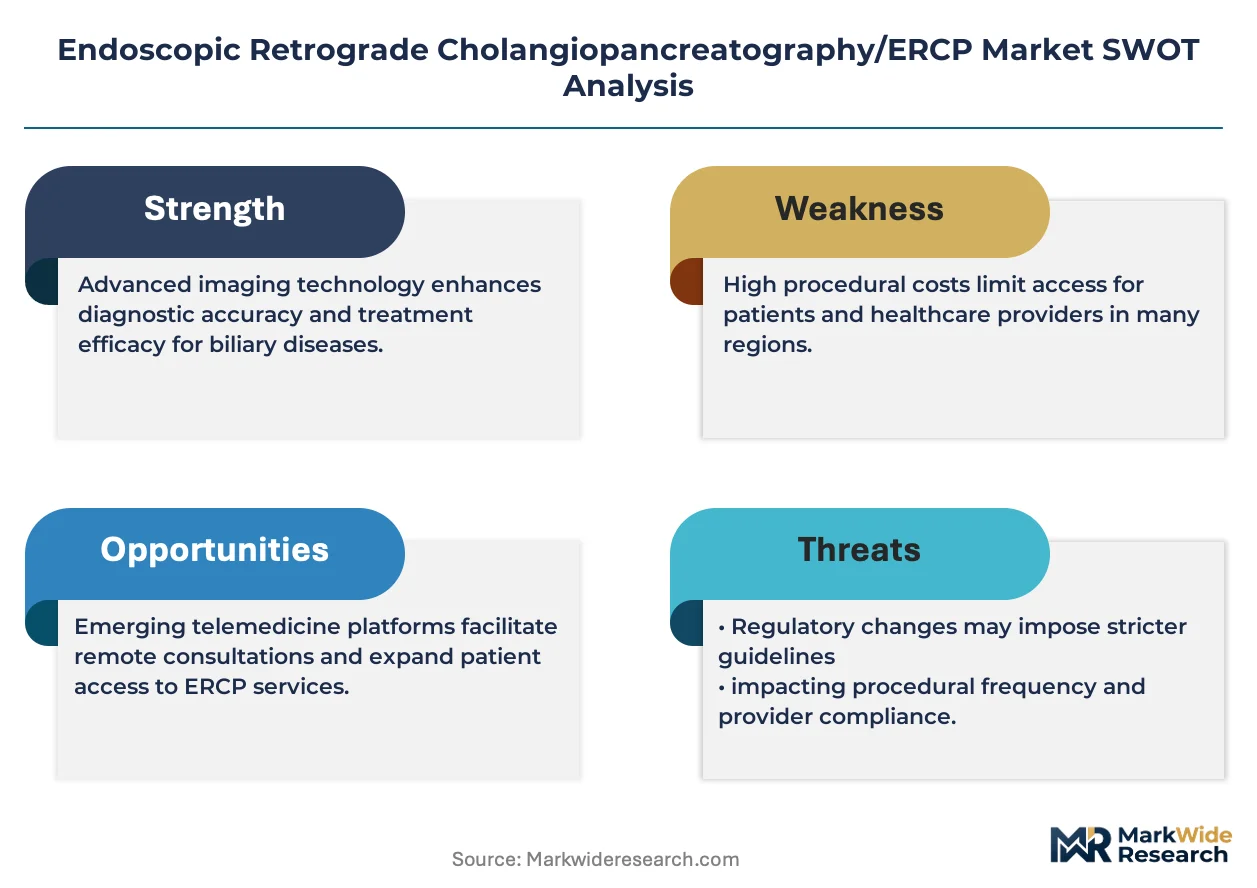
Single-use duodenoscope economics are compressing the reusable endoscope refurbishment cycle, forcing hospitals to recalculate capital allocation between capital-intensive sterilization infrastructure and per-procedure disposable costs.
Growth Catalysts
- EU MDR Class IIa device classification:Stringent validation requirements for reusable duodenoscopes are accelerating hospital procurement of single-use alternatives in tertiary academic centers.
- Fluoroscopy-guided biliary interventions:Rising incidence of cholangiocarcinoma is expanding procedural complexity and driving demand for advanced ERCP platforms in oncology service lines.
- North American hospital consolidation:Health system mergers are centralizing high-margin interventional gastroenterology procedures into flagship campuses with dedicated ERCP labs.
Market Restraints
- Ethylene oxide sterilization dependency:EPA emission limits on EtO sterilization facilities are constraining reprocessing capacity and extending instrument turnaround times.
- Duodenoscope supply concentration:Three manufacturers control over 85% of installed reusable base, creating vulnerability to FDA enforcement actions or manufacturing disruptions.
- Single-use cost premium:Per-procedure disposable endoscope pricing remains 3-4x above reusable reprocessing costs, limiting adoption in community hospital settings.
Strategic Opportunities
- India's tertiary hospital expansion:Government PLI scheme incentives for medical device manufacturing are attracting ERCP platform assembly investments to serve South Asian demand.
- Artificial intelligence-fluoroscopy convergence:Real-time ductal anatomy recognition algorithms are enabling autonomous instrument guidance and reducing radiation exposure.
- Direct-to-hospital stent distribution:Bypassing traditional distributor markups through GPO-negotiated contracts is capturing margin in high-volume stone management procedures.
Industry Challenges
- Advanced endoscopy fellowship scarcity:ERCP credentialing requires 180+ supervised procedures, creating a 2-3 year pipeline bottleneck for qualified interventionalists.
- ISO 13485 certification timeline:New market entrants face 18-24 month quality management system validation before EU or US market access.
- Legacy C-arm fluoroscopy integration:PACS connectivity standards vary across installed Siemens, GE, and Philips systems, complicating unified workflow software deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopic Retrograde Cholangiopancreatography/ERCP Market |
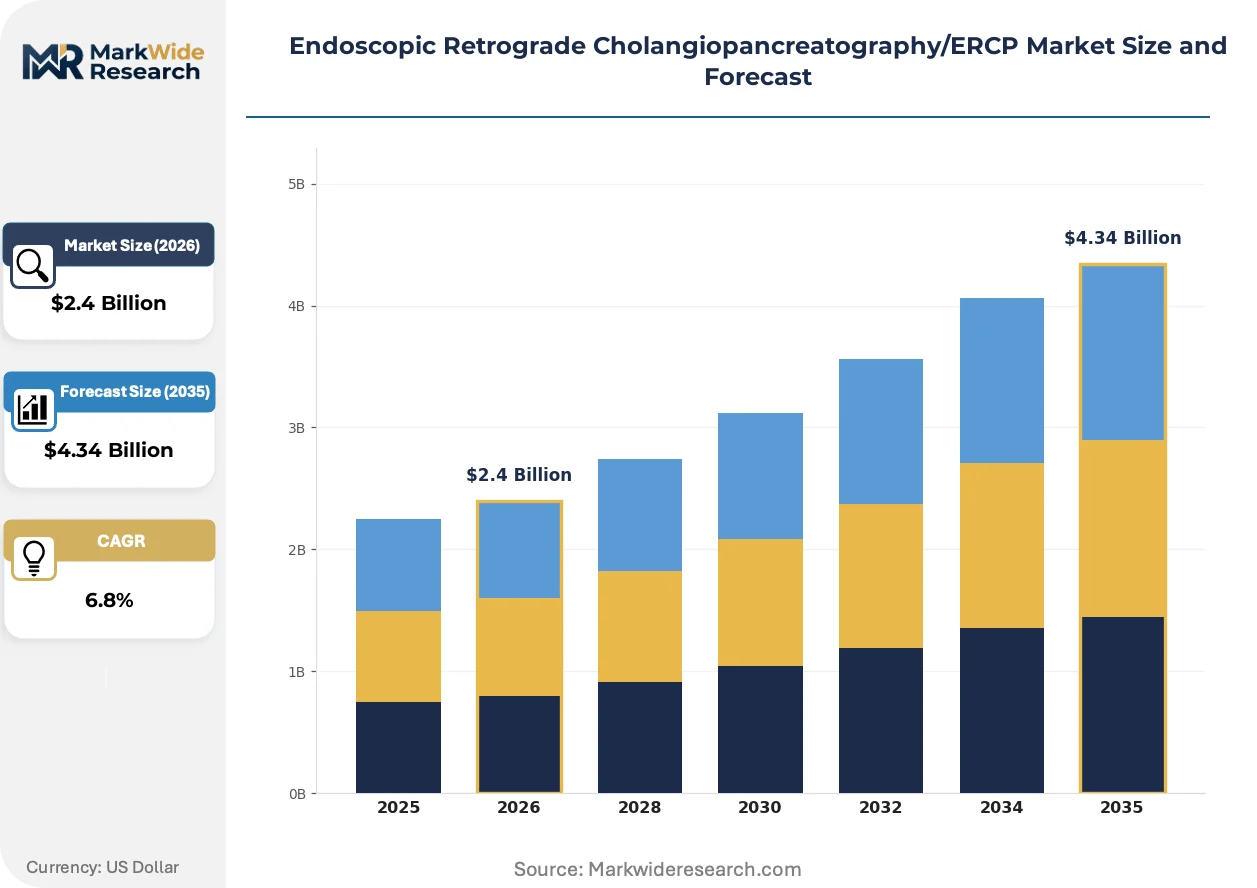
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Contrast Agents, Accessories, Imaging Systems Application: Bile Duct Stones, Cholangiocarcinoma, Pancreatitis, Biliary Strictures End User: Hospitals, Surgical Centers, Outpatient Clinics, Research Facilities Technology: Fluoroscopy, Ultrasound, CT Imaging, MRI |
| Companies Covered | CONMED Corporation, HOYA Corporation, Olympus Corporation, Cook Medical, KARL STORZ SE & Co. KG, Boston Scientific Corporation, Medtronic plc, Ambu A/S, Fujifilm Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopic Retrograde Cholangiopancreatography/ERCP Market Shifts & Advancements
Technology trajectories in ERCP are bifurcating between disposable instrument platforms and AI-augmented reusable systems, with regulatory pressure acting as the decisive variable in hospital procurement decisions.
Single-use duodenoscope technology is decomposing the traditional capital equipment model by eliminating reprocessing infrastructure requirements. Tertiary academic medical centers in the United States are piloting disposable platforms for immunocompromised patient populations. This shift is compressing the addressable market for sterilization equipment manufacturers while expanding recurring revenue pools for disposable instrument suppliers.
FDA's 2024 updated duodenoscope reprocessing guidance mandates enhanced surveillance sampling and periodic culture testing from all US facilities. The industrial consequence is a 15-20% increase in sterile processing department operating costs. High-volume ERCP centers are responding by accelerating transition plans to single-use alternatives or outsourcing reprocessing to third-party sterilization specialists.
Hospital purchasing committees are consolidating vendor relationships across endoscopy and interventional radiology departments to extract volume-based pricing concessions. Traditional distributor networks serving independent GI practices are losing share to manufacturer-direct contracts with integrated delivery networks. This concentration is most visible in the southeastern United States, where HCA and Tenet health systems have standardized on single-source ERCP platform agreements.
Endoscopic Retrograde Cholangiopancreatography/ERCP Market Segmentation
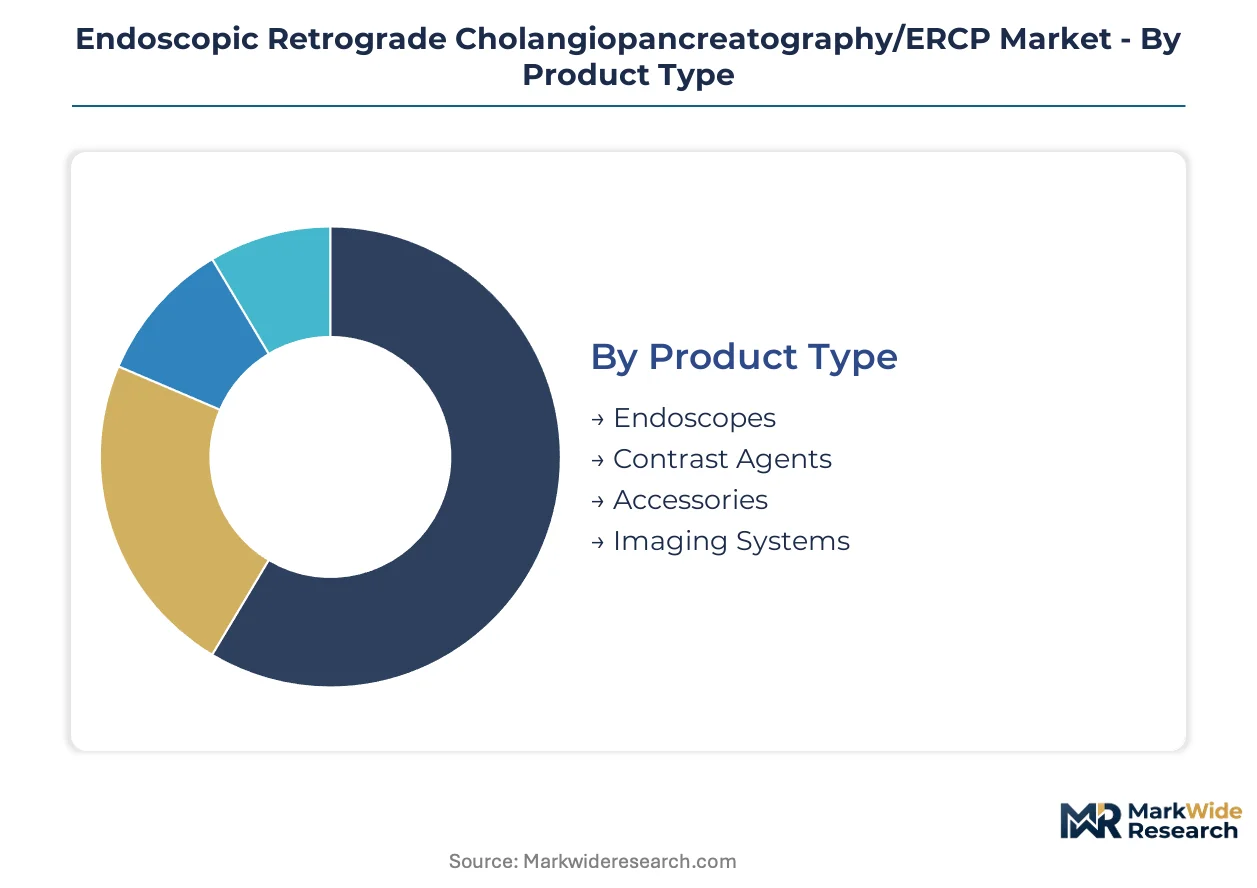
ERCP market segmentation reveals divergent procurement patterns across product categories. Capital-intensive endoscopes and imaging systems concentrate in tertiary academic centers with dedicated sterile processing infrastructure, while consumables distribute broadly through distributor and direct-contract channels.
Product Type:
Endoscopes and imaging systems anchor domestic manufacturing footprints in the United States and Japan, while accessories and contrast agents flow through globalized supply chains with significant European and Asian contract manufacturing.
- Endoscopes:Side-viewing duodenoscopes with elevator channel mechanisms enable ampullary cannulation and instrument exchange. Demand clusters in United States tertiary academic medical centers pursuing single-use transition strategies amid FDA reprocessing mandates. Olympus Corporation and Pentax Medical dominate installed base maintenance through captive service networks.
- Contrast Agents:Iodinated radiopaque solutions facilitate real-time fluoroscopic visualization of biliary and pancreatic ductal architecture. European manufacturing concentration—particularly German and Swiss chemical synthesis facilities—supplies global hospital networks under EMA and FDA dual regulatory filings. Procurement committees negotiate annual volume contracts with radiology pharmacy consolidators.
- Accessories:Guidewires, sphincterotomes, retrieval balloons, and stent delivery systems generate recurring revenue through per-procedure consumption. Asian contract manufacturers supply private-label portfolios to distributor networks.
- Imaging Systems:C-arm fluoroscopy units with digital subtraction angiography capability integrate with endoscopy suites. Siemens Healthineers, GE Healthcare, and Philips Medical Systems anchor installed base in North American hospital construction cycles.
Endoscopes command the established base. The steepest expansion runs through accessories.
Application:
Procedure volume distributes across benign and malignant indications with sharply diverging reimbursement profiles and technology intensity requirements.
- Bile Duct Stones:Choledocholithiasis extraction via sphincterotomy and balloon sweep constitutes the mature procedural volume leader. Community hospital settings in the United States perform bulk of stone management with standard reusable platforms and moderate-complexity accessory sets.
- Cholangiocarcinoma:Malignant biliary stricture stenting and brush cytology sampling demands advanced interventional platforms with intraductal ultrasound and cholangioscopy integration. Oncology service lines at MD Anderson Cancer Center, Memorial Sloan Kettering, and Johns Hopkins drive technology adoption.
- Pancreatitis:Pancreatic duct stenting and stone fragmentation address chronic pancreatitis complications. German and Japanese academic centers publish protocol evidence influencing global practice patterns.
- Biliary Strictures:Benign stricture dilation and sequential stenting bridges benign and malignant care pathways. Transplant hepatology programs at Cleveland Clinic and Mayo Clinic concentrate complex case volume.
Bile duct stones anchor procedural volume. Cholangiocarcinoma applications gain share fastest.
End User:
Facility type determines capital allocation authority, reprocessing infrastructure investment, and patient acuity mix.
- Hospitals:Integrated delivery networks with dedicated ERCP labs employ full-time interventionalists and maintain sterile processing departments. HCA Healthcare and Tenet Healthcare systems in the southeastern United States standardize platform procurement across multi-hospital networks.
- Surgical Centers:Ambulatory surgery centers with Medicare certification perform selected stone extraction procedures. California and Texas certificate-of-need regulations constrain expansion.
- Outpatient Clinics:Gastroenterology practice-based endoscopy units refer complex cases to hospital affiliates. Independent practitioner associations in Florida and Arizona aggregate purchasing through group purchasing organizations.
- Research Facilities:Academic medical centers with NIH funding pursue device innovation protocols and training curriculum development. Massachusetts General Hospital and University of Pennsylvania maintain active ERCP fellowship programs.
Hospitals retain the dominant installed base. Surgical centers show the fastest volume trajectory.
Technology:
Imaging modality selection balances real-time guidance precision against radiation exposure and capital equipment requirements.
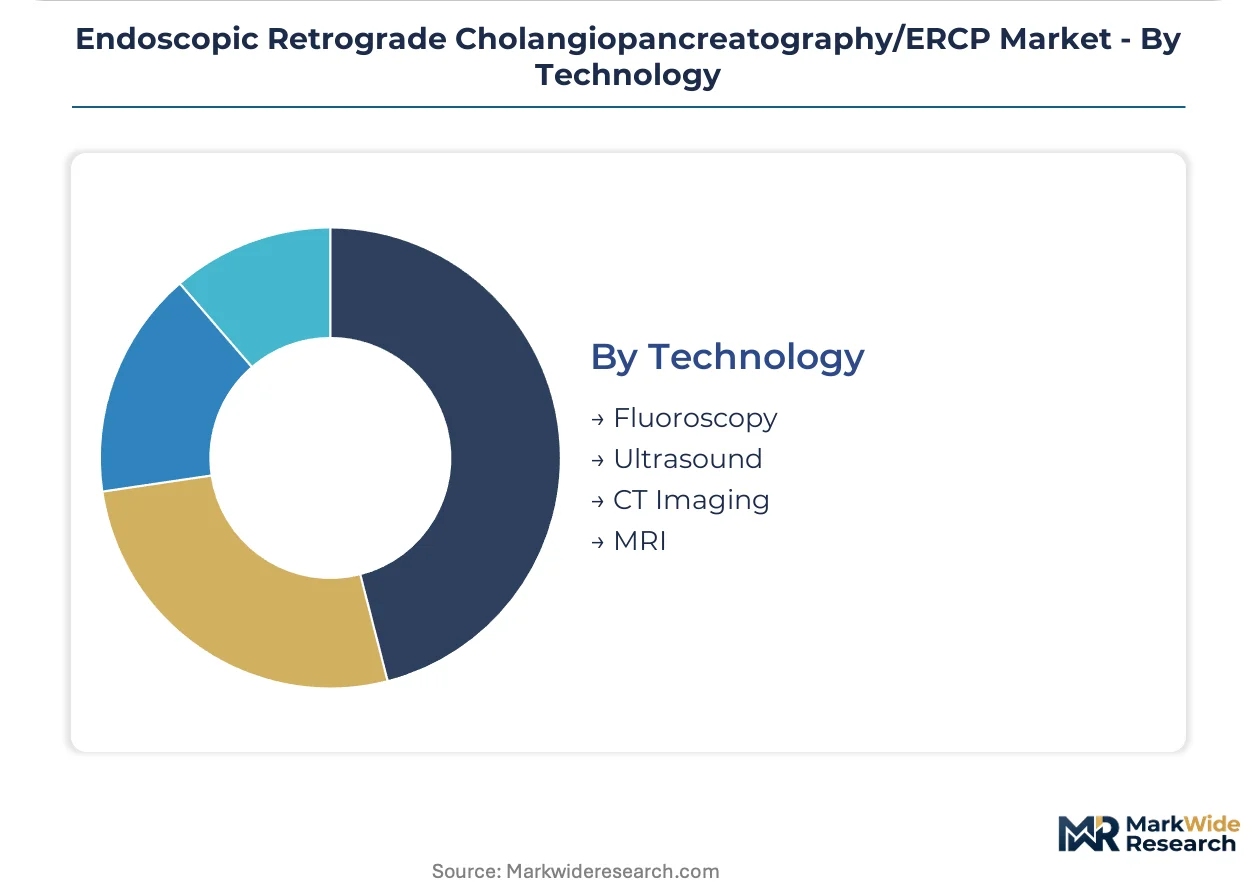
- Fluoroscopy:C-arm digital subtraction angiography provides continuous real-time ductal visualization during instrument manipulation. Every ERCP suite requires fluoroscopy integration; Siemens, GE, and Philips systems populate United States hospital construction.
- Ultrasound:Intraductal ultrasound probes characterize stricture etiology and guide tissue sampling. Japanese manufacturers Olympus and Fujifilm lead probe miniaturization.
- CT Imaging:Pre-procedural CT cholangiography plans intervention approach and identifies variant anatomy. Outpatient imaging centers in United States metropolitan markets perform preoperative staging.
- MRI:MRCP provides non-invasive biliary tree visualization without radiation exposure. Pediatric and pregnant patient populations drive adoption at Children's Hospital of Philadelphia and Mayo Clinic Rochester.
Fluoroscopy underpins every procedural workflow. Ultrasound adoption climbs fastest among advanced interventional platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government production-linked incentives and hospital consolidation programs are redrawing procurement geographies for ERCP platforms. Tertiary academic centers concentrate demand in mature markets while emerging economies build interventional gastroenterology capacity through targeted infrastructure investment.
United States
Health system mergers at HCA and Tenet are centralizing complex biliary procedures into flagship campuses with dedicated ERCP labs. FDA's 2024 duodenoscope reprocessing guidance mandates enhanced surveillance sampling, accelerating single-use adoption at MD Anderson Cancer Center and Memorial Sloan Kettering. The southeastern hospital corridor from Florida through Georgia standardizes platform procurement across integrated delivery networks.
Germany
Academic medical centers in Munich and Heidelberg publish protocol evidence that influences global pancreatitis management practice patterns. EU MDR Class IIa device classification imposes stringent validation requirements for reusable duodenoscopes, favoring established manufacturers with regulatory infrastructure. The Baden-Württemberg medical technology cluster anchors endoscope refurbishment service networks serving Central European hospitals.
Japan
Domestic manufacturers Olympus and Fujifilm leverage vertically integrated production to sustain pricing power across premium visualization platforms. PMDA regulatory pathways align with FDA timelines, enabling simultaneous market entry for next-generation duodenoscope designs. The Nagoya medical device corridor concentrates intraductal ultrasound probe miniaturization expertise.
India
Government PLI scheme incentives for medical device manufacturing are attracting ERCP platform assembly investments to serve South Asian demand. CDSCO regulatory harmonization with international standards accelerates import substitution for accessories and consumables. Tertiary hospital expansion in Maharashtra and Karnataka concentrates procedural volume in Mumbai and Bangalore metropolitan markets.
China
NMPA's streamlined Class III device review pathways are expanding market access for domestic endoscope manufacturers. Dual carbon goals pressure hospitals to evaluate reusable platform lifecycle costs against single-use alternatives. The Yangtze River Delta medical cluster around Shanghai concentrates fluoroscopy system integration expertise for hybrid ERCP-IR suites.
Endoscopic Retrograde Cholangiopancreatography/ERCP Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with captive endoscope manufacturing and specialized interventional accessory suppliers. Market structure concentrates around three archetypes: integrated visualization platform manufacturers, interventional device specialists with deep catheter expertise, and emerging single-use disposable challengers. Dominant competitive moves include backward integration into proprietary elevator channel mechanisms and direct-to-hospital contracting that bypasses traditional distributor markups.
Among diversified platform manufacturers, Olympus Corporation and Fujifilm Holdings Corporation exemplify the integrated archetype with captive supply of visualization systems and service networks. Boston Scientific Corporation occupies a position within the interventional specialist tier, while Ambu A/S represents the single-use challenger model. Cook Medical and KARL STORZ SE & Co. KG anchor the European-based specialist segment with established hospital contracting relationships.
| Leading Market Players |
|---|
| CONMED Corporation |
| HOYA Corporation |
| Olympus Corporation |
| Cook Medical |
| KARL STORZ SE & Co. KG |
| Boston Scientific Corporation |
| Medtronic plc |
| Ambu A/S |
| Fujifilm Holdings Corporation |
| Others |
Supply & Pricing Matrix
ISO 13485 certification gates both supply qualification and price differentiation simultaneously, bifurcating manufacturers into qualified incumbents with hospital-direct contracting leverage and excluded aspirants forced through distributor markups. This regulatory threshold concentrates pricing power among established players while compressing margins for uncertified competitors attempting market entry.
Pricing Analysis
Cost-plus contracts with medical-grade polymer indexation dominate duodenoscope procurement between Japanese manufacturers and United States hospital systems. Three-tier pricing structure across premium visualization platforms, standard reusable systems, and economy single-use alternatives differentiates by FDA clearance tier and after-sales service bundling. Pricing pressure stems from single-use alternatives compressing reusable refurbishment economics. Community hospitals exhibit highest price sensitivity; tertiary academic centers prioritize infection control over per-procedure cost.
Supply Chain Analysis
Inventory cycles for elevator channel mechanisms stretch 90-120 days due to precision machining requirements in Japanese and German component facilities. Duodenoscope assembly draws from United States imaging sensors, Japanese optical glass, and German precision motors. Single-source vulnerability concentrates in elevator wire manufacturing. Distribution runs through GPO-negotiated contracts with integrated delivery networks rather than independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive moat anchored in regulatory entrenchment, where FDA duodenoscope reprocessing mandates and EU MDR Class IIa classification create insurmountable validation timelines for prospective challengers.
For Market Incumbents: Shield installed base revenue through captive refurbishment service networks and backward integration into proprietary elevator channel mechanisms. Counter single-use substitution threats by embedding AI-fluoroscopy convergence into premium platform upgrades. Prioritize ISO 13485 certification maintenance as the primary competitive lever against emerging disposable challengers. For New Entrants and Emerging Players: Lead with single-use duodenoscope economics targeting community hospitals constrained by EPA ethylene oxide sterilization capacity limits. India's tertiary hospital expansion under PLI scheme incentives offers the most penetrable geography. Pursue CDSCO harmonization pathways to bypass incumbent distributor relationships through direct hospital contracting. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core endoscopy divisions amid portfolio rationalization. Long-term viability hinges on regulatory infrastructure amortization across decade-plus validation cycles. Monitor FDA enforcement action frequency as the critical inflection signal for single-use substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct GPO contracts with HCA and Tenet bypass distributor markups and lock volume commitments. |
| CE Marking Pathway | EU MDR Class IIa validation accelerates single-use adoption in German and French academic centers. |
| Software Companion Development | AI-fluoroscopy integration at MD Anderson reduces radiation exposure and differentiates premium platforms. |
| FDA Submission | Enhanced reprocessing guidance compliance maintains reusable system access to high-volume ERCP labs. |
| Reimbursement Strategy | Medicare ASC certification expansion in Texas and California unlocks ambulatory surgery center volume. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with interventional gastroenterologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS Medicare procedure databases, hospital procurement records, and EU MDR technical documentation. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue estimates.
Across the projection horizon, the analytical framework segmented volume and value by product type, application indication, end-user facility tier, and imaging technology modality. CAGRs derived from installed base turnover rates and single-use substitution elasticity. Forecast inputs incorporated EPA ethylene oxide facility capacity constraints and fellowship program graduation pipeline data.
Forecasts assume regulatory continuity in FDA reprocessing guidance and EU MDR enforcement; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopy Equipment and Software Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Non-Invasive Colon Cancer Screening Market
Endoscopy
Global Colonoscopes Market
Endoscopy
Asia Pacific Endoscopy Devices Market
Endoscopy
Colonic Stents Market
Endoscopy
Global Colonoscopy Devices Market
Endoscopy
Global Veterinary Endoscopy Market
Endoscopy
Polyp Biopsy Market
Endoscopy
Endorectal Balloon Market
Endoscopy
Sigmoidoscope Market
Endoscopy
Endoscopy Video Systems Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Mexico Endoscopy Devices Market