
 Cellular Encapsulation Market | 2026-2036
Cellular Encapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Encapsulation Market Analytics
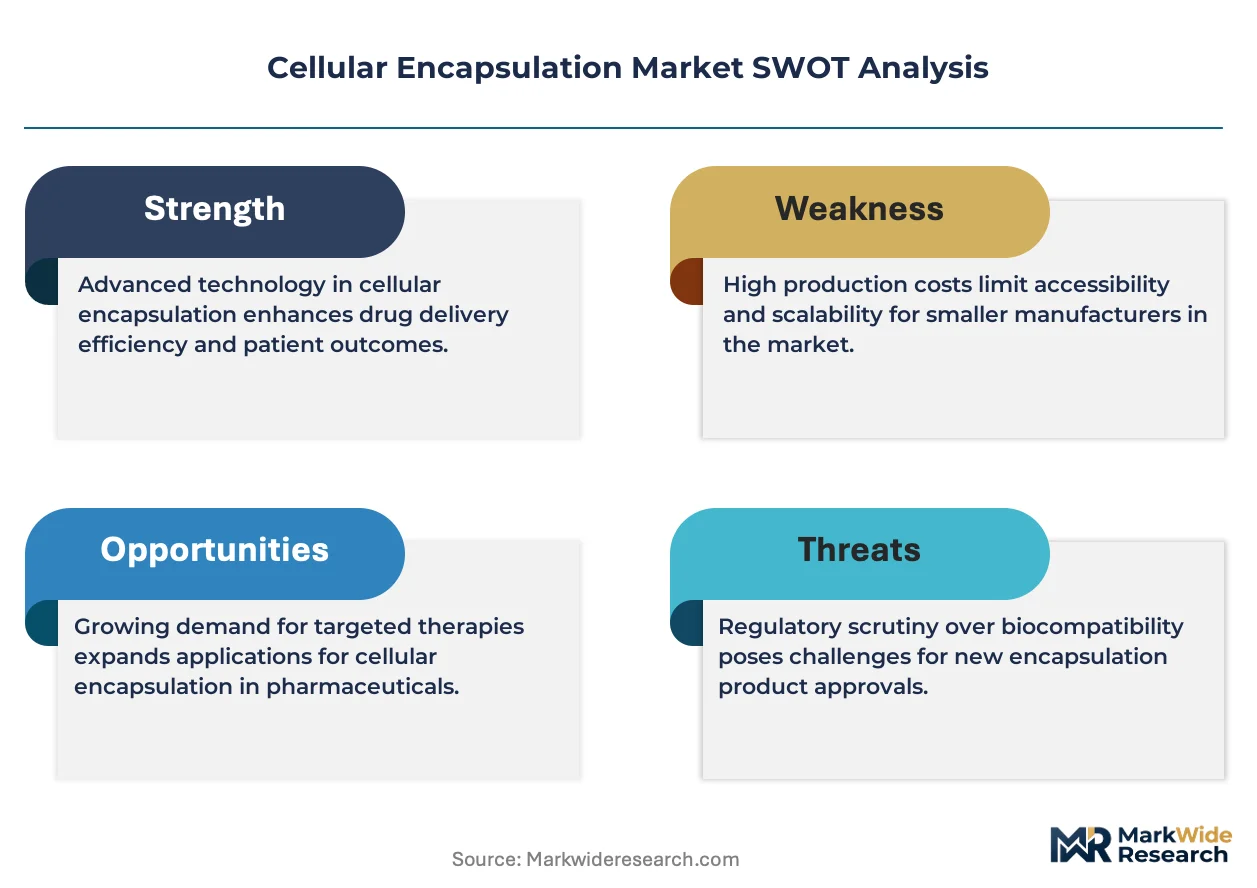
Healthcare provider procurement for encapsulated cell therapies is consolidating around large academic medical centers and specialized diabetes treatment networks. Thermo Fisher Scientific Inc. leverages its bioproduction equipment portfolio to supply encapsulation-grade materials at scale. Sigilon Therapeutics Inc. anchors its position in implantable cell therapies through proprietary Afibromer biomaterial platforms. Lonza Group AG sustains competitive differentiation with integrated contract development and manufacturing services spanning encapsulation through final fill-finish.
Cellular encapsulation encloses living cells within semipermeable membranes or matrices, typically using alginate-polylysine-alginate multilayers or synthetic hydrogels with pore sizes of 50–200 nanometers to permit nutrient diffusion while shielding cargo from immune recognition. The technique enables sustained therapeutic protein secretion, cell viability maintenance, and controlled release in applications from pancreatic islet transplantation to probiotic delivery. Hydrogels dominate current revenue owing to tunable mechanical properties and established clinical validation, while microcapsules represent the fastest-expanding category driven by advances in concentric nozzle extrusion and layer-by-layer assembly. Spray drying technology leads manufacturing throughput for nutraceutical and probiotic encapsulation, though coacervation commands premium pricing in pharmaceutical applications requiring precise core-shell morphology.
The FDA regulates encapsulated cell products as combination products or biologics depending on primary mode of action, creating distinct approval pathways that shape development timelines and clinical trial design. The EMA's Medical Device Regulation and the EU's Good Manufacturing Practice standards for advanced therapy medicinal products impose stringent material characterization requirements on alginate and synthetic polymer suppliers. Japan's PMDA has accelerated conditional approval frameworks for regenerative medicine products, influencing encapsulation technology investment priorities. Stakeholders must monitor evolving jurisdictional classifications of living cell products as these determinations dictate manufacturing standards, post-market surveillance obligations, and partnership structures across the value chain.
Market Dynamics
Alginate supply concentration in Norway and Scotland is forcing encapsulation manufacturers to secure multi-year offtake agreements as pharmaceutical-grade seaweed harvests face climate volatility and competing industrial demand.
Growth Catalysts
- FDA's regenerative medicine advanced therapy (RMAT) designation:The expedited review pathway for encapsulated islet cell products compresses development timelines and attracts venture funding into clinical-stage programs.
- Electrohydrodynamic spraying:This manufacturing technology achieves sub-100-micron capsule diameters with narrow size distribution, enabling intraportal delivery routes previously inaccessible to larger microcapsules.
- Germany's Diabeloop consortium:Academic medical centers in Munich and Heidelberg are establishing standardized encapsulation protocols for artificial pancreas systems, creating reference implementations for EU-wide adoption.
Market Restraints
- Pharmaceutical-grade alginate cost volatility:Purified low-viscosity alginate from limited North Atlantic harvests commands 8-12x commodity pricing, compressing margins for high-volume probiotic applications.
- Pericapsular fibrotic overgrowth (PFO):The foreign body response to implanted capsules remains the dominant cause of therapeutic failure in long-term islet transplantation, requiring immunosuppressive adjuncts that defeat encapsulation's purpose.
- EMA's MDR material characterization requirements:Extensive extractables and leachables testing for synthetic hydrogels adds 18-24 months to qualification timelines for new encapsulation platforms.
Strategic Opportunities
- Japan's conditional approval framework for regenerative medicines:PMDA's early commercialization pathway for encapsulated cell therapies with demonstrated safety enables revenue generation during Phase II efficacy studies.
- Central nervous system delivery:Convection-enhanced delivery of encapsulated dopamine-secreting cells for Parkinson's disease represents an underpenetrated application with limited competing modalities.
- Layer-by-layer nanofilm assembly:Integration with microfluidic manufacturing enables precise control over capsule permeability and mechanical strength, opening chronic protein replacement indications.
Industry Challenges
- Bioprocess engineering talent scarcity:The intersection of cell biology, polymer chemistry, and GMP manufacturing requires specialized expertise concentrated at fewer than twenty academic programs worldwide.
- ISO 10993 biocompatibility certification timelines:Extended sensitization and implantation studies for novel encapsulation materials delay product launches by 24-36 months beyond technical validation.
- Legacy fill-finish infrastructure incompatibility:Existing biologics manufacturing lines require substantial reconfiguration to handle shear-sensitive encapsulated cell suspensions without viability loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Encapsulation Market |
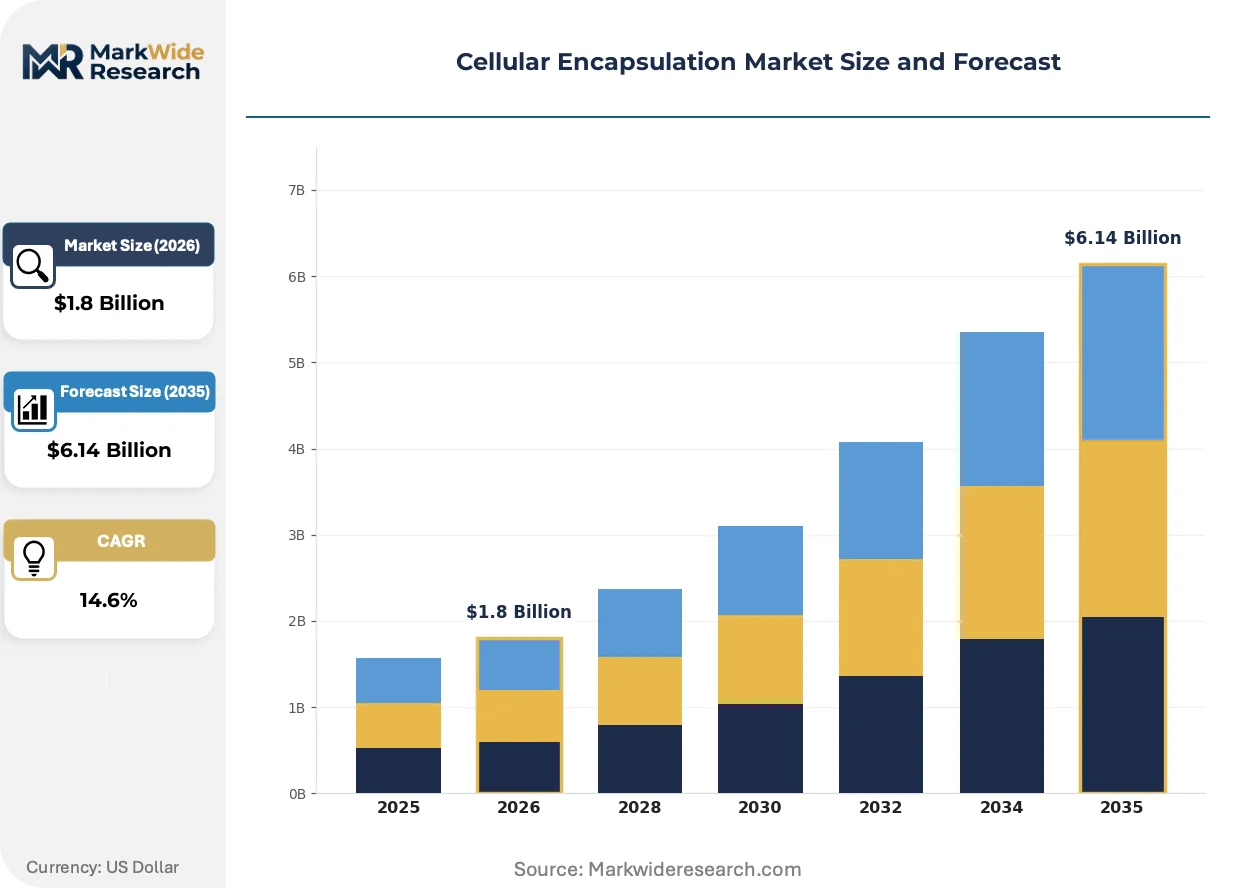
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcapsules, Microspheres, Nanoemulsions, Hydrogels Application: Pharmaceuticals, Food Preservation, Nutraceuticals, Cosmetics Technology: Spray Drying, Coacervation, Solvent Evaporation, Electrospinning End User: Healthcare Providers, Food Manufacturers, Cosmetic Companies, Research Institutions |
| Companies Covered | Corning Incorporated, Living Cell Technologies Limited, Thermo Fisher Scientific Inc., PharmaCyte Biotech Inc., Sigilon Therapeutics Inc., Merck KGaA, ViaCyte Inc., GE Healthcare Life Sciences, Lonza Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Encapsulation Market Evolving Landscape
Convergent advances in biomaterials science and microscale manufacturing are compressing the gap between bench-scale encapsulation protocols and commercial bioproduction requirements.
Electrospun nanofibrous encapsulation matrices are electrifying the chronic wound care segment by enabling sustained release of growth factors from living keratinocyte populations. Burn centers in Texas and Massachusetts are piloting these constructs for full-thickness wound coverage. The technology is electrifying competitive positioning by merging cell therapy efficacy with off-the-shelf availability previously restricted to acellular skin substitutes.
REACH Annex XVII restrictions on persistent organic pollutants are tightening purity specifications for synthetic polymer precursors used in hydrogel encapsulation. European chemical suppliers are investing in dedicated pharmaceutical-grade production lines to avoid cross-contamination with industrial polymer batches. Alginate producers in France and Spain face heightened analytical burden for heavy metal and endotoxin documentation under ECHA's updated guidance.
Academic medical centers are consolidating encapsulation therapy procurement through centralized tissue engineering core facilities rather than individual investigator-initiated manufacturing. The University of Pennsylvania and Stanford Medicine have established captive encapsulation capabilities serving multiple therapeutic programs. This concentration is most visible in the United States, where NIH-funded centers of excellence are standardizing quality systems ahead of commercial manufacturing transitions.
Cellular Encapsulation Market Segmentation
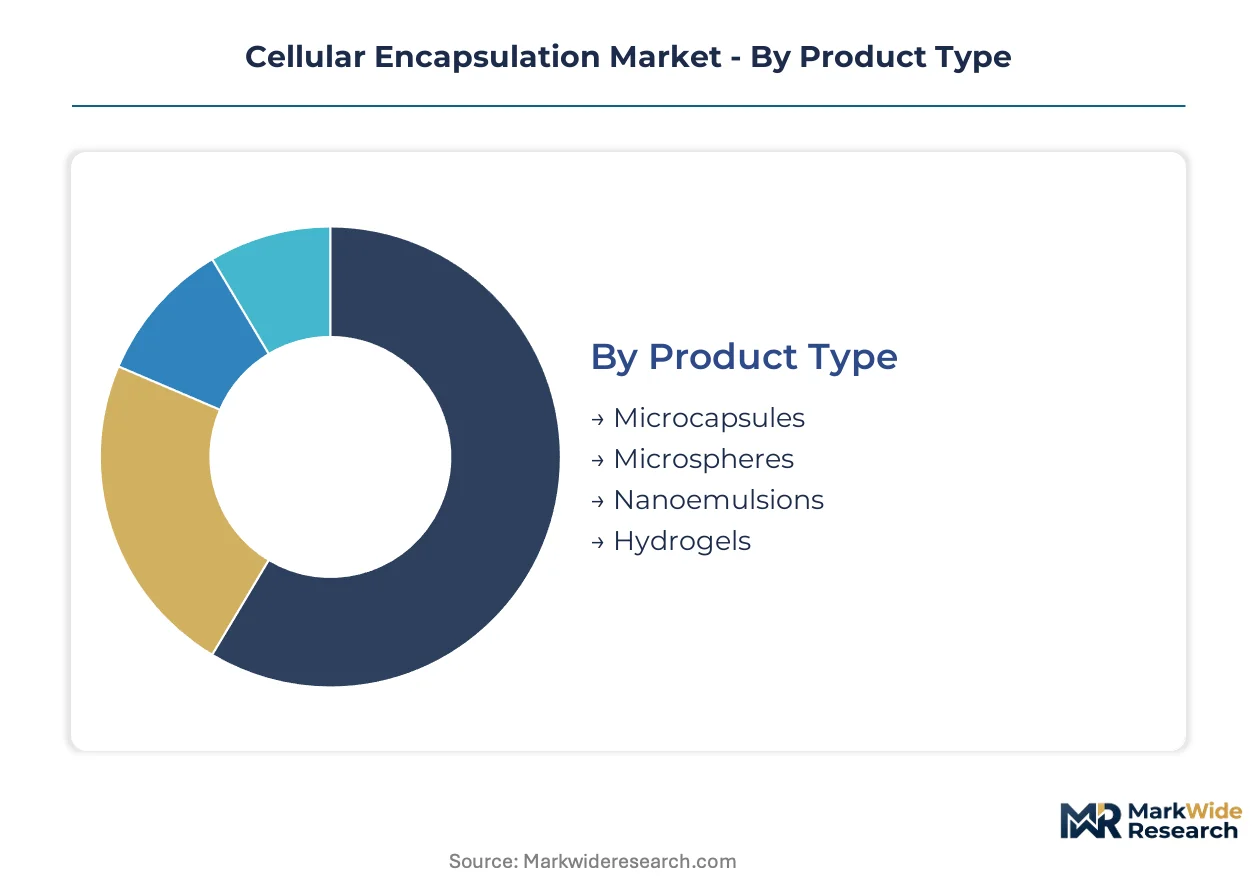
Cellular encapsulation technology demands distinct capital allocation across product formats, with manufacturing scale-up costs varying by three orders of magnitude between laboratory electrospinning and commercial spray-drying infrastructure. Segmentation reveals where equipment investments concentrate and which technical pathways attract development funding.
Product Type:
Hydrogels command the heaviest upfront capital burden due to sterile bioreactor requirements and GMP-grade polymer purification infrastructure.
- Hydrogels:Three-dimensional polymer networks with tunable crosslinking densities between 0.1-10% w/v enable sustained nutrient diffusion for living cell populations. Academic medical centers in the United States prioritize these matrices for pancreatic islet encapsulation programs, though per-batch production costs limit widespread probiotic deployment.
- Microcapsules:Concentric nozzle extrusion produces alginate-polylysine multilayers with 50-200 nanometer pore sizes for immune isolation. Germany's Diabeloop consortium has standardized these protocols for artificial pancreas systems, accelerating EU-wide clinical adoption.
- Microspheres:Solid polymeric matrices ranging 1-1000 microns in diameter serve controlled-release pharmaceutical applications.
- Nanoemulsions:Sub-micron lipid droplets stabilize hydrophobic actives for cosmetic and nutraceutical delivery.
Hydrogels absorb the bulk of installed capacity; microcapsules are expanding most quickly.
Application:
Pharmaceutical applications generate premium pricing through combination product regulatory pathways, while food preservation operates at commodity margins demanding volume efficiency.
- Pharmaceuticals:Encapsulated cell therapies for diabetes and oncology command development budgets exceeding $100 million per program. The FDA's RMAT designation compresses timelines for islet cell products, concentrating venture funding in Boston and San Francisco biotech clusters.
- Food Preservation:Probiotic encapsulation for shelf-stable functional foods requires high-throughput manufacturing at sub-cent per-dose economics. Norwegian alginate suppliers face harvest volatility that compresses margins for European dairy manufacturers.
- Nutraceuticals:Vitamin and omega-3 protection through spray-dried matrices serves aging populations in Japan and Germany.
- Cosmetics:Living cell extracts in encapsulation formats target premium skincare segments with limited regulatory burden.
Pharmaceuticals capture the dominant revenue share; nutraceuticals are climbing the fastest as preventive health expenditure rises.
Technology:
Manufacturing method selection determines equipment depreciation schedules and facility qualification timelines.
- Spray Drying:Continuous thermal processing achieves throughputs exceeding 100 kg/hour for probiotic and nutraceutical powders. Food manufacturers in the Netherlands and Denmark have consolidated procurement around this technology for bulk ingredient supply.
- Coacervation:Phase separation techniques enable precise core-shell morphology for pharmaceutical applications requiring burst-release kinetics. EMA extractables testing requirements extend qualification timelines for new installations.
- Solvent Evaporation:Organic phase removal produces uniform microspheres for hydrophobic drug loading.
- Electrospinning:Nanofiber matrix generation serves chronic wound care with living keratinocyte delivery. Burn centers in Texas and Massachusetts pilot these constructs for full-thickness coverage.
Spray drying dominates manufacturing capacity; electrospinning is gaining share fastest in regenerative medicine applications.
End User:
Procurement authority concentrates differently across customer types, with healthcare providers demanding extensive validation documentation.
- Healthcare Providers:Academic medical centers in the United States, Germany, and Japan maintain captive encapsulation capabilities through centralized tissue engineering cores. Stanford Medicine and the University of Pennsylvania have established internal manufacturing ahead of commercial transitions.
- Food Manufacturers:Large dairy and bakery conglomerates source encapsulated probiotics through multi-year supply agreements with alginate processors.
- Cosmetic Companies:Premium skincare brands commission custom encapsulation for differentiated active delivery.
- Research Institutions:Investigator-initiated programs drive early-stage protocol development before commercial handoff.
Healthcare providers command the highest specification requirements; food manufacturers are scaling fastest as functional food segments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Atlantic alginate harvests in Norway and Scotland anchor raw material availability for encapsulation manufacturers worldwide. Pharmaceutical-grade seaweed sourcing constraints concentrate production planning around these coastal regions. Climate volatility and competing industrial demand are forcing multi-year offtake agreements across the value chain.
United States
FDA's RMAT designation accelerates encapsulated islet cell therapy development timelines, compressing venture funding cycles in Boston and San Francisco biotech clusters. The agency's evolving guidance on combination products shapes manufacturing standards for alginate-polylysine multilayers. Stanford Medicine and the University of Pennsylvania have established captive encapsulation capabilities through centralized tissue engineering cores.
Germany
The Diabeloop consortium in Munich and Heidelberg standardizes microcapsule protocols for artificial pancreas systems, creating reference implementations for EU-wide adoption. EMA's Medical Device Regulation imposes stringent extractables and leachables testing on synthetic hydrogels. REACH Annex XVII restrictions on persistent organic pollutants tighten purity specifications for polymer precursors used in pharmaceutical-grade encapsulation.
Japan
PMDA's conditional approval framework for regenerative medicines enables early commercialization of encapsulated cell therapies during Phase II efficacy studies. METI funding priorities target chronic protein replacement indications through layer-by-layer nanofilm assembly. Tokyo and Osaka academic medical centers maintain deep clinical trial pipelines for stem cell derivatives.
United Kingdom
Scottish alginate processors face harvest volatility from North Atlantic seaweed beds, compressing margins for European dairy manufacturers sourcing probiotic encapsulation materials. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit standards with FDA combination product pathways. London-based contract development organizations specialize in GMP translation of bench-scale encapsulation protocols.
Switzerland
Swissmedic's stringent biocompatibility certification timelines for novel encapsulation materials extend product launch schedules beyond technical validation. Basel and Zurich host concentrated bioprocess engineering expertise at the intersection of polymer chemistry and cell biology. The country's precision manufacturing heritage supports microfluidic integration with concentric nozzle extrusion systems.
Cellular Encapsulation Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue implantable cell therapy specialization and biomaterial platform differentiation. The market structures around three archetypes: diversified life science conglomerates with bioproduction equipment portfolios, dedicated encapsulation technology developers with proprietary polymer systems, and contract manufacturing organizations with integrated fill-finish capabilities. Consolidation pressures favor strategic partnerships over vertical integration, while capacity expansion concentrates in GMP-grade alginate purification and microfluidic manufacturing infrastructure.
Among diversified conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA occupy positions spanning encapsulation-grade materials supply through analytical instrumentation. Lonza Group AG exemplifies the integrated contract manufacturing archetype with capabilities extending from encapsulation protocol development to final sterile processing. Sigilon Therapeutics Inc. represents the dedicated biotechnology model, anchoring its position through proprietary Afibromer biomaterial platforms for implantable applications.
| Leading Market Players |
|---|
| Corning Incorporated |
| Living Cell Technologies Limited |
| Thermo Fisher Scientific Inc. |
| PharmaCyte Biotech Inc. |
| Sigilon Therapeutics Inc. |
| Merck KGaA |
| ViaCyte Inc. |
| GE Healthcare Life Sciences |
| Lonza Group AG |
| Others |
Value Network & Pricing Analysis
Academic medical centers and specialized diabetes treatment networks concentrate procurement authority, locking in contract-based long-term offtake agreements that insulate pharmaceutical-grade alginate pricing from commodity volatility while exposing probiotic manufacturers to spot-market swings.
Pricing Analysis
Volume-mass food preservation applications operate at sub-cent per-dose commodity margins, while pharmaceutical cell therapies command premium pricing through combination product regulatory pathways. Three-tier pricing structure across GMP-certified premium, pharmaceutical-grade standard, and technical-grade economy levels separates clinical trial materials from commercial therapeutics from industrial inputs. Pricing pressure stems from pharmaceutical-grade alginate cost volatility in North Atlantic harvests, compressing margins for high-volume probiotic applications. Food manufacturers exhibit highest price sensitivity due to thin conversion economics, while healthcare providers absorb premium pricing for validated encapsulation protocols.
Supply Chain Analysis
ISO 10993 biocompatibility certification and EMA extractables testing gate entry into pharmaceutical supply chains, extending qualification timelines for novel encapsulation materials. Raw material supply draws from Norwegian and Scottish alginate processors, German synthetic polymer suppliers, and Japanese precision equipment manufacturers. Pharmaceutical-grade seaweed harvests, synthetic hydrogel precursors, and microfluidic manufacturing components constitute critical input dependencies. Single-source vulnerability concentrates in North Atlantic alginate harvesting regions facing climate volatility. Distribution runs through contract manufacturing organizations with integrated fill-finish capabilities serving biotech clusters in Boston, San Francisco, and Basel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encapsulation technology developers are racing to secure backward integration into GMP-grade alginate purification and captive microfluidic manufacturing capabilities to defend margin structures against raw material volatility and bioprocess engineering talent scarcity.
For Market Incumbents: To counter pericapsular fibrotic overgrowth failures in long-term islet transplantation, established players should deepen investment in layer-by-layer nanofilm assembly R&D and secure multi-year offtake agreements with Norwegian alginate processors to anchor raw material cost structures against harvest volatility. For New Entrants and Emerging Players: Enter via central nervous system delivery applications for Parkinson's disease, where convection-enhanced delivery of encapsulated dopamine-secreting cells faces limited competing modalities and less mature competitive defense. Target Japan's conditional approval pathway for early revenue generation during Phase II studies. For Investors and Strategic Acquirers: The window for entry favors mid-cap contract development organizations with demonstrated GMP translation capabilities and established relationships with academic medical center tissue engineering cores. Watch PMDA conditional approval decisions and FDA RMAT designations as inflection signals for platform validation and revenue timing.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Alginate Offtake Agreement | Secures pharmaceutical-grade raw material supply from Norwegian harvesters against climate-driven volatility. |
| Layer-by-Layer Nanofilm Assembly Scale-Up | Enables precise permeability control for chronic protein replacement indications via microfluidic integration. |
| Captive Tissue Engineering Core Facility | Stanford Medicine and University of Pennsylvania models standardize quality systems ahead of commercial transitions. |
| PMDA Conditional Approval Pathway Entry | Generates revenue during Phase II efficacy studies for encapsulated cell therapies with demonstrated safety profiles. |
| ISO 10993 Biocompatibility Certification Investment | Accelerates product launch timelines by 18-24 months through preemptive sensitization and implantation study completion. |
Research Methodology
Document review covered FDA RMAT designation filings, EMA Medical Device Regulation guidance documents, and PMDA conditional approval frameworks, complemented by interviews with bioprocess engineering directors at contract manufacturing organizations, regulatory affairs leads at encapsulation technology developers, and procurement managers at academic medical center tissue engineering cores. Secondary validation drew from ClinicalTrials.gov encapsulated islet cell therapy pipelines, SEC 10-K disclosures from diversified life science conglomerates, and NIH funding databases for regenerative medicine centers of excellence. Bottom-up encapsulation protocol development timelines and top-down venture funding flow analysis were triangulated against installed manufacturing capacity estimates.
Cross-referencing historical FDA approval timelines for combination products against expert panel inputs on evolving material characterization requirements shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product format (hydrogel, microcapsule, microsphere), application (pharmaceutical, nutraceutical, food preservation), manufacturing technology (spray drying, coacervation, electrospinning), and end-user procurement authority structure. CAGRs were derived from equipment investment cycles, clinical trial enrollment trajectories, and regulatory pathway compression effects. Forecast inputs incorporated alginate harvest yield variability, electrohydrodynamic spraying equipment depreciation schedules, and EMA extractables testing queue lengths.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in FDA combination product classification determinations or North Atlantic seaweed harvest failures. Forecasts reflect assumptions regarding RMAT designation continuity, REACH Annex XVII enforcement intensity, and PMDA conditional approval framework stability. A model refresh is warranted upon material change in alginate supply concentration or electrohydrodynamic spraying equipment cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
Wearable ECG Sensor Market
Medical Devices
North America Medical Devices Market
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
Brachytherapy Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
TMJ Implants Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Lacrimal Devices Market
Medical Devices
India Hemostats Market
Medical Devices
Laryngeal Airway Mask Market
Medical Devices
Sweden Ophthalmic Devices Market
Medical Devices
Peritoneal Catheter Systems Market