
 Pelvic Electro-Stimulators Market | 2026-2036
Pelvic Electro-Stimulators Market Size, Share, and Industry Trends Forecast 2026-2036
Pelvic Electro-Stimulators Market Intelligence
Wireless connectivity and app-integrated biofeedback is tilting device architecture toward patient-managed home care platforms. Medtronic leverages its implantable neuromodulation portfolio to anchor premium positioning in sacral nerve stimulation. Laborie specializes in urodynamics and pelvic floor diagnostics, extending its reach into complementary stimulation systems. TensCare competes on cost-engineered transcutaneous devices for physiotherapy providers across European markets.
Pelvic electro-stimulators deliver controlled electrical impulses to pelvic floor musculature or associated neural pathways, typically operating at frequencies between 1-100 Hz with pulse widths of 100-400 microseconds to induce contraction, relaxation, or neuromodulatory effects. These devices serve primarily to restore continence function, rehabilitate post-surgical or postpartum musculature, and manage chronic pelvic pain syndromes through non-invasive or minimally invasive intervention. Transcutaneous systems dominate volume due to lower capital requirements and broader clinical access, while implantable neuromodulation captures disproportionate value through recurring procedure revenues and long-term patient retention. Intravaginal and perineal form factors are gaining traction in home care settings where discretion and self-administration override clinical supervision preferences.
FDA 510(k) pathways and EMA MDR compliance frameworks govern device safety and clinical evidence standards, with FDA recently demanding enhanced post-market surveillance for implantable pelvic stimulators following adverse event clustering. The EU MDR transition is forcing smaller manufacturers to consolidate or exit as notified body capacity constrains certification timelines. Stakeholders must monitor reimbursement recalibration in Medicare and statutory health insurance systems, as coverage determinations increasingly predicate on randomized trial evidence rather than historical precedent.
Market Dynamics
Wireless biofeedback integration is compressing the boundary between clinical supervision and patient-managed home therapy, forcing manufacturers to re-architect device ecosystems around connectivity infrastructure rather than standalone hardware.
Growth Catalysts
- Postpartum rehabilitation protocols:Maternity wards in Germany and Japan are embedding electro-stimulation into standard pelvic floor recovery pathways, expanding reimbursable indications beyond urinary incontinence.
- MDR compliance consolidation:Stricter EU MDR certification timelines are eliminating marginal competitors, concentrating volume among notified-body-certified manufacturers with established clinical data packages.
- Sacral nerve modulation:Implantable neuromodulation systems for fecal incontinence and non-obstructive urinary retention are capturing expanded CMS coverage in the United States.
Market Restraints
- Implantable device supply concentration:Critical lead and generator components rely on a limited supplier base in Switzerland and Ireland, creating vulnerability to single-source disruptions.
- Silicone and biocompatible polymer costs:Intravaginal probe manufacturing faces input price volatility from medical-grade elastomer markets tied to semiconductor and automotive demand.
- Transcutaneous efficacy ceiling:Surface electrode penetration depth limits therapeutic reach to superficial musculature, constraining addressable patient populations with deep pelvic floor dysfunction.
Strategic Opportunities
- Remote therapeutic monitoring reimbursement:New CPT codes in the United States are enabling billing for app-connected home therapy sessions previously classified as non-reimbursable self-care.
- Pediatric neurogenic bladder:Clean intermittent catheterization programs in academic medical centers are testing adjunctive stimulation protocols for spina bifida populations.
- AI-driven personalization:Machine learning algorithms analyzing contraction patterns are converging with pressure-sensor arrays to automate intensity titration without clinician intervention.
Industry Challenges
- Clinical evidence generation timelines:Randomized controlled trials for FDA de novo pathways require 24-36 month follow-up periods, compressing competitive response windows to emerging indications.
- Cross-functional talent scarcity:Device firms struggle to recruit engineers with simultaneous expertise in neuromodulation physiology, wireless firmware security, and Class III quality systems.
- Legacy EMR integration:Home-use platforms must reconcile proprietary data formats with Epic and Cerner architectures to satisfy hospital system procurement requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pelvic Electro-Stimulators Market |
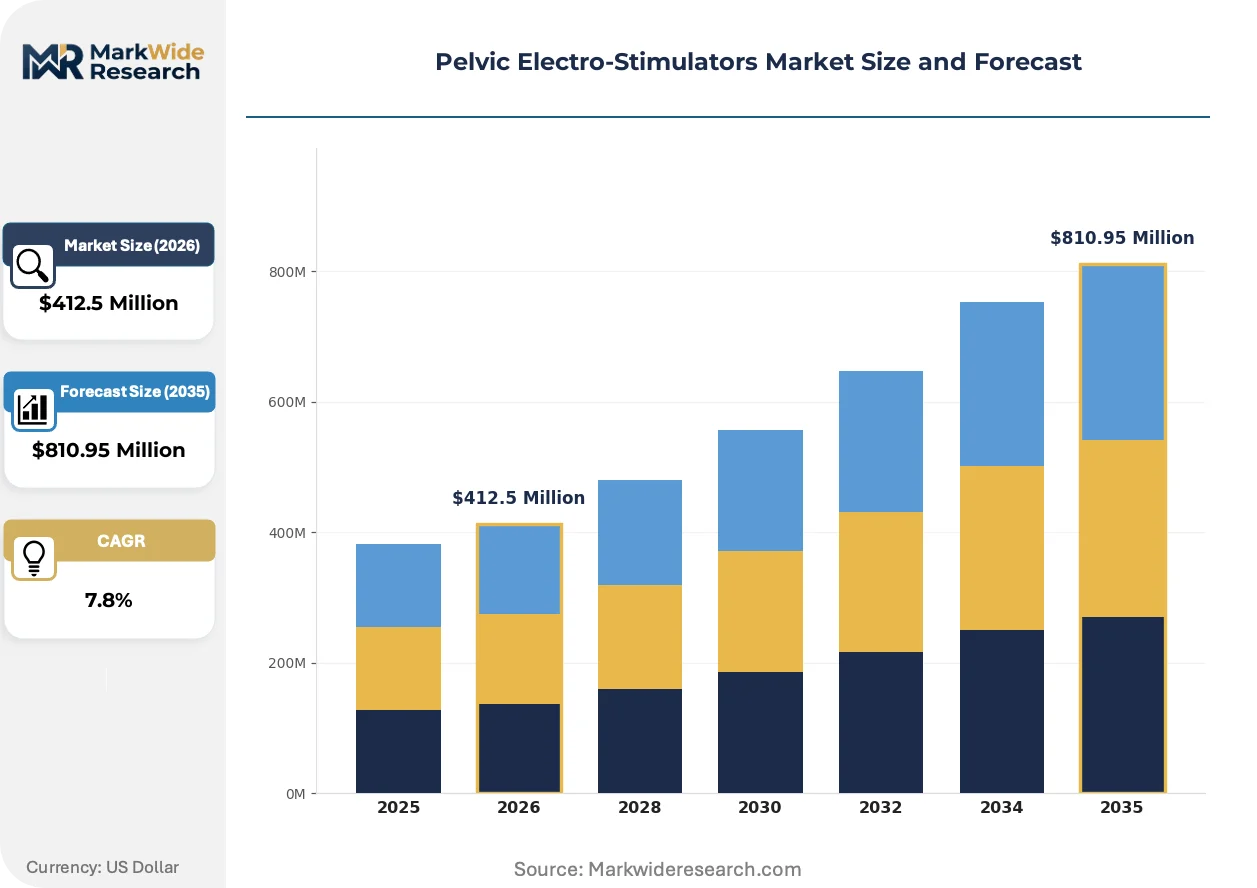
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $810.95 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transcutaneous, Implantable, Perineal, Intravaginal, Anal Application: Urinary Incontinence, Fecal Incontinence, Pelvic Floor Rehabilitation, Erectile Dysfunction, Chronic Pelvic Pain End User: Specialty Clinics, Rehabilitation Centers, Physiotherapy Providers, Home Care Settings, Urology Hospitals Technology: Electrical Stimulation, Magnetic Stimulation, Biofeedback, Neuromodulation, Radiofrequency |
| Companies Covered | Medtronic, Boston Scientific, Laborie, InControl Medical, The Prometheus Group, Zynex, TensCare, BTL Industries, Verity Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pelvic Electro-Stimulators Market Strategic Shifts & Innovations
Digital biomarker extraction and algorithmic therapy adjustment are displacing fixed-parameter protocols, transforming pelvic electro-stimulation from prescribed hardware into adaptive software-mediated interventions.
Bluetooth Low Energy-enabled intravaginal probes with embedded pressure transducers are virtualizing the traditional clinic-based biofeedback session, allowing real-time pelvic floor contraction visualization on patient smartphones. Urology practices in the Netherlands and Australia are piloting these systems for post-prostatectomy rehabilitation, reducing in-person visit burdens while maintaining therapeutic fidelity. This virtualization is compressing reimbursement models toward per-session digital health codes rather than capital equipment purchases.
EU MDR Article 10 post-market clinical follow-up obligations are extending surveillance timelines for implantable pelvic stimulators from two to five years, forcing manufacturers to rebuild clinical affairs teams and budget for extended registry maintenance. Notified bodies in Germany and Italy are prioritizing review bandwidth toward high-risk device categories, delaying clearance timelines for novel transcutaneous systems. Smaller manufacturers without legacy MDD certificates are responding by withdrawing from European markets or seeking Swissmedic parallel pathways.
Direct-to-patient subscription models are disrupting traditional durable medical equipment distribution channels for home-use transcutaneous devices. Physical therapy clinics in the United States that previously dispensed devices are unbundling hardware provision from supervised sessions, referring patients to manufacturer-managed rental programs. This channel shift is most pronounced in metropolitan markets with high deductibles, where patients absorb upfront costs and seek subscription predictability over capital outlays.
Pelvic Electro-Stimulators Market Segmentation
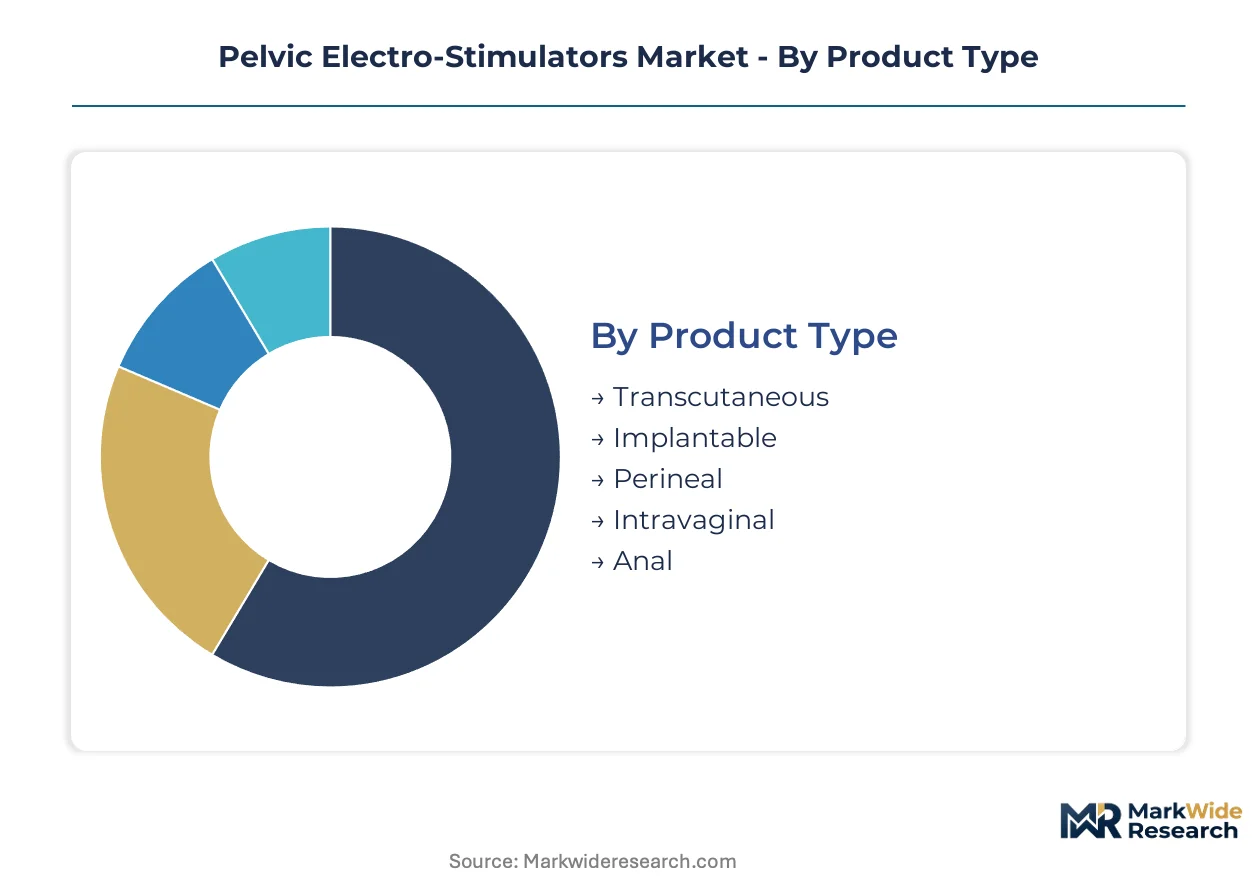
Segmentation in pelvic electro-stimulators reveals divergent service intensity and margin profiles across form factors and delivery settings. Product architecture and reimbursement pathway determine whether manufacturers capture value through capital equipment, disposable consumables, or recurring procedure fees.
Product Type:
After-sales service intensity varies dramatically across form factors, with implantable systems demanding surgical support infrastructure and transcutaneous devices requiring minimal technical intervention.
- Implantable:Surgical placement of lead arrays and pulse generators targets refractory fecal incontinence and non-obstructive urinary retention. CMS coverage expansion in the United States and statutory health insurance alignment in Germany concentrate demand among high-volume urology hospitals.
- Transcutaneous:Surface electrode systems operate at 1-100 Hz with pulse widths of 100-400 microseconds for pelvic floor rehabilitation. Physiotherapy providers across European markets favor these devices for lower capital requirements and broader clinical access.
- Intravaginal:Probe-based systems for postpartum recovery enable self-administered home therapy with pressure-sensor biofeedback integration.
- Perineal:External electrode placement serves patients contraindicated for internal probe insertion.
- Anal:Specialized probe configurations address fecal incontinence and post-surgical sphincter rehabilitation.
By volume, transcutaneous leads. By growth pace, intravaginal is ahead.
Application:
Clinical indication shapes regulatory evidence requirements and reimbursement complexity, with urinary incontinence offering established pathways and chronic pelvic pain demanding de novo trial investment.
- Urinary Incontinence:Stress and urge incontinence protocols represent the most mature reimbursable indication across Medicare and European statutory systems. Post-prostatectomy rehabilitation in urology hospitals and postpartum protocols in German maternity wards concentrate device procurement.
- Pelvic Floor Rehabilitation:Post-surgical and postpartum musculature restoration spans hospital, clinic, and home care settings. Wireless biofeedback integration is compressing reimbursement toward per-session digital health codes.
- Fecal Incontinence:Sacral nerve stimulation targets refractory cases with implantable systems capturing expanded CMS coverage.
- Erectile Dysfunction:Penile rehabilitation protocols following radical prostatectomy utilize perineal and intracavernosal stimulation approaches.
- Chronic Pelvic Pain:Neuromodulatory applications face longer FDA de novo pathways requiring 24-36 month follow-up periods.
Urinary incontinence dominates current volume. Pelvic floor rehabilitation is expanding most quickly.
End User:
Procurement authority and reimbursement capture diverge sharply between institution-based settings and direct-to-patient channels.
- Home Care Settings:Patient-managed platforms with app-integrated biofeedback are displacing clinic-dependent models. Subscription rental programs in high-deductible United States markets bypass traditional durable medical equipment distribution.
- Urology Hospitals:High-volume implantable procedures and complex pelvic floor cases anchor premium device procurement in Germany, the United States, and Japan.
- Physiotherapy Providers:Transcutaneous device dispensing and supervised session billing concentrate in European markets with aligned rehabilitation reimbursement.
- Specialty Clinics:Gynecology and urology practices pilot wireless intravaginal systems for postpartum and post-prostatectomy rehabilitation.
- Rehabilitation Centers:Post-acute pelvic floor programs integrate electro-stimulation into multidisciplinary continence care.
Urology hospitals lead by revenue concentration. Home care settings are gaining share fastest.
Technology:
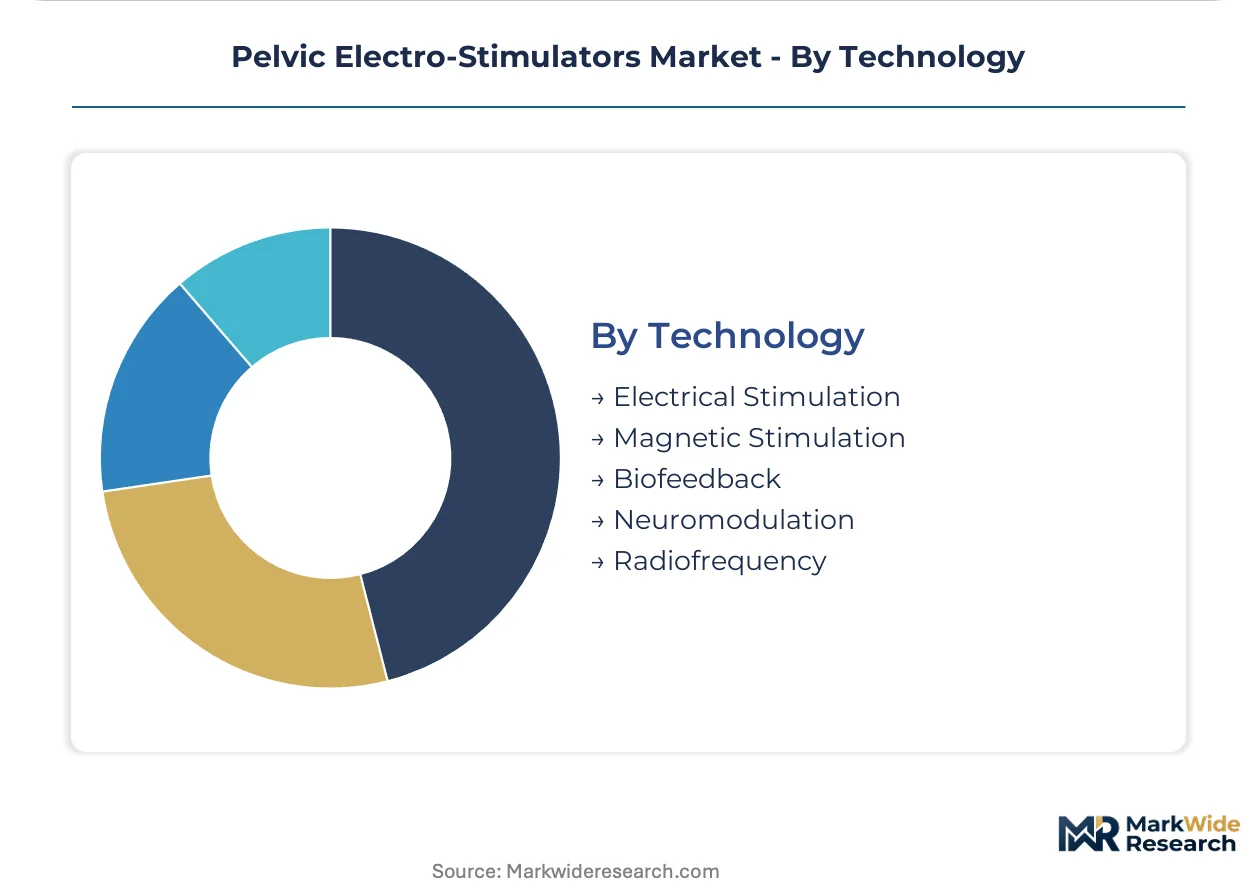
Technology modality determines the boundary between hardware commoditization and software-mediated value capture.
- Neuromodulation:Implantable sacral nerve stimulation systems command premium positioning through recurring procedure revenues and long-term patient retention. FDA and EMA evidence requirements are tightening for new implantable entrants.
- Biofeedback:Pressure-sensor arrays and real-time contraction visualization on patient smartphones are virtualizing traditional clinic-based sessions. Netherlands and Australia urology practices pilot these systems for remote therapeutic monitoring.
- Electrical Stimulation:Fixed-parameter and algorithm-adjusted impulse delivery spans transcutaneous, intravaginal, and implantable form factors.
- Magnetic Stimulation:Non-invasive deep tissue penetration addresses patients with contraindications to electrode placement.
- Radiofrequency:Thermal tissue modulation complements electro-stimulation in select pelvic floor applications.
Electrical stimulation leads by installed base. Biofeedback is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export transcutaneous pelvic electro-stimulators to physiotherapy networks across France and the Netherlands, establishing a westward trade corridor that channels continental European demand through Rhine-Ruhr distribution hubs.
United States
Post-prostatectomy rehabilitation protocols and expanded CMS coverage for sacral nerve stimulation drive hospital procurement. FDA post-market surveillance requirements for implantable pelvic stimulators tightened following adverse event clustering in 2023. Minneapolis and Boston anchor neuromodulation R&D clusters where academic medical centers pilot wireless biofeedback systems.
Germany
Statutory health insurance alignment for pelvic floor rehabilitation and maternity ward integration of electro-stimulation sustain device demand. EU MDR Article 10 post-market clinical follow-up obligations extend surveillance timelines to five years for implantable systems. Stuttgart and Munich concentrate notified-body-certified manufacturers rebuilding clinical affairs teams for extended registry maintenance.
Japan
Aging demographics and reimbursement alignment for urinary incontinence management concentrate clinical uptake in urology hospitals. PMDA clearance pathways for implantable neuromodulation systems demand enhanced evidence packages. Tokyo and Osaka metropolitan areas host high-volume implantation centers testing adjunctive stimulation protocols for neurogenic bladder populations.
Netherlands
Urology practices pilot Bluetooth-enabled intravaginal probes with pressure-sensor biofeedback for remote therapeutic monitoring. EMA MDR compliance frameworks govern device safety standards as notified bodies prioritize high-risk categories. Amsterdam and Rotterdam medical technology clusters virtualize traditional clinic-based sessions through smartphone-integrated platforms.
Australia
Post-prostatectomy rehabilitation programs in academic medical centers reduce in-person visit burdens through app-connected home therapy. TGA regulatory pathways align with international standards while enabling pilot programs for digital health reimbursement codes. Sydney and Melbourne anchor telehealth infrastructure supporting patient-managed pelvic floor platforms.
Pelvic Electro-Stimulators Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent reimbursement capture models. Implantable neuromodulation systems concentrate value among surgical device firms with recurring procedure revenues, while transcutaneous and home-use platforms fragment across physiotherapy distributors and direct-to-patient subscription channels. Three archetypes dominate: premium implantable specialists, cost-engineered transcutaneous suppliers, and digital health platform integrators. M&A activity targets wireless connectivity capabilities and notified-body certification assets, while geographic expansion focuses on Medicare-aligned United States markets and statutory-insurance-aligned German networks.
Among the implantable neuromodulation tier, Medtronic and Boston Scientific occupy positions anchored by sacral nerve stimulation portfolios and surgical support infrastructure. Laborie exemplifies the diagnostic-to-therapeutic extension archetype, leveraging urodynamics expertise into complementary stimulation systems. TensCare represents the cost-engineered transcutaneous specialist competing across European physiotherapy markets with lower capital-requirement devices. These three firms illustrate the divergence between premium surgical positioning and accessible rehabilitation platforms.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific |
| Laborie |
| InControl Medical |
| The Prometheus Group |
| Zynex |
| TensCare |
| BTL Industries |
| Verity Medical |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Swiss and Irish suppliers for implantable lead and generator components determines both the premium tier spreads separating implantable neuromodulation from transcutaneous systems and the elongated supply chain shape favoring surgical device firms with captive manufacturing partnerships. This concentration forces transcutaneous manufacturers toward cost-engineered sourcing while implantable specialists absorb biocompatible polymer volatility through long-term offtake agreements.
Pricing Analysis
Current-generation wireless biofeedback-integrated intravaginal probes command substantial premiums over prior-generation fixed-parameter transcutaneous units, while next-generation AI-driven personalization platforms are piloting value-based reimbursement models. The dominant pricing structure stratifies across premium implantable systems, standard wireless home-use devices, and economy transcutaneous units for physiotherapy providers. Price differentiation hinges on FDA clearance tier and after-sales service bundling. Cost compression in the economy tier is intensifying because physiotherapy distributors face direct-to-patient subscription competition. Hospital purchasing committees exhibit lowest price sensitivity, while individual patients in high-deductible plans drive economy tier demand.
Supply Chain Analysis
Contract manufacturing concentration rests with Swiss precision component specialists and Irish medical device foundries holding capacity for implantable pulse generators and lead arrays. Geographic supply concentration draws from Switzerland, Ireland, and Germany for critical neuromodulation components, with Malaysia and China supplying transcutaneous electrode assemblies. Raw material dependencies center on medical-grade silicone elastomers, platinum-iridium alloys for electrodes, and lithium-ion cells for implantable power systems. Single-source vulnerability in Swiss lead manufacturing creates exposure to regulatory restriction delays. Distribution runs through hospital system GPO contracts for implantables and physiotherapy distributor networks for transcutaneous devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pelvic electro-stimulation is approaching a platform-economics inflection where app-integrated biofeedback ecosystems and remote therapeutic monitoring interoperability will determine competitive survival. Manufacturers must architect around connectivity infrastructure rather than standalone hardware to capture recurring revenue streams.
For Market Incumbents: Insulate sacral nerve stimulation premium positioning by deepening backward integration into biocompatible polymer production and securing exclusive hospital system partnerships before wireless home-use platforms achieve reimbursement parity. FDA post-market surveillance tightening and EU MDR Article 10 compliance costs threaten marginal players with exit, creating consolidation leverage for notified-body-certified manufacturers with established clinical data packages. For New Entrants and Emerging Players: Build out direct-to-patient subscription channels in high-deductible United States metropolitan markets and pediatric neurogenic bladder protocols at academic medical centers, the most penetrable white-space segments underserved by implantable specialists. A software-first go-to-market angle leveraging AI-driven intensity titration can bypass capital equipment procurement barriers that favor entrenched surgical device firms. For Investors and Strategic Acquirers: Wireless connectivity-capable digital health platform integrators with notified-body certification assets represent the highest-conviction acquisition target archetype for medium-term consolidation plays. Long-term viability over the coming decade hinges on reimbursement strategy execution rather than hardware innovation alone. The signal to watch is CMS coverage determination timing for remote therapeutic monitoring codes, which will indicate when home-use platforms achieve economic parity with clinic-dependent models.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance separates notified-body-certified manufacturers from market exits. |
| Hospital System Partnership | GPO contract anchoring secures implantable procedure volume against subscription disruption. |
| Software Companion Development | App-integrated biofeedback virtualizes clinic sessions for remote therapeutic monitoring reimbursement. |
| Reimbursement Strategy | CPT code alignment determines whether home-use platforms achieve economic parity with clinic models. |
| Backward Integration | Captive biocompatible polymer production insulates margin against medical-grade elastomer volatility. |
Research Approach
Desk research of FDA 510(k) filings, EMA MDR submission databases, CMS coverage determination records, and hospital procurement contract registries preceded structured interviews with urology department heads, biomedical engineering directors, GPO contracts managers, and physiotherapy clinic owners. Primary intelligence combined with secondary validation across regulatory documentation and reimbursement databases enabled bottom-up unit economics modeling and top-down market sizing triangulation.
Assumptions held fixed include statutory health insurance alignment in Germany and Japan, FDA evidence requirements for implantable devices, and biocompatible polymer cost trajectories, while variables included CMS remote therapeutic monitoring reimbursement expansion timing and EU notified body review bandwidth allocation. The analytical framework segmented by product architecture, clinical indication, delivery setting, and technology modality across the projection horizon. CAGRs derived from procedure volume forecasts, device replacement cycles, and pricing trajectory assumptions for wireless biofeedback platforms.
Sensitivities concentrate around FDA post-market surveillance enforcement intensity, EU MDR certification timeline delays, and CMS coverage determination pacing for digital health codes. Forecasts reflect these assumptions with acknowledged revision risk from regulatory chokepoints or reimbursement recalibration. Quarterly review of notified body capacity indicators, adverse event reporting trends, and CPT code proposal dockets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
External Pacemakers Market
Medical Devices
Anorectal Manometry Systems Market
Medical Devices
Semiconductor Laser Therapeutic Device Market
Medical Devices
Italy Spinal Surgery Devices Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
US Stethoscope Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Global Transradial Access Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Non-Invasive Brain Stimulation System Market
Medical Devices
Surgical Display Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market
Medical Devices
Home Sleep Apnea Testing Devices Market