
 Global Blood Clot Retrieval Devices Market | 2026-2036
Global Blood Clot Retrieval Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Clot Retrieval Devices Market Foresight
Neurovascular centers is rebalancing the end-user mix as stroke networks centralize complex procedures away from general surgical hospitals. Stryker Corporation anchors North American catheter supply chains through in-house nitinol manufacturing. Medtronic plc competes across aspiration and stent retriever portfolios with integrated balloon guide platforms. Penumbra, Inc. specializes in vacuum-assisted thrombectomy systems that reduce distal embolization risk during clot extraction.
Blood clot retrieval devices are interventional instruments designed to extract occlusive thrombi from cerebral or peripheral vasculature, typically constructed from nickel-titanium alloys with distal capture baskets or aspiration lumens ranging from 3F to 6F in diameter. These devices restore perfusion in acute ischemic stroke and other thrombotic conditions where pharmacological dissolution carries hemorrhage risk. Stent retrievers command the largest revenue pool due to established clinical evidence and reimbursement parity across major markets. Aspiration devices represent the fastest-expanding segment as direct aspiration first pass techniques gain protocol adoption in comprehensive stroke centers. Mechanical thrombectomy systems retain premium positioning where combined stent-aspiration approaches justify higher procedure reimbursement.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape device design requirements and clinical trial obligations for manufacturers seeking market access. ISO 13485 quality management standards and Japan's PMDA pre-market approval processes add compliance layers that favor established players with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving health technology assessment criteria from Germany's Federal Joint Committee and England's NICE as these bodies increasingly tie reimbursement to randomized trial evidence of functional independence at ninety days.
Market Dynamics
Mechanical thrombectomy protocols are consolidating procedural workflows around direct aspiration first pass techniques, compressing device selection criteria and forcing manufacturers to prove integrated platform performance rather than standalone retrieval efficacy.
Growth Catalysts
- CE Marking under EU MDR:Stricter clinical evidence requirements for stent retrievers are filtering out marginal competitors and concentrating procurement among validated suppliers with dedicated quality management systems.
- Comprehensive stroke center expansion:Neurovascular networks in the United States, Germany, and Japan are standardizing mechanical thrombectomy as frontline therapy for large vessel occlusion, expanding addressable procedure volumes.
- Nitinol alloy processing:Advances in laser-cut hypotube manufacturing are enabling thinner-walled delivery catheters with improved trackability through tortuous cerebral anatomy.
Market Restraints
- Nitinol raw material concentration:Superelastic alloy supply chains cluster with a limited set of specialized metallurgical processors, exposing device manufacturers to input cost volatility and allocation risk.
- Japan PMDA pre-market approval timelines:Extended clinical trial requirements for novel retrieval mechanisms delay commercial entry by 18-24 months relative to FDA 510(k) pathways.
- Pharmacological thrombolysis:Tenecteplase and alteplase protocols retain first-line protocol status in resource-constrained settings, limiting mechanical thrombectomy penetration in emerging markets.
Strategic Opportunities
- India stroke care infrastructure:Underpenetrated neurointerventional capacity in tier-two cities creates whitespace for mobile stroke unit deployment and hub-and-spoke retrieval networks.
- Artificial intelligence triage integration:Automated large vessel occlusion detection on non-contrast CT is converging with ambulance-based treatment initiation, compressing door-to-puncture intervals.
- US Medicare severity-adjusted reimbursement:DRG payment differentials for comprehensive versus primary stroke centers incentivize hospital capital investment in dedicated thrombectomy suites.
Industry Challenges
- Neurointerventionalist training pipeline:Fellowship program capacity constraints limit the supply of operators capable of performing complex intracranial navigation under fluoroscopic guidance.
- ISO 13485 certification maintenance:Auditing burden for multi-site manufacturing facilities diverts engineering resources from next-generation device development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Clot Retrieval Devices Market |
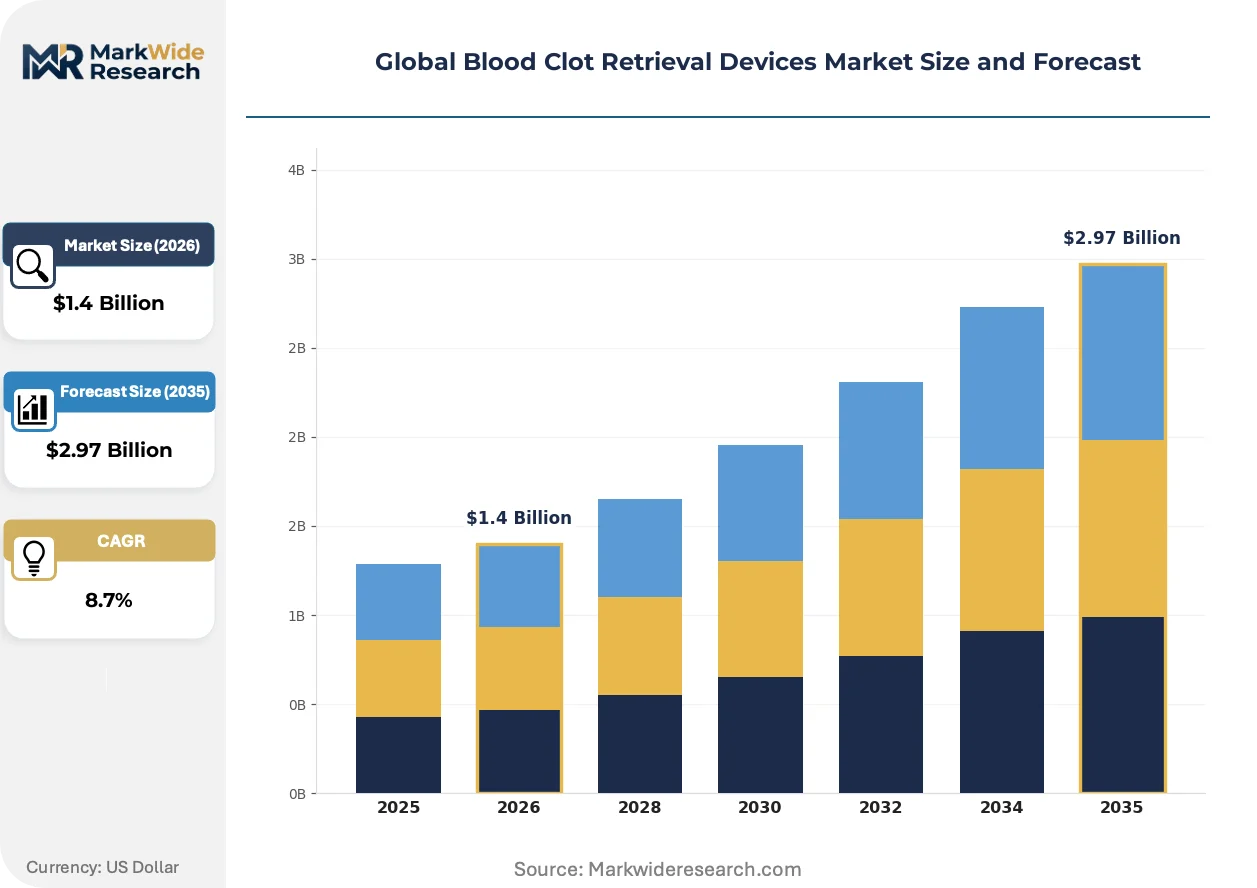
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stent Retrievers, Aspiration Devices, Mechanical Thrombectomy Systems, Combined Approach Devices Therapy Area: Ischemic Stroke, Deep Vein Thrombosis, Pulmonary Embolism, Peripheral Artery Disease End User: Specialty Clinics, Neurovascular Centers, Surgical Hospitals, Imaging Centers Technology: Microcatheter-Based, Balloon Guide Catheter, Vacuum-Assisted, Laser Thrombectomy |
| Companies Covered | Stryker Corporation, Medtronic plc, Johnson & Johnson, Boston Scientific Corporation, Penumbra, Inc., Terumo Corporation, Teleflex Incorporated, Argon Medical Devices, Inc., Inari Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Clot Retrieval Devices Market Shifts & Advancements
Device architectures are fusing aspiration and stent-retriever modalities into single-procedure platforms, while regulatory bodies tighten evidentiary standards for functional outcomes and real-world performance monitoring.
Bifurcated tip aspiration catheters with distal flow control are converging with large-bore balloon guide systems to enable complete clot ingestion without fragmentation. Comprehensive stroke centers in the United States are adopting these integrated platforms for first-line large vessel occlusion cases. The technology is converging with established stent-retriever protocols to create hybrid workflows that reduce distal embolization rates and improve modified thrombolysis in cerebral infarction scores.
EU Medical Device Regulation post-market surveillance requirements now mandate systematic collection of ninety-day modified Rankin Scale outcomes for all CE-marked thrombectomy devices. Manufacturers must maintain periodic safety update reports and trend analysis of serious incidents across notified body jurisdictions. Aspiration device portfolios face heightened scrutiny in Germany and France where health technology assessment bodies tie reimbursement to randomized trial evidence of functional independence.
Hospital procurement committees are consolidating vendor relationships around full-platform contracts covering aspiration catheters, stent retrievers, balloon guides, and access sheaths. This bundling displaces single-device purchasing and compresses pricing flexibility for standalone retrieval technologies. The shift is most pronounced in Japan where consolidated stroke center networks negotiate multi-year supply agreements with integrated device manufacturers.
Global Blood Clot Retrieval Devices Market Segmentation
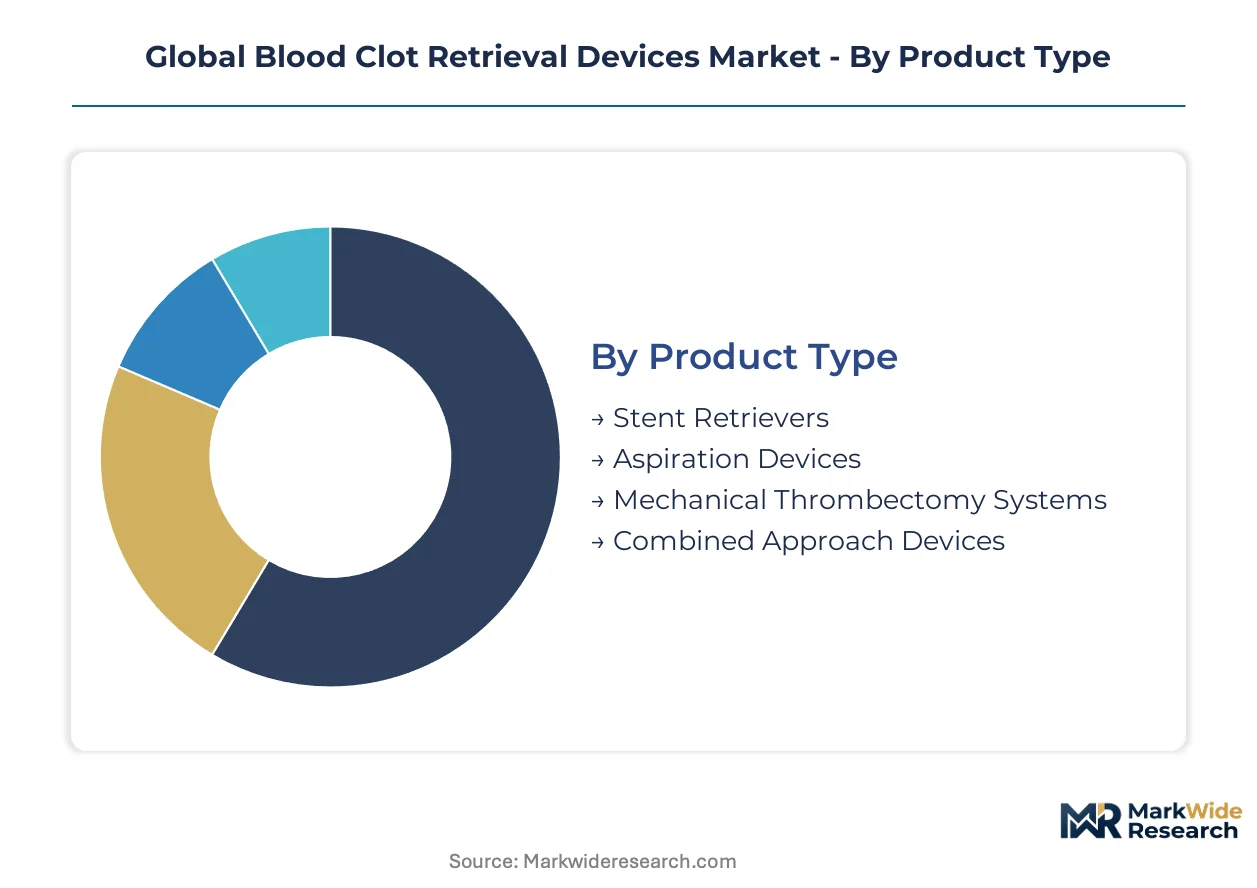
Device taxonomy in blood clot retrieval separates procurement pathways and reimbursement logic across neurovascular centers. Product architecture, therapy indication, and delivery technology each create distinct competitive arenas with divergent regulatory evidence requirements.
Product Type:
Stent retrievers and aspiration systems anchor current mechanical thrombectomy protocols, with hybrid platforms now entering comprehensive stroke center workflows.
- Stent Retrievers:Nickel-titanium alloy constructs with radial force-optimized strut patterns deploy across large vessel occlusions in the anterior circulation. Demand concentrates in the United States and Germany where reimbursement parity with intravenous thrombolysis supports frontline deployment in comprehensive stroke centers. FDA 510(k) clearance pathways favor incremental design modifications over novel retrieval mechanisms.
- Aspiration Devices:Large-bore catheter systems with distal aspiration lumens enable direct clot ingestion without stent deployment. Neurovascular centers in Japan and the United States are standardizing aspiration-first protocols for M1 segment occlusions. PMDA pre-market approval timelines in Japan extend commercial entry by 18-24 months relative to FDA pathways.
- Mechanical Thrombectomy Systems:Integrated platforms combining aspiration and stent-retriever modalities in single-procedure workflows.
- Combined Approach Devices:Hybrid architectures enabling sequential or simultaneous deployment of multiple retrieval mechanisms.
Mature deployment sits with stent retrievers. Newer deployment is concentrated in aspiration devices.
Therapy Area:
Clinical indication determines device sizing, navigation complexity, and evidence requirements for functional outcome claims.
- Ischemic Stroke:Acute large vessel occlusion in the anterior and posterior circulation represents the primary addressable population for mechanical thrombectomy. Comprehensive stroke centers in the United States, Germany, and Japan drive procedure volume concentration. Germany's Federal Joint Committee ties reimbursement to ninety-day modified Rankin Scale evidence of functional independence.
- Deep Vein Thrombosis:Iliofemoral and caval thrombus extraction employs larger-caliber aspiration systems with venous access sheaths. Demand clusters in surgical hospitals with interventional radiology capabilities across the United States and Western Europe. CE marking under EU MDR imposes post-market surveillance obligations for venous intervention outcomes.
- Pulmonary Embolism:Catheter-directed thrombus removal from main and lobar pulmonary arteries.
- Peripheral Artery Disease:Limb-salvage thrombectomy in femoropopliteal and tibial vessels.
Established clinical evidence concentrates in ischemic stroke. Emerging application volumes are climbing fastest in deep vein thrombosis.
End User:
Facility type determines capital equipment requirements, operator training depth, and case volume thresholds for device procurement contracts.
- Neurovascular Centers:Dedicated thrombectomy suites with biplane fluoroscopy and twenty-four-hour neurointerventionalist coverage command premium device pricing. These facilities in the United States negotiate bundled contracts covering aspiration catheters, stent retrievers, balloon guides, and access sheaths. Medicare severity-adjusted DRG differentials incentivize hospital capital investment in comprehensive versus primary stroke center designation.
- Surgical Hospitals:General acute care facilities with interventional radiology or cardiology capabilities performing secondary thrombectomy referrals.
- Specialty Clinics:Outpatient vascular intervention centers with limited stroke care scope.
- Imaging Centers:Diagnostic facilities with emerging interventional capabilities for triage and transfer coordination.
Procedure complexity anchors in neurovascular centers. Hub-and-spoke expansion is redirecting volume toward surgical hospitals with telestroke support.
Technology:
Delivery and extraction mechanisms differentiate trackability, clot engagement, and distal embolization risk profiles.
- Microcatheter-Based:Low-profile delivery systems enable navigation through tortuous cerebral anatomy with 3F-4F distal outer diameters. Laser-cut hypotube manufacturing advances in the United States and Germany support thinner-walled constructions with improved pushability. ISO 13485 quality management standards govern multi-site production facility auditing.
- Vacuum-Assisted:Continuous aspiration systems reduce distal embolization risk during clot extraction.
- Balloon Guide Catheter:Flow arrest and aspiration combination platforms.
- Laser Thrombectomy:Photoacoustic clot disruption with aspiration integration.
Commercial penetration is deepest in microcatheter-based systems. Vacuum-assisted platforms are gaining share fastest in comprehensive stroke center protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Massachusetts and Minnesota concentrate thrombectomy device engineering talent. FDA 510(k) clearance pathways attract venture funding toward these clusters. Reimbursement differentials between comprehensive and primary stroke centers reshape hospital capital allocation across national networks.
United States
Medicare severity-adjusted DRG payment differentials incentivize hospital investment in dedicated thrombectomy suites. FDA maintains 510(k) clearance pathways for incremental stent-retriever design modifications. Comprehensive stroke centers in Houston and Phoenix standardize mechanical thrombectomy as frontline large vessel occlusion therapy.
Germany
The Federal Joint Committee ties device reimbursement to ninety-day modified Rankin Scale evidence of functional independence. CE marking under EU MDR imposes post-market surveillance obligations on all marketed thrombectomy systems. Neurovascular networks in Bavaria and North Rhine-Westphalia consolidate procurement around validated suppliers with ISO 13485 certification.
Japan
PMDA pre-market approval timelines extend commercial entry by eighteen to twenty-four months relative to FDA pathways. METI funding programs support domestic catheter manufacturing capabilities. Stroke center networks in Tokyo and Osaka negotiate multi-year supply agreements with integrated device manufacturers.
India
Underpenetrated neurointerventional capacity in tier-two cities creates whitespace for mobile stroke unit deployment. CDSCO regulatory frameworks for class C and D medical devices establish clinical trial requirements for novel retrieval mechanisms. Hub-and-spoke retrieval networks in Maharashtra and Karnataka compress door-to-puncture intervals through telestroke coordination.
United Kingdom
NICE health technology assessment criteria increasingly tie reimbursement to randomized trial evidence of functional independence. NHS England stroke service specifications mandate twenty-four-hour thrombectomy availability at designated centers. Neurovascular units in London and Manchester attract capital investment through outcome-based commissioning frameworks.
Global Blood Clot Retrieval Devices Market Competitive Landscape
Top-tier vendors anchor integrated platform supply, while mid-tier specialists concentrate on single-modality retrieval technologies. The vendor base stratifies across three tiers: diversified medical technology conglomerates with catheter manufacturing capabilities, dedicated neurovascular device firms with regulatory affairs infrastructure, and emerging aspirants seeking CE marking under EU MDR. Competitive positioning depends on backward integration into nitinol alloy processing, in-house laser-cut hypotube manufacturing, and captive supply of balloon guide systems. Geographic expansion into underpenetrated stroke networks and strategic partnerships with comprehensive stroke center procurement committees represent dominant competitive moves.
Among diversified medical technology conglomerates, Stryker Corporation and Medtronic plc occupy positions exemplifying integrated platform strategies. Stryker anchors North American catheter supply chains through in-house manufacturing capabilities. Medtronic competes across aspiration and stent-retriever portfolios with balloon guide integration. Penumbra, Inc. represents the dedicated neurovascular specialist archetype, with vacuum-assisted thrombectomy systems gaining protocol adoption in comprehensive stroke centers.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medtronic plc |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Penumbra, Inc. |
| Terumo Corporation |
| Teleflex Incorporated |
| Argon Medical Devices, Inc. |
| Inari Medical, Inc. |
| Others |
Supply & Pricing Matrix
Laser-cut hypotube engineering talent in Massachusetts and Minnesota commands wage premiums that compress margin spreads between premium and economy-tier catheter platforms. Labor-cost differentials between these specialized manufacturing clusters and emerging assembly locations in Mexico and Costa Rica translate into pricing-tier spreads of roughly thirty percent for equivalent device specifications.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent orders from scheduled procurement cycles, with comprehensive stroke centers paying fifteen to twenty percent premiums for same-week catheter delivery. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, ISO 13485 certification status, and bundled after-sales technical support. Pricing pressure stems from hospital procurement committees consolidating vendor relationships around full-platform contracts. Surgical hospitals with telestroke support exhibit highest price sensitivity; neurovascular centers with dedicated thrombectomy suites demonstrate lowest sensitivity due to outcome-based reimbursement differentials.
Supply Chain Analysis
Dual-sourcing requirements from Japan's PMDA and Germany's Federal Joint Committee mandate multi-supplier qualification for nitinol alloy feedstock, forcing device manufacturers to maintain validated relationships with at least two metallurgical processors. Geographic supply concentration centers on United States, Germany, and Japan for laser-cut hypotube manufacturing; nitinol raw material processing clusters in United States and Japan. Raw material dependencies include nickel-titanium superelastic alloys, platinum-iridium radiopaque markers, and medical-grade polymer extrusions. Single-source vulnerability in specialized nitinol melt capacity represents the dominant structural risk. Distribution runs through hospital procurement committees and group purchasing organizations with multi-year supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over nitinol alloy processing and in-house laser-cut hypotube manufacturing determines margin capture and supply security.
For Market Incumbents: Lock in backward integration into nitinol melt capacity and expand dedicated thrombectomy suite partnerships at comprehensive stroke centers in Houston and Phoenix. CE marking under EU MDR is filtering out marginal competitors; ISO 13485 certification investment represents the critical lever for procurement committee retention. Defend against aspiration-first protocol displacement by proving integrated platform performance in randomized trial evidence. For New Entrants and Emerging Players: Capture whitespace in India's tier-two city hub-and-spoke networks where mobile stroke unit deployment outpaces established supply infrastructure. CDSCO regulatory frameworks for class C and D medical devices create eighteen-to-twenty-four-month entry barriers that favor partnerships with domestic distributors possessing clinical trial navigation expertise. Target telestroke-coordinated surgical hospitals as the most penetrable end-user segment. For Investors and Strategic Acquirers: Re-rating potential sits with dedicated neurovascular specialists possessing vacuum-assisted thrombectomy platforms given aspiration-first protocol adoption in comprehensive stroke centers. Long-term viability across the next decade hinges on reimbursement parity with intravenous thrombolysis and health technology assessment body alignment. Watch for PMDA pre-market approval timeline compression as the inflection signal for Japan market entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance obligations now mandate ninety-day modified Rankin Scale outcome collection. |
| Hospital System Partnership | Bundled contracts covering aspiration catheters, stent retrievers, and balloon guides displace single-device purchasing. |
| Backward Integration | In-house nitinol alloy processing insulates margin capture from superelastic feedstock allocation volatility. |
| Software Companion Development | Artificial intelligence triage integration compresses door-to-puncture intervals for large vessel occlusion detection. |
| Reimbursement Strategy | Medicare severity-adjusted DRG differentials incentivize comprehensive versus primary stroke center capital investment. |
Research Methodology
FDA 510(k) clearance databases, CE marking notifications under EU MDR, and CMS Medicare reimbursement schedules formed the secondary backbone for device approval timeline and pricing benchmark analysis. Primary interviews with neurointerventionalists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers cross-validated procedural volume assumptions and procurement pattern shifts. Bottom-up and top-down triangulation reconciled manufacturer shipment data with hospital admission records for acute ischemic stroke.
Bottom-up modeling aggregated procedure volumes across comprehensive stroke centers, surgical hospitals, and emerging hub-and-spoke networks; top-down validation checked aggregate manufacturer revenue against macro healthcare expenditure trends. Segmentation dimensions included product architecture, therapy indication, end-user facility type, and delivery technology platform. CAGRs derived from logistic diffusion curves for mechanical thrombectomy protocol adoption, adjusted for PMDA approval lag effects and health technology assessment body reimbursement decisions.
The model holds under stable FDA 510(k) clearance timelines and continued Medicare DRG parity for mechanical thrombectomy; deviation in EU MDR post-market surveillance enforcement stringency or nitinol raw material export restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Sacroiliac Joint Fusion Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Middle East and Africa Non-Surgical Procedures Market
Medical Devices
Vortex Mixer Market
Medical Devices
Military Wearable Medical Device Market
Medical Devices
Pacemaker/Defibrillator Lead Extraction Kits Market
Medical Devices
Sputum Ejection Machine Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
Air Oxygen Blender Market
Medical Devices
Balloon Inflation Devices Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Epistaxis Devices Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market