
 Neonatal & Preterm Infant Enteral Feeding Devices Market | 2026-2036
Neonatal & Preterm Infant Enteral Feeding Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neonatal & Preterm Infant Enteral Feeding Devices Market Insights
Closed-loop enteral feeding with integrated flow sensors and alarm systems is tilting device architecture toward mechatronic platforms. Medtronic leverages its pump automation heritage to anchor premium NICU installations. Fresenius Kabi sustains European hospital channel control through specialized neonatal nutrition delivery systems. Cardinal Health competes on procurement scale, occupying broad distribution networks across North American pediatric facilities.
Neonatal and preterm infant enteral feeding devices comprise precision-engineered pumps, catheters, and gravity-fed systems designed to deliver measured breast milk or formula directly to the gastrointestinal tract of infants born before thirty-seven weeks gestation or weighing below 2.5 kilograms, with flow accuracy typically specified within 0.1 millilitre per hour increments to prevent aspiration or necrotizing enterocolitis. Feeding pumps dominate installed value in tertiary NICUs where continuous micro-volume delivery justifies capital expenditure, while silicone catheters gain preference over PVC alternatives as material biocompatibility standards harden. Home care settings represent the fastest-expanding end user channel, though hospital procurement still captures the deepest margin pools through bundled device-nutrition contracts.
FDA premarket notification requirements and the EU Medical Device Regulation shape material selection, sterilization validation, and clinical evidence thresholds for market access. The FDA's specific guidance on enteral feeding set safety and EMA's MDR classification of neonatal devices as Class IIa or higher compel manufacturers to maintain dedicated regulatory affairs functions. Stakeholders must monitor evolving reimbursement codes for home-based enteral nutrition as payer policies increasingly influence device selection criteria beyond clinical specifications alone.
Market Dynamics
Closed-loop enteral feeding systems with integrated flow sensors and alarm mechanisms are compressing installed equipment lifecycles across tertiary NICUs, forcing capital refresh decisions ahead of traditional replacement schedules.
Growth Catalysts
- EU MDR Class IIa reclassification:Stricter clinical evidence requirements for neonatal devices are filtering out marginal suppliers and concentrating procurement among validated manufacturers with dedicated regulatory affairs infrastructure.
- Home care channel expansion:Payer reimbursement codes for domiciliary enteral nutrition are extending device utilization beyond hospital discharge, creating secondary equipment demand from home health agencies.
- Silicone catheter substitution:Material biocompatibility standards hardening against PVC alternatives are redirecting catheter procurement toward medical-grade silicone formulations with lower thrombogenicity profiles.
Market Restraints
- Specialized polymer supply concentration:Medical-grade silicone and platinum-cured elastomer feedstocks concentrate among a limited supplier base in Germany and Japan, exposing device manufacturers to input cost volatility and allocation risk.
- FDA 510(k) clinical evidence thresholds:Premarket notification requirements for novel enteral feeding set designs are extending regulatory timelines and compressing returns on incremental product iterations.
- Gravity-fed system substitution:Low-acuity NICU settings and step-down units continue deploying non-pump alternatives for intermittent feeding protocols, capping premium pump penetration in cost-constrained facilities.
Strategic Opportunities
- Japanese metropolitan NICU network expansion:METI-funded perinatal center consolidation in Tokyo, Osaka, and Nagoya is creating bundled procurement opportunities for integrated feeding-nutrition systems.
- Sensor-embedded catheter convergence:Integration of micro-pressure transducers with enteral access devices is enabling real-time intragastric pressure monitoring, differentiating premium offerings from commodity alternatives.
- US CMS home health reimbursement expansion:Medicare and Medicaid policy shifts toward covering enteral nutrition equipment for qualifying preterm infant discharge populations are accelerating home care channel development.
Industry Challenges
- Biomedical engineering talent scarcity:NICU device development requires specialized expertise in microfluidics and neonatal physiology that concentrates among limited academic and industrial training pipelines.
- Legacy pump fleet interoperability:Tertiary hospitals face integration complexity when connecting new sensor-enabled feeding systems to existing electronic health record architectures and alarm management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neonatal & Preterm Infant Enteral Feeding Devices Market |
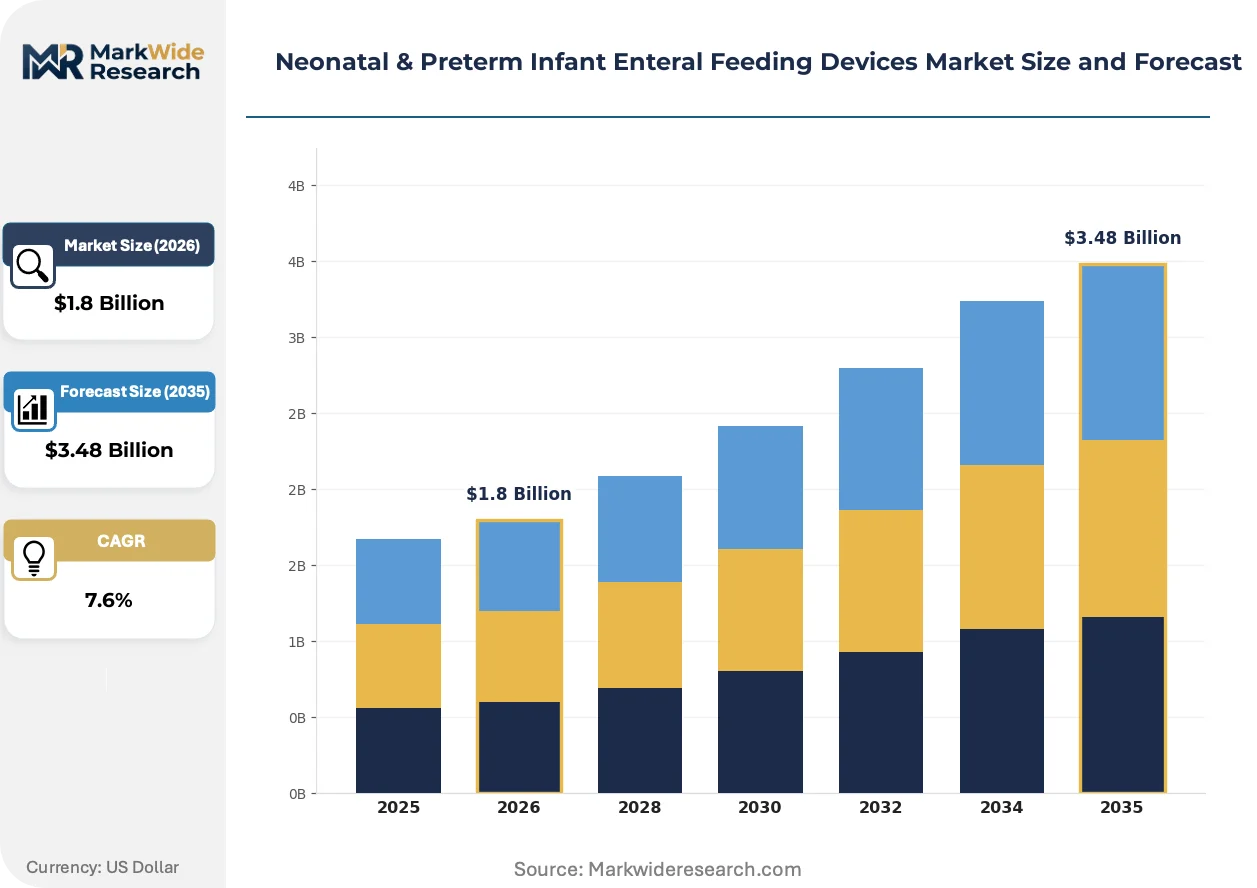
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Feeding Pumps, Syringe Pumps, Gravity Feeders, Catheters Material: Polycarbonate, Polypropylene, Silicone, PVC End User: Neonatal Intensive Care Units, Pediatric Hospitals, Home Care Settings, Outpatient Clinics Distribution Channel: Direct Sales, Online Sales, Medical Distributors, Hospital Procurement |
| Companies Covered | Medtronic, Fresenius Kabi, Cardinal Health, Abbott Laboratories, Amsino International, Applied Medical Technology, Moog Medical Devices, Avanos Medical, Qosina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neonatal & Preterm Infant Enteral Feeding Devices Market Trends and Innovations
Enteral feeding device architecture is converging with mechatronic platforms, compressing the boundary between precision fluid delivery and patient monitoring systems across neonatal care settings.
Smart enteral feeding pumps with integrated load cells and occlusion detection algorithms are hybridizing traditional volumetric delivery with continuous physiological feedback. Tertiary NICU departments in the United States and Germany are prioritizing these systems for infants below 1,000 grams birth weight. The technology is hybridizing capital procurement decisions, forcing hospitals to evaluate pumps as monitoring investments rather than isolated nutrition delivery tools.
REACH restrictions on phthalate plasticizers and EU MDR substance disclosure requirements are accelerating material transitions across European supply chains. Manufacturers must reformulate PVC components or complete validated substitutions to medical-grade thermoplastic elastomers. Neonatal catheter and tubing segments face the steepest compliance burden, with German notified bodies requiring extended biocompatibility testing protocols.
Hospital procurement departments are unbundling device acquisition from enteral nutrition formula supply, reversing historical bundled contracting structures. Pediatric facilities in Japan and the United States are separating pump capital expenditure from recurring nutrition purchases to improve cost transparency. This pattern is most pronounced in academic medical centers with dedicated value analysis committees overseeing neonatal product selection.
Neonatal & Preterm Infant Enteral Feeding Devices Market Segmentation
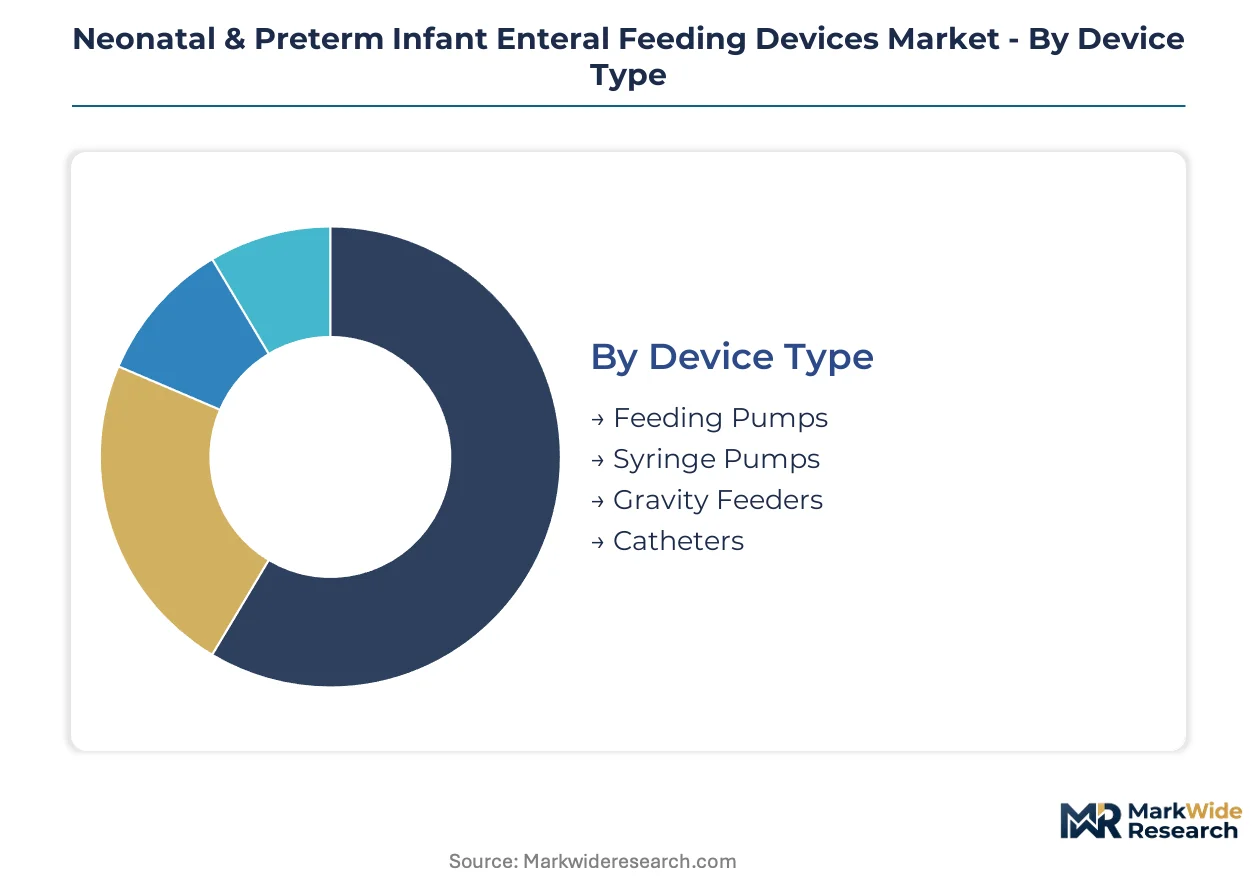
Device segmentation in neonatal enteral feeding reflects divergent clinical workflows across acute and transitional care settings. Procurement patterns split between capital-intensive pump installations in tertiary NICUs and disposable-heavy models for home discharge pathways.
Device Type:
Clinical acuity determines device selection across the neonatal care continuum.
- Feeding Pumps:Precision volumetric pumps deliver continuous micro-flows calibrated to 0.1 millilitre per hour increments for infants below 1,000 grams. Tertiary NICUs in the United States and Germany prioritize these systems for their integration with electronic health record alarm management platforms.
- Syringe Pumps:These compact devices enable intermittent bolus delivery with programmable occlusion pressure limits. Pediatric hospitals in Japan favor syringe pumps for their smaller footprint in space-constrained neonatal units.
- Gravity Feeders:Passive flow systems rely on height differential without electronic control. Step-down units and cost-constrained facilities deploy gravity feeders for stable infants transitioning to oral feeding.
- Catheters:Silicone and polyurethane formulations provide enteral access with varying durometer stiffness for premature gastrointestinal anatomy. Home care agencies source catheters through specialized enteral nutrition distributors.
The dominant share belongs to Feeding Pumps, while Home Care Settings are expanding catheter and gravity feeder volumes fastest.
Material:
Regulatory pressure on polymer biocompatibility is restructuring supplier relationships across device categories.
- Silicone:Platinum-cured medical-grade silicone offers superior thrombogenicity profiles and thermal stability for long-dwell catheters. German notified bodies under EU MDR mandate extended biocompatibility testing for silicone formulations in neonatal applications.
- PVC:Phthalate-plasticized polyvinyl chloride faces REACH restrictions and EMA substance disclosure requirements. Manufacturers reformulating legacy tubing sets confront validation timelines that extend procurement cycles.
- Polycarbonate:Transparent, impact-resistant polymer serves pump housings and connector bodies requiring visual flow monitoring. Japanese device makers specify polycarbonate for its compatibility with gamma sterilization protocols.
- Polypropylene:Lightweight, chemically resistant material appears in disposable syringe barrels and enteral feeding set components. Polypropylene cost advantages support high-volume home care disposables.
Silicone commands premium positioning in catheter segments, with PVC substitution accelerating most quickly under European regulatory timelines.
End User:
Care setting determines performance requirements and reimbursement pathways for device procurement.
- Neonatal Intensive Care Units:Tertiary NICUs demand closed-loop systems with integrated flow sensors and alarm integration. These facilities capture the deepest margin pools through bundled device-nutrition contracts.
- Home Care Settings:Domiciliary enteral nutrition programs require portable pumps and simplified catheter systems for parental administration. CMS reimbursement expansion for qualifying preterm infant discharges is accelerating equipment demand from home health agencies.
- Pediatric Hospitals:General pediatric units without dedicated NICU infrastructure utilize intermediate-complexity devices for late-preterm infants. These facilities balance acquisition cost against clinical capability.
- Outpatient Clinics:Limited enteral feeding needs in ambulatory settings concentrate on catheter maintenance and feeding tube replacement. Outpatient volume remains constrained by procedure reimbursement limitations.
NICU installations generate the highest per-unit revenue, though Home Care Settings are climbing the fastest as payer policies extend coverage beyond hospital discharge.
Distribution Channel:
Channel strategy reflects capital equipment versus consumable economics and customer scale.
- Hospital Procurement:Centralized purchasing committees in academic medical centers negotiate bundled contracts spanning pumps, catheters, and enteral formula. Value analysis oversight in US teaching hospitals is unbundling device acquisition from nutrition supply.
- Medical Distributors:Specialized enteral nutrition distributors maintain inventory breadth for home care agencies and smaller pediatric facilities. Cardinal Health and regional players compete on logistics coverage and technical support.
- Direct Sales:Manufacturers deploy clinical specialists for pump installations and staff training in tertiary NICUs. Direct relationships secure replacement consumable commitments over equipment lifecycle.
- Online Sales:E-commerce channels serve home care patients and outpatient clinics with standardized catheter and gravity feeder replenishment. Online penetration remains limited by reimbursement documentation requirements.
Hospital Procurement captures the largest transaction values, with Medical Distributors gaining share fastest in the expanding home care channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision enteral feeding pumps to tertiary NICUs across the United States and Japan, establishing a high-value trade corridor that concentrates advanced device deployment in metropolitan hospital networks.
United States
CMS reimbursement expansion for home-based enteral nutrition and tertiary NICU consolidation in Boston and Houston drive device procurement. FDA 510(k) premarket notification requirements shape material validation timelines for silicone catheter introductions. The Southeast corridor from Atlanta to Florida anchors distribution networks serving expanding perinatal centers.
Germany
EU MDR Class IIa reclassification filters supplier bases while METI-funded perinatal networks in partner countries absorb exported systems. ECHA REACH restrictions on phthalate plasticizers accelerate silicone formulation transitions across Baden-Württemberg manufacturing clusters. The Rhine-Ruhr metropolitan zone concentrates notified body relationships and sterilization validation capacity.
Japan
Perinatal center consolidation in Tokyo, Osaka, and Nagoya creates bundled procurement opportunities for integrated feeding-nutrition systems. PMDA device classification protocols align with EMA standards for neonatal Class IIa submissions. The Kansai industrial belt hosts specialized polymer compounders supplying platinum-cured silicone feedstocks.
United Kingdom
NHS specialized commissioning for neonatal intensive care concentrates procurement authority in academic medical centers across London and Manchester. MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment pathways. The Cambridge-Oxford corridor anchors biomedical engineering talent pipelines for microfluidic device development.
China
Domestic NICU infrastructure expansion in Shanghai and Guangzhou absorbs imported precision pumps while local manufacturers scale gravity-fed alternatives. NMPA medical device registration requirements tighten clinical evidence standards for neonatal applications. The Yangtze River Delta concentrates contract manufacturing capacity for silicone catheter assembly.
Neonatal & Preterm Infant Enteral Feeding Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments where hospital value analysis committees unbundle device acquisition from nutrition supply. The vendor base concentrates among diversified medical technology conglomerates with dedicated neonatal divisions and mid-cap specialists with focused enteral feeding portfolios. Three archetypes dominate: diversified conglomerates leveraging pump automation heritage, nutrition-integrated suppliers controlling formula-device bundles, and regional distributors capturing home care channel expansion. Competitive moves center on regulatory affairs infrastructure scaling and sensor-embedded catheter convergence for real-time monitoring differentiation.
Among diversified medical technology conglomerates, Medtronic and Fresenius Kabi occupy positions anchoring premium-tier installations through automation heritage and European hospital channel control respectively. Cardinal Health exemplifies the distribution-scale archetype, with North American logistics networks spanning pediatric facility procurement. These three represent distinct competitive vectors: technology integration, nutrition-device bundling, and procurement scale.
| Leading Market Players |
|---|
| Medtronic |
| Fresenius Kabi |
| Cardinal Health |
| Abbott Laboratories |
| Amsino International |
| Applied Medical Technology |
| Moog Medical Devices |
| Avanos Medical |
| Qosina |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in German platinum-cured silicone compounding is tightening feedstock allocation for neonatal catheter manufacturers, compressing margins for device makers unable to secure long-term supply commitments while forcing premium pricing for validated medical-grade formulations.
Pricing Analysis
Next-generation sensor-embedded feeding pumps command substantial premiums over gravity-fed alternatives and legacy volumetric systems. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) clearance status and EMA MDR Class IIa certification level. Cost compression in standard-tier pumps is intensifying because hospital value analysis committees are unbundling device acquisition from nutrition supply contracts. Home care agencies exhibit the highest price sensitivity, while tertiary NICU procurement committees prioritize clinical integration over unit cost.
Supply Chain Analysis
Medical-grade silicone feedstocks draw from specialized compounders in Germany, Japan, and the United States. Platinum-cured elastomer and polycarbonate resin dependencies expose device manufacturers to allocation risk during polymer production cycles. Single-source vulnerability concentrates around notified body sterilization validation capacity in the Rhine-Ruhr metropolitan zone. Distribution runs through specialized enteral nutrition distributors serving home care channels alongside direct sales teams for hospital pump installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neonatal device development hinges on scarce expertise in microfluidics and neonatal physiology, creating durable competitive moats for firms with established biomedical engineering pipelines and regulatory affairs infrastructure.
For Market Incumbents: Insulate premium pump installations by securing exclusive catheter supply agreements with German silicone compounders, while accelerating FDA 510(k) submissions for sensor-integrated next-generation systems before EU MDR Class IIa reclassification fully consolidates supplier bases. Threats from home care channel specialists and formula-device unbundling demand proactive reimbursement strategy investment. For New Entrants and Emerging Players: Establish a beachhead in Japanese metropolitan NICU networks where METI-funded perinatal center consolidation is creating procurement windows for integrated feeding-nutrition systems. Home care catheter replacement cycles offer the most penetrable entry point, with simplified gravity-fed designs enabling distributor partnerships without capital-intensive pump development. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with installed pump fleets generating captive catheter replacement demand. Long-term viability across the analysis window favors targets with vertical integration into medical-grade silicone sourcing and established notified body relationships. Watch FDA guidance evolution on enteral feeding set safety as an inflection indicator for regulatory compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Accelerated clearance timelines differentiate sensor-enabled pumps from legacy alternatives in tertiary NICU procurement. |
| EU MDR Class IIa Certification Pathway | Extended biocompatibility testing protocols filter marginal suppliers and consolidate market share among validated manufacturers. |
| Hospital System Partnership | Bundled device-nutrition contracts with academic medical centers secure replacement consumable commitments over equipment lifecycle. |
| Software Companion Development | EHR alarm management integration transforms pumps from isolated tools into monitoring infrastructure investments. |
| Reimbursement Strategy | CMS home health code expansion for qualifying preterm infant discharges unlocks secondary equipment demand from home health agencies. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across tertiary NICU departments, home care agencies, and device manufacturing operations. Primary interviews with neonatologists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers were cross-referenced against FDA 510(k) filings, EMA MDR submission databases, CMS reimbursement code updates, and hospital procurement records. Bottom-up equipment installation counts and top-down market sizing were triangulated to validate volume estimates.
Calibration against historical CAGR patterns and regulatory timeline impacts shaped the projection framework across device type, material formulation, end user setting, and distribution channel dimensions. Modeled inputs incorporated EU MDR reclassification compliance costs, silicone feedstock price trajectories, and home care reimbursement expansion scenarios. Growth rates were derived from segment-level demand elasticity and replacement cycle analysis.
Sensitivities concentrate around FDA premarket notification timeline extensions, German silicone supplier allocation decisions, and Japanese perinatal center consolidation pace. Forecasts reflect documented assumptions regarding regulatory compliance cost pass-through and hospital capital expenditure priorities. Cross-checking against GPO contract disclosure databases and notified body certification registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Organ Care Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
Global Doppler Ultrasound Systems Market
Medical Devices
Diabetes Devices Market
Medical Devices
Healthcare Additive Manufacturing Market
Medical Devices
Pannus Retraction Device Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Human Enhancement Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Global Heart Valve Devices Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
Skull Deformity Implants Market
Medical Devices
Asia-Pacific Ambulatory Infusion Pumps Market
Medical Devices
Solar Surgical Light Market
Medical Devices
United Kingdom Ultrasound Devices Market