
 Artificial Vital Organs and Medical Bionics Market | 2026-2036
Artificial Vital Organs and Medical Bionics Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Vital Organs and Medical Bionics Market Intelligence
The capital-intensity divergence between integrated device manufacturers and component suppliers is unwinding traditional competitive boundaries in this space. Medtronic plc leverages its vertically structured cardiac rhythm portfolio to sustain manufacturing scale across implantable pacemakers and ventricular assist systems. Berlin Heart GmbH anchors its position through specialized pediatric mechanical circulatory support devices that occupy a narrow but defensible clinical niche.
Artificial vital organs and medical bionics encompass electromechanical and biological systems engineered to replace or augment native organ function, typically incorporating biocompatible alloys, polymer membranes, and miniaturized power transfer mechanisms operating at physiological thresholds. The primary commercial purpose centers on extending survival and restoring sensorimotor capability in patients with end-stage organ failure or traumatic limb loss. Cardiac devices command the dominant revenue position within product type segmentation, while neuromodulation devices represent the fastest-expanding margin pool driven by chronic pain and movement disorder indications. Robotics and synthetic biology within technology segmentation are attracting disproportionate R&D allocation as manufacturers seek programmable, adaptive tissue interfaces.
FDA premarket approval pathways and EU MDR conformity assessments shape product development timelines and market access costs for device developers across North America and Europe. Japan's PMDA and South Korea's MFDS impose additional clinical evidence requirements that filter entrants and concentrate commercial activity among established multinationals. Stakeholders must monitor evolving reimbursement thresholds for bioengineered implants and the shifting liability landscape around AI-enabled bionic control systems.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins and forcing device manufacturers to absorb lifecycle service costs that previously generated recurring revenue streams.
Growth Catalysts
- EU MDR Compliance Deadlines:Stricter conformity assessment timelines are filtering marginal competitors and concentrating procurement among established suppliers with notified body relationships.
- Japan's Reimbursement Expansion:PMDA pathway maturation for ventricular assist devices and neural implants is unlocking hospital budget allocation for high-acuity interventions.
- Biocompatible Polymer Membranes:Advances in thromboresistant surface engineering are reducing anticoagulant dependency and expanding implantable cardiac device candidacy.
Market Restraints
- Palladium and Platinum Volatility:Electrode and capacitor raw material cost swings squeeze gross margins on pacemakers and neurostimulators without pricing pass-through mechanisms.
- Single-Source Component Dependency:Miniaturized inductive charging coils and hermetic feedthroughs concentrate among German and Swiss precision manufacturers, creating supply vulnerability.
- Battery Chemistry Limitations:Lithium-iodine cell energy density constraints enforce replacement surgery cycles that limit total addressable patient lifetime value.
Strategic Opportunities
- India's CDSCO Streamlining:Medical device rules harmonization with IMDRF standards is reducing registration timelines for cardiac rhythm and neuromodulation products.
- Closed-Loop Neural Control:Convergence of embedded machine learning inference with sub-threshold stimulation protocols enables adaptive pain and movement disorder therapy.
- Direct-to-Provider Distribution:Bypassing distributor markups through hospital system GPO contracts captures margin and deepens clinical training relationships.
Industry Challenges
- Electrophysiology-AI Hybrid Talent Scarcity:Recruitment of engineers fluent in both neural signal processing and regulatory quality systems lags R&D pipeline demands.
- ISO 14155 Clinical Trial Complexity:Multinational investigational device exemption coordination consumes 18-24 month lead times before PMA submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Vital Organs and Medical Bionics Market |
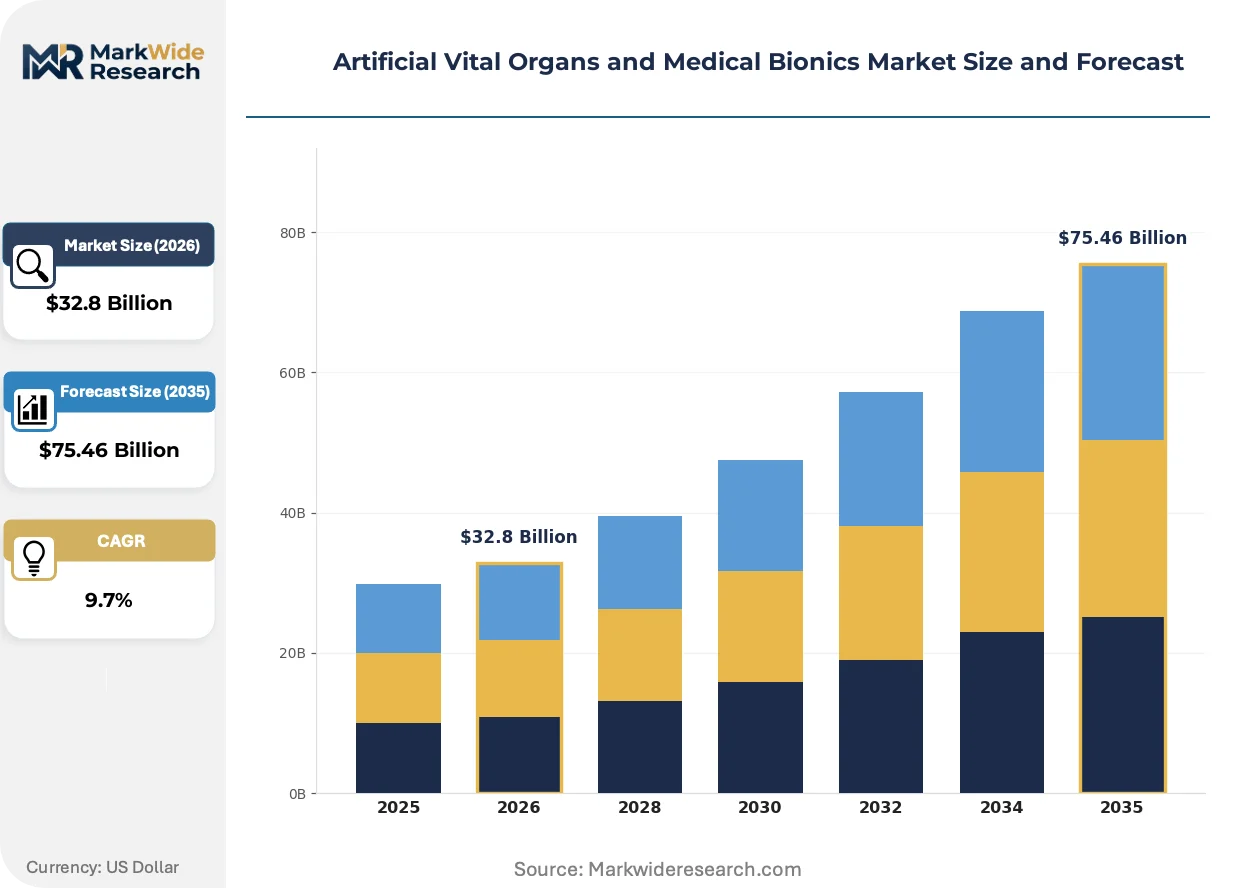
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $75.46 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Devices, Renal Devices, Neuromodulation Devices, Prosthetics Application: Organ Replacement, Functional Restoration, Pain Management, Neurological Disorders End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Technology: Bioengineering, Nanotechnology, Robotics, Synthetic Biology |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Edwards Lifesciences Corporation, Abiomed Inc., Cochlear Ltd., Ekso Bionics Holdings Inc., Berlin Heart GmbH, Zimmer Biomet Holdings Inc., Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Vital Organs and Medical Bionics Market Strategic Shifts & Innovations
Programmable tissue interfaces are replacing fixed-function electromechanical implants, enabling post-implant therapy adjustment without surgical revision.
Leadless pacemaker technology is displacing transvenous systems in bradyarrhythmia management. Electrophysiology departments at tertiary centers in Germany and the United States are prioritizing catheter-delivered devices for infection-risk reduction. This shift is compressing the addressable market for traditional pulse generator and lead portfolios while expanding procedure volume in interventional cardiology suites.
EU MDR Article 117 requirements for device-drug combination products are forcing resubmission of heparin-coated cannulas and antibiotic-impregnated drivelines. Manufacturers with legacy CE certificates face notified body backlogs extending conformity assessment timelines. Cardiac assist device developers are responding by segregating pharmaceutical coating supply chains from mechanical component manufacturing to isolate regulatory risk.
Hospital value analysis committees now require total cost-of-ownership modeling that incorporates device longevity, explant probability, and complication-related readmission expense. This behavioral shift favors suppliers with longitudinal outcome data over those competing on acquisition price alone. The United States academic medical center segment exhibits the most pronounced migration toward lifecycle contracting frameworks.
Artificial Vital Organs and Medical Bionics Market Segmentation
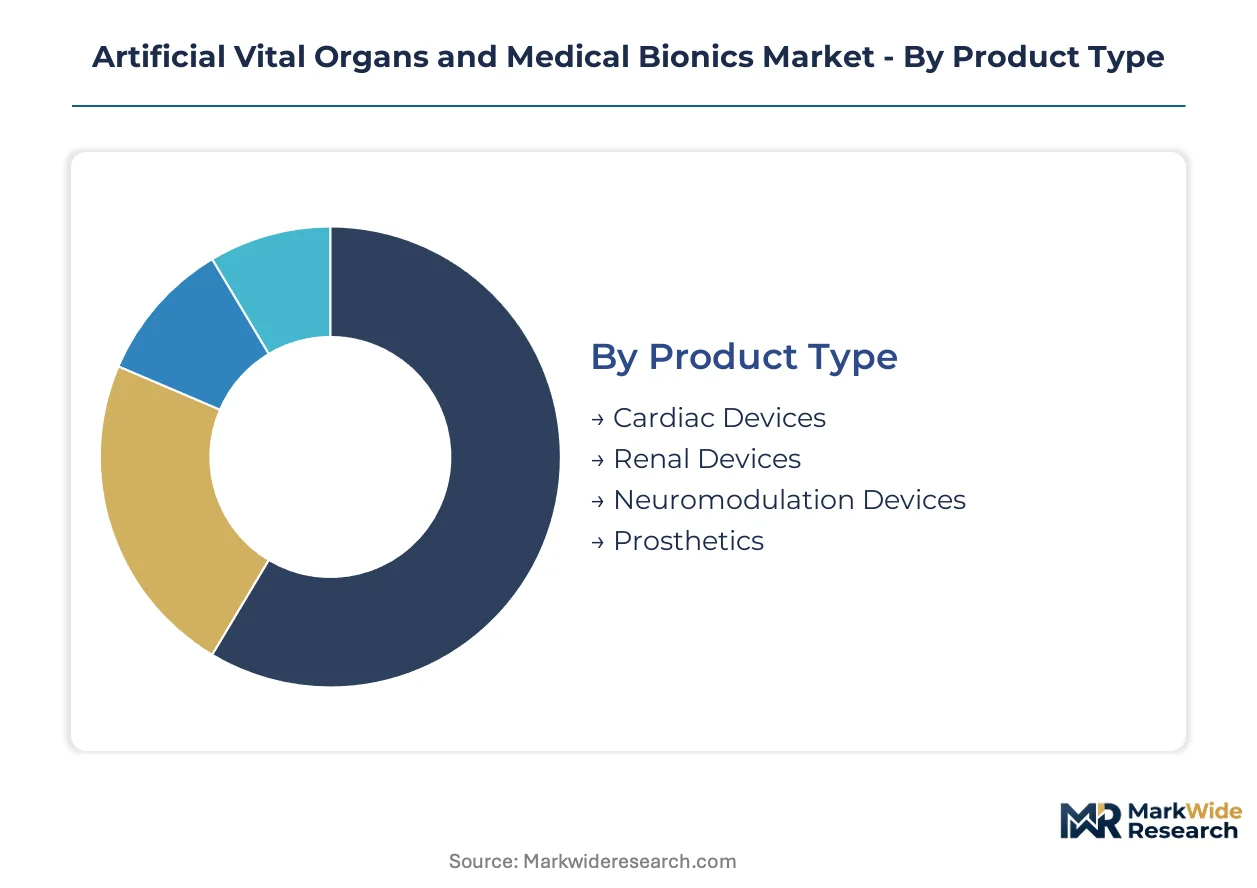
Segmentation in artificial vital organs and medical bionics reveals divergent competitive intensity across therapeutic domains. Substitution threats from pharmaceutical alternatives and minimally invasive procedures reshape investment allocation across product categories.
Product Type:
Cardiac devices face intensifying substitution pressure from catheter-based ablation therapies and heart failure pharmacology, while prosthetics confront lower threat levels due to irreversible limb loss physiology.
- Cardiac Devices:Encompass ventricular assist systems, total artificial hearts, and implantable rhythm management hardware fabricated from titanium alloys and biocompatible polymers. Demand concentrates in German university hospitals and United States academic medical centers where ECMO-to-VAD bridge protocols have standardized; anticoagulant burden and driveline infection risk constrain candidacy expansion.
- Neuromodulation Devices:Include spinal cord stimulators, deep brain stimulators, and vagus nerve stimulators delivering targeted electrical impulses via implanted pulse generators. Adoption clusters in Japanese pain management centers and United States movement disorder clinics; closed-loop feedback algorithms and rechargeable battery architectures are displacing fixed-output systems.
- Renal Devices:Wearable and implantable artificial kidney prototypes utilizing hemofiltration membranes and electrochemical regeneration. Experimental-stage devices target dialysis-dependent populations in dialysis centers.
- Prosthetics:Myoelectric and osseointegrated limb replacement systems with sensorimotor feedback capabilities. German and Japanese rehabilitation institutes drive demand for bionic hand and lower-limb configurations.
Cardiac devices retain volume leadership; neuromodulation devices hold the steepest expansion curve.
Application:
Cost tier stratification separates acute surgical intervention from chronic disease management, with organ replacement commanding premium pricing and pain management operating at lower reimbursement thresholds.
- Organ Replacement:Definitive surgical substitution of failed native organs with mechanical or biohybrid alternatives. United States transplant centers and German cardiac surgery departments allocate capital budgets for ventricular assist device implantation; donor organ scarcity sustains mechanical bridge-to-transplant demand.
- Neurological Disorders:Deep brain stimulation for Parkinson's disease, essential tremor, and epilepsy. Japanese neurology clinics and United States functional neurosurgery programs are expanding deep brain stimulation candidacy; directional lead technology improves therapeutic window precision.
- Functional Restoration:Sensorimotor recovery through neural-controlled prosthetics and exoskeleton systems. Military rehabilitation facilities and civilian trauma centers in the United States prioritize upper-limb bionic restoration.
- Pain Management:Spinal cord and peripheral nerve stimulation for chronic refractory pain. Outpatient pain clinics in Germany and the United States are transitioning to burst and high-frequency stimulation paradigms.
Organ replacement captures the highest reimbursement intensity; neurological disorders are climbing the fastest.
End User:
Customer type determines procurement complexity, with hospital systems leveraging GPO leverage and home care requiring simplified user interfaces and remote monitoring infrastructure.
- Hospitals:Tertiary and quaternary centers performing implantation surgery and acute device management. United States academic medical centers and German university hospitals concentrate cardiac and neural implant volumes; value analysis committees now mandate total cost-of-ownership modeling.
- Rehabilitation Centers:Post-acute facilities specializing in prosthetic fitting and neurorehabilitation. Japanese and German rehabilitation institutes lead osseointegrated prosthetic adoption; bionic limb training protocols extend length-of-stay.
- Clinics:Ambulatory settings managing device programming and non-surgical follow-up. Pain management and movement disorder clinics in the United States handle neuromodulator adjustment and battery replacement.
- Home Care:Patient-directed management of wearable renal assist devices and external cardiac support systems. Remote monitoring platforms enable driveline and power supply oversight outside institutional settings.
Hospitals dominate procurement volume; home care is gaining share fastest.
Technology:
Maturity gradients separate established bioengineering platforms from emerging synthetic biology approaches, with R&D allocation shifting toward programmable and self-regulating tissue interfaces.
- Bioengineering:Established discipline integrating biocompatible materials, mechanical design, and physiological modeling. Titanium and cobalt-chrome alloys, ePTFE membranes, and hermetic sealing technologies underpin current-generation cardiac and renal devices.
- Synthetic Biology:Engineered biological systems and gene circuits enabling living tissue-device integration. Research-stage applications include biohybrid kidneys with cellular metabolic function and immunomodulatory implant coatings.
- Robotics:Powered exoskeletons, surgical implantation systems, and neural-controlled prosthetic limbs. Japanese rehabilitation robotics and United States military amputee programs drive exoskeleton and bionic limb development.
- Nanotechnology:Surface modification, drug-eluting coatings, and biosensor miniaturization at sub-micron scales. Thromboresistant nanostructured surfaces and glucose-responsive membranes are in preclinical evaluation.
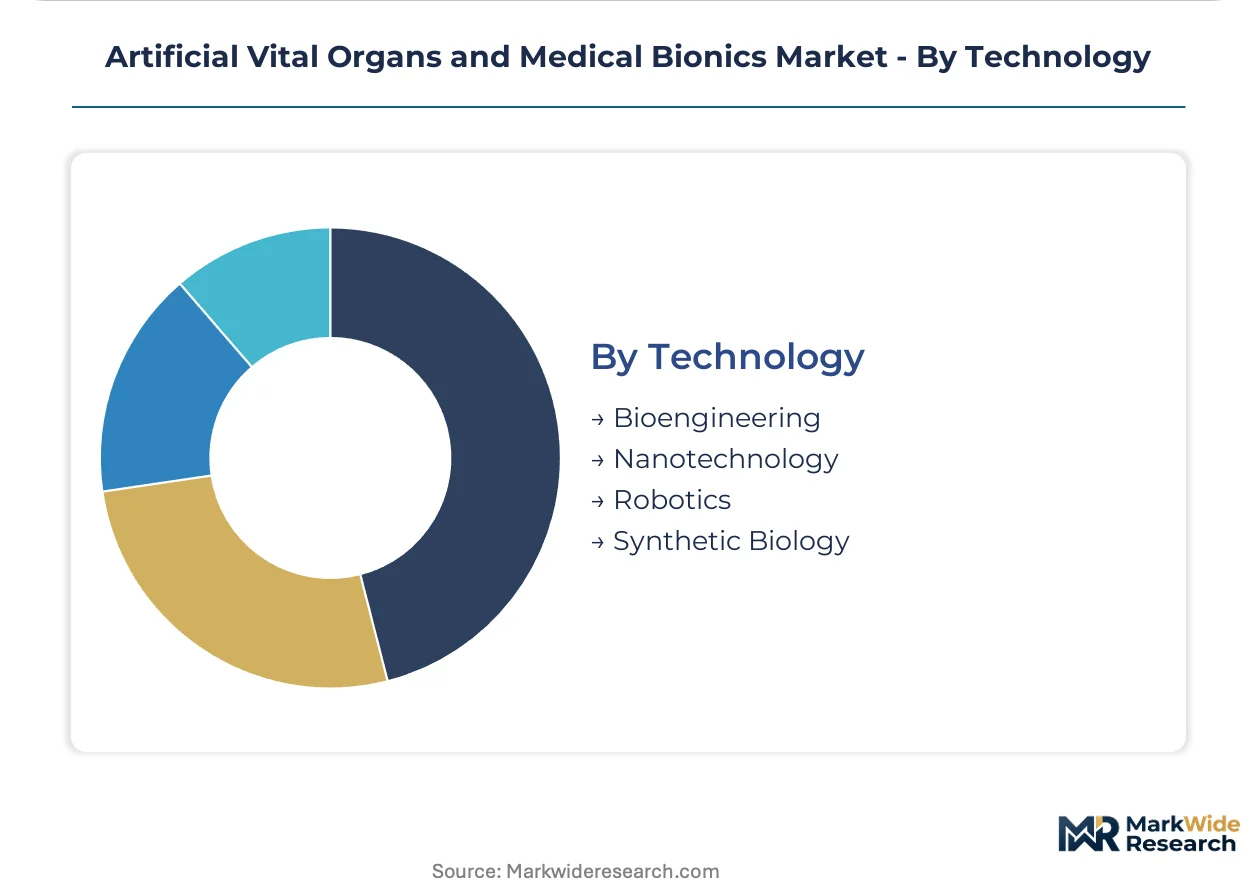
Bioengineering retains commercial dominance; synthetic biology holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds German levels by roughly 40 percent for comparable ventricular assist devices, while Japanese reimbursement authorities impose reference pricing that compresses margins for neuromodulation hardware.
United States
Academic medical centers in Boston and Houston drive procurement volumes for implantable cardiac rhythm devices and mechanical circulatory support systems. FDA premarket approval pathways enforce 18-24 month clinical evidence timelines that filter marginal entrants. The Cleveland Clinic and Mayo Clinic anchor device evaluation protocols that shape hospital purchasing committee standards nationwide.
Germany
University hospitals in Berlin and Munich concentrate implantation volumes for ventricular assist devices and total artificial hearts. EU MDR Article 117 conformity assessments for device-drug combinations extend regulatory timelines for heparin-coated cannulas. The Bad Oeynhausen Heart Center and Heidelberg University Hospital coordinate notified body relationships that accelerate market access for compliant manufacturers.
Japan
Pain management clinics in Tokyo and Osaka drive adoption of spinal cord stimulators and deep brain stimulators for movement disorders. PMDA reimbursement expansion for ventricular assist devices unlocks hospital capital allocation for high-acuity cardiac interventions. The National Cerebral and Cardiovascular Center in Osaka anchors clinical evidence generation for neural implant candidacy expansion.
India
Cardiac surgery departments in Mumbai and Delhi generate demand for affordable ventricular assist device alternatives and pacemaker systems. CDSCO medical device rules harmonization with IMDRF standards compresses registration timelines for cardiac rhythm products. The All India Institute of Medical Sciences in Delhi and Fortis Escorts Heart Institute in New Delhi concentrate physician training for implantable device procedures.
South Korea
Rehabilitation institutes in Seoul and Busan prioritize osseointegrated prosthetic limbs and exoskeleton systems for traumatic amputees. MFDS clinical evidence requirements for neural implants filter market entry toward established multinationals with Korean subsidiary infrastructure. The Seoul National University Hospital and Samsung Medical Center anchor prosthetic fitting protocols that influence regional procurement standards.
Artificial Vital Organs and Medical Bionics Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated device manufacturers sustaining scale through vertically structured cardiac portfolios while specialized component suppliers capture margin in miniaturized power transfer and hermetic sealing technologies. The market structure concentrates procurement authority among hospital GPOs and academic medical center value analysis committees that mandate total cost-of-ownership modeling. Three archetypes dominate: diversified multinationals with rhythm management scale, pediatric mechanical circulatory support specialists occupying narrow clinical niches, and precision component fabricators supplying inductive charging and feedthrough subsystems. Competitive moves center on M&A to secure notified body relationships under EU MDR timelines and direct-to-provider distribution contracts that bypass traditional distributor markups.
Among diversified multinationals, Medtronic plc and Boston Scientific Corporation occupy positions exemplifying integrated cardiac rhythm and neuromodulation scale. Berlin Heart GmbH represents the specialized pediatric mechanical circulatory support archetype with concentrated expertise in narrow clinical indications. Cochlear Ltd. anchors the neural implant specialist tier with focused cochlear and auditory brainstem system positioning. These three companies illustrate the strategic segmentation between broad portfolio breadth, clinical niche depth, and sensory restoration specialization that shapes competitive dynamics across procurement negotiations and regulatory pathway investments.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Edwards Lifesciences Corporation |
| Abiomed Inc. |
| Cochlear Ltd. |
| Ekso Bionics Holdings Inc. |
| Berlin Heart GmbH |
| Zimmer Biomet Holdings Inc. |
| Terumo Corporation |
| Others |
Cost & Logistics Intelligence
Leadless pacemaker migration from transvenous systems is simultaneously relocating manufacturing capacity toward catheter-delivered device specialists in Germany and the United States while compressing pricing premiums for traditional pulse generator portfolios. This substitution dynamic concentrates procurement leverage among interventional cardiology suites and forces legacy manufacturers to absorb service lifecycle costs previously monetized through lead replacement revenue streams.
Pricing Analysis
The customization-premium spread between patient-configured neuromodulation systems and standard-output devices reaches widest divergence in Japanese pain management centers and United States academic medical centers. Pricing stratifies across premium, standard, and economy tiers driven by rechargeable battery architecture and closed-loop algorithm sophistication. Cost compression in the standard tier intensifies as hospital value analysis committees mandate total cost-of-ownership modeling that incorporates explant probability and complication-related readmission expense. German university hospitals exhibit least price sensitivity due to EU MDR compliance investment recovery timelines, while Indian cardiac surgery departments in Mumbai and Delhi demonstrate highest sensitivity to acquisition price.
Supply Chain Analysis
Extended inventory cycles for hermetic feedthroughs and miniaturized inductive charging coils signal supply concentration among Swiss and German precision manufacturers. Geographic supply concentration centers on Germany for mechanical circulatory support components, Switzerland for hermetic sealing technologies, and Japan for biocompatible polymer membrane fabrication. Raw material dependencies rest on palladium and platinum for neurostimulator electrodes, lithium-iodine cells for pulse generator power, and titanium alloys for implantable housings. Single-source vulnerability concentrates in notified body relationships under EU MDR Article 117 timelines. Distribution runs through hospital system GPO contracts that bypass traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial vital organs and medical bionics market functions as a defensive-moat arena where regulatory entrenchment through FDA premarket approval and EU MDR conformity assessment creates prohibitive switching costs for hospital procurement committees.
For Market Incumbents: Secure notified body relationships under compressed EU MDR timelines to defend against emerging entrants lacking conformity assessment infrastructure. Deepen backward integration into biocompatible polymer membrane supply to isolate pharmaceutical coating regulatory risk from mechanical component manufacturing. Capacity concentration in German university hospital corridors and United States academic medical center networks reinforces procurement committee influence over device evaluation protocols. For New Entrants and Emerging Players: Anchor in India's CDSCO streamlined registration pathway for cardiac rhythm products to bypass FDA and EU MDR timeline barriers that filter established competitors. Target white-space in wearable renal assist devices for home care settings where remote monitoring platforms enable patient-directed management outside institutional procurement. Pursue direct-to-provider distribution contracts that capture margin and deepen clinical training relationships with hospital system GPOs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision component fabricators supplying hermetic feedthroughs and inductive charging subsystems to tier-one device manufacturers. Long-term viability centers on programmable tissue interface capabilities across the 5-10 year innovation horizon. Acquisition priority targets component suppliers with captive relationships to German and Swiss notified bodies. The inflection signal to monitor is FDA breakthrough device designation volume for closed-loop neural control systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket approval timelines for closed-loop neuromodulation systems in United States academic medical centers. |
| EU MDR Notified Body Partnership | Secures conformity assessment capacity for heparin-coated cannula resubmissions under Article 117 requirements. |
| Hospital System GPO Contract | Captures procurement volume from value analysis committees mandating total cost-of-ownership modeling. |
| Reimbursement Strategy Development | Unlocks PMDA budget allocation for ventricular assist devices in Japanese cardiac surgery departments. |
| Software Companion Development | Enables adaptive pain therapy algorithms for spinal cord stimulators in outpatient pain clinics. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with implanting physicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through FDA premarket approval filings, EU MDR notified body registers, CMS Medicare reimbursement databases, and hospital procurement contract disclosures. Bottom-up triangulation across device shipment volumes and top-down reconciliation against hospital capital expenditure reports anchored market sizing.
Across the analysis window, the forecast framework modeled product type segmentation by cardiac devices, neuromodulation systems, renal devices, and prosthetics; application segmentation across organ replacement, neurological disorders, functional restoration, and pain management; and technology segmentation spanning bioengineering, synthetic biology, robotics, and nanotechnology. CAGRs were derived from procedure volume elasticity to reimbursement expansion and regulatory pathway maturation. Industry-specific inputs incorporated EU MDR compliance deadline acceleration and PMDA ventricular assist device reimbursement expansion.
Decision-makers should treat outputs as directional under assumptions of stable palladium and platinum input costs and sustained hospital GPO consolidation; material deviation in raw material volatility or procurement authority concentration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Biologic Injectors Market
Medical Devices
Automated CPR Devices Market
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Global Vaginal Sling Market
Medical Devices
North America Arthroscopy Devices Market
Medical Devices
Syndesmosis Repair System Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Facial Pumps Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Asia-Pacific Radiotherapy Market
Medical Devices
Adult Water Flosser Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market