
 Anorectal Manometry Systems Market | 2026-2036
Anorectal Manometry Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Anorectal Manometry Systems Market Outlook
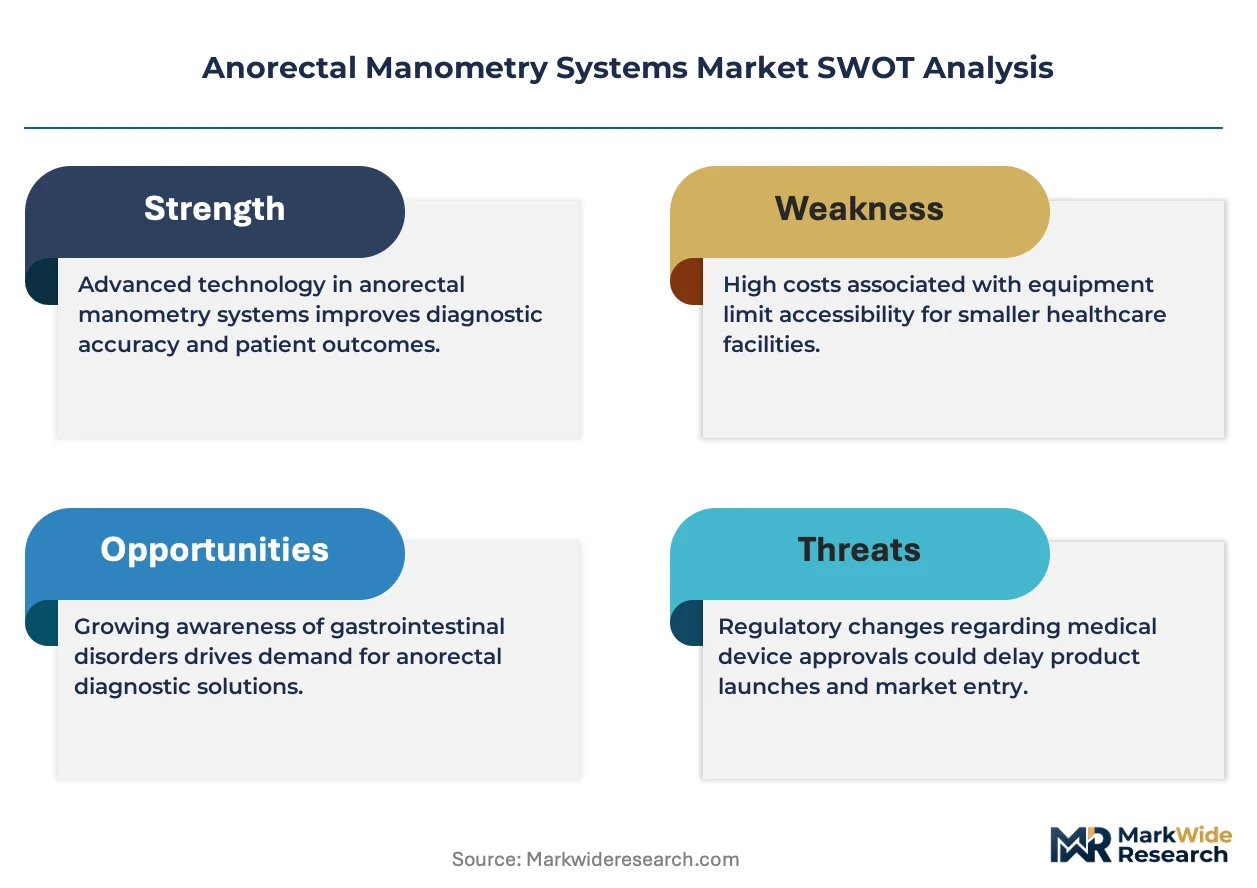
The capital-intensity divergence between high-end electromechanical platform developers and basic handheld manufacturers is collapsing as digital sensor costs fall and miniaturization accelerates. Medtronic PLC leverages its integrated surgical ecosystem to bundle manometry with neuromodulation and imaging workflows. Laborie Medical Technologies anchors its position through dedicated urology-gastroenterology channel control across tertiary hospitals. Medical Measurement Systems competes on European manufacturing scale and CE-marked customization for national health service procurement.
Anorectal manometry systems measure pressure, sensation, and reflex responses within the anal canal and rectum using water-perfused or solid-state catheters with circumferential pressure sensors, typically sampling at 10-50 Hz to generate topographic pressure maps. These devices serve colorectal surgeons, gastroenterologists, and pelvic floor specialists in diagnosing defecatory disorders, fecal incontinence, and preoperative sphincter function. Stationary systems still occupy the highest-margin installed base in academic medical centers, while wireless monitors represent the fastest-growing product type as ambulatory diagnostic protocols expand. Hospitals dominate end-user demand, though diagnostic centers are capturing volume as referral networks decentralize gastrointestinal workups away from inpatient settings.
FDA 510(k) premarket notification requirements govern Class II anorectal manometry device clearance in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence and post-market surveillance obligations for CE-marked systems entering European markets. The FDA's Digital Health Center of Excellence and evolving software-as-medical-device guidance increasingly shape how software solutions with AI-assisted pressure interpretation gain market access. Stakeholders must monitor how MDR notified body capacity constraints and FDA cybersecurity guidance for interconnected diagnostic devices reshape competitive timelines and compliance costs.
Market Dynamics
Digital sensor miniaturization and falling semiconductor costs are collapsing the price-performance gap between high-end electromechanical platforms and basic handheld units, forcing manufacturers to redefine competitive differentiation around software integration and workflow connectivity rather than hardware specifications alone.
Growth Catalysts
- Rising colorectal surgery volumes:Aging demographics in the United States are expanding referrals for anorectal physiology testing, particularly for fecal incontinence and defecatory disorder assessments in tertiary hospitals.
- FDA 510(k) pathway efficiency:The streamlined premarket notification process for Class II medical devices accelerates product entry timelines, reducing regulatory friction for solid-state catheter innovations.
- Wireless ambulatory protocols:Extended monitoring capabilities outside clinical settings are opening new diagnostic workflows for pelvic floor dysfunction, driving replacement demand among gastroenterology clinics.
Market Restraints
- Capital intensity of stationary systems:High upfront investment requirements for academic medical center installations limit penetration among smaller diagnostic centers and independent practices.
- EU MDR clinical evidence burdens:Stricter post-market surveillance obligations and notified body capacity constraints are extending CE-marking timelines for European market entry.
- Disposable catheter cost volatility:Supply concentration for specialized pressure-sensor components creates input cost uncertainty that compresses margin structures across product tiers.
Strategic Opportunities
- Decentralized diagnostic networks:Referral patterns are shifting gastrointestinal workups away from inpatient settings toward freestanding diagnostic centers in suburban United States markets.
- AI-assisted pressure interpretation:The FDA's Digital Health Center of Excellence guidance creates a pathway for software-as-medical-device solutions that automate topographic map analysis.
- Pelvic floor physiotherapy integration:Convergence between manometry systems and biofeedback training platforms opens reimbursement-aligned service bundles for urology-gastroenterology combined practices.
Industry Challenges
- Specialized technician scarcity:Operation of water-perfused and solid-state systems requires trained gastroenterology nurses or pelvic floor physiologists, creating bottlenecks for test throughput expansion.
- Cybersecurity compliance for interconnected devices:FDA guidance on networked diagnostic equipment imposes additional validation burdens for manufacturers integrating cloud-based data storage and remote monitoring capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anorectal Manometry Systems Market |
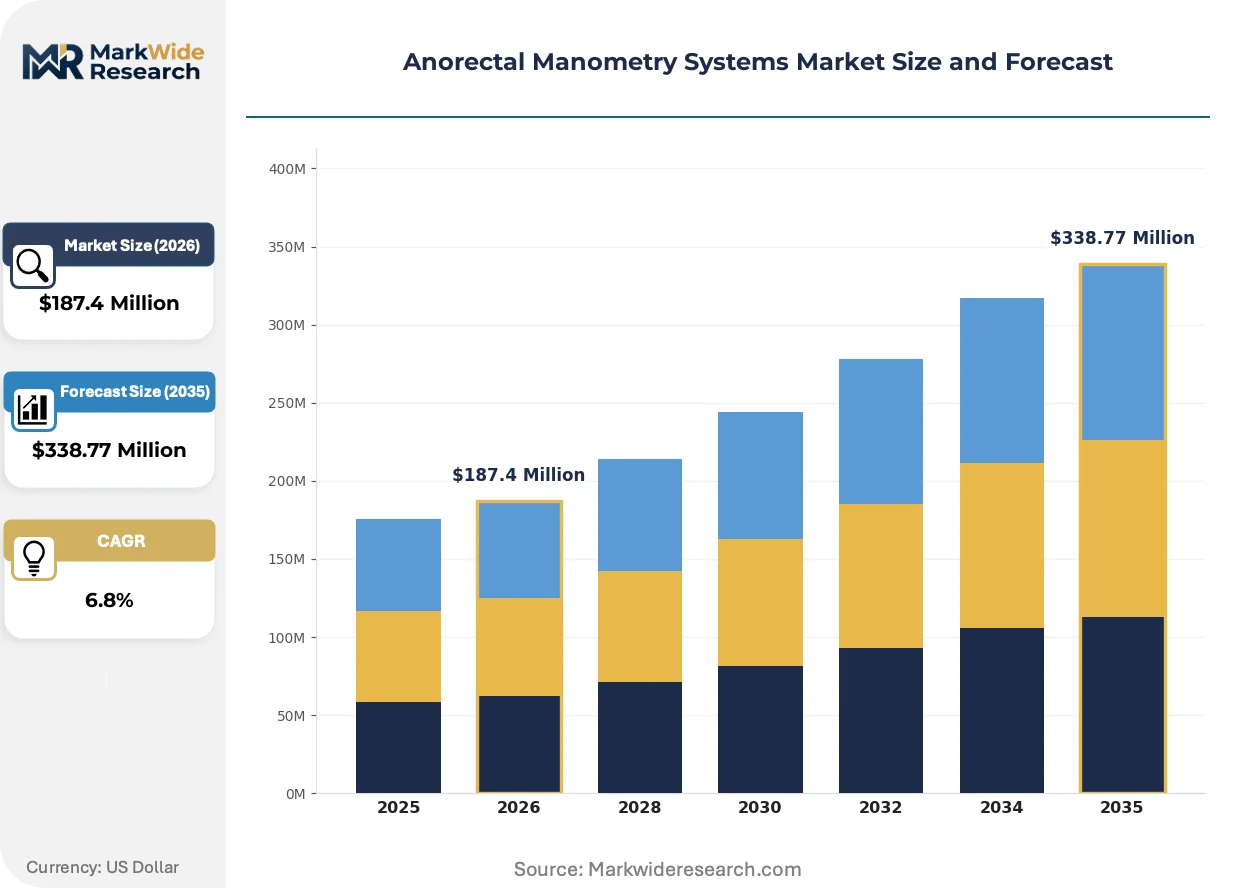
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Stationary Systems, Wireless Monitors, Software Solutions End User: Hospitals, Clinics, Diagnostic Centers, Research Institutes Technology: Hydraulic Systems, Electromechanical Devices, Digital Sensors, Biomechanical Platforms Application: Gastrointestinal Disorders, Functional Bowel Disorders, Constipation Evaluation, Surgical Assessment |
| Companies Covered | Mui Scientific, Medical Measurement Systems, Laborie Medical Technologies, Arndorfer Medical Specialties, Sandhill Scientific, Medtronic PLC, Synectics Medical Limited, Given Imaging Ltd., Diversatek Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anorectal Manometry Systems Market Strategic Shifts
Sensor fusion and embedded computing are redefining what constitutes a complete diagnostic platform, with software capabilities now determining competitive position more than raw hardware specifications. This shift is compressing traditional category boundaries between stationary, portable, and fully ambulatory systems.
Solid-state microelectromechanical pressure sensors are replacing water-perfused catheter technology in mid-tier product lines, offering higher sampling rates and improved patient tolerance during prolonged studies. Community hospitals and regional diagnostic chains are adopting these platforms at twice the pace of academic centers. The installed base is bifurcating between premium systems with full surgical workflow integration and stripped-down units optimized for high-throughput screening environments.
The EU Medical Device Regulation's intensified clinical evidence requirements are reshaping how manufacturers structure post-market surveillance programs for CE-marked anorectal manometry systems. European notified bodies now demand prospective registry data for novel catheter designs, extending approval timelines. Smaller manufacturers are responding by partnering with academic medical centers for real-world evidence generation rather than funding standalone pivotal trials.
Service unbundling is disrupting traditional capital-equipment sales models as buyers separate hardware acquisition from software maintenance and clinical training contracts. Diagnostic center chains in the United States are negotiating standalone service agreements with third-party clinical education firms rather than accepting bundled manufacturer packages. This pattern is most visible in Florida and Texas, where private equity-backed gastroenterology platforms are standardizing equipment across multi-site networks.
Anorectal Manometry Systems Market Segmentation
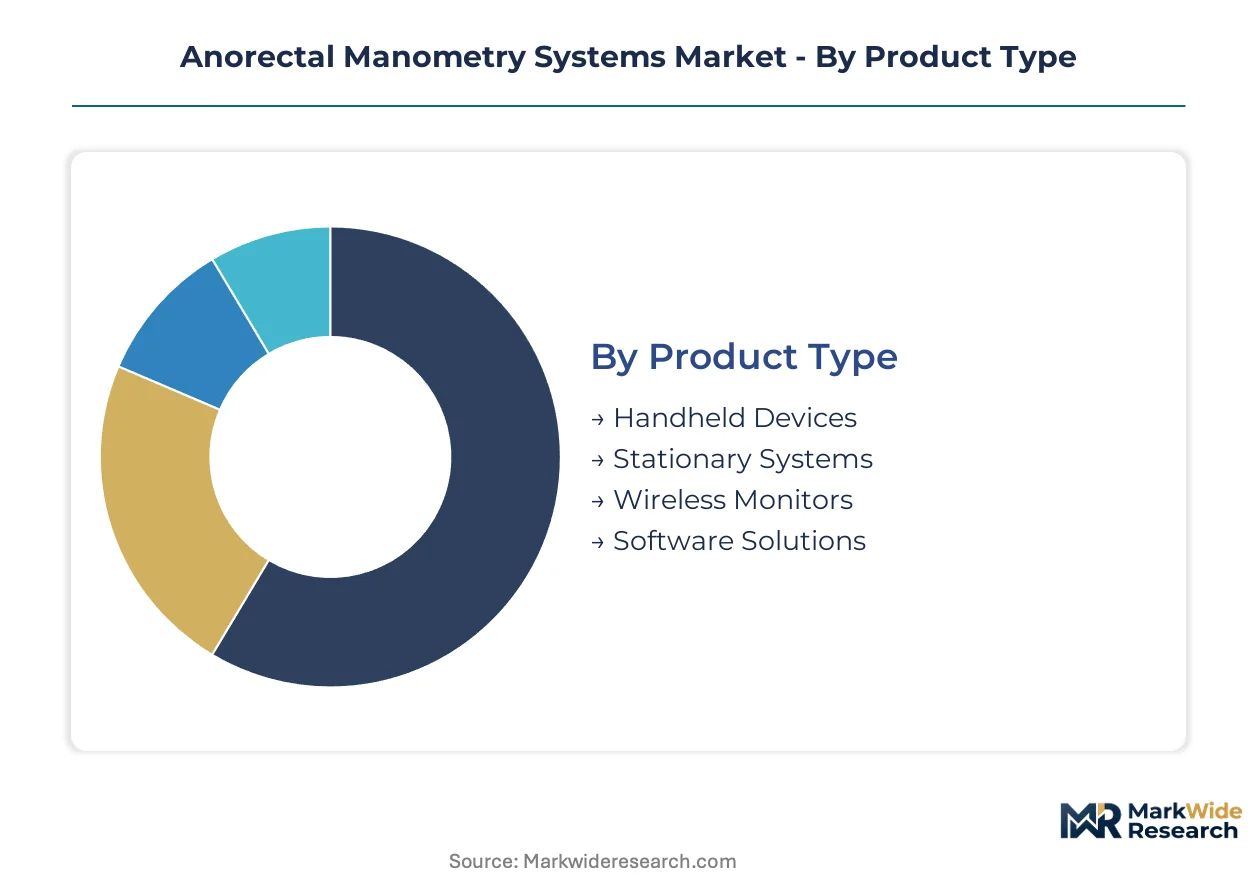
Segmentation in anorectal manometry systems reveals how regulatory pathways, clinical workflows, and capital constraints fragment purchasing behavior across healthcare settings. Manufacturers must align product architectures with distinct compliance burdens and reimbursement environments rather than pursuing universal platform designs.
Product Type:
FDA 510(k) clearance timelines vary substantially across product categories, with stationary systems facing extended validation for software integration while handheld devices navigate abbreviated review cycles.
- Handheld Devices:Portable units with solid-state microelectromechanical pressure sensors and simplified topographic mapping capabilities. Demand concentrates in suburban diagnostic centers across the United States where capital constraints limit stationary system acquisition.
- Stationary Systems:Electromechanical platforms with circumferential sensor arrays sampling at 10-50 Hz, integrated with surgical planning software and EMR connectivity. Academic medical centers in the United States anchor procurement volumes as tertiary hospitals expand pelvic floor dysfunction assessment protocols.
- Wireless Monitors:Ambulatory systems enabling extended rectal pressure monitoring outside clinical settings. Gastroenterology clinics in Florida and Texas adopt these for decentralized diagnostic networks.
- Software Solutions:AI-assisted pressure interpretation modules and cloud-based data analytics platforms. The FDA's Digital Health Center of Excellence shapes market access pathways for algorithmic diagnostic aids.
Stationary systems handle the majority of throughput; wireless monitors are expanding most quickly on share.
End User:
Cost tier differentiation separates capital-intensive hospital installations from leaner diagnostic center deployments, with reimbursement alignment determining purchasing authority distribution.
- Hospitals:Tertiary institutions with integrated colorectal surgery and gastroenterology departments. United States hospital systems in metropolitan clusters drive premium system adoption through bundled surgical workflow contracts.
- Clinics:Specialized gastroenterology and urology-gastroenterology combined practices. Private equity-backed multi-site networks in Texas standardize equipment across suburban locations.
- Diagnostic Centers:Freestanding facilities capturing decentralized gastrointestinal workups. Florida-based chains negotiate standalone service agreements separate from manufacturer bundles.
- Research Institutes:Academic centers generating real-world evidence for EU MDR compliance. European notified bodies demand prospective registry data from these institutions for novel catheter validations.
Hospitals dominate capital deployment; diagnostic centers are climbing the fastest on volume share.
Technology:
Application requirements differentiate technologies by measurement precision demands and procedural tolerance thresholds across patient populations.
- Hydraulic Systems:Water-perfused catheters with established clinical validation but higher technician dependency. Legacy installations persist in European national health service procurement frameworks.
- Electromechanical Devices:Motor-driven catheter advancement with automated pressure calibration. Community hospitals in the United States adopt these at twice the pace of academic centers for throughput optimization.
- Digital Sensors:Solid-state microelectromechanical systems replacing hydraulic technology in mid-tier lines. Higher sampling rates and improved patient tolerance during prolonged studies drive replacement cycles.
- Biomechanical Platforms:Integrated systems combining pressure measurement with sphincter electromyography and ultrasound. Pelvic floor physiotherapy convergence opens reimbursement-aligned service bundles.
Digital sensors command the steepest expansion trajectory; hydraulic systems retain installed base defense in European markets.
Application:
Volume concentration across clinical indications reflects referral pattern shifts toward functional rather than structural gastrointestinal assessments.
- Gastrointestinal Disorders:Comprehensive evaluation of defecatory dysfunction and anorectal pain syndromes. Tertiary hospital gastroenterology departments in the United States generate the highest test volumes.
- Functional Bowel Disorders:Irritable bowel syndrome and pelvic floor dyssynergia assessment. Diagnostic centers target these indications for high-throughput screening protocols.
- Constipation Evaluation:Outlet obstruction and slow-transit differentiation. Community hospitals expand testing capacity as aging demographics expand referral pools.
- Surgical Assessment:Preoperative sphincter function evaluation and postoperative outcome monitoring. Academic medical centers integrate these workflows with neuromodulation and imaging platforms.
Gastrointestinal disorders anchor clinical throughput; functional bowel disorders are gaining share fastest as diagnostic networks decentralize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that of European markets by a substantial margin, driven by higher reimbursement rates for anorectal physiology testing and faster FDA 510(k) clearance timelines. Germany and France face compressed margins under EU MDR compliance burdens, while Japan and Australia present intermediate value capture opportunities shaped by national health technology assessment frameworks.
United States
Colorectal surgery volumes in tertiary hospitals drive stationary system procurement, with private equity-backed gastroenterology platforms in Florida and Texas standardizing equipment across suburban diagnostic networks. FDA 510(k) premarket notification requirements govern Class II device entry, accelerating solid-state catheter innovations relative to European timelines. The Cleveland Clinic and Mayo Clinic anchor high-throughput testing protocols that shape manufacturer product roadmaps.
Germany
Medical Measurement Systems leverages domestic manufacturing scale to supply CE-marked systems for national health service procurement frameworks across Bavaria and North Rhine-Westphalia. EU MDR notified body capacity constraints extend validation timelines for novel catheter designs, forcing partnerships with academic medical centers for real-world evidence generation. Berlin-based research institutes generate prospective registry data that satisfies intensified post-market surveillance obligations.
Japan
PMDA regulatory pathways for Software as a Medical Device create market access channels for AI-assisted pressure interpretation modules in Tokyo and Osaka metropolitan clusters. Aging demographics expand fecal incontinence assessment referrals, while METI industrial policy supports domestic sensor miniaturization capabilities. Kanto region hospitals integrate manometry with neuromodulation workflows for pelvic floor dysfunction.
United Kingdom
NHS England procurement frameworks concentrate demand in London and Southeast academic medical centers, with NICE technology appraisals determining reimbursement eligibility for wireless ambulatory systems. Brexit-related divergence from EU MDR implementation creates parallel compliance obligations for manufacturers serving both markets. Manchester and Birmingham regional networks decentralize gastrointestinal workups toward freestanding diagnostic centers.
Australia
TGA conformity assessment procedures for Class IIa medical devices align with EU MDR standards, though streamlined review timelines attract early-stage product launches. New South Wales and Victoria hospital systems adopt solid-state platforms for community hospital throughput optimization. Private diagnostic chains in Sydney and Melbourne negotiate standalone service agreements separate from manufacturer bundles.
Anorectal Manometry Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated surgical ecosystem developers commanding premium positioning while regional specialists compete on manufacturing scale and customization. The vendor base concentrates around three strategic tiers: multinational platform bundlers, European manufacturing-scale specialists, and regional channel-control operators. Dominant competitive moves include strategic partnerships for real-world evidence generation under EU MDR and portfolio diversification into software-as-medical-device solutions.
Within the integrated platform tier, Medtronic PLC anchors positioning through surgical workflow bundling that combines manometry with neuromodulation and imaging systems. Laborie Medical Technologies exemplifies dedicated channel-control strategy across urology-gastroenterology combined practices. Medical Measurement Systems represents European manufacturing-scale specialization with CE-marked customization capabilities for national health service procurement. Mui Scientific and Sandhill Scientific occupy positions among North American-focused diagnostic equipment developers serving decentralized referral networks.
| Leading Market Players |
|---|
| Mui Scientific |
| Medical Measurement Systems |
| Laborie Medical Technologies |
| Arndorfer Medical Specialties |
| Sandhill Scientific |
| Medtronic PLC |
| Synectics Medical Limited |
| Given Imaging Ltd. |
| Diversatek Healthcare |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for solid-state pressure sensor modules concentrate pricing power with German and Japanese component suppliers, while catheter assembly plants in the United States and Netherlands absorb inventory risk through consignment arrangements with tertiary hospital buyers. This lead-time band compresses margin structures for mid-tier manufacturers unable to secure volume commitments from semiconductor foundries.
Pricing Analysis
The customization-premium spread between configured-to-order stationary systems and standard handheld units reaches three-to-one multiples, with FDA 510(k) certification tier and surgical workflow integration serving as the primary price differentiation drivers. Subscription-based software maintenance contracts now dominate the pricing model for academic medical center installations, while per-unit transactional sales persist in diagnostic center chains. Pricing pressure stems from falling digital sensor costs that collapse hardware differentiation, with private equity-backed gastroenterology platforms in Florida and Texas exhibiting the highest price sensitivity through consolidated procurement.
Supply Chain Analysis
Inventory buffers for specialized microelectromechanical pressure sensors run lean at fifteen-to-thirty days across the United States, Germany, and Japan, forcing manufacturers into expedited freight modes when demand spikes. The supply chain draws from Taiwanese semiconductor foundries for sensor fabrication, German precision machining for catheter housings, and United States polymer extrusion for biocompatible tubing. Single-source vulnerability concentrates in solid-state sensor die production, with distribution running through manufacturer-direct field service organizations for stationary systems and third-party medical device distributors for handheld units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face substitution defense imperatives as high-resolution anorectal ultrasound and magnetic resonance defecography capture referral volume for pelvic floor dysfunction assessment. Market positioning must harden around workflow integration and real-time data connectivity that imaging modalities cannot replicate.
For Market Incumbents: Compound defensive moats by deepening backward integration into solid-state sensor design and securing exclusive GPO contracts with the ten largest United States hospital systems. The ultrasound substitution threat demands software-as-medical-device investments that embed manometry into electronic medical record workflows, while CE marking capacity constraints in Europe create first-mover advantages for manufacturers with notified body relationships.
For New Entrants and Emerging Players: Anchor in wireless ambulatory monitoring for suburban diagnostic centers in Texas and Florida, the most penetrable segment where capital constraints exclude stationary system incumbents. Service unbundling creates white-space for standalone clinical education firms that decouple training from manufacturer hardware bundles, with AI-assisted pressure interpretation offering a software-only go-to-market angle that bypasses FDA hardware clearance timelines.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because category boundaries between manometry, biofeedback, and neuromodulation are collapsing into integrated pelvic floor platforms. Acquisition targets should display European manufacturing scale with CE-marked customization capabilities or software-as-medical-device revenue streams with FDA Digital Health Center of Excellence validation. The signal to watch is reimbursement code consolidation that bundles diagnostic testing with therapeutic intervention, accelerating platform substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Streamlined Class II clearance accelerates solid-state catheter innovations relative to European MDR timelines. |
| CE Marking Pathway | EU MDR notified body capacity constraints favor manufacturers with established academic medical center partnerships for real-world evidence. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic procurement standards shape manufacturer product roadmaps for surgical workflow integration. |
| Software Companion Development | AI-assisted pressure interpretation modules create recurring revenue streams and defend against imaging substitution. |
| Reimbursement Strategy | CPT code alignment with pelvic floor physiotherapy biofeedback training expands addressable market for combined diagnostic-therapeutic bundles. |
Study Parameters
Desk research of FDA 510(k) premarket notification databases, EU MDR notified body guidance documents, and hospital procurement contract disclosures preceded structured interviews with colorectal surgeons, gastroenterology clinic administrators, biomedical engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, professional society clinical guidelines, and medical device trade flow records. Bottom-up test volume estimates by healthcare setting triangulated against top-down capital equipment spending patterns across the analysis window.
Variance decomposition across product type, end-user setting, technology platform, and geographic regulatory cluster shaped the analytical framework for value projections over the projection horizon. CAGRs derived from logistic adoption curves fitted to historical installed base data and replacement cycle assumptions, with sensor miniaturization cost curves and ambulatory protocol expansion rates serving as key forecast inputs.
Material uncertainties — EU MDR implementation delays, FDA cybersecurity guidance evolution for interconnected devices, and disposable catheter supply concentration — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement stability and clinical guideline endorsement trajectories that could shift with randomized trial outcomes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Liver-On-Chip Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Soft Contact Lenses Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Europe C-Arms Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Craniomaxillofacial Devices Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Tracheobronchial Suction Catheters Market
Medical Devices
Global Blood Processing Devices and Consumables Market