
 Europe Cardiac Assist Devices Market | 2026-2036
Europe Cardiac Assist Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cardiac Assist Devices Market Foresight
Hospital procurement networks across Europe is reconfiguring how cardiac assist devices reach end users, with centralized tendering and value-based purchasing now governing large-volume acquisitions. Abiomed leverages direct-to-institution sales teams to sustain premium positioning in ventricular assist device segments. Berlin Heart anchors its competitive stance through deep specialization in pediatric mechanical circulatory support, a niche with limited vendor alternatives.
Cardiac assist devices comprise electromechanical pumps, oxygenators, and total replacement hearts designed to supplement or replace native cardiac function in patients with end-stage heart failure or cardiogenic shock; these systems typically operate at flow rates of 5–10 liters per minute and incorporate biocompatible materials such as titanium alloys and textured polyurethane blood-contacting surfaces to prevent thrombus formation. Ventricular assist devices dominate current revenue pools due to established Bridge-to-Transplant and Destination Therapy indications, while extracorporeal membrane oxygenation represents the fastest-expanding category as extracorporeal life support protocols diffuse beyond traditional cardiac surgery into emergency and critical care settings. Total artificial hearts occupy a narrow but strategically significant segment where competitors differentiate through pulsatile versus continuous-flow architectures and transcutaneous energy transfer systems.
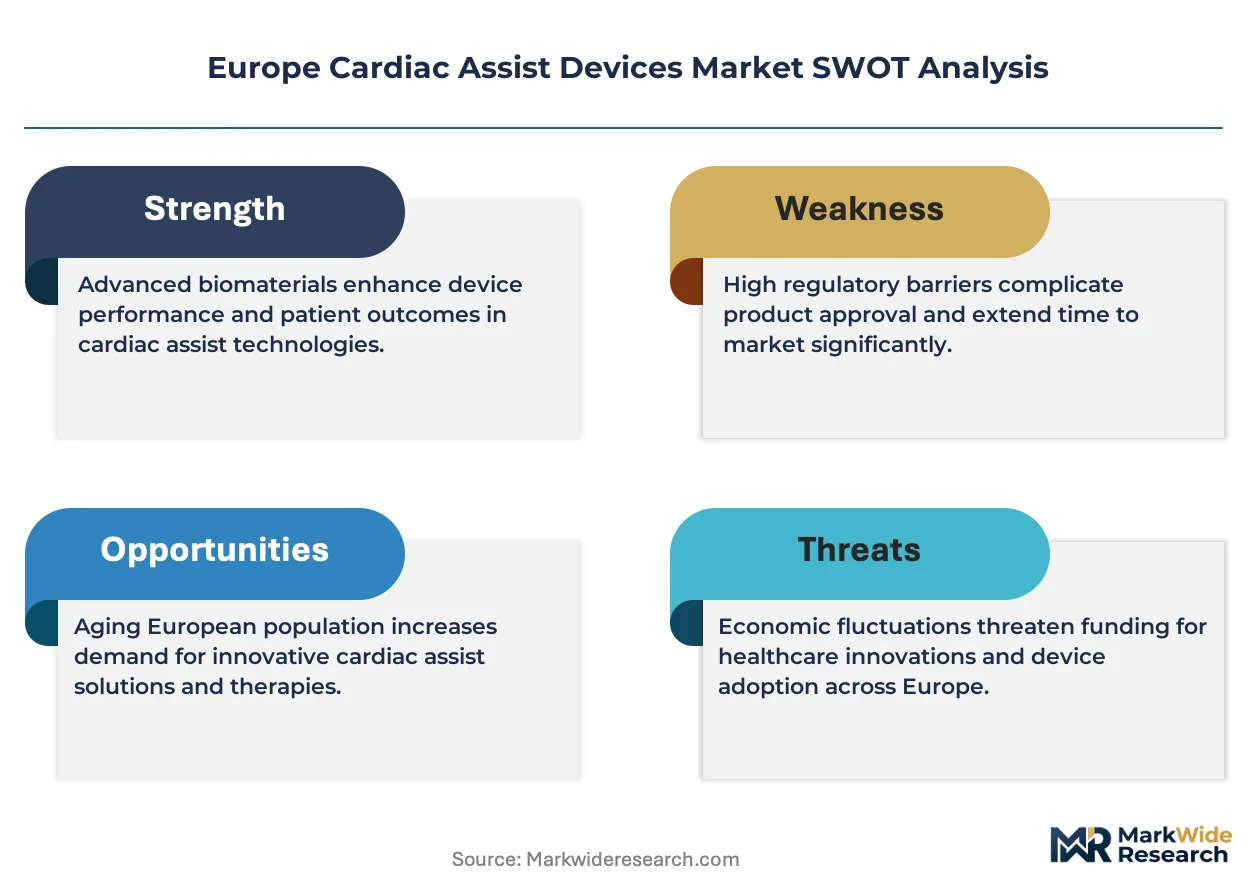
The EU Medical Device Regulation and CE marking framework govern market access, with notified bodies now requiring substantially expanded clinical follow-up data for active implantable cardiovascular devices compared to prior Medical Device Directive standards. EMA coordination on post-market surveillance and the F-Gas Regulation's constraints on sterilization gases further shape manufacturing compliance burdens and supply chain configuration. Stakeholders must monitor how evolving HTA assessment methodologies in France, Germany, and Italy reshape reimbursement thresholds for next-generation devices versus established pump platforms.
Market Dynamics
The EU Medical Device Regulation is compressing market access timelines for active implantable cardiovascular devices, forcing manufacturers to restructure clinical evidence generation and post-market surveillance systems ahead of notified body recertification cycles.
Growth Catalysts
- Destination Therapy expansion:National health technology assessment bodies in Germany and France are broadening reimbursement for long-term ventricular assist device implantation beyond bridge-to-transplant indications, enlarging the addressable patient pool.
- Critical care protocol diffusion:Extracorporeal membrane oxygenation is migrating from specialized cardiac surgery centers into emergency medicine and medical intensive care units, creating new deployment sites across tertiary hospital networks.
- F-Gas Regulation adaptation:Sterilization infrastructure investments compliant with the EU F-Gas Regulation's phasedown schedule are securing supply chain continuity for ethylene oxide-dependent device manufacturers.
Market Restraints
- Titanium alloy supply concentration:Aerospace and medical grade titanium feedstock sourcing clusters in Eastern European processing facilities create geographic single-point vulnerability for pump housing manufacturers.
- MDR clinical evidence burdens:The EU Medical Device Regulation's expanded post-implant follow-up requirements are extending regulatory approval timelines and inflating pre-market clinical investigation budgets for novel continuous-flow architectures.
- Allogeneic heart transplantation:Improvements in organ preservation and allocation logistics are shortening waitlist durations in select Eurotransplant zones, compressing the bridge-to-transplant window for mechanical circulatory support.
Strategic Opportunities
- Pediatric mechanical circulatory support:Underpenetrated markets in Italy and Spain present expansion vectors for Berlin Heart's EXCOR platform and competing paracorporeal systems sized for neonatal and infant circulatory failure.
- Transcutaneous energy transfer:Convergence of inductive power coupling with miniaturized implantable electronics is eliminating percutaneous drivelines, addressing the dominant infection pathway in long-term ventricular assist device therapy.
- Centralized tendering evolution:Hospital procurement networks in the Netherlands and Belgium are piloting outcome-based contracting frameworks that reward device durability and readmission reduction over upfront capital expenditure.
Industry Challenges
- Perfusionist workforce scarcity:Extracorporeal life support program expansion is outpacing specialized training pipeline output in the United Kingdom and Nordic countries, constraining 24/7 ECMO service availability.
- Legacy system integration:Next-generation magnetically levitated centrifugal pumps require proprietary console interfaces that complicate interoperability with existing intensive care monitoring architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cardiac Assist Devices Market |
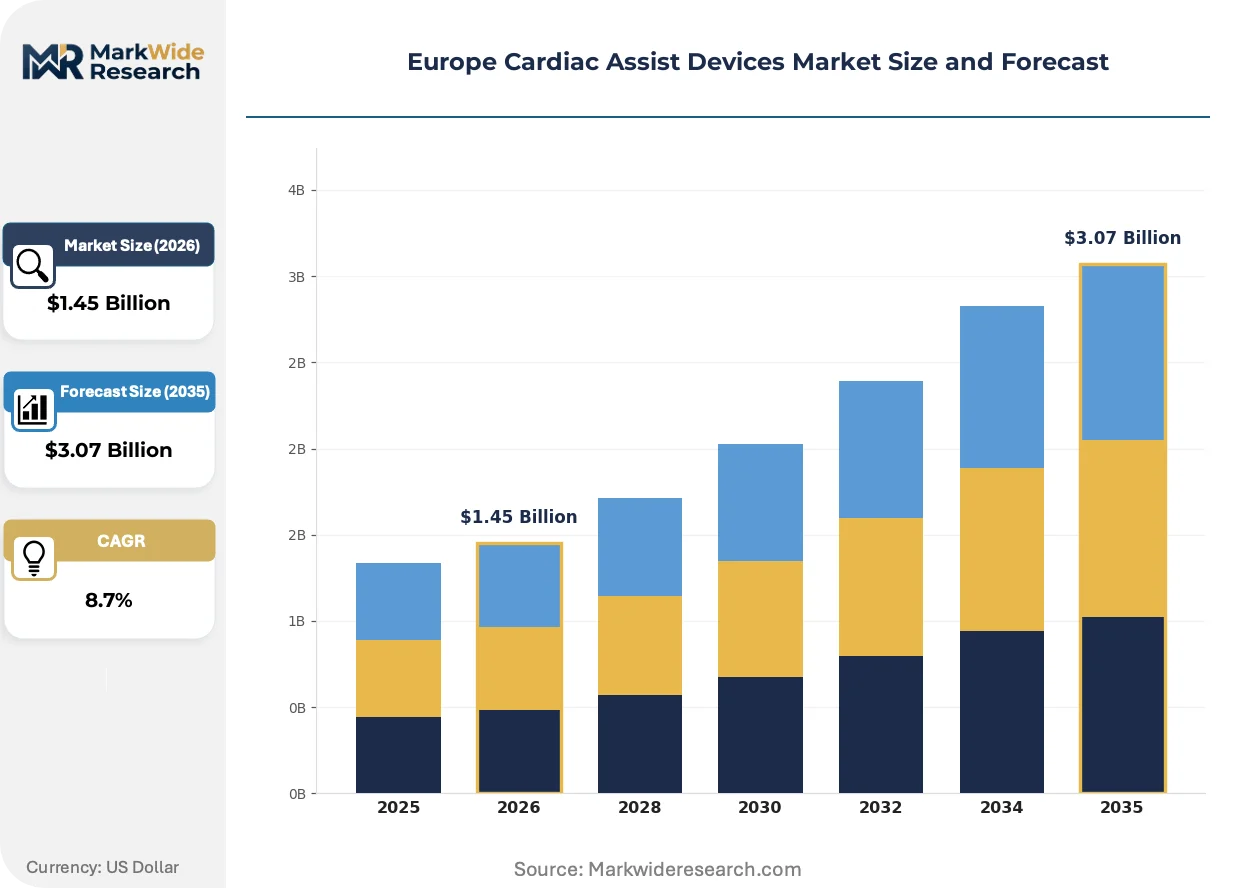
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Ventricular Assist Devices, Intra-Aortic Balloon Pumps, Total Artificial Hearts, Extracorporeal Membrane Oxygenation End User: Hospitals, Cardiology Clinics, Ambulatory Surgical Centers, Specialized Heart Centers Technology: Pump Technology, Oxygenation Technology, Controller Technology, Monitoring Technology Application: Heart Failure, Shock Management, Perioperative Support, Transplantation |
| Companies Covered | Abiomed, Berlin Heart, Carmat, Cardiobridge GmbH, LivaNova, Teleflex, Medtronic, Jarvik Heart, CorWave SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cardiac Assist Devices Market Shifts & Advancements
Device architecture and care delivery models are diverging from established bridge-to-transplant paradigms toward chronic disease management frameworks, with regulatory and procurement systems scrambling to adapt reimbursement and surveillance infrastructure.
Magnetically levitated centrifugal blood pumps are eliminating mechanical bearing wear as a failure mode in long-term ventricular assist device therapy. German and Dutch heart centers are prioritizing these platforms for Destination Therapy candidacy. The technology is hybridizing pulsatile and continuous-flow physiologies through programmable speed modulation algorithms that mimic native cardiac output variability.
The EU Medical Device Regulation's 2021 implementation is mandating substantially expanded clinical follow-up databases for active implantable cardiovascular devices. Manufacturers must now sustain 15-year post-market surveillance cohorts with annual safety reporting to notified bodies. Pediatric mechanical circulatory support segments face the steepest compliance cost escalation due to smaller denominator populations and extended follow-up windows.
Hospital procurement networks are consolidating ventricular assist device acquisitions through multi-year framework agreements with single-source or dual-source vendor panels. Large-volume academic medical centers in Germany are displacing transactional purchasing with total cost-of-ownership contracts that bundle device, consumables, and technical support. This concentration is most visible in North Rhine-Westphalia's university hospital alliance tendering structure.
Europe Cardiac Assist Devices Market Segmentation
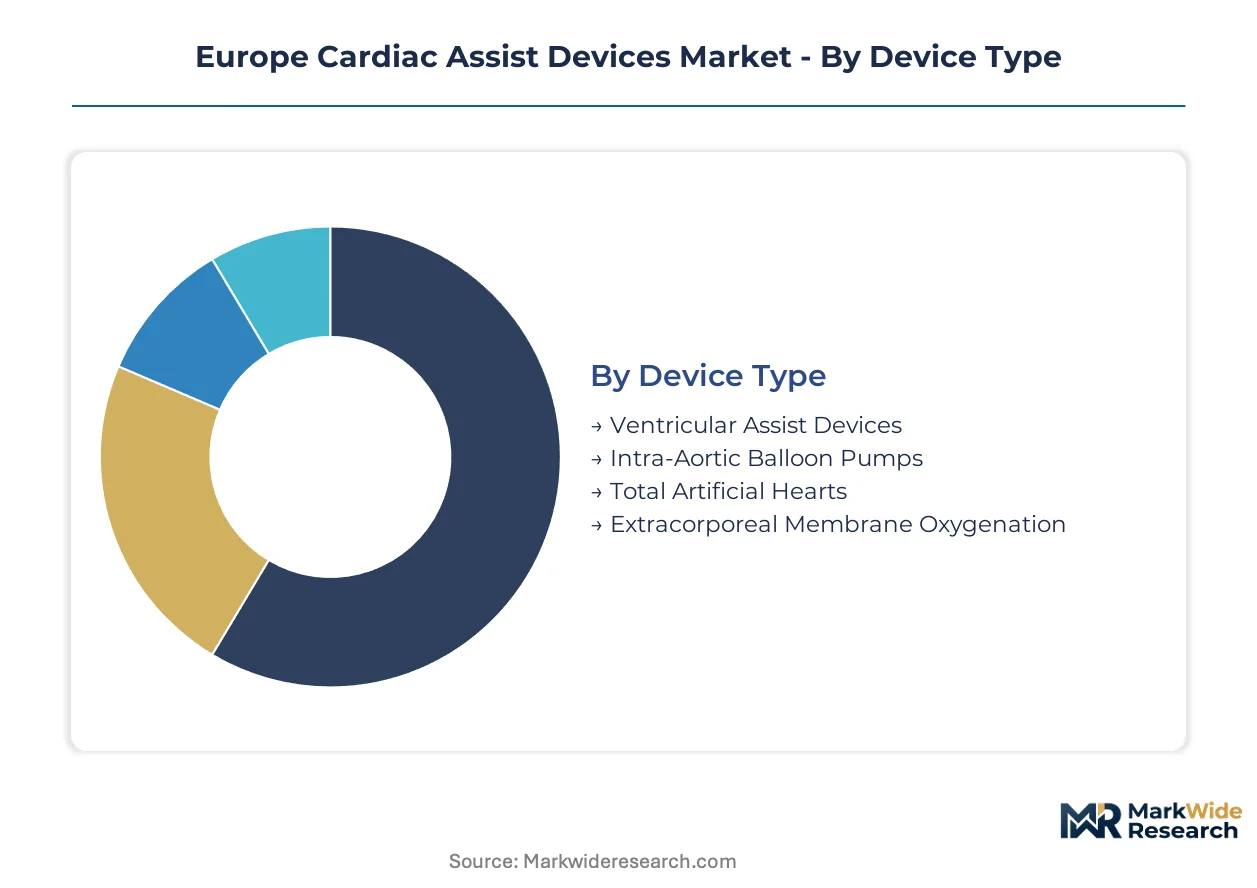
Segmentation reveals how cardiac assist devices diverge across clinical workflows, reimbursement tiers, and technical service requirements. Each dimension carries distinct margin profiles and aftermarket dependencies that reshape vendor economics across European procurement networks.
Device Type:
After-sales service intensity varies sharply across device architectures, with implantable systems demanding longitudinal technical support and consumables-driven platforms requiring rapid field response capabilities.
- Ventricular Assist Devices:Electromechanical pumps comprising continuous-flow rotodynamic or pulsatile displacement architectures deliver 5–10 liters per minute cardiac output support. German heart centers in North Rhine-Westphalia concentrate procurement of these systems for Destination Therapy expansion, driven by broadening national reimbursement beyond bridge-to-transplant indications.
- Extracorporeal Membrane Oxygenation:Integrated pump-oxygenator circuits providing cardiopulmonary bypass support through membrane gas exchange technology. Demand concentrates in emergency medicine and medical intensive care units across tertiary hospital networks in the Netherlands and Belgium, propelled by protocol diffusion beyond traditional cardiac surgery.
- Intra-Aortic Balloon Pumps:Counterpulsation devices augmenting coronary perfusion through phased helium inflation.
- Total Artificial Hearts:Biventricular replacement systems eliminating native cardiac function dependence.
By volume, Ventricular Assist Devices leads. By growth pace, Extracorporeal Membrane Oxygenation is ahead.
End User:
Procurement authority concentrates differently across facility types, with academic medical centers wielding framework agreement leverage while ambulatory settings operate on transactional purchasing.
- Specialized Heart Centers:Dedicated cardiac surgery and advanced heart failure facilities performing high-complexity mechanical circulatory support implantation. These centers across Western Europe anchor ventricular assist device volume through centralized tendering and value-based purchasing frameworks.
- Hospitals:General acute care institutions with cardiac surgery capabilities and extracorporeal life support programs. Tertiary networks in Germany and France drive ECMO expansion as critical care protocols migrate into emergency medicine.
- Cardiology Clinics:Outpatient-focused facilities managing heart failure progression and VAD candidacy screening.
- Ambulatory Surgical Centers:Limited-service settings with restricted scope for cardiac assist device deployment.
Specialized Heart Centers capture the highest per-procedure value. Hospitals demonstrate the steepest expansion trajectory for ECMO service lines.
Technology:
Component-level differentiation determines interoperability constraints and upgrade pathway economics across European installed bases.
- Pump Technology:Magnetically levitated centrifugal and mechanical bearing axial flow architectures. German and Dutch centers prioritize magnetically levitated platforms for Destination Therapy, eliminating bearing wear as a failure mode through electromagnetic suspension.
- Controller Technology:Embedded systems managing pump speed modulation, alarm thresholds, and power management. Next-generation consoles incorporating programmable algorithms that hybridize pulsatile and continuous-flow physiologies concentrate demand in advanced heart centers.
- Oxygenation Technology:Membrane oxygenator designs with hollow fiber or sheet membrane gas exchange surfaces.
- Monitoring Technology:Hemodynamic parameter tracking and remote telemetry systems.
Pump Technology commands the deepest R&D investment. Controller Technology is gaining share fastest through miniaturization and algorithmic sophistication.
Application:
Clinical indication framing determines reimbursement coding, regulatory evidence requirements, and patient selection criteria across European health technology assessment regimes.
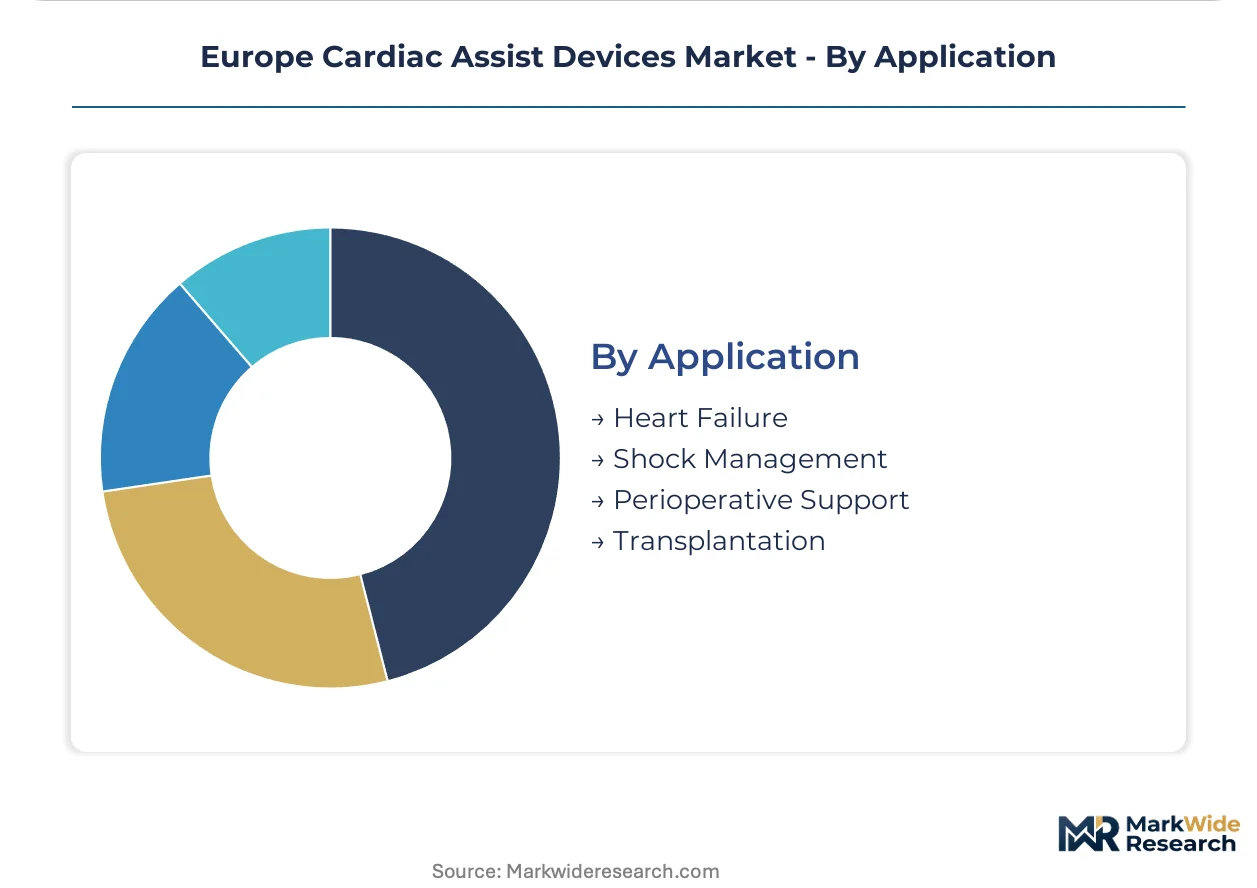
- Heart Failure:Chronic end-stage myocardial dysfunction requiring mechanical circulatory support as bridge-to-transplant or Destination Therapy. German and French HTA bodies are broadening long-term VAD reimbursement, enlarging the addressable pool beyond transplant waitlist candidates.
- Shock Management:Acute cardiogenic shock and circulatory collapse requiring emergent mechanical support. ECMO deployment for shock refractory to conventional therapy is expanding across emergency departments and medical ICUs in tertiary networks.
- Perioperative Support:Temporary circulatory assistance during and after cardiac surgical procedures.
- Transplantation:Bridge-to-transplant mechanical support maintaining candidacy during organ allocation.
Heart Failure generates the largest revenue base. Shock Management is climbing the fastest as ECMO protocols penetrate emergency medicine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German university hospital alliances while Italian and Spanish procurement networks operate on thinner margins. Western European reimbursement density creates a two-tier access landscape across the continent.
Germany
North Rhine-Westphalia's university hospital alliances anchor ventricular assist device volume through centralized tendering frameworks. The Federal Joint Committee (G-BA) has broadened Destination Therapy reimbursement beyond bridge-to-transplant indications. Berlin Heart maintains deep specialization in pediatric mechanical circulatory support from its headquarters in the capital.
France
Parisian academic medical centers drive ECMO protocol diffusion into emergency medicine and medical intensive care units. The Haute Autorité de Santé (HAS) is reshaping health technology assessment methodologies for next-generation pump platforms. The Île-de-France cluster concentrates cardiac surgery excellence and value-based purchasing pilots.
Italy
Underpenetrated pediatric mechanical circulatory support markets in Lombardy and Emilia-Romagna present expansion vectors for paracorporeal systems. The Italian Medicines Agency (AIFA) coordinates post-market surveillance with EMA frameworks. Milan's Policlinico hospital network is piloting outcome-based contracting for long-term VAD therapy.
Netherlands
Randstad hospital procurement networks are piloting total cost-of-ownership contracts bundling device, consumables, and technical support. The Dutch Healthcare Authority (NZa) monitors centralized tendering evolution across tertiary networks. Rotterdam and Amsterdam heart centers prioritize magnetically levitated centrifugal pumps for Destination Therapy candidacy.
United Kingdom
Perfusionist workforce scarcity in the NHS constrains 24/7 ECMO service availability despite expanding extracorporeal life support programs. The Medicines and Healthcare products Regulatory Agency (MHRA) aligns active implantable device oversight with EU MDR standards. London's Guy's and St Thomas' NHS Foundation Trust anchors shock management protocol development.
Europe Cardiac Assist Devices Market Competitive Landscape
Multi-product cardiovascular conglomerates and specialized mechanical circulatory support pure-plays split the market into divergent capability tiers. Consolidation pressures favor scale-driven players with integrated sterilization infrastructure and longitudinal clinical evidence databases. Three archetypes dominate: diversified medtech majors with cardiac surgery portfolios, VAD-specialized innovators with magnetically levitated platforms, and ECMO-focused critical care suppliers. Competitive moves center on M&A to secure pediatric niche positioning and strategic partnerships to navigate EU MDR recertification cycles.
Among diversified medtech majors, Medtronic and LivaNova occupy positions spanning implantable pumps and extracorporeal platforms. Abiomed exemplifies the VAD-specialized archetype through direct-to-institution sales teams sustaining premium positioning. Berlin Heart anchors the pediatric mechanical circulatory support tier with limited vendor alternatives in neonatal and infant circulatory failure. Carmat and CorWave SA represent French innovation clusters pursuing transcutaneous energy transfer architectures.
| Leading Market Players |
|---|
| Abiomed |
| Berlin Heart |
| Carmat |
| Cardiobridge GmbH |
| LivaNova |
| Teleflex |
| Medtronic |
| Jarvik Heart |
| CorWave SA |
| Others |
Supply & Pricing Matrix
Titanium alloy feedstock processing clusters in Eastern Europe concentrate upstream supply for pump housing manufacturers, anchoring margin capture among German university hospital alliances that command volume-based purchasing leverage. This geographic concentration of aerospace-grade and medical-grade titanium sourcing creates asymmetric pricing power between component suppliers and finished device vendors across European procurement networks.
Pricing Analysis
Configured-to-order pricing for magnetically levitated centrifugal pumps commands a 15-25% premium over standard mechanical bearing axial flow systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by after-sales service bundling and controller algorithm sophistication. Cost compression in the standard tier is intensifying because Dutch and Belgian hospital procurement networks are piloting total cost-of-ownership contracts that shift value capture toward consumables and technical support. Academic medical centers in Germany exhibit the lowest price sensitivity due to G-BA reimbursement density, while Italian and Spanish regional health systems demonstrate acute sensitivity to upfront capital expenditure.
Supply Chain Analysis
Contract manufacturing for controller electronics and console assembly concentrates among EMS providers in Germany, Switzerland, and the Netherlands. Raw material dependencies center on titanium alloys from Eastern European processors, biocompatible polyurethanes from German specialty chemical producers, and rare-earth magnets for magnetic levitation systems sourced through Asian trading networks. Single-source vulnerability in ethylene oxide sterilization infrastructure feeds from the EU F-Gas Regulation's phasedown schedule, which threatens supply continuity for device manufacturers without compliant sterilization investments. Distribution runs through centralized hospital procurement networks and GPO frameworks that bundle device acquisition with multi-year technical service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's cardiac assist devices market sits in early-cycle expansion as Destination Therapy reimbursement broadens beyond bridge-to-transplant indications in Germany and France, enlarging the chronic patient pool for long-term mechanical circulatory support.
For Market Incumbents: Entrench position through backward integration into titanium alloy machining and sterilization infrastructure to secure supply continuity under EU F-Gas Regulation constraints. Acquire pediatric mechanical circulatory support capabilities to defend against Berlin Heart's niche dominance in neonatal and infant segments. Prioritize magnetically levitated platform R&D to maintain technology differentiation as Destination Therapy volumes concentrate in German and Dutch heart centers. For New Entrants and Emerging Players: Pursue white-space opportunities in Italian and Spanish pediatric mechanical circulatory support markets, where paracorporeal system penetration remains underdeveloped relative to German benchmarks. Target emergency medicine ECMO deployment in French and British tertiary networks, where critical care protocol diffusion outpaces specialized perfusionist workforce growth. Lead with transcutaneous energy transfer architectures that eliminate percutaneous drivelines, addressing the dominant infection pathway in long-term VAD therapy. For Investors and Strategic Acquirers: Capital is best deployed toward specialized mechanical circulatory support pure-plays with magnetically levitated platforms and established CE marking pathways under EU MDR standards. Long-term viability over the next decade hinges on longitudinal clinical evidence databases that satisfy expanded post-market surveillance requirements for active implantable cardiovascular devices. Monitor quarterly hospital procurement tender awards in North Rhine-Westphalia and Randstad networks as inflection indicators for pricing power shifts toward outcome-based contracting frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance secures market access across German, French, and Dutch procurement networks. |
| Hospital System Partnership | Framework agreements with North Rhine-Westphalia university hospital alliances anchor volume commitments. |
| Backward Integration | In-house titanium alloy machining reduces Eastern European supply concentration vulnerability. |
| Software Companion Development | Programmable speed modulation algorithms differentiate magnetically levitated platforms for Destination Therapy. |
| Reimbursement Strategy | G-BA and HAS engagement shapes health technology assessment thresholds for next-generation pump architectures. |
Research Methodology
Desk research of EU MDR guidance documents, EMA post-market surveillance databases, and hospital procurement tender records preceded structured interviews with cardiac surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Primary fieldwork with ventricular assist device program directors and ECMO coordinators across German, French, and Dutch heart centers was validated against secondary sources including notified body certification records, HTA assessment reports from G-BA and HAS, and medical device trade flow data. Bottom-up procedure volume estimates and top-down market sizing triangulated across these data streams.
Assumptions held fixed across the projection horizon include current EU MDR enforcement intensity, existing G-BA Destination Therapy reimbursement parameters, and F-Gas Regulation phasedown schedules for sterilization gases. Variables incorporated into scenario analysis encompass HTA methodology evolution in France and Italy, perfusionist workforce pipeline output in the United Kingdom and Nordic countries, and magnetically levitated platform adoption curves in German and Dutch centers. CAGRs were derived from segmented procedure volume projections weighted by device ASP trajectories and service revenue attachment rates across ventricular assist device, ECMO, and total artificial heart categories.
Macroeconomic conditions sit as an overlay; deviation in eurozone healthcare expenditure growth rates or cardiac surgery reimbursement indexation would shift the trajectory of Destination Therapy expansion. Forecasts reflect assumptions regarding stable regulatory enforcement and continued EMA-notified body coordination on post-market surveillance. Quarterly review of G-BA benefit assessment decisions and Dutch Healthcare Authority tender monitoring reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
Global Cardiac Output Monitoring Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Global Pericardiocentesis Procedures Market
Cardiovascular Devices
Global Blood Pressure Cuffs Market
Cardiovascular Devices
Endovascular Stent Market
Cardiovascular Devices
US Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Global Critical Limb Ischemia Treatment Market
Cardiovascular Devices
Global Coronary Stent Market
Cardiovascular Devices
Global Aortic Repair Devices Market
Cardiovascular Devices
Wearable Cardiac Devices Market
Cardiovascular Devices
Patient-Controlled Injectors Market
Cardiovascular Devices
Cardiac Ablation Technologies Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market