
 Global Intravenous (IV) Equipment Market | 2026-2036
Global Intravenous (IV) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intravenous (IV) Equipment Market Foresight
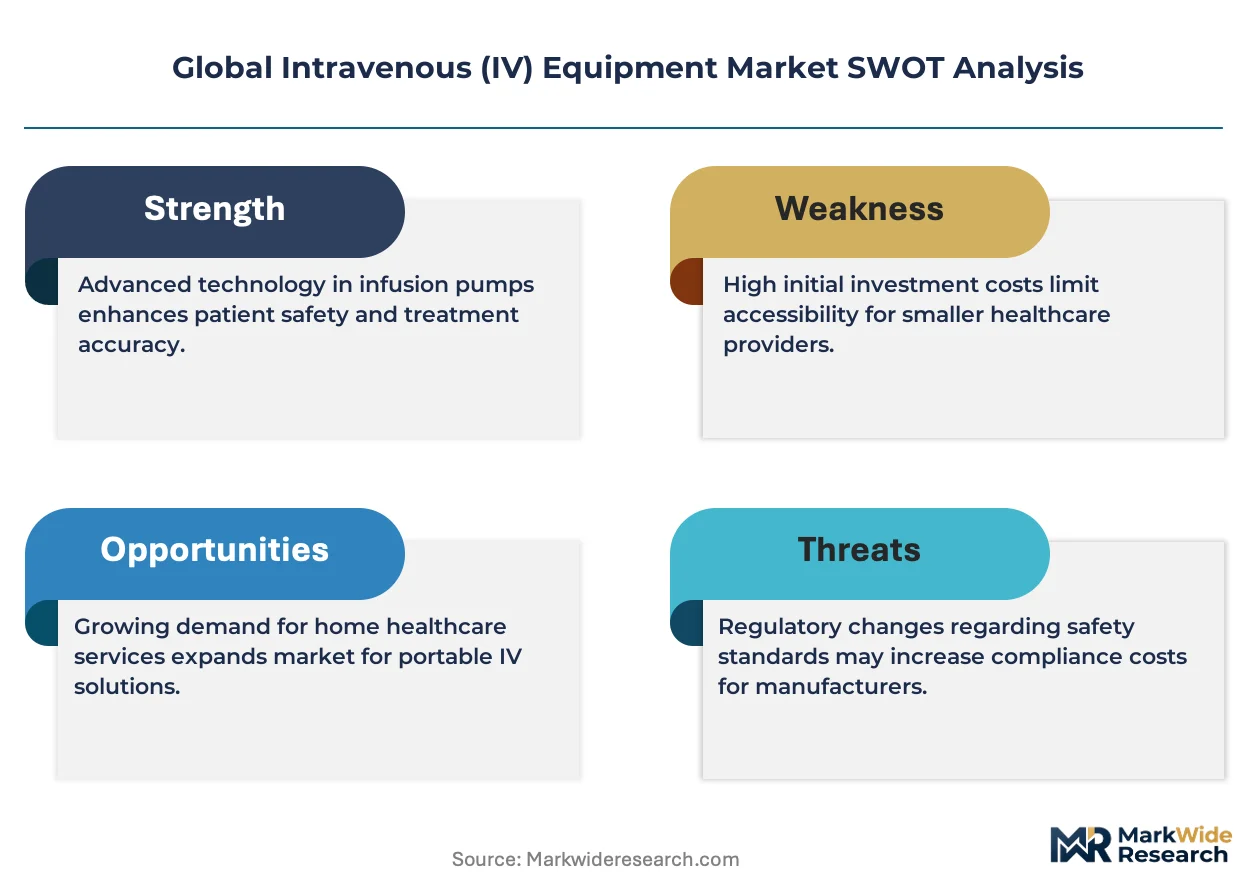
A capital-intensity divergence between high-volume manufacturers and precision-engineering specialists is redrawing competitive boundaries in IV equipment. Baxter International leverages its integrated plasma-derived therapy portfolio to anchor hospital system contracts across North America. B. Braun SE sustains manufacturing depth in infusion pumps through captive polymer compounding and mold fabrication in Germany and Malaysia. Terumo Corporation differentiates via micro-engineering leadership in safety-engineered IV catheters, competing against commodity producers with thinner-gauge, higher-flow designs.
Intravenous equipment encompasses sterile disposable and durable devices engineered for vascular access, fluid administration, and programmable drug delivery, typically manufactured from medical-grade PVC, polypropylene, or silicone with Luer-lock or needle-free connectors rated to withstand pressures exceeding 300 mmHg. Its primary commercial purpose centers on enabling precise, contamination-free therapeutic delivery in acute and ambulatory care settings. Infusion pumps and smart wireless-enabled systems command disproportionate margin pools as hospitals prioritize dose-error reduction and EMR integration, while IV sets and cannulas operate as high-velocity, price-sensitive categories where scale economics determine supplier viability. Electronic and wireless-enabled technologies are displacing mechanical alternatives in tertiary centers, though disposable platforms retain dominance in emerging markets and cost-constrained clinics.
The FDA's infusion pump guidance and premarket notification requirements shape product development timelines and interoperability investment levels for manufacturers seeking US market access, while the EU MDR and REACH substance restrictions compel material reformulation and extended clinical documentation for CE-marked devices. BIS certification in India and NMPA registration in China create parallel compliance tracks that favor multinationals with dedicated regulatory affairs infrastructure across jurisdictions. Stakeholders must monitor how FDA digital health pre-certification and EU AI Act risk classification will reshape validation burdens for algorithm-driven smart pumps before committing capital to next-generation platforms.
Market Dynamics
The FDA's pump interoperability mandate is compressing technology refresh cycles as integrated delivery networks consolidate supplier contracts around wireless-enabled platforms, forcing equipment vendors to accelerate R&D timelines or exit tertiary hospital procurement.
Growth Catalysts
- Smart Infusion System Mandates:The FDA's renewed emphasis on dose-error reduction systems is pulling capital toward EMR-integrated pumps in US tertiary hospitals.
- Surgical Volume Expansion:Rising procedure counts in Indian and Chinese tertiary centers are amplifying procurement of disposable IV sets and safety-engineered catheters.
- EU MDR Compliance Window:Extended clinical documentation requirements for CE-marked devices are favoring manufacturers with dedicated regulatory infrastructure across Germany, France, and Italy.
Market Restraints
- Medical-Grade Polymer Cost Volatility:PVC and polypropylene feedstock prices fluctuate with petrochemical indices, compressing margins on high-velocity disposable categories.
- German Precision Component Concentration:Captive mold fabrication and polymer compounding capabilities cluster in Baden-Württemberg and Bavaria, creating single-source vulnerability for European pump manufacturers.
- Mechanical Pump Substitution Ceiling:Cost-constrained clinics in rural India and Southeast Asia retain gravity-fed and mechanical alternatives, limiting smart system penetration.
Strategic Opportunities
- Brazilian Ambulatory Surgery Center Expansion:ANVISA's streamlined registration pathways for Class II devices are opening procurement channels outside hospital-centric distribution.
- Algorithm-Driven Dose Optimization:Convergence of machine learning analytics with infusion pump firmware is creating premium pricing tiers for closed-loop anesthesia and chemotherapy protocols.
- Japan's Telehealth Infrastructure Investment:METI funding for home-based infusion therapy is expanding addressable market beyond acute care into chronic disease management.
Industry Challenges
- Firmware Validation Talent Scarcity:FDA digital health pre-certification and EU AI Act risk classification requirements are outpacing supply of embedded systems engineers with medical device regulatory experience.
- Legacy EMR Integration Friction:Smart pump interoperability with hospital information systems demands custom HL7/FHIR middleware development, extending deployment timelines and inflating implementation costs.
- REACH Substance Reformulation Costs:ECHA restrictions on phthalate plasticizers in PVC IV sets are forcing material science investments without immediate pricing power recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intravenous (IV) Equipment Market |
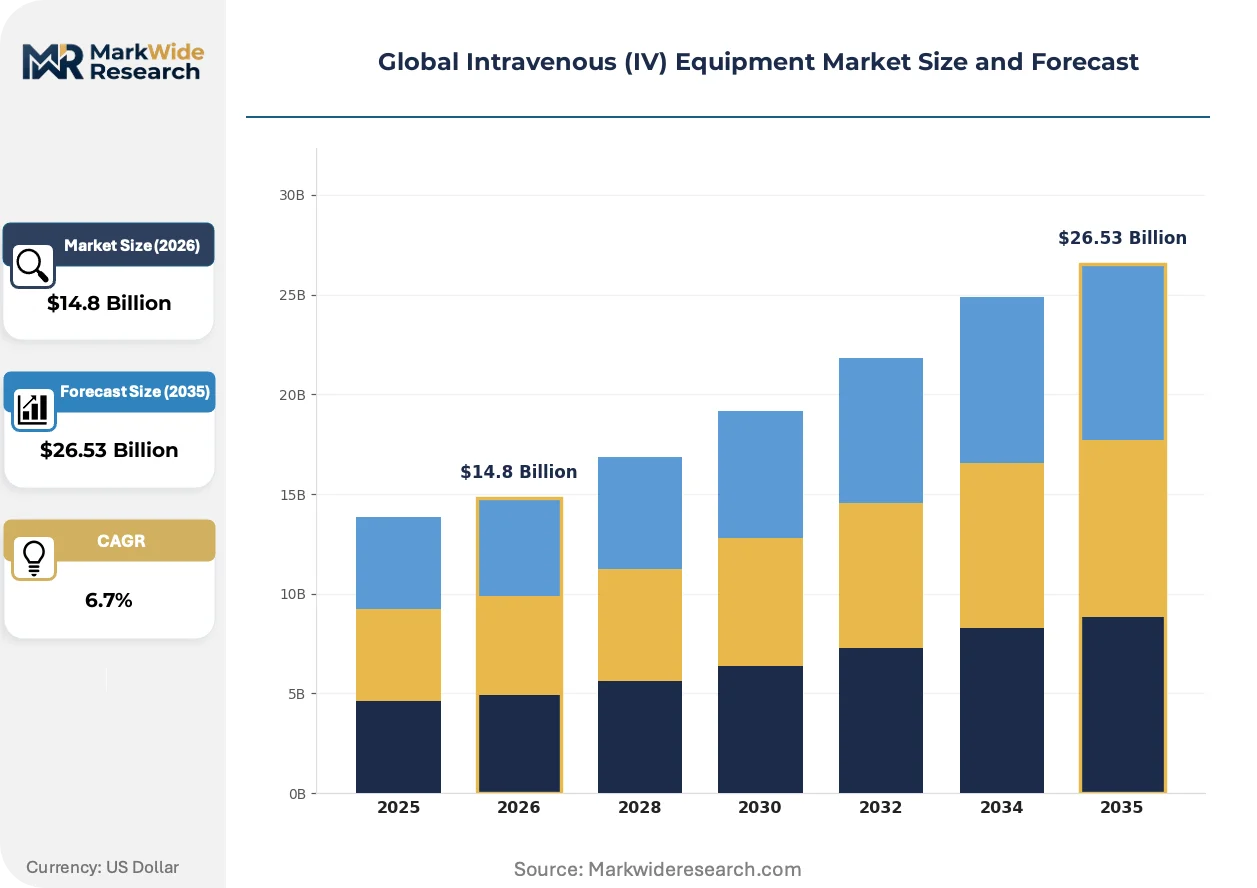
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IV Cannulas, Infusion Pumps, IV Sets, Syringe Pumps, IV Catheters Application: Fluid Replacement, Drug Delivery, Blood Transfusion, Nutritional Support, Anesthesia End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Healthcare Providers, Diagnostic Laboratories Technology: Mechanical, Electronic, Disposable, Smart, Wireless-enabled |
| Companies Covered | Baxter International, Terumo Corporation, Becton, Dickinson and Company, Moog Inc., Teleflex Incorporated, B. Braun SE, ICU Medical, Inc., Cardinal Health, Fresenius SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intravenous (IV) Equipment Market Shifts & Advancements
Wireless connectivity and predictive analytics are redrawing competitive boundaries between precision-engineering specialists and high-volume disposable manufacturers, with regulatory pre-certification emerging as the decisive capability differentiator.
Closed-loop smart infusion systems is bifurcating the installed base between algorithm-enabled platforms and mechanical alternatives. Tertiary hospitals in the United States and Germany are consolidating procurement around dose-error reduction systems with bi-directional EMR communication. This technology compression is squeezing mid-tier pump vendors without captive software development or cloud infrastructure capabilities.
REACH substance restrictions and EU MDR extended clinical documentation requirements are accelerating material reformulation timelines for CE-marked devices. Manufacturers must generate extended biocompatibility data for polymer alternatives to phthalate plasticizers in IV sets. German and French regulatory affairs teams are absorbing disproportionate compliance costs, favoring multinationals with dedicated European infrastructure over import-dependent distributors.
Hospital procurement departments are unbundling after-sales service contracts from equipment purchase agreements, forcing pump vendors to compete on discrete maintenance and calibration pricing. Integrated delivery networks in Texas, California, and Florida are piloting third-party biomedical engineering services for legacy system upkeep. This disintermediation is most visible in US markets where IDN consolidation has concentrated buyer leverage.
Global Intravenous (IV) Equipment Market Segmentation
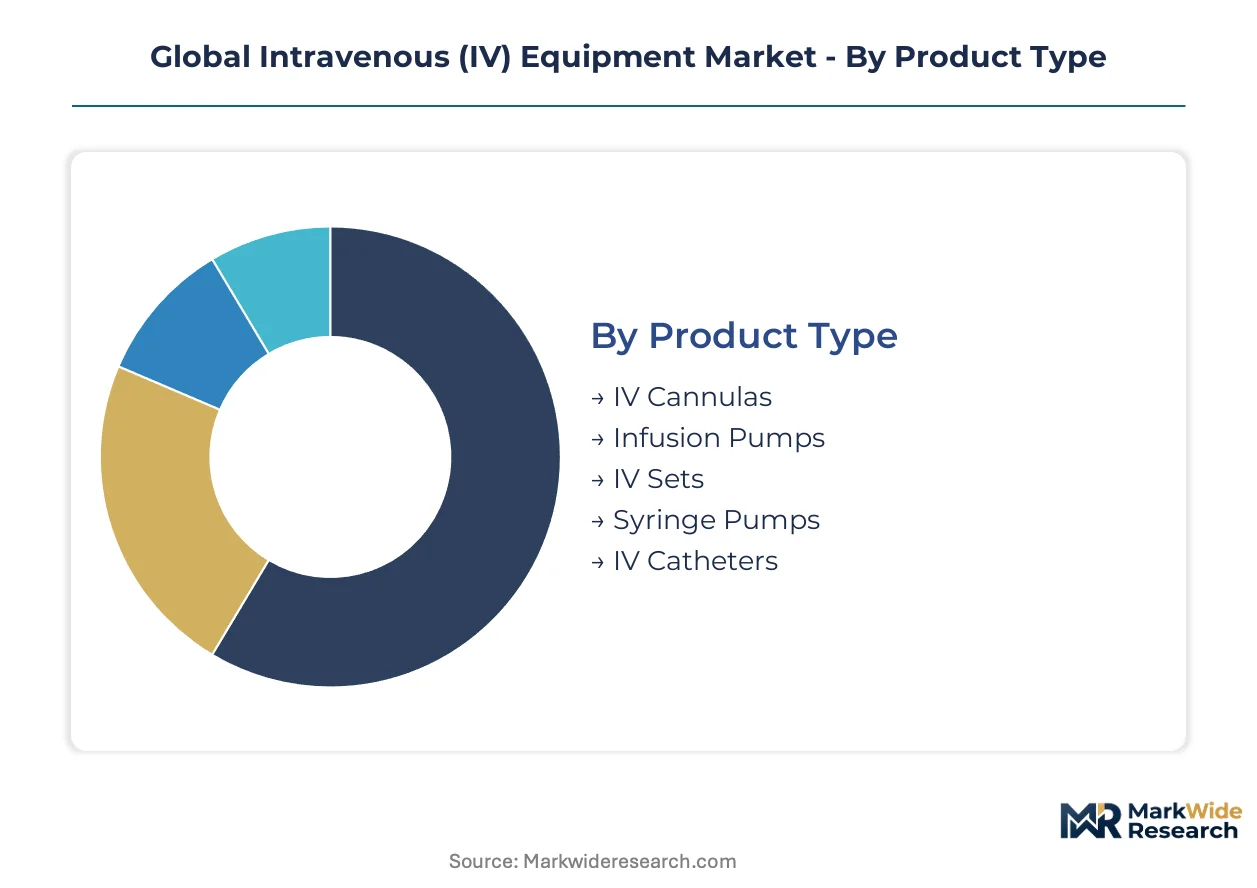
IV equipment segmentation reveals divergent margin profiles across product categories. Technology tiers and application settings determine pricing power, procurement cycles, and regulatory exposure for manufacturers.
Product Type:
Substitution pressure from smart systems is compressing demand for mechanical alternatives, reshaping competitive boundaries across disposable and durable device categories.
- Infusion Pumps:Programmable electromechanical devices deliver fluids, nutrients, and medications at controlled rates with dose-error reduction software. Demand concentrates in US tertiary hospitals where FDA interoperability mandates drive EMR-integrated procurement.
- IV Cannulas:Short-term vascular access devices manufactured from medical-grade stainless steel and fluorinated ethylene propylene. Surgical volume expansion in Indian and Chinese tertiary centers amplifies procurement of safety-engineered variants with needlestick protection.
- IV Sets:Sterile disposable tubing assemblies with Luer-lock connectors rated for pressures exceeding 300 mmHg. REACH substance restrictions in Europe compel material reformulation for phthalate-free PVC alternatives.
- Syringe Pumps:Precision volumetric devices for low-flow-rate medication delivery in anesthesia and neonatal intensive care. German and Japanese precision component manufacturers dominate high-accuracy variants.
- IV Catheters:Polyurethane or silicone devices for extended vascular access with integrated extension tubing. Home healthcare expansion in Japan and Brazil creates demand for patient-managed peripherally inserted central catheter systems.
IV sets anchor the volume base while infusion pumps gain share at the steepest rate.
Application:
Cost tier stratification separates high-acuity hospital applications from commoditized outpatient procedures, determining technology specifications and supplier selection criteria.
- Drug Delivery:Programmable infusion of chemotherapy, antibiotics, and biologics requiring dose-error reduction systems and closed-loop safety interlocks. US integrated delivery networks consolidate procurement around wireless-enabled platforms with bi-directional EMR communication.
- Anesthesia:Target-controlled infusion of hypnotics, analgesics, and neuromuscular blocking agents demanding algorithm-driven pharmacokinetic modeling. Tertiary hospitals in Germany and the United States pilot machine learning-optimized closed-loop systems.
- Fluid Replacement:Volume resuscitation and maintenance therapy using gravity-fed or pump-assisted crystalloid administration. Cost-constrained clinics in rural India retain mechanical alternatives, limiting smart system penetration.
- Blood Transfusion:Filtered delivery of packed red cells, platelets, and plasma with warming and pressure-assisted capabilities. Blood bank integration requirements favor suppliers with validated cold-chain compatibility.
- Nutritional Support:Enteral and parenteral feeding via dedicated pumps with occlusion detection and flush protocols. Home healthcare providers in Japan leverage METI-funded telehealth infrastructure for remote monitoring.
Fluid replacement commands the highest shipment volumes while drug delivery delivers the steepest margin expansion trajectory.
End User:
Customer type concentration determines service contract structures, with procurement leverage shifting from individual facilities toward consolidated integrated delivery networks.
- Hospitals:Tertiary acute care facilities with centralized pharmacy, biomedical engineering, and infection control infrastructure. Texas, California, and Florida IDNs unbundle after-sales service contracts from equipment purchase agreements, forcing discrete maintenance pricing competition.
- Ambulatory Surgical Centers:Outpatient procedure facilities requiring rapid turnover and sterilization-compatible disposables. ANVISA's streamlined Class II registration in Brazil opens procurement channels outside hospital-centric distribution.
- Home Healthcare Providers:Community-based infusion therapy services managing chronic disease patients with portable pump systems. Japan's METI funding for home-based therapy expands addressable market beyond acute care.
- Clinics:Primary and specialty care settings with limited biomedical engineering support favoring simple mechanical devices. Southeast Asian rural clinics retain gravity-fed alternatives due to cost constraints and intermittent power supply.
- Diagnostic Laboratories:Blood draw and specimen processing facilities requiring butterfly needles and evacuated tube systems with minimal vascular access duration. High-velocity disposable procurement prioritizes scale economics over technology integration.
Hospitals anchor the volume base while ambulatory surgical centers gain share at the steepest rate.
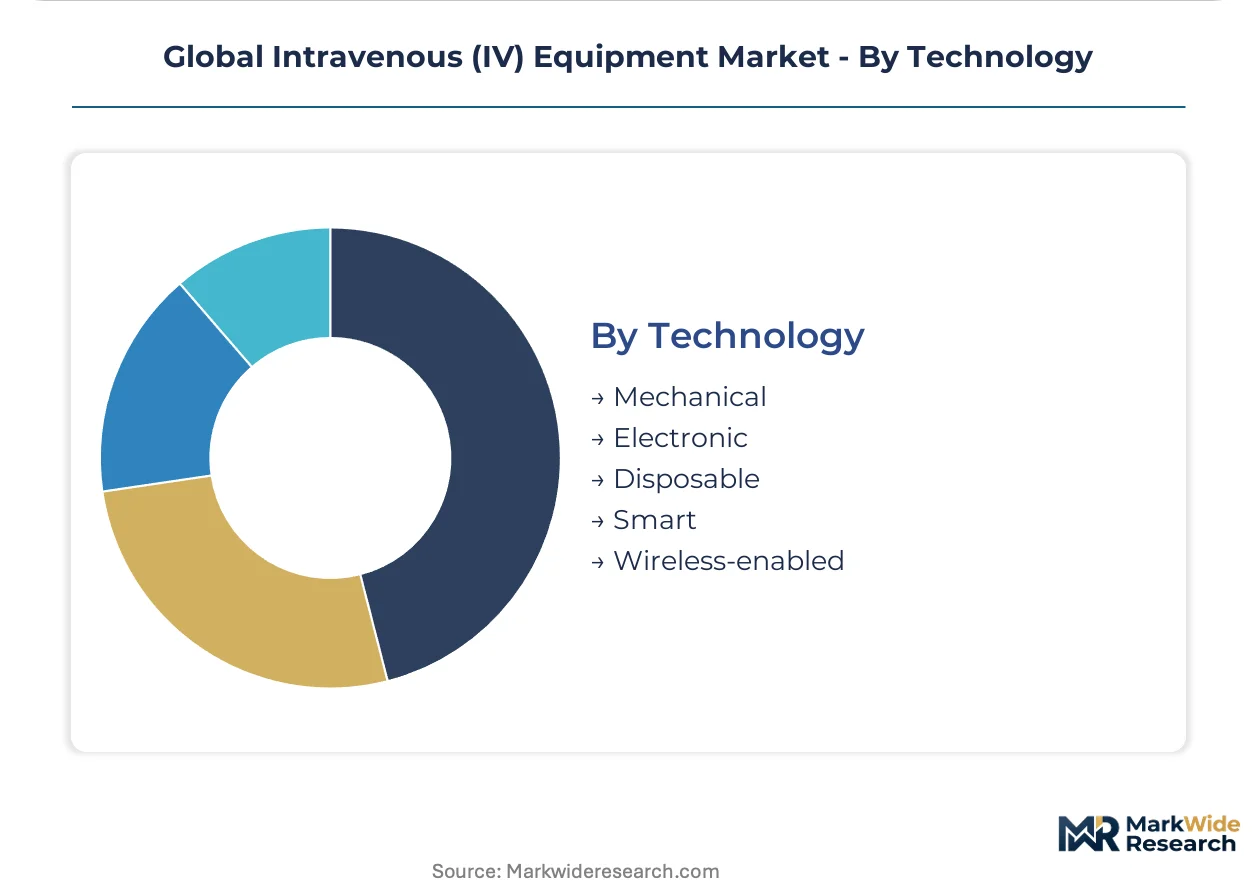
Technology:
Maturity gradients separate established mechanical platforms from emerging algorithm-enabled systems, with regulatory pre-certification emerging as the decisive capability differentiator.
- Smart:Dose-error reduction systems with drug libraries, bar-code verification, and predictive occlusion algorithms. FDA digital health pre-certification requirements and EU AI Act risk classification reshape validation burdens for firmware development.
- Wireless-enabled:Bi-directional communication with hospital information systems via HL7/FHIR protocols enabling remote monitoring and centralized alarm management. Legacy EMR integration friction extends deployment timelines and inflates implementation costs for US tertiary deployments.
- Electronic:Microprocessor-controlled flow rate regulation with battery backup and programmable profiles. Mid-tier pump vendors without captive software development capabilities face technology compression from smart system mandates.
- Disposable:Single-use gravity-fed or elastomeric devices with no electronic components, dominant in emerging markets and cost-constrained settings. PVC and polypropylene feedstock price volatility compresses margins on high-velocity categories.
- Mechanical:Spring-loaded or vacuum-driven systems without electrical power requirements, retained in resource-limited environments. Substitution ceiling limits penetration as smart systems displace electronic alternatives in tertiary centers.
Disposable technology anchors the volume base while wireless-enabled systems gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while cost-sensitive procurement dominates Indian and Chinese tertiary centers, creating divergent margin profiles across geographies. Germany sustains premium positioning through precision-engineering capabilities, whereas Brazil and Japan expand ambulatory and home-care channels respectively. Regulatory fragmentation across FDA, EU MDR, and NMPA compliance tracks shapes capital allocation for multinationals.
United States
Integrated delivery networks in Texas, California, and Florida consolidate supplier contracts around wireless-enabled platforms with bi-directional EMR communication. FDA interoperability mandates compress technology refresh cycles while digital health pre-certification requirements reshape validation burdens. Hospital procurement departments unbundle after-sales service contracts, forcing discrete maintenance pricing competition in Dallas-Fort Worth and Houston medical corridors.
Germany
Captive mold fabrication and polymer compounding capabilities in Baden-Württemberg and Bavaria sustain manufacturing depth for precision infusion components. EU MDR extended clinical documentation requirements favor manufacturers with dedicated European regulatory infrastructure. The Stuttgart and Munich industrial clusters absorb disproportionate compliance costs for phthalate-free material reformulation under REACH restrictions.
China
Surgical volume expansion in Beijing and Shanghai tertiary centers amplifies procurement of disposable IV sets and safety-engineered catheters. NMPA registration creates parallel compliance tracks that favor multinationals with dedicated regulatory affairs infrastructure. The Yangtze River Delta manufacturing belt concentrates domestic production of high-velocity disposable categories.
India
Rising procedure counts in Mumbai and Delhi tertiary hospitals drive demand for mechanical alternatives in cost-constrained settings. BIS certification requirements favor established players with localized quality management systems. The Maharashtra and Gujarat industrial corridors host contract manufacturing for export-oriented disposable tubing assemblies.
Brazil
ANVISA's streamlined registration pathways for Class II devices open procurement channels outside hospital-centric distribution in São Paulo and Rio de Janeiro. Ambulatory surgery center expansion creates demand for rapid-turnover sterilization-compatible disposables. The Southeast industrial belt concentrates regional distribution infrastructure for Latin American market access.
Global Intravenous (IV) Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the IV equipment market. The vendor base stratifies between precision-engineering specialists with captive polymer capabilities and high-volume disposable manufacturers competing on scale economics. Three archetypes dominate: integrated therapy conglomerates with hospital system anchoring power, mid-tier pump vendors facing technology compression, and regional disposable specialists. Competitive moves center on regulatory pre-certification investment and EMR interoperability partnerships.
Within the integrated therapy tier, Baxter International and Fresenius SE & Co. KGaA exemplify conglomerates leveraging diversified medical portfolios to anchor hospital system contracts. B. Braun SE occupies a position among precision-engineering specialists with captive manufacturing depth. Terumo Corporation represents micro-engineering leadership archetypes competing through thinner-gauge, higher-flow catheter designs. These three anchors illustrate how geographic manufacturing concentration and regulatory infrastructure scale separate viable suppliers from compressed mid-tier competitors.
| Leading Market Players |
|---|
| Baxter International |
| Terumo Corporation |
| Becton, Dickinson and Company |
| Moog Inc. |
| Teleflex Incorporated |
| B. Braun SE |
| ICU Medical, Inc. |
| Cardinal Health |
| Fresenius SE & Co. KGaA |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for medical-grade polymers tether pricing power to petrochemical index volatility, compressing margins on high-velocity disposable categories while concentrating margin capture in smart pump systems with captive firmware development. This lead-time exposure shapes how manufacturers allocate capital between commodity IV sets and wireless-enabled platforms with bi-directional EMR integration.
Pricing Analysis
Configured-to-order pricing for EMR-integrated smart pumps commands a substantial premium over standard mechanical alternatives. Three-tier pricing structure across premium, standard, and economy levels separates FDA-pre-certified wireless systems from electronic mid-tier devices and gravity-fed disposables. Cost compression in disposable categories intensifies because PVC and polypropylene feedstock prices fluctuate with energy markets. Ambulatory surgical centers in Brazil exhibit the highest price sensitivity, while US integrated delivery networks prioritize interoperability over unit cost.
Supply Chain Analysis
Germany and Malaysia anchor captive polymer compounding and precision mold fabrication for infusion pump components, while China concentrates high-velocity disposable manufacturing in the Yangtze River Delta belt. Medical-grade PVC, polypropylene, and silicone elastomers feed from petrochemical complexes with price volatility exposure. Single-source vulnerability clusters in Baden-Württemberg precision engineering corridors. Distribution runs through hospital-centric procurement networks consolidating around integrated delivery network contracts in Texas, California, and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Intravenous (IV) Equipment Market represents a high-growth disruption as FDA pump interoperability mandates compress technology refresh cycles and algorithm-driven dose optimization redefines premium pricing tiers.
For Market Incumbents: Fortify regulatory pre-certification infrastructure against firmware validation talent scarcity by embedding embedded systems engineers within European and US regulatory affairs teams. Deepen backward integration into polymer compounding to offset feedstock cost volatility threatening disposable margins. Prioritize cloud infrastructure partnerships that accelerate HL7/FHIR middleware deployment timelines for IDN procurement consolidation. For New Entrants and Emerging Players: Differentiate on algorithm-driven closed-loop anesthesia protocols where machine learning analytics create defensible premium positioning against mechanical alternatives. Target Brazilian ambulatory surgery centers through ANVISA's streamlined Class II registration pathways as the most penetrable geography outside hospital-centric distribution. Pursue telehealth infrastructure partnerships in Japan to access METI-funded home infusion therapy expansion. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical conglomerates seeking to divest non-core pump portfolios amid technology compression pressures. Long-term viability over a multi-year horizon hinges on regulatory pre-certification scale and EMR interoperability depth. Monitor FDA digital health pre-certification approval velocity as the decisive inflection signal for algorithm-enabled platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification | Accelerates smart pump validation timelines for US market access against interoperability mandates. |
| EU MDR Extended Clinical Documentation | Favors manufacturers with dedicated European regulatory infrastructure over import-dependent distributors. |
| Hospital System Partnership | Secures long-term procurement contracts as IDNs consolidate supplier relationships around wireless platforms. |
| Software Companion Development | Enables predictive occlusion algorithms and dose-error reduction systems commanding premium pricing tiers. |
| Reimbursement Strategy | Aligns smart infusion capabilities with CMS quality metrics driving IDN capital allocation decisions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract awards. Interviews with biomedical engineers, hospital purchasing committee members, infusion pump product managers, and regulatory affairs specialists inform demand-side and supply-side validation. Bottom-up shipment modeling triangulates against top-down expenditure analysis across the analysis window.
Segmentation dimensions modeled span product type, application setting, end-user category, and technology tier across the projection horizon. CAGRs derive from regression analysis of historical shipment velocity against surgical volume expansion and regulatory compliance investment cycles. Forecast inputs incorporate REACH substance reformulation timelines and NMPA registration pathway durations for China market access.
The analysis sits within stated boundaries; outcomes outside sustained FDA interoperability enforcement or abrupt petrochemical price spikes would require recalibration. Forecasts reflect documented assumptions regarding smart system adoption curves and IDN consolidation trajectories. Recalibration cycles align with material shifts in regulatory pre-certification requirements and EMR integration standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Automatic Stair Climbing Wheelchair Market
Medical Devices
Spinal Implant Market
Medical Devices
Snare Devices Market
Medical Devices
Global Non Fusion Spinal Devices Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Global Mechanical Ventilators Market
Medical Devices
Insulin Storage Devices Market
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
Scoliosis Traction Chairs Market
Medical Devices
Ear Tube Devices Market
Medical Devices
Electrophysiology Ablation Market
Medical Devices
Airway Management Devices Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Soft Tissue Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Medical Device and Accessories Market