
 Implantable Drug Infusion Pumps Market | 2026-2036
Implantable Drug Infusion Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Implantable Drug Infusion Pumps Market Outlook
Germany is reshaping European manufacturing capacity for precision implantable drug delivery systems through dedicated medtech production corridors near Tuttlingen and Freiburg. Medtronic leverages its vertically integrated supply chain for implantable pump components across neurological and diabetes applications. Flowonix Medical specializes in intrathecal delivery platforms for chronic pain management, sustaining its position through focused R&D investment in programmable micro-pump architectures. Tricumed Medizintechnik anchors German engineering standards in mechanical reservoir pump designs for regional anesthesia.
Implantable drug infusion pumps are sealed, biocompatible devices surgically placed beneath the skin to deliver precise medication doses directly to targeted anatomical sites via catheters, typically constructed from titanium or polymer housings with silicone elastomer reservoirs capable of multi-year implantation cycles. These systems serve chronic therapeutic categories requiring site-specific, continuous, or patient-controlled dosing regimens that oral or external infusion methods cannot reliably achieve. Pain management pumps currently dominate clinical volume due to established intrathecal opioid protocols, while electronic pump technology captures premium margin pools through programmable flow-rate algorithms and remote monitoring integration. Chemotherapy pumps represent the fastest-growing product category as regional oncology protocols expand beyond hepatic arterial infusion into peritoneal and limb-perfusion applications.
FDA premarket approval requirements for combination drug-device products enforce rigorous biocompatibility, battery longevity, and catheter occlusion testing standards that extend development timelines but elevate barrier-to-entry protections for qualified manufacturers. The EU Medical Device Regulation mandates notified body oversight and unique device identification traceability, reshaping market access conditions for implantable pump systems across European member states. Stakeholders must monitor evolving reimbursement coding decisions for implantable infusion therapies across public and private payers, as coverage determinations directly influence physician prescribing patterns and patient access thresholds.
Market Dynamics
Oncology departments are expanding regional chemotherapy protocols, forcing manufacturers to redesign pump architectures for peritoneal and limb-perfusion applications while navigating FDA combination product approval timelines.
Growth Catalysts
- Regional Cancer Protocols:Hepatic arterial infusion standards are extending into peritoneal and isolated limb perfusion, creating demand for programmable flow-rate systems in academic medical centers.
- Medicare Reimbursement Codes:United States coverage determinations for implantable infusion therapies reduce patient access thresholds and stabilize physician prescribing confidence.
- Chronic Pain Prevalence:Established intrathecal opioid delivery protocols sustain volume demand across pain management clinics and ambulatory surgical centers.
Market Restraints
- Titanium Supply Concentration:Biocompatible housing materials depend on limited specialty metal suppliers, exposing manufacturers to input cost volatility and long-lead procurement cycles.
- FDA Premarket Approval Timelines:Combination drug-device requirements enforce extended biocompatibility and battery longevity testing, compressing competitive windows for new entrants.
- External Infusion Substitution:Ambulatory external pumps with smart connectivity threaten intrathecal pain management volume in cost-sensitive payer environments.
Strategic Opportunities
- Remote Monitoring Integration:Bluetooth-enabled dose tracking and physician dashboard connectivity create premium positioning for electronic pump platforms against mechanical alternatives.
- German Medtech Corridors:Precision manufacturing clusters near Tuttlingen and Freiburg offer contract development capabilities for programmable micro-pump architectures.
- EU MDR Traceability Mandates:Unique device identification requirements favor manufacturers with established quality management systems, consolidating market access for prepared suppliers.
Industry Challenges
- Biocompatibility Certification Complexity:Silicone elastomer reservoir materials require extensive cytotoxicity and sensitization testing under ISO 10993 standards, extending development cycles.
- Catheter Occlusion Engineering:Multi-year implantation reliability demands advanced fluid dynamics modeling and proprietary coating technologies that concentrate expertise among established suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implantable Drug Infusion Pumps Market |
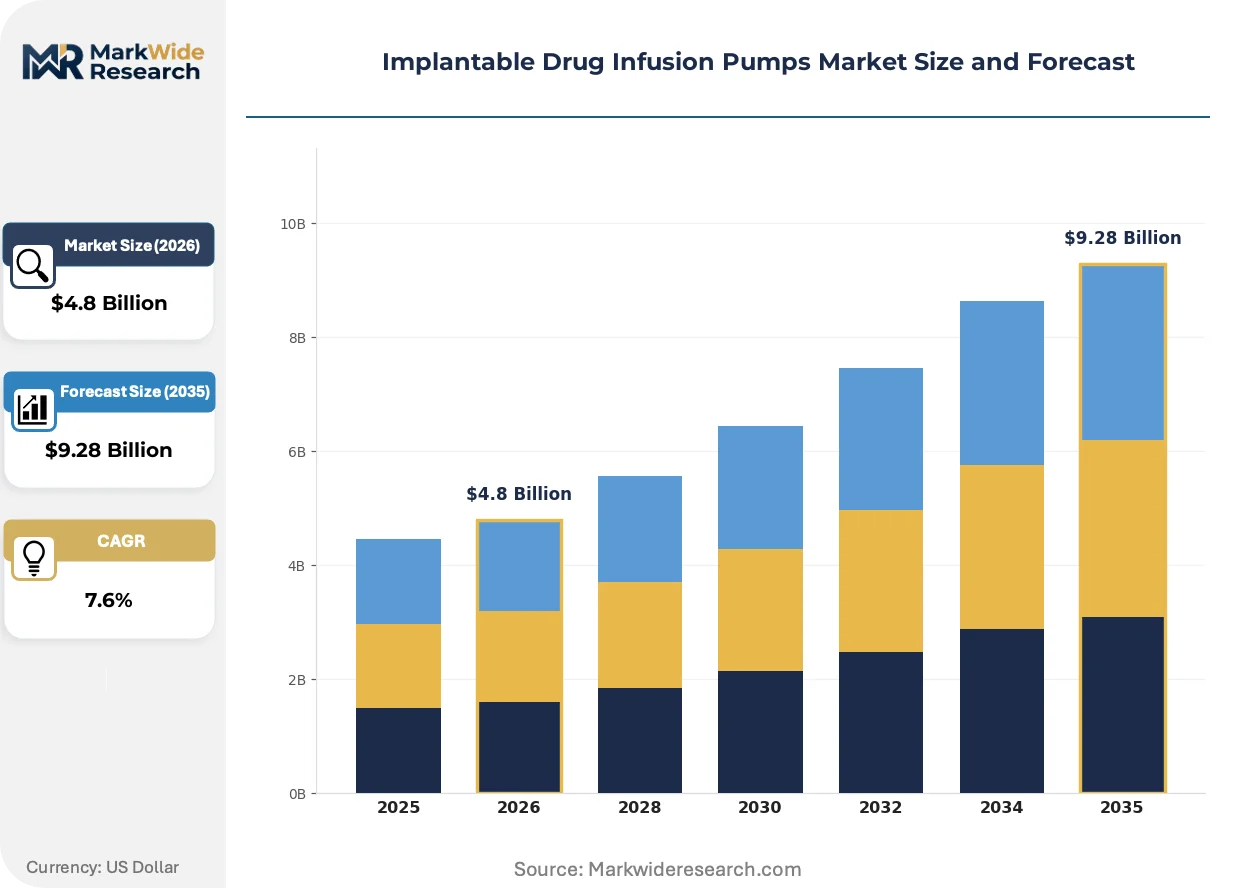
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Pain Management Pumps, Chemotherapy Pumps, Antibiotic Pumps Technology: Micro-pump Technology, Electronic Pump Technology, Mechanical Pump Technology, Reservoir Pump Technology End User: Hospitals, Home Healthcare, Specialty Clinics, Ambulatory Surgical Centers Delivery Mode: Intravenous, Intra-arterial, Subcutaneous, Epidural |
| Companies Covered | Medtronic, Flowonix Medical, Tricumed Medizintechnik, Boston Scientific Corporation, Smiths Medical, Intera Oncology, Infusyn Therapeutics, B. Braun, ICU Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implantable Drug Infusion Pumps Market Strategic Shifts
Programmable micro-pump architectures are displacing mechanical reservoir designs across chronic therapeutic categories, while regulatory traceability mandates and shifting procurement models reshape competitive positioning.
Closed-loop dosing algorithms with real-time physiological feedback are digitizing implantable pump functionality. Academic medical centers in the United States are piloting these systems for intrathecal pain management at accelerated adoption curves. The technology is digitizing clinical workflow integration by enabling remote titration adjustments and reducing in-person intervention frequency.
EU Medical Device Regulation mandates unique device identification traceability across implantable pump systems. Notified body oversight requirements have reshaped market access conditions, elevating compliance costs for smaller manufacturers. Electronic pump categories face the steepest certification burdens, driving consolidation toward vertically integrated suppliers with captive regulatory affairs capabilities.
Hospital procurement committees are unbundling device acquisition from catheter placement and refill services, compressing vendor switching cycles. Group purchasing organizations are consolidating implantable pump sourcing across regional health systems, displacing individual physician preference contracting. This pattern is most visible in United States integrated delivery networks where standardized formularies now govern intrathecal therapy selection.
Implantable Drug Infusion Pumps Market Segmentation
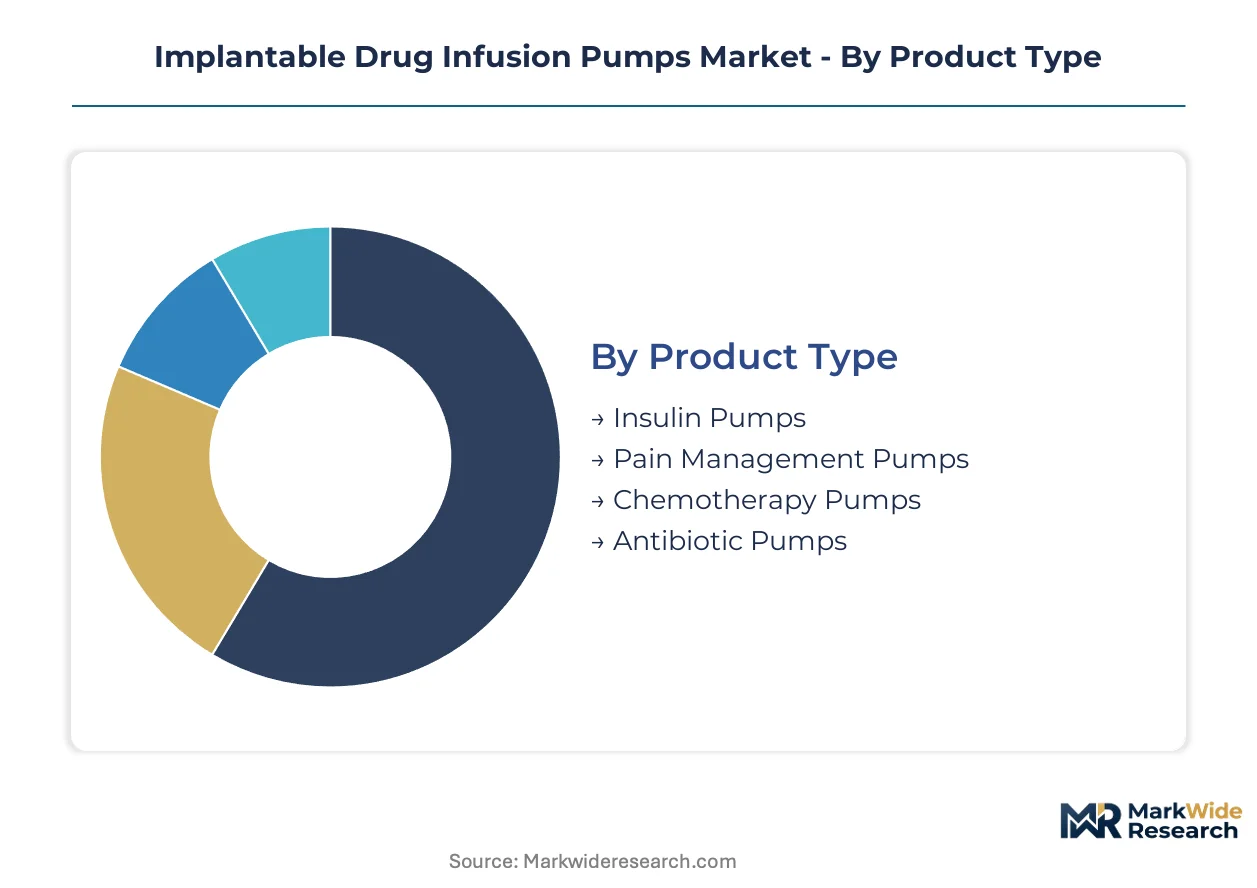
Product architecture and delivery site specificity determine reimbursement pathways and procurement decisions across implantable pump categories. Technology maturity and end-user setting create divergent margin profiles that reshape competitive positioning.
Product Type:
Cost tier stratification separates chronic disease management from acute oncology interventions, with reimbursement intensity varying by therapeutic category and implantation complexity.
- Insulin Pumps:Titanium-housed devices with programmable basal-bolus algorithms serve type 1 diabetes patients requiring precise glycemic control. Demand concentrates in United States academic medical centers where endocrinology departments prioritize closed-loop integration with continuous glucose monitors.
- Pain Management Pumps:Intrathecal opioid delivery systems with silicone elastomer reservoirs dominate clinical volume through established palliative care protocols. United States pain clinics and ambulatory surgical centers sustain procurement despite external pump substitution threats in cost-sensitive environments.
- Chemotherapy Pumps:Regional cancer therapy devices for hepatic arterial and peritoneal infusion.
- Antibiotic Pumps:Targeted antimicrobial delivery for osteomyelitis and deep tissue infections.
Pain management pumps command the established base. The steepest expansion runs through chemotherapy pumps as regional oncology protocols multiply.
Technology:
Application requirements dictate pump architecture selection, with programmable systems capturing premium positioning against mechanical alternatives in chronic therapeutic settings.
- Micro-pump Technology:Miniaturized piezoelectric or electroosmotic actuators enable precise nanoliter-per-hour flow control for intrathecal and subcutaneous applications. German precision manufacturing corridors near Tuttlingen anchor production capacity for these architectures.
- Electronic Pump Technology:Battery-powered systems with programmable flow-rate algorithms and Bluetooth connectivity support remote monitoring integration. United States Medicare reimbursement codes favor these platforms for chronic pain management, though FDA combination product approval timelines compress competitive windows.
- Mechanical Pump Technology:Pressure-driven or osmotic systems without electronic components for cost-sensitive deployments.
- Reservoir Pump Technology:Passive silicone elastomer storage with fixed-rate delivery for short-term antibiotic infusion.
Electronic pump technology captures premium margins. Micro-pump architectures are gaining share fastest through miniaturization demands.
End User:
Customer type determines service bundling models and procurement authority, with institutional buyers increasingly unbundling device acquisition from placement and refill services.
- Hospitals:Integrated delivery networks with standardized formularies govern intrathecal therapy selection across oncology and anesthesia departments. United States hospital procurement committees now separate pump acquisition from catheter placement contracts, compressing vendor switching cycles.
- Home Healthcare:Remote monitoring-enabled platforms support patient-managed refills and dose adjustments outside clinical settings.
- Specialty Clinics:Pain management and endocrinology practices with physician preference contracting.
- Ambulatory Surgical Centers:Cost-optimized mechanical pump procurement for same-day implantation procedures.
Hospitals anchor volume concentration. Home healthcare is expanding most quickly through remote monitoring integration.
Delivery Mode:
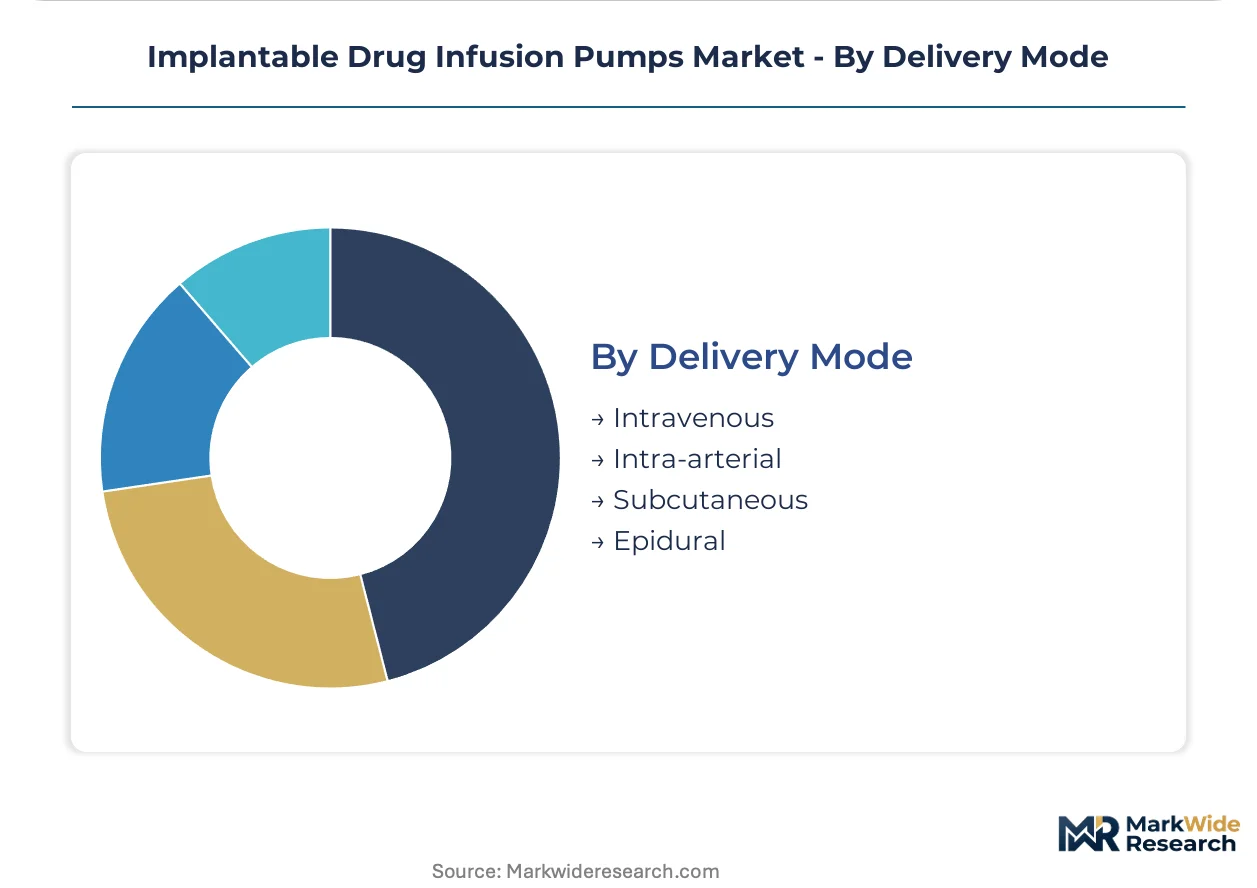
Volume and anatomical target site create distinct engineering requirements for catheter design and biocompatibility certification.
- Intravenous:Systemic delivery through central venous access ports for chemotherapy and antibiotic applications.
- Intra-arterial:Regional perfusion via hepatic or limb arteries enables concentrated dosing with reduced systemic toxicity. Academic medical centers in the United States are extending these protocols from hepatic arterial infusion into isolated limb perfusion for melanoma and sarcoma.
- Subcutaneous:Insulin delivery with programmable basal rates for diabetes management.
- Epidural:Local anesthetic and opioid administration for post-surgical and chronic pain control.
Intra-arterial delivery commands oncology premium positioning. Epidural applications sustain the broadest installed base across pain management protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways anchor United States demand, while EU MDR traceability mandates and German precision manufacturing clusters reshape European access conditions. Medicare reimbursement policies and notified body oversight create divergent regulatory environments across major markets.
United States
Medicare reimbursement codes for implantable infusion therapies stabilize physician prescribing confidence across oncology and pain management departments. FDA combination product requirements enforce extended biocompatibility testing that elevates barriers for new entrants. Academic medical centers in Boston and Houston pilot closed-loop dosing algorithms with real-time physiological feedback.
Germany
Notified body oversight under EU MDR mandates unique device identification traceability across implantable pump systems. Precision manufacturing corridors near Tuttlingen and Freiburg anchor production capacity for programmable micro-pump architectures. Baden-Württemberg engineering standards concentrate expertise in mechanical reservoir designs for regional anesthesia applications.
Japan
PMDA regulatory frameworks govern combination drug-device approvals with emphasis on battery longevity and catheter reliability testing. Chronic pain prevalence sustains intrathecal opioid delivery volume through established palliative care protocols. Osaka-based manufacturing clusters specialize in titanium housing fabrication for multi-year implantation cycles.
United Kingdom
NICE technology appraisals influence National Health Service procurement decisions for implantable chemotherapy pumps in regional oncology protocols. MHRA post-market surveillance requirements align with EU MDR standards for biocompatibility certification. London teaching hospitals extend hepatic arterial infusion standards into peritoneal applications.
Switzerland
Swissmedic approval pathways emphasize ISO 10993 biocompatibility standards for silicone elastomer reservoir materials. Premium pricing environments support electronic pump platforms with Bluetooth-enabled remote monitoring integration. Basel-area medtech clusters focus on programmable flow-rate algorithms for chronic therapeutic categories.
Implantable Drug Infusion Pumps Market Competitive Environment
Vertically integrated conglomerates and specialized intrathecal delivery specialists split the market into distinct capability tiers. Consolidation pressures favor suppliers with captive regulatory affairs capabilities and established quality management systems. Diversified medical technology conglomerates and focused pain management specialists represent the dominant strategic archetypes. Competitive moves concentrate on backward integration into titanium component supply and technology licensing for programmable micro-pump architectures.
Among diversified medical technology conglomerates, Medtronic exemplifies the vertically integrated archetype across neurological and diabetes pump applications. Flowonix Medical occupies a position within the specialized intrathecal delivery tier, representing focused R&D investment in programmable architectures. Tricumed Medizintechnik anchors German engineering standards in mechanical reservoir pump designs, sitting within the precision manufacturing specialist tier.
| Leading Market Players |
|---|
| Medtronic |
| Flowonix Medical |
| Tricumed Medizintechnik |
| Boston Scientific Corporation |
| Smiths Medical |
| Intera Oncology |
| Infusyn Therapeutics |
| B. Braun |
| ICU Medical |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in precision titanium component machining across Osaka-based manufacturing clusters is elevating supplier pricing power and compressing margins for pump assemblers unable to secure long-term offtake agreements. This utilization squeeze propagates through the value chain, forcing device manufacturers to absorb input volatility or pass costs to hospital procurement committees with tightening formulary budgets.
Pricing Analysis
Geographic price spreads between United States academic medical centers and European national health systems exceed 40 percent for equivalent electronic pump platforms, reflecting reimbursement intensity differentials rather than manufacturing cost variation. Pricing stratifies across premium programmable systems with remote monitoring integration, standard electronic platforms with basic titration capability, and economy mechanical alternatives for short-term antibiotic infusion. Pricing pressure stems from group purchasing organization consolidation across United States integrated delivery networks, which unbundles device acquisition from service contracts and compresses vendor switching cycles. Ambulatory surgical centers exhibit the highest price sensitivity due to fixed reimbursement schedules, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Upstream feedstock concentration in specialty-grade titanium sponge production centers on Japan, Russia, and Kazakhstan, with limited qualified suppliers for biocompatible alloy formulations meeting ASTM F67 standards. Component fabrication for pump housings draws from precision machining clusters in Germany, Switzerland, and Japan, while silicone elastomer reservoir materials source from certified medical-grade polymer suppliers in the United States and Germany. Single-source vulnerability in battery cell supply for electronic platforms creates exposure to raw material cost volatility in lithium and cobalt markets. Distribution runs through authorized distributor networks with technical service capabilities, bypassing general medical device wholesalers for implantable categories requiring specialized handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from refill synchronization programs and remote monitoring subscriptions is expanding faster than hardware sales, transforming capital equipment vendors into recurring-revenue platforms. This shift rewards manufacturers that integrate software companion applications and predictive maintenance algorithms into their commercial models.
For Market Incumbents: Harden regulatory affairs capabilities to defend against FDA combination product approval timeline compression, which threatens to erode first-mover advantages in programmable architectures. Prioritize backward integration into titanium component supply through captive machining capacity or exclusive offtake agreements with Osaka-based fabricators. Deepen hospital system partnerships to lock in standardized formulary placement before procurement committee unbundling accelerates. For New Entrants and Emerging Players: Pursue white-space opportunities in peritoneal chemotherapy pump designs, where regional oncology protocol expansion outpaces incumbent product development cycles. Target cost-optimized mechanical platforms for antibiotic infusion in ambulatory surgical centers, where price sensitivity exceeds brand loyalty. Enter through contract development partnerships with German precision manufacturing corridors near Tuttlingen to bypass capital-intensive facility buildout. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with integrated remote monitoring platforms and established refill service networks, indicating superior long-term cash flow quality across the 5-10 year investment horizon. Prioritize acquisition targets with captive regulatory affairs capabilities and EU MDR certification track records. Watch for inflection signals in Medicare reimbursement coding decisions for implantable infusion therapies, which directly govern physician prescribing confidence and patient access thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Premarket approval for combination drug-device products enforces extended biocompatibility testing that elevates barriers for new entrants. |
| CE Marking Pathway | EU MDR traceability mandates favor manufacturers with established quality management systems and unique device identification capabilities. |
| Hospital System Partnership | Integrated delivery network formulary placement secures volume commitments before procurement committee unbundling accelerates vendor switching. |
| Software Companion Development | Bluetooth-enabled dose tracking and physician dashboard connectivity create premium positioning against mechanical alternatives in chronic pain management. |
| Reimbursement Strategy | Medicare coverage determinations for implantable infusion therapies directly influence physician prescribing patterns and patient access thresholds. |
Study Parameters
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at combination product manufacturers, then refined through secondary validation. Primary fieldwork encompassed structured interviews with clinicians administering intrathecal therapies, procurement officers at academic medical centers, and aftermarket service heads at distributor organizations. Secondary sources included FDA 510(k) and PMA filings, CMS Medicare reimbursement coding databases, hospital procurement contract repositories, and EU MDR notified body certification records. Bottom-up volume estimates by product segment were triangulated against top-down market sizing derived from manufacturer revenue disclosures and import-export trade data.
Demand-supply balance modeling across the projection horizon incorporated installed base growth, replacement cycle dynamics, and regional regulatory approval velocity by market. Segmentation dimensions included product architecture, delivery mode, end-user setting, and geographic reimbursement cluster. CAGRs were derived from regression analysis of historical volume trends adjusted for protocol adoption curves in regional oncology and chronic pain management. Industry-specific forecast inputs captured FDA premarket approval pipeline status, EU MDR transition timelines, and Medicare coverage determination schedules.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, specialty metal commodity prices, or payer reimbursement intensity would shift the trajectory materially. Forecasts reflect documented assumptions regarding regulatory approval timelines, protocol adoption rates, and competitive entry patterns. Cross-checking against external benchmarks such as CMS procedure volume data and manufacturer order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiac Valve Market
Cardiovascular Devices
Global Valvular Heart Disease Treatment Market
Cardiovascular Devices
Patient-Controlled Injectors Market
Cardiovascular Devices
Global Cardiac Resynchronization Therapy Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
Global Aortic Valve Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Global Abdominal Aortic Aneurysm Treatment Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Japan Cardiovascular Devices Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Peripheral Vascular Devices Market