
 Australia Laser Hair Removal Market | 2026-2036
Australia Laser Hair Removal Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Laser Hair Removal Market Intelligence
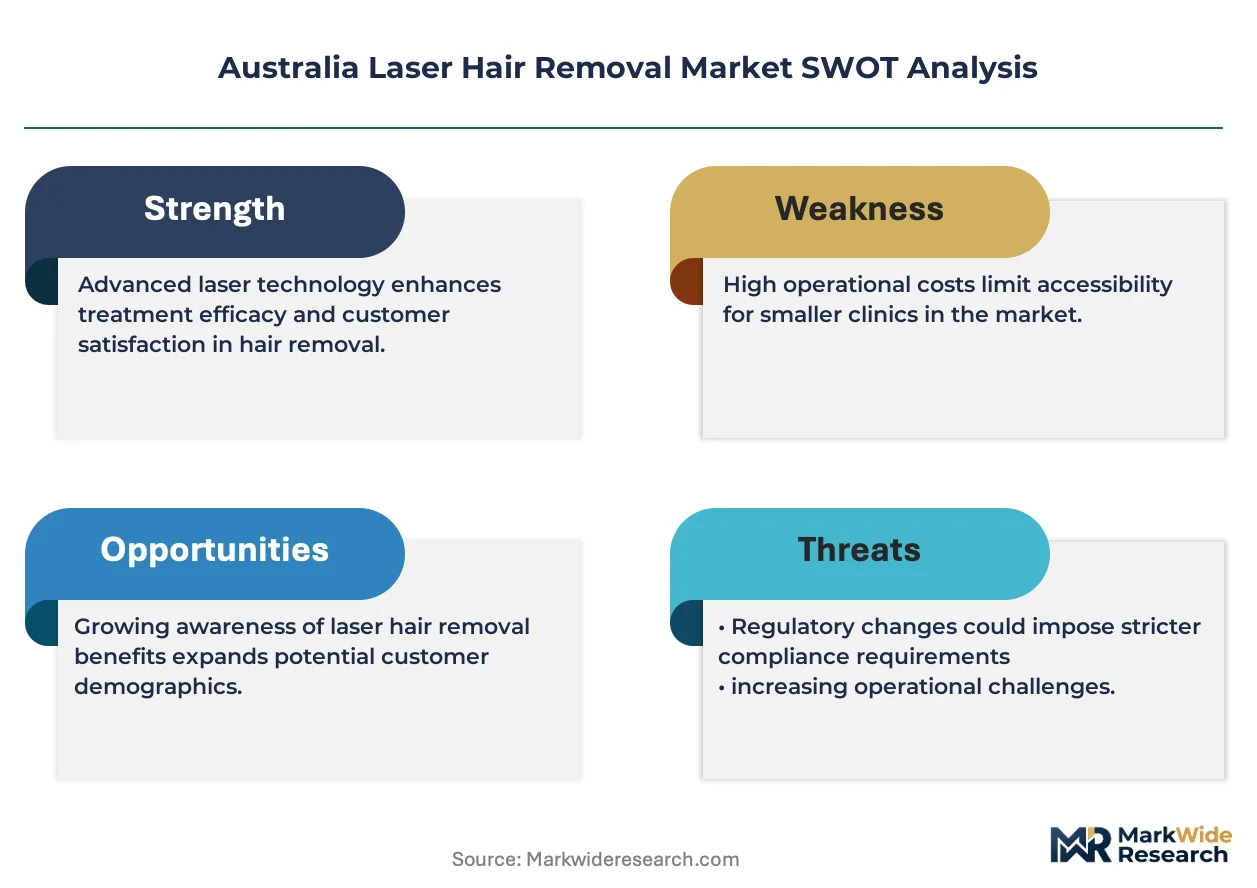
Qualified dermal therapist availability is bifurcating the Australia laser hair removal landscape into premium clinic chains and budget service corridors. Laser Clinics Australia leverages its national footprint to sustain volume leadership across metropolitan catchments. Clear Skincare Clinics anchors its position through vertical control of training academies and proprietary protocols. Results Laser Clinic differentiates via concentrated presence in Sydney and Melbourne corridors where disposable income thresholds support repeat treatment cycles.
Laser hair removal employs selective photothermolysis to target melanin within hair follicles using wavelengths between 755 nm and 1064 nm, with diode and alexandrite systems dominating professional installations for their efficacy across Fitzpatrick skin types I through IV. The technology serves both cosmetic hair reduction and adjunctive skin rejuvenation applications in clinical settings. Diode laser systems occupy the largest installed base among product categories due to versatility across diverse patient profiles, while Nd:YAG configurations are gaining traction for darker skin type compatibility. Dermatology clinics capture the highest margin pool within end user segments, though medical spas are expanding share through bundled aesthetic service menus.
TGA device registration requirements and AS/NZS 4173 laser safety standards shape equipment procurement decisions and clinic accreditation pathways across Australian states. Therapeutic Goods Administration oversight of intense pulsed light and laser apparatus ensures minimum performance thresholds that filter lower-tier imports from commercial distribution. State-based radiation health regulators in Queensland, Western Australia, and South Australia impose supplementary operator licensing mandates that vary in stringency. Stakeholders must monitor harmonization pressure between federal device standards and emerging state-level cosmetic procedure reforms that could reshape clinic compliance burdens and capital requirements.
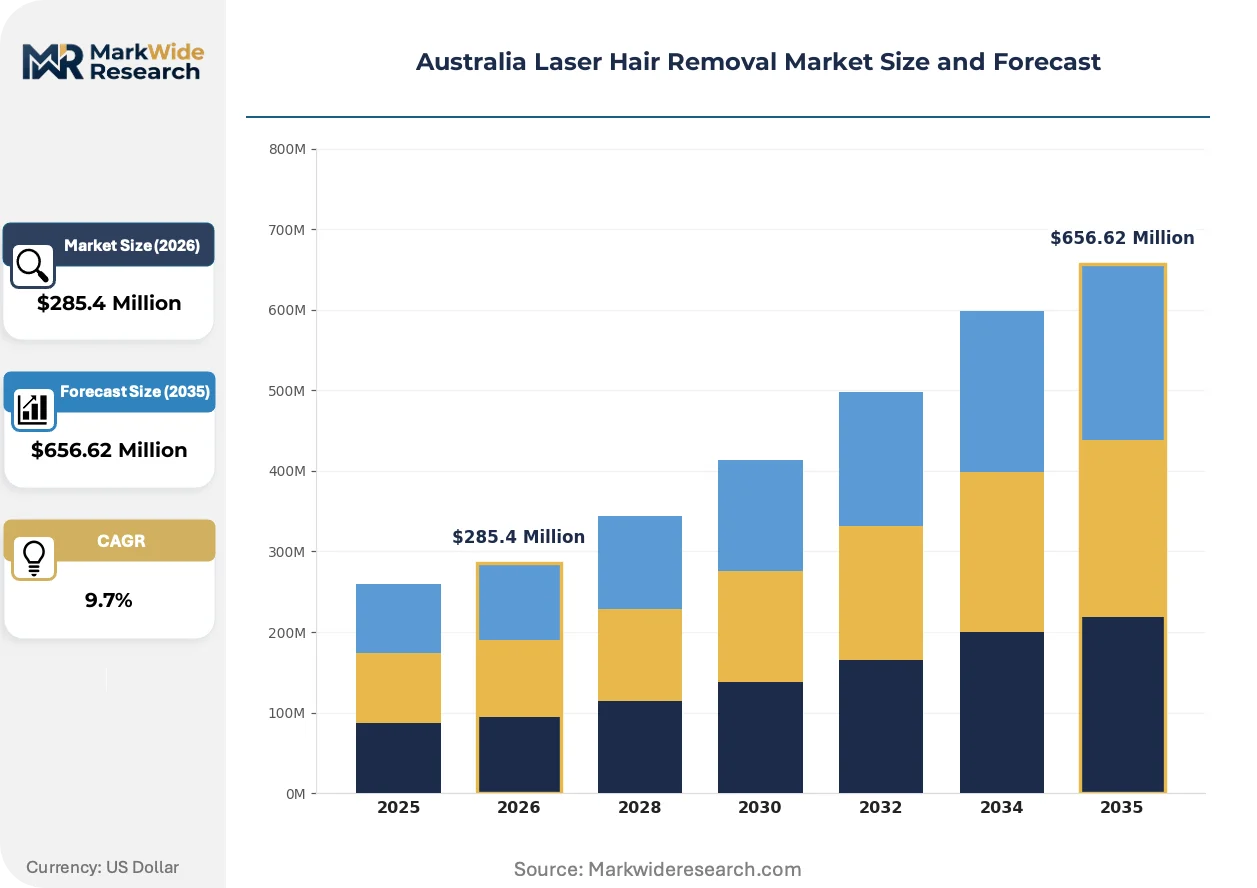
Market Dynamics
TGA clearance protocols are tightening safety benchmarks nationwide while diode and alexandrite laser systems consolidate professional installations. This dual pressure on compliance and equipment standards is compressing clinic margins and reshaping procurement priorities across New South Wales and Victoria.
Growth Catalysts
- AS/NZS 4173 laser safety standards:Federal safety benchmarks are filtering lower-tier imports from commercial distribution, elevating equipment quality thresholds and protecting incumbent clinic investments.
- Dermatology clinics in Sydney and Melbourne corridors:Disposable income thresholds in these metropolitan catchments support repeat treatment cycles and sustain premium service pricing.
- Selective photothermolysis wavelength optimization:Diode systems operating between 755 nm and 1064 nm now serve dual cosmetic and adjunctive skin rejuvenation applications, expanding addressable patient profiles.
Market Restraints
- State-based radiation health operator licensing:Queensland, Western Australia, and South Australia impose supplementary mandates that vary in stringency, creating compliance fragmentation and cross-border operational friction.
- Qualified dermal therapist scarcity:Training pipeline limitations are bifurcating the landscape into premium clinic chains with captive academies versus budget service corridors with higher staff turnover.
- Intense pulsed light substitution:Lower-cost IPL apparatus competes for Fitzpatrick skin types I through III, pressuring laser system utilization rates in price-sensitive segments.
Strategic Opportunities
- Medical spa bundled aesthetic menus:Service integration beyond standalone hair reduction is capturing share from single-purpose clinics through cross-selling efficiency.
- Nd:YAG configuration penetration:Darker skin type compatibility gaps present expansion white space currently underserved by dominant alexandrite and diode installations.
- Harmonization of federal-state cosmetic procedure reforms:Emerging regulatory alignment could reduce compliance burden variance and lower multi-jurisdiction capital requirements for national chains.
Industry Challenges
- TGA device registration timeline compression:Therapeutic Goods Administration oversight of intense pulsed light and laser apparatus extends procurement cycles and delays revenue recognition for new equipment deployments.
- Vertical training academy control:Clinics lacking proprietary credentialing pathways face margin pressure from competitors with in-house therapist pipelines and protocol standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Laser Hair Removal Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $656.62 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alexandrite Laser, Diode Laser, Nd:YAG Laser, IPL End User: Salons, Dermatology Clinics, Medical Spas, Beauty Centers Technology: Ruby Laser, Broadband Light, Pulsed Laser, Fractional Laser Application: Hair Removal, Skin Rejuvenation, Pigmentation Correction, Tattoo Removal |
| Companies Covered | Results Laser Clinic, Advanced Clinics Australia, Silk Laser Clinics, Richmond Skin and Laser Clinic, Victorian Laser and Skin, Australian Laser & Skin Clinics, Australian Skin Clinic, Clear Skincare Clinics, Laser Clinics Australia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Laser Hair Removal Market Strategic Shifts & Innovations
Technology convergence and regulatory harmonization pressures are actively reshaping equipment procurement and service delivery models. Clinics must now balance wavelength versatility against compliance automation to sustain competitive positioning.
Multi-wavelength platform systems are decomposing the traditional single-modality installation model. Dermatology clinics and medical spas are adopting these configurable units to reduce capital redundancy across patient demographics. This consolidation is decomplicating equipment footprints while compressing per-treatment cost structures for mid-tier operators.
TGA device registration requirements are tightening performance thresholds for intense pulsed light and laser apparatus entering Australian distribution. The industrial consequence is accelerated obsolescence of legacy imports that fail updated electromagnetic compatibility and clinical efficacy documentation. Professional-grade segments are responding by prioritizing vendors with established TGA clearance histories and domestic service infrastructure.
Subscription-based treatment packaging is displacing single-session purchasing across metropolitan Melbourne and Sydney corridors. Younger demographic cohorts are driving this shift toward predictable budgeting and relationship-based clinic loyalty. Medical spas with bundled aesthetic service menus are capturing this behavioral pivot more effectively than standalone hair reduction specialists.
Australia Laser Hair Removal Market Segmentation
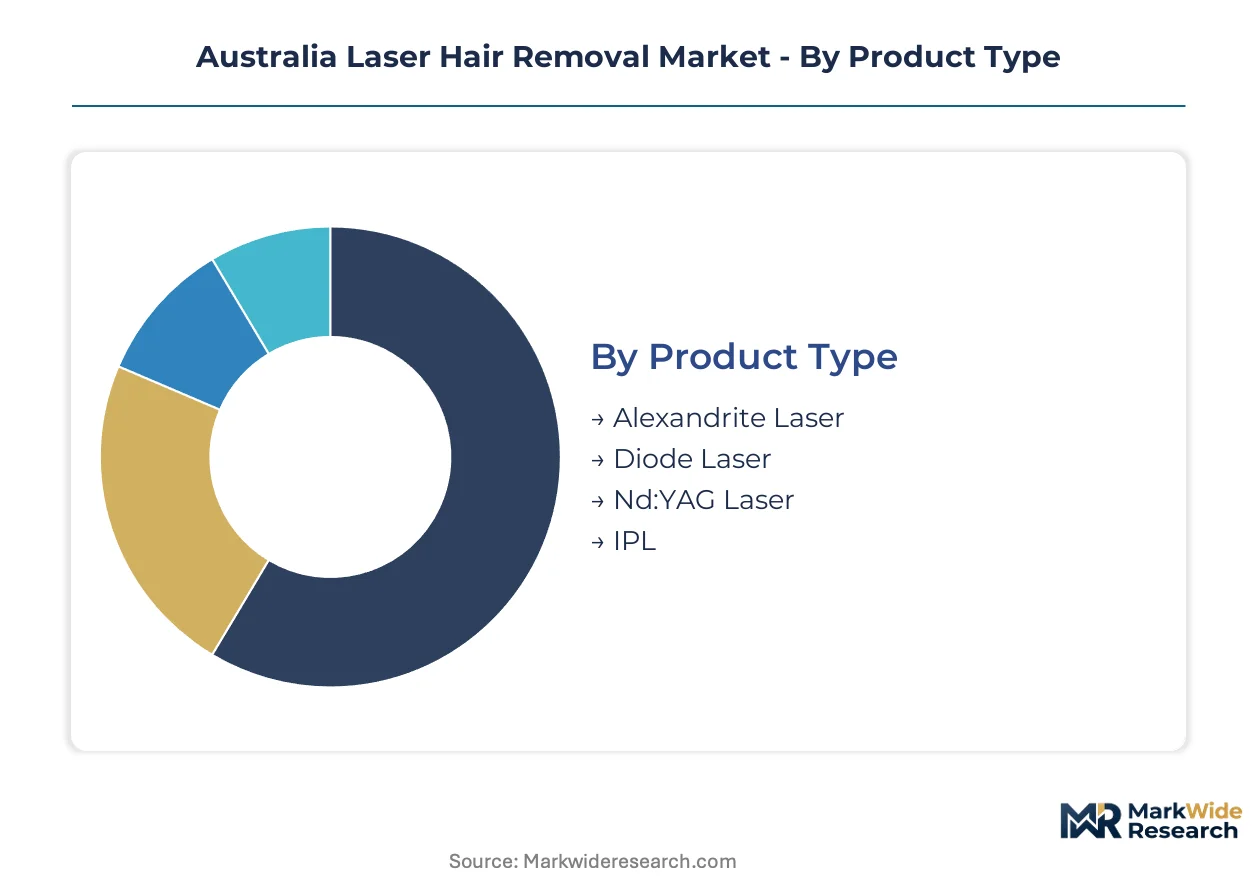
Laser hair removal equipment procurement in Australia follows distinct regulatory pathways that segment buyers by compliance capability. TGA clearance requirements and AS/NZS 4173 safety standards filter market participants across product categories and end-user channels.
Product Type:
TGA device registration protocols differentiate laser platforms by electromagnetic compatibility documentation and clinical efficacy thresholds, creating procurement friction that favors established vendors with domestic service infrastructure.
- Diode Laser:Operating wavelengths between 800 nm and 1000 nm deliver selective photothermolysis across Fitzpatrick skin types I through IV. Dermatology clinics in Sydney and Melbourne corridors deploy these systems for dual cosmetic and adjunctive skin rejuvenation applications, supported by disposable income thresholds that sustain premium service pricing.
- Alexandrite Laser:The 755 nm wavelength offers rapid treatment cycles for lighter skin types with high melanin absorption coefficients. Demand concentrates in premium clinic chains with captive training academies, where protocol standardization maximizes treatment consistency and patient retention.
- Nd:YAG Laser:Longer 1064 nm penetration enables safer application on darker skin types previously underserved by dominant installations.
- IPL:Lower-cost intense pulsed light apparatus competes for price-sensitive segments across Fitzpatrick types I through III.
Diode laser systems handle the majority of throughput; Nd:YAG configurations are gaining share fastest among professional installations.
End User:
Margin capture varies sharply across service delivery channels, with vertical integration into training pipelines determining competitive durability.
- Dermatology Clinics:Physician-supervised facilities command premium pricing through medical credibility and complex case handling. New South Wales and Victoria regulations require radiation health operator licensing that elevates barrier to entry.
- Medical Spas:Bundled aesthetic service menus capture younger demographics through subscription-based treatment packaging in metropolitan corridors. Cross-selling efficiency displaces standalone hair reduction specialists.
- Salons:Budget service corridors face qualified dermal therapist scarcity and higher staff turnover.
- Beauty Centers:Intermediate positioning requires equipment versatility without full medical-grade compliance burdens.
Dermatology clinics capture the highest margin pool; medical spas are climbing the fastest on volume share.
Technology:
Platform convergence is decomplicating equipment footprints as multi-wavelength systems reduce capital redundancy.
- Pulsed Laser:Q-switched and long-pulse modalities dominate professional hair reduction through precise thermal damage control.
- Broadband Light:Wavelength filtering enables customized treatment parameters across diverse patient profiles.
- Fractional Laser:Microthermal zone technology extends applications into skin resurfacing and collagen remodeling.
- Ruby Laser:The 694 nm wavelength retains niche deployment for fine hair and specific pigmentation targets.
Pulsed laser configurations anchor installed base; broadband light platforms show steepest expansion trajectory in new procurements.
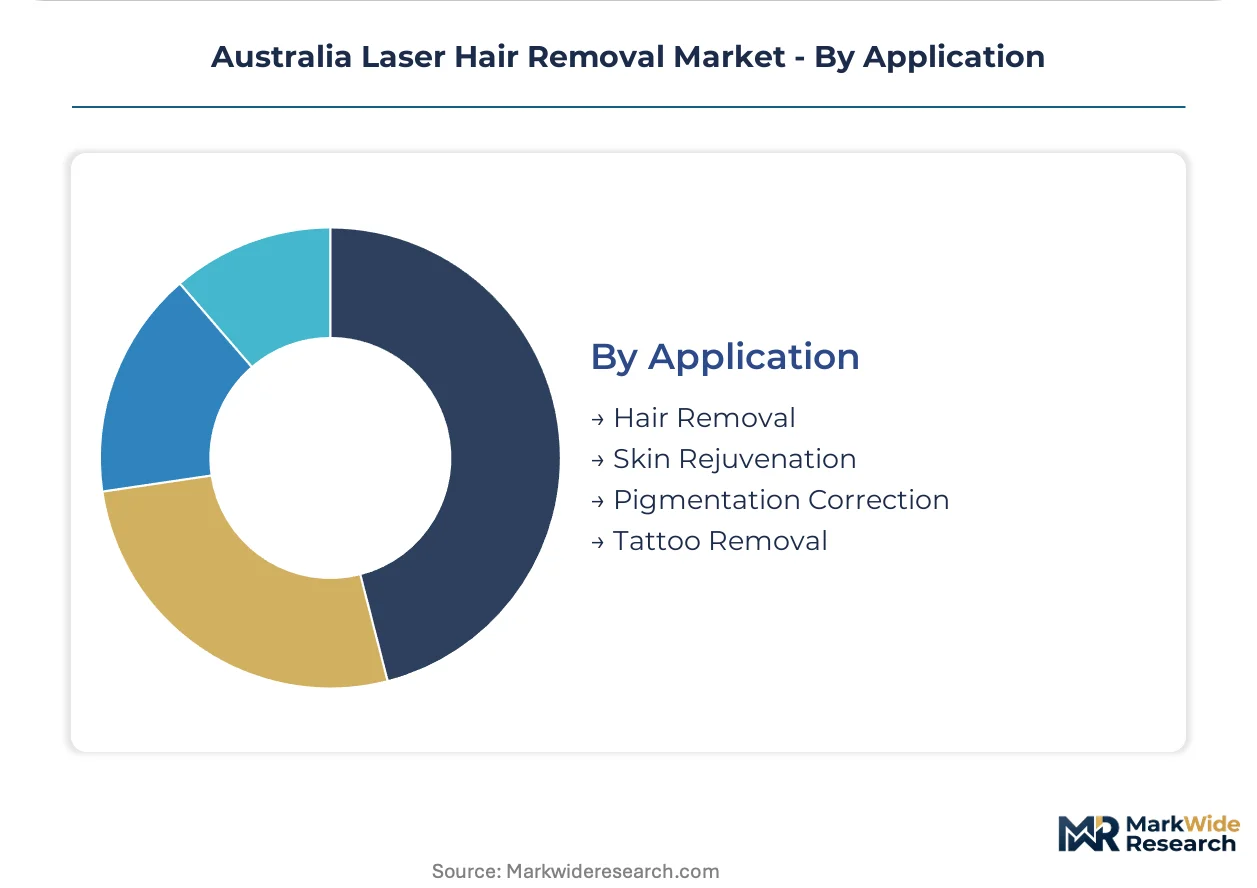
Application:
Service menu breadth determines customer lifetime value capture beyond initial treatment cycles.
- Hair Removal:Core demand driver with repeat treatment cycles generating predictable revenue streams across Fitzpatrick skin types I through VI.
- Skin Rejuvenation:Collagen stimulation and texture improvement applications expand addressable patient profiles.
- Pigmentation Correction:Solar lentigines and melasma treatments leverage existing laser infrastructure.
- Tattoo Removal:Q-switched applications repurpose installed base for adjacent aesthetic procedures.
Hair removal commands dominant procedure volume; skin rejuvenation represents the fastest-growing service line for margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales and Victoria deploy laser hair removal systems for dual cosmetic and skin rejuvenation applications, while Queensland and Western Australia concentrate demand in medical spa channels with bundled aesthetic menus. This consumption-mix differential separates premium dermatology clinic corridors from budget service territories.
New South Wales
Sydney metropolitan catchments sustain repeat treatment cycles through disposable income thresholds that support premium service pricing. TGA device registration requirements filter lower-tier imports from commercial distribution, elevating equipment quality benchmarks. The Sydney CBD and North Shore corridor hosts the densest concentration of physician-supervised dermatology clinics.
Victoria
Melbourne's inner suburbs drive subscription-based treatment packaging adoption among younger demographic cohorts seeking predictable budgeting. AS/NZS 4173 laser safety standards shape clinic accreditation pathways and operator certification requirements. The Melbourne metropolitan area anchors national volume leadership for professional-grade installations.
Queensland
Brisbane and Gold Coast corridors exhibit expanding medical spa penetration with cross-selling efficiency displacing standalone hair reduction specialists. State-based radiation health regulators impose supplementary operator licensing mandates beyond federal requirements. South East Queensland clusters concentrate budget service corridor expansion.
Western Australia
Perth metropolitan demand concentrates in beauty centers and intermediate positioning facilities requiring equipment versatility without full medical-grade compliance burdens. The state's radiation health licensing varies in stringency compared to eastern counterparts. Perth's suburban corridors face qualified dermal therapist scarcity pressures.
South Australia
Adelaide catchments show concentrated Nd:YAG laser adoption for darker skin type compatibility previously underserved by dominant installations. State-level cosmetic procedure reforms are emerging alongside federal device standards. The Adelaide metropolitan area supports niche premium clinic positioning.
Australia Laser Hair Removal Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with national footprint scale separating volume leaders from regional concentrators. Clinic chains with captive training academies command margin premiums through protocol standardization and therapist pipeline control. Three archetypes dominate: vertically integrated national chains, metropolitan corridor specialists, and budget service aggregators. Competitive moves concentrate on geographic densification in Sydney and Melbourne corridors and backward integration into training infrastructure.
Among national-scale integrators, Laser Clinics Australia occupies a position exemplifying volume leadership through metropolitan catchment density, while Clear Skincare Clinics represents the academy-controlled archetype with proprietary credentialing pathways. Results Laser Clinic anchors the metropolitan specialist tier through concentrated Sydney and Melbourne presence. These three patterns illustrate how scale, training control, and geographic focus differentiate competitive durability.
| Leading Market Players |
|---|
| Results Laser Clinic |
| Advanced Clinics Australia |
| Silk Laser Clinics |
| Richmond Skin and Laser Clinic |
| Victorian Laser and Skin |
| Australian Laser & Skin Clinics |
| Australian Skin Clinic |
| Clear Skincare Clinics |
| Laser Clinics Australia |
| Others |
Cost & Logistics Intelligence
Long-term equipment financing arrangements with TGA-registered vendors lock in supply access and price visibility for Australian clinic operators navigating AS/NZS 4173 compliance mandates. These structured procurement contracts insulate premium clinic chains from spot-market volatility in laser device availability while compressing capital deployment timelines for mid-tier entrants.
Pricing Analysis
Subscription-based treatment packaging dominates patient-facing revenue models across Sydney and Melbourne metropolitan corridors. Pricing stratifies across premium physician-supervised dermatology clinics, standard medical spa bundled menus, and economy salon corridors based on TGA device registration tier and operator certification level. Cost compression in budget service tiers intensifies as IPL substitution erodes laser system utilization rates. Medical spas exhibit lowest price sensitivity due to cross-selling efficiency; standalone hair reduction specialists face acute margin pressure from patient churn.
Supply Chain Analysis
Just-in-time device procurement preferences prevail among Australian clinic operators seeking to minimize obsolescence risk from tightening TGA electromagnetic compatibility standards. Laser platform supply concentrates in Germany, the United States, and Israel, with diode and alexandrite system assemblies drawing from precision optical component manufacturers in Japan and South Korea. Single-source vulnerability in TGA clearance documentation creates procurement bottlenecks for new market entrants. Distribution runs through authorized domestic service infrastructure rather than direct import channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory harmonization pressure between federal TGA standards and emerging state-level cosmetic procedure reforms constitutes a high-growth disruption vector for equipment vendors and clinic operators alike. Technology convergence toward multi-wavelength platforms accelerates competitive displacement of single-modality installations.
For Market Incumbents: Secure proprietary training academy pipelines to insulate margin position from qualified dermal therapist scarcity. Lock in TGA-registered vendor relationships with domestic service infrastructure to preempt compliance-driven procurement friction. Capacity addition in Adelaide and Perth corridors captures Nd:YAG penetration opportunities for darker skin type compatibility.
For New Entrants and Emerging Players: Differentiate on wavelength versatility through multi-platform configurations that reduce capital redundancy across patient demographics. Target South Australia and Western Australia sub-regions where dermatology clinic density remains below Sydney-Melbourne saturation levels. Deploy subscription-based treatment packaging to capture younger demographic cohorts seeking predictable budgeting.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated clinic chains with captive credentialing pathways and established TGA clearance histories. Long-term viability hinges on regulatory compliance automation capabilities and cross-selling efficiency in bundled aesthetic menus. Watch for harmonization of federal-state cosmetic procedure reforms as inflection signal for multi-jurisdiction capital requirement reductions.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Wavelength Platform Adoption | Reduces capital redundancy across Fitzpatrick skin type diversity in TGA-regulated installations. |
| Proprietary Training Academy Development | Captive dermal therapist pipelines insulate margin position from labor scarcity pressures. |
| Subscription-Based Treatment Packaging | Predictable revenue streams align with younger demographic budgeting preferences in metropolitan corridors. |
| TGA Registration Pathway Investment | Established clearance histories accelerate procurement cycles and filter lower-tier import competition. |
| Medical Spa Channel Expansion | Cross-selling efficiency in bundled aesthetic menus displaces standalone hair reduction specialists. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with clinic operators, biomedical equipment procurement managers, and TGA regulatory affairs specialists; and secondary validation through Therapeutic Goods Administration device registration databases, AS/NZS 4173 safety standard documentation, and state-based radiation health regulator licensing records. Bottom-up equipment installation counts across New South Wales, Victoria, Queensland, Western Australia, and South Australia were triangulated against top-down market value estimates.
The forecast framework spans the projection horizon without binding to specific calendar endpoints. Segmentation dimensions modeled include product type, end-user channel, technology configuration, and application breadth across the Australian state-level regulatory cluster. CAGRs were derived from equipment procurement velocity and treatment cycle repeat rates. Industry-specific inputs encompass TGA clearance timeline compression effects and qualified dermal therapist training pipeline constraints.
The analysis sits within stated boundaries; outcomes outside stable TGA regulatory trajectories and sustained metropolitan disposable income thresholds would require recalibration. Forecasts reflect assumptions regarding harmonization pressure between federal device standards and state-level cosmetic procedure reforms. Revision becomes warranted when IPL substitution rates or Nd:YAG penetration velocities cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Lip Filler Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Europe Medical Aesthetic Devices Market
Medical Aesthetics
Korea Medical Aesthetics Market
Medical Aesthetics
Contouring Implants Market
Medical Aesthetics
Germany Hair Transplant Market
Medical Aesthetics
India Hair Transplant Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Lip Augmentation Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
Non-Hyaluronic Acid Dermal Filler Market