
 Non-Invasive Brain Stimulation System Market | 2026-2036
Non-Invasive Brain Stimulation System Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Brain Stimulation System Market Analytics
ISO 13485 certification for medical device quality management is unwinding competitive dynamics across the non-invasive brain stimulation landscape. BrainsWay leverages its deep transcranial magnetic stimulation specialization to anchor clinical adoption in psychiatric care settings. MagVenture sustains manufacturing scale across European and North American distribution channels, while Neurocare Group AG differentiates through integrated therapy center networks that combine device placement with clinician training protocols.
A non-invasive brain stimulation system delivers electromagnetic or electrical energy across the cranium to modulate neural activity without surgical implantation, typically operating at field strengths between 1.5 to 2 Tesla for TMS coils or 1-2 milliamperes for tDCS applications, with primary purpose centered on treating medication-resistant depression and chronic neuropathic pain. Transcranial magnetic stimulation occupies the largest revenue pool given its established reimbursement codes and extensive clinical trial backing, while transcranial direct current stimulation represents the fastest-expanding segment due to lower device costs and emerging home-use protocols. Depression therapy applications command premium pricing through hospital-based delivery models, whereas home care settings are reshaping access economics for maintenance treatment regimens.
FDA 510(k) clearance pathways and the EU Medical Device Regulation shape product development timelines and clinical evidence thresholds for market entry, with MDR's enhanced post-market surveillance requirements extending compliance burdens for manufacturers. The country's national pharmaceutical regulator in Japan applies PMDA consultation procedures that lengthen approval cycles but strengthen payer acceptance for novel neuromodulation indications. Stakeholders must monitor evolving FDA guidance on adaptive trial designs for psychiatric device indications, as regulatory agility will determine which manufacturers capture expanding anxiety treatment and cognitive enhancement segments before reimbursement frameworks crystallize.
Market Dynamics
Reimbursement pathway fragmentation is forcing device manufacturers to architect dual-track commercialization strategies that separate hospital-based acute treatment from decentralized maintenance protocols.
Growth Catalysts
- FDA 510(k) pathway maturation:Psychiatric device indications now carry clearer predicate device benchmarks, compressing pre-submission consultation timelines for transcranial magnetic stimulation systems.
- Hospital neuromodulation center expansion:Academic medical centers in the United States, Germany, and Japan are establishing dedicated outpatient clinics that bundle device placement with clinician certification programs.
- Home-use tDCS protocol emergence:Lower-intensity transcranial direct current stimulation applications are migrating beyond clinical supervision into patient-managed maintenance regimens.
Market Restraints
- MDR post-market surveillance burden:EU Medical Device Regulation mandates for enhanced clinical follow-up data are extending compliance costs and recertification cycles for transcranial magnetic stimulation manufacturers.
- Superconducting coil supply concentration:Cryogenic cooling system components for high-field TMS devices depend on a limited supplier base concentrated in German and Japanese precision engineering clusters.
- Placebo response variability:Psychiatric indication trials face elevated noise-to-signal ratios in depression endpoints, complicating pivotal study design and statistical powering.
Strategic Opportunities
- PMDA consultation procedure leverage:Japan's structured pre-submission dialogue pathways enable manufacturers to anchor novel anxiety disorder claims with prospective payer engagement.
- Integrated therapy center networks:Device placement combined with standardized clinician training protocols creates recurring revenue streams through per-treatment service fees rather than capital equipment sales alone.
- Adaptive trial design adoption:FDA guidance on Bayesian and adaptive methodologies for psychiatric devices permits mid-study protocol modifications that reduce overall enrollment requirements.
Industry Challenges
- Neurophysiologist training pipeline constraints:Specialized expertise in motor threshold determination and coil positioning protocols remains concentrated in academic medical centers, limiting scalable deployment.
- ISO 13485 certification complexity:Medical device quality management system audits for software-enabled stimulation systems require documentation of algorithm version control and electromagnetic compatibility testing.
- Legacy electronic health record integration:Treatment session data capture and outcome tracking systems must interface with hospital IT architectures that lack standardized neuromodulation workflow modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Brain Stimulation System Market |
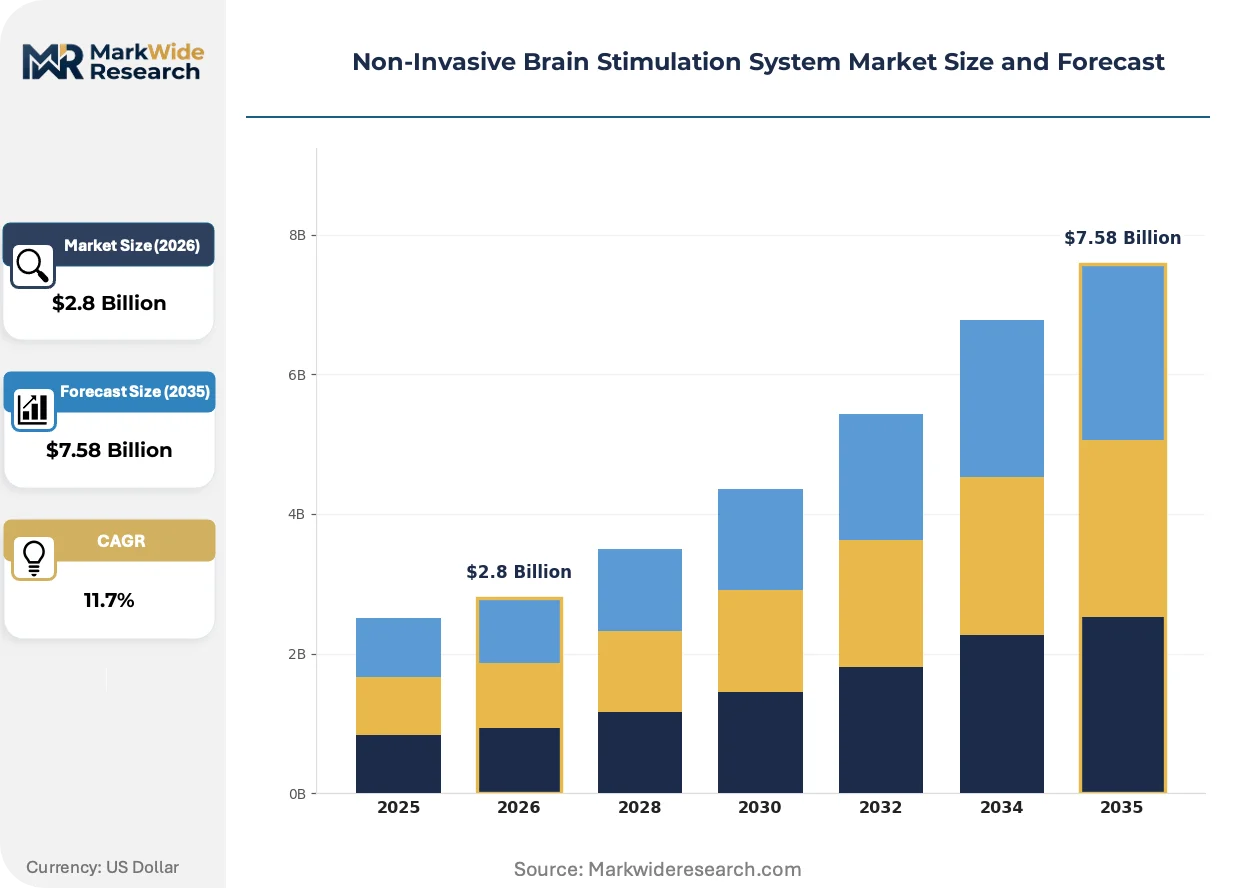
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transcranial Magnetic Stimulation, Transcranial Direct Current Stimulation, Electromagnetic Field Stimulation, Neuromodulation Devices Application: Depression Therapy, Anxiety Treatment, Pain Management, Cognitive Enhancement End User: Hospitals, Rehabilitation Centers, Research Institutions, Home Care Settings Technology: Electroencephalography, Functional MRI, Brain-Computer Interfaces, Neurofeedback Systems |
| Companies Covered | BrainsWay, MagVenture, Magstim, NeoSync, Inc., Brainbox Ltd., eNeura Inc., Flow Neuroscience, Magnus Medical, Inc., Neurocare Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Brain Stimulation System Market Evolving Landscape
Computational personalization of stimulation parameters is displacing standardized dosing protocols, while regulatory frameworks adapt to accommodate software-as-medical-device functionality in therapeutic platforms.
Deep transcranial magnetic stimulation coil architectures is bifurcating treatment delivery between superficial cortical targeting and limbic system engagement for obsessive-compulsive disorder applications. Psychiatric specialty clinics in the United States are adopting H-coil configurations at accelerated procurement cycles compared to conventional figure-eight designs. This hardware divergence is compressing the addressable patient population into severity-stratified treatment pathways that separate medication-resistant depression from comorbid anxiety presentations.
EU Medical Device Regulation's enhanced post-market clinical follow-up requirements are extending surveillance obligations for transcranial magnetic stimulation systems beyond the traditional two-year horizon. Manufacturers must now architect prospective registry infrastructure capable of capturing longitudinal safety signals across diverse neurological and psychiatric indications. The psychiatric device segment is responding by embedding remote monitoring capabilities that automate session adherence tracking and adverse event documentation.
After-sales service unbundling is fragmenting the traditional capital equipment procurement model into componentized arrangements separating hardware lease, maintenance, and per-use consumables. Hospital purchasing committees are negotiating three-year operational expenditure contracts that shift coil replacement and software upgrade responsibilities to device vendors. This restructuring is most visible in German university hospital networks where procurement offices prioritize total cost-of-ownership metrics over upfront capital expenditure minimization.
Non-Invasive Brain Stimulation System Market Segmentation
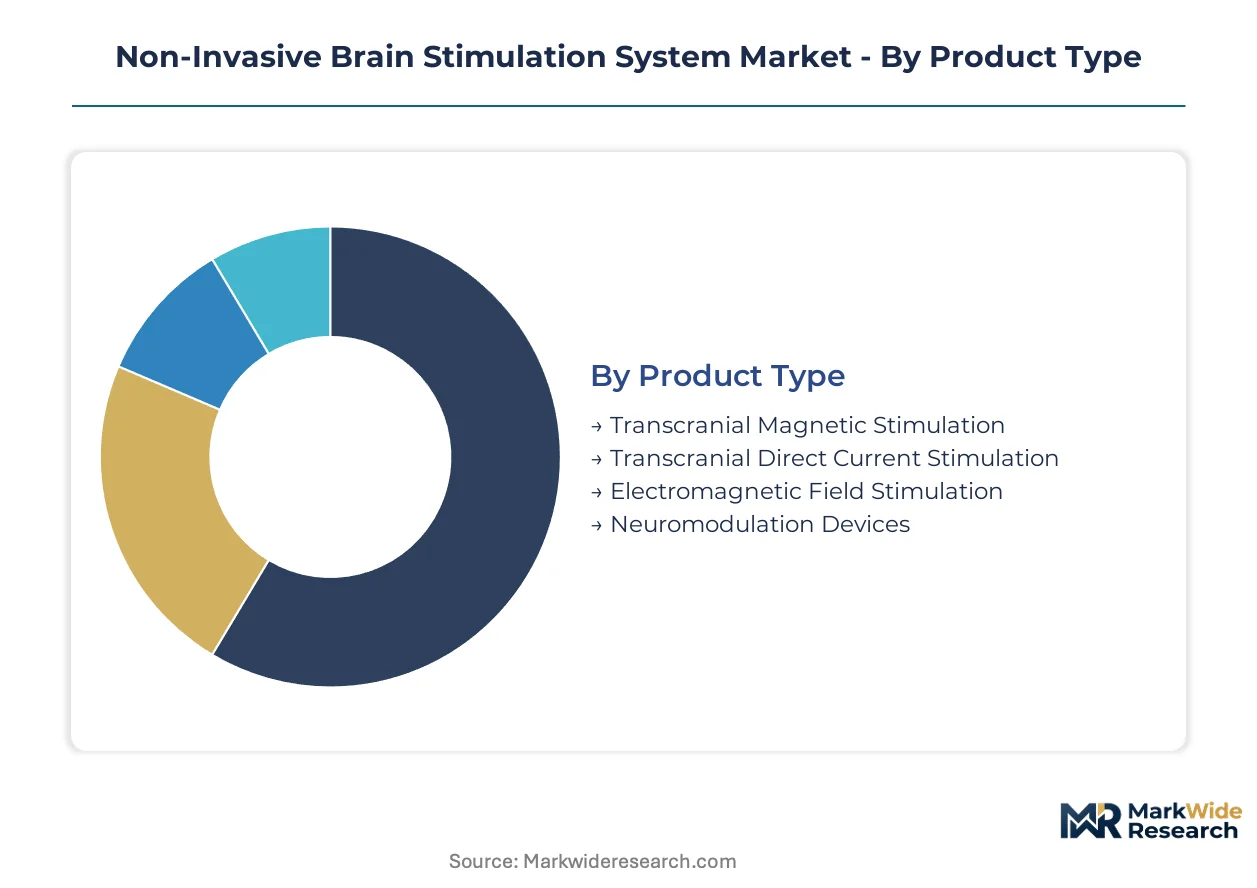
Segmentation in the non-invasive brain stimulation system market reveals divergent commercial pathways between capital-intensive hospital deployments and emerging decentralized care models. Technology choices and end-user settings determine reimbursement eligibility, regulatory burden, and equipment lifecycle economics.
Product Type:
Transcranial magnetic stimulation systems dominate domestic hospital procurement in the United States and Germany, while transcranial direct current stimulation devices increasingly serve export markets seeking lower-cost entry points.
- Transcranial Magnetic Stimulation:High-field electromagnetic coils operating at 1.5 to 2 Tesla generate focal cortical depolarization through rapid pulse delivery. Demand concentrates in academic medical centers across the United States and Japan where FDA 510(k) and PMDA pathways anchor insurance reimbursement for medication-resistant depression. Superconducting coil maintenance contracts and cryogenic cooling requirements sustain recurring vendor revenue streams.
- Transcranial Direct Current Stimulation:Low-intensity current delivery at 1-2 milliamperes through scalp electrodes modulates resting membrane potential without inducing action potentials. Home-use protocols in European rehabilitation networks and direct-to-consumer channels in North America are displacing clinic-bound delivery, though regulatory classification remains fragmented across CE marking jurisdictions and FDA enforcement discretion.
- Electromagnetic Field Stimulation:Pulsed electromagnetic field devices target peripheral-to-central nervous system signaling with lower spatial precision than TMS. Wellness and sports medicine applications in German physiotherapy practices drive niche adoption outside psychiatric reimbursement frameworks.
- Neuromodulation Devices:Hybrid platforms combining multiple stimulation modalities with integrated neuroimaging feedback. Research consortia in Japan and the Netherlands pilot closed-loop architectures for personalized dosing algorithms.
Transcranial magnetic stimulation holds the largest share; momentum sits with transcranial direct current stimulation.
Application:
Cost tier stratification separates premium-priced hospital depression protocols from emerging anxiety and cognitive applications where evidence requirements remain unsettled.
- Depression Therapy:Established indication with dedicated CPT reimbursement codes in the United States and NICE technology appraisal guidance in the United Kingdom. Hospital neuromodulation centers in Germany and Japan bundle acute treatment courses with maintenance scheduling protocols.
- Anxiety Treatment:Generalized anxiety and post-traumatic stress disorder applications are gaining regulatory attention through FDA breakthrough device designations and PMDA priority consultation pathways. Academic medical centers in Boston and Tokyo anchor pivotal trial enrollment.
- Pain Management:Chronic neuropathic and fibromyalgia applications leverage existing TMS infrastructure with modified coil positioning. Rehabilitation networks in France and Canada pilot bundled payment models separating diagnostic workup from stimulation delivery.
- Cognitive Enhancement:Healthy population applications for attention and memory modulation operate outside medical device regulatory frameworks in most jurisdictions. Direct-to-consumer channels face advertising scrutiny from the FTC and comparable consumer protection bodies.
Depression therapy commands premium pricing; anxiety treatment is climbing the fastest toward formal reimbursement.
End User:
Customer type determines capital deployment models, with hospitals favoring equipment purchase and home care settings demanding lease-to-own or subscription architectures.
- Hospitals:Academic medical centers and community hospital systems in the United States, Germany, and Japan constitute the core installed base. Neuromodulation service line profitability depends on psychiatrist referral networks and dedicated technician staffing.
- Rehabilitation Centers:Post-stroke motor recovery and chronic pain protocols in European neurorehabilitation networks integrate stimulation with physical therapy workflows. Outpatient reimbursement codes vary substantially across German Länder and French regional health authorities.
- Research Institutions:National brain initiatives in the United States, European Union, and Japan fund mechanistic studies and biomarker discovery. Equipment procurement favors flexible coil configurations and open programming interfaces.
- Home Care Settings:tDCS devices for maintenance depression treatment and wellness applications are penetrating direct-to-consumer channels. Regulatory boundaries between medical device and general wellness product classification remain contested at FDA and in EU member state implementations of MDR.
Hospitals retain the dominant installed base; home care settings are gaining share fastest through tDCS protocol expansion.
Technology:
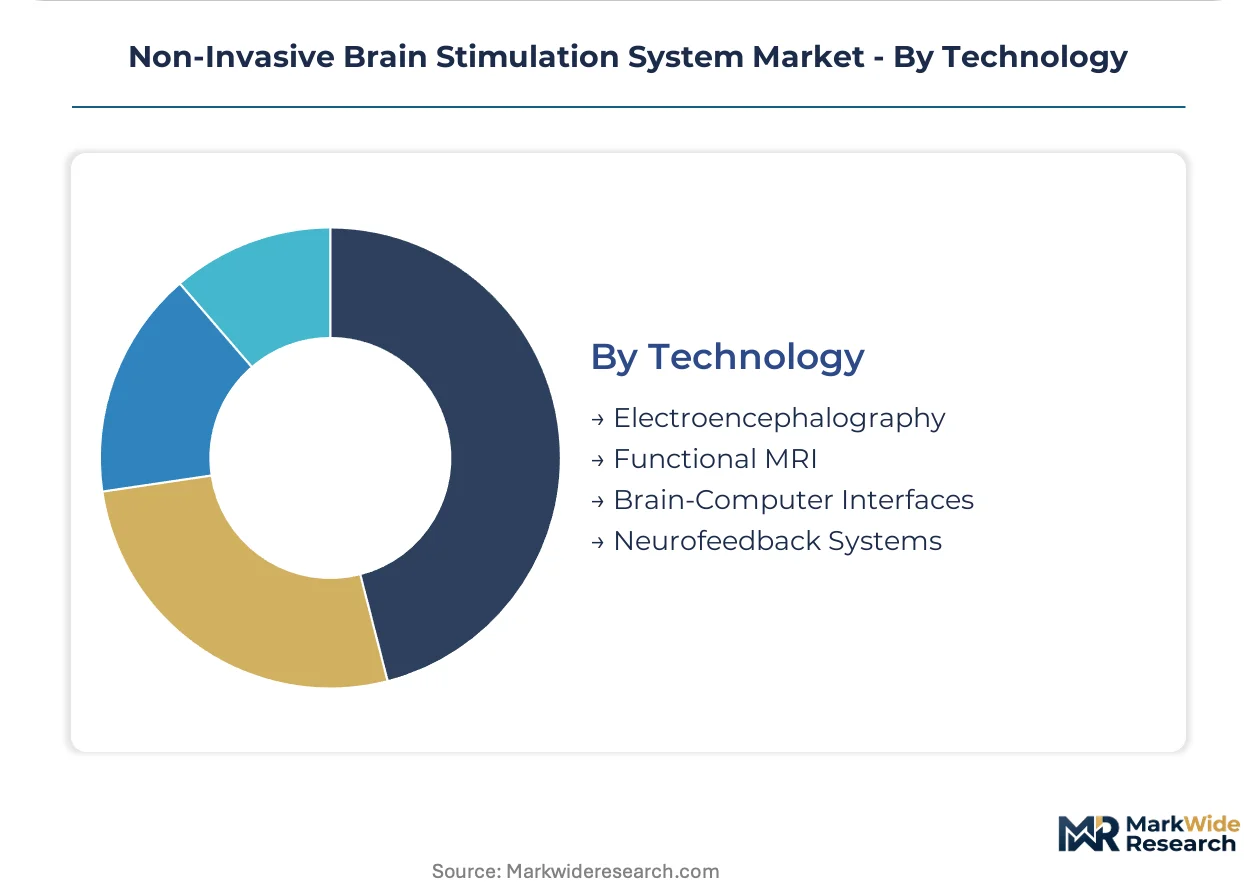
Integration maturity separates standalone stimulation systems from multimodal platforms combining real-time neuroimaging with adaptive parameter adjustment.
- Electroencephalography:Real-time cortical state monitoring enables closed-loop stimulation timing and response biomarker extraction. Research collaborations between device manufacturers and university neuroscience departments in the Netherlands and California pilot seizure prediction and sleep architecture applications.
- Functional MRI:Pre-treatment targeting and post-treatment plasticity assessment anchor precision dosing protocols. High capital requirements restrict deployment to major academic medical centers in the United States, Germany, and Japan with dedicated research MRI suites.
- Brain-Computer Interfaces:Bidirectional neural signal translation enables intention-driven stimulation parameter modulation. DARPA and EU Horizon funding programs support motor restoration applications in spinal cord injury populations.
- Neurofeedback Systems:Real-time physiological signal display for patient self-regulation training. ADHD and anxiety applications in German psychotherapeutic practices operate under medical device regulation for therapeutic claims.
Electroencephalography integration holds the largest current deployment; brain-computer interfaces show the steepest expansion trajectory through defense and rehabilitation research funding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement code expansion in the United States anchors hospital neuromodulation investment, while PMDA consultation pathways in Japan and MDR compliance frameworks in Germany reshape competitive positioning across major demand centers.
United States
Academic medical centers in Boston and the San Francisco Bay Area anchor depression therapy adoption through dedicated outpatient neuromodulation clinics. FDA 510(k) pathway maturation for psychiatric device indications compresses pre-submission timelines and clarifies predicate device benchmarks. Hospital purchasing committees in the Midwest and Southeast negotiate three-year operational expenditure contracts prioritizing total cost-of-ownership metrics.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia drive procurement of high-field TMS systems with bundled maintenance and coil replacement agreements. EU Medical Device Regulation post-market surveillance requirements extend clinical follow-up obligations beyond traditional two-year horizons for manufacturers serving German markets. Precision engineering clusters around Stuttgart supply cryogenic cooling components for superconducting coil systems.
Japan
PMDA structured pre-submission dialogues enable manufacturers to anchor novel anxiety disorder claims with prospective payer engagement before pivotal trial initiation. National brain initiative funding through Kanto region research consortia supports mechanistic studies and biomarker discovery for closed-loop stimulation architectures. Tokyo and Osaka academic centers concentrate specialized neurophysiologist expertise in motor threshold determination protocols.
United Kingdom
NICE technology appraisal guidance for transcranial magnetic stimulation in medication-resistant depression stabilizes hospital reimbursement eligibility across NHS trusts. Research institutions in London and Cambridge pilot hybrid platforms combining multiple stimulation modalities with integrated neuroimaging feedback. Procurement offices prioritize equipment with open programming interfaces to support flexible coil configuration research.
Canada
Rehabilitation networks in Ontario and Quebec pilot bundled payment models separating diagnostic workup from stimulation delivery for chronic neuropathic pain applications. Health Canada regulatory pathways for home-use tDCS devices remain under enforcement discretion, creating uncertainty for direct-to-consumer channel development. Montreal and Vancouver academic centers anchor enrollment for anxiety and PTSD indication trials.
Non-Invasive Brain Stimulation System Market Competitive Landscape
Player mix skews toward specialized neuromodulation device manufacturers with deep psychiatric care expertise, creating a tiered structure where clinical evidence generation capabilities separate premium positioning from commodity hardware supply. Strategic archetypes include integrated therapy center operators combining device placement with clinician certification, precision coil engineering specialists serving cryogenic system requirements, and software-enabled platform developers pursuing adaptive dosing algorithms. Competitive moves concentrate on M&A targeting complementary stimulation modalities and strategic partnerships with academic medical centers for pivotal trial enrollment.
Within the integrated therapy center tier, Neurocare Group AG and BrainsWay exemplify service-based differentiation through bundled clinician training protocols and per-treatment revenue models. MagVenture occupies a position among European precision engineering specialists sustaining manufacturing scale across distributed North American and European channels. These three entities collectively represent the dominant competitive archetypes: network-integrated service delivery, manufacturing scale with aftermarket service unbundling, and clinical specialization anchoring psychiatric indication adoption.
| Leading Market Players |
|---|
| BrainsWay |
| MagVenture |
| Magstim |
| NeoSync, Inc. |
| Brainbox Ltd. |
| eNeura Inc. |
| Flow Neuroscience |
| Magnus Medical, Inc. |
| Neurocare Group AG |
| Others |
Value Network & Pricing Analysis
Six-to-nine month lead times for superconducting coil assemblies concentrate pricing power with German and Japanese precision engineering clusters, compressing margins for device vendors unable to secure long-term offtake agreements. This inventory constraint binds hospital procurement committees to bundled service contracts that embed coil replacement and cryogenic maintenance into operational expenditure frameworks.
Pricing Analysis
Certification level creates the primary spread between premium FDA 510(k)-cleared systems and CE-marked alternatives awaiting MDR recertification. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center deployments from community hospital installations and research-only configurations. Cost compression in the standard tier is intensifying because PMDA consultation requirements in Japan extend development timelines without commensurate pricing uplift. Rehabilitation centers exhibit the highest price sensitivity due to fragmented outpatient reimbursement codes, while university hospital networks prioritize total cost-of-ownership metrics over upfront capital minimization.
Supply Chain Analysis
Cryogenic cooling system sourcing from Stuttgart and Osaka engineering clusters anchors superconducting coil performance specifications for high-field TMS devices. Manufacturing draws from niobium-titanium superconductor feedstock concentrated in Japanese metalworking facilities and precision-machined coil housings from German automotive supplier networks. Single-source vulnerability in liquid helium logistics exposes vendors to regional distribution disruptions. Distribution runs through direct hospital sales teams in the United States and specialized medical device distributors serving European rehabilitation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through FDA 510(k) predicate accumulation and PMDA consultation precedent creates durable defensive moats for established neuromodulation device manufacturers. Switching costs for hospital neuromodulation centers escalate with embedded clinician training protocols and electronic health record integration investments.
For Market Incumbents: Consolidate coil manufacturing capabilities through captive supply arrangements with Stuttgart precision engineering clusters to secure superconducting component allocation. Deepen software-as-medical-device functionality to capture adaptive dosing algorithm revenue streams before reimbursement frameworks crystallize for anxiety and cognitive enhancement indications. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks offer the most penetrable regulatory pathway for novel obsessive-compulsive disorder and post-traumatic stress disorder claims. Target home-use tDCS maintenance protocols in European direct-to-consumer channels where MDR enforcement discretion creates temporary classification ambiguity. Lead with subscription-based per-treatment revenue models that bypass capital equipment procurement committee resistance. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because FDA and PMDA consultation precedents compound over decades into irreproducible predicate device libraries. Acquisition candidates should display integrated therapy center networks with recurring per-treatment revenue streams rather than pure hardware manufacturing scale. Monitor PMDA anxiety disorder reimbursement decisions as the signal indicating when maintenance treatment economics will shift from hospital-based to decentralized care models.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR recertification timelines determine competitive access to German university hospital procurement cycles. |
| Hospital System Partnership | Bundled clinician training protocols with academic medical centers in Boston and Tokyo anchor referral network capture. |
| Software Companion Development | Adaptive dosing algorithms embedded in stimulation platforms enable recurring SaaS revenue beyond hardware sales. |
| Reimbursement Strategy | CPT code expansion for anxiety indications in United States hospital systems unlocks addressable population scaling. |
| FDA Submission | Breakthrough device designation for PTSD applications compresses pre-submission consultation timelines against predicate benchmarks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital neuromodulation center directors, biomedical engineers, GPO contracts managers, and psychiatric service line administrators; and secondary validation against FDA 510(k) filings, PMDA consultation records, CMS Medicare reimbursement databases, and hospital procurement contract registries. Bottom-up equipment installation counts triangulated against top-down neuromodulation service line revenue estimates.
Across the analysis window, the forecasting framework modeled technology type, application indication, end-user setting, and regional regulatory cluster segmentation. CAGRs derived from equipment replacement cycles, reimbursement code expansion trajectories, and clinician training pipeline constraints. Forecast inputs incorporated PMDA consultation completion rates and MDR post-market surveillance compliance cost assumptions.
Underlying assumptions cover stable FDA predicate device accumulation rates and sustained German precision engineering cluster output, with deviation risk concentrated in MDR recertification timeline extensions and liquid helium supply logistics disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market
Medical Devices
Membrane Oxygenators Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market
Medical Devices
Chile Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Asia-Pacific Refractive Surgery Devices Market
Medical Devices
Global Cranial Implants Market
Medical Devices
North America Pen Needles Market
Medical Devices
Implantable Drug Delivery Devices Market
Medical Devices
Global Prosthetics Market
Medical Devices
Home Dialysis Systems Market
Medical Devices
Global Liposuction Surgery Devices Market
Medical Devices
Supraglottic Device Market
Medical Devices
Bronchial Thermoplasty Catheter Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
Global Occlusion Devices Market
Medical Devices
South Africa Respiratory Devices Market