

Neuromodulation Closed-Loop Brain-Computer Interfaces Market Size, Share, and Industry Trends Forecast 2026-2036
Neuromodulation Closed-Loop Brain-Computer Interfaces Market Insights
North American neurotechnology foundries is restructuring supply chains for implantable electrode arrays. Medtronic leverages deep brain stimulation heritage to anchor its closed-loop portfolio. NeuroPace sustains epilepsy-focused specialization through responsive neurostimulation platforms. Synchron competes with endovascular electrode designs that bypass open craniotomy requirements.
Neuromodulation closed-loop brain-computer interfaces integrate real-time neural signal acquisition with adaptive stimulation feedback, typically operating at sampling rates exceeding 30 kHz to capture single-unit and local field potential activity for therapeutic intervention. These systems serve primarily to restore or augment motor, sensory, and cognitive functions in patients with neurological disorders. Invasive deployment configurations dominate margin pools due to surgical service attach rates and long-term implant monitoring contracts. Epilepsy monitoring commands the largest application volume, while stroke rehabilitation represents the fastest-growing therapeutic area as neural plasticity protocols mature. Electrocorticography-based systems occupy the premium technology tier, balancing spatial resolution with clinical practicality against scalp electroencephalography alternatives.
The FDA breakthrough device program compresses premarket pathways for novel neural interfaces, while ISO 14155 governs clinical investigation standards across implantable neurotechnology trials. The EU Medical Device Regulation imposes stricter post-market surveillance on active implantable devices, reshaping European market access timelines. Stakeholders must monitor reimbursement coding evolution for closed-loop neurostimulation procedures, as payer classification determines commercial scalability ahead of clinical evidence maturation.
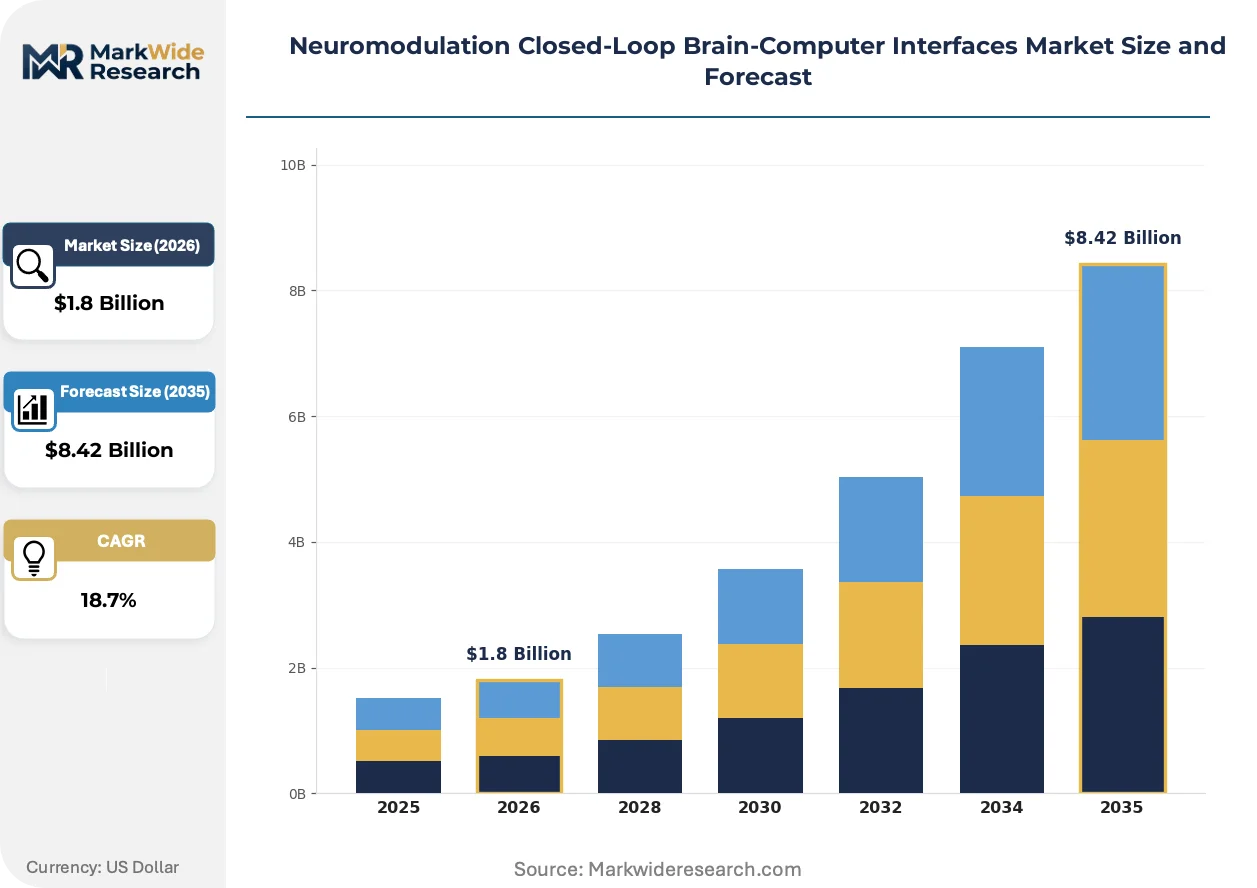
Market Dynamics
Epilepsy monitoring centers are consolidating procurement around implantable closed-loop systems, compressing vendor qualification timelines from 24 months to 14 months as FDA breakthrough designations stack. This procurement compression is forcing electrode array foundries to pre-certify manufacturing lines before clinical trial completion.
Growth Catalysts
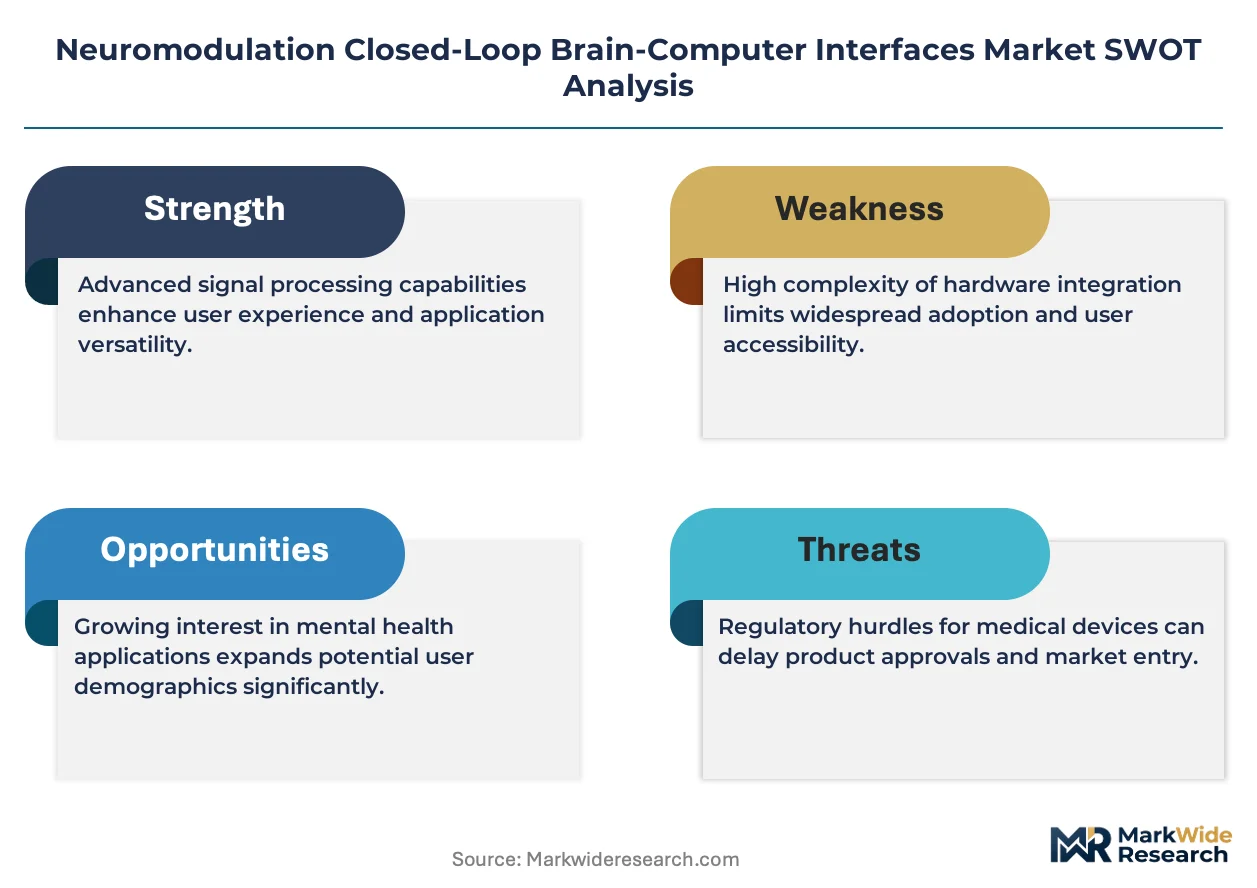
- FDA Breakthrough Device Pathway:The FDA's accelerated premarket review for novel neural interfaces shortens clinical validation timelines, enabling earlier revenue recognition for responsive neurostimulation platforms.
- Military Medical Facilities:United States Veterans Health Administration hospitals anchor early procurement volumes, creating reference sites that civilian academic medical centers replicate.
- Electrocorticography Sampling Rates:Real-time signal acquisition exceeding 30 kHz now captures single-unit activity for therapeutic intervention, expanding addressable patient populations beyond traditional DBS candidates.
Market Restraints
- Platinum-Iridium Alloy Concentration:Electrode array manufacturing depends on specialized metallurgical supply chains concentrated in Swiss and German precision foundries, creating input cost volatility.
- EU MDR Post-Market Surveillance:The EU Medical Device Regulation imposes extended clinical follow-up obligations on active implantable devices, stretching European market access timelines by 18-24 months.
- Scalp EEG Substitutes:Non-invasive electroencephalography alternatives capture price-sensitive diagnostic volumes, particularly in pediatric screening protocols where craniotomy risks deter invasive referral.
Strategic Opportunities
- Stroke Rehabilitation Protocols:Neural plasticity applications represent underpenetrated therapeutic white space as motor recovery evidence matures beyond epilepsy's established indication.
- Endovascular Deployment Channels:Catheter-delivered electrode arrays bypass open craniotomy requirements, opening interventional neuroradiology suites as alternative procedure venues.
- ISO 14155 Harmonization:Standardized clinical investigation frameworks across implantable neurotechnology trials reduce redundant study design costs for multi-regional submissions.
Industry Challenges
- Neural Signal Processing Talent Scarcity:Real-time adaptive algorithm development requires cross-trained engineers fluent in both electrophysiology and embedded systems, a skill intersection with limited supply.
- Long-Term Implant Monitoring Infrastructure:Closed-loop systems demand continuous telemetry contracts that strain hospital IT security frameworks and remote patient monitoring reimbursement codes.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuromodulation Closed-Loop Brain-Computer Interfaces Market Trends and Innovations
Signal processing architectures are migrating toward edge-computing configurations that enable local adaptive stimulation without cloud dependency. This shift compresses latency windows while complicating cybersecurity validation protocols.
Machine learning inference engines are converging with implantable pulse generators to enable patient-specific seizure prediction models. Epilepsy monitoring centers in the United States are piloting these adaptive algorithms ahead of broader therapeutic area expansion. The technology is converging with long-term implant monitoring contracts to create recurring revenue structures distinct from traditional device sales.
The EU Medical Device Regulation is recasting post-market clinical follow-up obligations for active implantable neurotechnology. Manufacturers must now maintain prospective registries spanning 15-year device lifecycles, forcing infrastructure investments that smaller electrode array suppliers cannot absorb. Stroke rehabilitation applications face the steepest compliance burden given immature long-term efficacy datasets.
Academic medical center procurement committees are unbundling device procurement from surgical service contracts, forcing vendors to compete on hardware margins alone. Interventional neuroradiology departments are capturing case volumes that previously flowed to functional neurosurgery divisions. This behavioral shift is most visible in United States academic hospitals where GME funding structures reward subspecialty service line expansion.
Neuromodulation Closed-Loop Brain-Computer Interfaces Market Segmentation
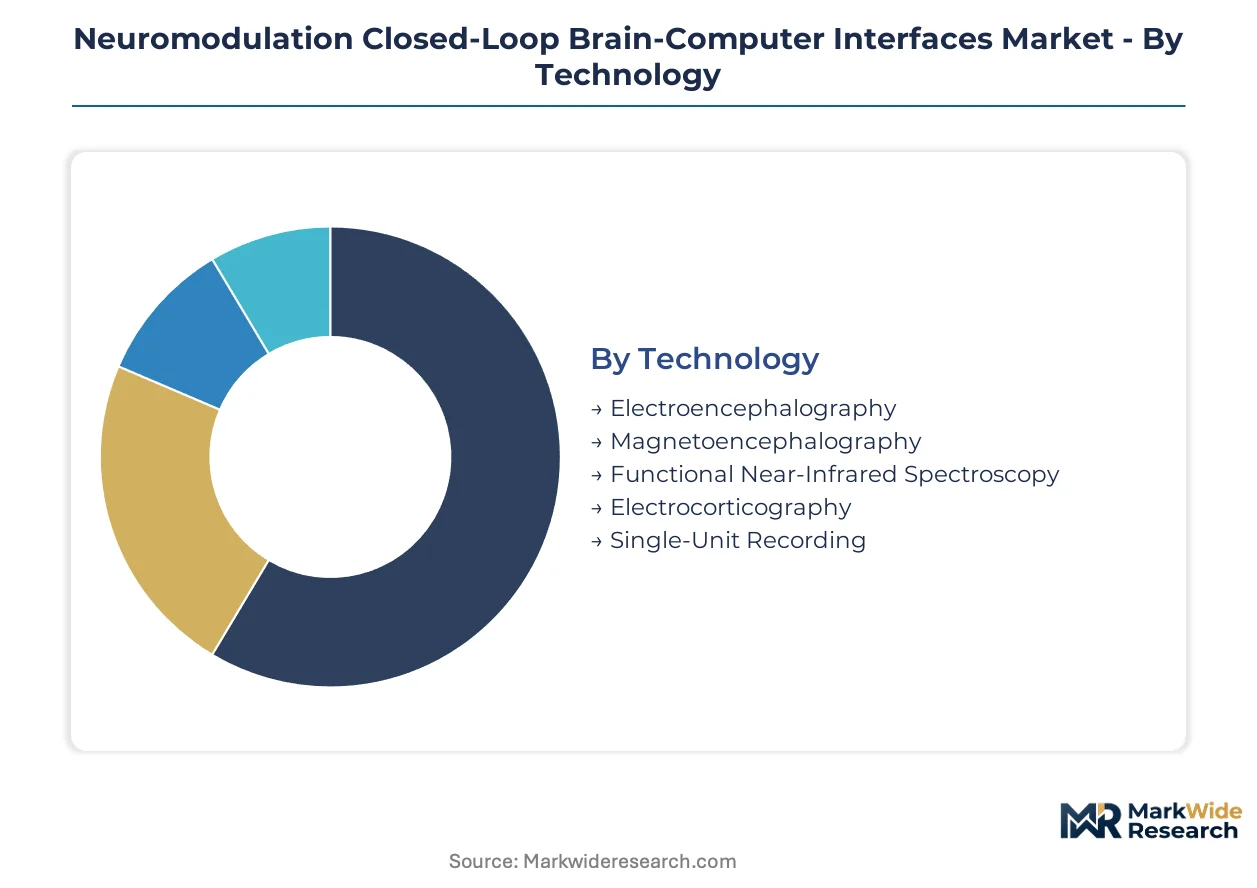
Technology selection determines upfront capital requirements and regulatory pathway complexity for closed-loop neuromodulation systems. Deployment configuration and application focus further stratify operating margins and reimbursement eligibility across vendor portfolios.
Technology:
Capital intensity peaks with invasive signal acquisition modalities requiring surgical infrastructure and long-term implant monitoring contracts.
- Electrocorticography:Subdural electrode arrays deliver high spatial resolution through direct cortical contact. Academic medical centers in the United States anchor procurement volumes as FDA breakthrough designations accelerate clinical validation timelines for responsive neurostimulation platforms.
- Single-Unit Recording:Microelectrode penetration captures individual neuron action potentials at sampling rates exceeding 30 kHz. Research laboratories concentrate demand where adaptive algorithm development requires granular spike train data for therapeutic intervention protocols.
- Electroencephalography:Scalp-mounted electrodes enable non-invasive neural monitoring with lower infrastructure barriers.
- Magnetoencephalography:Superconducting quantum interference devices detect magnetic field fluctuations from neural current flow.
- Functional Near-Infrared Spectroscopy:Optical hemodynamic imaging supports portable brain monitoring without electromagnetic interference constraints.
Most installed capacity flows through Electrocorticography. Expansion is steepest in Single-Unit Recording.
Application:
Reimbursement coding maturity separates established therapeutic indications from investigational protocols still accumulating clinical evidence.
- Epilepsy Monitoring:Responsive neurostimulation systems command the largest application volume with established FDA PMA pathways and dedicated CPT codes. Veterans Health Administration hospitals anchor United States procurement, creating reference sites that civilian academic centers replicate.
- Stroke Rehabilitation:Neural plasticity protocols represent underpenetrated therapeutic white space as motor recovery evidence matures. Neurorehabilitation centers are piloting closed-loop feedback systems ahead of broader payer coverage determinations.
- Motor Disorders:Deep brain stimulation heritage extends to adaptive closed-loop configurations for Parkinson's disease and essential tremor.
- Pain Management:Spinal cord stimulation platforms integrate neural feedback for chronic intractable pain modulation.
- Cognitive Enhancement:Investigational applications target memory augmentation and attention regulation with limited regulatory precedent.
Epilepsy Monitoring retains the dominant revenue share. Stroke Rehabilitation is gaining share fastest as neural plasticity protocols demonstrate functional outcomes.
End User:
Procurement authority and funding mechanisms vary sharply across institutional categories, shaping vendor sales motion and contract structure.
- Military Medical Facilities:United States Veterans Health Administration and Defense Health Agency programs anchor early adoption with dedicated neurotechnology research budgets. Walter Reed National Military Medical Center and affiliated polytrauma centers maintain specialized procurement committees for implantable neural interfaces.
- Neurorehabilitation Centers:Dedicated stroke and trauma recovery facilities concentrate demand for motor restoration protocols. These centers negotiate bundled device and therapy contracts that compress hardware margins while expanding service revenue attach rates.
- Research Laboratories:NIH-funded institutions drive preclinical validation studies for novel electrode array designs.
- Academic Institutions:Medical school affiliated hospitals balance clinical service delivery with investigator-initiated trial participation.
- Specialized Clinics:Private epilepsy and movement disorder centers focus on established indications with clear reimbursement pathways.
Military Medical Facilities channel the highest per-site procurement volumes. Neurorehabilitation Centers are expanding most quickly as outpatient neural plasticity protocols proliferate.
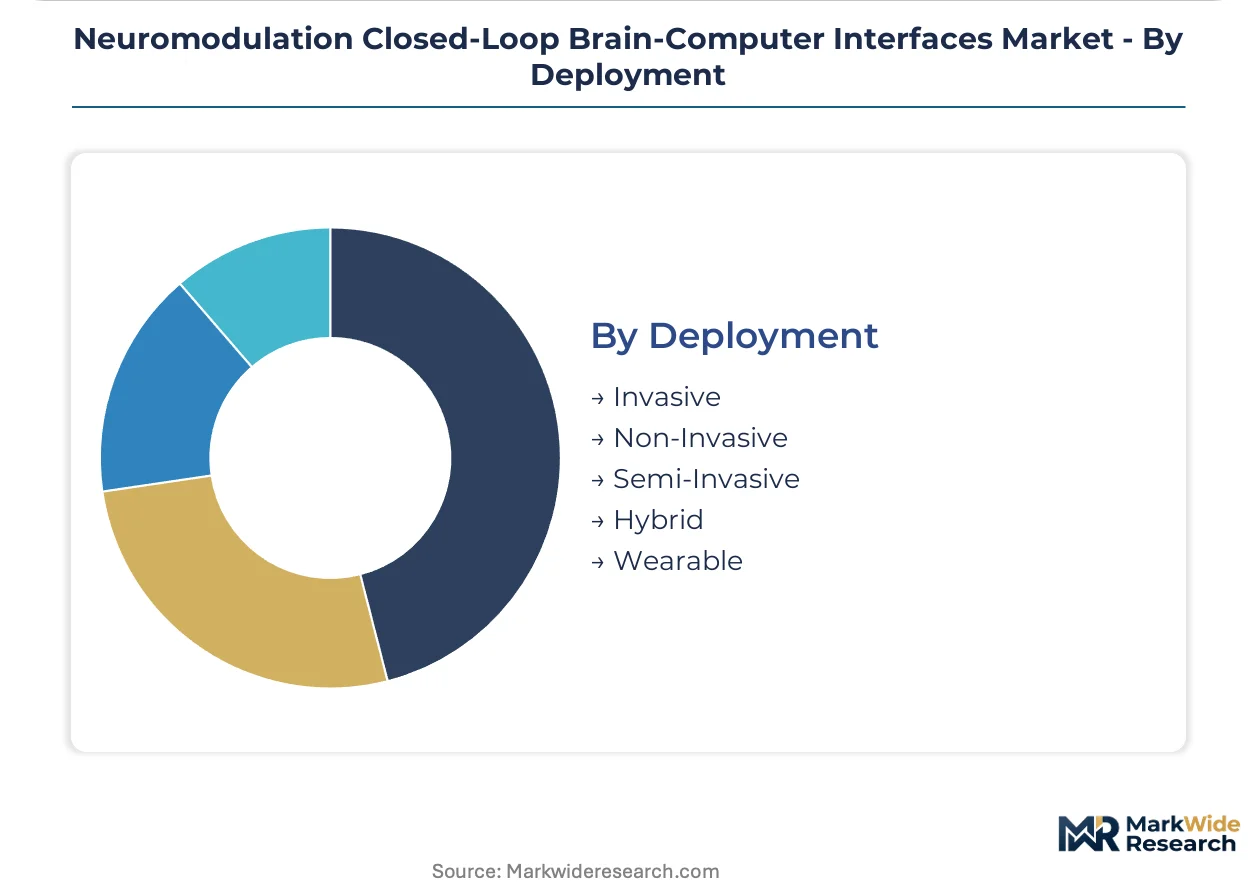
Deployment:
Surgical risk profile and procedure venue requirements determine addressable patient populations and competitive dynamics.
- Invasive:Craniotomy-dependent implantation captures premium pricing through surgical service attach rates and long-term monitoring contracts. Functional neurosurgery divisions at United States academic medical centers control referral flows and vendor qualification timelines.
- Semi-Invasive:Endovascular electrode delivery via interventional neuroradiology suites bypasses open craniotomy requirements. Synchron and competing platforms target this configuration to expand eligible patient populations beyond traditional deep brain stimulation candidates.
- Non-Invasive:Transcranial and scalp-based systems serve screening and pediatric populations where surgical risks deter invasive referral.
- Hybrid:Combined invasive and external components enable staged therapy escalation.
- Wearable:External closed-loop systems target ambulatory monitoring with consumer-grade form factors.
Invasive deployment retains the dominant margin pool. Semi-Invasive configurations are climbing the fastest as interventional neuroradiology departments capture case volumes from functional neurosurgery divisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EU MDR compliance costs drive electrode array production toward jurisdictions with streamlined active-implantable pathways. Swiss and German precision foundries retain metallurgical expertise while expanding cleanroom capacity in lower-cost European locales.
United States
Veterans Health Administration hospitals anchor procurement volumes through dedicated neurotechnology research budgets. FDA breakthrough device designations compress premarket review timelines for responsive neurostimulation platforms. Academic medical centers in Massachusetts and California control vendor qualification flows for implantable neural interfaces.
Germany
Precision foundries in Baden-Württemberg supply platinum-iridium electrode arrays to global neuromodulation device manufacturers. EU MDR post-market surveillance obligations extend clinical follow-up timelines for active implantable devices. The Tübingen-Stuttgart medical technology cluster concentrates electrocorticography system development alongside Max Planck Institute neuroscience research partnerships.
Switzerland
Specialized metallurgical suppliers dominate high-reliability electrode material production for invasive brain-computer interfaces. Swissmedic maintains distinct regulatory pathways for breakthrough neurotechnology that diverge from centralized EU procedures. The Lake Geneva region hosts contract manufacturers serving both European and North American neuromodulation OEMs.
China
Domestic neurotechnology firms are scaling electrocorticography electrode production under NMPA innovation fast-track programs for implantable devices. Government-backed semiconductor initiatives channel funding toward neural signal processing chip development. Beijing and Shanghai academic hospitals pilot closed-loop epilepsy systems ahead of reimbursement coding formalization.
Japan
PMDA Sakigake designation pathways accelerate clinical validation for novel neural interfaces targeting stroke rehabilitation applications. METI funding supports brain-machine interface commercialization through public-private research consortia. The Kansai region's medical device manufacturing base supplies electrode components to Asia-Pacific neuromodulation system integrators.
Neuromodulation Closed-Loop Brain-Computer Interfaces Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue endovascular deployment configurations that bypass open craniotomy requirements. Market structure consolidates around three archetypes: diversified medical technology conglomerates with deep brain stimulation heritage, specialized responsive neurostimulation platform developers, and venture-backed neural interface innovators. Dominant competitive moves include strategic partnerships with academic medical centers for clinical validation and technology licensing agreements for electrode array manufacturing.
Within the diversified conglomerate tier, Medtronic anchors established neuromodulation portfolios. NeuroPace exemplifies specialized responsive neurostimulation platform developers focused on epilepsy monitoring. Synchron occupies a position among emerging entrants pursuing catheter-delivered electrode deployment. These three represent distinct strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Medtronic |
| NeuroPace |
| Synchron |
| Paradromics |
| Precision Neuroscience |
| Blackrock Neurotech |
| CorTec |
| Neuralink |
| Beijing Xinzhida Neurotechnology |
| Others |
Pricing and Supply Chain Analysis
Platinum-iridium alloy procurement from Baden-Württemberg foundries flows through three pricing tiers determined by electrode array precision grades and FDA breakthrough designation status. Raw material concentration in Swiss-German metallurgical supply chains compresses margin flexibility for mid-tier manufacturers while premium-tier vendors capture pricing power through long-term implant monitoring contract bundling.
Pricing Analysis
Distributor margins for electrode array components compress hardware pricing by 15-25 points before hospital procurement committees. Three-tier pricing structure across premium, standard, and economy levels separates FDA PMA-approved systems from CE-marked alternatives and investigational devices. Pricing pressure stems from academic medical centers unbundling device procurement from surgical service contracts. Pediatric screening protocols show highest price sensitivity due to scalp EEG substitute availability, while Veterans Health Administration programs demonstrate lowest sensitivity given dedicated neurotechnology research budgets.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss precision foundries for platinum-iridium electrode metallurgy. Manufacturing concentration in Baden-Württemberg, the Lake Geneva region, and emerging cleanroom capacity in lower-cost European locales creates geographic dependency. Raw material inputs draw from South African platinum group metals, German precision machining equipment, and specialized polymer substrates for biocompatible insulation. Tariff exposure on raw platinum group metals introduces cost volatility. Distribution runs through neuromodulation OEM direct sales forces and specialized neurotechnology distributors serving academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as FDA breakthrough designations compress premarket timelines and expand reimbursable indications. Neural plasticity protocol maturation extends addressable patient populations beyond epilepsy into stroke rehabilitation.
For Market Incumbents: Deepen vertical integration into electrode array manufacturing to defend margin position against unbundling procurement trends at academic medical centers. Secure captive supply of platinum-iridium alloys from Baden-Württemberg foundries before EU MDR compliance costs reshape supplier qualification timelines. Invest in ISO 14155 harmonization infrastructure to reduce redundant clinical study costs across multi-regional submissions. For New Entrants and Emerging Players: Enter via endovascular deployment configurations that bypass open craniotomy requirements and open interventional neuroradiology suites as alternative procedure venues. Target stroke rehabilitation applications as the most penetrable therapeutic white space where neural plasticity evidence is maturing ahead of established reimbursement coding. Pursue strategic partnerships with military medical facilities to establish reference sites that civilian academic centers replicate. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR post-market surveillance obligations force infrastructure investments that smaller electrode array suppliers cannot absorb. Five-to-ten year viability favors platforms with responsive neurostimulation algorithm portfolios and long-term implant monitoring contract revenue structures. Acquisition target archetype: specialized electrode array foundries with FDA pre-certified manufacturing lines. Signal to watch: reimbursement coding formalization for closed-loop neurostimulation in stroke rehabilitation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated premarket review compresses clinical validation timelines for responsive neurostimulation platforms. |
| Electrode Array Manufacturing Scale-Up | Pre-certified production lines in Baden-Württemberg secure supply before procurement compression intensifies. |
| Long-Term Implant Monitoring Contract | Recurring telemetry revenue structures reduce hardware margin dependence at academic medical centers. |
| Interventional Neuroradiology Partnership | Catheter-delivered deployment expands eligible patient populations beyond traditional craniotomy candidates. |
| Neural Signal Processing Talent Acquisition | Cross-trained engineers fluent in electrophysiology and embedded systems remain scarce across the industry. |
Research Methodology
Bottom-up epilepsy monitoring center and neurorehabilitation facility modeling reconciled against top-down electrode array manufacturing capacity tracking forms the analytical core. Primary interviews with functional neurosurgeons, interventional neuroradiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) and PMA filings, ClinicalTrials.gov registry entries, CMS Medicare reimbursement databases, and EU MDR notified body documentation. Triangulation across stakeholder inputs and regulatory filings ensures segmentation integrity.
Historical trendline analysis of responsive neurostimulation system deployments informed projection modeling across technology, application, end user, and deployment configuration dimensions. CAGRs derive from segmented adoption curves weighted by reimbursement coding maturity and clinical evidence accumulation. Forecast inputs include FDA breakthrough designation pipeline velocity, EU MDR post-market surveillance cost trajectories, and neural plasticity protocol publication rates in stroke rehabilitation.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in long-term implant monitoring reimbursement coding formalization introduce uncertainty bands. Forecasts reflect documented assumptions regarding regulatory pathway acceleration and clinical evidence maturation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.