
 Semiconductor Laser Therapeutic Device Market | 2026-2036
Semiconductor Laser Therapeutic Device Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Laser Therapeutic Device Market Insights
The gap between premium surgical laser platforms and commodity pain therapy devices is expanding in measurable ways. Lumenis Inc. leverages its vertically integrated supply chain to dominate high-margin surgical segments. Biolase anchors its position through specialized dental laser portfolios that command pricing power in North American clinics. IRIDEX Corporation competes on ophthalmic precision, sustaining R&D intensity that commodity players cannot match.
A semiconductor laser therapeutic device emits coherent light from a solid-state gain medium—typically gallium arsenide or indium phosphide diodes operating at wavelengths from 635 nm to 980 nm—to induce photochemical or thermal biological effects for tissue repair, pain modulation, or surgical incision. Diode lasers lead unit shipments due to compact form factors and falling semiconductor costs, while low-level laser technology captures expanding home-use and rehabilitation clinic demand where non-invasive protocols prevail. Pulse laser architectures command premium positioning in dermatology applications requiring precise thermal confinement.
The FDA's 510(k) framework and the EU Medical Device Regulation shape product standards, with CE marking under MDR now requiring clinical evidence reviews that extend market access timelines for new entrants. Japan's PMDA enforces stringent quality management system audits that favor established manufacturers with localized regulatory affairs capabilities. Stakeholders must monitor how evolving reimbursement codes for photobiomodulation therapies in major markets will reshape volume distribution between institutional and ambulatory settings.
Market Dynamics
Semiconductor laser therapeutic device manufacturers face intensifying pressure from the FDA's compressed 510(k) review timelines, which reward established players with robust quality management systems while squeezing smaller entrants on compliance velocity and documentation burden.
Growth Catalysts
- Photobiomodulation reimbursement expansion:Germany's statutory health insurers are adding low-level laser therapy codes for chronic pain management, expanding institutional procurement volumes in metropolitan hospital clusters.
- Diode cost deflation:Gallium arsenide wafer processing advances from semiconductor foundries are compressing bill-of-materials costs for 635-980 nm therapeutic modules.
- Home-use protocol validation:Rehabilitation clinics in Japan's Kanto region are certifying patient-operated devices for between-visit pain modulation, creating ambulatory demand outside institutional settings.
Market Restraints
- Indium phosphide supply concentration:Foundry capacity for 980 nm high-power diodes concentrates among three East Asian contract manufacturers, exposing procurement to geographic disruption.
- Clinical evidence thresholds:The EU MDR's expanded clinical evaluation requirements for Class IIa therapeutic devices extend CE marking timelines and documentation costs for new market entrants.
- Non-invasive neuromodulation substitution:Transcranial magnetic stimulation systems are capturing refractory migraine treatment protocols previously addressed by infrared laser therapy.
Strategic Opportunities
- Veterinary therapeutic expansion:Equine rehabilitation centers in Kentucky and Florida are adopting diode laser systems for soft-tissue injury protocols, opening a non-regulated channel with faster procurement cycles.
- AI-guided dosage optimization:Integration of machine learning algorithms with tissue spectroscopy sensors enables real-time fluence adjustment, differentiating premium platforms in dermatology applications.
- India's PLI scheme for medical electronics:Production-linked incentives for domestic manufacturing of therapeutic devices attract component suppliers to establish localized diode packaging facilities.
Industry Challenges
- Laser safety officer certification bottlenecks:Hospital systems in Japan require PMDA-recognized training credentials for equipment operators, constraining deployment velocity in expanding clinic networks.
- Legacy EMR integration complexity:Ambulatory surgical centers face interoperability friction when connecting laser therapy documentation modules to existing electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Laser Therapeutic Device Market |
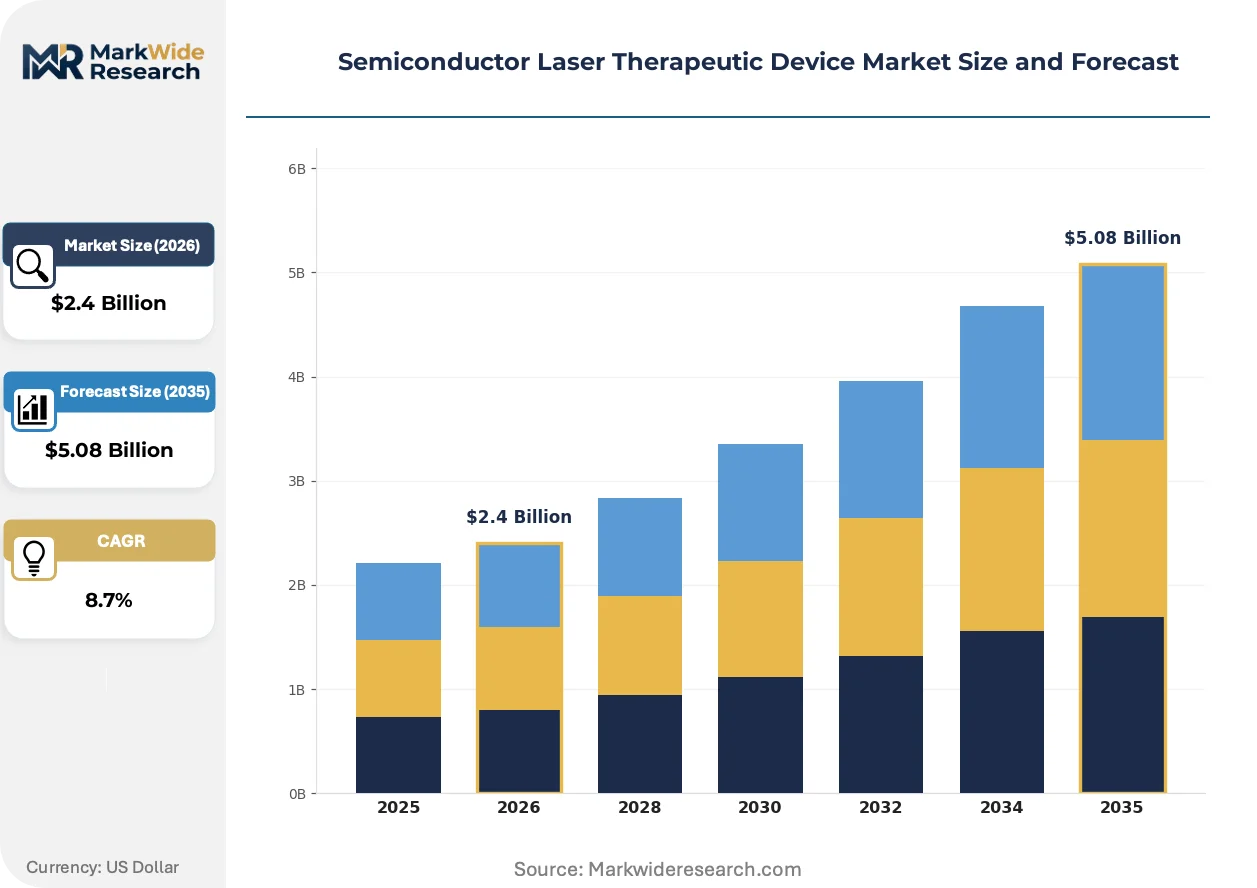
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Lasers, Fiber Lasers, Solid-State Lasers, Gas Lasers Application: Pain Management, Surgical Procedures, Dermatology, Dentistry End User: Hospitals, Clinics, Dental Practices, Research Institutes Technology: High-Power Lasers, Low-Level Lasers, Pulse Lasers, Continuous Wave Lasers |
| Companies Covered | Lumenis Inc., Biolase, IRIDEX Corporation, Dornier MedTech GmbH, PHYSIOMED ELEKTROMEDIZIN AG, LISA LASER, WON TECH, Cynosure, Wuhan HNC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Laser Therapeutic Device Market Trends and Innovations
Photonic integration and regulatory automation are compressing product development cycles while fragmenting competitive advantage between hardware miniaturization specialists and software-enabled therapy protocol platforms.
Multi-wavelength diode arrays with integrated micro-optics are rewriting therapeutic precision standards in dermatology and pain management applications. Academic medical centers in Boston and Heidelberg are validating these architectures for personalized photobiomodulation protocols. The technology is compressing treatment session durations from twenty minutes to under five, forcing hardware manufacturers to compete on software-defined protocol libraries rather than raw optical power specifications.
The EU MDR's post-market surveillance requirements for Class IIa laser devices are mandating systematic clinical follow-up data collection from CE-marked products. German notified bodies are enforcing quarterly adverse event reporting thresholds that favor manufacturers with established pharmacovigilance infrastructure. Ophthalmic laser segments face the steepest compliance burden, with IRIDEX Corporation and comparable specialists investing in dedicated European regulatory affairs teams to maintain market access velocity.
Japanese metropolitan hospital clusters are consolidating procurement authority through centralized purchasing cooperatives serving Tokyo and Osaka metro areas. These entities unbundle device acquisition from service contracts, forcing manufacturers to compete on transparent lifecycle cost models rather than bundled financing. The shift favors domestic players with localized technical service networks and compresses margins for foreign entrants dependent on third-party distribution partnerships.
Semiconductor Laser Therapeutic Device Market Segmentation
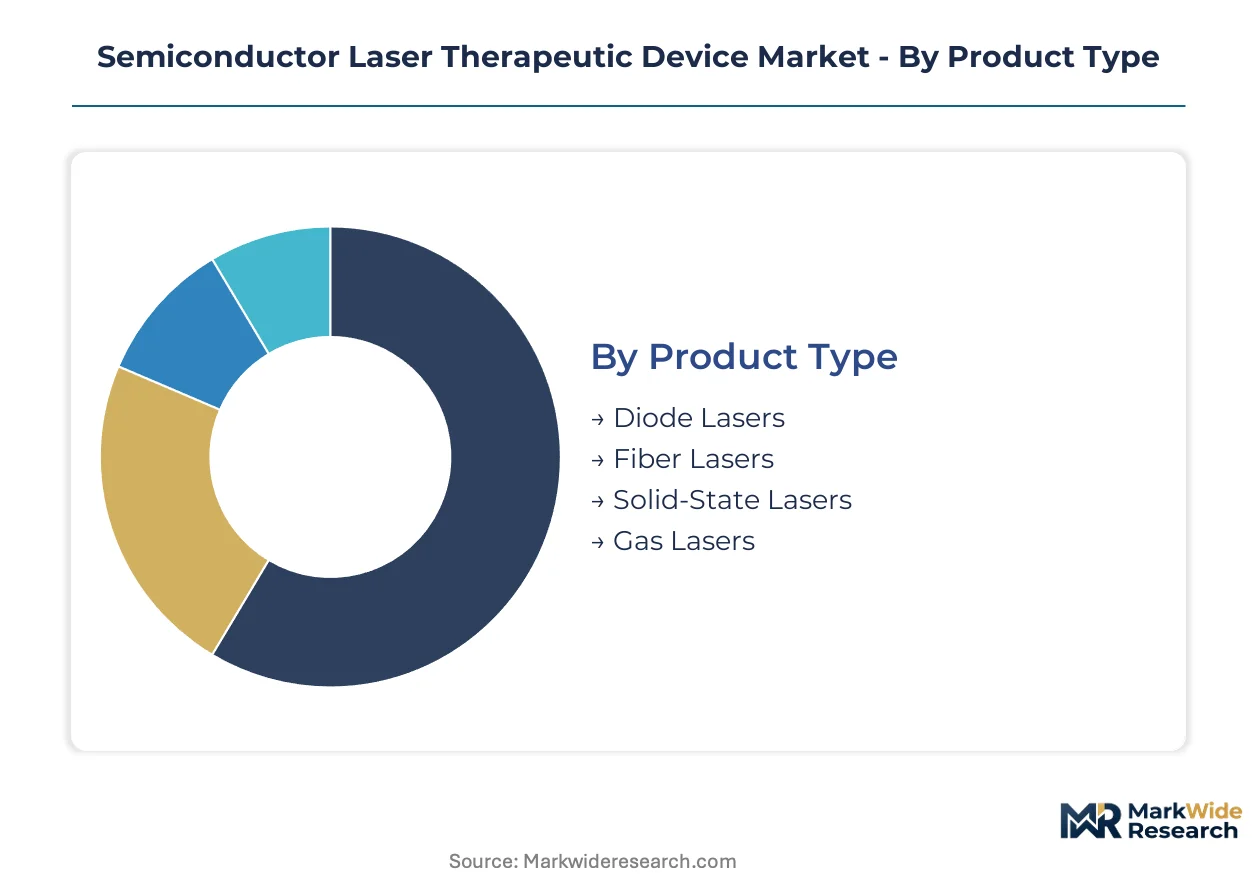
Segmentation in the semiconductor laser therapeutic device market reveals how device architecture, clinical application, and procurement setting interact to determine pricing power and regulatory pathway complexity. Understanding these cross-cutting dimensions helps manufacturers prioritize R&D investment and distribution partnerships.
Product Type:
Integration depth varies sharply across laser architectures, with some segments designed for standalone therapeutic workstations and others engineered for embedded surgical platforms.
- Diode Lasers:Gallium arsenide or indium phosphide diodes emitting 635-980 nm wavelengths dominate compact pain therapy systems. German hospital procurement clusters in Munich and Berlin are accelerating orders for chronic pain management protocols. Falling semiconductor foundry costs are compressing bill-of-materials for 635-980 nm modules.
- Fiber Lasers:Doped silica gain media deliver superior beam quality for precision surgical applications requiring thermal confinement. Demand concentrates in Japanese ophthalmic suites where PMDA-mandated quality management systems favor established suppliers with localized service networks.
- Solid-State Lasers:Crystal-based gain media such as Nd:YAG support high-peak-power dermatology platforms.
- Gas Lasers:CO2 and excimer architectures retain niche positioning in specialized ablative procedures.
Diode lasers lead volumes today; fiber lasers are gaining share fastest.
Application:
Cost tier stratification separates capital-intensive surgical installations from reimbursable outpatient protocols and elective cosmetic procedures.
- Pain Management:Low-level laser therapy for musculoskeletal and neuropathic conditions drives ambulatory clinic adoption. Germany's statutory health insurers are expanding reimbursement codes for photobiomodulation, directly lifting institutional procurement in metropolitan hospital clusters.
- Surgical Procedures:High-precision cutting and coagulation applications command premium pricing in integrated operating theaters. FDA 510(k) clearance pathways for Class II surgical lasers reward manufacturers with robust quality management systems.
- Dermatology:Aesthetic and medical skin treatments span professional and consumer device categories.
- Dentistry:Soft-tissue procedures and photobiomodulation for oral healing support specialized dental laser portfolios.
Surgical procedures capture the highest revenue per unit; pain management is expanding most quickly.
End User:
Customer type determines procurement authority structure, with centralized purchasing cooperatives reshaping competitive dynamics in consolidated health systems.
- Hospitals:Acute care institutions with capital equipment budgets and laser safety officer certification requirements. Japanese metropolitan clusters around Tokyo and Osaka are consolidating procurement through centralized cooperatives that unbundle device acquisition from service contracts.
- Clinics:Outpatient rehabilitation and pain management facilities with faster procurement cycles and lower compliance thresholds. Kentucky and Florida equine rehabilitation centers are adopting diode systems for veterinary soft-tissue protocols.
- Dental Practices:Specialty clinics with procedure-specific laser requirements and direct-to-practice distribution channels.
- Research Institutes:Academic medical centers validating multi-wavelength architectures and AI-guided dosage optimization protocols.
Hospitals dominate absolute spending; clinics show the steepest expansion trajectory.
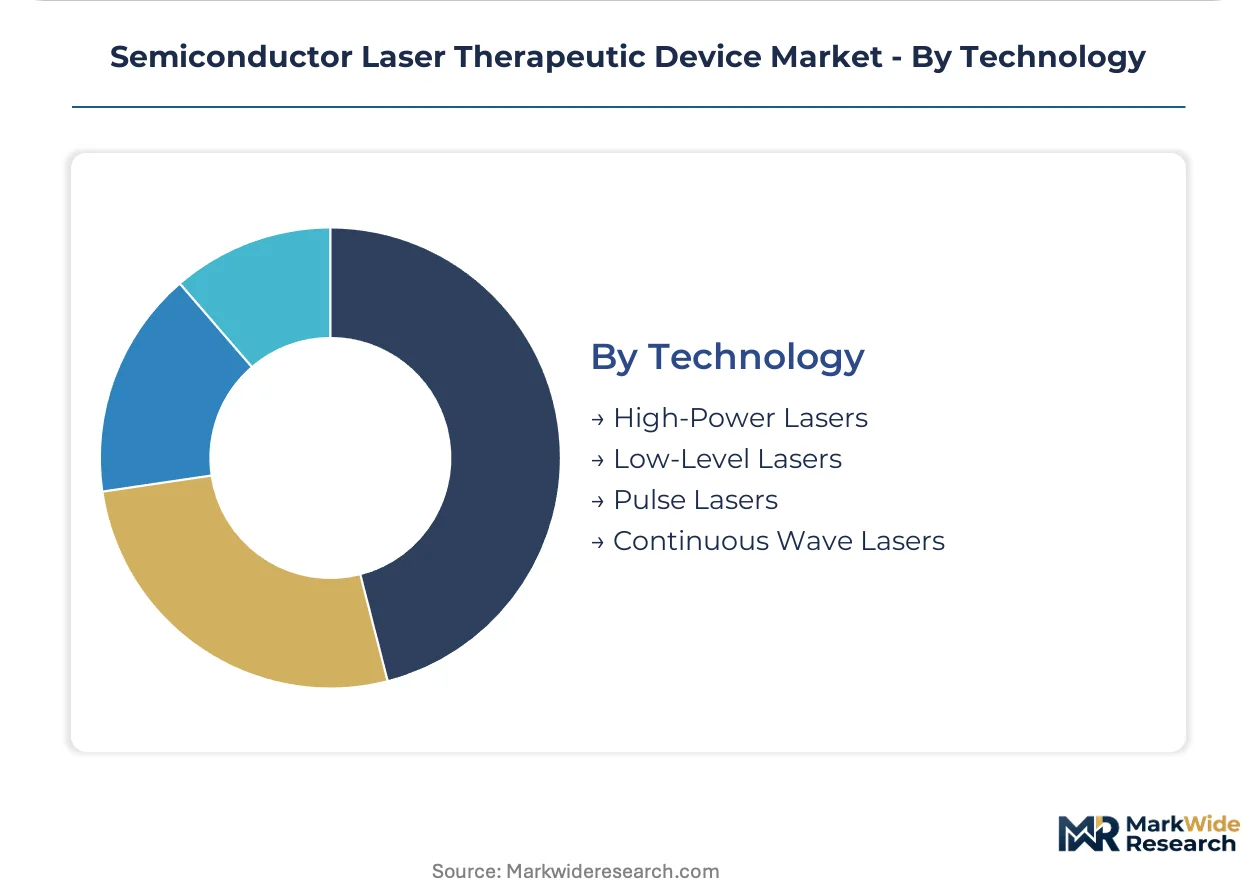
Technology:
Power delivery architecture and temporal modulation pattern determine thermal tissue interaction and corresponding regulatory classification burden.
- High-Power Lasers:Continuous or quasi-continuous output above therapeutic thresholds for surgical incision and ablation. EU MDR Class IIa requirements mandate systematic clinical follow-up data collection, favoring manufacturers with established pharmacovigilance infrastructure.
- Low-Level Lasers:Sub-thermal fluence for photochemical tissue repair and pain modulation. Home-use protocol validation in Japan's Kanto region is creating ambulatory demand outside institutional settings.
- Pulse Lasers:Q-switched or mode-locked architectures enabling precise thermal confinement in dermatology applications.
- Continuous Wave Lasers:Uninterrupted output for uniform tissue heating in selected surgical protocols.
Low-level lasers lead unit shipments; high-power lasers command the highest average selling prices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized photonics engineers and clinical laser safety officers concentrate in Germany, Japan, and the United States, anchoring the geographic distribution of therapeutic device innovation and procurement authority.
Germany
Metropolitan hospital clusters in Munich and Berlin are accelerating diode laser procurement for chronic pain management protocols. The country's statutory health insurers are expanding reimbursement codes for photobiomodulation under the national health framework. Bavaria's medical technology corridor around Erlangen hosts concentrated quality management system expertise serving EU MDR compliance requirements.
Japan
Centralized purchasing cooperatives serving Tokyo and Osaka metro areas are unbundling device acquisition from service contracts. PMDA enforces stringent quality management system audits that favor established manufacturers with localized regulatory affairs capabilities. The Kanto region's rehabilitation clinics are certifying patient-operated devices for between-visit pain modulation, creating ambulatory demand outside institutional settings.
United States
FDA's compressed 510(k) review timelines for Class II medical lasers reward manufacturers with robust quality management systems. The agency's updated clearance pathway is compressing time-to-market for manufacturers with established documentation infrastructure. Academic medical centers in Boston are validating multi-wavelength architectures for personalized photobiomodulation protocols.
China
Foundry capacity for gallium arsenide wafer processing is compressing bill-of-materials costs for 635-980 nm therapeutic modules. The country's national medical device regulator maintains stringent clinical evidence requirements for imported laser therapeutic devices. Wuhan's optoelectronics cluster supports domestic diode packaging capabilities for regional supply chain integration.
India
Production-linked incentives for domestic manufacturing of therapeutic devices are attracting component suppliers to establish localized diode packaging facilities. The Central Drugs Standard Control Organization oversees medical device registration with escalating quality system requirements. Maharashtra's medical electronics manufacturing corridor is emerging as a hub for contract assembly of low-level laser therapy systems.
Semiconductor Laser Therapeutic Device Market Competitive Landscape
Top-tier vendors anchor premium surgical segments, while mid-tier specialists populate pain management and dental applications. The competitive structure rewards backward integration into semiconductor foundry relationships and in-house production of optical subsystems. Three archetypes dominate: vertically integrated platform manufacturers, application-specific portfolio specialists, and regional contract assemblers. M&A activity concentrates on optical component suppliers, and strategic partnerships with academic medical centers accelerate protocol validation timelines.
Among Israel-based surgical laser developers, Lumenis Inc. exemplifies the vertically integrated platform archetype through its control over gallium arsenide supply channels. California-based Biolase occupies a position within the dental application specialist tier, leveraging procedure-specific portfolio concentration. IRIDEX Corporation represents the ophthalmic precision segment, where regulatory intensity and R&D requirements create defensive moats against commodity competition.
| Leading Market Players |
|---|
| Lumenis Inc. |
| Biolase |
| IRIDEX Corporation |
| Dornier MedTech GmbH |
| PHYSIOMED ELEKTROMEDIZIN AG |
| LISA LASER |
| WON TECH |
| Cynosure |
| Wuhan HNC |
| Others |
Pricing and Supply Chain Analysis
Gallium arsenide wafer spot indices cascade through semiconductor laser therapeutic device supply chains into three distinct pricing tiers: premium surgical platforms with bundled service contracts, mid-range pain therapy systems with unbundled procurement, and economy home-use devices with minimal aftermarket attachment.
Pricing Analysis
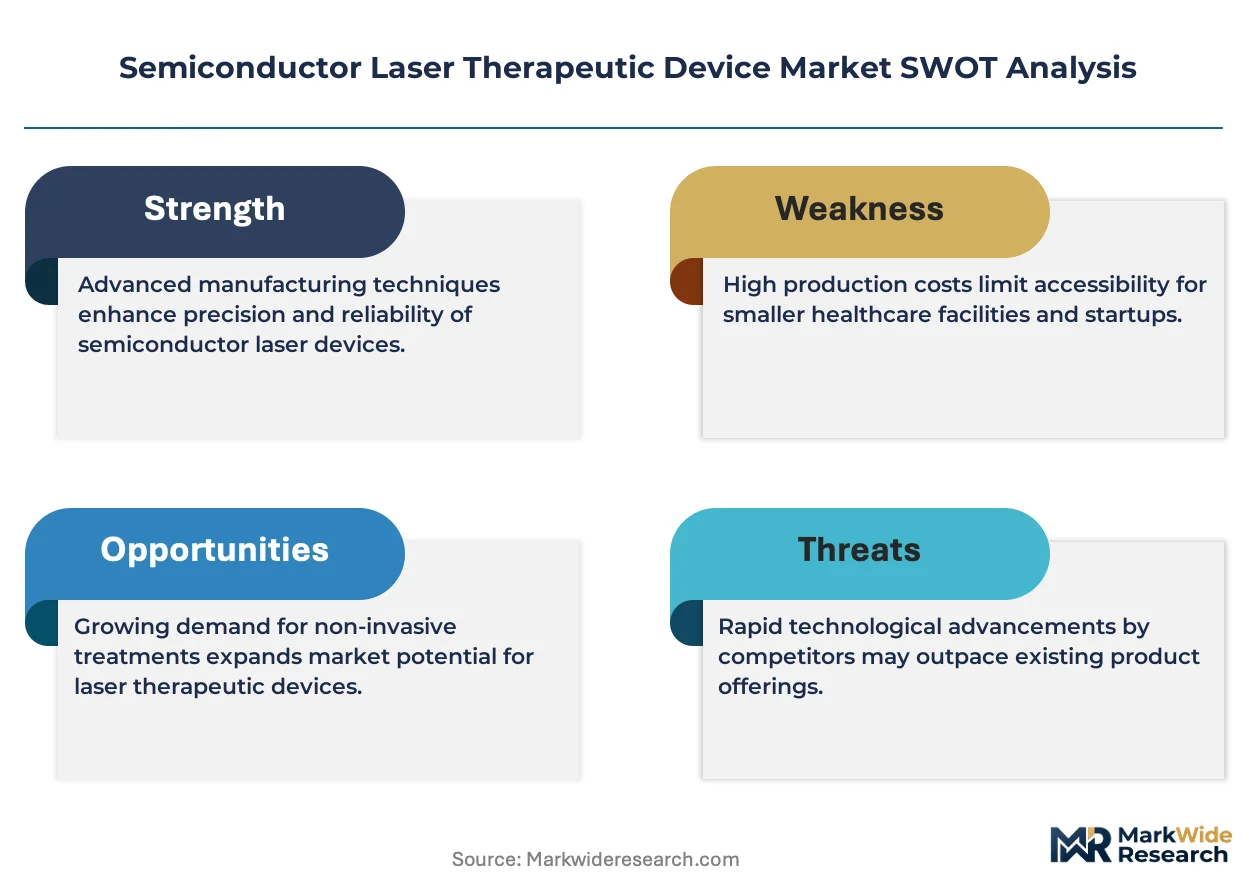
The bundled-versus-unbundled service split defines competitive positioning across procurement settings. Japanese metropolitan hospital cooperatives now mandate transparent lifecycle cost models that separate device acquisition from technical service agreements, compressing margins for foreign manufacturers dependent on bundled financing. Pricing stratifies across premium, standard, and economy tiers based on optical power specifications and FDA 510(k) clearance tier. Cost compression in the standard tier intensifies as gallium arsenide foundry output expands. Ambulatory clinics exhibit highest price sensitivity; integrated surgical suites demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from German hospital procurement clusters mandate multi-supplier qualification for 980 nm high-power diode modules. Foundry capacity concentrates in China, Taiwan, and South Korea for gallium arsenide wafer processing and indium phosphide epitaxy. Manufacturing rests on precision optical subsystems, semiconductor packaging, and thermal management components. Single-source vulnerability persists for specialized micro-optic arrays sourced from Japanese precision glass manufacturers. Distribution runs through regional medical device distributors with PMDA-recognized quality management credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA's compressed 510(k) review timelines compound advantage for established quality management systems and accelerate demand concentration among pre-cleared manufacturers.
For Market Incumbents: Deepen backward integration into gallium arsenide foundry relationships to defend margin position against commodity diode cost deflation. Expand dedicated European regulatory affairs teams to maintain CE marking velocity under EU MDR post-market surveillance requirements. Prioritize in-house production of optical subsystems over outsourced assembly.
For New Entrants and Emerging Players: Enter via veterinary therapeutic channels in Kentucky and Florida where procurement cycles bypass FDA premarket notification requirements. Target equine rehabilitation centers with simplified diode systems for soft-tissue injury protocols. Pursue direct-to-practice distribution partnerships with ambulatory pain clinics rather than consolidated hospital cooperatives.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance burdens exceed smaller entrants' pharmacovigilance infrastructure capacity. Long-term viability favors manufacturers with captive semiconductor packaging capabilities and localized technical service networks. Acquisition target archetype: mid-tier pain therapy specialists with established reimbursement code validation. Signal to watch: PMDA-recognized training credential bottlenecks constraining Japanese clinic network expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed review timelines reward established quality management documentation infrastructure. |
| CE Marking Pathway Investment | EU MDR clinical evidence requirements extend timelines but create defensive moats against new entrants. |
| Hospital System Partnership | Japanese metropolitan cooperatives unbundle contracts, favoring localized service network depth. |
| Software Companion Development | AI-guided dosage optimization differentiates premium dermatology platforms through real-time fluence adjustment. |
| Reimbursement Strategy | Germany's expanding photobiomodulation codes directly lift institutional procurement volumes. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers and hospital purchasing committees, secondary validation through FDA 510(k) filings and GPO contract databases, and trade data from semiconductor foundry disclosures — were reconciled through bottom-up and top-down triangulation. Stakeholder roles engaged included clinicians, laser safety officers, regulatory affairs specialists, and procurement managers at metropolitan hospital clusters. Secondary sources encompassed PMDA quality management audit records, EU MDR notified body guidance documents, and CMS reimbursement code updates.
Historical shipment data cross-referenced against panel input from device manufacturers anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, clinical application, end-user procurement setting, and power delivery technology. CAGRs were derived from installed base growth rates and replacement cycle assumptions. Industry-specific forecast inputs incorporated gallium arsenide wafer cost curves and photobiomodulation reimbursement expansion trajectories.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time foundry capacity utilization data introduce uncertainty bands around semiconductor cost assumptions. Forecasts reflect documented assumptions regarding FDA review velocity and EU MDR enforcement consistency. Deviation in PMDA training credential requirements or indium phosphide supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Over-The-Wire Micro-Guide Catheter Market
Medical Devices
UHD Surgical Display Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
Joint Reconstruction Devices Market
Medical Devices
Medical Device Tester Market
Medical Devices
Medical Devices Clinical Trials Market
Medical Devices
Blood Collection Devices Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Carotid Stenting Systems Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
Microscope Market
Medical Devices
North America Arthroscopy Devices Market
Medical Devices
Nerve Monitoring Devices Market