
 Point-Of-Care Ultrasound (Pocus) Device Market | 2026-2036
Point-Of-Care Ultrasound (Pocus) Device Market Size, Share, and Industry Trends Forecast 2026-2036
Point-Of-Care Ultrasound (Pocus) Device Market Insights
Emergency department procurement of point-of-care ultrasound systems is expanding beyond academic medical centers into community hospitals and freestanding urgent care networks. GE HealthCare leverages its installed base of cart-based systems to cross-sell handheld probes through enterprise purchasing agreements. Butterfly Network anchors its position through semiconductor-based single-probe architecture that collapses cost barriers for outpatient clinics. Siemens Healthineers competes on integrated AI-assisted measurement packages that reduce operator training time.
Point-of-care ultrasound devices are compact diagnostic imaging systems operating at frequencies between 2 and 15 MHz, designed for immediate clinical assessment without requiring patient transport to dedicated radiology suites. Handheld devices and portable ultrasound systems dominate volume shipments, while software solutions capture expanding recurring revenue streams through subscription-based image archiving and cloud-based AI interpretation. Desktop systems retain margin concentration in specialized applications such as cardiac assessment and obstetric monitoring where probe stability and extended imaging sessions matter.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development timelines and clinical evidence standards for manufacturers seeking commercial access. The FDA's emphasis on predicate device equivalence for iterative hardware creates compliance bottlenecks for novel wireless architectures, while MDR technical documentation demands strain smaller European notified bodies. Stakeholders must monitor evolving reimbursement codes for bedside ultrasound procedures, as payor acceptance determines whether hospital capital committees prioritize POCUS deployment against competing diagnostic modalities.
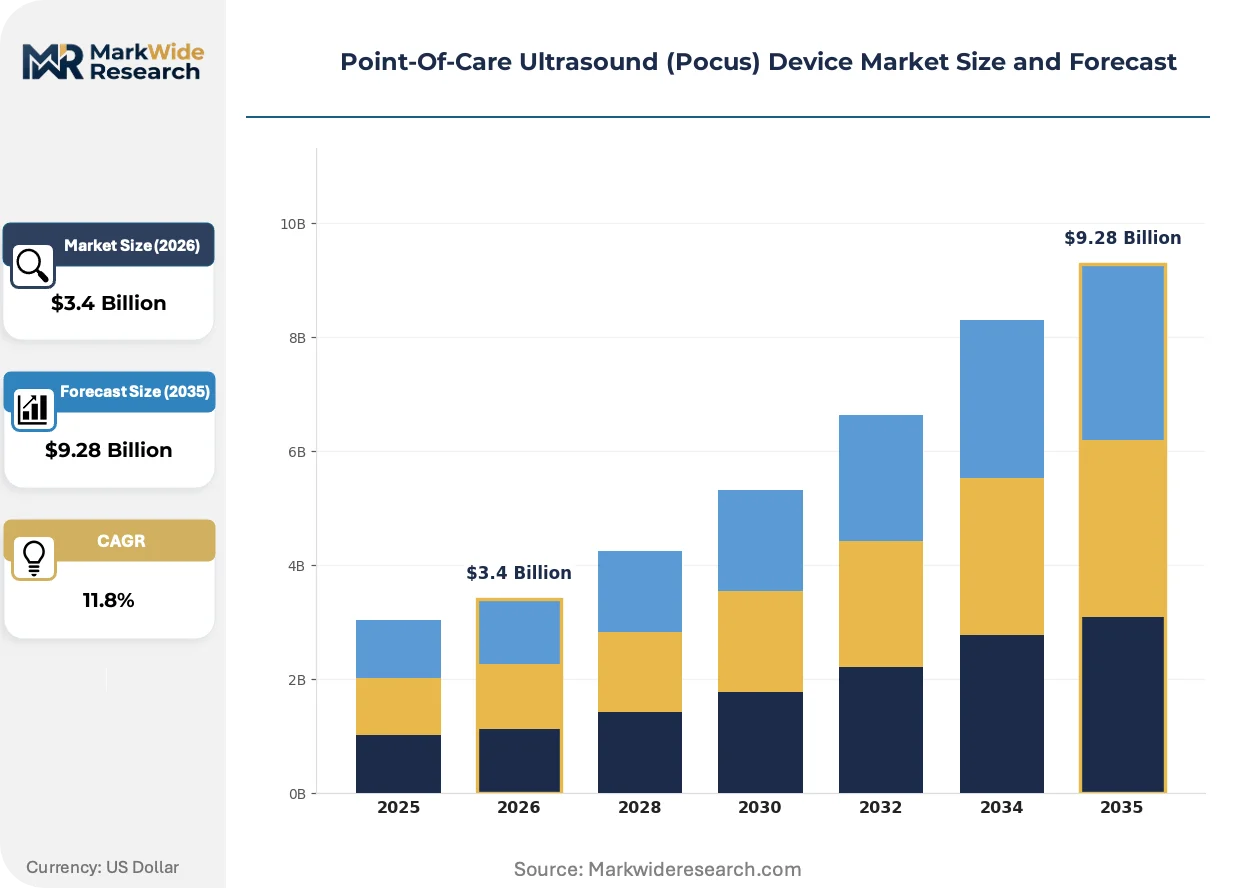
Market Dynamics
Semiconductor-based ultrasound-on-chip architectures are collapsing probe manufacturing costs while FDA 510(k) clearance bottlenecks for wireless devices create uneven competitive access across regulatory jurisdictions.
Growth Catalysts
- Emergency department decentralization:Community hospitals and freestanding urgent care networks in the United States are procuring handheld systems for bedside triage without radiology department mediation.
- EU MDR streamlined pathways:CE marking technical documentation under the Medical Device Regulation is accelerating market entry for wireless-enabled devices from notified bodies in Germany and the Netherlands.
- Rural outreach mandates:Hospital decentralization policies in China are accelerating procurement of portable imaging equipment for county-level medical institutions.
Market Restraints
- Piezoelectric crystal supply concentration:Specialty ceramic substrate production concentrates among Japanese and German material suppliers, exposing probe manufacturers to input cost volatility.
- FDA predicate device equivalence requirements:The Center for Devices and Radiological Health demands extensive clinical evidence for novel wireless architectures without established predicates, extending clearance timelines.
- Cart-based system substitution:Academic medical centers with sunk capital in premium radiology suites delay handheld adoption for cardiac and obstetric applications requiring extended imaging sessions.
Strategic Opportunities
- Outpatient clinic penetration in Germany:Specialist physician practices outside hospital networks represent underpenetrated demand for single-probe systems with AI-assisted measurement packages.
- Cloud-based image archiving convergence:Integration of edge computing with subscription-based PACS workflows creates recurring revenue streams independent of hardware refresh cycles.
- Telemedicine channel expansion:Direct-to-clinic distribution models are displacing traditional radiology equipment vendor relationships in rural United States markets.
Industry Challenges
- Operator training standardization:Emergency medicine residency programs lack harmonized competency frameworks for POCUS credentialing, creating deployment friction in community hospital settings.
- Legacy PACS integration complexity:Handheld devices require middleware development for DICOM compatibility with entrenched hospital information systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point-Of-Care Ultrasound (Pocus) Device Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Portable Ultrasound, Desktop Systems, Software Solutions End User: Emergency Departments, Clinics, Field Hospitals, Private Practices Technology: 2D Imaging, 3D Imaging, Doppler Imaging, Wireless Technology Application: Cardiac Assessment, Abdominal Examination, Obstetrics, Musculoskeletal Evaluation |
| Companies Covered | GE HealthCare, Koninklijke Philips N.V., Siemens Healthineers, Canon Medical Systems Corporation, Fujifilm Sonosite, Butterfly Network, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Esaote S.p.A., Samsung Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point-Of-Care Ultrasound (Pocus) Device Market Trends and Innovations
AI-assisted diagnostic algorithms and semiconductor-based probe miniaturization are compressing operator skill requirements while regulatory frameworks struggle to keep pace with wireless hardware evolution.
Capacitive micromachined ultrasound transducer technology is consolidating multiple imaging modalities into single-probe architectures. Emergency medicine departments in the United States are adopting these systems for rapid cardiac and abdominal assessment. The technology is consolidating what previously required three separate probes into handheld devices priced at fraction of cart-based alternatives.
EU MDR technical documentation demands are straining smaller European notified bodies, creating clearance backlogs for novel wireless devices. Manufacturers are redirecting regulatory submissions toward German and Dutch notified bodies with expanded capacity. Cardiac monitoring applications face the longest delays due to higher clinical evidence thresholds for Class IIa classification.
Hospital purchasing committees are unbundling after-sales service contracts from hardware procurement, negotiating cloud-based AI interpretation subscriptions separately. Community hospitals in Germany and the United States are driving this shift, preferring per-study pricing over capital-intensive enterprise agreements. Radiology department resistance to POCUS credentialing outside their oversight represents the primary organizational barrier to adoption.
Point-Of-Care Ultrasound (Pocus) Device Market Segmentation
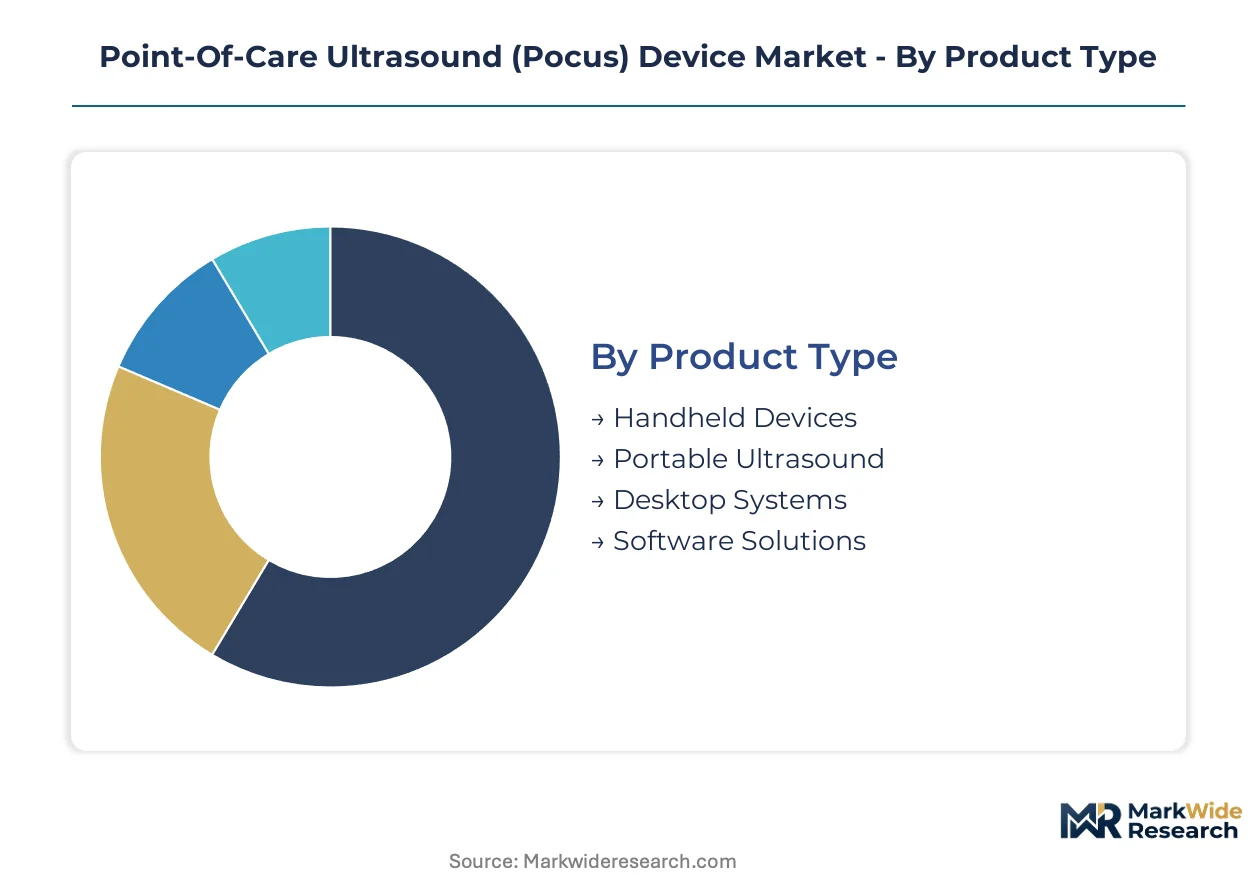
Point-of-care ultrasound segmentation reveals divergent capital requirements and deployment models across product architectures. Procurement committees weigh upfront hardware investment against recurring software subscriptions and training infrastructure. Understanding these trade-offs clarifies why certain configurations dominate specific clinical settings.
Product Type:
Capital intensity varies dramatically across physical form factors, with semiconductor manufacturing scale determining per-unit economics.
- Handheld Devices:CMUT-based single-probe architectures integrate multiple imaging modalities into pocket-sized units operating at 2-15 MHz. Emergency departments in the United States are standardizing these for bedside triage where radiology suite access creates treatment delays. Semiconductor fabrication at volume collapses marginal production costs below legacy piezoelectric alternatives.
- Portable Ultrasound:Cart-agnostic systems with detachable tablets balance imaging depth against mobility, typically deploying 3-5 interchangeable probes. County-level hospitals in China procure these under rural outreach mandates requiring equipment transport between satellite clinics. Battery chemistry and display panel costs constitute the primary capital components.
- Desktop Systems:Fixed installations with stabilized probe arms target extended cardiac and obstetric sessions.
- Software Solutions:Cloud-based AI interpretation and DICOM-compliant archiving generate recurring subscription revenue independent of hardware refresh cycles.
Desktop systems absorb the bulk of installed capacity in academic medical centers; handheld devices are expanding most quickly into community hospital networks.
End User:
Procurement authority and reimbursement pathways segment demand by organizational scale and clinical urgency.
- Emergency Departments:Level I trauma centers and freestanding urgent care networks in Germany and the United States deploy handheld systems for immediate triage without radiologist mediation. FDA 510(k) clearance timelines and EU MDR technical documentation shape vendor selection criteria.
- Clinics:Outpatient specialist practices outside hospital networks represent underpenetrated demand for single-probe systems with AI-assisted measurement packages.
- Field Hospitals:Military and disaster response configurations prioritize ruggedized portability and extended battery operation.
- Private Practices:Solo and small-group physician offices in Germany favor per-study pricing models over capital-intensive enterprise agreements.
Emergency departments command the highest procurement volumes; clinics are gaining share fastest as credentialing frameworks mature.
Technology:
Image processing sophistication determines hardware cost structures and operator training requirements.
- 2D Imaging:Conventional B-mode ultrasound remains the baseline capability across all product tiers.
- 3D Imaging:Volumetric reconstruction enables surface rendering for obstetric and musculoskeletal applications.
- Doppler Imaging:Color and spectral Doppler functionality adds hemodynamic assessment for cardiac and vascular evaluation.
- Wireless Technology:Bluetooth and Wi-Fi-enabled probe-to-tablet transmission eliminates cable constraints but triggers extended FDA predicate device equivalence reviews.
2D imaging retains the largest installed base; wireless technology faces the steepest regulatory clearance delays.
Application:
Clinical evidence thresholds and reimbursement codes segment demand by diagnostic complexity and procedural duration.
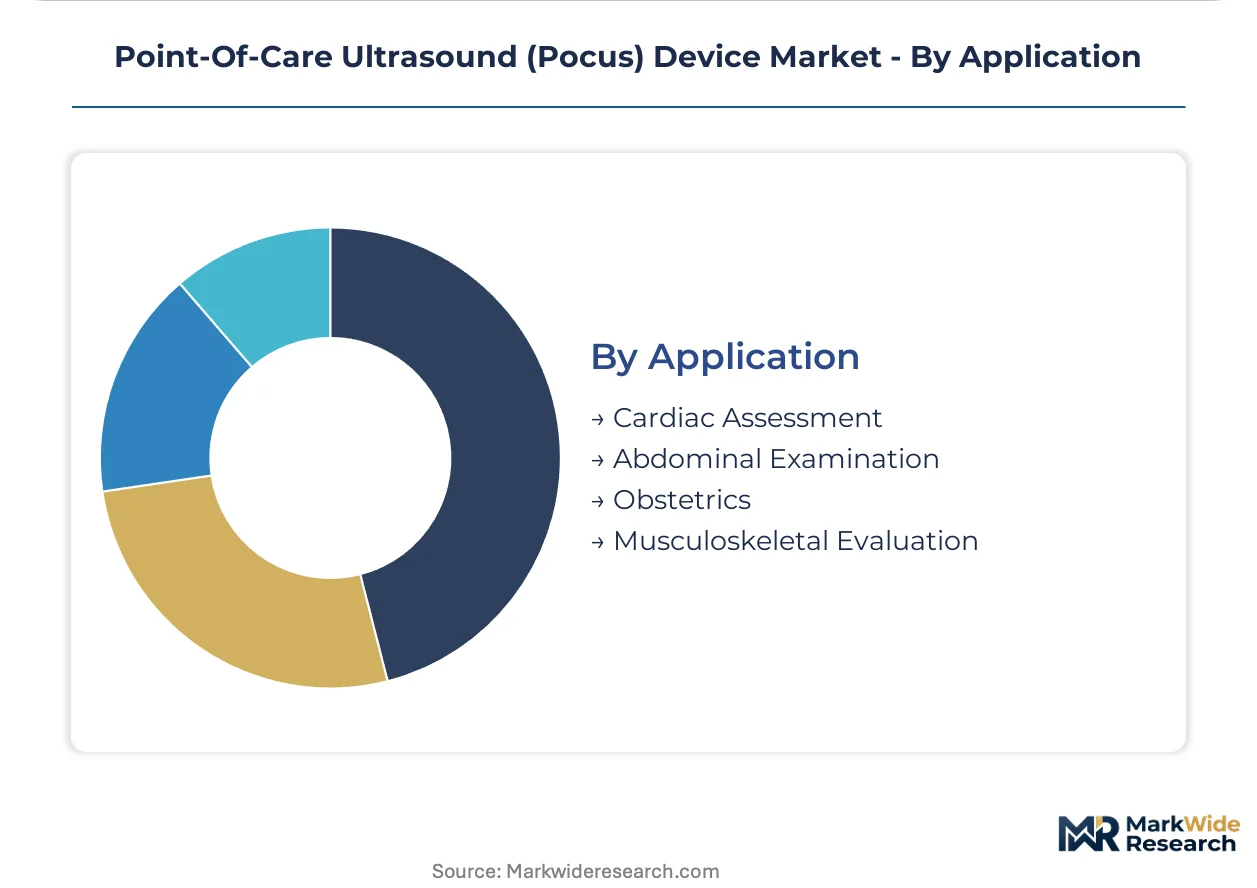
- Cardiac Assessment:Extended imaging sessions requiring probe stability and Doppler functionality favor desktop configurations in academic medical centers.
- Abdominal Examination:FAST protocols drive handheld adoption in emergency settings where rapid triage decisions determine patient disposition.
- Obstetrics:Fetal monitoring applications retain margin concentration in specialized practices requiring extended session capability.
- Musculoskeletal Evaluation:Sports medicine and rheumatology clinics deploy portable systems for guided injection procedures.
Abdominal examination generates the highest procedure volumes; musculoskeletal evaluation is climbing the fastest as outpatient clinic penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital decentralization policies and emergency department expansion concentrate procurement authority in the United States, Germany, and China, where rural outreach mandates and freestanding urgent care networks drive handheld system deployment.
United States
Emergency departments in Level I trauma centers and community hospitals deploy handheld systems for bedside triage without radiologist mediation. FDA 510(k) clearance pathways for wireless-enabled devices create competitive access bottlenecks that favor established predicate devices. The Southeast and Southwest regions host the fastest urgent care network expansion, with Texas and Florida leading freestanding clinic procurement.
Germany
Specialist physician practices outside hospital networks represent underpenetrated demand for single-probe systems with AI-assisted measurement packages. CE marking under EU MDR technical documentation accelerates market entry through notified bodies in Berlin and Munich. Bavaria and North Rhine-Westphalia concentrate outpatient clinic procurement, with Munich-based distributors expanding telemedicine channel partnerships.
China
County-level medical institutions accelerate portable imaging equipment procurement under hospital decentralization and rural outreach mandates. NMPA regulatory pathways prioritize domestic manufacturers for tier-2 and tier-3 hospital procurement. The Yangtze River Delta and Pearl River Delta clusters dominate semiconductor-based probe manufacturing, with Shanghai and Shenzhen anchoring CMUT fabrication scale.
Japan
Academic medical centers with sunk capital in premium radiology suites delay handheld adoption for cardiac applications requiring extended imaging sessions. PMDA technical documentation demands strain clearance timelines for novel wireless architectures. The Kanto region around Tokyo retains installed base concentration, while Osaka-based manufacturers develop integrated AI-assisted measurement packages for regional markets.
United Kingdom
NHS procurement frameworks prioritize per-study pricing models over capital-intensive enterprise agreements for community hospital networks. MHRA post-Brexit regulatory alignment with EU MDR creates transitional documentation requirements for wireless device submissions. London and the Southeast concentrate emergency department procurement, while Midlands-based urgent care networks expand handheld system standardization.
Point-Of-Care Ultrasound (Pocus) Device Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions in integrated imaging systems. The vendor base stratifies across three tiers: diversified medical technology conglomerates with installed base leverage, semiconductor-native disruptors collapsing probe manufacturing costs, and regional specialists serving price-sensitive procurement committees. Strategic archetypes include cross-selling incumbents leveraging enterprise purchasing agreements, single-probe architecture innovators, and AI-assisted measurement package developers. Dominant competitive moves encompass cloud-based subscription unbundling from hardware procurement and regulatory submission redirection toward high-capacity notified bodies.
Within the diversified conglomerate tier, GE HealthCare and Koninklijke Philips N.V. occupy positions shaped by installed base scale and enterprise purchasing agreement leverage. Siemens Healthineers anchors the European specialist vector through integrated AI-assisted measurement packages. Butterfly Network exemplifies the semiconductor-native disruptor archetype, with CMUT-based single-probe architectures collapsing cost barriers for outpatient clinic penetration. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. represents the Asia-Pacific scale-driven position, serving county-level hospital procurement under domestic regulatory preference frameworks.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Fujifilm Sonosite |
| Butterfly Network |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Esaote S.p.A. |
| Samsung Healthcare |
| Others |
Pricing and Supply Chain Analysis
Piezoelectric ceramic substrates from Japanese and German specialty suppliers cascade through probe manufacturing tiers into handheld devices priced for outpatient clinics versus cart-based systems anchoring premium hospital contracts. CMUT semiconductor fabrication at volume in Taiwan and China collapses marginal production costs below legacy crystal alternatives, forcing price compression through distribution channels serving community hospitals and urgent care networks.
Pricing Analysis
Volume shipments concentrate in handheld devices where semiconductor scale economics compress hardware margins, while desktop cardiac systems retain pricing power through extended session stability and Doppler functionality. Price differentiation separates FDA-cleared wireless architectures from CE-marked alternatives facing shorter EU MDR documentation timelines, with AI-assisted measurement subscriptions unbundling from hardware procurement. Pricing pressure stems from hospital purchasing committees negotiating per-study SaaS models over capital-intensive enterprise agreements. Community hospitals in Germany and the United States exhibit highest price sensitivity; academic medical centers with radiology suite sunk costs show lowest.
Supply Chain Analysis
FDA 510(k) predicate device equivalence and EU MDR technical documentation gate component sourcing, with notified body capacity in Germany and the Netherlands determining wireless probe market entry speed. Supply concentrates in Taiwan for CMUT semiconductor foundry services, Japan and Germany for piezoelectric ceramic substrates, and China for battery chemistry and display panel integration. Raw material dependencies include specialty ceramic substrates, lithium-ion cells, and high-frequency ASICs. Single-source vulnerability concentrates in Japanese ceramic suppliers exposed to input cost volatility. Distribution runs through radiology equipment vendor relationships in academic centers, telemedicine direct-to-clinic channels in rural United States markets, and Munich-based distributors expanding outpatient partnerships in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The point-of-care ultrasound market has become a vertical-integration race, with probe manufacturers pursuing backward control over CMUT semiconductor fabrication to escape ceramic substrate cost volatility and accelerate wireless clearance timelines.
For Market Incumbents: Anticipate semiconductor-native disruptors collapsing probe manufacturing costs by securing captive CMUT foundry capacity in Taiwan or the Yangtze River Delta before supply bottlenecks harden. Defend installed base leverage through unbundled cloud-based AI interpretation subscriptions that decouple recurring revenue from hardware refresh cycles, while redirecting regulatory submissions toward German and Dutch notified bodies with expanded MDR capacity to outpace clearance backlogs facing smaller competitors. For New Entrants and Emerging Players: Begin with outpatient specialist practices in Bavaria and North Rhine-Westphalia, where underpenetrated demand for single-probe systems with AI-assisted measurement packages escapes radiology department credentialing resistance. Target county-level medical institutions in China's Yangtze River Delta under rural outreach mandates prioritizing portable imaging procurement. Pursue direct-to-clinic distribution partnerships displacing traditional vendor relationships, with per-study pricing models that neutralize capital committee friction in community hospital settings. For Investors and Strategic Acquirers: FDA clearance timeline compression for novel wireless architectures without established predicates is the leading indicator that regulatory arbitrage strategies will separate winners from stranded hardware investments. Long-term viability over the next decade hinges on software recurring revenue attachment rates independent of probe refresh cycles, favoring targets with integrated AI-assisted measurement development and DICOM-compliant cloud archiving infrastructure. Watch for German notified body capacity expansion as the signal that EU MDR bottlenecks are easing for Class IIa cardiac submissions.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Optimization | Redirection toward German and Dutch notified bodies accelerates wireless device market entry against MDR backlogs. |
| CMUT Semiconductor Scale-Up | Captive foundry capacity in Taiwan or China collapses probe manufacturing costs below piezoelectric alternatives. |
| Cloud-Based AI Subscription Unbundling | Per-study pricing models decouple recurring revenue from hardware procurement cycles in community hospitals. |
| Hospital System Partnership | Enterprise purchasing agreements with urgent care networks lock out handheld competitors through cross-selling leverage. |
| Reimbursement Strategy Development | Payor acceptance for bedside ultrasound procedures determines capital committee prioritization against competing modalities. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract records, complemented by interviews with emergency medicine department heads, biomedical engineers, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary validation drew from CMS Medicare reimbursement data, hospital capital expenditure disclosures, and semiconductor foundry capacity reports. Bottom-up shipment modeling by product tier and top-down spending analysis by end-user segment were triangulated against clinician adoption surveys.
Cross-reference between historical volume trajectories and panel input from purchasing committee directors grounded the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-user organizational scale, imaging technology tier, and clinical application complexity, with regional regulatory pathway differentiation as an additional healthcare-specific dimension. CAGRs were derived from iterative convergence between unit economics modeling and reimbursement code expansion scenarios, incorporating CMUT manufacturing scale curves and wireless clearance timeline distributions as industry-specific forecast inputs.
Regulatory pathway delays at FDA and smaller European notified bodies, reimbursement code non-coverage decisions by major payors, and ceramic substrate supply disruptions are the dominant revision risks that would warrant forecast adjustment. Forecasts reflect assumptions about clinician credentialing framework maturation and cloud-based AI interpretation attach rates. A model refresh is warranted upon material change in FDA predicate device equivalence precedent for wireless architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Speech Generating Devices Market
Medical Devices
Internal Trauma Fixation Device Market
Medical Devices
Brazil Angioplasty Devices Market
Medical Devices
US Pulse Oximeters Market
Medical Devices
Endoprosthesis Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
Active Humidifier Devices Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
Intraoral Scanners Market
Medical Devices
Functional Electrical Stimulation Market
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Ear Tube Devices Market
Medical Devices
Facial Pumps Market
Medical Devices
At-Home Laser Hair Removal Devices Market