
 Pelvic Floor Diagnostics Market | 2026-2036
Pelvic Floor Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Pelvic Floor Diagnostics Market Analytics
Aftermarket service revenue is reconfiguring profitability structures across the pelvic floor diagnostics sector. Laborie Medical Technologies leverages its installed base of urodynamics systems to sustain recurring calibration and software update income. Medtronic plc anchors its position through deep channel control in ambulatory surgery centers. The Prometheus Group differentiates via specialized training programs that lock in clinician loyalty.
Pelvic floor diagnostics encompasses instrumental evaluation of urethral, vaginal, and anal sphincter function through pressure-flow studies, electromyographic signal acquisition, and real-time ultrasound imaging to quantify structural support defects and neuromuscular coordination. These assessments guide surgical planning, biofeedback therapy titration, and post-intervention recovery monitoring in urogynecology and colorectal practice. Ultrasound-based modalities occupy the largest margin pool due to capital equipment bundling and consumable probe requirements, while AI Analytics within the technology dimension represents the fastest-expanding segment as machine learning classifiers automate pressure-trace interpretation. Electromyography remains mature with stable replacement demand, though wireless monitoring integration is displacing tethered laboratory configurations.
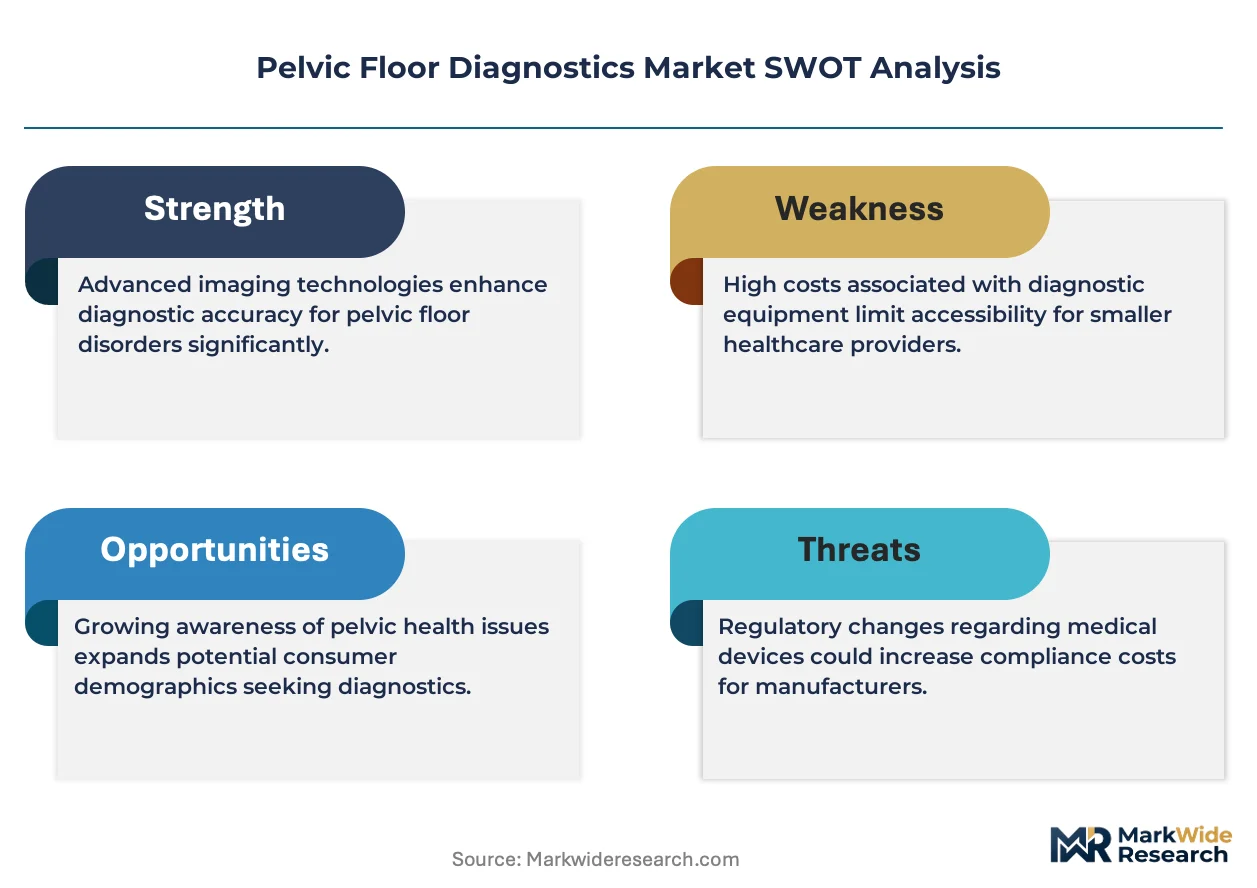
FDA premarket notification pathways shape device commercialization timelines for US manufacturers, while the EU Medical Device Regulation imposes clinical evidence requirements that filter market access for smaller developers. Japan's PMDA enforces Japan Industrial Standards compatibility for electromyographic hardware, creating localization barriers for imported systems. Stakeholders must monitor reimbursement coding decisions for remote pelvic floor biofeedback as telehealth parity policies evolve across Medicare and major private payers.
Market Dynamics
AI-enabled pressure-trace interpretation is compressing diagnostic timelines and forcing recalibration of traditional urodynamics workflows across hospital outpatient departments and ambulatory surgery centers.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:The FDA's premarket notification process for AI-integrated urodynamic systems accelerates device commercialization, reducing time-to-market for novel diagnostic platforms in the United States.
- Telehealth Parity Expansion:Medicare reimbursement alignment for remote pelvic floor biofeedback sessions unlocks procedural volume growth in fee-for-service and managed care environments.
- Electromyographic Hardware Miniaturization:Wireless signal acquisition modules replace tethered laboratory configurations, enabling point-of-care deployment in urogynecology clinics.
Market Restraints
- EU MDR Clinical Evidence Burden:The European Union's Medical Device Regulation imposes stringent clinical data requirements that filter market access for smaller developers lacking dedicated regulatory affairs infrastructure.
- Japan Industrial Standards Localization:PMDA enforcement of JIS compatibility for electromyographic hardware creates technical barriers and certification delays for imported systems.
- Capital Equipment Replacement Cycles:Extended depreciation schedules for ultrasound-based diagnostic platforms in hospital systems suppress near-term upgrade demand for high-margin probe technologies.
Strategic Opportunities
- Underpenetrated Ambulatory Surgery Centers:United States ASC networks represent expansion white space for non-invasive assessment tools as site-of-care migration accelerates procedural volume capture.
- AI-Ultrasound Convergence:Machine learning classifiers integrated with real-time imaging systems automate structural support defect quantification, reducing specialist interpretation bottlenecks.
- Germany's Diagnosis-Related Group Realignment:Bundled reimbursement reforms for pelvic floor dysfunction create incentive alignment for comprehensive diagnostic workups in hospital outpatient settings.
Industry Challenges
- Urogynecology Specialist Shortage:Limited fellowship-trained clinicians constrains throughput capacity for complex pressure-flow studies and electromyographic interpretation.
- Legacy System Integration Friction:Tethered laboratory configurations resist seamless data exchange with electronic health record platforms, complicating workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pelvic Floor Diagnostics Market |
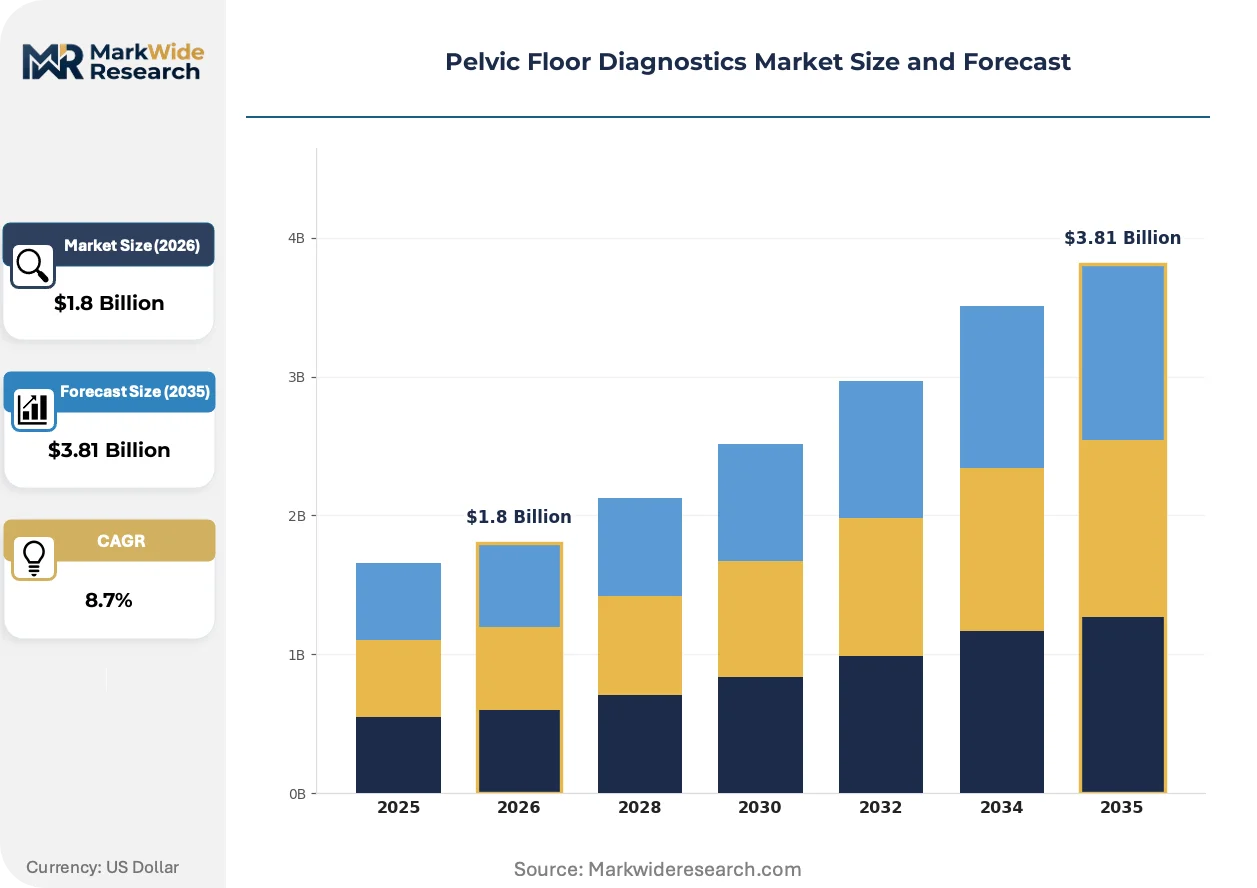
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, Electromyography, Pressure Sensors, Biofeedback Devices Application: Incontinence Assessment, Pelvic Organ Prolapse, Post-Surgery Recovery, Pain Management End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Technology: Wireless Monitoring, Wearable Devices, AI Analytics, Telehealth Solutions |
| Companies Covered | Laborie Medical Technologies, Medtronic plc, The Prometheus Group, Verathon Inc., Itronix Medical Ltd., Medspira LLC, Diversatek Healthcare, AdventHealth Medical Group, Alacer Biomedica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pelvic Floor Diagnostics Market Evolving Landscape
Diagnostic modality convergence and algorithmic automation are restructuring competitive advantage around software-enabled service models rather than standalone hardware sales.
Wireless electromyographic monitoring systems capture neuromuscular coordination data through portable surface electrode arrays, eliminating fixed laboratory infrastructure requirements. Hospital outpatient departments and ambulatory surgery centers in the United States and Germany are accelerating procurement of these untethered platforms. This mobility is rendering obsolete the capital-intensive, room-based urodynamics configurations that previously anchored diagnostic service lines.
Japan's PMDA has tightened enforcement of electromagnetic compatibility standards under revised medical device quality system regulations, extending certification timelines for foreign manufacturers. Domestic distributors now absorb pre-market testing costs to maintain supplier relationships. Electromyographic hardware imports face the steepest compliance burden, prompting some developers to pursue local manufacturing partnerships.
Aftermarket service unbundling is separating calibration contracts from initial capital sales, with hospital procurement officers negotiating standalone software update agreements. This shift pressures traditional equipment vendors to restructure recurring revenue models. The transformation is most visible in United States integrated delivery networks, where value analysis committees now scrutinize total cost-of-ownership rather than upfront capital expenditure alone.
Pelvic Floor Diagnostics Market Segmentation
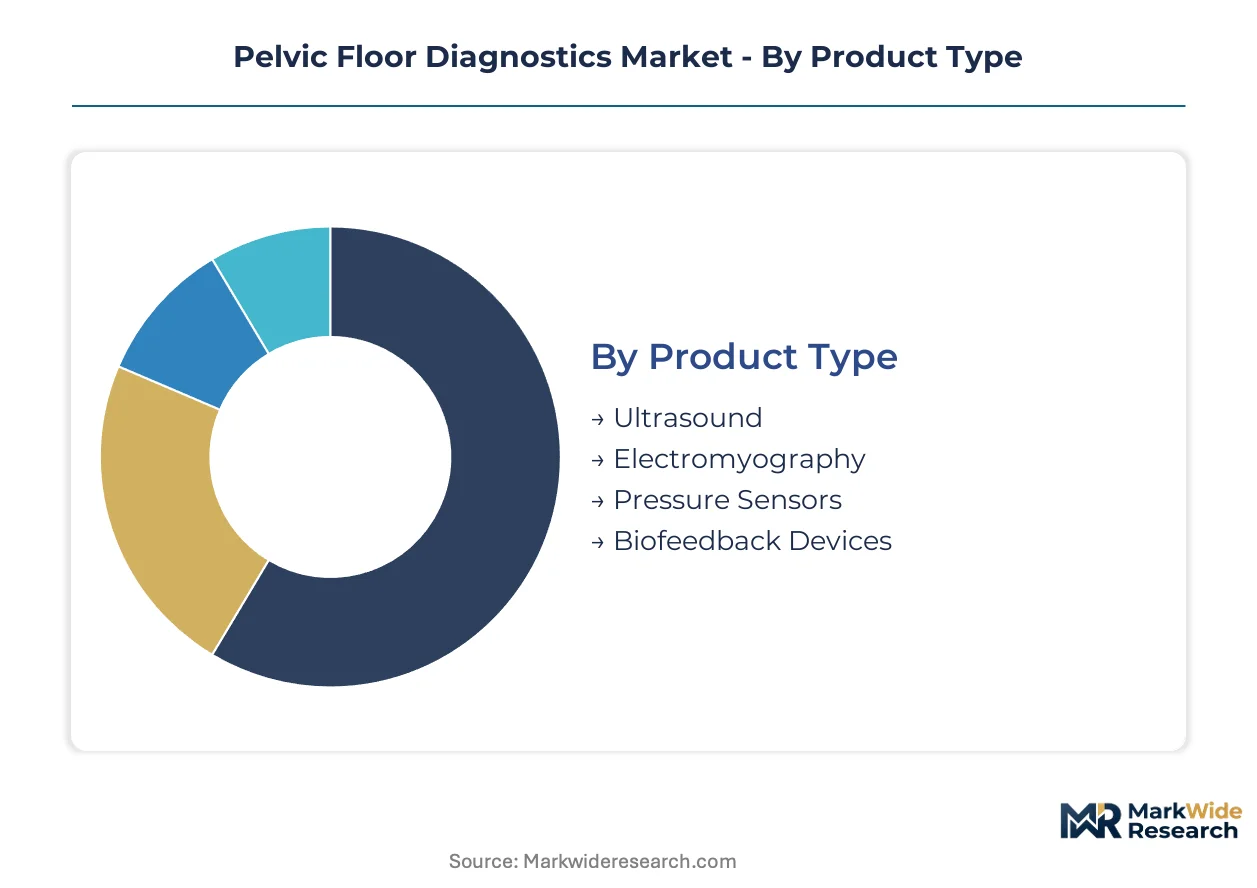
Pelvic floor diagnostics segmentation reveals distinct margin profiles and procurement dynamics across hardware modalities, clinical applications, and technology integration levels. Understanding these divisions exposes where capital concentrates versus where software-enabled services are displacing traditional equipment sales.
Product Type:
Cost tier differentiation separates capital-intensive imaging platforms from disposable-heavy physiological monitoring tools.
- Ultrasound:Real-time imaging systems quantify structural support defects through transperineal and endovaginal probe configurations. United States hospital outpatient departments bundle capital equipment with high-margin disposable probe requirements, though extended depreciation schedules suppress near-term replacement demand.
- Electromyography:Surface and needle electrode arrays capture neuromuscular coordination signals from urethral, anal, and vaginal sphincter complexes. Wireless signal acquisition modules are displacing tethered laboratory configurations in Germany's ambulatory urogynecology clinics.
- Pressure Sensors:Catheter-mounted transducers measure urethral closure pressure and detrusor contractility during voiding studies.
- Biofeedback Devices:Visual and auditory feedback systems train patients in voluntary pelvic muscle control.
Ultrasound commands the established base. The steepest expansion runs through biofeedback devices.
Application:
Clinical volume concentrates where reimbursement coding aligns with procedural complexity and outcomes documentation requirements.
- Incontinence Assessment:Urodynamic pressure-flow studies and cough stress tests diagnose stress, urge, and mixed urinary incontinence subtypes. United States Medicare reimbursement for complex urodynamics sustains hospital outpatient procedural volumes despite specialist throughput constraints.
- Pelvic Organ Prolapse:Quantification of cystocele, rectocele, and uterine descent guides surgical planning for mesh and native tissue repair. Japan's aging demographics and PMDA device registration requirements shape market access for advanced staging systems.
- Post-Surgery Recovery:Functional outcome monitoring tracks continence restoration and mesh complication resolution.
- Pain Management:Myofascial and neuropathic pelvic pain evaluation directs trigger point injection and neuromodulation therapy.
Incontinence assessment anchors current procedural volume. Pelvic organ prolapse is gaining share fastest as surgical mesh litigation resolution restores intervention confidence.
End User:
Site-of-care migration patterns redistribute diagnostic volume between institutional settings and distributed care locations.
- Hospitals:Integrated delivery networks maintain urodynamics laboratories with full catheterization and fluoroscopic capabilities. Germany's diagnosis-related group realignment creates incentive alignment for comprehensive diagnostic workups in hospital outpatient departments.
- Clinics:Urogynecology and colorectal specialty practices deploy portable ultrasound and wireless electromyography for point-of-care assessment. United States ambulatory surgery center networks represent expansion white space as procedural migration accelerates.
- Rehabilitation Centers:Pelvic floor physical therapy practices utilize biofeedback systems for neuromuscular retraining.
- Home Care:Remote monitoring platforms enable patient-directed pelvic muscle exercise programs.
Hospitals retain the highest-acuity caseload. Home care is climbing the fastest as telehealth parity policies mature.
Technology:
Integration depth separates legacy hardware vendors from software-enabled service providers across the diagnostic value chain.
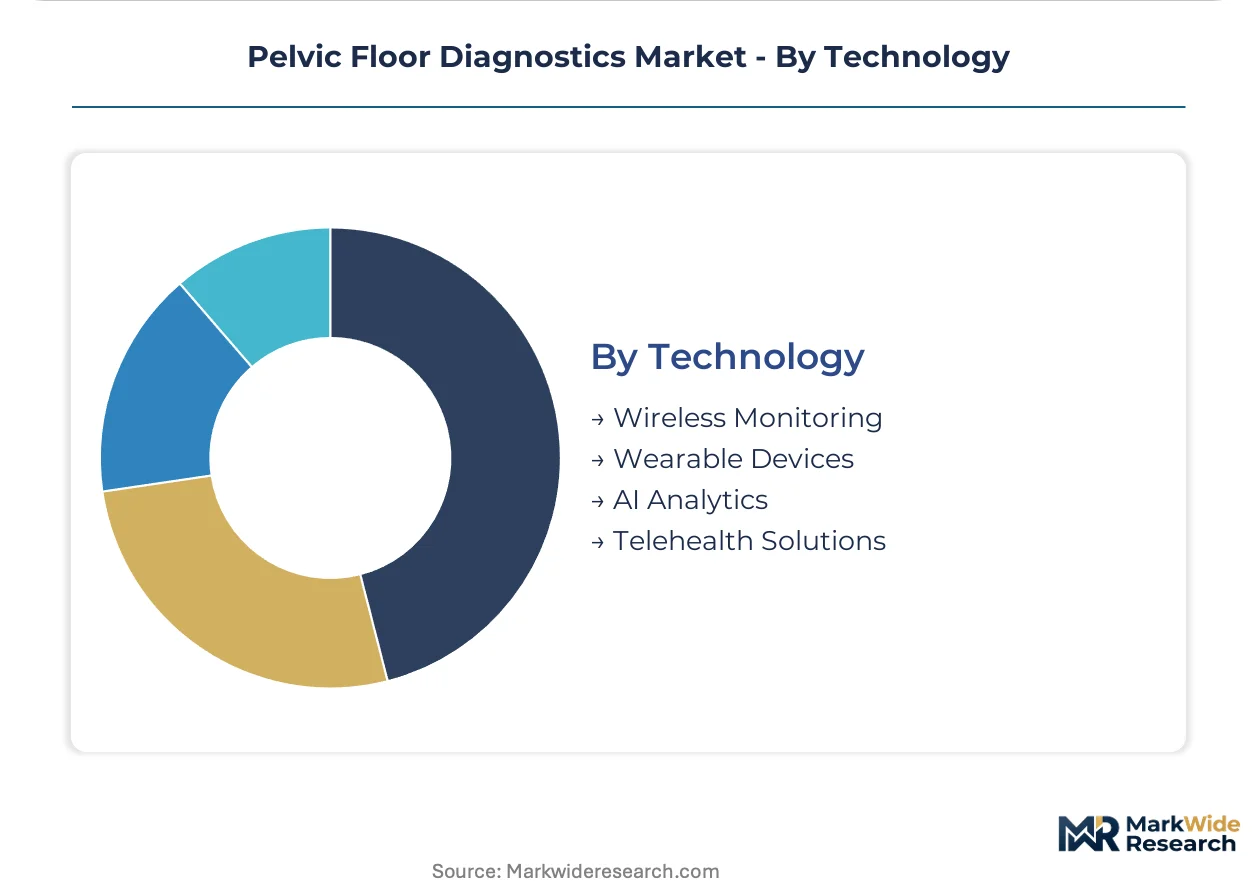
- AI Analytics:Machine learning classifiers automate pressure-trace interpretation and structural defect quantification, reducing specialist interpretation bottlenecks. FDA 510(k) pathway streamlining accelerates commercialization timelines for algorithm-integrated platforms in the United States.
- Wireless Monitoring:Bluetooth and proprietary radio protocols transmit physiological data without fixed laboratory infrastructure. Hospital procurement officers in United States integrated delivery networks negotiate standalone calibration and software update agreements separate from capital sales.
- Wearable Devices:Surface electrode arrays and pressure sensors enable continuous ambulatory monitoring.
- Telehealth Solutions:Remote biofeedback platforms connect patients with pelvic floor therapists through synchronous video and asynchronous data review.
Wireless monitoring commands the installed base. AI analytics shows the steepest expansion trajectory as diagnostic automation compresses interpretation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic modality preferences diverge sharply across major markets. The United States prioritizes AI-integrated urodynamics workflows, Germany emphasizes outpatient reimbursement efficiency, and Japan maintains stringent hardware certification regimes that favor localized production partnerships.
United States
Medicare reimbursement alignment for complex urodynamics sustains hospital outpatient procedural volumes despite specialist throughput constraints. FDA 510(k) pathway streamlining accelerates commercialization timelines for algorithm-integrated diagnostic platforms. Boston's medical device corridor hosts concentrated development activity for wireless electromyographic monitoring systems.
Germany
Diagnosis-related group realignment creates incentive alignment for comprehensive diagnostic workups in hospital outpatient departments. EU MDR clinical evidence requirements filter market access for smaller developers lacking dedicated regulatory affairs infrastructure. The Rhine-Ruhr metropolitan region anchors procurement networks for portable ultrasound and biofeedback systems.
Japan
Aging demographics and PMDA device registration requirements shape market access for advanced pelvic organ prolapse staging systems. METI enforcement of JIS compatibility for electromyographic hardware creates technical barriers and certification delays for imported systems. Tokyo-Osaka medical device clusters absorb pre-market testing costs through domestic distributor partnerships.
United Kingdom
NHS England procurement frameworks prioritize total cost-of-ownership calculations over upfront capital expenditure for diagnostic equipment. MHRA post-Brexit regulatory autonomy enables divergence from EU MDR timelines for novel device approvals. London's integrated care systems pilot remote pelvic floor biofeedback platforms under telehealth parity expansion programs.
South Korea
MFDS accelerated review pathways for AI-enabled medical devices attract foreign manufacturers seeking faster Asian market entry. National health insurance reimbursement for urogynecology procedures expands addressable patient populations beyond private clinic networks. Seoul's digital health ecosystem incubates wearable pressure sensor startups targeting home care monitoring applications.
Pelvic Floor Diagnostics Market Competitive Landscape
Capability concentration sits with specialized diagnostic technology developers; scale advantage sits with diversified medical device conglomerates. The market structure tiers across three distinct strata: integrated multinationals with deep channel control, mid-cap specialists leveraging installed base economics, and emerging technology vendors pursuing AI-software differentiation. Dominant competitive moves include aftermarket service unbundling to capture recurring calibration revenue and strategic partnerships with ambulatory surgery center networks to secure procedural volume capture.
Within the integrated multinational tier, Medtronic plc exemplifies scale-driven positioning through ambulatory surgery center channel dominance. Laborie Medical Technologies represents the installed-base archetype, leveraging urodynamics system deployments to sustain recurring service income. The Prometheus Group occupies the specialist training niche, differentiating through clinician education programs that reinforce platform loyalty.
| Leading Market Players |
|---|
| Laborie Medical Technologies |
| Medtronic plc |
| The Prometheus Group |
| Verathon Inc. |
| Itronix Medical Ltd. |
| Medspira LLC |
| Diversatek Healthcare |
| AdventHealth Medical Group |
| Alacer Biomedica |
| Others |
Value Network & Pricing Analysis
German sensor manufacturers concentrate supply of piezoelectric pressure transducers for urodynamic catheter systems, anchoring margin capture in downstream ultrasound probe assembly and AI-integrated software bundles. This upstream concentration shapes how procurement officers negotiate total cost-of-ownership across hospital integrated delivery networks.
Pricing Analysis
Long-term calibration service contracts dominate procurement structures, with United States hospital systems locking in multi-year aftermarket agreements separate from initial capital equipment sales. Price differentiation hinges on FDA 510(k) clearance tier and bundled software update frequency. Cost compression in standard electromyography hardware intensifies as wireless monitoring platforms commoditize signal acquisition modules. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize premium-tier AI analytics capabilities regardless of unit cost.
Supply Chain Analysis
Semiconductor feedstock for signal processing chips draws from Taiwan, South Korea, and Japan, with specialized analog-to-digital converters sourced from German precision electronics suppliers. Medical-grade silicone for catheter construction and lithium-ion cells for wireless electrode arrays represent critical component dependencies. Single-source vulnerability concentrates in advanced ultrasound transducer ceramics, where Japanese Industrial Standards certification creates supplier lock-in. Distribution runs through domestic distributor partnerships in Japan and direct hospital contracting in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment and installed-base switching costs protect incumbent positions against technology disruption.
For Market Incumbents: Build switching-cost moats through deep electronic health record integration and proprietary data formats that resist migration. Laborie Medical Technologies exemplifies this through urodynamics system deployments that anchor recurring calibration revenue. Threats from AI-native entrants with cloud-first architectures demand defensive certification investment in FDA 510(k) pathway streamlining. Vertical integration into wireless sensor manufacturing secures component supply against Taiwan semiconductor volatility. For New Entrants and Emerging Players: Establish a beachhead in ambulatory surgery center networks where incumbent presence remains thin and procurement flexibility runs higher. Remote pelvic floor biofeedback platforms represent the most penetrable segment as telehealth parity policies mature across Medicare and private payers. Home care monitoring applications offer secondary expansion terrain. A software-first go-to-market angle—selling AI analytics modules compatible with existing ultrasound hardware—sidesteps capital-intensive equipment manufacturing barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed urogynecology training platforms and wireless monitoring specialists lacking global regulatory infrastructure. Long-term viability centers on recurring revenue share and reimbursement code capture rather than hardware shipment volume. The signal to watch is CMS reimbursement decisions for remote biofeedback CPT codes, which would validate telehealth business models and trigger valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Integrated Urodynamics Platform | FDA 510(k) pathway streamlining accelerates commercialization timelines for algorithm-integrated diagnostic systems. |
| Wireless EMG Hardware Miniaturization | Bluetooth-enabled surface electrode arrays displace tethered laboratory configurations in ambulatory settings. |
| Hospital System Partnership | Integrated delivery network contracts secure procedural volume capture and lock in aftermarket service revenue. |
| Reimbursement Strategy Development | Medicare coding alignment for remote biofeedback unlocks addressable patient populations beyond clinic walls. |
| CE Marking Pathway Investment | EU MDR clinical evidence requirements filter market access for developers lacking regulatory infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from urogynecology clinicians, hospital biomedical engineers, GPO contracts managers, and regulatory affairs specialists at device manufacturers, then refined through secondary validation against FDA 510(k) filings, CMS reimbursement databases, hospital procurement records, and EU MDR technical documentation. Bottom-up modeling of equipment shipments and procedure volumes triangulated against top-down market sizing from capital expenditure trends.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation across product type, application, end user, and technology integration level. CAGRs derived from fitted growth curves applied to installed base expansion and replacement cycle timing. Forecast inputs incorporated PMDA certification timelines for Japanese market entry and Germany's diagnosis-related group realignment impacts on outpatient procedural volumes.
Stress conditions across FDA regulatory delays, Medicare reimbursement reversals, and Taiwan semiconductor supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about telehealth parity policy maturation and AI diagnostic automation adoption curves. Cross-checking against hospital capital expenditure surveys and ambulatory surgery center procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
Companion Diagnostics Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market
Diagnostic Devices
Immunology-Oncology ELISA Kits Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
AI Portable Chest X-ray Triage Device Market
Diagnostic Devices
Global DNA Test Kit Market
Diagnostic Devices
Automated Visual Field Analyzer Market
Diagnostic Devices
Europe Breath Analyzer Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Animal Pregnancy Test Kits Market