
 External Pacemakers Market | 2026-2036
External Pacemakers Market Size, Share, and Industry Trends Forecast 2026-2036
External Pacemakers Market Foresight
Market Context
Hospital procurement is bifurcating as ambulatory surgical centers gain share in external pacemaker purchasing. Medtronic leverages its transvenous technology portfolio to sustain dominance in acute care settings. Boston Scientific Corporation anchors its position through electrophysiology specialization, while Abbott differentiates via wireless monitoring integration across cardiology clinics.
Technical Definition and Segment Structure
An external pacemaker is a battery-powered pulse generator connected to the heart through temporary leads, delivering electrical impulses at rates between 30 and 180 beats per minute to manage bradyarrhythmias, tachycardias, and post-surgical conduction disturbances. Dual chamber pacemakers command premium positioning due to atrioventricular synchrony benefits, while transcutaneous technology segments face margin compression from commoditized emergency applications. Bluetooth-enabled devices represent the fastest-expanding technology category as remote patient monitoring protocols expand into home care settings.
Regulatory Frame and Outlook
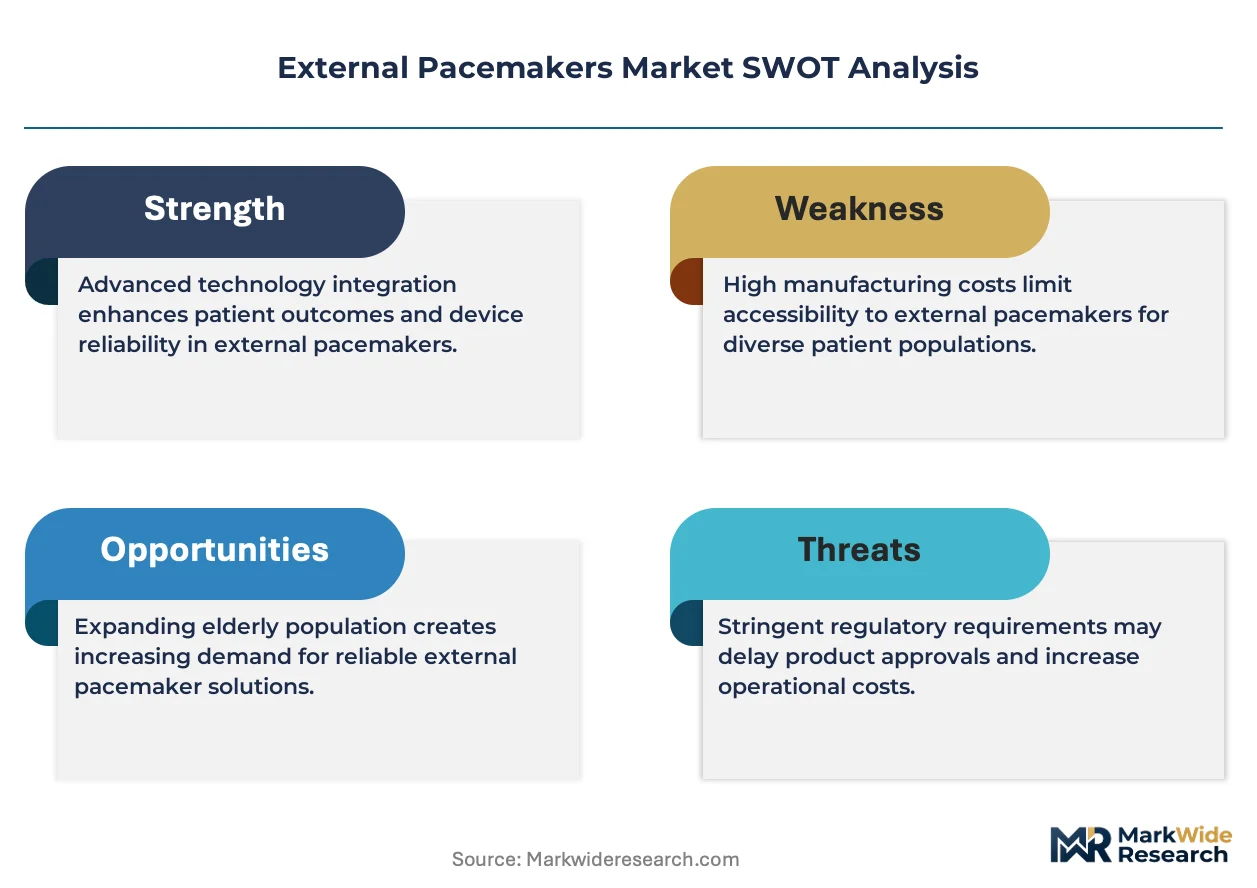
FDA premarket notification requirements, EU MDR technical documentation mandates, and IEC 60601-2-31 electromagnetic compatibility standards collectively elevate barriers for new entrants while accelerating wireless safety validation cycles. Japan's PMDA and China's NMPA impose additional clinical testing protocols for temporary pacing systems. Stakeholders must monitor evolving cybersecurity guidance for connected cardiac devices as regulatory bodies integrate software lifecycle requirements into hardware clearance pathways.
Market Dynamics
Bluetooth-enabled wireless monitoring is fragmenting traditional bedside pacing workflows as FDA and EU MDR electromagnetic compatibility standards force hardware redesigns toward connected architectures. This technology shift simultaneously opens remote patient monitoring revenue streams while compressing margins on conventional transcutaneous emergency units.
Growth Catalysts
- EU MDR technical documentation mandates:Stricter electromagnetic compatibility validation cycles are accelerating manufacturer investment in wireless safety testing infrastructure. Device makers are prioritizing Bluetooth Low Energy integration to preempt compliance gaps.
- Ambulatory surgical centers:These facilities are expanding temporary pacemaker procurement for same-day cardiac procedures. Their purchasing volume is reshaping distribution channels away from hospital-centric supply chains.
- Home care settings:Remote patient monitoring protocols are extending external pacemaker use beyond acute hospital environments. This shift creates recurring revenue opportunities through subscription-based telemetry services.
Market Restraints
- Silver and palladium price volatility:Temporary pacing leads rely on these conductive metals for electrode fabrication. Input cost swings compress gross margins on single-use disposable components.
- Transcutaneous technology commoditization:Emergency external pacing units face margin erosion from undifferentiated competitors. Price competition intensifies in ambulance and emergency department procurement.
- IEC 60601-2-31 electromagnetic compatibility:This standard elevates testing burdens for new entrants. Smaller manufacturers struggle to absorb validation costs for wireless-enabled devices.
Strategic Opportunities
- Japan's aging demographic:PMDA clinical testing requirements, once cleared, open access to a concentrated cardiac intervention market. Local partnership strategies accelerate regulatory navigation.
- Bluetooth-5G convergence:Integration of low-energy wireless with cellular backhaul enables real-time cloud-based arrhythmia analytics. This hybrid architecture supports predictive intervention protocols.
- China's NMPA pathway harmonization:Streamlined technical documentation for temporary pacing systems reduces time-to-market for compliant manufacturers. Early entrants capture cardiology clinic expansion in tier-2 cities.
Industry Challenges
- Cybersecurity validation timelines:FDA software lifecycle requirements for connected cardiac devices extend premarket notification cycles. Engineering teams must demonstrate threat modeling and patch management protocols.
- Electrophysiologist training gaps:Wireless monitoring systems demand competency in telemetry interpretation and remote troubleshooting. Academic medical centers struggle to integrate these skills into fellowship curricula.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | External Pacemakers Market |
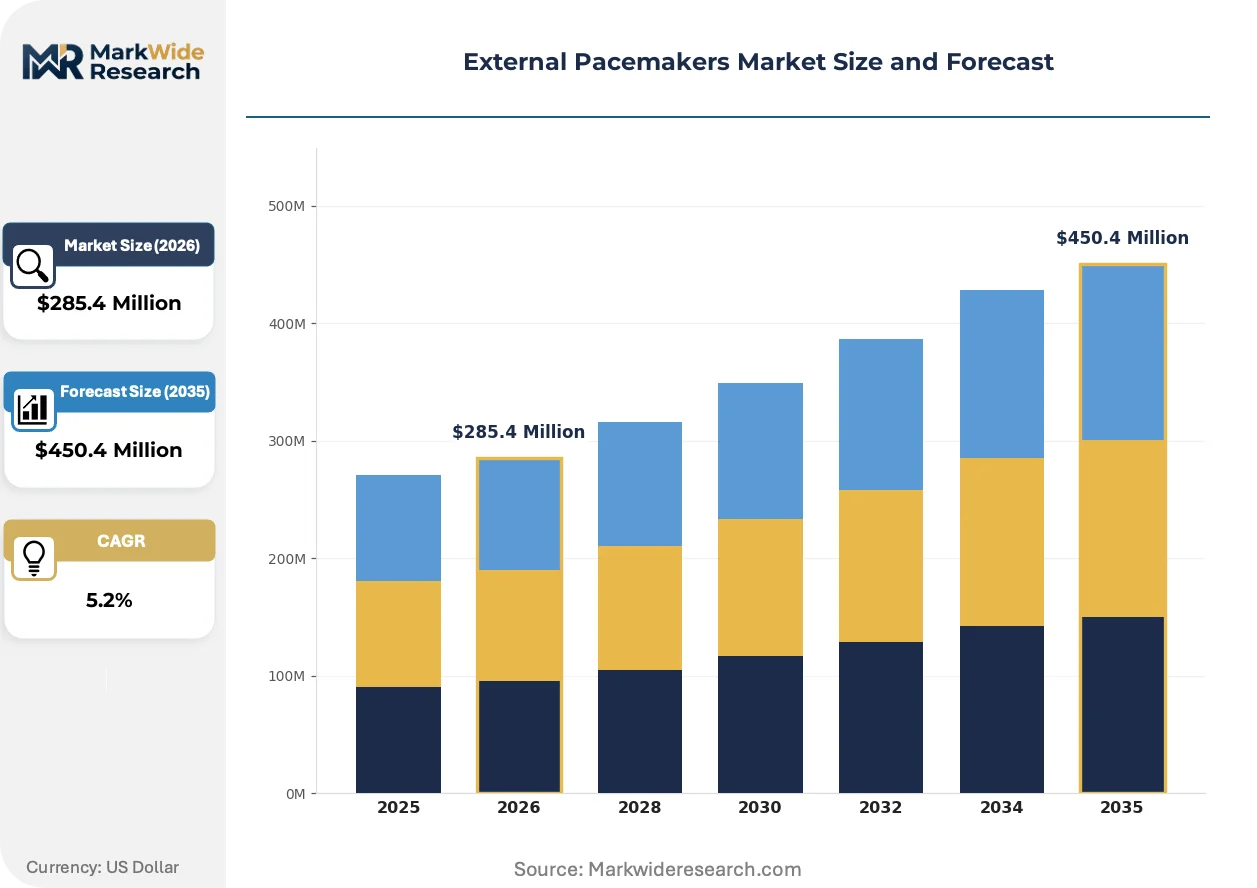
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $450.4 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temporary Pacemaker, External Demand Pacemaker, External Fixed Rate Pacemaker, Dual Chamber Pacemaker End User: Hospitals, Ambulatory Surgical Centers, Cardiology Clinics, Home Care Settings Application: Acute Cardiac Conditions, Electrophysiological Studies, Cardiac Surgery, Heart Failure Management Technology: Transvenous Technology, Transcutaneous Technology, Bluetooth-Enabled Devices, Wireless Monitoring Systems |
| Companies Covered | BIOTRONIK, Boston Scientific Corporation, Medtronic, OSCOR Inc., Shree Pacetronix, ZOLL Medical, Osypka Medical, MicroPort Scientific Corporation, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
External Pacemakers Market Shifts & Advancements
Wireless connectivity architectures are displacing tethered bedside systems across acute and post-acute care environments. This transformation is compressing traditional equipment refresh cycles while opening subscription-based revenue models that decouple hardware from service monetization.
Multi-parameter sensing is fragmenting the standalone external pacemaker category. Next-generation devices integrate invasive blood pressure, pulse oximetry, and respiratory rate monitoring alongside pacing functionality. Cardiac catheterization laboratories in Germany and Japan are piloting these consolidated platforms to reduce cable clutter and alarm fatigue. The structural consequence is margin compression for single-function competitors unable to bundle sensing modalities.
EU MDR post-market surveillance requirements are reshaping manufacturer liability exposure. Manufacturers must now maintain systematic procedures for collecting and reviewing experience gained from devices in production, including mandatory periodic safety update reports. Dual chamber pacemaker portfolios face heightened documentation burdens given their complexity class, pushing some suppliers toward simplified single-chamber configurations for European markets.
Hospital procurement committees are consolidating vendor relationships through capital equipment standardization programs. Cardiology departments in the United States increasingly mandate single-source contracts for temporary pacing systems to streamline biomedical engineering training and spare parts inventory. This concentration dynamic favors incumbents with broad electrophysiology portfolios over specialized external pacemaker suppliers, particularly in integrated delivery networks spanning multiple facilities.
External Pacemakers Market Segmentation
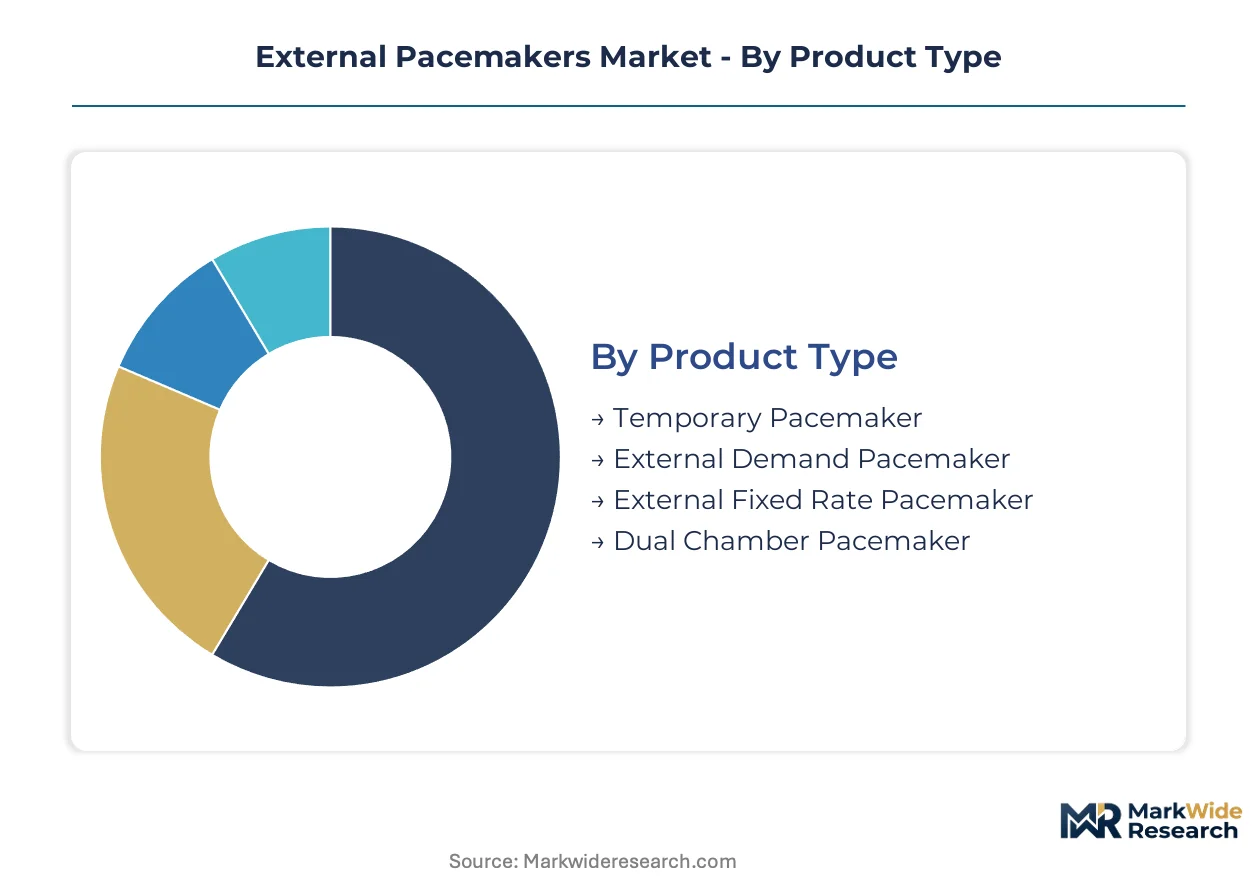
External pacemaker segmentation reveals distinct channel preferences across acute care versus post-acute environments. Procurement patterns diverge sharply between hospital capital equipment committees and ambulatory surgical center disposable purchasing workflows.
Product Type:
Distribution channels bifurcate between capital-intensive dual chamber systems and disposable temporary units. Hospital procurement committees dominate dual chamber acquisitions through multi-year service contracts, while emergency departments source temporary pacemakers through group purchasing organizations.
- Dual Chamber Pacemaker:These devices synchronize atrial and ventricular pacing through separate lead channels. Demand concentrates in Germany and Japan where electrophysiology laboratories prioritize atrioventricular synchrony for hemodynamic optimization. Premium positioning reflects FDA premarket notification complexity and EU MDR technical documentation burdens for multi-chamber configurations.
- Temporary Pacemaker:Single-chamber devices deliver 30-180 bpm pulse generation through temporary transvenous leads. Cardiology clinics in the United States drive procurement volume for post-procedural monitoring and acute bradyarrhythmia management. Disposable lead economics favor high-turnover purchasing patterns distinct from capital equipment cycles.
- External Demand Pacemaker:Rate-responsive units adjust pacing based on patient activity sensors.
- External Fixed Rate Pacemaker:Constant-rate devices serve emergency stabilization protocols.
By volume, Temporary Pacemaker leads. By growth pace, Dual Chamber Pacemaker is ahead.
End User:
Customer type determines service model architecture, from hospital biomedical engineering support to home care telemetry subscriptions. Margin structures vary threefold across these environments.
- Hospitals:Integrated delivery networks consolidate temporary pacing procurement through standardized vendor contracts. Biomedical engineering training requirements and spare parts inventory economies favor single-source relationships with electrophysiology portfolio suppliers.
- Home Care Settings:Remote patient monitoring protocols extend external pacemaker use beyond acute facilities. Bluetooth-enabled telemetry creates recurring subscription revenue streams decoupled from hardware monetization.
- Ambulatory Surgical Centers:Same-day cardiac procedure volumes reshape distribution channels.
- Cardiology Clinics:Specialized facilities drive dual chamber adoption for electrophysiological intervention.
By installed base, Hospitals dominate. By expansion trajectory, Home Care Settings are climbing the fastest.
Application:
Clinical use case dictates device specification, from emergency transcutaneous delivery to precise electrophysiological mapping support.
- Acute Cardiac Conditions:Emergency pacing for bradyarrhythmias and conduction disturbances requires rapid deployment capability. Transcutaneous technology serves ambulance and emergency department protocols where lead placement speed outweighs precision requirements.
- Electrophysiological Studies:Diagnostic and therapeutic catheter ablation procedures demand programmable pacing with precise cycle length control. Dual chamber systems with burst and ramp pacing modalities command premium positioning in specialized laboratories.
- Cardiac Surgery:Post-operative conduction disturbance management utilizes temporary epicardial or transvenous pacing.
- Heart Failure Management:Temporary resynchronization support bridges patients to definitive therapy.
By procedure volume, Acute Cardiac Conditions leads. By technology upgrade intensity, Electrophysiological Studies is gaining share fastest.
Technology:
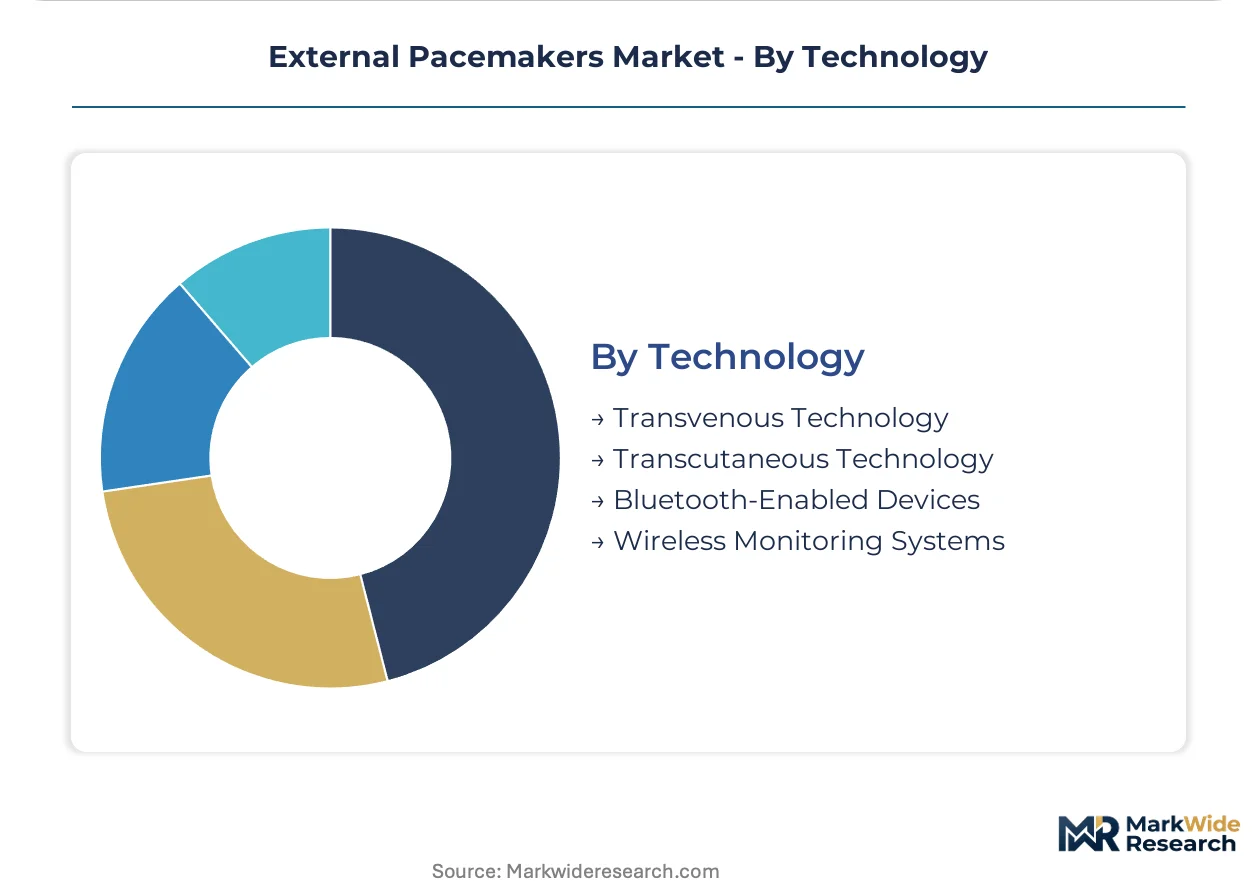
Wireless connectivity architectures are displacing tethered systems across all care environments, compressing traditional equipment refresh cycles.
- Bluetooth-Enabled Devices:Low-energy wireless integration enables remote parameter adjustment and alarm transmission. FDA and EU MDR electromagnetic compatibility standards accelerate manufacturer investment in Bluetooth Low Energy safety validation infrastructure.
- Transvenous Technology:Temporary lead placement through central venous access remains the clinical standard for precise pacing. Silver and palladium electrode fabrication costs create margin exposure to precious metal price volatility.
- Transcutaneous Technology:External pad-based emergency pacing faces commoditization pressure.
- Wireless Monitoring Systems:Cellular backhaul integration supports cloud-based arrhythmia analytics.
By current deployment, Transvenous Technology leads. By investment priority, Bluetooth-Enabled Devices show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan concentrate purchasing authority for external pacemaker systems. These three markets anchor demand through distinct regulatory pathways and aging demographic profiles that sustain cardiac intervention volumes.
United States
Ambulatory surgical centers in Texas and Florida are expanding temporary pacemaker procurement for same-day cardiac procedures. FDA premarket notification requirements for dual chamber configurations elevate documentation burdens for multi-chamber devices. The Greater Boston cluster anchors electrophysiology specialization with integrated delivery networks standardizing vendor contracts across multiple facilities.
Germany
Cardiology clinics in Bavaria and Baden-Württemberg prioritize atrioventricular synchrony benefits from dual chamber systems. EU MDR technical documentation mandates accelerate manufacturer investment in electromagnetic compatibility validation infrastructure. The Rhine-Ruhr industrial corridor concentrates biomedical engineering expertise for temporary pacing system maintenance and spare parts logistics.
Japan
PMDA clinical testing protocols for temporary pacing systems create regulatory barriers that favor established suppliers with local partnership networks. Tokyo and Osaka metropolitan areas concentrate electrophysiology laboratory capacity for diagnostic catheter ablation procedures. METI industrial policy supports domestic production of precision medical electronics for cardiac devices.
China
NMPA pathway harmonization for temporary pacing systems reduces time-to-market for compliant manufacturers in tier-2 cities. The Yangtze River Delta cluster in Shanghai-Jiangsu-Zhejiang anchors cardiology clinic expansion with government-funded healthcare infrastructure investment. MIIT standards for wireless medical devices accelerate Bluetooth-enabled telemetry adoption in hospital networks.
India
CDSCO medical device regulations for temporary pacemakers impose quality system requirements that differentiate organized manufacturers from unorganized suppliers. Maharashtra and Karnataka states concentrate cardiac care hospital chains in Mumbai and Bangalore. Government health insurance expansion under Ayushman Bharat drives procedural volume growth in secondary cities.
External Pacemakers Market Competitive Landscape
Player mix skews toward diversified cardiovascular device conglomerates with electrophysiology portfolios. The supplier base concentrates around three strategic tiers: integrated multi-modality cardiac device manufacturers, specialized temporary pacing system suppliers, and emergency medical equipment generalists. Competitive dynamics center on FDA premarket notification speed and EU MDR technical documentation completeness as primary differentiation vectors. M&A activity targets wireless telemetry capabilities while strategic partnerships secure precious metal electrode supply chains.
Among diversified cardiovascular conglomerates, Medtronic, Boston Scientific Corporation, and Abbott occupy anchor positions representing distinct competitive archetypes. Medtronic exemplifies the transvenous technology specialist with acute care setting dominance. Boston Scientific Corporation sits within the electrophysiology laboratory-focused tier. Abbott represents the wireless monitoring integration vector with telemetry service bundling capabilities. These three entities collectively shape procurement committee vendor standardization dynamics across United States integrated delivery networks and European hospital systems.
| Leading Market Players |
|---|
| BIOTRONIK |
| Boston Scientific Corporation |
| Medtronic |
| OSCOR Inc. |
| Shree Pacetronix |
| ZOLL Medical |
| Osypka Medical |
| MicroPort Scientific Corporation |
| Abbott |
| Others |
Supply & Pricing Matrix
Bluetooth Low Energy module substitution for legacy wired telemetry architectures is redrawing component sourcing maps toward Taiwan and South Korea while compressing hardware margins through semiconductor commoditization. This substitution dynamic simultaneously elevates electromagnetic compatibility validation costs and fragments pricing power across tiered supplier tiers.
Pricing Analysis
Cost-plus contracts with silver and palladium indexation dominate temporary pacing lead procurement, with precious metal price volatility passed through to hospital group purchasing organizations. Pricing stratifies across premium dual chamber systems with FDA premarket notification pedigree, standard Bluetooth-enabled units with EU MDR technical documentation, and economy transcutaneous emergency devices facing acute price erosion. Ambulance procurement committees exhibit highest price sensitivity due to undifferentiated emergency specifications, while electrophysiology laboratories accept premium positioning for atrioventricular synchrony benefits.
Supply Chain Analysis
Malaysia and Costa Rica anchor disposable lead manufacturing for US hospital networks, while Germany and Japan concentrate precision pulse generator assembly. Silver and palladium electrode fabrication draws from South African and Russian mining outputs, with platinum group metal price volatility creating margin exposure. Single-source dependency on Malaysian contract manufacturers for sterilized lead packaging presents tariff and logistics chokepoint risk. Distribution runs through group purchasing organizations for hospital systems and direct manufacturer relationships for ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
External pacemaker economics are pivoting toward platform interoperability as Bluetooth-5G convergence enables telemetry subscription bundling decoupled from hardware monetization. This ecosystem shift rewards suppliers controlling cloud-based arrhythmia analytics infrastructure alongside device manufacturing.
For Market Incumbents: Secure precious metal electrode supply through backward integration into South African platinum group metal offtake agreements to defend against palladium price volatility. Consolidate biomedical engineering training contracts across integrated delivery networks to preempt multi-source procurement committee mandates.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-track offers accelerated premarket notification pathways for AI-enabled arrhythmia prediction algorithms bundled with pacing hardware. Target cardiology clinics in Texas and Florida ambulatory surgical center corridors with disposable temporary pacemaker offerings priced below Medtronic and Boston Scientific Corporation contract tiers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed emergency medical equipment generalists lacking wireless telemetry capabilities. Five-to-ten year viability hinges on cloud infrastructure ownership rather than device manufacturing scale. Monitor FDA cybersecurity guidance finalization as inflection signal for connected cardiac device valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Bluetooth-5G Telemetry Integration | Enables real-time cloud-based arrhythmia analytics for predictive intervention protocols. |
| EU MDR Technical Documentation Investment | Accelerates electromagnetic compatibility validation infrastructure for wireless safety clearance. |
| Hospital System Partnership Consolidation | Streamlines biomedical engineering training and spare parts inventory across integrated delivery networks. |
| Precious Metal Supply Agreement | Secures silver and palladium electrode fabrication inputs against commodity price volatility. |
| Reimbursement Strategy for Remote Monitoring | Aligns telemetry subscription revenue with CMS remote patient monitoring billing codes. |
Research Methodology
Initial hypotheses were tested against primary input from electrophysiologists, hospital purchasing committee chairs, biomedical engineering directors, and group purchasing organization contract managers and refined through secondary validation against FDA premarket notification filings, EU MDR technical documentation databases, hospital procurement records, and precious metal commodity exchange data. Bottom-up demand modeling for temporary pacing procedures across acute cardiac conditions, electrophysiological studies, and post-surgical applications was triangulated against top-down manufacturer revenue aggregation.
Variance decomposition across product type, end user facility category, application severity, and wireless connectivity architecture shaped analytical framework construction over the projection horizon. CAGRs were derived from procedure volume elasticity to aging demographic penetration and technology substitution curves for Bluetooth-enabled devices displacing tethered systems. Forecast inputs incorporated PMDA clinical testing timeline assumptions for Japan market entry and NMPA pathway harmonization velocity for China tier-2 city expansion.
Underlying assumptions cover regulatory clearance timelines, precious metal price stability, and electromagnetic compatibility standard evolution, with deviation risk concentrated in FDA cybersecurity guidance implementation delays and EU MDR post-market surveillance documentation burdens. Recalibration cycles align with material shifts in wireless medical device standards and hospital procurement centralization mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Collateral Ligament Stabilizer System Market
Medical Devices
Urine Collection Devices Market
Medical Devices
Pectus Bar System Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Ligament Stabilizers Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Absorbable PGLA Surgical Sutures Market
Medical Devices
Walking Aids Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Cholecystectomy Devices Market
Medical Devices
Europe Ventilator Market
Medical Devices
Indwelling Catheter Market