
 Surgical Display Market | 2026-2036
Surgical Display Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Display Market Intelligence
Modular display bundles combining 4K monitors with centralized video management is realigning hospital procurement decisions toward integrated suite solutions rather than standalone hardware. Barco leverages its dominance in surgical visualization to anchor premium hybrid OR installations across North American hospital networks. EIZO Corporation specializes in color-calibrated diagnostic displays that sustain exacting grayscale standards for pathology-adjacent surgical workflows. Sony Corporation competes on imaging sensor-to-display pipeline control, extending its broadcast video heritage into endoscopic visualization systems.
A surgical display is a medical-grade visualization device engineered to reproduce color gamuts exceeding DCI-P3 standards with luminance uniformity within five percent across the active area, manufactured under ISO 13485 quality systems for sterile field compatibility. Its primary purpose is to render real-time endoscopic, laparoscopic, or open surgical imagery with sufficient fidelity to support clinical decision-making during operative procedures. LED-backlit LCD technology occupies the dominant installed base due to cost efficiency and supply chain maturity, while OLED surgical displays command premium positioning where perfect black levels enhance depth perception in neurovascular procedures. Touchscreen displays represent the fastest-growing product configuration as gesture-controlled sterile interfaces reduce nursing staff contact with non-sterile equipment during cardiac surgery applications.
FDA 510(k) premarket notification requirements and EU MDR Class IIa device classifications impose luminance stability and electromagnetic compatibility testing that shapes product development timelines for manufacturers seeking dual-territory approval. Japan's PMDA enforces JIS T 0601-1 safety standards that restrict market access for displays failing insulation and leakage current protocols specific to patient-proximate electrical equipment. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market surveillance obligations under EU MDR as connected surgical displays integrate with hospital IT networks and picture archiving systems.
Market Dynamics
Hybrid operating room construction is compressing replacement cycles as hospitals consolidate multiple visualization sources into unified command centers, forcing display vendors to bundle surgical monitors with centralized video management platforms rather than compete on standalone hardware specifications.
Growth Catalysts
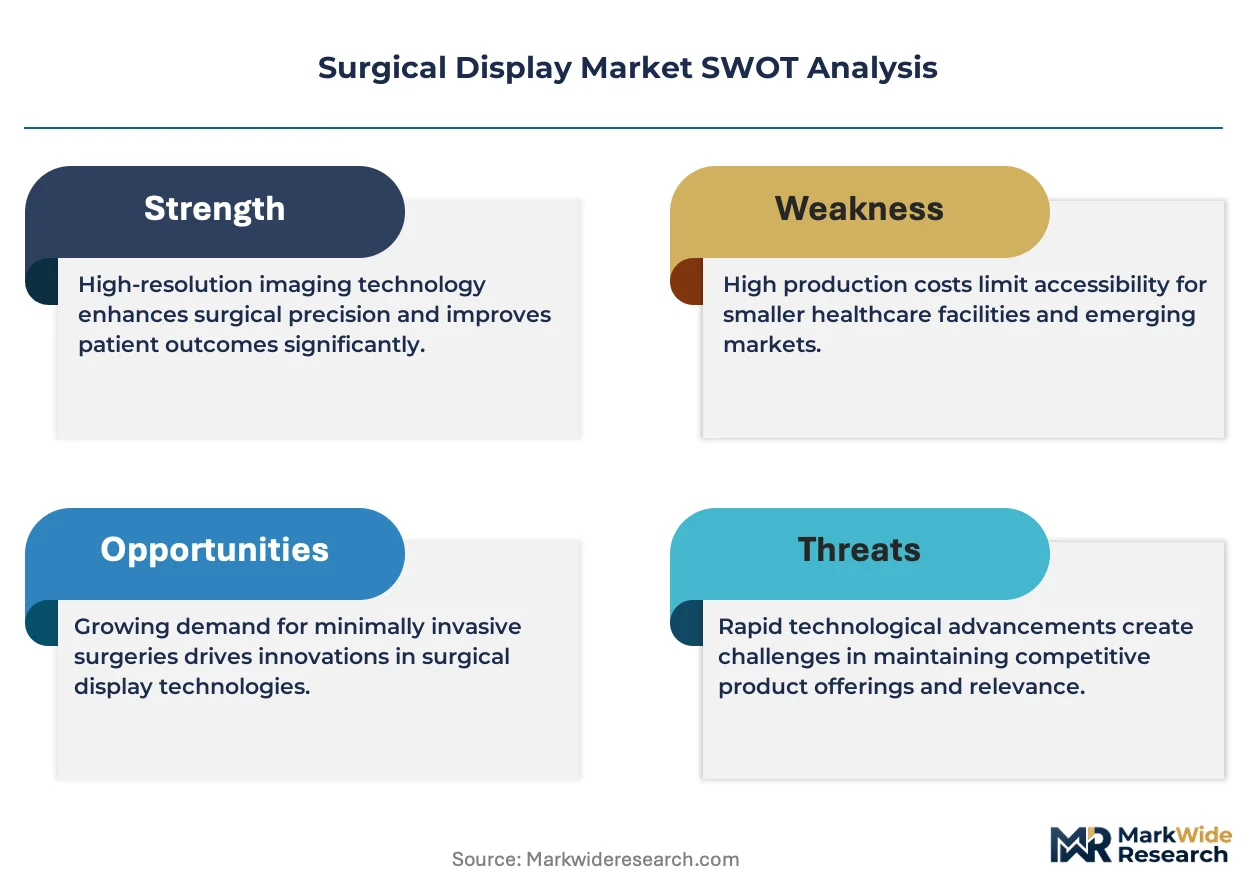
- FDA 510(k) pathway streamlining:Pre-market notification efficiencies for Class II medical devices accelerate dual-territory approval timelines, reducing time-to-revenue for manufacturers targeting US and EU markets simultaneously.
- Minimally invasive procedure expansion:Laparoscopic and endoscopic surgery volumes in ambulatory surgical centers drive procurement of high-resolution visualization systems capable of supporting real-time clinical decision-making.
- LED-backlit LCD supply chain maturity:Cost efficiencies from scaled manufacturing in East Asian component ecosystems enable price accessibility for mid-tier hospital networks previously excluded from premium surgical visualization.
Market Restraints
- EU MDR Class IIa certification friction:Stricter clinical evidence requirements and notified body capacity constraints extend approval timelines by twelve to eighteen months compared to prior Medical Device Directive frameworks.
- OLED panel supply concentration:Perfect black level displays for neurovascular applications depend on limited Korean and Japanese substrate manufacturers, creating input cost volatility and allocation risk.
- Grayscale calibration technical ceiling:Pathology-adjacent surgical workflows demand luminance uniformity within five percent that exceeds current mass-production tolerances, constraining yield rates and inflating unit economics.
Strategic Opportunities
- Touchscreen sterile interface penetration:Gesture-controlled displays reduce nursing staff contact with non-sterile equipment during cardiac surgery, opening premium positioning in infection-sensitive procedure categories.
- Japan PMDA JIS T 0601-1 compliance gap:Insulation and leakage current protocols specific to patient-proximate electrical equipment exclude non-compliant imports, creating protected market share for certified entrants.
- Cybersecurity integration services:FDA post-market surveillance obligations for connected surgical displays interfacing with hospital IT networks and picture archiving systems create recurring revenue streams beyond hardware sales.
Industry Challenges
- ISO 13485 quality system maintenance:Sterile field compatibility manufacturing requirements demand continuous audit readiness that strains mid-tier engineering organizations without dedicated regulatory affairs functions.
- Legacy PACS integration complexity:DICOM conformance testing for surgical displays connecting to heterogeneous hospital imaging archives consumes development resources and delays product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Display Market |
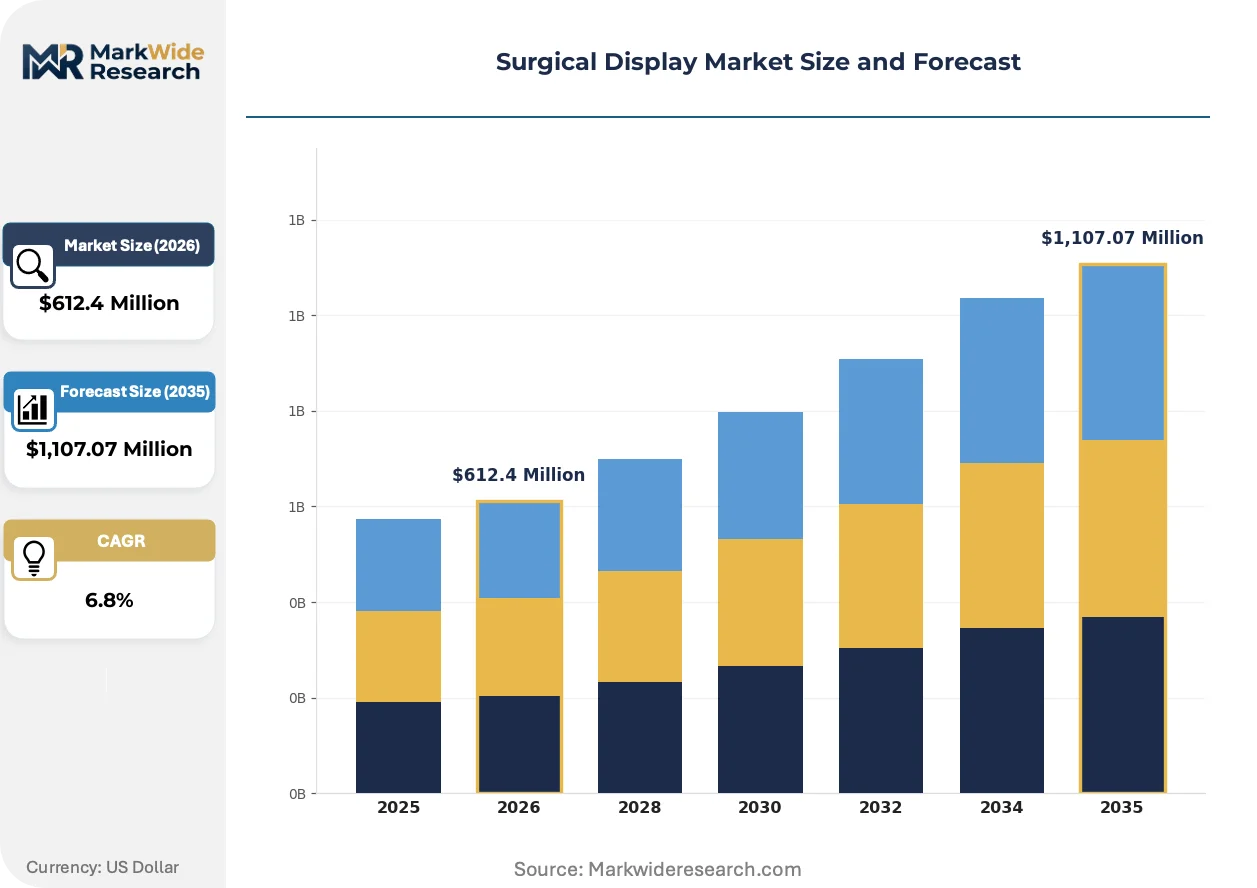
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitors, Projectors, Touchscreen Displays, 3D Displays Technology: LED, OLED, LCD, DLP End User: Hospitals, Surgical Centers, Research Institutions, Training Facilities Application: General Surgery, Orthopedic Surgery, Neurosurgery, Cardiac Surgery |
| Companies Covered | Barco, EIZO Corporation, Sony Corporation, Novanta Inc., LG Electronics, Siemens Healthineers, Jusha Medical, Advantech Co., Ltd., Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Display Market Strategic Shifts & Innovations
Display technology convergence with centralized video management is restructuring how hospitals evaluate procurement, shifting competitive differentiation from panel specifications toward ecosystem integration and sterile workflow compatibility.
OLED surgical visualization is consolidating premium positioning in neurovascular and ophthalmic procedures where perfect black levels enhance depth perception of fine anatomical structures. Academic medical centers in Germany and Japan are standardizing on these panels for hybrid OR installations despite forty to sixty percent cost premiums over LED-backlit alternatives. The technology is consolidating vendor margins at the high end while compressing differentiation opportunities for LCD-only portfolios.
EU MDR post-market surveillance obligations are tightening electromagnetic compatibility and luminance stability documentation requirements for Class IIa surgical displays. Manufacturers must now maintain clinical follow-up registries and periodic safety update reports that extend product lifecycle management costs. Cardiac surgery applications face the steepest compliance burden due to patient-proximate electrical safety classifications.
Hospital procurement departments are unbundling after-sales service contracts from hardware purchases, forcing display vendors to compete on discrete maintenance pricing rather than bundled lifetime cost proposals. German hospital networks pioneered this separation, with Japanese metropolitan health systems now adopting similar tender structures. Vendor responses concentrate on remote diagnostic capabilities that reduce on-site technical labor exposure.
Surgical Display Market Segmentation
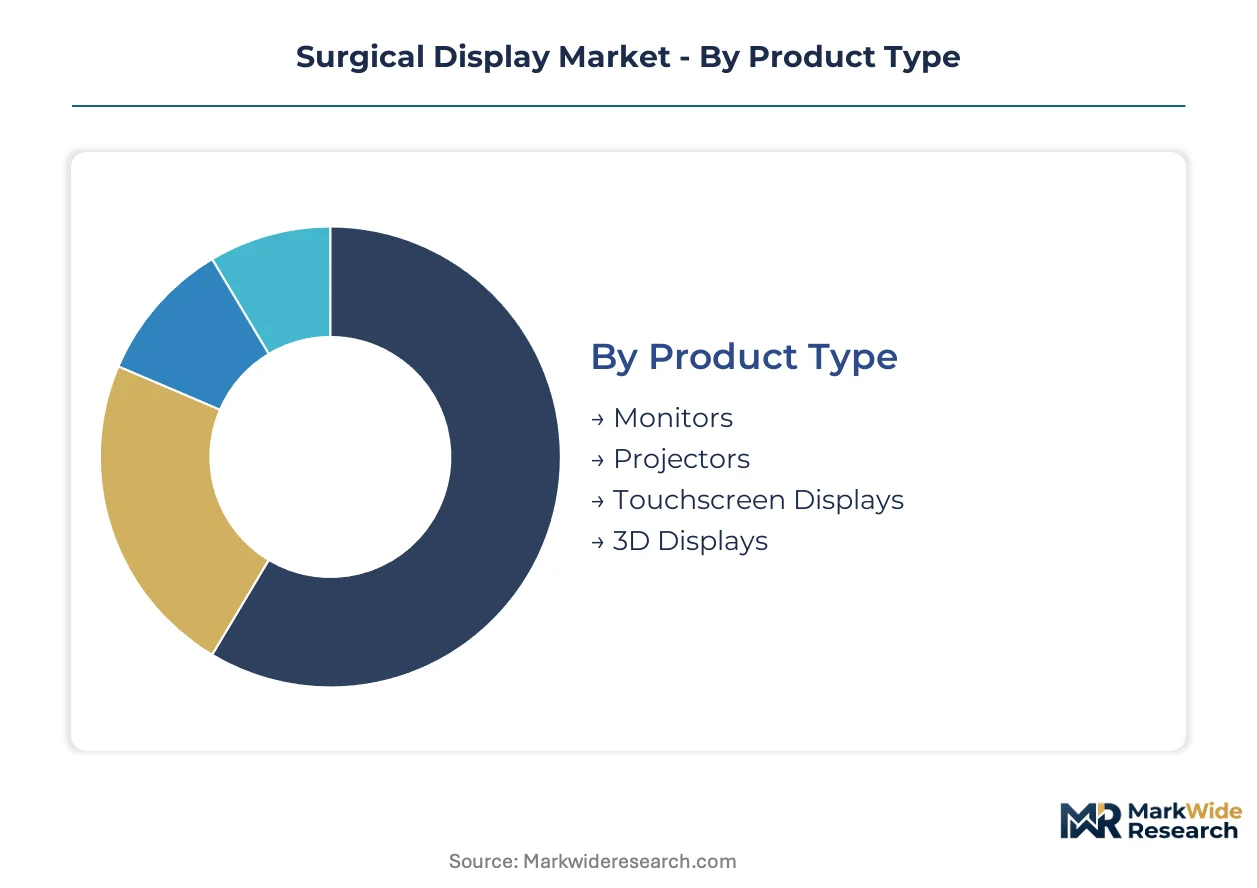
Surgical display procurement diverges sharply across clinical settings and technical specifications. Product type and technology choices determine sterile workflow compatibility, while end-user scale and application complexity dictate resolution and integration requirements.
Product Type:
Resolution specifications and sterile interface design separate premium installations from standard deployments.
- Monitors:LED-backlit LCD panels dominate installed base economics with DCI-P3 color gamut coverage and luminance uniformity within five percent across the active area. Hybrid operating room construction in the United States and Germany compresses replacement cycles as hospitals consolidate multiple visualization sources into unified command centers.
- Touchscreen Displays:Gesture-controlled sterile interfaces reduce nursing staff contact with non-sterile equipment during cardiac surgery applications. Ambulatory surgical centers in Japan are expanding procurement fastest as infection-sensitive procedure categories demand touchless workflow integration.
- Projectors:Large-format visualization for teaching hospitals and training facilities where multi-viewer observation requirements exceed direct-view monitor scale.
- 3D Displays:Depth-enhanced visualization for laparoscopic and endoscopic procedures requiring spatial anatomical orientation.
Mature deployment sits with monitors. Newer deployment is concentrated in touchscreen displays.
Technology:
Panel chemistry determines black level performance, power efficiency, and supply chain risk exposure.
- LED:Backlit LCD configurations leverage East Asian component ecosystem scale for cost accessibility in mid-tier hospital networks. Supply chain maturity enables price positioning previously excluded from premium surgical visualization procurement.
- OLED:Perfect black levels enhance depth perception in neurovascular and ophthalmic procedures where fine anatomical structure discrimination is critical. Academic medical centers in Germany and Japan standardize on these panels despite substantial cost premiums over LED-backlit alternatives.
- LCD:Direct-lit and edge-lit variants without LED enhancement for budget-constrained installations in developing health systems.
- DLP:Projection technology for ultra-large format surgical visualization in hybrid OR command centers requiring multi-source image fusion.
Volume concentration favors LED. Margin capture concentrates in OLED.
End User:
Capital intensity and integration complexity scale inversely with facility specialization.
- Hospitals:Hybrid operating room installations demand centralized video management platforms with DICOM conformance for picture archiving system integration. German hospital networks pioneered unbundled after-sales service contracts from hardware purchases.
- Surgical Centers:Ambulatory settings prioritize high-resolution visualization systems for minimally invasive procedure expansion with faster procurement cycles than acute care facilities.
- Research Institutions:Preclinical and translational research applications requiring color-calibrated diagnostic displays sustaining exacting grayscale standards for pathology-adjacent workflows.
- Training Facilities:Multi-viewer observation requirements and simulation-based education driving large-format projection and 3D visualization adoption.
Integration complexity peaks in hospitals. Procurement velocity is fastest in surgical centers.
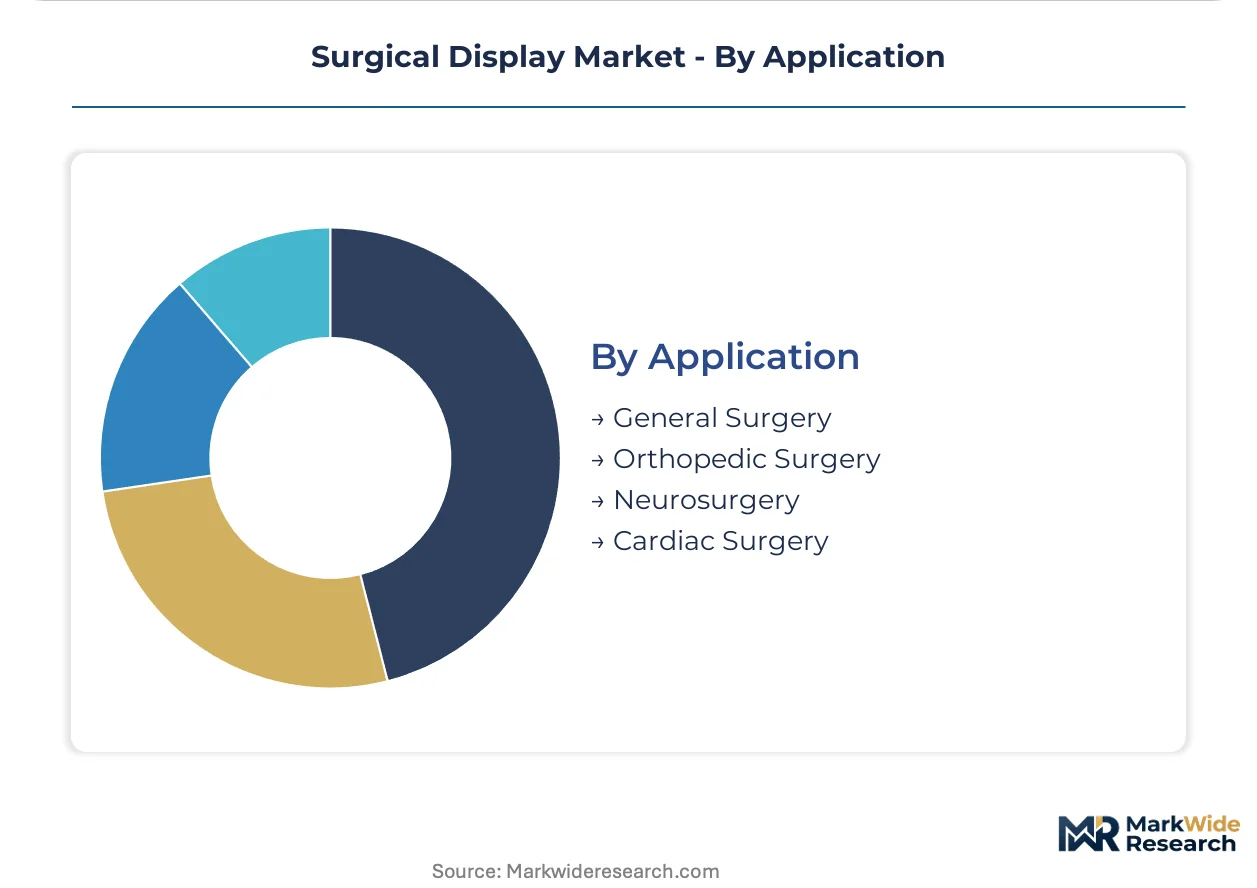
Application:
Visual fidelity requirements and electrical safety classifications vary with anatomical target and procedure invasiveness.
- General Surgery:Breadth of procedure types supports standardized 4K monitor configurations with centralized video management rather than specialty-optimized displays.
- Cardiac Surgery:Patient-proximate electrical safety classifications under EU MDR impose the steepest electromagnetic compatibility and luminance stability documentation burden. Touchscreen sterile interfaces are gaining share fastest in this category due to infection control protocols.
- Neurosurgery:Perfect black level demands for fine neurovascular structure visualization drive OLED panel adoption despite supply concentration risk from Korean and Japanese substrate manufacturers.
- Orthopedic Surgery:High-brightness requirements for arthroscopic visualization in illuminated operating environments favor LED-backlit LCD cost efficiency.
Regulatory burden concentrates in cardiac surgery. Premium technology penetration is deepest in neurosurgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing concentrates in East Asian supply chains while demand aggregates in mature healthcare systems with capital-intensive hybrid OR construction. The United States, Germany, and Japan absorb premium surgical display volumes through hospital network procurement. Regulatory divergence across FDA, EU MDR, and PMDA frameworks fragments approval pathways for manufacturers seeking multi-territory access.
United States
Hospital construction of hybrid operating rooms drives replacement cycles for centralized video management platforms. FDA 510(k) premarket notification pathways for Class II medical devices compress time-to-revenue for dual-territory applicants. Academic medical centers in Boston and Houston anchor premium installations requiring DICOM conformance for PACS integration.
Germany
Hospital networks pioneered unbundled after-sales service contracts from hardware purchases, forcing discrete maintenance pricing competition. EU MDR Class IIa certification requirements impose stricter clinical evidence standards than prior Medical Device Directive frameworks. Industrial clusters in Bavaria and Baden-Württemberg concentrate notified body capacity for electromagnetic compatibility testing.
Japan
PMDA enforces JIS T 0601-1 safety standards restricting market access for displays failing insulation and leakage current protocols. Metropolitan health systems in Tokyo and Osaka adopt tender structures separating hardware from service procurement. Ambulatory surgical centers expand fastest in touchscreen display procurement for infection-sensitive cardiac workflows.
South Korea
OLED substrate manufacturing concentrates supply for perfect black level panels serving neurovascular applications. Domestic display component ecosystems enable backward integration into surgical visualization systems. Seoul-based producers face allocation risk from competing demand in consumer electronics and automotive display segments.
China
NMPA medical device registration requirements diverge from FDA and EU MDR frameworks, extending localization timelines for foreign manufacturers. Tier-one hospitals in Beijing and Shanghai drive 4K monitor procurement for minimally invasive procedure expansion. Domestic producers leverage LED-backlit LCD supply chain scale for mid-tier hospital network price positioning.
Surgical Display Market Key Industry Players
The competitive structure tilts toward diversified electronics conglomerates with captive display component supply. Tiered positioning separates premium hybrid OR integrators from mid-tier monitor suppliers and regional specialists. Three archetypes dominate: imaging pipeline controllers, sterile workflow specialists, and component-scale fabricators. Capacity expansion in East Asian substrate manufacturing and strategic partnerships for centralized video management platforms constitute the dominant competitive moves.
Among diversified imaging technology providers, Barco and Sony Corporation occupy positions exemplifying premium-tier ecosystem integration. EIZO Corporation represents the specialist archetype focused on color-calibrated diagnostic standards. These three anchors demonstrate how competitive positioning flows from control over upstream imaging sensors, display panel chemistry, or sterile interface design rather than hardware specifications alone.
| Leading Market Players |
|---|
| Barco |
| EIZO Corporation |
| Sony Corporation |
| Novanta Inc. |
| LG Electronics |
| Siemens Healthineers |
| Jusha Medical |
| Advantech Co., Ltd. |
| Olympus Corporation |
| Others |
Cost & Logistics Intelligence
OLED versus LED-backlit LCD bifurcation manifests in divergent margin structures and sourcing strategies across surgical display procurement. Academic medical centers in Germany and Japan absorb forty to sixty percent cost premiums for perfect black level panels, while mid-tier hospital networks in the United States leverage East Asian LED supply chain scale for accessible price positioning. This tier divergence reshapes vendor portfolio decisions around captive substrate access versus modular procurement flexibility.
Pricing Analysis
Margin tightening in LED-backlit LCD tiers reflects Korean and Japanese substrate manufacturers' allocation leverage over OLED supply. Three-tier pricing structure across premium, standard, and economy levels stratifies by grayscale calibration precision and EU MDR Class IIa certification completeness. Ambulatory surgical centers exhibit highest price sensitivity due to compressed capital cycles, whereas hybrid OR installations in academic medical centers prioritize performance over unit cost. Pricing pressure stems from hospital procurement departments unbundling after-sales service contracts from hardware purchases.
Supply Chain Analysis
Freight cost volatility from East Asian component ecosystems amplifies working capital requirements for LED-backlit LCD panel importers. Display substrate manufacturing concentrates in South Korea, Japan, and China, with OLED panel supply anchored in Korean and Japanese fabrication facilities. Raw material dependencies span indium tin oxide for transparent electrodes, polarizer films from Japanese specialty chemical producers, and LED phosphor substrates. Single-source vulnerability from limited OLED substrate manufacturers creates allocation risk during consumer electronics demand spikes. Distribution runs through authorized medical device distributors with ISO 13485 quality system certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Class IIa device classification imposes clinical evidence requirements that extend approval timelines by twelve to eighteen months, erecting compliance moats around notified body-certified incumbents. This regulatory friction advantages manufacturers with dedicated regulatory affairs functions and existing MDR technical documentation.
For Market Incumbents: Anchor premium positioning through captive OLED substrate partnerships with Korean manufacturers, insulating margin capture from allocation volatility. Consolidate hybrid OR ecosystem integration by bundling centralized video management platforms with 4K monitor deployments, raising switching costs for hospital networks. Barco and Sony Corporation exemplify this defensive posture through imaging sensor-to-display pipeline control. For New Entrants and Emerging Players: Ambulatory surgical centers in Japan represent the most penetrable white-space target, given PMDA JIS T 0601-1 compliance gaps that exclude non-certified imports. Touchscreen sterile interface penetration in cardiac surgery applications offers premium positioning with lower certification burden than neurovascular OLED tiers. Partner with regional medical device distributors possessing existing hospital GPO contracts to bypass direct procurement committee access barriers. For Investors and Strategic Acquirers: Re-rating potential sits with sterile workflow specialists possessing FDA 510(k) clearance libraries and EU MDR technical documentation, given consolidation pressure from diversified imaging conglomerates. Five-to-ten year viability favors manufacturers with backward integration into LED component ecosystems or exclusive OLED substrate allocation agreements. Monitor notified body capacity constraints as inflection indicator for MDR approval timeline normalization and competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Investment | Notified body partnerships compress approval timelines for dual-territory market access. |
| OLED Substrate Supply Agreement | Exclusive allocation contracts with Korean manufacturers secure premium panel supply. |
| Centralized Video Management Platform Integration | Hybrid OR ecosystem bundling raises hospital network switching costs. |
| Touchscreen Sterile Interface Development | Gesture-controlled workflows penetrate infection-sensitive cardiac surgery categories. |
| Remote Diagnostic Capability Deployment | Unbundled service pricing responds to German and Japanese procurement separation trends. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this surgical display market assessment. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at notified bodies informed demand-side validation. FDA 510(k) premarket notification databases, EU MDR technical documentation registries, and PMDA approval records provided secondary anchor points. Bottom-up triangulation across hospital procurement databases and top-down validation from medical device trade statistics ensured cross-verification.
Segment-level granularity modeled product type, technology chemistry, end-user facility scale, and application-specific electrical safety classification across the projection horizon. Resolution tier, sterile interface design, and regional regulatory cluster constituted additional modeling dimensions. CAGRs derived from weighted average of historical replacement cycle compression and minimally invasive procedure volume trajectories. Forecast inputs incorporated hybrid OR construction pipeline data and ambulatory surgical center expansion rates without year-specific anchoring.
Caveats apply where notified body capacity constraints, OLED substrate allocation disruptions, or cybersecurity guidance evolution from FDA could materially shift the outlook. Forecasts reflect assumptions around stable regulatory enforcement intensity and continued hospital capital expenditure prioritization for visualization infrastructure. Stakeholders should weight assumptions against their own operating context and procurement cycle exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Venturi Mask Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Micro-Bypass Systems Market
Medical Devices
Organ Preservation & Perfusion Products Market
Medical Devices
Aneurysm Coiling & Embolization Devices Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Oxygen Delivery Systems Market
Medical Devices
Laryngoscopes Market
Medical Devices
Semiconductor Laser Therapeutic Device Market
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
Germany Ophthalmic Devices Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Arthroscopic Shaver Market