
 Wireless Portable Medical Devices Market | 2026-2036
Wireless Portable Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Portable Medical Devices Market Outlook
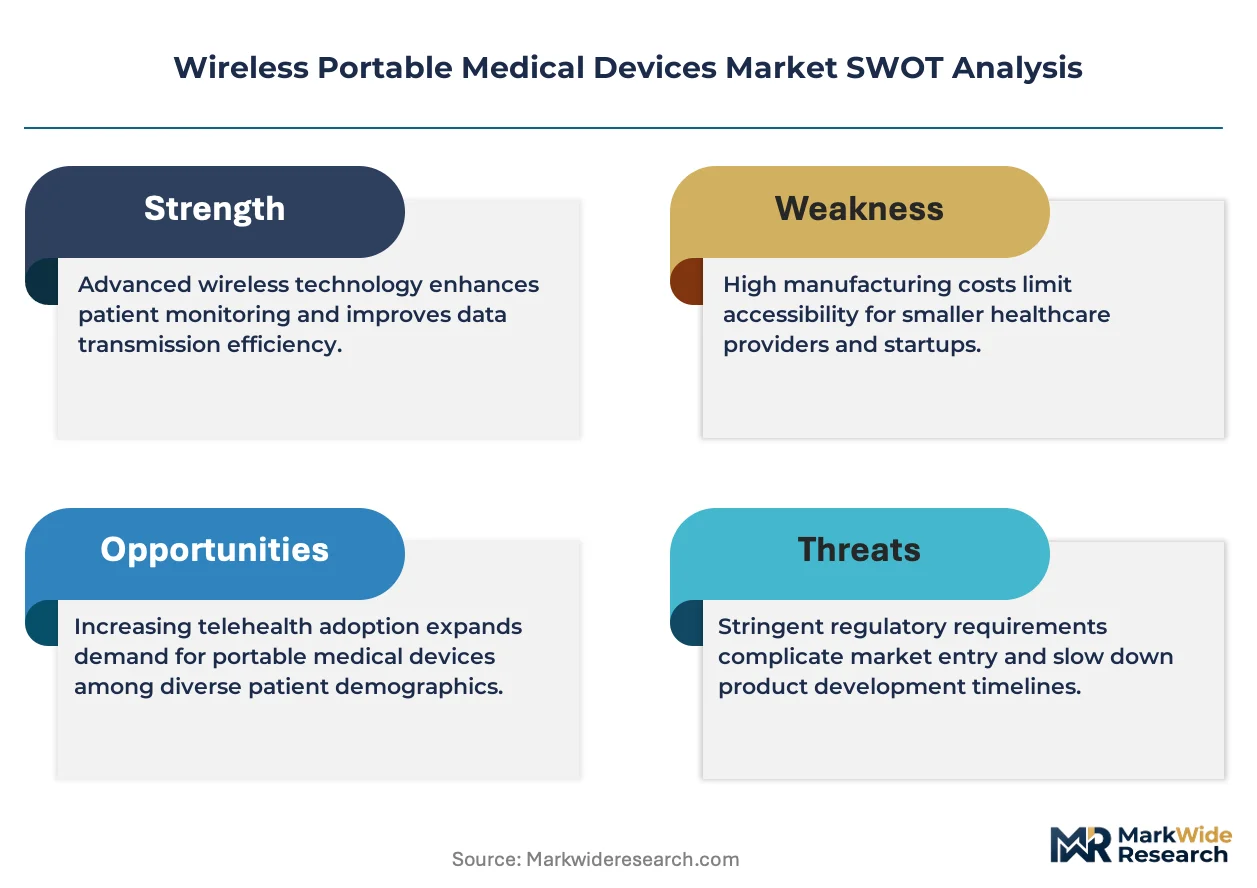
A shortage of biomedical engineers trained in radio-frequency integration and FDA quality system regulation is redrawing competitive boundaries across the Wireless Portable Medical Devices landscape. Philips Healthcare leverages its in-house RF engineering centers to sustain design-to-submission timelines that outpace smaller rivals. Medtronic anchors its position through backward integration into sensor fabrication, controlling critical MEMS supply for glucose and cardiac monitors. Abbott Laboratories differentiates via specialized focus on over-the-14-day wearables, occupying a defensible niche in consumer-accessible continuous monitoring.
Wireless portable medical devices comprise battery-powered, networked instruments that transmit physiological data via Bluetooth, Wi-Fi, Zigbee, or cellular protocols to clinical decision systems or patient-facing applications, typically operating within 2.4 GHz ISM bands with sub-1-watt power envelopes to satisfy FDA electromagnetic compatibility limits. Their primary purpose is to collapse the distance between patient physiology and clinical action, enabling ambulatory diagnosis and therapy adjustment without facility-based encounters. Wearable monitors lead the device type landscape, capturing the majority of unit volume as cardiac and metabolic indications broaden, while wireless diagnostic devices represent the fastest-expanding margin pool due to higher reimbursement and lower replacement frequency. Remote patient monitoring dominates application-level demand, though medication management is accelerating as smart pill bottles integrate cellular connectivity for adherence verification in clinical trials.
FDA quality system regulation and FCC Part 15 radio equipment authorization jointly govern market access, with the former mandating design controls and post-market surveillance while the latter certifies non-interference in shared spectrum bands. The EU MDR and GDPR create parallel compliance burdens for Bluetooth-linked devices that store biometric data on cloud servers, favoring vendors with established European notified body relationships. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled diagnostic algorithms, as forthcoming predicate rules for machine-learning-based arrhythmia detection will reshape submission strategies and R&D allocation across the competitive set.
Market Dynamics
The Wireless Portable Medical Devices market is being fundamentally restructured by the compression of FDA clearance timelines for Bluetooth-enabled continuous glucose monitors, which is collapsing barriers between consumer wellness and clinical-grade monitoring categories.
Growth Catalysts
- Medicare reimbursement for remote patient monitoring codes:The United States Centers for Medicare & Medicaid Services reimbursement structure is driving provider purchasing decisions toward wireless cardiac and metabolic monitors.
- Post-acute patient oversight protocols:Home care providers are expanding adoption of wireless monitors as hospital-at-home programs scale across North American and European healthcare systems.
- MEMS sensor fabrication advances:Miniaturization of glucose and cardiac sensing elements is enabling 14-day and longer wearables with disposable economics.
Market Restraints
- RF engineering talent scarcity:A shortage of biomedical engineers trained in radio-frequency integration and FDA quality system regulation is extending design-to-submission timelines for smaller entrants.
- Electromagnetic compatibility certification costs:FCC Part 15 authorization and FDA electromagnetic compatibility testing create fixed cost burdens that disproportionately constrain sub-$50 million revenue manufacturers.
- Cloud data residency requirements:EU GDPR biometric data storage mandates impose parallel compliance burdens for Bluetooth-linked devices, favoring vendors with established European notified body relationships.
Strategic Opportunities
- Clinical trial medication management:Smart pill bottles integrating cellular connectivity for adherence verification represent an emerging application with lower competitive density than cardiac monitoring.
- Artificial intelligence-enabled diagnostic algorithms:Forthcoming FDA predicate rules for machine-learning-based arrhythmia detection will reshape submission strategies and R&D allocation.
- Zigbee protocol adoption in institutional settings:Hospitals are deploying sub-1-watt mesh networks for inpatient telemetry, creating demand for dual-protocol Bluetooth-Zigbee devices.
Industry Challenges
- Post-market surveillance capability gaps:FDA quality system regulation mandates for design controls and adverse event reporting strain quality infrastructure at scaling manufacturers.
- Legacy electronic health record integration:Wireless diagnostic devices face API fragmentation and data format incompatibilities with entrenched hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Portable Medical Devices Market |
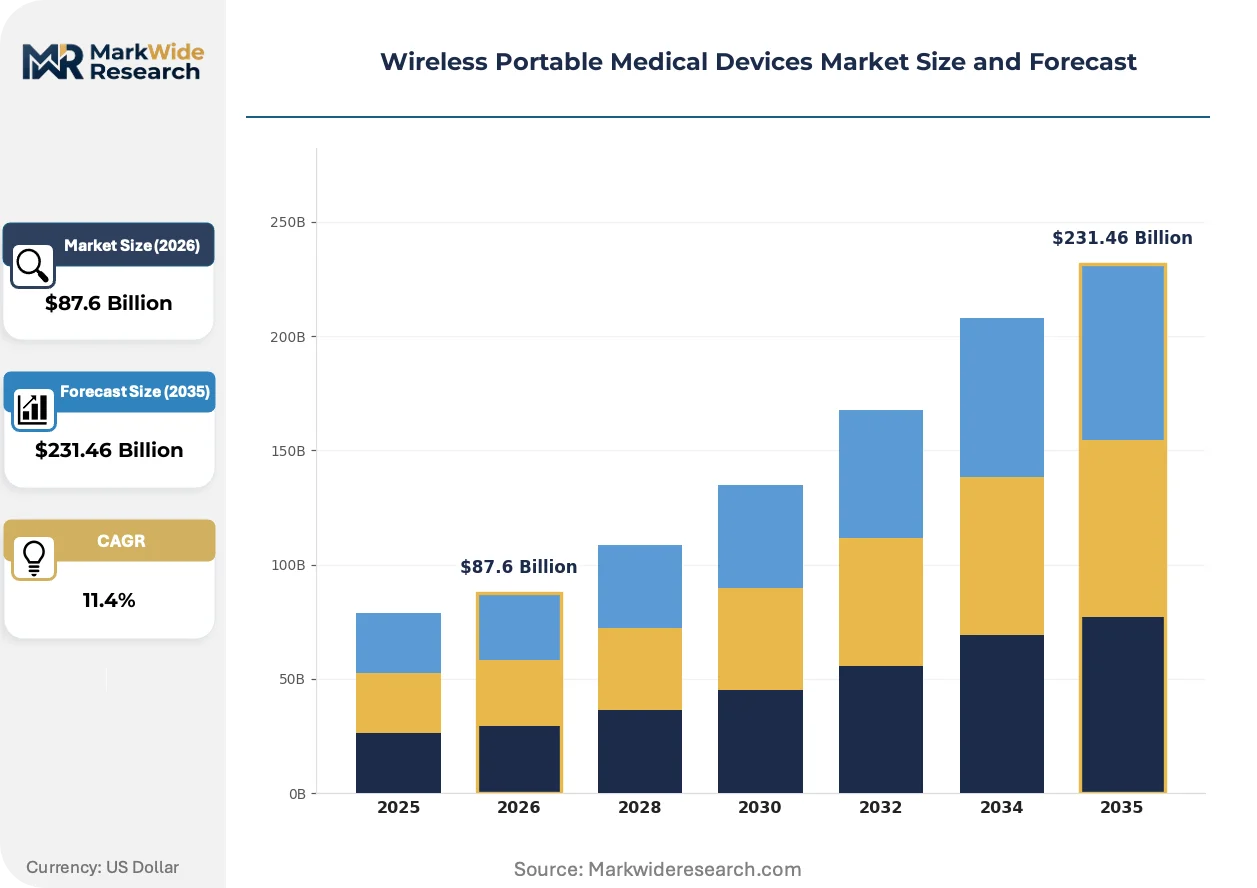
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearable Monitors, Handheld Sensors, Smart Pill Bottles, Wireless Diagnostic Devices Application: Remote Patient Monitoring, Chronic Disease Management, Health and Fitness Tracking, Medication Management End User: Healthcare Providers, Patients, Research Institutions, Home Care Providers Communication Technology: Bluetooth, Wi-Fi, Zigbee, Cellular |
| Companies Covered | GE Healthcare, Philips Healthcare, Medtronic, Omron Healthcare, Abbott Laboratories, Dexcom, Siemens Healthineers, Samsung Electronics, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Portable Medical Devices Market Strategic Shifts
Three forces are actively restructuring competitive boundaries: the decomposition of device architecture into modular sensing and connectivity layers, regulatory acceleration for software-as-medical-device submissions, and the migration of procurement authority from hospital IT departments to home health agency clinical directors.
Ultra-low-power system-on-chip architectures are decomposing the traditional integrated medical device model into separable sensing, processing, and transmission modules. Contract manufacturers in Taiwan and South Korea are capturing value from this disaggregation by offering pre-certified Bluetooth 5.3 subsystems that reduce OEM RF engineering requirements. This decomposition is compressing time-to-market for new entrants while eroding the historical advantage of captive RF engineering centers.
The EU Medical Device Regulation (MDR) and In Vitro Diagnostic Regulation (IVDR) are tightening clinical evidence requirements for Bluetooth-linked devices that store biometric data on cloud servers. Manufacturers must now demonstrate cybersecurity validation and post-market performance monitoring to maintain CE marking. Cardiac monitoring wearables face the steepest compliance burden, with notified bodies demanding extended follow-up data for arrhythmia detection algorithms.
Hospital procurement departments are losing authority over wireless portable device selection as home health agencies and accountable care organizations gain direct contracting power. These buyers prioritize total cost of ownership and patient adherence metrics over upfront device cost. The United States exhibits this shift most visibly, where Medicare Advantage plans are steering volume toward vendors offering integrated remote patient monitoring platforms with nursing support services.
Wireless Portable Medical Devices Market Segmentation
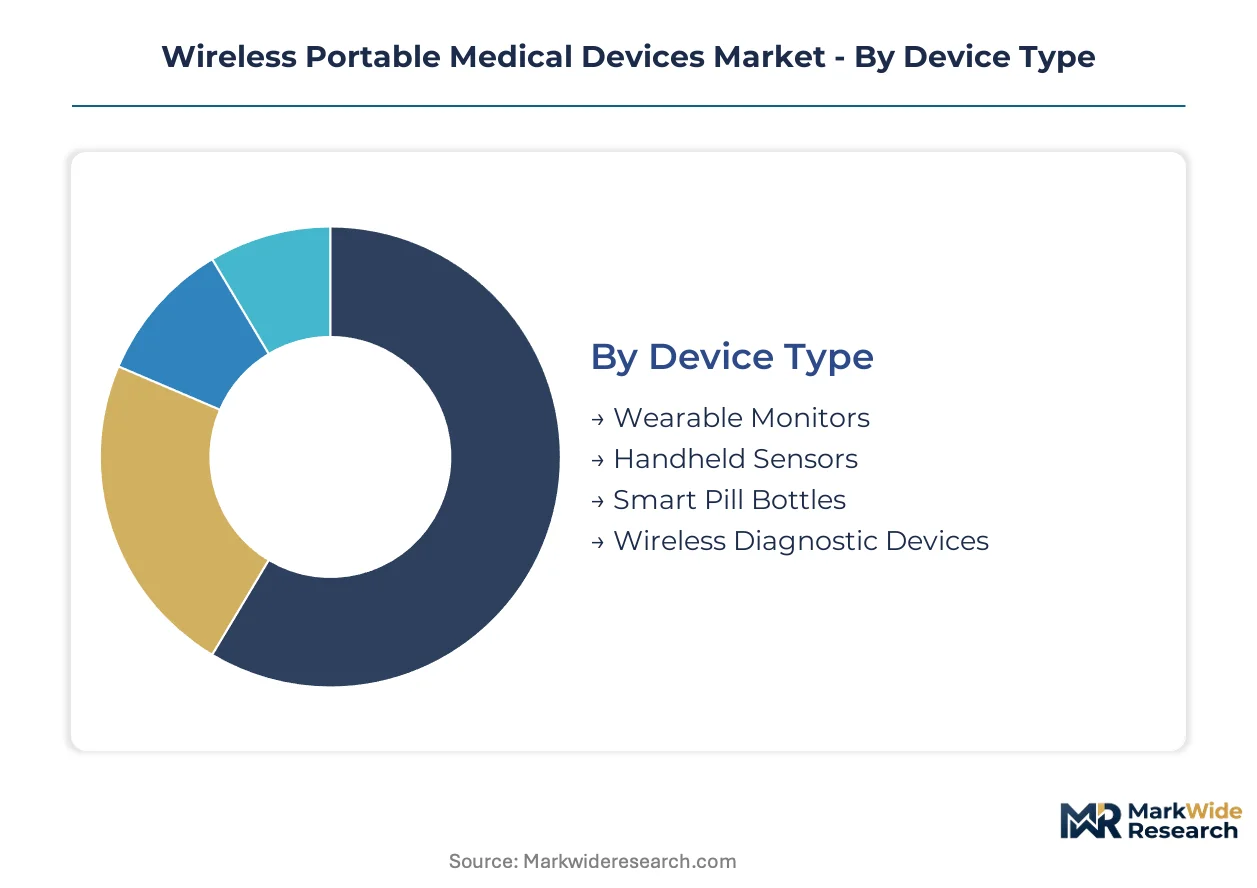
Segmentation in wireless portable medical devices determines regulatory pathways, reimbursement eligibility, and engineering resource allocation. Device type and application dictate FDA predicate selection, while communication technology shapes FCC authorization complexity and power envelope constraints.
Device Type:
FDA electromagnetic compatibility limits and FCC Part 15 authorization requirements fragment compliance burdens across form factors, with sub-1-watt power envelopes governing design trade-offs.
- Wearable Monitors:Battery-powered instruments integrating MEMS sensors with Bluetooth 5.3 subsystems for continuous cardiac and metabolic data transmission. Demand concentrates in Medicare-reimbursed remote patient monitoring programs across United States home health agencies, where 14-day wear duration drives disposable economics and recurring revenue models.
- Wireless Diagnostic Devices:Networked instruments transmitting physiological data to clinical decision systems via Wi-Fi or cellular protocols, typically operating at higher power budgets than wearables. Hospital procurement departments in Germany and France prioritize these for inpatient telemetry, though home health agencies are gaining contracting authority for ambulatory deployment.
- Handheld Sensors:Point-of-care instruments with intermittent connectivity for spot measurements.
- Smart Pill Bottles:Cellular-enabled containers for adherence verification in clinical trials.
Established volume favors wearable monitors; emerging adoption favors wireless diagnostic devices.
Application:
Reimbursement codes and clinical evidence requirements create divergent margin profiles across use cases, with hospital-at-home programs redrawing demand geography.
- Remote Patient Monitoring:Ambulatory data transmission enabling therapy adjustment without facility encounters, governed by FDA quality system regulation for post-market surveillance. United States Medicare reimbursement structures drive provider purchasing decisions, while EU MDR clinical evidence requirements tighten for cloud-stored biometric data.
- Medication Management:Smart pill bottles and adherence sensors integrating cellular connectivity for real-time verification in pharmaceutical trials. North American contract research organizations represent concentrated demand as decentralized trials expand, with lower competitive density than cardiac monitoring segments.
- Chronic Disease Management:Longitudinal monitoring for diabetes, heart failure, and COPD with integrated clinical decision support.
- Health and Fitness Tracking:Consumer-accessible devices operating at the wellness-clinical boundary, facing compressed FDA clearance timelines.
Procurement authority concentrates in remote patient monitoring; medication management shows steepest expansion trajectory as clinical trials decentralize.
End User:
Technical integration capabilities and regulatory liability exposure segment buyer requirements, with procurement authority migrating from hospital IT to clinical operators.
- Healthcare Providers:Hospital systems and physician practices requiring FDA-cleared devices with EHR integration and adverse event reporting infrastructure. United States accountable care organizations prioritize total cost of ownership over upfront device cost, driving volume toward vendors offering integrated platforms with nursing support.
- Home Care Providers:Agencies managing post-acute patient oversight through hospital-at-home programs, now holding direct contracting power previously held by hospital procurement departments. European notified body relationships prove decisive for GDPR-compliant cloud data residency.
- Patients:Direct consumers accessing over-the-counter or prescription-monitored devices.
- Research Institutions:Academic medical centers and contract research organizations demanding protocol-specific customization.
Institutional volume anchors healthcare providers; home care providers represent the fastest-growing customer type as hospital-at-home scales.
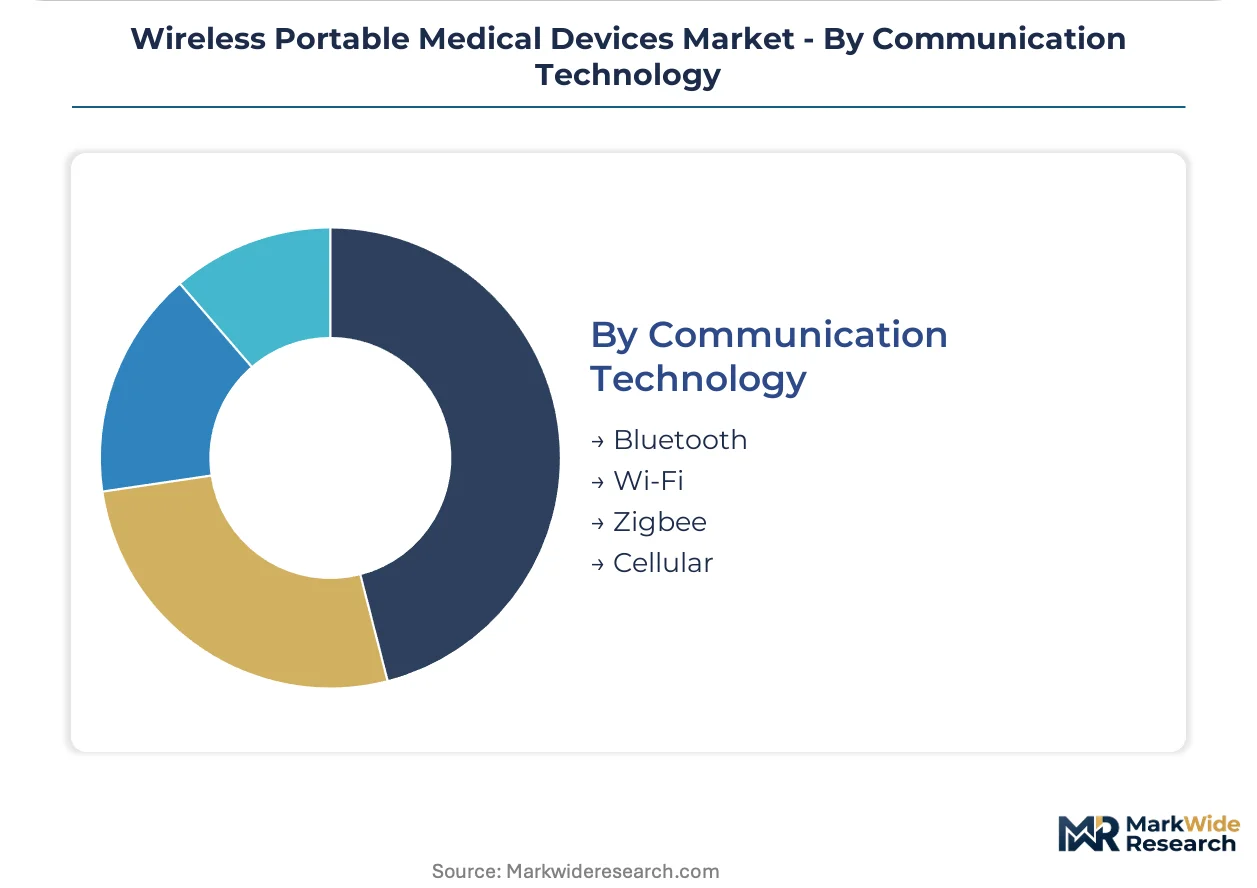
Communication Technology:
Spectrum allocation and power constraints govern device architecture, with dual-protocol flexibility emerging as a competitive differentiator in institutional settings.
- Bluetooth:2.4 GHz ISM band protocol dominating wearable monitors with sub-1-watt power envelopes and pre-certified subsystem availability from Taiwan and South Korea contract manufacturers. FDA clearance pathway compression for Bluetooth-enabled continuous glucose monitors is collapsing barriers between consumer wellness and clinical-grade categories.
- Cellular:Wide-area connectivity enabling real-time adherence verification and rural patient coverage, with higher power budgets and carrier certification requirements. Smart pill bottles in North American clinical trials depend on cellular for ubiquitous connectivity outside Wi-Fi range.
- Wi-Fi:Higher throughput protocol for wireless diagnostic devices in hospital settings.
- Zigbee:Sub-1-watt mesh networking protocol for inpatient telemetry in European and United States hospitals.
Bluetooth captures unit volume leadership; cellular and Zigbee are gaining share fastest as medication management and institutional mesh networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes wireless portable medical devices through Medicare-reimbursed remote patient monitoring programs, while Germany and Japan favor hospital-procured diagnostic instruments with stricter MDR compliance, and South Korea leverages domestic semiconductor fabrication for wearable component supply.
United States
Hospital-at-home programs and Medicare Advantage plans drive demand for Bluetooth-enabled cardiac and metabolic monitors. FDA quality system regulation governs design controls and post-market surveillance for all wireless medical devices. The Minneapolis-St. Paul corridor anchors Medtronic's sensor fabrication operations, while Boston's Route 128 cluster concentrates RF engineering talent for FDA submission preparation.
Germany
Hospital procurement departments prioritize wireless diagnostic devices with EHR integration and extended inpatient telemetry capabilities. EU MDR clinical evidence requirements tighten for cloud-stored biometric data from Bluetooth-linked cardiac wearables. The Baden-Württemberg region around Stuttgart hosts Siemens Healthineers' development centers for hospital-grade connectivity systems.
Japan
Metropolitan healthcare systems deploy sub-1-watt mesh networks for inpatient telemetry, creating demand for dual-protocol Bluetooth-Zigbee devices. PMDA and METI jointly oversee electromagnetic compatibility certification and post-market safety monitoring. The Kansai region around Osaka concentrates Omron Healthcare's manufacturing footprint for home-use blood pressure and glucose monitoring equipment.
South Korea
Domestic MEMS foundries supply miniaturized glucose and cardiac sensing elements to wearable OEMs across Asia-Pacific. MFDS regulates software-as-medical-device submissions with accelerating pathways for AI-enabled diagnostic algorithms. The Seoul Capital Area anchors Samsung Electronics' system-on-chip design centers for ultra-low-power medical device processors.
United Kingdom
Accountable care organizations prioritize total cost of ownership in wireless monitor procurement, favoring vendors with integrated nursing support services. MHRA post-Brexit regulatory frameworks align with EU MDR for CE marking continuity. The Cambridge-Oxford-London triangle concentrates early-stage RF engineering ventures and notified body relationships for GDPR-compliant cloud data residency.
Wireless Portable Medical Devices Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Wireless Portable Medical Devices landscape. The upper tier commands captive sensor fabrication and in-house RF engineering centers that compress design-to-submission timelines. Mid-scale specialists compete through focused application expertise in continuous glucose monitoring or cardiac telemetry. Dominant competitive moves include backward integration into MEMS supply and strategic partnerships with contract manufacturers in Taiwan and South Korea for pre-certified Bluetooth subsystems.
Among diversified health technology conglomerates, GE Healthcare and Siemens Healthineers occupy positions spanning hospital diagnostic systems and portable connectivity platforms. Philips Healthcare exemplifies the integrated-leader archetype through its captive RF engineering infrastructure. Dexcom and Abbott Laboratories represent the specialist tier with concentrated focus on metabolic monitoring wearables. Medtronic anchors the cardiac-monitoring vector through upstream control over critical sensor supply chains.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Medtronic |
| Omron Healthcare |
| Abbott Laboratories |
| Dexcom |
| Siemens Healthineers |
| Samsung Electronics |
| Boston Scientific Corporation |
| Others |
Value Chain & Pricing Dynamics
FDA electromagnetic compatibility limits and FCC Part 15 certification gates both supply qualification and price differentiation simultaneously, compressing margins for manufacturers lacking pre-certified Bluetooth subsystems while rewarding integrated leaders with captive RF engineering centers. Medicare reimbursement codes for remote patient monitoring create tiered demand elasticity across home health agencies and hospital systems.
Pricing Analysis
Long-term offtake contracts dominate procurement between wireless monitor OEMs and Taiwan-based contract manufacturers, with spot purchasing confined to MEMS sensor spot markets. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance tier, volume scale, and after-sales service bundling. Cost compression in standard-tier Bluetooth wearables is intensifying because pre-certified subsystem availability erodes historical RF engineering premiums. Home health agencies exhibit highest price sensitivity, while hospital systems prioritize total cost of ownership over per-unit acquisition cost.
Supply Chain Analysis
Inventory lead times for MEMS glucose sensors stretch 16-22 weeks, constraining production scheduling for wearable monitor OEMs. Supply concentrates in Taiwan for Bluetooth subsystems, South Korea for ultra-low-power system-on-chip processors, and the United States for FDA submission preparation infrastructure. Critical dependencies include silicon wafers, lithium-polymer batteries, and medical-grade polymers. Single-source vulnerability in Taiwan-based contract manufacturing for pre-certified RF modules threatens continuity. Distribution runs through hospital procurement departments, home health agency direct contracts, and pharmaceutical trial logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is emerging from a cyclical trough driven by FDA clearance pathway compression for Bluetooth-enabled continuous glucose monitors, which resets competitive timelines and opens acquisition windows for integrated players.
For Market Incumbents: Consolidate backward integration into MEMS sensor fabrication to defend against emerging fabless entrants leveraging Taiwan contract manufacturers. Lock long-term offtake agreements with South Korean foundries for ultra-low-power processors. Prioritize CE marking investment ahead of EU MDR enforcement tightening for cloud-stored biometric data.
For New Entrants and Emerging Players: Lead with medication management applications in North American clinical trials, where smart pill bottle demand runs ahead of cardiac monitoring competitive density. Target accountable care organization procurement committees with integrated remote patient monitoring platforms bundled with nursing support services. Pursue FDA 510(k) clearance for AI-enabled arrhythmia detection ahead of predicate rule finalization.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across Bluetooth wearable subsystems as contract manufacturers capture scale economies, compressing returns for capital-heavy integrated models. Favor acquisition targets with established European notified body relationships and GDPR-compliant cloud infrastructure. Watch FDA guidance publication timing on machine-learning-based diagnostic algorithms as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Acceleration | Bluetooth-enabled CGM clearances are collapsing wellness-clinical category barriers. |
| CE Marking Pathway Investment | EU MDR clinical evidence requirements tighten for cloud-stored cardiac biometric data. |
| Hospital System Partnership | Medicare Advantage plans steer volume toward integrated remote patient monitoring platforms. |
| Software Companion Development | AI-enabled arrhythmia detection predicates reshape R&D allocation across competitive set. |
| Reimbursement Strategy | CMS remote patient monitoring codes directly determine provider purchasing decisions. |
Study Parameters
A spread of perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and home health agency clinical directors converged on the working assumptions. Primary interviews combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body guidance. Bottom-up unit demand modeling triangulated against top-down addressable market sizing across the analysis window.
Segmentation dimensions modeled include device type, application, end user, and communication technology across the projection horizon. CAGRs derived from weighted average of historical growth patterns and forward-looking reimbursement policy trajectories. Forecast inputs incorporated MEMS sensor miniaturization curves and FCC Part 15 authorization timeline compression.
Forecasts assume regulatory continuity in FDA quality system regulation and EU MDR enforcement; material policy shifts would require re-modeling. Revision becomes warranted when FDA predicate rule publication for AI-enabled diagnostics crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Collateral Ligament Stabilizer System Market
Medical Devices
Cyberknife Technology Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Suction Catheters Market
Medical Devices
Global Plastic Surgery Devices Market
Medical Devices
Cervical Dilators Market
Medical Devices
Radiofrequency-Based Aesthetic Devices Market
Medical Devices
North America 3D Printing in Healthcare Market
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Artificial Retina Market
Medical Devices
Canada Ultrasound Devices Market
Medical Devices
Ingestible Thermometers Market
Medical Devices
Global Anesthesia Gas Blender Market