
 Kidney Stone Management Devices Market | 2026-2036
Kidney Stone Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Kidney Stone Management Devices Market Intelligence
The capability gap between large-scale R&D investment and niche procedural specialization is collapsing as minimally invasive techniques become standard. Boston Scientific Corporation leverages its extensive distribution network to dominate the ureteral stent and basket catheter segments. Olympus Corporation sustains its market position through leadership in advanced flexible ureteroscopy and visualization technologies. KARL STORZ SE & Co. KG specializes in high-quality rigid and semi-rigid nephroscopes for percutaneous nephrolithotomy.
Kidney stone management devices encompass a range of instruments used for the diagnosis, treatment, and removal of calculi from the urinary tract. These devices, including laser fibers with core diameters as small as 200 microns, are designed to facilitate minimally invasive procedures like ureteroscopy. Ureteral stents and laser fibers represent high-volume, recurring revenue streams within the product mix. In terms of application, ureteroscopy procedures are outpacing traditional shock wave lithotripsy due to higher stone-free rates, particularly in urology clinics and ambulatory surgical centers.
Market access is governed by stringent regulatory approvals, including the FDA's 510(k) pathway in the United States and CE marking under the Medical Device Regulation (MDR) in Europe. In China, the NMPA's registration process sets a high bar for market entry, influencing device design and material selection to meet local standards. Device manufacturers must now decide whether to prioritize investment in reusable or single-use endoscopes to align with evolving hospital sterilization protocols and cost-containment pressures.
Market Dynamics
The central force shaping the market is the procedural shift from traditional hospitals to ambulatory surgical centers. This migration prioritizes efficiency, rapid patient turnover, and cost-effective, minimally invasive technologies, influencing device design and purchasing decisions across the board.
Growth Catalysts
- Miniaturization Advances:The development of smaller, more flexible ureteroscopes and laser fibers with core diameters under 200 microns enables access to more complex anatomies with reduced patient trauma.
- Ambulatory Center Growth:Ambulatory surgical centers are expanding their urological service lines, driving demand for devices that support high-volume, efficient outpatient procedures.
- Advanced Healthcare Systems:High procedural volumes in geographies like Germany, supported by comprehensive reimbursement, sustain consistent demand for premium stone management devices.
Market Restraints
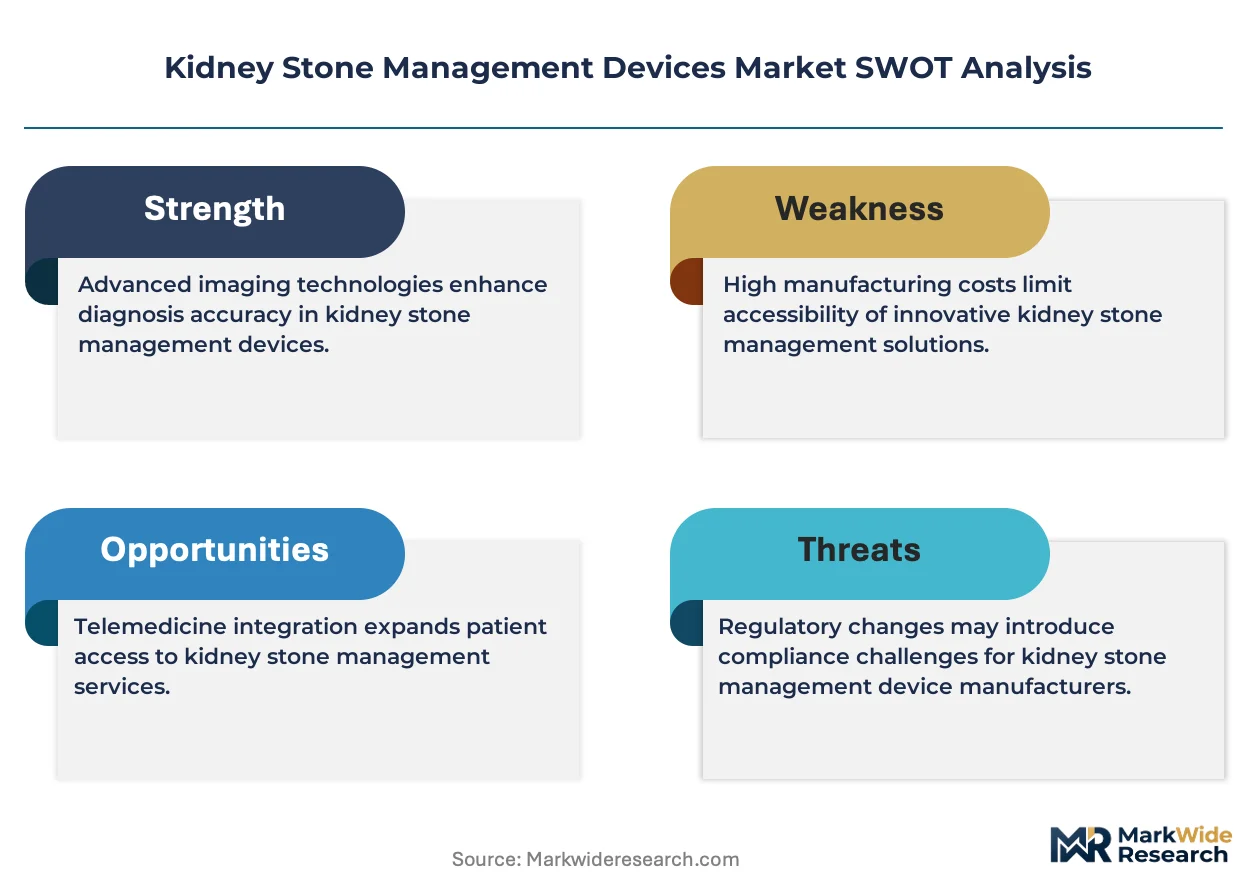
- Capital Equipment Costs:The high acquisition cost of advanced holmium or thulium laser systems and digital ureteroscopes can be a significant barrier for smaller clinics or hospitals in price-sensitive regions.
- Regulatory Hurdles:Stringent pre-market approval processes, including the FDA's 510(k) pathway and Europe's MDR, create long development timelines and increase compliance costs for new devices.
- ESWL Persistence:Extracorporeal shock wave lithotripsy remains a viable, non-invasive option for specific stone types and locations, representing a persistent substitution threat to instrument-based procedures.
Strategic Opportunities
- Single-Use Endoscopes:The development of cost-effective, disposable ureteroscopes addresses hospital concerns regarding sterilization costs, cross-contamination risks, and device downtime for repairs.
- Emerging Market Expansion:Increasing healthcare expenditure and a rising middle class in countries across Asia and Latin America present significant growth opportunities for device manufacturers.
- Thulium Fiber Laser Adoption:The superior efficiency and dusting capabilities of thulium fiber lasers offer a chance for manufacturers to displace older holmium laser technologies.
Industry Challenges
- Specialist Skill Gaps:A shortage of urologists proficient in complex endourological procedures, such as percutaneous nephrolithotomy, limits the adoption of associated specialized devices in certain regions.
- Reprocessing Complexity:Hospitals face significant operational and financial challenges in adhering to stringent sterilization protocols for reusable flexible ureteroscopes, risking device damage and procedural delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kidney Stone Management Devices Market |
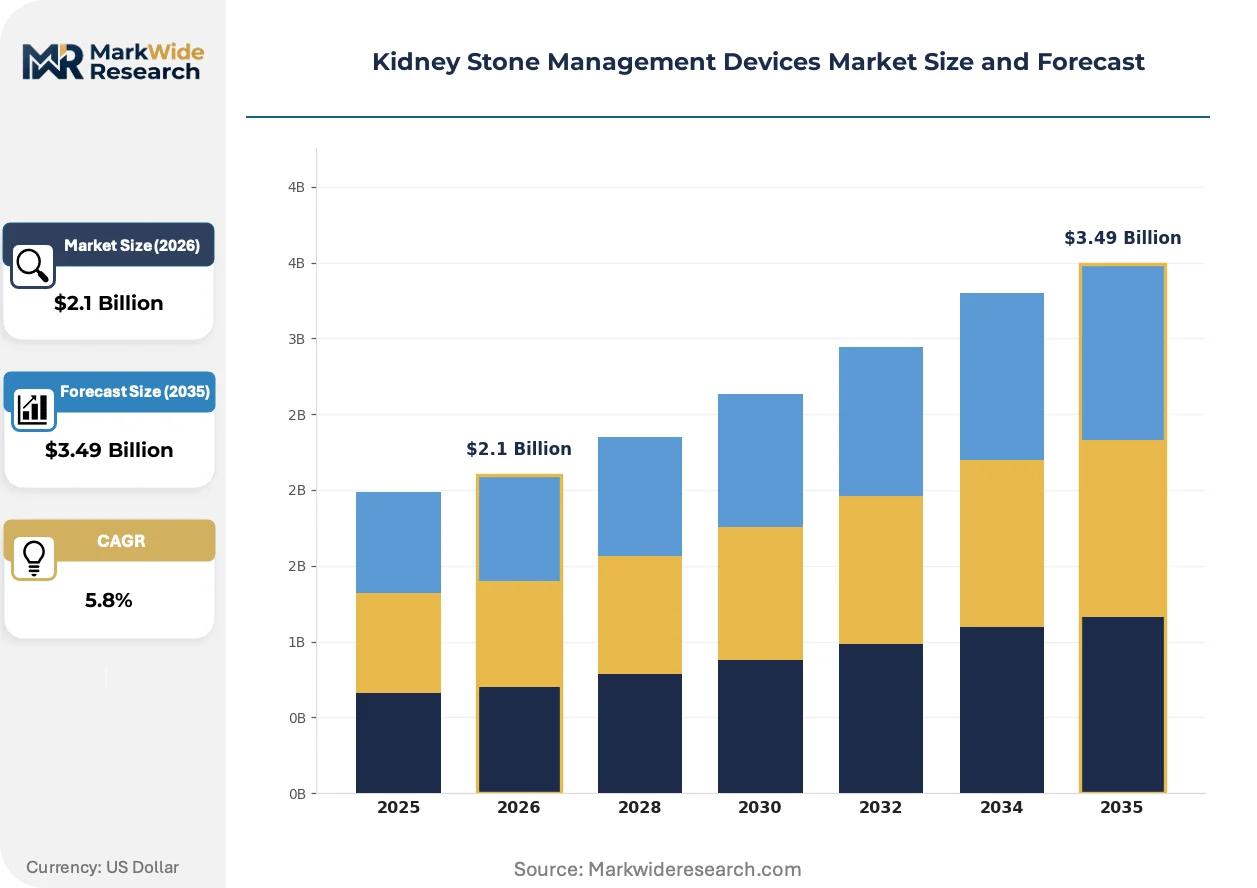
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shock Wave Lithotripters, Ureteral Stents, Nephroscopes, Laser Fibers, Basket Catheters Application: Stone Fragmentation, Ureteral Obstruction Relief, Percutaneous Nephrolithotomy, Ureteroscopy Procedures, Extracorporeal Treatment End User: Urology Clinics, Ambulatory Surgical Centers, Diagnostic Laboratories, Specialty Hospitals, Physician Offices Technology: Laser, Ultrasound, Electrohydraulic, Pneumatic, Electromagnetic |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, KARL STORZ SE & Co. KG, Cook Medical Inc., Richard Wolf GmbH, Dornier MedTech GmbH, EDAP TMS SA, Stryker Corporation, Coloplast A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kidney Stone Management Devices Market Strategic Shifts & Innovations
A fundamental tension between advanced reusable systems and emerging single-use technologies is reshaping the market. This dynamic forces healthcare providers to balance long-term capital investment against operational flexibility and infection control mandates.
Single-use digital ureteroscopes integrate imaging and illumination into a disposable device, eliminating reprocessing requirements. Ambulatory surgical centers and hospitals are adopting these instruments to increase procedural throughput and mitigate cross-contamination risks. This adoption is fragmenting the established market for reusable capital equipment, creating new competitive dynamics.
Europe's Medical Device Regulation (MDR) establishes more rigorous requirements for clinical evidence and post-market surveillance. This regulation increases the compliance burden and cost for manufacturers of devices like ureteral stents and laser systems. Consequently, companies targeting the EU must now dedicate greater resources to lifecycle management and data collection to maintain CE marking.
Hospital procurement is evolving from capital expenditure on reusable devices toward operational models favoring single-use instruments. This change disrupts the traditional sales cycle, which has long centered on large equipment purchases and associated service contracts. The shift is most visible in the United States, where cost-containment and risk management are primary administrative concerns.
Kidney Stone Management Devices Market Segmentation
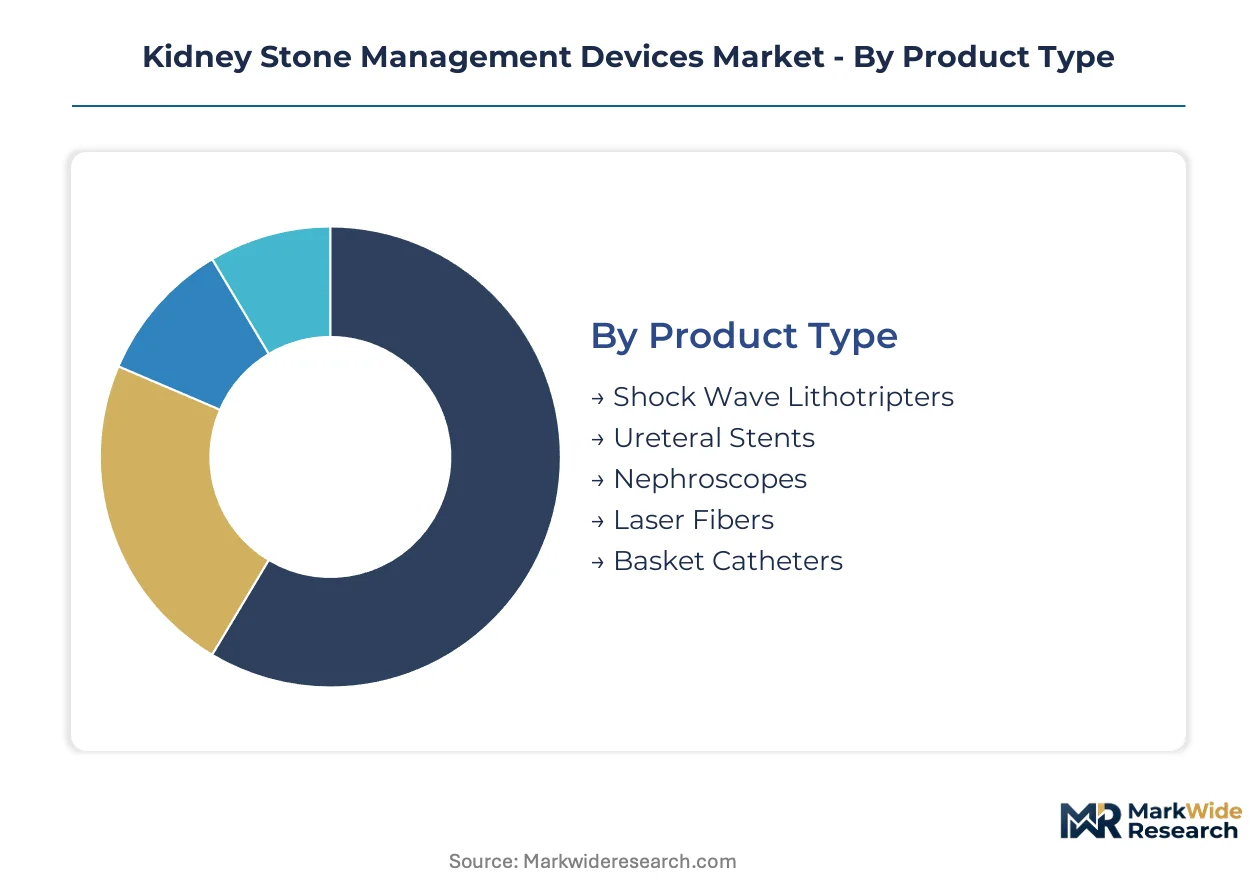
Segmentation within the kidney stone management devices market provides a granular view of product utility, application-specific demand, and end-user adoption patterns. This detailed categorization helps manufacturers align product development with evolving clinical needs and procurement priorities across different healthcare settings.
Product Type:
The market for kidney stone management devices is characterized by a diverse channel mix, with specific product types flowing through specialized procurement pathways.
- Ureteral Stents:These are flexible, hollow tubes inserted into the ureter to ensure urine flow from the kidney to the bladder, primarily for obstruction relief. Demand is concentrated in both hospitals and ambulatory surgical centers due to their high-volume, recurring use in post-procedure management.
- Laser Fibers:These devices, with core diameters as small as 200 microns, deliver laser energy for stone fragmentation during ureteroscopy. Miniaturization advances drive their adoption in minimally invasive procedures, especially in settings prioritizing reduced patient trauma.
- Shock Wave Lithotripters:Non-invasive systems that use focused shock waves to break kidney stones into smaller fragments for natural passage.
- Nephroscopes:Instruments used for direct visualization and instrumentation within the kidney, particularly during percutaneous nephrolithotomy procedures.
- Basket Catheters:Devices designed to capture and extract stone fragments from the urinary tract during endoscopic procedures.
Ureteral stents dominate the installed base. Laser fibers are where expansion concentrates.
Application:
Application segmentation highlights the procedural focus within kidney stone management, guiding device design and clinical adoption.
- Ureteroscopy Procedures:This minimally invasive technique involves inserting a ureteroscope into the urinary tract to visualize and treat kidney stones. These procedures are outpacing traditional shock wave lithotripsy due to higher stone-free rates, particularly in urology clinics and ambulatory surgical centers.
- Percutaneous Nephrolithotomy:A surgical procedure to remove large kidney stones directly from the kidney through a small incision in the back. This application requires specialized nephroscopes and is limited by specialist skill gaps in certain regions.
- Stone Fragmentation:The general process of breaking down kidney stones into smaller, manageable pieces using various energy sources.
- Ureteral Obstruction Relief:Procedures aimed at alleviating blockages in the ureter, often involving the placement of ureteral stents.
- Extracorporeal Treatment:Non-invasive methods like shock wave lithotripsy, used for specific stone types and locations.
Ureteroscopy procedures currently command the largest share of device utilization. Percutaneous nephrolithotomy procedures represent the fastest-growing trajectory.
End User:
End-user categories reflect the evolving landscape of care delivery, influencing purchasing decisions and device preferences.
- Ambulatory Surgical Centers:Outpatient facilities focused on efficient, rapid patient turnover for surgical procedures. These centers are expanding their urological service lines, driving demand for cost-effective, minimally invasive devices.
- Urology Clinics:Specialized medical practices providing diagnostic, therapeutic, and preventive care for urological conditions. These clinics are primary sites for high-volume ureteroscopy procedures.
- Specialty Hospitals:Healthcare institutions dedicated to specific medical disciplines, often equipped for complex kidney stone management cases.
- Diagnostic Laboratories:Facilities providing analytical services crucial for identifying stone composition and guiding treatment strategies.
- Physician Offices:Primary care or specialist offices where initial diagnosis and follow-up care for kidney stone patients often occur.
Ambulatory surgical centers exhibit the most significant growth in procedural volume. Urology clinics maintain a substantial foundational patient base.
Technology:
Technology differentiation underpins device efficacy and procedural innovation, shaping investment priorities for manufacturers.
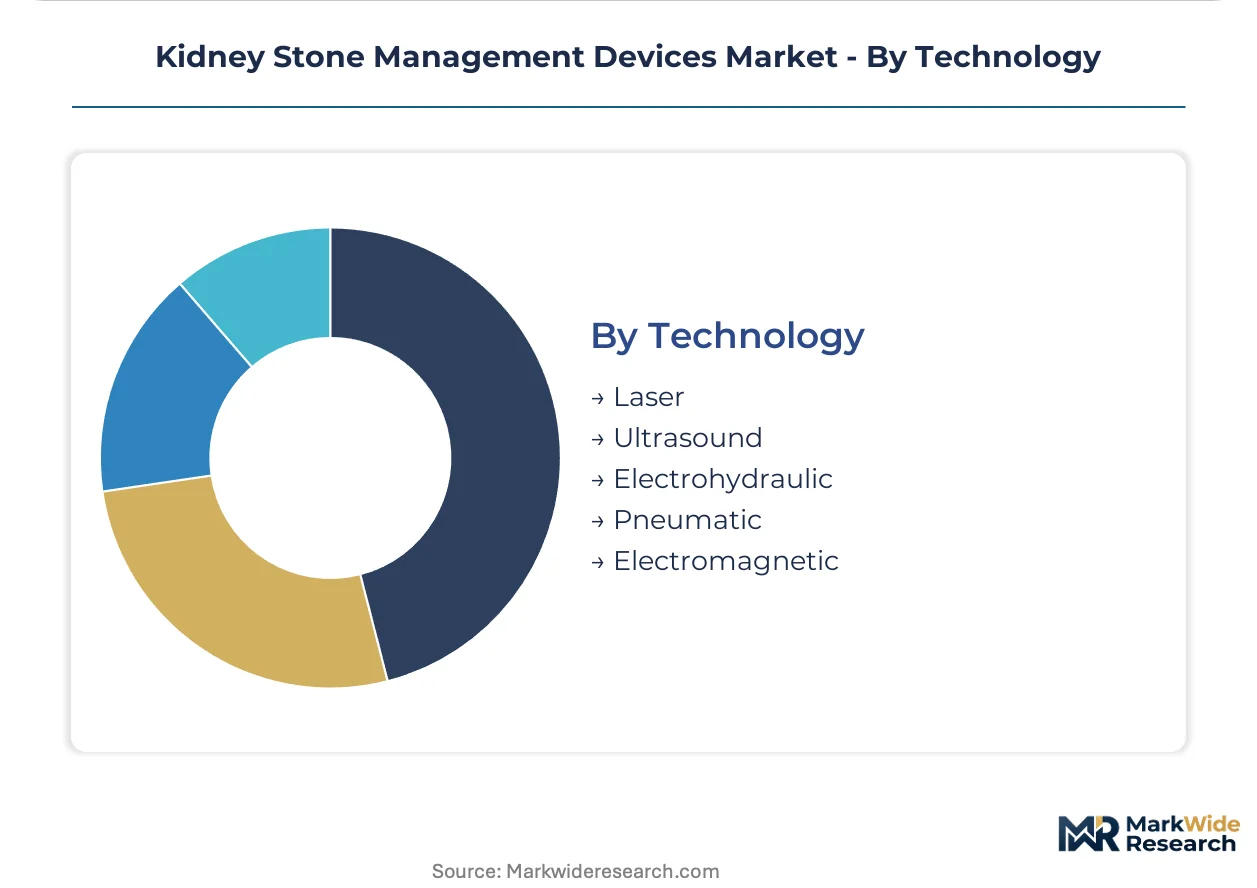
- Laser:Utilizes focused laser energy (e.g., holmium, thulium fiber) for precise fragmentation and dusting of kidney stones. Thulium fiber lasers offer superior efficiency, driving adoption in advanced urology practices.
- Ultrasound:Employs high-frequency sound waves for diagnostic imaging, stone localization, and, in some cases, fragmentation. Ultrasound is frequently used for real-time guidance during percutaneous nephrolithotomy.
- Electrohydraulic:Uses electrical discharges to create shockwaves for stone fragmentation, often employed in conjunction with endoscopes.
- Pneumatic:Utilizes compressed air to generate mechanical impact, breaking down stones through direct contact.
- Electromagnetic:A technology primarily used in extracorporeal shock wave lithotripsy systems to generate shock waves.
Laser technology holds the largest share of advanced stone fragmentation procedures. Ultrasound technology demonstrates steady utility in diagnostic and guidance roles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exhibits a demand concentration for premium kidney stone management devices, driven by its advanced healthcare system and high procedural volumes. The United States market, conversely, prioritizes rapid patient turnover and cost-effective, minimally invasive technologies in ambulatory surgical centers. This differential influences device design and procurement strategies across these key regions.
United States
Demand for single-use endoscopes is rising in ambulatory surgical centers due to efficiency gains. The FDA's 510(k) pathway governs market access and device innovation. Major medical device hubs like Boston and Minneapolis drive research into miniaturized ureteroscopes and flexible laser fibers.
Germany
High procedural volumes and comprehensive reimbursement sustain consistent demand for advanced stone management devices. European MDR establishes rigorous requirements for clinical evidence and post-market surveillance. Munich and Tuttlingen host clusters of medical technology manufacturers specializing in urological instruments.
China
Increasing healthcare expenditure and a rising middle class are expanding the patient base for kidney stone treatments. The NMPA's registration process sets a high bar for market entry, influencing device design. Shanghai and Shenzhen are emerging as centers for local device manufacturing and distribution.
Japan
An aging population and advanced medical infrastructure contribute to steady demand for minimally invasive urological procedures. The PMDA regulates medical device approvals, ensuring high safety and efficacy standards. Tokyo's medical technology sector focuses on precision instruments and advanced laser systems for stone fragmentation.
India
Growing awareness and improving healthcare access are increasing the utilization of kidney stone management devices. Government initiatives, including the PLI scheme, encourage domestic manufacturing and reduce import reliance. Bengaluru and Pune are becoming significant R&D and production hubs for medical equipment.
Kidney Stone Management Devices Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the kidney stone management devices market. This structure combines highly consolidated segments, such as ureteral stents, with more fragmented niches for specialized instruments like single-use endoscopes. Strategic archetypes include diversified medical device conglomerates, focused endourology specialists, and emerging technology innovators. Companies are actively pursuing portfolio diversification and strategic partnerships to navigate evolving clinical needs and regulatory landscapes.
Within the established medical device landscape, Boston Scientific Corporation and Olympus Corporation exemplify leaders with extensive product portfolios and global distribution networks. Boston Scientific Corporation focuses on high-volume segments like ureteral stents and basket catheters, leveraging its market reach. KARL STORZ SE & Co. KG, a German-based company, anchors the premium segment for high-quality rigid and semi-rigid nephroscopes used in complex procedures. These companies collectively demonstrate how deep specialization or broad market penetration defines competitive positioning.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| KARL STORZ SE & Co. KG |
| Cook Medical Inc. |
| Richard Wolf GmbH |
| Dornier MedTech GmbH |
| EDAP TMS SA |
| Stryker Corporation |
| Coloplast A/S |
| Others |
Cost & Logistics Intelligence
Single-use endoscopes replacing reusable capital equipment simultaneously reshapes procurement patterns and introduces new cost-per-procedure pricing economics. This dynamic forces manufacturers to re-evaluate production locations and distribution strategies to meet evolving market demands.
Pricing Analysis
After-sales service and recurring consumable revenue streams drive lifetime value for advanced kidney stone management systems. The pricing structure stratifies across premium, standard, and economy tiers, influenced by device sophistication and regulatory approvals like FDA clearance. Price differentiation stems from the quality grade of laser fibers and the brand premium associated with established manufacturers. Pricing pressure stems from ambulatory surgical centers prioritizing cost-effective, high-volume solutions. Ambulatory surgical centers exhibit the highest price sensitivity, while specialty hospitals prioritize advanced features and clinical outcomes.
Supply Chain Analysis
Specialized optical components and medical-grade polymers represent a chokepoint in the kidney stone management device supply chain. Manufacturing concentrates significantly in Germany for high-precision instruments and in the United States for advanced laser systems. Raw material dependencies include rare earth elements for laser fibers and specific biocompatible plastics for ureteral stents. Regulatory restrictions, particularly CE marking under Europe's MDR, create a structural risk by increasing compliance costs. Distribution runs through established direct sales forces and specialized medical device distributors, particularly for high-volume consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kidney stone management devices market presents a defensive moat story, primarily due to regulatory entrenchment. Stringent FDA and CE marking requirements create high barriers to entry, protecting established players with approved product portfolios.
For Market Incumbents: Compound existing market share by investing heavily in miniaturization R&D for ureteroscopes and laser fibers. Diversify product portfolios to include both reusable and single-use endoscopes, mitigating the threat of displacement by emerging disposable technologies. Strengthen channel control within ambulatory surgical centers to ensure consistent product uptake and defend against new entrants. This strategy addresses the persistent substitution threat from extracorporeal shock wave lithotripsy.
For New Entrants and Emerging Players: Differentiate on cost-effectiveness and specialized procedural outcomes, targeting the growing segment of ambulatory surgical centers. Focus on developing innovative single-use devices that reduce reprocessing complexity and cross-contamination risks for hospitals. The most penetrable segment remains high-volume, minimally invasive ureteroscopy procedures. A value-based procurement approach, demonstrating clear cost savings and clinical benefits, can accelerate market penetration.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with niche technology specialists possessing strong intellectual property in laser or visualization technologies. The market offers long-term viability driven by an aging global population and rising stone prevalence. Identify acquisition targets with established regulatory pathways and robust distribution networks in key growth regions like China and India. The adoption rate of thulium fiber lasers serves as a critical signal to watch for technological inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Securing European market access for new devices is crucial for global revenue growth. |
| FDA 510(k) Submission Prioritization | Expediting regulatory clearance in the United States enables faster market entry for innovative products. |
| Hospital System Partnership Development | Forging alliances with large hospital networks ensures stable procurement channels and product adoption. |
| Miniaturized Ureteroscope R&D | Developing smaller, more flexible instruments expands treatment options for complex anatomies. |
| Thulium Fiber Laser Integration | Incorporating advanced laser technology improves stone fragmentation efficiency and patient outcomes. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings within this analysis. The study involved extensive discussions with key industry stakeholders, including urologists, hospital purchasing committees, device R&D engineers, and GPO contracts managers. Secondary validation drew from FDA filings, CE marking databases, medical device industry reports, and company financial disclosures. This approach ensured a robust bottom-up and top-down triangulation of market insights.
Sensitivity analysis framed the forecast framework, which integrated a comprehensive analytical model across the analysis window. Segmentation dimensions modeled included product type, application, end-user, technology, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical market trends, projected procedural volumes, and anticipated device miniaturization rates. Key forecast inputs included evolving healthcare reimbursement policies and technological advancements in stone fragmentation.
Material uncertainties — including rapid technological shifts and unforeseen regulatory changes — sit outside the modeled envelope. Forecasts reflect a specific set of assumptions regarding market dynamics and competitive landscape. Practitioners should keep alternative scenarios live as healthcare policy reforms and clinical practice guidelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
Osteotomy Plates Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
In Vitro and in Vivo Microelectrode Array Market
Medical Devices
C-Arms Devices Market
Medical Devices
Coronary Guidewires Market
Medical Devices
Global Pessary Market
Medical Devices
Contraceptive Devices Market
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Japan Respiratory Devices Market
Medical Devices
Medical Smart Wearable Devices Market
Medical Devices
Light Therapy Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market