
 North America HVAC Cables Market | 2026-2036
North America HVAC Cables Market Size, Share, and Industry Trends Forecast 2026-2036
North America HVAC Cables Market Analysis
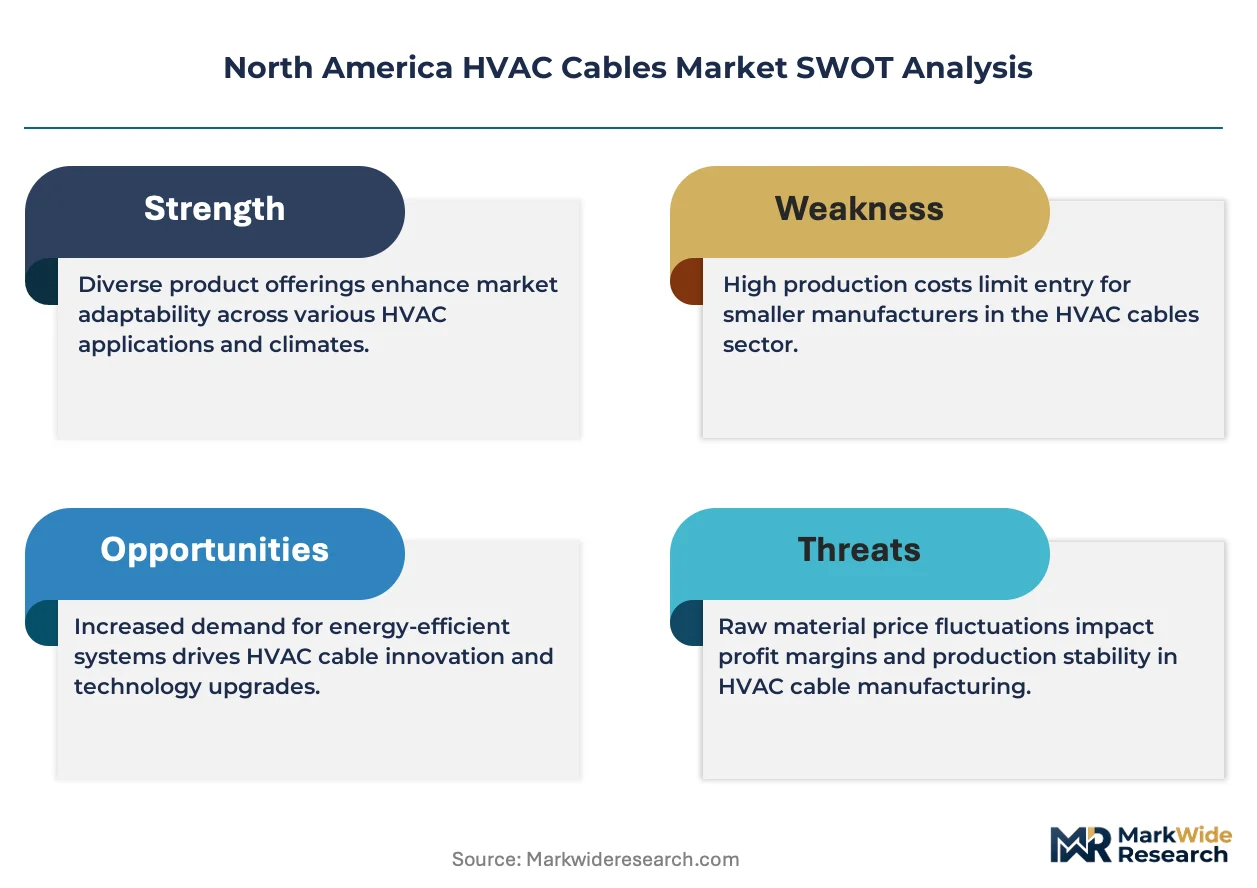
Wholesale distribution networks for electrical supplies is tilting toward specialized HVAC cable portfolios as contractors consolidate purchasing power. Prysmian Group leverages its North American manufacturing footprint to sustain delivery reliability across volatile copper markets. Southwire anchors its position through extensive contractor loyalty programs and regional distribution partnerships. Nexans competes on fluoropolymer and cross-linked polyethylene expertise for high-temperature commercial installations.
North America HVAC cables are insulated electrical conductors engineered for heating, ventilation, air conditioning, and refrigeration systems, typically rated between 600V and 2000V with thermoplastic or thermoset jackets resisting moisture, oil, and temperature cycling. These cables distribute power from service panels to compressors, fan motors, and control circuits in buildings and industrial facilities. Thermoset products dominate value pools due to superior thermal endurance in rooftop and mechanical room environments, while metal-clad variants gain traction in industrial end-user segments where physical protection requirements are stringent. Specialty cables incorporating low-smoke zero-halogen compounds represent the fastest-expanding product type as commercial and government end users enforce stricter fire safety protocols.
The National Electrical Code, enforced by local authorities having jurisdiction across the United States, mandates ampacity and insulation ratings that directly determine cable selection for HVAC circuits. Canada's Electrical Code, administered by provincial regulators, imposes parallel standards that shape cross-border product harmonization for manufacturers serving both markets. Mexico's national electrical standards, overseen by the national standardization body, create additional compliance layers for integrated North American supply chains. Stakeholders must monitor evolving energy efficiency standards that will progressively dictate conductor sizing and material specifications for connected equipment.
Market Dynamics
The EPA's phasedown of hydrofluorocarbons under the AIM Act is compressing equipment replacement cycles across the United States, forcing wholesale cable procurement adjustments as contractors retrofit commercial buildings with compliant HVAC systems.
Growth Catalysts
- AIM Act Compliance Deadlines:The EPA's phasedown schedule mandates refrigerant transitions that accelerate HVAC unit replacements, pulling forward cable demand in commercial and industrial installations across the United States.
- Low-Smoke Zero-Halogen Mandates:Fire safety protocols in high-occupancy buildings are expanding specification of LSZH-jacketed cables for plenum and riser applications in healthcare and education facilities.
- Southern US Cooling Load Concentration:Persistent heat stress in Texas, Florida, and Arizona is driving above-average infrastructure investment in rooftop HVAC systems requiring thermoset-insulated conductors.
Market Restraints
- Copper Price Volatility:LME copper fluctuations create margin compression for distributors holding inventory, with spot price swings of 20-30 percent within single quarters disrupting contractor bidding accuracy.
- Cross-Border Certification Friction:Divergent testing requirements between UL standards in the United States and CSA certification in Canada force manufacturers to maintain parallel product lines, elevating SKU complexity.
- Aluminum Conductor Substitution:Cost-driven specification of aluminum feeder cables in large commercial projects is displacing copper in secondary distribution runs, constraining volume growth in traditional HVAC cable categories.
Strategic Opportunities
- Mexico Manufacturing Integration:Nearshoring of HVAC equipment production to Baja California and Nuevo León is creating demand for harmonized cable specifications serving integrated US-Mexico supply chains.
- Smart Building Convergence:Integration of power and data transmission in single-cable architectures for connected HVAC controls is opening specification opportunities with building automation integrators.
- Canadian Federal Green Building Incentives:The Canada Greener Homes Initiative and provincial retrofit programs are accelerating commercial building envelope and mechanical system upgrades in Ontario and British Columbia.
Industry Challenges
- Electrician Shortage in Installation Trades:The National Electrical Contractors Association reports persistent gaps in certified technician availability, extending project timelines and compressing contractor margins across the southern United States.
- Legacy Control System Integration:Retrofit projects requiring compatibility with existing pneumatic and analog control infrastructure complicate cable specification and increase engineering overhead for contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America HVAC Cables Market |
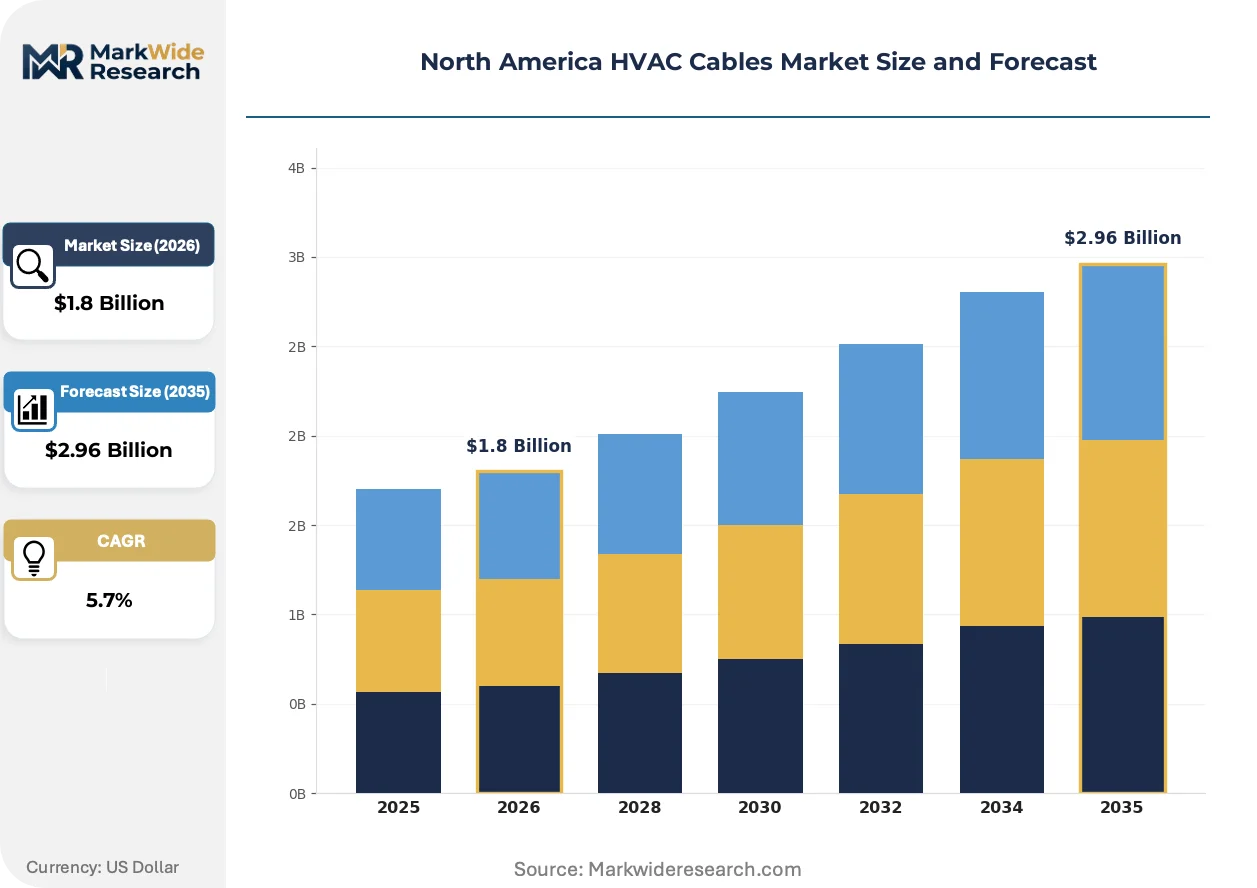
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Heating, Ventilation, Air Conditioning, Refrigeration Product Type: Thermoplastic, Thermoset, Metal-Clad, Specialty Installation Method: Indoor, Outdoor, Suspended, Surface-Mounted End User: Residential, Commercial, Industrial, Government |
| Companies Covered | Prysmian Group, Nexans, Sumitomo, NKT, Southwire, ZTT, Elsewedy Electric, Valard Construction, KEC International Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America HVAC Cables Market Emerging Trajectories
Digital integration of building systems is rewiring procurement priorities as power and data convergence reshapes cable architecture requirements across commercial construction.
Power-over-Ethernet (PoE) cabling for HVAC zone controls is digitizing thermostat and sensor networks by enabling single-circuit delivery of electricity and data to distributed equipment. Large commercial developers in Texas and California are specifying PoE-ready infrastructure in new Class A office builds. This convergence is digitizing traditional low-voltage control wiring, compressing demand for separate communication cable pulls.
The EPA's Significant New Alternatives Policy (SNAP) program is accelerating refrigerant transition timelines that force equipment replacement and rewiring. Commercial building owners face stranded asset risk from R-410A phaseout schedules, compressing depreciation cycles. The southern United States bears the highest retrofit density as cooling-dominated load profiles magnify compliance urgency.
Consolidation of electrical distributor purchasing is shifting contractor loyalty toward integrated supply houses with specialized HVAC cable inventories. Independent contractors in Florida and Arizona are consolidating spend with regional distributors offering just-in-time delivery and bulk pricing tiers. This concentration is most visible in fast-growth metropolitan construction corridors where project velocity rewards procurement efficiency.
North America HVAC Cables Market Segmentation
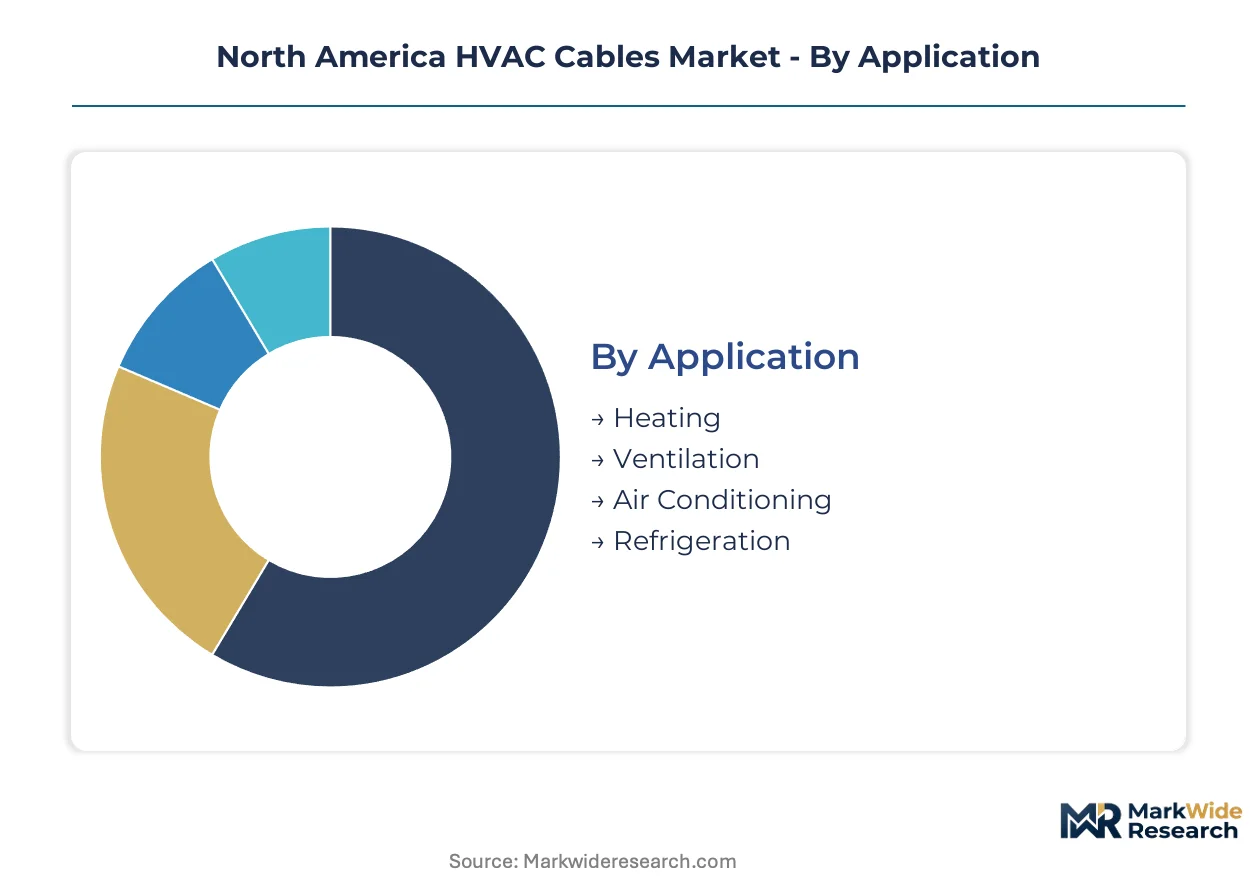
HVAC cable procurement patterns diverge sharply across application environments, with specification engineers weighting thermal endurance, fire safety protocols, and physical protection differently. Segment boundaries determine margin pools, with thermoset and specialty compounds commanding premium positioning against commodity thermoplastic alternatives.
Application:
Application segmentation tracks where thermal loads and refrigerant handling requirements concentrate specification complexity across building systems.
- Heating:Cables for boiler circuits and heat pump compressor feeds require cold-weather flexibility ratings and resistance to thermal cycling in northern US and Canadian climates. Demand clusters in Midwest and Northeast retrofit markets where natural gas-to-electric conversions are accelerating equipment replacement.
- Ventilation:Power distribution to air handling units and exhaust fans emphasizes ampacity for variable frequency drive loads in high-rise commercial cores. Texas and Florida building codes are driving specification of higher conductor counts for dedicated outdoor air systems in humid climates.
- Air Conditioning:Thermoset insulation dominates rooftop and split-system installations across the southern United States where cooling degree days compress equipment duty cycles.
- Refrigeration:Low-temperature-rated cables serve walk-in coolers and industrial cold storage in food processing corridors along the US-Mexico border.
Air conditioning holds installed capacity. Ventilation is rotating up the share rankings.
Product Type:
Material chemistry and jacket construction separate price tiers and determine suitability for mechanical stress and fire safety environments.
- Thermoplastic:PVC-jacketed conductors dominate residential and light commercial installations for cost-sensitive replacement markets. Southern US contractor preferences favor rapid-pull designs in tract housing developments where speed of installation compresses labor costs.
- Thermoset:Cross-linked polyethylene and EPR compounds deliver superior thermal endurance for rooftop units and mechanical rooms where ambient temperatures exceed standard ratings. Commercial developers in Arizona and Nevada are mandating thermoset for all projects above 75kW cooling load.
- Metal-Clad:Interlocked aluminum armor protects conductors in industrial facilities and data centers where physical damage risk elevates code requirements.
- Specialty:Low-smoke zero-halogen formulations are expanding most quickly in healthcare and education facilities across Ontario and British Columbia where provincial fire codes are tightening faster than US federal benchmarks.
Thermoset commands the value pool. Specialty compounds are climbing the fastest.
Installation Method:
Physical routing constraints determine jacket durability requirements and labor productivity tradeoffs across construction types.
- Indoor:Plenum and riser-rated cables penetrate fire-rated assemblies in high-rise commercial cores, with LSZH jackets displacing standard PVC in California and New York jurisdictions.
- Outdoor:UV-resistant and moisture-blocking compounds serve rooftop equipment pads and ground-level condensing units across the southern United States where sun exposure accelerates jacket degradation.
- Suspended:Support wire and messenger cable integration enables overhead distribution in warehouse and big-box retail construction throughout the Midwest.
- Surface-Mounted:Exposed runs in retrofit industrial facilities favor metal-clad protection where conduit installation is cost-prohibitive.
Outdoor methods dominate replacement volume. Suspended installations are gaining specification share.
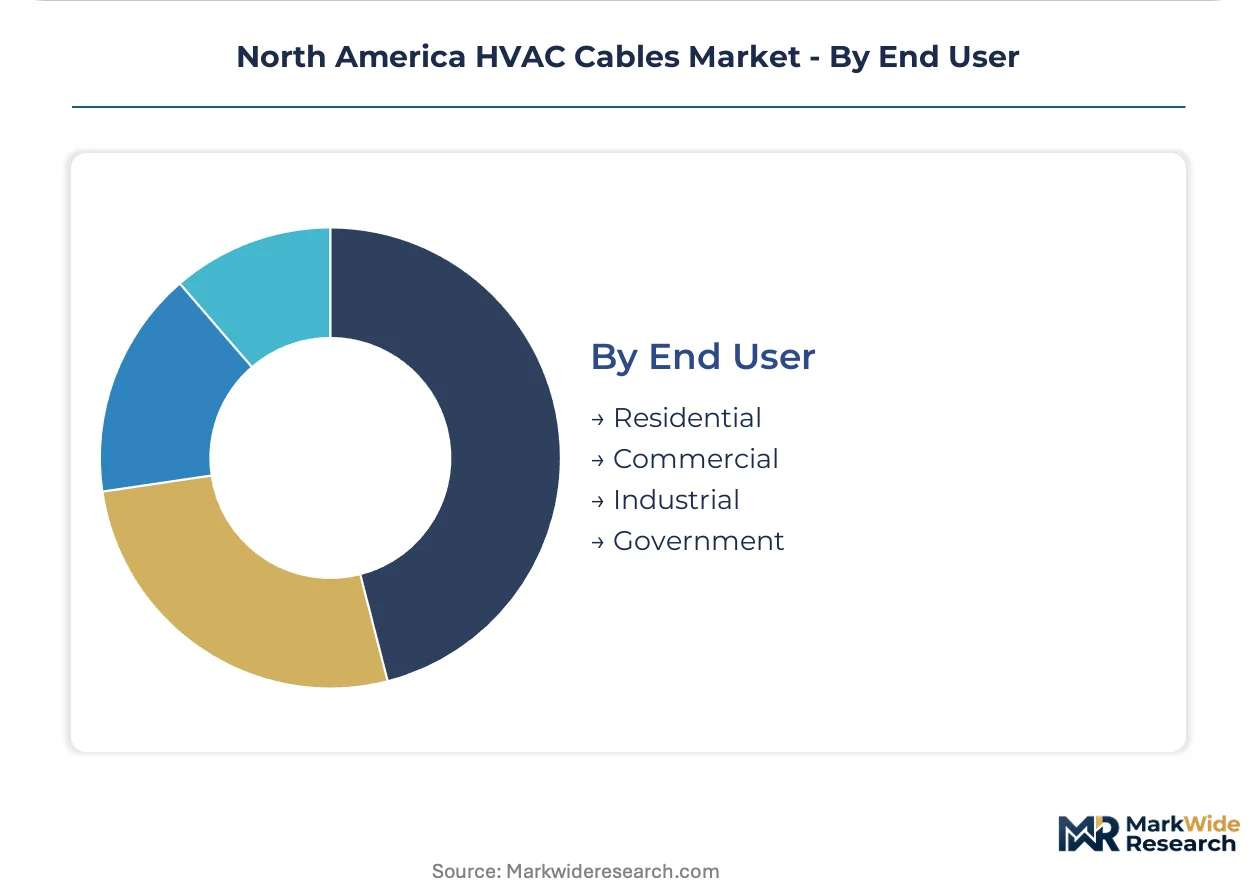
End User:
Customer type determines procurement centralization, specification authority, and sensitivity to total installed cost versus lifecycle value.
- Residential:Single-family and multifamily construction drives high-volume, price-sensitive procurement through regional electrical distributors. Builder preferences in Florida and Texas favor just-in-time delivery models that minimize inventory carrying costs.
- Commercial:Class A office and retail developers specify premium compounds for warranty compliance and insurance rate optimization. Corporate sustainability mandates in California are accelerating LSZH specification for LEED certification points.
- Industrial:Manufacturing and cold storage facilities prioritize metal-clad and high-ampacity feeders for equipment protection and continuous operation reliability.
- Government:Federal, state, and municipal projects enforce Buy American provisions and enhanced fire safety protocols that constrain supplier pools to domestic manufacturers with established compliance documentation.
Commercial channels concentrate specification authority. Government procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA's AIM Act compliance deadlines dominate infrastructure planning across the United States, while provincial energy retrofit programs reshape procurement patterns in Canada and nearshoring dynamics alter supply chain configurations in Mexico.
United States
Cooling-dominated load profiles in Texas, Florida, and Arizona are accelerating rooftop HVAC replacements under AIM Act refrigerant phasedown schedules. The EPA's Significant New Alternatives Policy compresses equipment depreciation cycles, forcing commercial building owners toward compliant system overhauls. Dallas-Fort Worth and Phoenix construction corridors concentrate demand for thermoset-insulated conductors in high-ambient-temperature installations.
Canada
The Canada Greener Homes Initiative and provincial retrofit programs in Ontario and British Columbia are expanding specification of low-smoke zero-halogen cables in healthcare and education facilities. Health Canada's parallel electrical code administration to the US NEC creates certification harmonization pressure for cross-border manufacturers. Vancouver and Toronto metropolitan areas anchor demand for fire-safety-enhanced cabling in high-rise commercial cores.
Mexico
Nearshoring of HVAC equipment production to Baja California and Nuevo León is generating demand for harmonized cable specifications across integrated US-Mexico supply chains. The national standardization body's electrical standards create additional compliance layers for manufacturers serving North American markets. Tijuana and Monterrey industrial clusters concentrate foreign direct investment in climate-controlled manufacturing facilities requiring specialized power distribution.
North America HVAC Cables Market Vendor Landscape
Integrated cable manufacturers and specialized electrical distributors split the market into distinct competitive spheres. Three strategic archetypes dominate: vertically integrated producers with captive copper sourcing, regional distributors with contractor loyalty programs, and specialty compound developers serving fire-safety-critical installations. Competitive moves center on manufacturing footprint consolidation near southern US demand centers and portfolio expansion into smart-building convergence products.
Among North American and European-headquartered manufacturers, Prysmian Group, Nexans, and Southwire exemplify the integrated production archetype. Prysmian represents manufacturing footprint scale with North American production assets. Nexans occupies a position emphasizing fluoropolymer and cross-linked polyethylene expertise. Southwire anchors the distributor-relationship vector through extensive contractor loyalty infrastructure. These three sit within the premium-tier supplier pool where specification authority concentrates in commercial and government procurement channels.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Sumitomo |
| NKT |
| Southwire |
| ZTT |
| Elsewedy Electric |
| Valard Construction |
| KEC International Ltd |
| Others |
Supply Flow & Price Mechanics
The Laredo-Colombia freight corridor's volatile diesel and cross-border logistics costs compress distributor margins across the southern United States while amplifying price differentiation between bulk-contracted thermoplastic inventory and configured-to-order thermoset and specialty compounds.
Pricing Analysis
The customization-premium spread separates standard PVC-jacketed thermoplastic cables from engineered thermoset and LSZH configurations by a factor reflecting copper grade, UL certification tier, and project-scale volume discounts. Three-tier pricing structure across premium, standard, and economy levels tracks insulation chemistry, with thermoset commanding position in rooftop mechanical specifications and LSZH compounds extracting premiums in healthcare and education procurement channels. Cost compression in standard thermoplastic grades is intensifying because aluminum conductor substitution in feeder applications displaces copper volume. Residential contractors in Florida and Texas exhibit the highest price sensitivity, while commercial developers in Arizona and Nevada prioritize lifecycle value over unit cost.
Supply Chain Analysis
Upstream feedstock concentration in Chilean copper mining, US Gulf Coast petrochemical complexes, and Chinese fluoropolymer production shapes raw material cost trajectories for North American cable manufacturers. Cross-linked polyethylene compounds draw from ethylene feedstocks anchored in Texas and Louisiana, while specialty halogen-free flame retardants hinge on Asian chemical processing capacity. Single-source vulnerability in fluoropolymer supply creates exposure for Nexans and Prysmian specialty product lines. Distribution runs through consolidated electrical supply houses with just-in-time delivery contracts, compressing independent distributor participation in fast-growth metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America HVAC Cables Market represents an early-cycle expansion story as AIM Act refrigerant phasedown deadlines force equipment replacement waves across cooling-dominated southern states, pulling forward cable demand from traditional depreciation cycles.
For Market Incumbents: Build specification authority moats through deeper captive copper sourcing and UL/CSA dual-certification investments that aluminum substitution threats cannot replicate. Anchor distributor relationships with just-in-time inventory guarantees in Dallas-Fort Worth and Phoenix construction corridors. Prioritize thermoset capacity expansion over thermoplastic commoditization. For New Entrants and Emerging Players: Mid-market commercial buildings in Baja California and Nuevo León represent the most penetrable entry point as nearshored HVAC equipment production creates demand for harmonized US-Mexico cable specifications. Target government procurement channels in Ontario and British Columbia where provincial fire codes are tightening faster than US federal benchmarks. Lead with LSZH compound expertise and Health Canada compliance documentation. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated electrical distributors with stranded contractor loyalty programs in Arizona and Nevada metropolitan construction corridors. Long-term viability rests on exposure to thermoset and specialty compound value pools rather than commodity thermoplastic volume. Watch EPA SNAP program enforcement acceleration as the inflection indicator for replacement cycle velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rod Production | Prysmian and Southwire captive smelting capacity insulates margin compression from LME volatility. |
| Dual UL-CSA Certification Investment | Harmonized product lines reduce SKU complexity for cross-border commercial projects. |
| LSZH Compound R&D Partnership | Healthcare and education facility procurement in Vancouver and Toronto rewards fire-safety innovation. |
| Mexico Manufacturing Footprint Expansion | Baja California and Nuevo León proximity aligns with nearshored HVAC equipment supply chains. |
| Smart Building Convergence Product Launch | PoE-ready cable architectures capture specification authority with Texas and California building automation integrators. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with electrical contractor purchasing managers, distributor inventory planners, and commercial building specification engineers, and secondary validation against NEC and Canadian Electrical Code documentation, EPA AIM Act regulatory filings, and copper market data from the London Metal Exchange. Bottom-up and top-down triangulation cross-checked distributor shipment patterns against construction permit databases and HVAC equipment import records.
Forecast inputs considered application segmentation across heating, ventilation, air conditioning, and refrigeration; product type tiering through thermoplastic, thermoset, metal-clad, and specialty compounds; and end-user procurement behavior across residential, commercial, industrial, and government channels. CAGRs were derived from equipment replacement cycle modeling tied to refrigerant phasedown schedules and provincial retrofit program trajectories. Regional cooling degree day correlations and copper price scenario analysis shaped sensitivity bounds.
Practitioners should monitor EPA enforcement acceleration, LME copper volatility spikes, and provincial fire code harmonization progress for early signals of forecast revision. Cross-checking against McGraw-Hill construction contract value indices and AHRI equipment shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Submarine Cables Market
Cables
Cable Management System Market
Cables
Multicore Cables Market
Cables
Submarine Cabling Systems Market
Cables
Twisted Pair Cable Market
Cables
Global Cable Blowing Equipment Market
Cables
Cable Market
Cables
Instrumentation Cables Market
Cables
Power Cable Accessories Market
Cables
Global Ethernet Cable Market
Cables
Audio and Video Cables Market
Cables
Mineral Insulated (MI) Cable Market
Cables
Downhole Cables Market
Cables
North America Wire and Cable Market
Cables
High-Speed Interconnects Market
Cables
Cable Flange Market