
 SATA Connector Market | 2026-2036
SATA Connector Market Size, Share, and Industry Trends Forecast 2026-2036
SATA Connector Market Analysis
LCP resin is rebalancing cost-performance economics in high-density SATA connector molding, displacing conventional thermoplastics in thermally stressed server backplane applications. TE Connectivity leverages vertical integration across contact plating and housing extrusion to sustain margin control in enterprise-grade supply chains. Molex anchors North American demand through dedicated production lines for hyperscale data center customers. Amphenol ICC differentiates via precision stamping expertise in micro-SATA variants for embedded storage modules.
A SATA connector is an electromechanical interface that transmits data between host bus adapters and mass storage devices, typically rated for 1.5 to 6 Gbit/s signaling speeds with seven conductive pins in a staggered low-profile housing. Internal SATA connectors dominate volume shipments for enterprise hard drive and solid-state drive deployments, while SATA Express retains niche traction in legacy workstation transitions where PCIe compatibility bridges upgrade cycles. Cloud computing applications command premium positioning due to signal integrity requirements in 24/7 operational environments.
FCC electromagnetic interference limits and EU RoHS substance restrictions compel manufacturers to reformulate plating chemistries and validate shielding architectures for US and European market access. China's GB standards and Japan's JIS certification layers add compliance complexity for multi-region product portfolios. OEM procurement teams must weigh connector roadmap longevity against the transition timeline to NVMe and PCIe native interfaces in next-generation storage architectures.
Market Dynamics
Enterprise storage infrastructure expansion is compressing connector lifecycle timelines as hyperscale operators demand higher signal integrity under thermal stress. LCP resin adoption is rebalancing material economics against legacy thermoplastics in server backplane applications.
Growth Catalysts
- Cloud Infrastructure Scaling:Hyperscale data center operators in Taiwan, South Korea, and Japan are expanding storage server deployments. These facilities require high-density SATA connectors rated for 24/7 operational environments.
- EU RoHS Directive:Substance restrictions on halogenated materials are compelling housing reformulation across connector portfolios. Manufacturers validating lead-free plating chemistries gain preferential access to European enterprise procurement channels.
- Embedded Storage Modules:Industrial automation and edge computing hardware are integrating micro-SATA variants for compact solid-state storage. This application segment pulls precision-stamped connector architectures into non-traditional deployments.
Market Restraints
- Copper Alloy Volatility:Contact plating substrates face input cost pressure from commodity metal markets. Connector manufacturers lack pricing power to pass through alloy surges to locked enterprise supply agreements.
- East Asian Supply Concentration:Molding and stamping capacity clusters in Taiwan and South Korea create geographic risk exposure. Single-source dependencies for high-temperature LCP resin compound vulnerability.
- NVMe Interface Substitution:Native PCIe storage protocols are displacing SATA in performance-critical server tiers. Connector roadmap longevity compresses as enterprise buyers accelerate interface transition timelines.
Strategic Opportunities
- India Manufacturing Expansion:Production-linked incentive schemes for electronics hardware are attracting connector assembly investments. Domestic data center buildouts create captive demand for locally sourced storage interfaces.
- Automotive Telematics Integration:Connected vehicle architectures are adopting ruggedized SATA connectors for onboard data logging. This vertical escapes the hyperscale pricing pressure dominating enterprise segments.
- Japan JIS Certification Layer:Premium-tier connector qualification pathways reward precision manufacturing capabilities. Suppliers achieving JIS validation command positioning in medical and industrial instrumentation markets.
Industry Challenges
- Signal Integrity Engineering Talent:High-speed connector design requires specialized electromagnetic simulation expertise. Workforce scarcity in Taiwan and Japan constrains product development velocity for next-generation backplane solutions.
- Multi-Region Certification Overlap:Simultaneous FCC, EU RoHS, China GB, and Japan JIS validation extends product launch timelines. Testing redundancy consumes engineering resources without incremental market access benefit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SATA Connector Market |
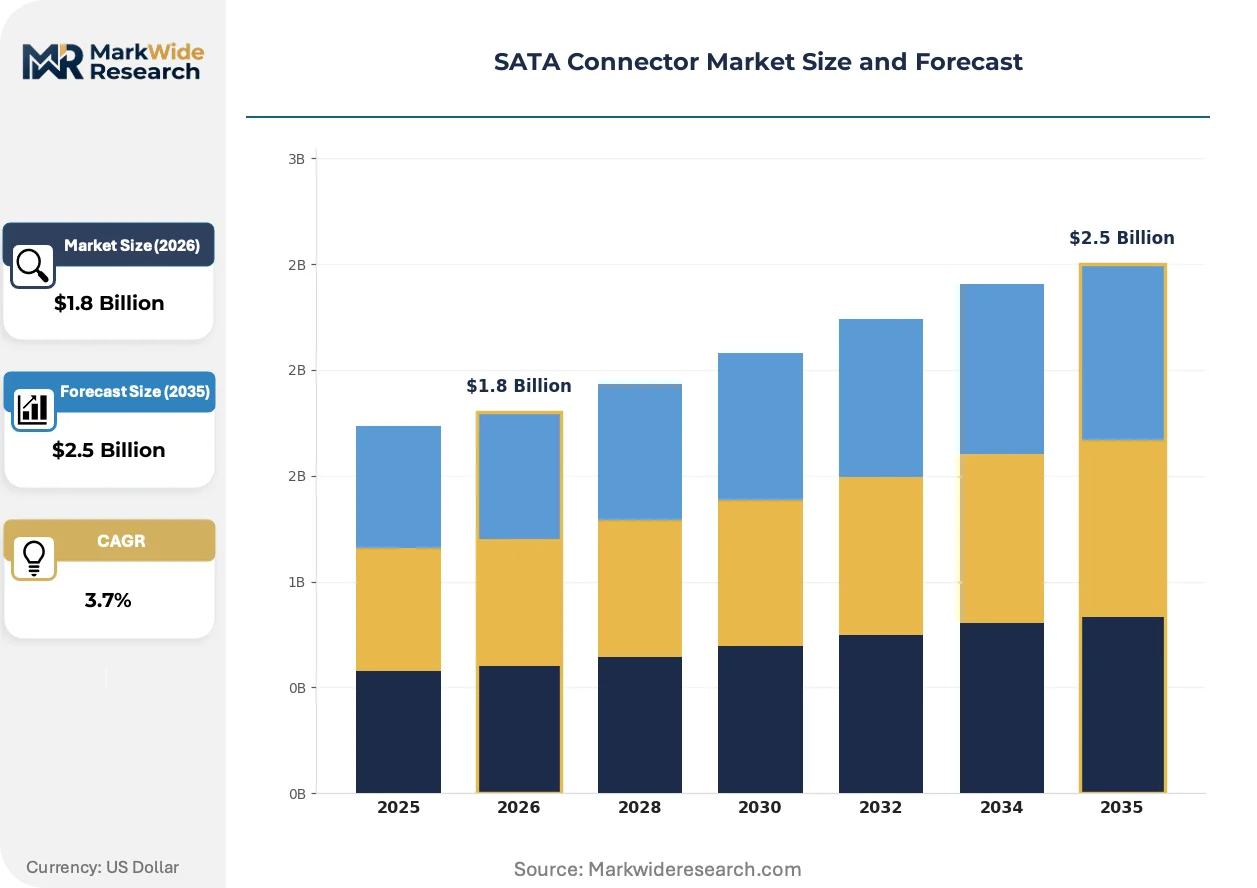
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal SATA, External SATA, SATA Express, Power SATA Connection Type: Standard, eSATA, Power Connector, Mini SATA Application: Data Storage, Cloud Computing, Gaming Consoles, Workstations End User: Consumers, Enterprises, OEMs, Retailers |
| Companies Covered | Foxconn (FIT), Smiths Interconnect, TE Connectivity, JAE, Kyocera, Amphenol ICC, 3M, ACES Electronics, Molex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SATA Connector Market Emerging Trajectories
Material science advances and interface protocol evolution are restructuring competitive positioning in storage connectivity. Regulatory chemistry constraints and thermal performance demands are converging to reshape connector architecture roadmaps.
Liquid crystal polymer resin is electrifying high-density molding applications previously dominated by conventional thermoplastics. Server backplane manufacturers in East Asian manufacturing clusters are adopting LCP housings for sustained thermal cycling performance. This material transition is compressing qualification cycles for legacy polyamide compounds while enabling finer pitch geometries in multi-lane configurations.
China's GB standards on halogenated substance limits are tightening material specifications for connector housings exported to domestic data center operators. Manufacturers reformulating phosphorus-based flame retardants into housing compounds face eighteen-month validation timelines. Enterprise-grade product lines destined for Chinese cloud infrastructure are absorbing disproportionate compliance engineering overhead relative to standard industrial variants.
Hyperscale procurement teams are consolidating supplier relationships around vertically integrated connector vendors capable of captive plating and extrusion. Direct contracting models are displacing distribution-centric purchasing for storage server buildouts. This concentration is most visible in North American data center expansion projects where single-source accountability reduces qualification burden across multi-site deployments.
SATA Connector Market Segmentation
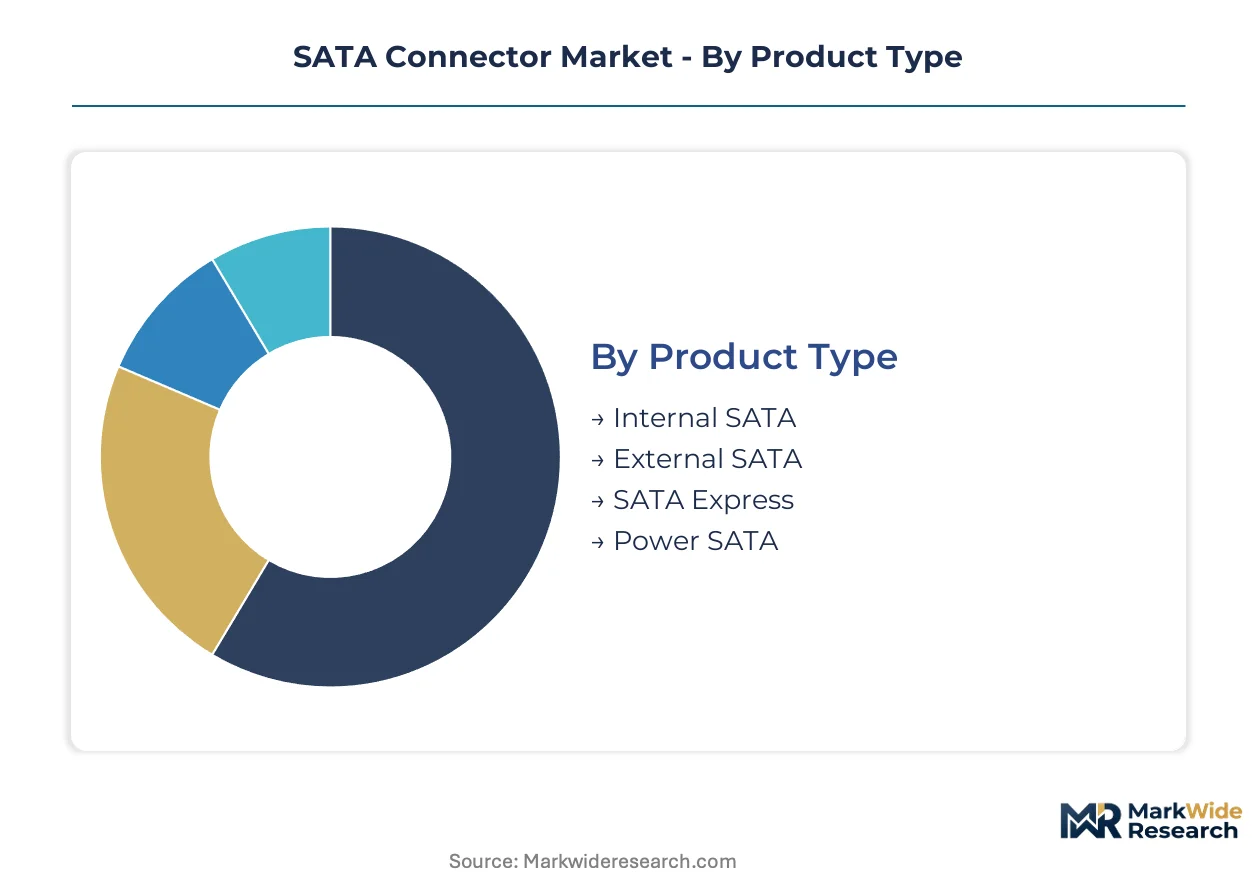
SATA connector demand fragments across interface generations and deployment contexts, with upgrade-cycle timing determining which product variants capture volume. Enterprise procurement teams weigh backward compatibility against forward roadmap alignment when segmenting supplier portfolios.
Product Type:
Upgrade-cycle positioning determines which SATA variants retain procurement priority as NVMe transition accelerates in performance-tier storage.
- Internal SATA:Seven-pin data interfaces in staggered low-profile housings dominate enterprise hard drive and solid-state drive deployments. Hyperscale data centers in Taiwan and South Korea specify these connectors for 24/7 operational environments where signal integrity under thermal stress commands specification priority.
- External SATA:Shielded cable assemblies with latching mechanisms serve direct-attached storage expansion and legacy backup systems. Industrial automation deployments in Japan pull ruggedized external variants into non-traditional edge computing applications.
- SATA Express:PCIe-compatible bridging interfaces retain niche traction in workstation transitions where motherboard compatibility extends upgrade cycles.
- Power SATA:Fifteen-pin supply connectors integrate with data interfaces in enterprise backplane architectures.
Internal SATA sits at the top of the volume ranking, with SATA Express climbing the fastest as workstation refresh cycles extend legacy compatibility requirements.
Connection Type:
Cost-tier differentiation separates standardized commodity connectors from certified variants commanding premium positioning in regulated end-uses.
- Standard:Baseline seven-pin configurations serve consumer electronics and entry-level enterprise storage where cost minimization dominates procurement criteria.
- eSATA:Shielded external variants with enhanced electromagnetic compatibility specifications address FCC interference limits in US market access requirements.
- Power Connector:Dedicated supply interfaces separate from data signaling enable modular power distribution in high-density server chassis designs.
- Mini SATA:Compact form factors integrate into embedded storage modules for industrial automation and medical instrumentation where JIS certification layers add qualification overhead.
Standard connectors dominate shipment volumes, though Mini SATA gains share fastest as edge computing hardware miniaturizes storage architectures.
Application:
Application context determines thermal specification and signal integrity requirements that segment supplier qualification pathways.
- Data Storage:Enterprise hard drive and solid-state drive arrays constitute the foundational demand pool for high-density backplane connectors. Cloud service providers in Japan and South Korea specify extended-temperature variants for infrastructure scaling.
- Cloud Computing:Hyperscale facilities command premium-grade connectors with validated plating chemistries under EU RoHS substance restrictions.
- Gaming Consoles:Consumer electronics manufacturers prioritize cost-optimized standard interfaces with reduced qualification burden.
- Workstations:Professional computing deployments bridge legacy SATA and emerging NVMe through SATA Express compatibility layers.
Data Storage anchors application demand, while Cloud Computing expands most quickly as hyperscale operators consolidate supplier relationships around vertically integrated vendors.
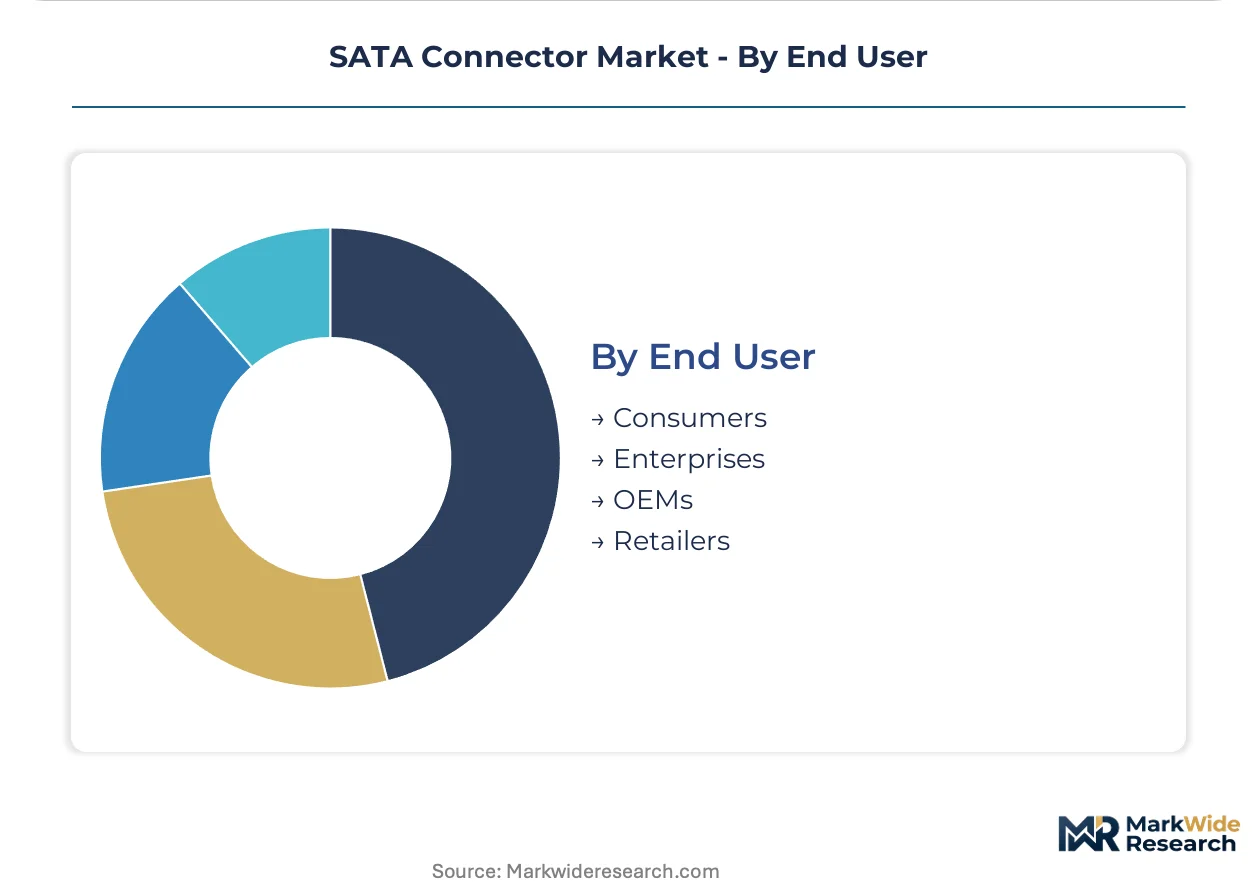
End User:
Customer-type concentration shapes pricing architecture and contract structure across direct procurement and distribution channels.
- Consumers:Individual purchasers access SATA connectors through retail distribution and aftermarket channels with minimal technical specification requirements.
- Enterprises:Hyperscale operators and corporate IT departments negotiate direct supply agreements with plating and extrusion capabilities specified.
- OEMs:Original equipment manufacturers integrate connectors into server, storage, and industrial hardware with multi-year qualification cycles.
- Retailers:Distribution-centric purchasing models serve small-to-medium enterprise and consumer segments with standardized product lines.
Enterprises sit at the top of the volume ranking, with OEMs climbing the fastest as hardware manufacturers consolidate connector sourcing around captive production capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters in Taiwan, South Korea, and Japan concentrate SATA connector production capacity. These geographies anchor global supply chains for enterprise storage infrastructure. Regional demand patterns diverge between hyperscale cloud buildouts and legacy industrial applications.
China
Domestic cloud service providers are scaling storage server deployments in the Yangtze River Delta and Pearl River Delta regions. GB standards on halogenated substance limits compel housing reformulation with eighteen-month validation timelines. Shenzhen and Dongguan manufacturing clusters absorb disproportionate compliance engineering overhead for enterprise-grade product lines.
Japan
Precision instrumentation and medical device manufacturers pull micro-SATA variants into embedded storage modules. METI oversees JIS certification layers that reward manufacturing accuracy with premium market positioning. Nagoya and Osaka industrial corridors host suppliers achieving validation for high-reliability connector architectures.
South Korea
Hyperscale operators specify extended-temperature connectors for 24/7 operational environments in Seoul Capital Area data centers. The country's national electronics regulator enforces electromagnetic compatibility specifications aligned with global enterprise procurement standards. Busan-Ulsan manufacturing zones concentrate stamping and plating capacity for captive supply to domestic server OEMs.
United States
North American data center expansion projects consolidate supplier relationships around vertically integrated vendors. FCC electromagnetic interference limits compel shielding architecture validation for market access. Greater Dallas and Phoenix metro areas concentrate hyperscale facility buildouts demanding single-source accountability across multi-site deployments.
India
Production-linked incentive schemes for electronics hardware attract connector assembly investments from multinational suppliers. Domestic data center buildouts create captive demand for locally sourced storage interfaces. Maharashtra and Karnataka states anchor emerging manufacturing clusters serving both local consumption and re-export markets.
SATA Connector Market Vendor Landscape
Global majors compete with regional champions across plating chemistry and precision stamping capabilities. The vendor base separates into three tiers: integrated giants with captive extrusion, mid-scale specialists with JIS or GB certification focus, and commodity assemblers serving consumer electronics. Two dominant competitive moves are reshaping positioning: backward integration into contact plating substrates and strategic partnerships with LCP resin compounders.
Among Taiwan and Japan-based fabricators, Foxconn (FIT), JAE, and Kyocera exemplify the precision-manufacturing archetype. These entities occupy positions where certification density—spanning FCC, EU RoHS, China GB, and Japan JIS—creates defensive moats against commodity competition. TE Connectivity and Molex represent the vertically integrated tier with in-house production of plating and housing extrusion. Amphenol ICC sits within the specialist segment, anchoring expertise in micro-form-factor architectures for non-traditional embedded deployments.
| Leading Market Players |
|---|
| Foxconn (FIT) |
| Smiths Interconnect |
| TE Connectivity |
| JAE |
| Kyocera |
| Amphenol ICC |
| 3M |
| ACES Electronics |
| Molex |
| Others |
Supply Flow & Price Mechanics
Copper alloy spot indices on the London Metal Exchange cascade through contact plating substrates into three-tier pricing stratification across enterprise, industrial, and consumer-grade SATA connector tiers. Locked long-term supply agreements with hyperscale data center operators prevent manufacturers from passing through commodity surges, compressing margins in the standard-grade segment while JIS-certified premium variants retain pricing power.
Pricing Analysis
Input-cost pass-through constraints dominate pricing architecture as copper alloy volatility meets fixed enterprise contracts. Three-tier pricing structure across premium, standard, and economy levels separates JIS-validated precision-stamped variants from commodity seven-pin configurations. Cost compression in standard-grade segments intensifies because locked hyperscale agreements cap repricing flexibility. Consumer electronics buyers exhibit highest price sensitivity, while medical instrumentation procurement teams prioritize certification grade over unit cost.
Supply Chain Analysis
Workforce scarcity for high-speed electromagnetic simulation engineers in Taiwan and Japan constrains product development velocity across precision stamping operations. Supply concentrates in Taiwan, South Korea, and Japan for molding and plating capacity, with LCP resin compounding drawing from specialized petrochemical feedstocks. Single-source vulnerability for high-temperature LCP resin compounds creates structural risk exposure. Distribution runs through direct contracting models for hyperscale operators, displacing traditional distribution channels in enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SATA connector market represents a late-cycle quality story as hyperscale operators consolidate procurement around vertically integrated vendors capable of captive plating and extrusion. Premium specification demand from cloud infrastructure scaling rewards certification density and thermal performance validation.
For Market Incumbents: Deploy JIS certification layering to defend positioning in medical and industrial instrumentation segments against NVMe interface substitution in performance-tier storage. Backward integration into contact plating substrates sustains margin control as copper alloy volatility pressures standard-grade competitors. Capacity addition in India captures production-linked incentive schemes while serving emerging domestic data center buildouts. For New Entrants and Emerging Players: Launch via automotive telematics integration to escape hyperscale pricing pressure dominating enterprise segments. Ruggedized SATA connectors for onboard data logging in connected vehicles represent the most penetrable application white-space. Precision stamping expertise for micro-SATA variants targets embedded storage modules in industrial automation hardware. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialists possessing GB and JIS certification density without legacy NVMe transition drag. Five-to-ten year viability hinges on connector roadmap longevity against PCIe native interface displacement timelines. Watch hyperscale procurement consolidation velocity as the inflection indicator for supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plating | Captive contact plating substrate production insulates margin control against copper alloy spot volatility. |
| JIS Certification Investment | METI-supervised validation pathways unlock premium positioning in Nagoya and Osaka medical device corridors. |
| India Manufacturing Footprint | Maharashtra and Karnataka assembly investments capture PLI scheme benefits and local data center demand. |
| LCP Resin Partnership | Strategic alliances with high-temperature compounders secure supply for thermally stressed server backplane applications. |
| Automotive Telematics Vertical | Ruggedized connector qualification for connected vehicle architectures diversifies revenue beyond hyperscale concentration. |
Methodological Framework
Bottom-up data storage deployment modeling reconciled against top-down connector supply tracking forms the analytical core of this study. Primary interviews with connector procurement managers at hyperscale operators, plating chemistry engineers, and precision stamping operations directors combined with secondary validation from SEC filings, customs trade records, and cloud infrastructure capex disclosures. Triangulation across enterprise hardware OEMs and industrial automation system integrators anchored volume estimates.
Input-output matrices mapping LCP resin consumption to finished connector shipments structured the forecast framework across the analysis window. Segmentation dimensions modeled include product type, connection grade, application context, and end-user procurement channel. CAGRs derived from elasticity analysis of storage server buildouts against interface transition timelines. Copper alloy price trajectories and GB standards compliance timelines fed industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated NVMe substitution or extended SATA Express workstation refresh cycles. Practitioners should monitor hyperscale direct contracting consolidation rates and JIS certification achievement timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Space Grade Connectors Market
Connectors
USB Type-C Market
Connectors
DIN Connectors Market
Connectors
Mexico Connector Market
Connectors
Australia Connector Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Terminal Pins Market
Connectors
Latin America Connector Market
Connectors
Magnetic Connector Market
Connectors
Hazardous Location Connectors Market
Connectors
Pin Retainer Market
Connectors
Cable Connectors and Adapters Market
Connectors
Japan Connector Market
Connectors
LCP Connectors Market
Connectors
AS-Interface Market
Connectors
Asia-Pacific Connector Market