
 US Optical Sensors Market | 2026-2036
US Optical Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
US Optical Sensors Market Analytics
The capital-intensity divergence between foundry-dependent and vertically integrated players is reorganizing competitive tiers in the US optical sensors sector. Texas Instruments leverages captive wafer fabrication to sustain margin control across industrial automation deployments. Honeywell International Inc. anchors its position through aerospace-grade certification pathways that competitors struggle to replicate. Sick AG specializes in precision photoelectric systems for factory-floor applications, occupying a defensible niche against broader-portfolio rivals.
US optical sensors convert electromagnetic radiation in the ultraviolet through infrared spectrum into electrical signals, typically employing silicon, InGaAs, or germanium substrates with responsivity thresholds calibrated to specific wavelength bands. These devices enable machine vision, distance measurement, and ambient light detection across automated systems. Image sensors command the largest revenue pool among product categories, while LIDAR sensors represent the fastest-expanding segment as autonomous vehicle programs scale. MEMS-based technology is displacing conventional analog architectures in consumer electronics, concentrating value capture among suppliers with micromachining expertise.
The FDA governs optical sensor performance in diagnostic and surgical equipment through 21 CFR quality standards, while NHTSA mandates specific detection ranges for advanced driver-assistance systems. FCC regulations on electromagnetic interference shape design constraints for wireless-integrated optical modules. Stakeholders must weigh California's evolving autonomous vehicle testing rules against Michigan's manufacturing incentives when siting R&D and production assets.
Market Dynamics
Automotive LIDAR deployment is compressing development cycles across the US optical sensors sector, forcing suppliers to reconcile aerospace-grade reliability standards with consumer-electronics cost structures.
Growth Catalysts
- NHTSA ADAS Mandates:Detection-range requirements for forward-collision warning systems are expanding sensor volumes across domestic vehicle production lines. Tier-1 suppliers are qualifying multiple optical sources per platform.
- InGaAs Substrate Proliferation:Near-infrared sensitivity improvements are unlocking medical imaging applications previously served by X-ray modalities. Surgical navigation systems now integrate photonic guidance layers.
- Michigan Manufacturing Incentives:State-level tax abatements for sensor packaging facilities are concentrating capital deployment in the Detroit-Toledo corridor. Automotive OEMs are co-lating R&D with component suppliers.
Market Restraints
- Silicon Wafer Supply Concentration:Domestic foundry capacity for sensor-grade substrates remains concentrated among three merchant suppliers. Price volatility in 300mm wafer contracts compresses gross margins for fabless designers.
- FCC EMI Certification Burden:Wireless-integrated optical modules face extended testing timelines for Part 15 compliance. Development schedules stretch 4-6 months longer than wired equivalents.
- Quantum Dot Substitution Threat:Colloidal quantum dot photodetectors are achieving comparable responsivity at lower processing temperatures. Legacy silicon PIN architectures face displacement in cost-sensitive consumer applications.
Strategic Opportunities
- Texas Photonics Corridor:Austin-San Antonio metroplex offers underutilized cleanroom capacity for MEMS optical foundry services. Defense contractors are seeking qualified domestic sources for ITAR-controlled components.
- FDA Breakthrough Device Pathway:Expedited review timelines for optical diagnostic platforms are compressing time-to-revenue for novel imaging modalities. Fluorescence-guided surgery systems qualify for priority processing.
- Silicon Photonics Convergence:Integration of CMOS electronics with optical waveguides is enabling chip-scale LIDAR engines. Foundry partnerships between MEMS specialists and semiconductor fabs are unlocking volume manufacturing.
Industry Challenges
- Multiphysics Simulation Expertise Gap:Packaging engineers capable of modeling thermal-optical-mechanical interactions remain scarce. Recruitment timelines for senior photonics architects exceed nine months in California and Arizona markets.
- ISO 26262 Functional Safety Certification:Automotive optical sensors require ASIL-D qualification for autonomous emergency braking applications. Documentation burdens add 18-24 months to product development cycles.
- Legacy Industrial Network Integration:Factory-floor photoelectric sensors must bridge proprietary fieldbus protocols with OPC-UA standards. Firmware development for protocol translation consumes engineering resources without differentiation value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Optical Sensors Market |
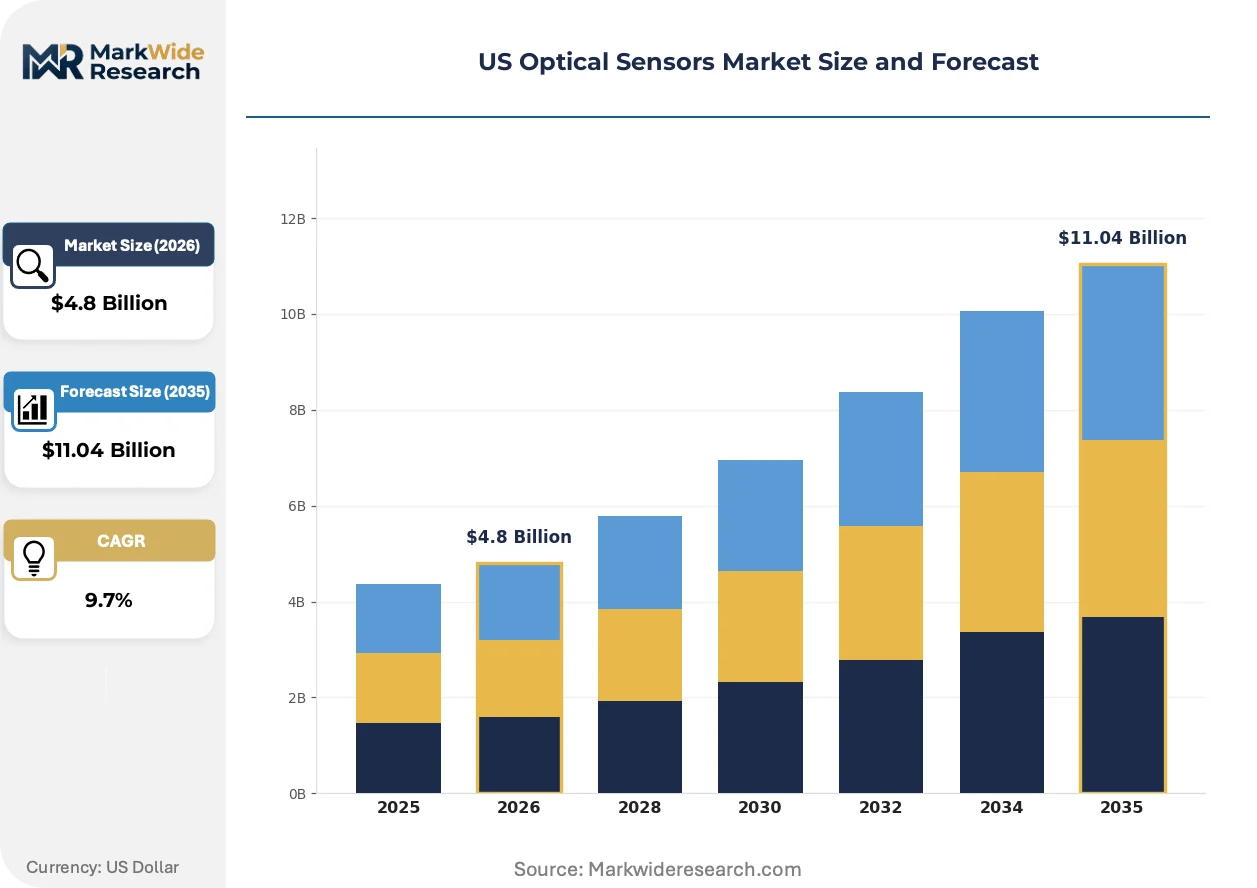
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Image Sensors, Fiber Optic Sensors, LIDAR Sensors, Photodiodes Technology: Analog Sensors, Digital Sensors, MEMS-based Sensors, Smart Sensors End User: Automotive, Consumer Electronics, Industrial Automation, Healthcare Application: Automotive Safety, Robotics, Consumer Devices, Environmental Monitoring |
| Companies Covered | Mouser Electronics Inc., Sick AG, Rockwell Automation, Honeywell International Inc., Eaton Corporation, Texas Instruments, Analog Devices, Inc., ams-OSRAM AG, Broadcom Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Optical Sensors Market Evolving Landscape
Solid-state beam steering architectures are redefining performance-cost tradeoffs across automotive and industrial sensing applications, compressing the viable window for mechanical scanning technologies.
Solid-state optical phased arrays are displacing microelectromechanical mirrors in automotive LIDAR designs. Detroit-based autonomous vehicle programs are qualifying silicon photonics engines for 2027 model year deployment. The shift is collapsing bill-of-materials costs while extending mean-time-between-failures by eliminating moving parts.
California's evolving autonomous vehicle testing regulations are mandating redundant sensor coverage for expanded operational design domains. The California DMV requires dual-modality perception stacks with independent optical and radar validation. Tier-1 suppliers are architecting sensor fusion platforms that treat optical inputs as safety-critical subsystems rather than convenience features.
Defense procurement offices are unbundling sensor hardware from integrated platform contracts. Program managers at Army Futures Command now acquire optical payloads through separate commercial-item pathways. This behavioral shift is concentrating demand among qualified domestic suppliers with existing facility clearances, compressing vendor selection cycles from 24 months to 8-12 months.
US Optical Sensors Market Segmentation
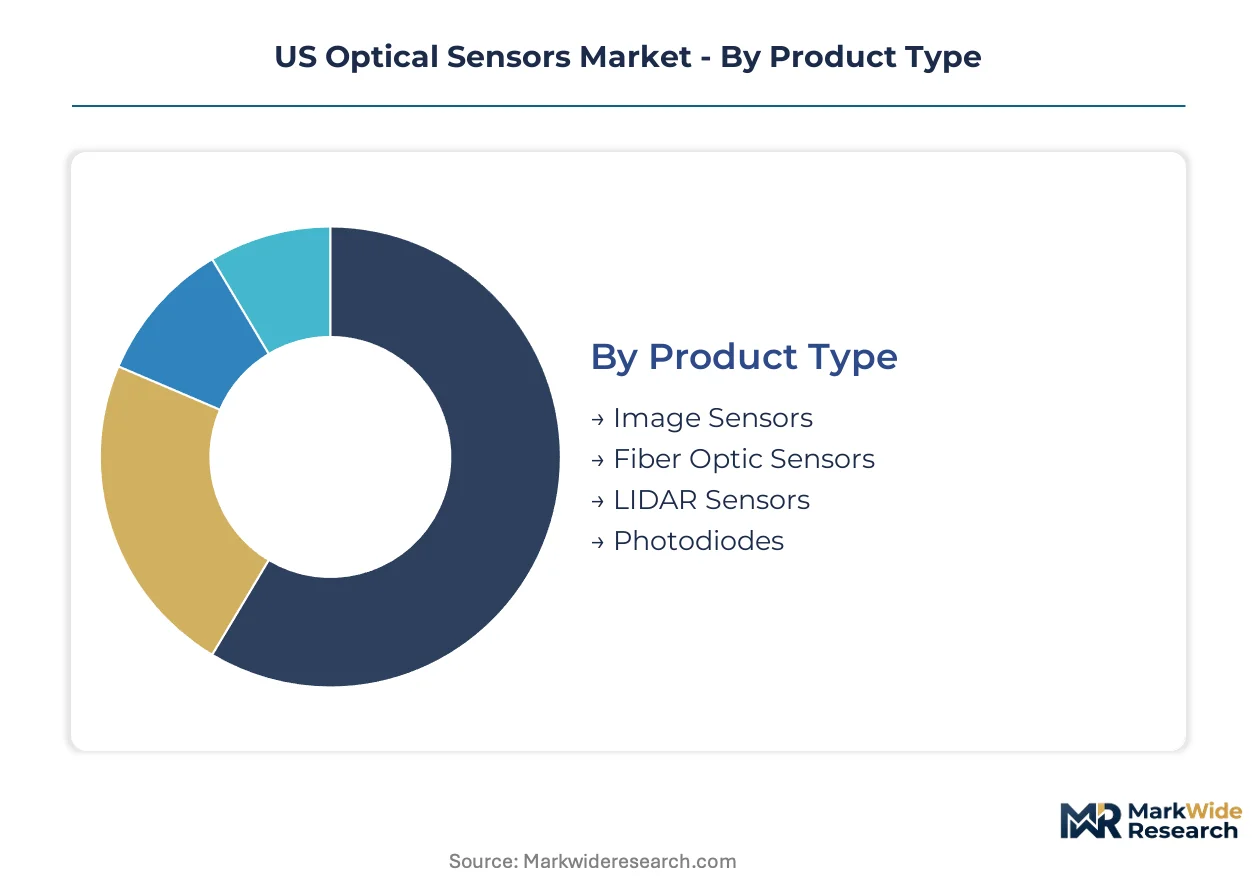
Optical sensor architectures diverge sharply across wavelength sensitivity, signal processing topology, and environmental ruggedization requirements. Procurement patterns in this market cluster around application-specific performance thresholds rather than interchangeable commodity specifications.
Product Type:
LIDAR sensors face acute substitution pressure from solid-state optical phased arrays, while image sensors confront quantum dot photodetector encroachment in cost-sensitive consumer tiers.
- Image Sensors:Silicon-based CMOS and CCD architectures dominate machine vision and smartphone camera modules. California's technology corridor concentrates design activity for high-resolution formats, though InGaAs variants are penetrating medical imaging for near-infrared surgical guidance.
- LIDAR Sensors:Time-of-flight and frequency-modulated continuous-wave systems enable autonomous vehicle perception stacks. Michigan automotive OEMs are qualifying solid-state silicon photonics engines for production deployment, collapsing mechanical scanning cost structures.
- Fiber Optic Sensors:Intrinsic and extrinsic configurations measure strain, temperature, and pressure in harsh environments. Oilfield services in Texas deploy distributed acoustic sensing for pipeline monitoring.
- Photodiodes:PIN and avalanche structures convert optical signals to electrical current in industrial automation. Discrete component demand concentrates in Arizona packaging facilities.
Image sensors retain volume leadership; LIDAR sensors hold the steepest expansion curve.
Technology:
Cost tier stratification separates legacy analog implementations from digital architectures with embedded processing capabilities.
- MEMS-based Sensors:Micromachined mirrors and interferometric structures enable compact optical switching and adaptive optics. Austin-San Antonio cleanroom capacity supports domestic MEMS foundry services for ITAR-controlled defense applications.
- Smart Sensors:Integrated CMOS electronics with on-chip signal processing reduce host controller burden. Factory-floor deployments in Michigan's automotive belt favor OPC-UA protocol compatibility.
- Digital Sensors:Direct bitstream outputs eliminate analog-to-digital converter latency. Consumer electronics OEMs prioritize digital interfaces for simplified system integration.
- Analog Sensors:Continuous voltage or current outputs persist in legacy industrial installations. Maintenance replacement cycles sustain demand despite architectural obsolescence.
MEMS-based sensors command premium pricing tiers; smart sensors are expanding most quickly through industrial IoT integration.
End User:
Application maturity varies dramatically, with automotive safety mandates forcing the steepest technology refresh cycles.
- Automotive:NHTSA forward-collision warning mandates expand sensor volumes across domestic production lines. Tier-1 suppliers qualify multiple optical sources per platform, with ASIL-D functional safety certification adding 18-24 months to development timelines.
- Healthcare:FDA 21 CFR quality standards govern diagnostic and surgical equipment performance. Fluorescence-guided surgery systems qualify for Breakthrough Device priority review, compressing time-to-revenue.
- Industrial Automation:Photoelectric sensors bridge proprietary fieldbus protocols with modern standards. Sick AG specializes in precision factory-floor applications occupying defensible niches.
- Consumer Electronics:Ambient light and proximity sensors integrate into smartphones and wearables. MEMS-based architectures displace conventional analog designs, concentrating value among micromachining specialists.
Automotive commands the highest unit value; healthcare holds the steepest expansion curve through surgical navigation adoption.
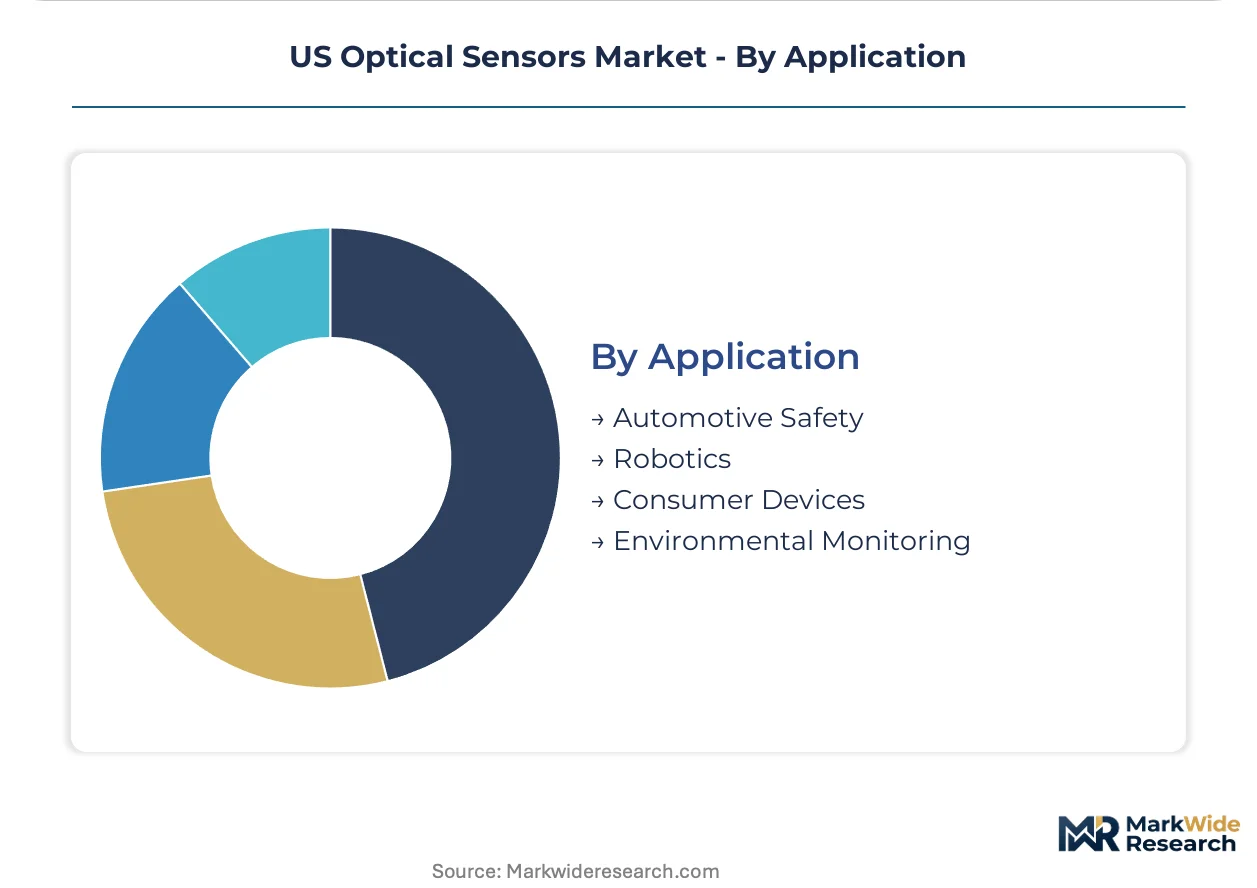
Application:
Geographic concentration of R&D investment shapes competitive positioning across use cases.
- Automotive Safety:Advanced driver-assistance systems require redundant optical and radar validation per California DMV expanded operational design domain rules. Dual-modality perception stacks treat optical inputs as safety-critical subsystems.
- Robotics:Machine vision and distance measurement enable collaborative robot navigation. Industrial deployments concentrate in Michigan's Detroit-Toledo corridor with state-level packaging facility incentives.
- Consumer Devices:Biometric authentication and gesture recognition drive sensor integration. Design activity clusters in California with FCC Part 15 EMI certification extending wireless-integrated module timelines.
- Environmental Monitoring:Spectral analysis and gas detection applications deploy in utility and agriculture sectors. Remote sensing payloads qualify through Army Futures Command commercial-item pathways.
Automotive safety retains volume leadership; robotics holds the steepest expansion curve through manufacturing automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Michigan's automotive belt exhibit acute price sensitivity for high-volume LIDAR contracts, while California's technology corridor tolerates premium pricing for aerospace-grade certification. Texas photonics clusters occupy a mid-elasticity position balancing defense procurement reliability with commercial scalability.
California
Silicon photonics R&D and autonomous vehicle testing programs concentrate sensor demand in the San Francisco Bay Area and Los Angeles metroplex. The California DMV mandates redundant optical-radar perception stacks for expanded operational design domains, forcing Tier-1 suppliers to qualify dual-modality architectures. San Jose and San Diego host MEMS foundry services competing for ITAR-controlled defense contracts.
Michigan
Detroit-Toledo corridor automotive OEMs drive the steepest volume expansion for forward-collision warning sensors under NHTSA mandates. State-level tax abatements for sensor packaging facilities are concentrating capital deployment alongside domestic vehicle production lines. Grand Rapids and Ann Arbor anchor Tier-1 supplier R&D co-location with manufacturing assets.
Texas
Austin-San Antonio metroplex cleanroom capacity supports underutilized MEMS optical foundry services seeking qualified domestic sources. Army Futures Command procurement offices are unbundling sensor hardware from integrated platform contracts, compressing vendor selection cycles for cleared facilities. Dallas-Fort Worth defense contractors are qualifying photonic payloads through commercial-item pathways.
Arizona
Phoenix-Tucson corridor packaging facilities concentrate discrete photodiode demand from industrial automation and medical imaging end users. Semiconductor fabrication infrastructure originally built for consumer electronics is retooling for sensor-grade substrate processing. Tempe and Chandler host back-end assembly operations serving California and Texas design houses.
Massachusetts
Greater Boston's precision photonics ecosystem supplies surgical navigation and fluorescence-guided imaging systems qualifying for FDA Breakthrough Device priority review. MIT and Harvard research partnerships are accelerating InGaAs substrate development for near-infrared medical applications. Worcester and Lowell host specialized packaging operations for healthcare-grade optical modules.
US Optical Sensors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the US optical sensors sector, creating a tiered competitive structure. Vertically integrated semiconductor conglomerates with captive wafer fabrication sustain margin control against fabless designers vulnerable to silicon supply volatility. The market fragments across three strategic archetypes: aerospace-grade certification specialists, MEMS micromachining experts, and broad-portfolio industrial automation suppliers. Dominant competitive moves include foundry partnerships for silicon photonics volume manufacturing and ASIL-D functional safety certification investments extending product development timelines.
Among diversified technology conglomerates, Texas Instruments and Honeywell International Inc. exemplify the vertically integrated archetype with in-house substrate production capabilities. Sick AG occupies a specialist position within precision factory-floor photoelectric systems, representing the defensible-niche strategy against broader-portfolio rivals. These three entities anchor distinct competitive vectors—captive fabrication, aerospace certification pathways, and industrial precision—rather than competing directly on interchangeable specifications.
| Leading Market Players |
|---|
| Mouser Electronics Inc. |
| Sick AG |
| Rockwell Automation |
| Honeywell International Inc. |
| Eaton Corporation |
| Texas Instruments |
| Analog Devices, Inc. |
| ams-OSRAM AG |
| Broadcom Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day wafer inventory cycles in sensor-grade silicon substrates concentrate pricing leverage among domestic foundries serving automotive and defense buyers. This lead-time band compresses margin flexibility for fabless designers while rewarding vertically integrated players with captive fabrication capacity.
Pricing Analysis
After-sales service contracts and field calibration services drive lifetime value in industrial optical sensor deployments. Three-tier pricing structure across aerospace-certified, automotive-grade, and consumer-tier levels segments buyers by reliability requirements and volume scale. Cost compression in consumer-grade image sensors intensifies as quantum dot photodetectors achieve comparable responsivity at lower processing temperatures. Michigan automotive OEMs exhibit acute price sensitivity for high-volume LIDAR contracts, while California defense contractors tolerate premium pricing for ITAR-controlled components with domestic provenance.
Supply Chain Analysis
Inventory cycles stretching to ninety days for sensor-grade silicon wafers expose fabless designers to price volatility from concentrated domestic foundry supply. Raw material dependencies center on silicon substrates, InGaAs wafers, and germanium blanks sourced from merchant suppliers in the United States, Japan, and Germany. Single-source vulnerability in 300mm wafer contracts for advanced CMOS image sensors threatens production continuity for automotive safety programs. Distribution runs through Tier-1 automotive suppliers, industrial automation distributors, and direct defense procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US optical sensors market sits in cyclical recovery as NHTSA ADAS mandates force technology refresh cycles across domestic vehicle production lines.
For Market Incumbents: Consolidate around aerospace-grade certification pathways and MEMS micromachining expertise that emerging competitors cannot rapidly replicate. Deepen backward integration into sensor-grade wafer fabrication to insulate margins from silicon supply volatility. Prioritize ASIL-D functional safety investments to capture autonomous emergency braking sensor volumes. For New Entrants and Emerging Players: Lead with solid-state optical phased array architectures for automotive LIDAR applications where mechanical scanning incumbents face displacement pressure. Target the Texas photonics corridor for defense contracts unbundled from integrated platform procurement. Pursue foundry partnerships with established MEMS cleanroom operators rather than greenfield fabrication investment. For Investors and Strategic Acquirers: Long-term, this sits as a defense-industrial convergence play because Army Futures Command procurement behavioral shifts are compressing vendor selection cycles for cleared domestic suppliers. Acquisition candidates with existing facility security clearances and ITAR-controlled production lines offer embedded optionality. Monitor California DMV autonomous vehicle testing rule expansions as the signal for LIDAR demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Functional Safety Certification | Unlocks autonomous emergency braking sensor volumes under NHTSA mandates. |
| Silicon Photonics Foundry Partnership | Enables volume manufacturing of chip-scale LIDAR engines for automotive deployment. |
| ITAR-Controlled Facility Clearance | Qualifies suppliers for Army Futures Command unbundled procurement pathways. |
| FDA Breakthrough Device Pathway Submission | Compresses review timelines for fluorescence-guided surgery systems. |
| MEMS Cleanroom Capacity Expansion | Captures defense and industrial demand in the Austin-San Antonio corridor. |
Research Methodology
A spread of perspectives from Tier-1 automotive procurement officers, MEMS foundry operations managers, FDA regulatory affairs leads, and defense program managers converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC 10-K filings, NHTSA Federal Register notices, FDA 510(k) clearance databases, and vehicle production data. Bottom-up unit economics and top-down market sizing triangulated across the modeling period.
Segmentation dimensions modeled include product type, technology architecture, end-user industry, and application use case across the projection horizon. CAGRs derived from regression analysis against automotive safety mandate implementation schedules and surgical navigation adoption curves. Forecast inputs incorporated InGaAs substrate cost trajectories and solid-state beam steering yield improvements.
The analysis sits within stated boundaries; outcomes outside NHTSA rulemaking timelines or FDA review pace assumptions would require recalibration. Forecasts reflect documented assumptions about defense procurement behavioral shifts and automotive OEM platform standardization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
CMP Polishing Machine Market
Optical Components
Acousto Optic Devices Market
Optical Components
Electro-Optic Modulators Market
Optical Components
3-7mm Galvo Scanner Market
Optical Components
Laser Photomask Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Passive Optical Component Market
Optical Components
Asia Pacific Optical Sensors Market
Optical Components
Quartz Glass Substrate Market
Optical Components
LAMEA Lithium Niobate Modulator Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Flexible Glass for Flexible Electronics Market
Optical Components
Global Diffractive Optical Elements Market