
 Cable Organisers Market | 2026-2036
Cable Organisers Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Organisers Market Analytics
RoHS compliance is recalibrating the cost-of-entry calculus for cable organiser manufacturers serving European industrial customers. HellermannTyton Group PLC leverages its integrated polymer compounding operations to sustain margin control across halogen-free product lines. Panduit Corp. anchors its competitive position through deep channel control in North American data center projects. Schneider Electric SE extends its electrical infrastructure dominance by bundling cable management with switchgear and power distribution systems.
Cable organisers encompass mechanical and electromechanical devices designed to route, secure, protect, and identify electrical and data cables within built environments, typically manufactured from injection-molded nylon 6/6, stainless steel 316, or woven polyester with operating temperature ratings from minus 40 to 85 degrees Celsius. Their primary commercial purpose is to maintain signal integrity, prevent mechanical damage, and enable traceability in dense cable populations across industrial, commercial, and residential installations. Plastic cable ties occupy the largest volume share due to commodity pricing and universal applicability, while metal cable trays command premium positioning in heavy industrial settings where load-bearing capacity and fire resistance justify higher unit economics. The IT sector end-use segment generates the fastest growth trajectory as hyperscale data center construction drives demand for overhead and underfloor routing systems with integrated airflow management.
FDA oversight of cable materials in medical device manufacturing, EPA regulations on volatile organic compound emissions from coating processes, and FCC electromagnetic compatibility standards for structured cabling installations collectively shape product design and market access requirements across the United States. The EU F-Gas Regulation and CE marking directives further constrain material selection and thermal performance claims for products deployed in European climate control and refrigeration applications. Stakeholders must monitor evolving building electrification codes and net-zero construction mandates that will redefine cable density requirements in commercial and residential developments.
Market Dynamics
Hyperscale data center buildouts are compressing procurement cycles for structured cable management systems while EU RoHS compliance is recalibrating material specifications across European industrial channels.
Growth Catalysts
- EU RoHS Directive:Restrictions on hazardous substances in electrical components are redirecting material sourcing toward halogen-free polymers, creating specification upgrade cycles across industrial automation retrofits.
- Hyperscale cloud expansion:Data center construction by cloud operators is accelerating demand for overhead and underfloor routing systems with integrated airflow management capabilities.
- German manufacturing investment:New production facilities and automation upgrades across Baden-Württemberg and Bavaria require extensive cable routing infrastructure for power and data networks.
Market Restraints
- Engineering resin cost volatility:Nylon 6/6 and halogen-free polymer feedstocks face price pressure from petrochemical supply fluctuations, squeezing margin structures on standard-grade cable ties.
- Specialty compounder concentration:European halogen-free polymer supply concentrates among integrated chemical groups, creating single-source risk for mid-tier cable organiser manufacturers.
- Metal tray substitution ceiling:Stainless steel 316 cable trays face technical limitations in weight-sensitive overhead installations, constraining penetration in certain data center configurations.
Strategic Opportunities
- India industrial corridor buildout:PLI scheme incentives for electronics manufacturing and semiconductor packaging are generating greenfield demand for cable management in Tamil Nadu and Gujarat facilities.
- Net-zero construction mandates:Building electrification codes across commercial developments are redefining cable density requirements, expanding addressable market for high-capacity routing systems.
- Digital twin convergence:Integration of cable management BIM models with facility management platforms creates attach opportunities for RFID-enabled identification and traceability systems.
Industry Challenges
- Polymer formulation expertise gap:Halogen-free compound development requires specialized flame-retardant chemistry knowledge that competes with broader electrical insulation talent pools.
- Multi-jurisdiction certification timelines:Simultaneous UL, CE, and BIS approval processes extend product launch cycles by 8-14 months for manufacturers serving cross-border projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Organisers Market |
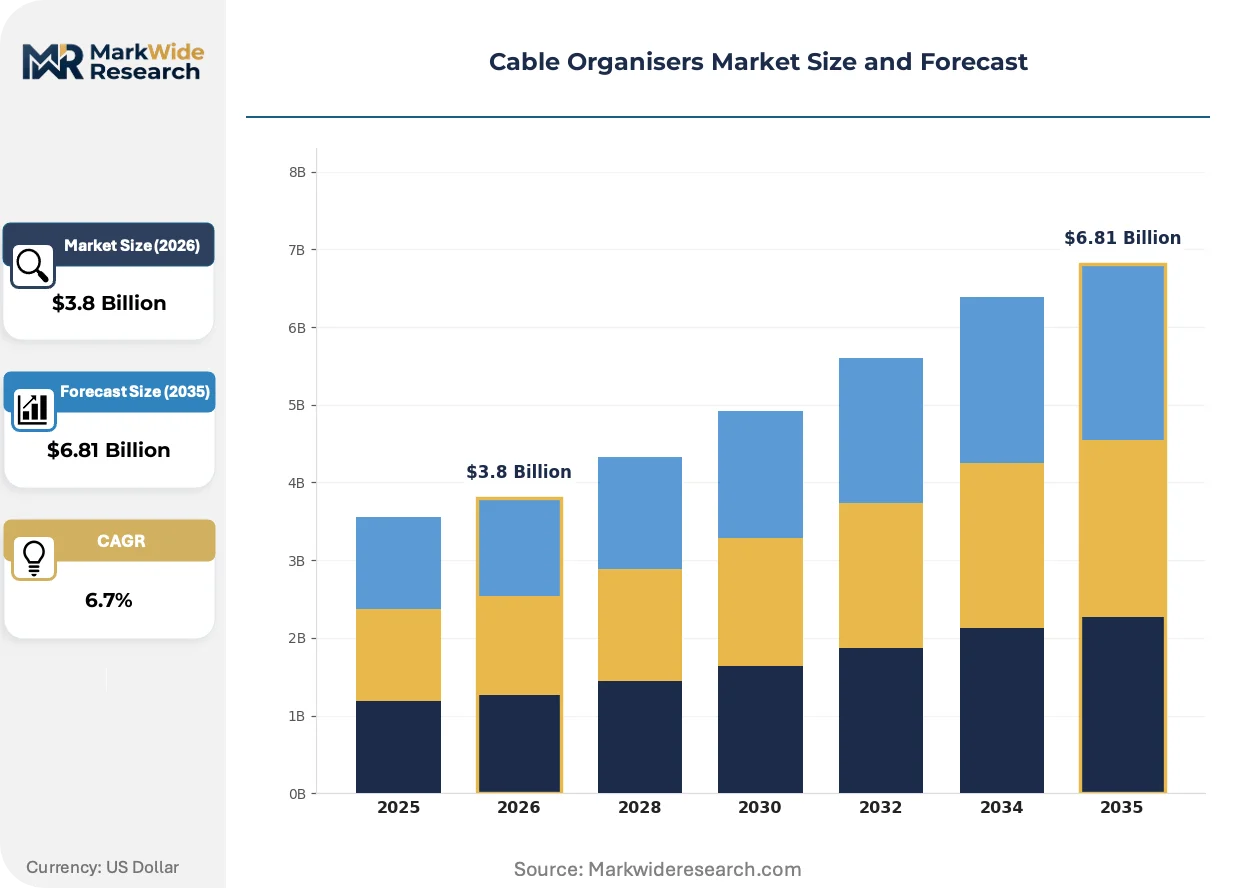
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Clips, Cable Ties, Cable Trays, Cable Sleeves Material: Plastic, Metal, Fabric, Rubber End User: Residential, Commercial, Industrial, IT Sector Functionality: Organization, Protection, Insulation, Identification |
| Companies Covered | TE Connectivity Ltd., HellermannTyton Group PLC, Thomas & Betts Corp., Niedax Group, Marco Cable Management, Schneider Electric SE, Panduit Corp., Legrand SA, Chatsworth Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Organisers Market Evolving Landscape
Material science advances and regulatory tightening are converging to reshape product specifications, while procurement centralization among hyperscale operators is compressing supplier qualification timelines.
Modular cable tray systems with tool-free snap-fit assembly are electrifying installation economics in data center environments. Facility operators at hyperscale campuses are specifying these systems for rapid reconfiguration during server refresh cycles. The technology is compressing mechanical contractor labor hours by eliminating traditional bolted connections and specialized fastening hardware.
REACH substance restrictions on persistent organic pollutants are forcing reformulation of flame-retardant additives in nylon 6/6 compounds. Compounders serving European cable tie manufacturers must validate alternative phosphorus-based systems without compromising UL 94 V-0 ratings. Industrial automation OEMs in Germany are accelerating supplier audits to ensure SVHC compliance documentation across their routing component portfolios.
Direct procurement relationships between hyperscale data center developers and cable management specialists are disintermediating traditional electrical distributor channels. Tier-one cloud operators are consolidating vendor lists to twenty or fewer approved suppliers with integrated design support capabilities. This concentration is most visible in Northern Virginia and Frankfurt am Main, where multiple concurrent campus developments create volume leverage for specification lock-in.
Cable Organisers Market Segmentation
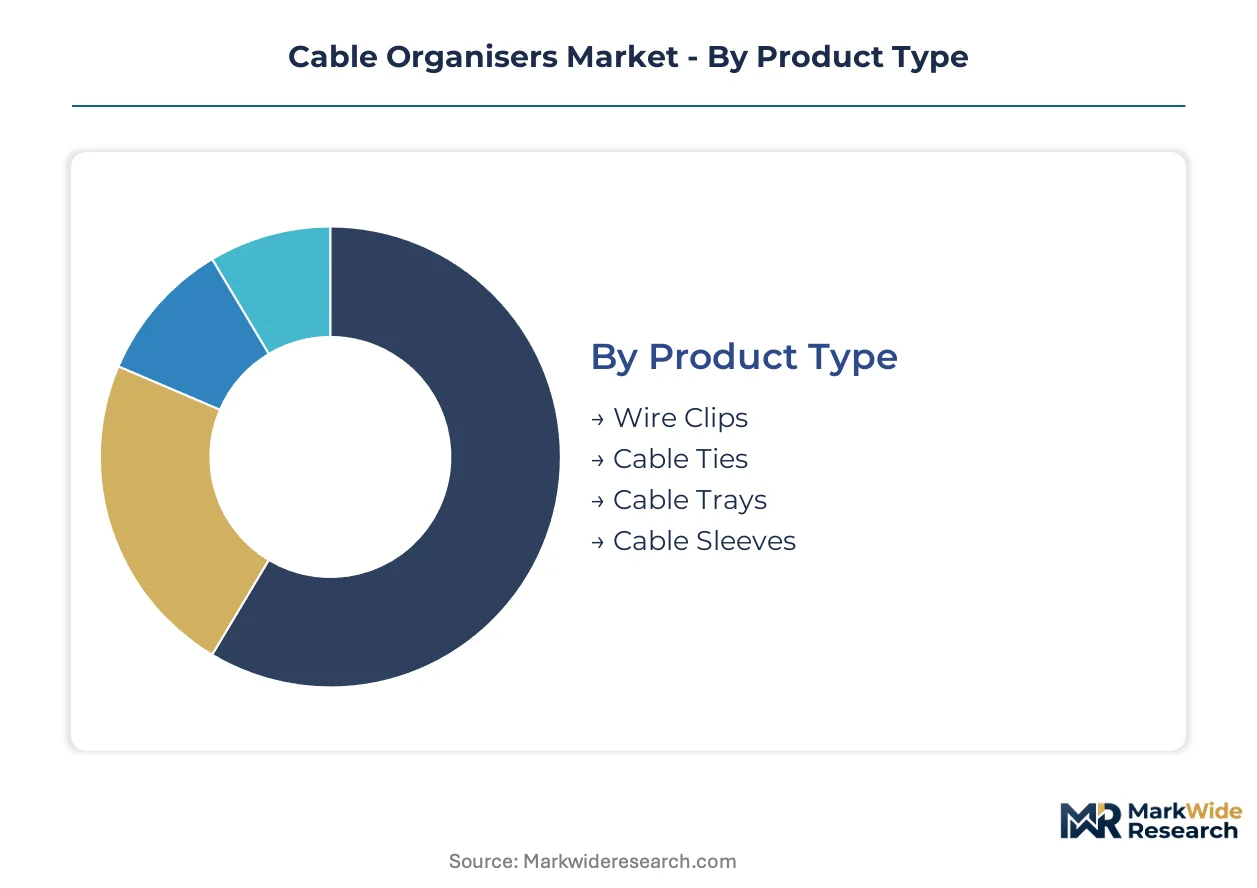
Cable organiser procurement patterns diverge sharply across installation environments, from commodity-grade residential hardware to mission-critical data center infrastructure requiring thermal and electromagnetic specifications. Material selection and functional requirements map directly to end-use severity, creating distinct margin tiers and supplier qualification barriers within each segment category.
Product Type:
Standardization dominates low-complexity fastening while modularity commands premium positioning in infrastructure-scale routing systems.
- Cable Ties:Injection-molded nylon 6/6 or halogen-free polymer strips with self-locking heads, available in standard, releasable, and mounted variants. German automotive and industrial automation OEMs drive specification upgrades toward heat-stabilized grades resistant to 105°C engine bay temperatures. Procurement concentrates through electrical distributors serving MRO channels.
- Cable Trays:Ladder, perforated, and wire-mesh configurations in stainless steel 316 or fiberglass-reinforced polymer. Hyperscale data center operators in Northern Virginia and Frankfurt am Main specify modular snap-fit systems for rapid reconfiguration during server refresh cycles. Load-bearing capacity and fire-resistance ratings justify 3-5x unit economics versus plastic alternatives.
- Wire Clips:Adhesive-backed or nail-mounted retention devices for surface cable routing, typically manufactured from polypropylene or spring steel. Residential and light commercial electrical contractors represent the primary demand channel.
- Cable Sleeves:Braided polyester, neoprene, or split-loom corrugated tubing for abrasion protection and aesthetic bundling. Gaming PC builders and audiovisual installers favor expandable braided designs for visible cable management.
Leading the category by volume: Cable Ties. Expanding most quickly: Cable Trays.
Material:
Cost tiers stratify from commodity petrochemical feedstocks through engineered compounds with regulatory compliance premiums.
- Plastic:Nylon 6/6 dominates commodity cable ties through balance of tensile strength, temperature resistance, and injection-molding economics. EU RoHS and REACH compliance is recalibrating formulations toward halogen-free flame-retardant systems, with phosphorus-based additives displacing brominated compounds.
- Metal:Stainless steel 316 cable trays and ladder systems serve heavy industrial and offshore applications where corrosion resistance and load capacity override weight penalties. Fabrication concentrates among regional metalworking specialists with plasma cutting and automated welding capabilities.
- Fabric:Woven polyester and Kevlar-reinforced sleeves provide flexible abrasion protection with electromagnetic shielding variants for sensitive signal cabling. Custom lengths and color-coding support identification protocols in broadcast and medical equipment.
- Rubber:Neoprene and EPDM grommets, edge guards, and cushion mounts address vibration damping and chafing protection in automotive and railway rolling stock.
Plastic commands absolute volume share. Metal captures highest value per kilogram.
End User:
Customer sophistication spans retail DIY purchasers through specification-engineered procurement teams at hyperscale operators.
- IT Sector:Data center developers and colocation operators drive demand for overhead and underfloor routing with integrated airflow management. Direct procurement relationships with approved vendor lists disintermediate traditional electrical distribution, consolidating supply among twenty or fewer specialists with BIM integration capabilities.
- Industrial:Manufacturing facility retrofits and greenfield automation deployments in Germany, India, and the United States require extensive power and data cable infrastructure. Specifiers prioritize UL-listed and CE-marked components with documented flame-spread ratings.
- Commercial:Office fit-outs, retail environments, and healthcare facilities balance aesthetic concealment with accessibility for maintenance. Building electrification codes are expanding cable density requirements in net-zero construction mandates.
- Residential:Home improvement retailers and electrical contractors supply standard-grade cable ties, clips, and surface raceways. Price sensitivity limits specification complexity to basic color and length variants.
Industrial installations represent the largest absolute revenue pool. IT Sector climbs the fastest.
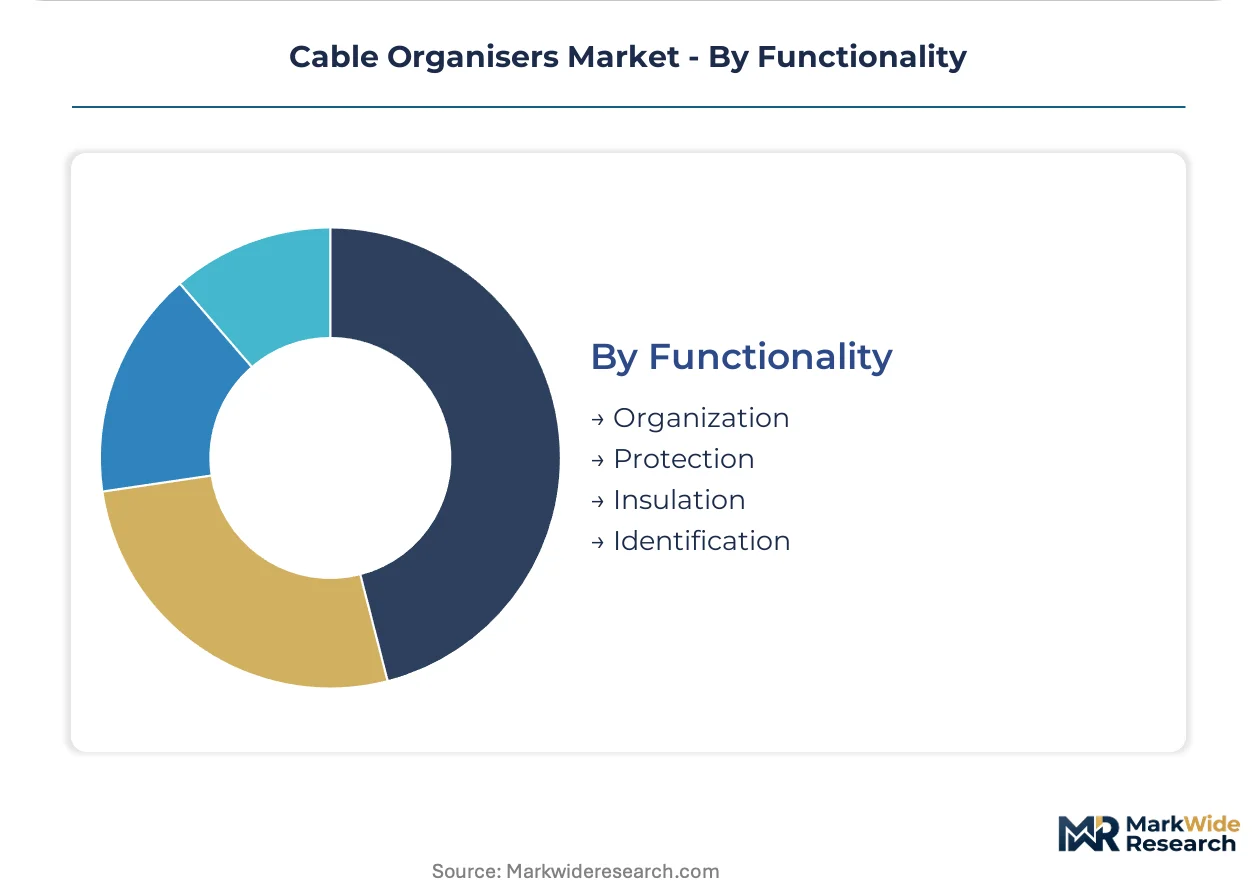
Functionality:
Basic mechanical retention gives way to intelligent identification and environmental protection as installation criticality escalates.
- Organization:Routing, bundling, and strain relief functions through cable ties, trays, and clips. The foundational purpose across all end-use segments, with differentiation emerging through installation speed and reconfigurability.
- Protection:Abrasion resistance, moisture sealing, and mechanical impact absorption via sleeves, grommets, and conduit systems. Industrial and outdoor applications specify IP ratings and UV stabilization.
- Identification:Color-coding, printed markers, and RFID-enabled tags enabling traceability in dense cable populations. Digital twin convergence is attaching sensor-enabled identification to facility management platforms.
- Insulation:Dielectric separation and thermal management in high-voltage and high-temperature environments. Material selection must satisfy IEC and UL electrical safety standards.
Organization generates foundational volume. Identification gains share fastest through smart infrastructure convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Tamil Nadu and Gujarat concentrate India's emerging electronics manufacturing capacity. German industrial automation clusters absorb premium-grade cable management systems. Data center developments in Northern Virginia and Frankfurt am Main compress procurement timelines for infrastructure-scale routing products.
United States
Hyperscale cloud operators in Northern Virginia drive specification-grade demand for modular cable tray systems with integrated airflow management. FCC electromagnetic compatibility standards constrain material selection for structured cabling installations. Dallas-Fort Worth and Phoenix data center corridors expand vendor qualification programs for approved supplier lists.
Germany
Automotive OEMs in Baden-Württemberg and industrial automation deployments in Bavaria require heat-stabilized cable ties rated to 105°C engine bay temperatures. EU RoHS and REACH directives mandate halogen-free polymer formulations across supplier portfolios. Stuttgart and Munich engineering offices accelerate SVHC compliance audits for routing component vendors.
India
PLI scheme incentives for electronics manufacturing and semiconductor packaging generate greenfield cable management demand in Tamil Nadu and Gujarat facilities. BIS certification requirements extend product launch timelines for cross-border suppliers. Chennai and Ahmedabad industrial corridors attract tier-one component manufacturers seeking localization advantages.
China
Data center construction in the Yangtze River Delta and Pearl River Delta sustains volume procurement of overhead routing systems. GB standards and MIIT regulations govern flame-retardant performance claims for electrical installation products. Shanghai and Shenzhen hyperscale campuses consolidate vendor relationships with integrated design support capabilities.
Japan
Precision manufacturing facilities in the Kanto region specify high-reliability cable identification systems for dense automation environments. METI energy efficiency guidelines influence thermal management specifications for data center infrastructure. Tokyo and Yokohama industrial zones maintain stringent JIS compliance requirements for imported routing components.
Cable Organisers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Electrical infrastructure groups bundle cable management with switchgear and power distribution systems. Pure-play specialists concentrate on polymer compounding and channel control in specific geographies. Competitive moves center on backward integration into halogen-free compound production and direct procurement relationships with hyperscale operators.
Among diversified electrical infrastructure groups, Schneider Electric SE and Legrand SA occupy positions spanning integrated power and routing solutions. HellermannTyton Group PLC exemplifies the polymer compounding specialist archetype with integrated material operations. Panduit Corp. anchors the channel-control segment through deep relationships in North American data center projects. TE Connectivity Ltd. represents the connectivity-focused conglomerate with cable management as an adjacent portfolio element.
| Leading Market Players |
|---|
| TE Connectivity Ltd. |
| HellermannTyton Group PLC |
| Thomas & Betts Corp. |
| Niedax Group |
| Marco Cable Management |
| Schneider Electric SE |
| Panduit Corp. |
| Legrand SA |
| Chatsworth Products Inc. |
| Others |
Value Network & Pricing Analysis
EU RoHS compliance mandates are gating qualified supply access and premium-tier pricing power by restricting halogen-free polymer formulations to certified compounders with validated flame-retardant chemistry. Buyers seeking SVHC-compliant cable management systems face contracted vendor pools and extended qualification timelines that sustain margin premiums for integrated manufacturers.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning while spot inventory commands discount tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Cost compression in standard-grade nylon cable ties is intensifying because petrochemical feedstock volatility squeezes compounder margins. Residential electrical contractors exhibit highest price sensitivity, while hyperscale data center procurement teams prioritize specification compliance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from German automotive OEMs and hyperscale operators mandate multi-supplier qualification across halogen-free polymer feedstocks. Manufacturing concentrates in Germany, China, and the United States for injection-molded components and stainless steel fabrication. Supply rests on caprolactam monomer, phosphorus-based flame retardants, and 316-grade stainless steel coil. Single-source vulnerability concentrates among European specialty compounders with REACH-validated additive packages. Distribution runs through electrical distributors serving MRO channels and direct procurement relationships with tier-one infrastructure developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Halogen-free polymer compounding capacity constraints are propping pricing premiums by limiting qualified supplier participation in European industrial channels. Supply scarcity among REACH-compliant compounders sustains margin structures for backward-integrated manufacturers.
For Market Incumbents: Deepen captive supply of phosphorus-based flame-retardant compounds to defend against specialty chemical group concentration risk. Expand compounding operations in Baden-Württemberg to secure proximity to automotive OEM specification teams. Prioritize BIM integration capabilities to maintain position on hyperscale approved vendor lists.
For New Entrants and Emerging Players: Mid-tier Indian electronics manufacturers represent an underserved buyer archetype with accelerating cable management demand from PLI scheme investments. Target Tamil Nadu and Gujarat industrial corridors with localized BIS certification and rapid-turn customization services. Establish direct relationships with semiconductor packaging facility engineering teams before distributor channel lock-in solidifies.
For Investors and Strategic Acquirers: Consolidation among European cable tie manufacturers is the leading indicator that polymer formulation expertise scarcity is driving acquisition premiums. Five-to-ten year viability favors integrated compounders with validated SVHC documentation and hyperscale direct procurement relationships. Watch for REACH substance restriction expansions triggering forced supplier replacement cycles as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Halogen-Free Compounding | Captive supply of REACH-compliant polymers secures margin control against specialty chemical concentration. |
| BIM Model Integration for Digital Twin Convergence | RFID-enabled cable identification attaches to facility management platforms at hyperscale campuses. |
| Localized BIS Certification in India | Chennai and Ahmedabad industrial corridors demand shortened approval timelines for cross-border suppliers. |
| Direct Procurement Relationship Development | Tier-one cloud operators in Northern Virginia and Frankfurt consolidate vendor lists to twenty or fewer specialists. |
| Modular Snap-Fit System Expansion | Tool-free cable tray assembly compresses mechanical contractor labor hours during data center server refresh cycles. |
Research Methodology
Document review covered SEC 10-K filings, EU REACH substance restriction databases, and hyperscaler capital expenditure disclosures, complemented by interviews with polymer compounding plant managers, data center facility engineering directors, electrical distributor procurement leads, and industrial automation OEM specification engineers. Secondary validation drew from customs trade data, BIS certification registries, and construction project development databases. Bottom-up demand modeling and top-down market sizing were triangulated across primary and secondary inputs.
Cross-reference between historical volume trajectories and expert panel input anchored the analytical framework across the analysis window. Segmentation dimensions included product type, material formulation, end-use severity tier, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and replacement cycle compression. Forecast inputs incorporated data center construction pipeline tracking and industrial automation retrofit intensity indices.
Revisions become necessary when REACH substance restriction expansions, petrochemical supply disruptions, or hyperscale procurement centralization shifts materialize. Deviation in halogen-free polymer compounding capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Global Low Voltage Cable Market
Cables
Class 1E Electric Cables Market
Cables
Fire Resistance Cable Market
Cables
Nuclear Multi-Conductor Cables Market
Cables
Europe Cable Management Market
Cables
Power Cable Accessories Market
Cables
EPR Cable Market
Cables
North America Coaxial Cable Market
Cables
Europe Cable Joints Market
Cables
Cable Management Accessories Market
Cables
LED Cable Market
Cables
Audio and Video Cables Market
Cables
Insulated Wire and Cable Market
Cables
Cable Detector Market
Cables
North America Wire and Cable Market
Cables
HVDC Cables Market