
 Europe Cable Management Market | 2026-2036
Europe Cable Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cable Management Market Foresight
German cable tray manufacturers is recalibrating capacity to serve accelerating data center builds across the Rhine-Ruhr and Frankfurt regions. Legrand SA leverages its European distribution network to sustain project-level contracts for commercial infrastructure. Schneider Electric SE anchors its position through integrated building electrification portfolios that bundle cable management with switchgear and energy management systems.
Europe cable management encompasses the engineered routing, protection, and organization of electrical and data cables through trays, conduits, ladders, and fastening systems, typically fabricated from galvanized steel, aluminum, PVC, or halogen-free thermoplastics rated for fire resistance and electromagnetic shielding. Its primary commercial purpose is to ensure safety compliance, reduce installation labor, and extend cable service life across buildings and industrial plants. Trays and conduits dominate value capture given their structural role in heavy-current and data-intensive environments, while accessories generate recurring revenue through retrofit and maintenance cycles. Plastic materials are gaining share in commercial and residential applications as REACH-compliant halogen-free compounds displace legacy PVC formulations.
CE marking under the EU Construction Products Regulation mandates fire-performance classification for cable management systems installed in public buildings and transport infrastructure. ECHA's REACH restrictions on halogenated flame retardants are reshaping material specifications across the supply chain, compelling reformulation of plastic compounds. The EU Green Deal's embodied carbon requirements are beginning to filter into public procurement criteria for construction materials. Stakeholders must monitor how the EU AI Act's infrastructure requirements for high-performance computing clusters translate into cable density specifications for new data center builds.
Market Dynamics
Data center construction across Germany and France is compressing cable management procurement cycles while REACH compliance mandates are forcing wholesale material reformulation across plastic compound supply chains.
Growth Catalysts
- EU Green Deal embodied carbon rules:Public procurement criteria now favor low-carbon cable tray and conduit materials, redirecting specification authority toward sustainability-certified suppliers.
- Hyperscale data center clustering:Frankfurt and Amsterdam metro areas are generating concentrated demand for high-density cable routing systems rated for 400G+ fiber deployments.
- Halogen-free thermoplastic advances:Polypropylene and thermoplastic elastomer compounds are achieving fire-performance ratings previously exclusive to PVC, unlocking commercial building retrofits.
Market Restraints
- Galvanized steel price volatility:Hot-rolled coil input costs fluctuate with energy-intensive European steel production curbs, compressing tray manufacturer margins.
- German supply concentration:Three mid-cap fabricators control roughly half of continental tray capacity, creating vulnerability to localized production disruptions.
- REACH registration timelines:New halogen-free flame retardant chemistries face 18-24 month ECHA evaluation windows, delaying product commercialization.
Strategic Opportunities
- Eastern European data center greenfield:Poland and Romania offer underpenetrated markets where cable density specifications lag Western hyperscale standards.
- EU AI Act infrastructure mandates:High-performance computing cluster requirements will specify enhanced electromagnetic shielding for power distribution cabling.
- Direct-to-contractor digital platforms:B2B marketplaces are disintermediating traditional electrical distributor networks for standard conduit and fastening SKUs.
Industry Challenges
- Fire-performance certification bottlenecks:CE marking under the Construction Products Regulation requires third-party testing that extends lead times by 8-12 weeks.
- Legacy building retrofit integration:Existing concrete-embedded conduit systems obstruct modular cable tray installation in heritage commercial structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cable Management Market |
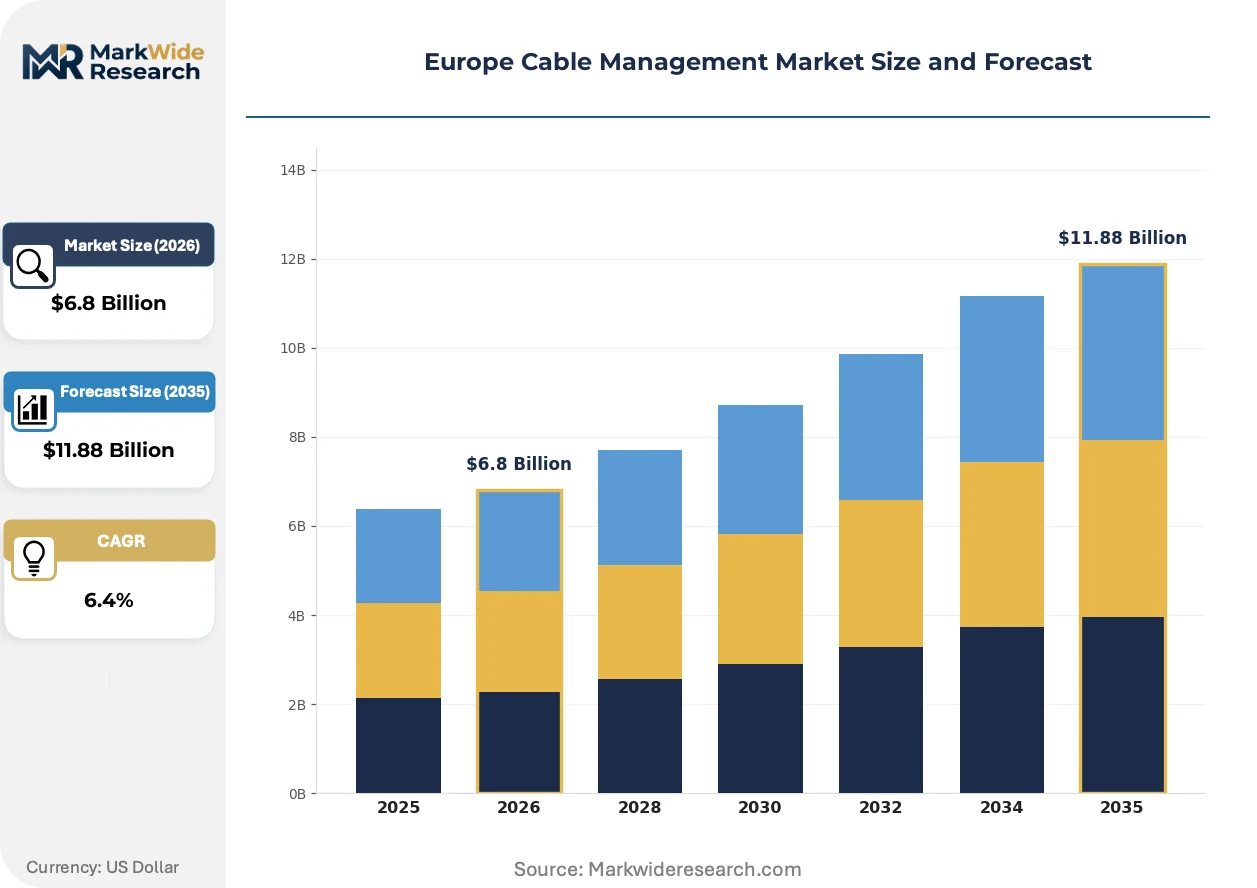
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cables, Trays, Conduits, Accessories Material: Plastic, Metal, Rubber, Composite End User: Telecom, IT Services, Manufacturing, Construction Application: Data Centers, Industrial Settings, Residential, Commercial |
| Companies Covered | Legrand SA, Schneider Electric SE, Thomas & Betts Corporation (ABB Ltd), Hellermann Tyton, Marco Cable Management, NIEDAX GROUP, Eaton Corporation, Vantrunk International, Panduit, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cable Management Market Shifts & Advancements
Material science advances and procurement digitization are restructuring how cable management systems are specified, sourced, and installed across European construction value chains.
Intelligent cable management systems incorporating IoT-enabled thermal monitoring and predictive maintenance algorithms are converging with building management system architectures. Data center operators in Frankfurt and Amsterdam are specifying these sensor-integrated trays for mission-critical power distribution. This convergence is compressing the traditional separation between passive infrastructure and active building systems.
REACH restrictions on halogenated flame retardants are compelling compounders to validate phosphorus-nitrogen and metal hydroxide alternatives. ECHA's 2023-2024 substance evaluations have disqualified several legacy brominated formulations from new product introductions. Cable tray manufacturers serving French public transport infrastructure are responding fastest due to stringent smoke-toxicity requirements.
Engineering firms are consolidating vendor panels and demanding lifecycle cost documentation rather than upfront material pricing. Tier-one contractors in Germany's Rhine-Ruhr industrial corridor now require 25-year service life guarantees and embodied carbon disclosures. This behavioral shift is most pronounced in healthcare and education verticals where public procurement rules enforce total-cost evaluation.
Europe Cable Management Market Segmentation
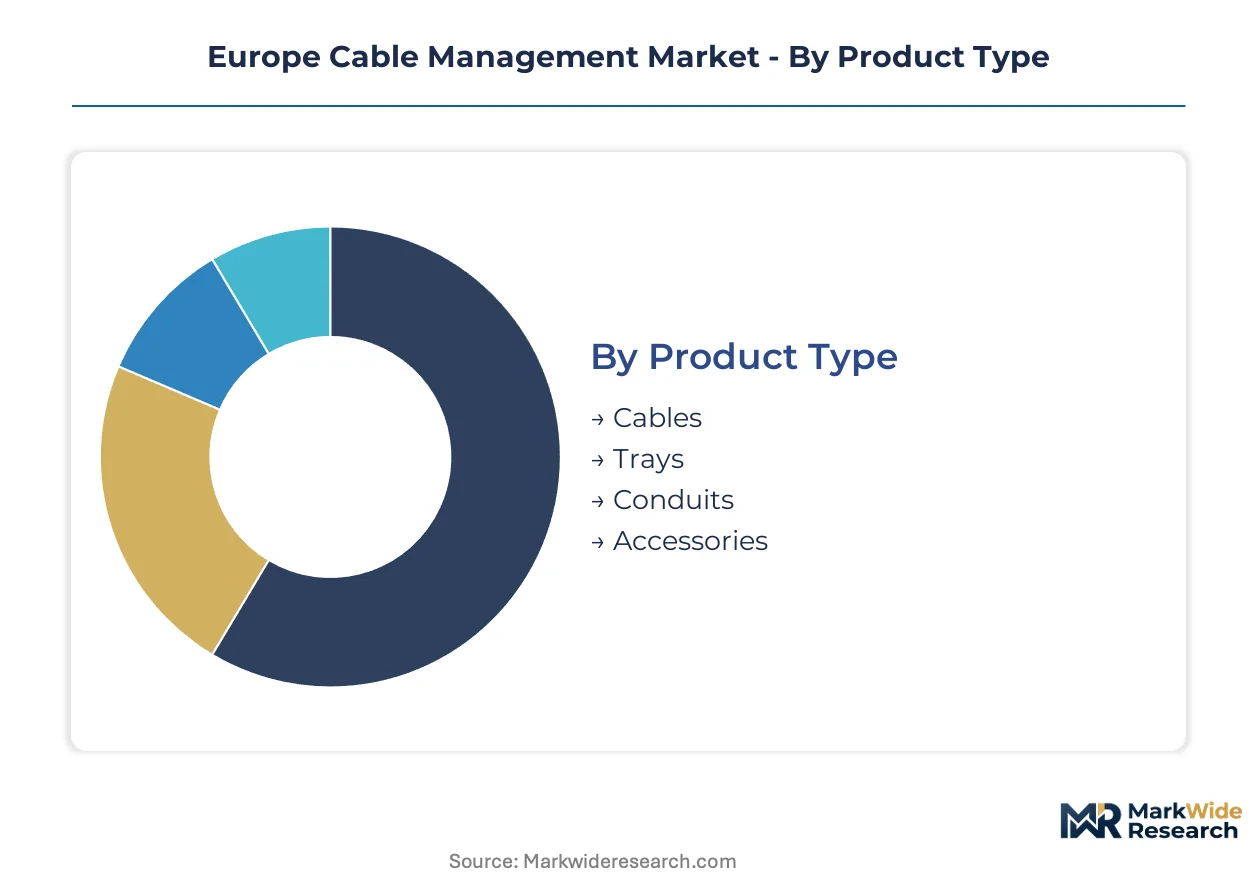
Segmentation in Europe cable management reveals how specification authority flows from project type to material choice. Understanding these splits exposes where procurement cycles compress and where regulatory compliance reshapes supplier selection.
Product Type:
Integration depth varies sharply—trays and conduits function as standalone structural infrastructure, while cables and accessories embed within broader electrical systems.
- Trays:Galvanized steel and aluminum ladder structures route heavy-current and data cables across industrial plants and hyperscale facilities. Demand concentrates in Frankfurt and Amsterdam data center corridors where 400G+ fiber densities require engineered load-bearing pathways.
- Conduits:Rigid and flexible tubing systems protect power and signal cables from mechanical damage and environmental exposure. French public transport infrastructure projects are driving specification of low-smoke zero-halogen variants under stringent fire-toxicity mandates.
- Cables:Power distribution and fiber optic transmission media integrate into tray and conduit systems as purchased components rather than standalone infrastructure. Procurement typically bundles with broader electrical contractor packages.
- Accessories:Fasteners, supports, and connection hardware generate recurring retrofit revenue through maintenance cycles. These items embed within facility management budgets rather than capital construction allocations.
Trays lead volumes today; conduits are gaining share fastest.
Material:
Cost tiers separate premium-certified formulations from commodity-grade alternatives, with regulatory compliance acting as the primary price escalator.
- Metal:Galvanized steel and aluminum dominate heavy-load industrial applications where structural integrity and electromagnetic shielding prove critical. Rhine-Ruhr manufacturing corridors sustain concentrated demand despite hot-rolled coil price volatility compressing fabricator margins.
- Plastic:PVC and halogen-free thermoplastic compounds serve commercial and residential builds where weight reduction and corrosion resistance matter. REACH restrictions on halogenated flame retardants are accelerating substitution toward phosphorus-nitrogen formulations in French and German public buildings.
- Rubber:Elastomeric compounds provide flexibility and vibration damping in mobile equipment and harsh-environment installations. Applications concentrate in industrial machinery and transport infrastructure.
- Composite:Fiberglass-reinforced and mineral-filled materials occupy niche roles requiring non-conductive, lightweight, and corrosion-resistant properties. Offshore and chemical processing facilities in North Sea corridors represent primary uptake zones.
Metal dominates installed base; plastic is expanding most quickly.
End User:
Customer type determines contract structure—project-based capital expenditure versus recurring operational procurement.
- IT Services:Hyperscale data center operators and cloud infrastructure providers specify high-density cable routing for mission-critical power distribution. Frankfurt and Amsterdam metro areas generate concentrated demand with compressed procurement cycles.
- Construction:Commercial and residential building developers integrate cable management into electrical subcontractor packages. EU Green Deal embodied carbon criteria are redirecting specification authority toward sustainability-certified suppliers in German healthcare and education verticals.
- Manufacturing:Industrial plant operators prioritize durability and modularity for production line reconfiguration. Demand clusters in Germany's automotive and machinery production corridors.
- Telecom:Network infrastructure operators deploy outdoor-rated conduit and tray systems for 5G backhaul and fiber distribution. Poland and Romania greenfield builds lag Western density specifications, creating upgrade cycles.
Construction leads contract volumes; IT Services shows the steepest expansion trajectory.
Application:
Application maturity separates established retrofit markets from greenfield specification opportunities.
- Data Centers:Hyperscale and colocation facilities demand high-density, thermally monitored cable infrastructure for power and fiber distribution. Frankfurt's clustering of compute capacity is intensifying procurement of sensor-integrated tray systems.
- Industrial Settings:Manufacturing plants and process facilities require heavy-duty metal tray systems rated for mechanical loading and chemical exposure. Germany's industrial corridor sustains replacement cycles for aging infrastructure.
- Commercial:Office buildings, retail, and hospitality projects specify lighter-weight plastic and composite systems. CE marking under the Construction Products Regulation mandates fire-performance classification for public building installations.
- Residential:Single and multi-family housing employs standard conduit and fastening systems through electrical contractor channels. Procurement digitization via B2B marketplaces is disintermediating traditional distributor networks for these SKUs.
Industrial Settings anchor current volumes; Data Centers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance costs and ECHA registration timelines are redistributing cable management production toward jurisdictions with established chemical safety infrastructure, narrowing the arbitrage window for peripheral manufacturers.
Germany
Hyperscale data center construction in Frankfurt and the Rhine-Ruhr corridor is compressing procurement cycles for high-density cable trays. ECHA's substance evaluations under REACH are disqualifying legacy halogenated flame retardants from new product introductions. Three mid-cap fabricators control roughly half of continental tray capacity, concentrating supply risk in North Rhine-Westphalia's industrial belt.
France
Public transport infrastructure projects are driving specification of low-smoke zero-halogen conduit variants under stringent fire-toxicity mandates. The EU Green Deal's embodied carbon criteria are redirecting procurement authority toward sustainability-certified suppliers in healthcare and education verticals. Île-de-France's metro expansion and Grand Paris Express are generating concentrated demand for CE-marked cable management systems.
Netherlands
Amsterdam's clustering of cloud infrastructure is intensifying demand for 400G+ fiber-rated cable routing systems. The Dutch national building code's fire-performance classification requirements are filtering into commercial specification standards. Randstad logistics hubs are serving as distribution nodes for REACH-compliant halogen-free compounds across the Benelux region.
Poland
Greenfield data center builds are lagging Western density specifications, creating upgrade cycles for cable infrastructure. The country's national building regulator is aligning fire-safety standards with EU Construction Products Regulation requirements. Warsaw and Kraków metro areas are attracting hyperscale investments that will specify enhanced electromagnetic shielding for power distribution.
United Kingdom
Post-Brexit regulatory divergence from REACH is creating compliance complexity for cross-border supply chains. London's financial services data centers are maintaining procurement specifications aligned with EU fire-performance standards. The Southeast's commercial construction pipeline is embedding cable management into electrical subcontractor packages with 25-year service life guarantees.
Europe Cable Management Market Competitive Landscape
German and French producers anchor the premium tier; Italian and Polish specialists hold mid-market positions through cost-competitive fabrication. The vendor base organizes around three strategic archetypes: integrated building electrification portfolios, distribution-network players with project-level contracting capabilities, and focused tray-and-conduit fabricators serving regional industrial corridors. M&A activity concentrates on acquiring REACH-compliant compound formulation expertise, while capacity expansion targets Eastern European greenfield data center zones.
Within the integrated portfolio tier, Legrand SA and Schneider Electric SE exemplify archetypes that bundle cable management with broader electrical infrastructure offerings. Thomas & Betts Corporation, operating under ABB Ltd, represents the industrial conglomerate model where cable routing functions as a component within comprehensive power distribution systems. These three entities occupy positions that reflect distinct strategic postures: project-level contracting authority, building system integration depth, and industrial-scale manufacturing reach.
| Leading Market Players |
|---|
| Legrand SA |
| Schneider Electric SE |
| Thomas & Betts Corporation (ABB Ltd) |
| Hellermann Tyton |
| Marco Cable Management |
| NIEDAX GROUP |
| Eaton Corporation |
| Vantrunk International |
| Panduit |
| Others |
Supply & Pricing Matrix
CE-marking certification tiers split the European cable management landscape into premium fire-rated and commodity-grade supply pools, with REACH-compliant halogen-free compound formulations commanding structural margin premiums while galvanized steel tray fabricators absorb hot-rolled coil volatility through project-based contract structures. This bifurcation channels procurement authority toward sustainability-certified suppliers in German healthcare and French public transport verticals, compressing distributor margins for standard PVC conduit SKUs.
Pricing Analysis
Distributor margins compress most acutely in standard conduit and fastening SKUs where B2B marketplaces disintermediate traditional electrical wholesaler networks. Three-tier pricing structure across premium, standard, and economy levels reflects fire-performance certification grade and embodied carbon disclosure completeness. Pricing pressure stems from hot-rolled coil input cost volatility and REACH registration timeline delays for new flame retardant chemistries. IT Services hyperscale buyers show least price sensitivity given mission-critical uptime requirements, while residential construction contractors exhibit acute sensitivity to per-meter conduit pricing.
Supply Chain Analysis
CE marking and ECHA REACH registration requirements gate market access for compound suppliers and tray fabricators, concentrating qualified production in Germany, France, and the Netherlands. Raw material dependencies center on hot-rolled galvanized steel coil, aluminum extrusion billets, and phosphorus-nitrogen flame retardant formulations. Supply chain risk concentrates in single-source vulnerability for halogen-free thermoplastic compounds during 18-24 month ECHA evaluation windows. Distribution runs through electrical distributor networks for project-level contracts and direct-to-contractor digital platforms for standard SKU replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European cable management has matured into a late-cycle quality market where specification authority migrates toward REACH-compliant, fire-certified suppliers as EU Green Deal procurement criteria harden across German healthcare and French transport infrastructure.
For Market Incumbents: Anchor market position through captive supply of REACH-registered halogen-free compounds and backward integration into aluminum extrusion capacity. Defend against Eastern European cost-competitive entrants by locking 25-year service life guarantees with Rhine-Ruhr data center operators. Prioritize certification investment for low-smoke zero-halogen variants ahead of French public transport expansion timelines. For New Entrants and Emerging Players: The mid-market price-point gap between premium CE-marked systems and commodity PVC conduit creates white-space opportunity in Polish and Romanian data center greenfield builds where density specifications lag Western hyperscale standards. Target telecom infrastructure operators in Warsaw and Kraków metro areas with outdoor-rated electromagnetic shielding solutions. Pursue direct-to-contractor digital platform partnerships to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH formulation expertise concentrates among mid-cap German compounders with limited geographic diversification. Frame long-term viability around 5-10 year regulatory compliance moats rather than volume scale. Target acquisition profiles emphasizing ECHA-registered substance portfolios and established CE marking test house relationships. Watch for inflection signals in EU AI Act infrastructure mandates specifying enhanced electromagnetic shielding for high-performance computing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Compound Formulation | ECHA registration locks in multi-year supply relationships with German automotive and data center contractors. |
| Direct-to-Contractor Digital Platform | B2B marketplace integration disintermediates traditional electrical distributor networks for standard SKU procurement. |
| Sensor-Integrated Tray Systems | IoT-enabled thermal monitoring converges cable management with building management system architectures in Frankfurt facilities. |
| Eastern European Capacity Expansion | Polish and Romanian greenfield data center zones offer underpenetrated markets with upgrade cycle potential. |
| Backward Integration into Aluminum Extrusion | In-house billet processing insulates margin from LME price volatility and energy-intensive European smelter curbs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cable tray fabricator procurement directors, electrical contractor project managers, ECHA regulatory affairs specialists, and data center infrastructure engineers with secondary validation against EU Construction Products Regulation filings, ECHA substance evaluation databases, SEC disclosures from listed building electrification portfolios, and German federal procurement records. Bottom-up SKU-level volume estimates and top-down sectoral expenditure analysis triangulated to produce segment-weighted market outputs.
Segment-weighting approaches applied differential growth assumptions across product type, material formulation, end-user vertical, and application intensity dimensions. Modeled splits included tray versus conduit versus accessory capture rates, metal versus plastic versus composite material shares, IT Services versus Construction versus Manufacturing end-user procurement cycles, and Data Center versus Industrial versus Commercial application densities. CAGRs derived from regression analysis of historical capex patterns and regulatory compliance cost trajectories, with hyperscale data center clustering intensity and REACH registration timeline delays as primary forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for intelligent IoT-enabled cable management systems would alter the outlook if building management system integration standards diverge from current convergence trajectories. Forecasts reflect assumptions regarding ECHA evaluation timeline stability and EU Green Deal procurement criteria enforcement intensity. A model refresh is warranted upon material change in EU AI Act infrastructure specification releases or REACH substance restriction amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Europe Cable Accessories Market
Cables
Single Core Cables Market
Cables
Network Cable Tester Market
Cables
EPR Cable Market
Cables
Industrial Cable Reels Market
Cables
Copper Cabling Systems Market
Cables
Global Cable Blowing Equipment Market
Cables
Cable Accessories Market
Cables
Power and Control Cable Market
Cables
Global Wires and Cables Market
Cables
Magnetic Charging Cable Market
Cables
Military Fiber Optic Cables Market
Cables
High Voltage Cable Termination Market
Cables
North America Coaxial Cable Market
Cables
Audio and Video Cables Market
Cables
Mexico Wires and Cables Market