
 Audio and Video Cables Market | 2026-2036
Audio and Video Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Audio and Video Cables Market Outlook
Copper-clad aluminum conductor construction is realigning cost-performance tradeoffs across mid-tier HDMI and RCA product lines. Belden Inc. sustains premium positioning through rigorous signal-integrity testing protocols for broadcast applications. Prysmian Group leverages integrated fiber-optic manufacturing to serve professional audio and data-center interconnect demand. Amphenol Corporation anchors its competitive stance through modular connector platforms that span multiple broadcast and networking standards.
Audio and video cables are electromechanical assemblies engineered to transmit analog or digital signals between source and display or reproduction equipment, with critical parameters including impedance matching, shielding effectiveness measured in decibels of attenuation, and bandwidth capacity governed by conductor geometry and dielectric material selection. The primary commercial purpose centers on preserving signal fidelity across distances ranging from in-device interconnects to facility-scale distribution in broadcast and enterprise environments. HDMI product lines command the largest revenue share due to ubiquity in consumer electronics and mandatory 4K/8K compatibility requirements, while fiber optic material segments exhibit the steepest trajectory as professional audio and broadcasting applications migrate to optical transmission for immunity to electromagnetic interference and extended reach. Copper material categories remain volume-dominant in computer networking and home theater applications where cost sensitivity and legacy infrastructure compatibility constrain substitution.
HDMI Forum specification licensing, European Union REACH substance restrictions on halogenated flame retardants, and FCC Part 15 electromagnetic emissions standards in the United States collectively dictate material choices, testing burdens, and market access conditions for cable manufacturers. CE marking requirements under EU directive frameworks mandate conformity assessment before products enter European distribution channels, while RoHS compliance restricts hazardous substance content across all electrical and electronic equipment sold in member states. Stakeholders must monitor specification revision cycles, evolving substance restrictions, and regional certification reciprocity agreements to align product roadmaps with compliance obligations and procurement qualification timelines.
Market Dynamics
Broadcast infrastructure modernization across Western Europe is compressing procurement cycles for professional-grade interconnects while HDMI 2.1 specification mandates force consumer cable portfolio refreshes. Copper conductor volatility and fiber-optic capacity expansion are redrawing cost-performance boundaries across all tiers.
Growth Catalysts
- Fiber-to-the-Home Deployments:National broadband initiatives in Vietnam and India are accelerating optical cable pull-through for residential AV distribution. Infrastructure contractors specify armored fiber assemblies for last-mile durability.
- REACH Substance Mandates:ECHA restrictions on halogenated flame retardants are forcing reformulation of PVC jacket compounds toward phosphorus-based alternatives. Compliant cable producers capture preferential placement in EU retail channels.
- 8K Broadcast Transition:Professional sports production facilities in Germany and the United Kingdom are rewiring with 48Gbps-rated HDMI and SDI-over-fiber for uncompressed video transport. Studio rebuilds specify shielded twisted-pair with enhanced EMC performance.
Market Restraints
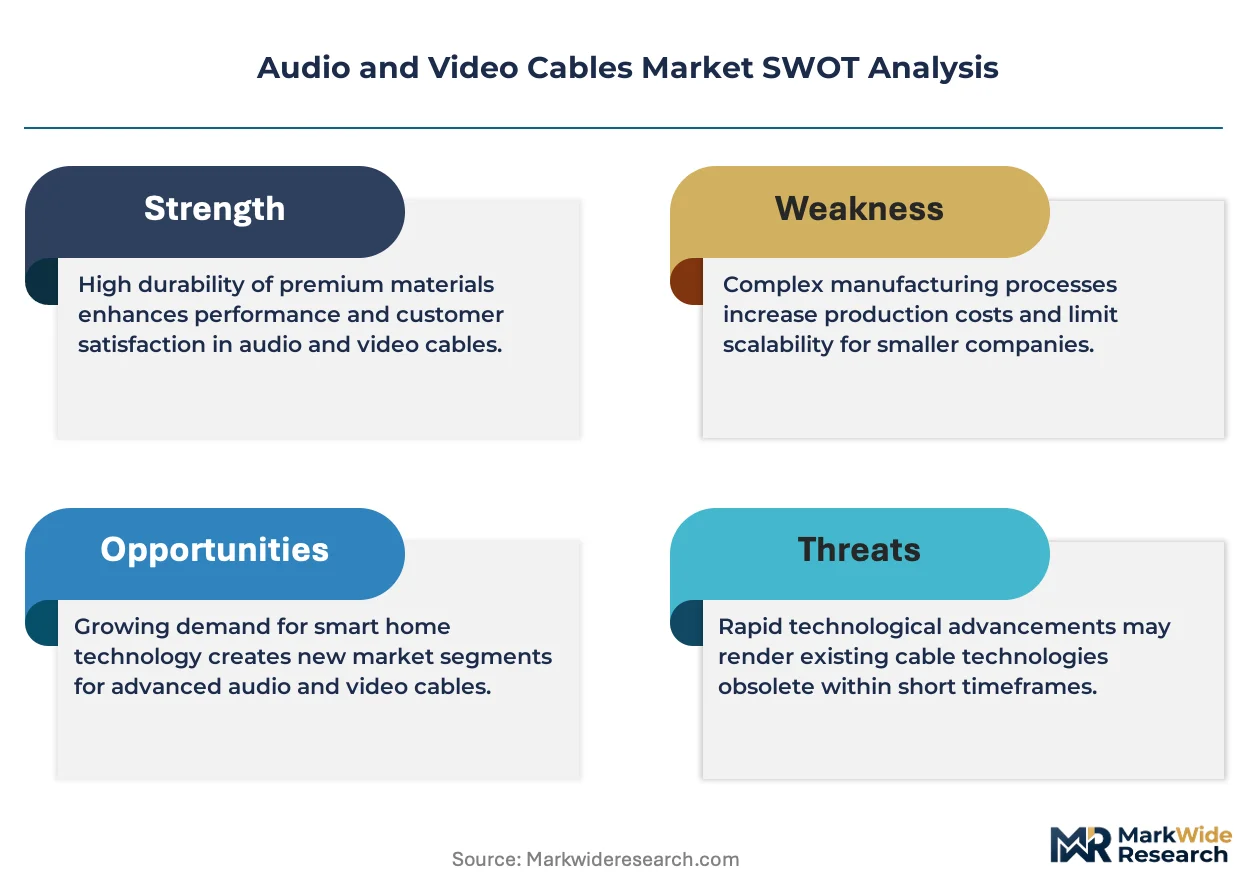
- Copper Price Volatility:LME copper fluctuations above historical baselines compress margin on mid-tier HDMI and speaker cable categories. Manufacturers hedge through forward contracts or clad-aluminum conductor substitution.
- Optical Component Concentration:Laser diode and photodetector supply concentrates among East Asian foundries, creating single-source vulnerability for fiber-optic cable assemblers. Qualifying secondary vendors extends development timelines.
- Wireless Audio Substitution:Low-latency Bluetooth and Wi-Fi 6E implementations displace analog interconnects in consumer home theater and portable audio applications. Cable-dependent niches compress to audiophile and professional monitoring segments.
Strategic Opportunities
- Underpenetrated Professional AV in Southeast Asia:Convention center and house-of-worship builds in Indonesia and the Philippines specify structured AV cabling for digital signage and sound reinforcement. Local distribution partnerships reduce landed cost disadvantages.
- EU Green Deal Procurement Incentives:Public sector tenders increasingly weight lifecycle carbon footprint in cable selection criteria. Recycled-content copper and bio-based jacket materials qualify for preferential scoring.
- Active Optical Cable Convergence:Hybrid copper-fiber assemblies with embedded signal conditioning electronics bridge distance limitations in data center and broadcast campus applications. Signal-integrity chip integration enables thinner gauge construction.
Industry Challenges
- HDMI Forum Licensing Complexity:Specification compliance testing and royalty administration create administrative overhead for product managers. Certification backlog at authorized test centers delays product launches.
- Legacy Infrastructure Integration:Facility retrofit projects demand backward-compatible connectivity for SDI, analog audio, and early-generation HDMI equipment. Engineering teams manage signal format conversion and impedance matching across hybrid plant architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio and Video Cables Market |
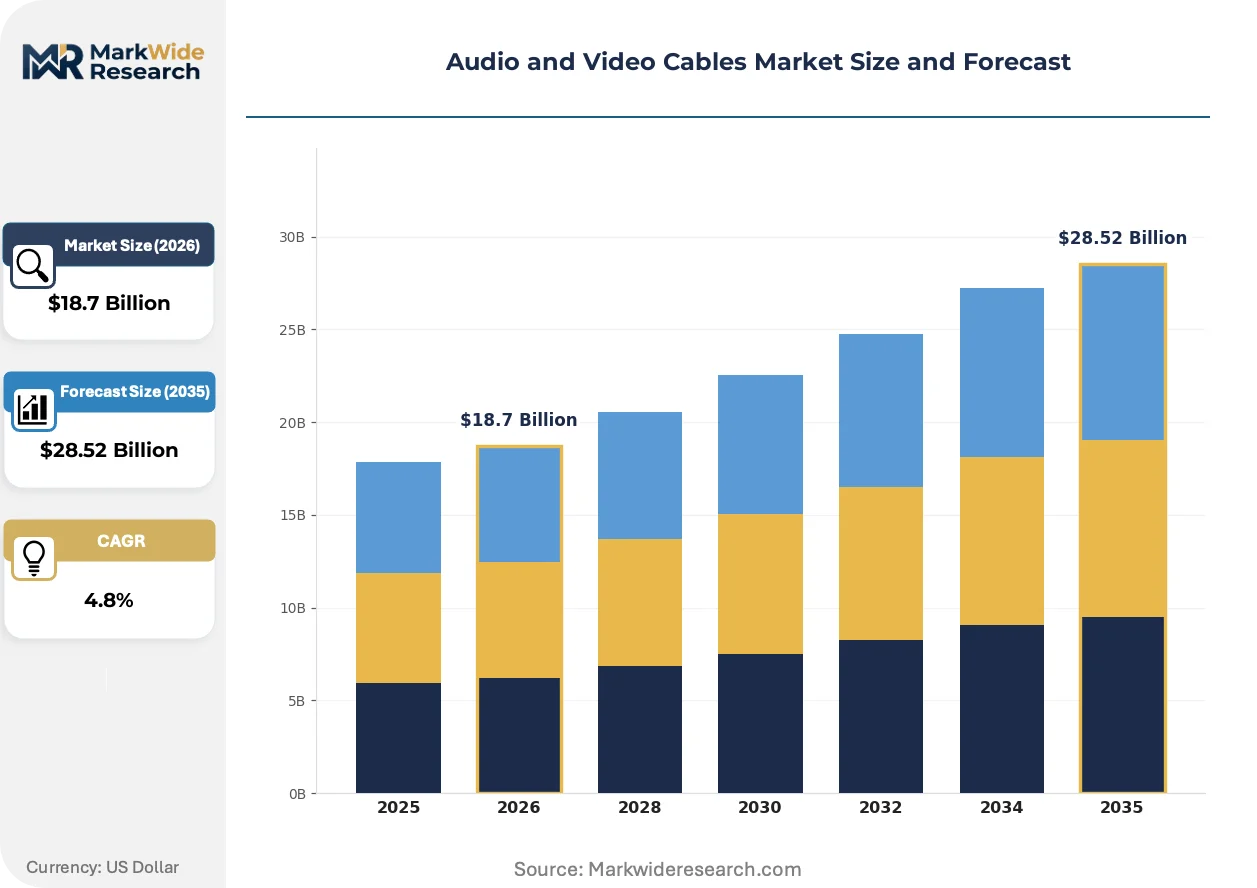
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDMI, VGA, RCA, Optical Connector Type: Male, Female, Coaxial, Jack Application: Home Theater, Professional Audio, Computer Networking, Broadcasting Material: Copper, Fiber Optic, Aluminum, PVC |
| Companies Covered | Amphenol Corporation, Belden Inc., Black Box Corporation, WESCO International, Commscope, Prysmian Group, Nexans, LEGRAND SA, Monster Cable Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio and Video Cables Market Strategic Shifts
Active electronics integration and materials science advances are redefining performance boundaries across copper and optical interconnect categories. Specification velocity and sustainability mandates are compressing traditional product lifecycles.
Hybrid active optical cable technology is consolidating long-reach signal distribution in broadcast mobile units and post-production facilities. These assemblies embed clock recovery and equalization chips within connector overmolds, enabling 100-meter HDMI and DisplayPort runs without external boosters. Sports production truck builders in the United Kingdom and Germany specify these for camera tethering and monitor routing.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing compound reformulation across European-sourced cable jackets. ECHA enforcement actions against non-compliant imports tighten border controls. Manufacturers with in-house compounding capabilities accelerate TPU and LSZH alternative qualification to maintain CE marking validity.
Enterprise procurement teams are consolidating AV infrastructure spend under IT category management, collapsing traditional AV contractor autonomy. This behavioral shift elevates structured cabling standards and BICSI certification requirements above legacy contractor preferences. Corporate headquarters builds in the United States and France increasingly specify IT-grade labeling, testing documentation, and extended warranty terms previously uncommon in commercial AV.
Audio and Video Cables Market Segmentation
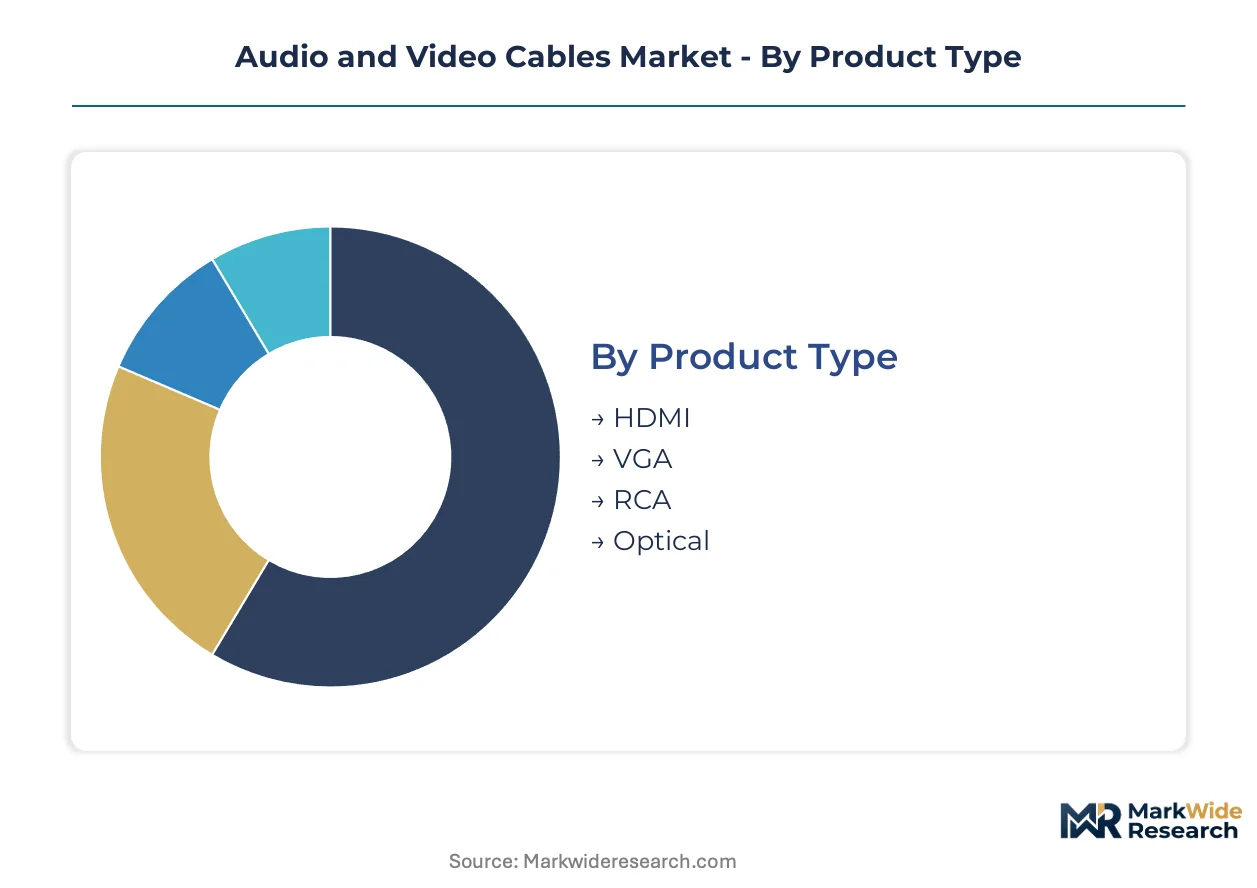
Signal integrity requirements and installation environments vary sharply across cable categories, forcing manufacturers to maintain parallel certification portfolios. Procurement teams in broadcasting and enterprise IT apply divergent qualification criteria that segment supplier relationships by product architecture.
Product Type:
HDMI Forum specification licensing and HDMI ATC certification dominate compliance burdens for digital interconnects, while analog categories face lighter administrative overhead but stricter electromagnetic compatibility testing under FCC Part 15 and CE marking frameworks.
- HDMI:High-bandwidth digital interface supporting uncompressed video and audio transmission through 19-pin configurations. Studio rebuilds in Germany and the United Kingdom specify 48Gbps-rated Ultra High Speed variants for 8K broadcast workflows. HDMI Forum specification revisions force annual portfolio refreshes.
- Optical:Fiber-based transmission using laser or LED sources for immunity to electromagnetic interference. Professional sports production facilities in the United Kingdom deploy SDI-over-fiber for camera tethering across extended distances. Active optical cable integration with embedded signal conditioning is climbing fastest.
- VGA:Analog RGB video interface with DE-15 connector, now legacy in consumer applications but persisting in industrial control and legacy projector installations. Corporate retrofit projects in France maintain backward-compatible connectivity.
- RCA:Coaxial connector system for composite video and unbalanced audio, concentrated in budget home theater and automotive aftermarket channels. Copper-clad aluminum conductor construction dominates cost-optimized product lines.
Leading the category by volume: HDMI. Expanding most quickly: Optical.
Connector Type:
Gendered and coaxial architectures command distinct tooling investments and assembly labor content, with male-terminated assemblies capturing higher unit volumes in OEM supply while female and jack configurations concentrate in field-installation and repair channels.
- Male:Pin-based plug configuration serving as source-side termination in standard interconnect assemblies. Consumer electronics OEMs in Vietnam and China specify gold-plated contact finishes for oxidation resistance in humid climates.
- Coaxial:Concentric conductor geometry with characteristic impedance control for RF and video applications. Broadcast infrastructure contractors in Germany specify precision 75-ohm assemblies for satellite and terrestrial distribution.
- Female:Socket receptacle for panel-mount or in-line splice applications. Professional AV rack builders favor shielded chassis-mount variants for grounding continuity.
- Jack:Cylindrical connector family spanning 3.5mm, 6.35mm, and 2.5mm diameters for audio applications. Portable audio and headphone amplifier segments drive demand for strain-relief-enhanced designs.
Highest shipment volumes: Male-terminated assemblies. Fastest growth: Coaxial for RF video distribution.
Application:
End-use environments dictate shielding specifications, flex-cycle durability, and fire-resistance ratings, with professional broadcasting and computer networking applications imposing the most stringent performance verification protocols.
- Broadcasting:Facility-scale signal distribution requiring SMPTE compliance and extended temperature operation. Mobile production units in the United Kingdom specify armored fiber and tactical-grade copper for repeated deployment cycles.
- Professional Audio:Studio and live sound environments demanding balanced analog and digital audio transport. Concert venue builds in Germany specify AES/EBU-compliant twisted-pair for stage-to-FOH runs.
- Home Theater:Residential AV installation with emphasis on concealment flexibility and consumer aesthetic finishes. National broadband initiatives in India accelerate fiber-to-the-home deployments for residential AV distribution.
- Computer Networking:Structured cabling for enterprise data and AV-over-IP convergence. Corporate headquarters builds in France increasingly specify IT-grade labeling and BICSI certification requirements.
Revenue concentration: Broadcasting. Steepest expansion trajectory: Professional Audio for live event infrastructure.
Material:
REACH Annex XVII substance restrictions and RoHS compliance reshape material selection, with ECHA enforcement against halogenated flame retardants accelerating reformulation toward phosphorus-based and bio-based alternatives.
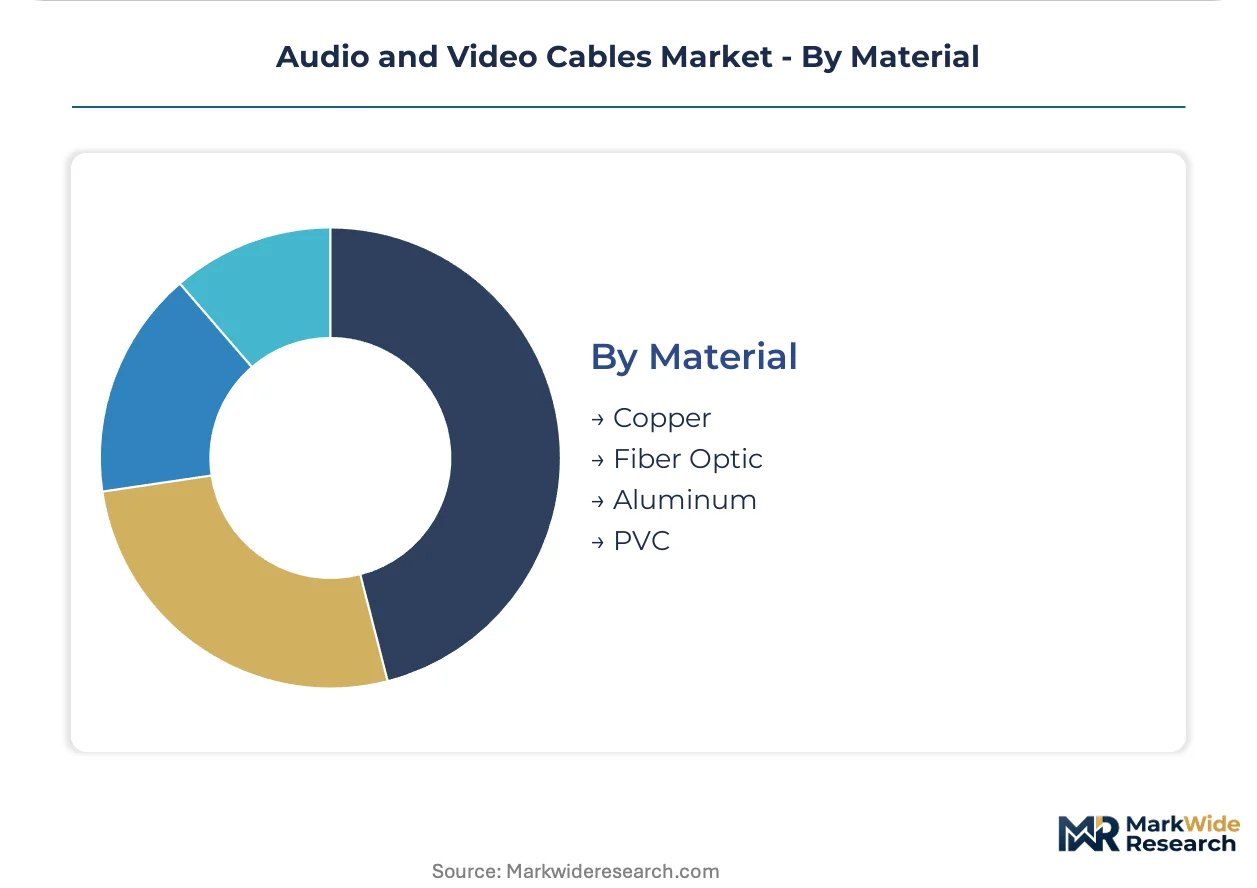
- Copper:Primary conductor for electrical conductivity and solderability, available in solid, stranded, and clad-aluminum configurations. LME price volatility above historical baselines compresses margins on mid-tier HDMI categories.
- Fiber Optic:Glass or plastic waveguide for optical signal transmission with complete EMI immunity. Laser diode supply concentration among East Asian foundries creates single-source vulnerability for cable assemblers.
- Aluminum:Lightweight conductor for cost-sensitive applications, typically deployed as copper-clad construction for conductivity enhancement. REACH-compliant jacket compounding with TPU alternatives maintains CE marking validity.
- PVC:Legacy jacket material facing regulatory pressure from short-chain chlorinated paraffin restrictions. Manufacturers with in-house compounding capabilities accelerate LSZH alternative qualification.
Dominant by tonnage: Copper. Gaining share fastest: Fiber Optic for professional broadcast migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Broadcast infrastructure upgrades and consumer electronics manufacturing scale concentrate demand across Germany, the United Kingdom, Vietnam, India, and China. Each geography presents distinct regulatory frameworks and procurement patterns.
Germany
Professional sports production facilities in Munich and Berlin are rewiring with 48Gbps-rated HDMI and SDI-over-fiber for uncompressed 8K video transport. REACH Annex XVII restrictions on halogenated flame retardants enforced by ECHA compel PVC jacket reformulation toward phosphorus-based TPU alternatives. Studio rebuilds in the Cologne-Düsseldorf corridor specify shielded twisted-pair with enhanced EMC performance.
United Kingdom
Mobile production units serving Premier League broadcasts demand armored fiber and tactical-grade copper for repeated deployment cycles. CE marking requirements under EU directive frameworks mandate conformity assessment before products enter distribution channels. Post-production clusters in London and Salford specify hybrid active optical cables with embedded signal conditioning for camera tethering.
Vietnam
National broadband initiatives are accelerating optical cable pull-through for residential AV distribution. Infrastructure contractors specify armored fiber assemblies for last-mile durability in humid tropical conditions. Consumer electronics OEMs in Ho Chi Minh City and Hanoi source gold-plated contact finishes for oxidation resistance.
India
Fiber-to-the-home deployments under BharatNet and private operator expansion are scaling domestic demand. TRAI regulations on telecom infrastructure quality influence procurement specifications for structured cabling. Manufacturing clusters in Noida and Sri City concentrate electronics assembly for mid-tier HDMI and RCA product lines.
China
Domestic electronics manufacturing scale and export-oriented production concentrate both supply and demand. MIIT standards on electromagnetic compatibility shape product design for internal and external markets. Shenzhen and Dongguan anchor fiber-optic component supply chains, though laser diode concentration creates single-source vulnerability for cable assemblers.
Audio and Video Cables Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium broadcast applications favoring established names while consumer tiers accommodate OEM suppliers. The vendor base organizes around three strategic archetypes: integrated cable-and-connector specialists, pure-play fiber-optic manufacturers, and diversified electrical component conglomerates. Capacity expansion in Vietnam and India and strategic partnerships for REACH-compliant material sourcing represent dominant competitive moves.
Within the integrated specialist tier, Amphenol Corporation and Belden Inc. exemplify modular platform strategies that span multiple broadcast and networking standards. Prysmian Group anchors the fiber-optic manufacturing archetype with captive optical fiber production. These three entities represent distinct positioning vectors—connector-centric, signal-integrity-focused, and materials-integrated—without overlapping core competencies.
| Leading Market Players |
|---|
| Amphenol Corporation |
| Belden Inc. |
| Black Box Corporation |
| WESCO International |
| Commscope |
| Prysmian Group |
| Nexans |
| LEGRAND SA |
| Monster Cable Products Inc. |
| Others |
Value Chain & Pricing Dynamics
Broadcast infrastructure contractors in Germany and the United Kingdom concentrate procurement authority for professional-grade interconnects, forcing manufacturers toward project-based contract pricing with certification-linked premiums rather than spot-market transactions. This buyer consolidation enables volume-tiered negotiations while squeezing margin on standard HDMI consumer tiers through OEM direct sourcing.
Pricing Analysis
Volume shipments in consumer HDMI and RCA categories compress margin through copper-clad aluminum substitution and direct OEM contracting, while premium broadcast and fiber-optic segments sustain value-based pricing through SMPTE compliance and active optical cable integration. Price differentiation hinges on HDMI Forum certification tier and REACH-compliant jacket compound qualification, with CE marking validity commanding measurable premiums in EU retail channels. Cost compression in mid-tier copper assemblies intensifies because LME volatility and wireless audio substitution erode pricing power. System integrators and enterprise IT procurement teams exhibit lowest price sensitivity, while budget home theater retailers and automotive aftermarket channels drive aggressive unit-cost negotiation.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke fulfillment patterns for European and Asia-Pacific broadcast contractors, with last-mile armored fiber assemblies shipping direct from Vietnam and India manufacturing clusters. Manufacturing concentrates in China, Vietnam, and India for copper conductor extrusion and connector assembly, while East Asian foundries dominate laser diode and photodetector supply for fiber-optic cable production. Raw material dependencies span LME copper cathodes, optical fiber preforms, phosphorus-based flame retardants, and gold-plating chemistries. Single-source vulnerability in laser diode supply creates qualification bottlenecks for fiber-optic assemblers. Distribution runs through AV systems integrators, IT value-added resellers, and direct OEM supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Audio and Video Cables Market sits in active technology transition as fiber-optic and active optical cable architectures displace legacy copper interconnects in professional broadcast and enterprise AV-over-IP deployments. This displacement compresses product lifecycles and redirects R&D investment toward embedded signal conditioning and optical component integration.
For Market Incumbents: Lock in broadcast infrastructure relationships through extended warranty terms and on-site signal-integrity engineering support that emerging competitors cannot replicate. Deepen backward integration into optical fiber preform manufacturing to reduce dependency on East Asian laser diode suppliers. Defend against wireless audio substitution by emphasizing latency-critical professional monitoring and live sound applications where cable reliability remains non-negotiable. For New Entrants and Emerging Players: Professional AV distributors in Indonesia and the Philippines represent the most penetrable channel for white-space entry, as convention center and house-of-worship builds specify structured AV cabling without entrenched incumbent relationships. Target fiber-to-the-home deployment contractors in Vietnam and India with armored fiber assemblies priced below Prysmian and Nexans landed cost structures. Lead with REACH-compliant TPU jacket formulations that qualify for EU Green Deal procurement scoring advantages. For Investors and Strategic Acquirers: The window for entry favors integrated cable-and-connector specialists with captive optical fiber production and modular platform architectures spanning multiple broadcast standards. Long-term viability rests on qualification timelines for HDMI Forum specification compliance and ECHA substance restriction adaptation. Watch active optical cable adoption rates in sports production truck builds as the inflection signal for technology-transition maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Fiber Preform Manufacturing | Prysmian Group's captive fiber production reduces laser diode supply vulnerability for SDI-over-fiber assemblies. |
| REACH-Compliant Jacket Compound Qualification | ECHA enforcement against halogenated flame retardants rewards manufacturers with in-house TPU and LSZH compounding capabilities. |
| Active Optical Cable Platform Launch | Hybrid copper-fiber assemblies with embedded signal conditioning capture 100-meter HDMI runs in UK and German broadcast trucks. |
| Distribution Partnership in Southeast Asia | Local alliances in Indonesia and Philippines reduce landed cost disadvantages for professional AV infrastructure tenders. |
| HDMI Forum Certification Investment | Authorized Test Center compliance backlog creates competitive moat for incumbents with dedicated certification resources. |
Study Parameters
Independent corroboration across procurement directors at German broadcast facilities, supply chain managers at Vietnam consumer electronics OEMs, and regulatory affairs leads at EU cable manufacturers underwrites the qualitative findings in this study. Primary interviews with broadcast infrastructure contractors, IT category management executives, and professional AV systems integrators combined with secondary validation from HDMI Forum specification documents, ECHA substance restriction databases, and TRAI telecom infrastructure quality filings. Bottom-up shipment data from manufacturing clusters in China, Vietnam, and India triangulates against top-down procurement spend analysis across the analysis window.
Rate-of-change decomposition across product type, application, and material segments structures the analytical framework, with CAGRs derived from segment-level volume and value trajectory modeling throughout the forecast period. Segmentation dimensions span HDMI, optical, VGA, and RCA product architectures; broadcasting, professional audio, home theater, and computer networking applications; and copper, fiber optic, aluminum, and PVC material categories. Forecast inputs incorporate REACH Annex XVII enforcement timelines, national broadband deployment schedules in Vietnam and India, and HDMI specification revision cycles.
Caveats apply where copper price volatility, laser diode supply disruption, or wireless audio substitution acceleration could materially shift the outlook. Forecasts reflect documented assumptions on specification adoption rates and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Testing Market
Cables
Cable Management System Market
Cables
Cable Accessories Market
Cables
Europe Cable Joints Market
Cables
South Africa Wire and Cable Market
Cables
United States Cable Accessories Market
Cables
Asia-Pacific Cable Joints Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
High Voltage Cable Termination Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
HVDC Cables Market
Cables
LED Cable Market
Cables
FFC/FPC Jumper Cables Market
Cables
Smartphone Type-C Charging and Data Cable Market
Cables
Global Ethernet Cable Market
Cables
Twisted Pair Cable Market