
 Asia Pacific Reed Sensors Switches Market | 2026-2036
Asia Pacific Reed Sensors Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Reed Sensors Switches Market Outlook
China's dual carbon goals under MEE is decoupling reed switch demand from electromechanical relay architectures across industrial automation lines. Littelfuse Inc leverages its fuse-to-sensor integration platform to anchor premium automotive contracts in Japan and South Korea. OKI Sensor Device Corporation sustains manufacturing scale through captive hermetic sealing lines that dominate magnetic reed switch supply to domestic elevator and security OEMs. Standex Electronics specializes in high-temperature switch variants that occupy niche positions in Indian HVAC compressor controls.
Reed sensors switches are hermetically sealed electromechanical devices comprising ferromagnetic reeds encapsulated in inert gas-filled glass envelopes, actuated by magnetic fields to open or close circuits with contact resistance typically below 100 milliohms. These devices serve as isolation-critical position and proximity detectors where environmental sealing and zero standby power consumption matter. Magnetic reed switches retain structural leadership across the product type landscape due to decades of design maturity and lowest unit cost at volume. Contactless technology within the application dimension is expanding fastest as medical device manufacturers in South Korea and Taiwan adopt wear-resistant alternatives to mechanical limit switches. Normally open switches command concentrated margin pools in security systems deployment where installation simplicity reduces field service costs.
Japan's METI enforces JIS standards for component reliability in automotive safety circuits, compelling reed switch suppliers to maintain failure rate documentation below 0.1 parts per million. India's BIS certification mandates for electronics imports create procedural barriers that filter out uncertified magnetic sensor vendors from government tender participation. South Korea's MFDS regulates medical device component traceability, pushing reed switch makers toward laser-etched part serialization. Stakeholders must monitor how divergent national certification timelines reshape supplier qualification costs across the Asia Pacific manufacturing footprint.
Market Dynamics
Automotive electrification programs across Japan and South Korea are accelerating procurement of contactless position sensors, while China's dual carbon goals under MEE are decoupling reed switch demand from legacy relay technologies across industrial automation corridors.
Growth Catalysts
- Automotive electrification mandates:METI-backed EV component localization in Japan and South Korea is expanding hermetically sealed sensor procurement for battery management systems and motor position detection.
- MEE dual carbon enforcement:China's Ministry of Ecology and Environment decarbonization targets are forcing industrial automation lines to replace electromechanical relays with zero-standby-power reed switches.
- Medical device traceability rules:South Korea's MFDS laser-etching mandates for component serialization are pulling reed switch makers into high-margin healthcare supply chains.
Market Restraints
- Raw material concentration:Specialty ferromagnetic alloy supply concentrates in a narrow band of East Asian smelters, exposing switch manufacturers to input price volatility and allocation risk.
- Technical performance ceiling:Glass envelope hermetic sealing imposes absolute temperature limits that exclude reed switches from emerging high-thermal automotive underhood applications.
- Import certification friction:India's BIS electronics import mandates create procedural barriers that filter uncertified magnetic sensor vendors from government tender participation.
Strategic Opportunities
- Indian HVAC compressor controls:High-temperature switch variants remain underpenetrated in Indian residential and commercial cooling equipment, creating white space for specialized suppliers.
- Security system installation simplification:Normally open switch configurations reduce field service costs in access control deployments across Southeast Asian smart building projects.
- Contactless wear-resistant alternatives:Medical device manufacturers in Taiwan are adopting magnetic reed switches to replace mechanical limit switches in diagnostic equipment with high cycle-count requirements.
Industry Challenges
- Hermetic sealing skill scarcity:Captive glass-to-metal sealing expertise concentrates in legacy Japanese and Korean manufacturing lines, constraining new entrant scale-up.
- JIS reliability documentation burden:METI enforcement of sub-0.1 parts per million failure rate records compels suppliers to maintain costly statistical process control systems.
- Legacy system integration complexity:Electromechanical relay architectures in established industrial automation lines resist retrofit to contactless reed switch topologies without control system redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Reed Sensors Switches Market |
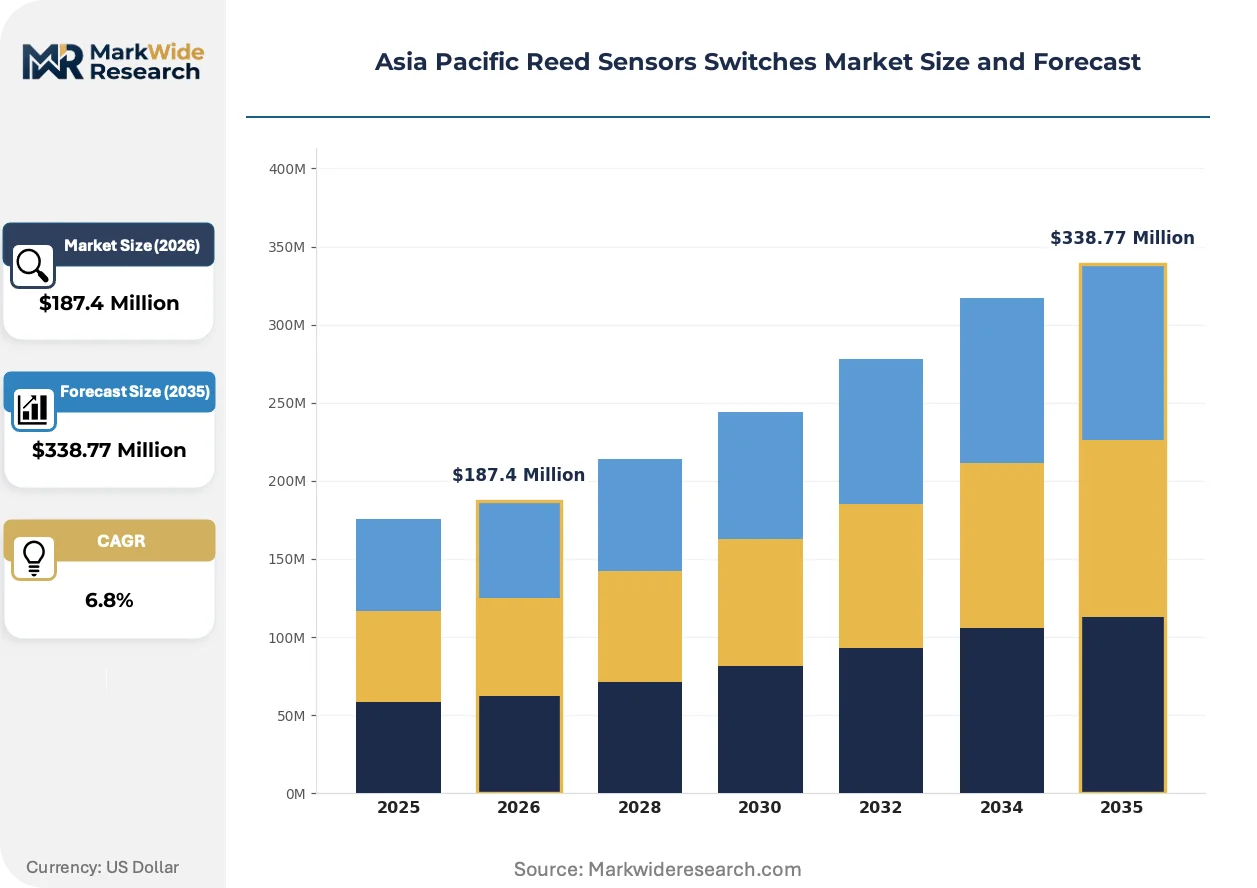
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Reed Switches, Normally Open Switches, Normally Closed Switches, High-Temperature Switches End User: Electronics, Automotive, Industrial Automation, HVAC Systems Application: Security Systems, Motor Control, Consumer Appliances, Medical Devices Technology: Analog, Digital, Wireless, Contactless |
| Companies Covered | Littelfuse Inc, OKI Sensor Device Corporation, PIC GmbH, Standex Electronics, Coto Technology, Comus International, Reed Switch Development Corporation, Hamlin Electronics, GE-Ding Information Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Reed Sensors Switches Market Strategic Shifts
Magnetic sensing architectures are undergoing functional convergence with semiconductor-based alternatives, while regulatory traceability mandates and procurement centralization are compressing supplier qualification timelines across East Asian manufacturing corridors.
MEMS-based magnetic sensors are converging with traditional reed switch applications in automotive position detection, offering programmable sensitivity thresholds that reed switches cannot match. Tier-1 suppliers in South Korea are piloting hybrid architectures that combine reed switch reliability with MEMS configurability for battery management systems. This convergence is compressing the addressable market for standalone reed switches in premium automotive contracts.
Japan's METI has tightened JIS C 0910 reliability documentation requirements for safety-critical automotive circuits, compelling reed switch suppliers to maintain continuous failure mode analysis. Industrial consequence includes extended supplier qualification cycles and elevated compliance overhead for components entering Japanese OEM supply chains. Korean automotive sensor divisions are responding by pre-qualifying dual-source reed switch vendors to mitigate single-supplier audit risk.
Medical device OEMs in Taiwan and South Korea are consolidating magnetic sensor procurement through designated component distributors rather than direct manufacturer relationships. This channel concentration is displacing fragmented spot-buying patterns that previously characterized small-batch diagnostic equipment production. The shift is most visible in Seoul and Taipei metropolitan manufacturing zones where MFDS traceability rules favor distributor-managed serialization records.
Asia Pacific Reed Sensors Switches Market Segmentation
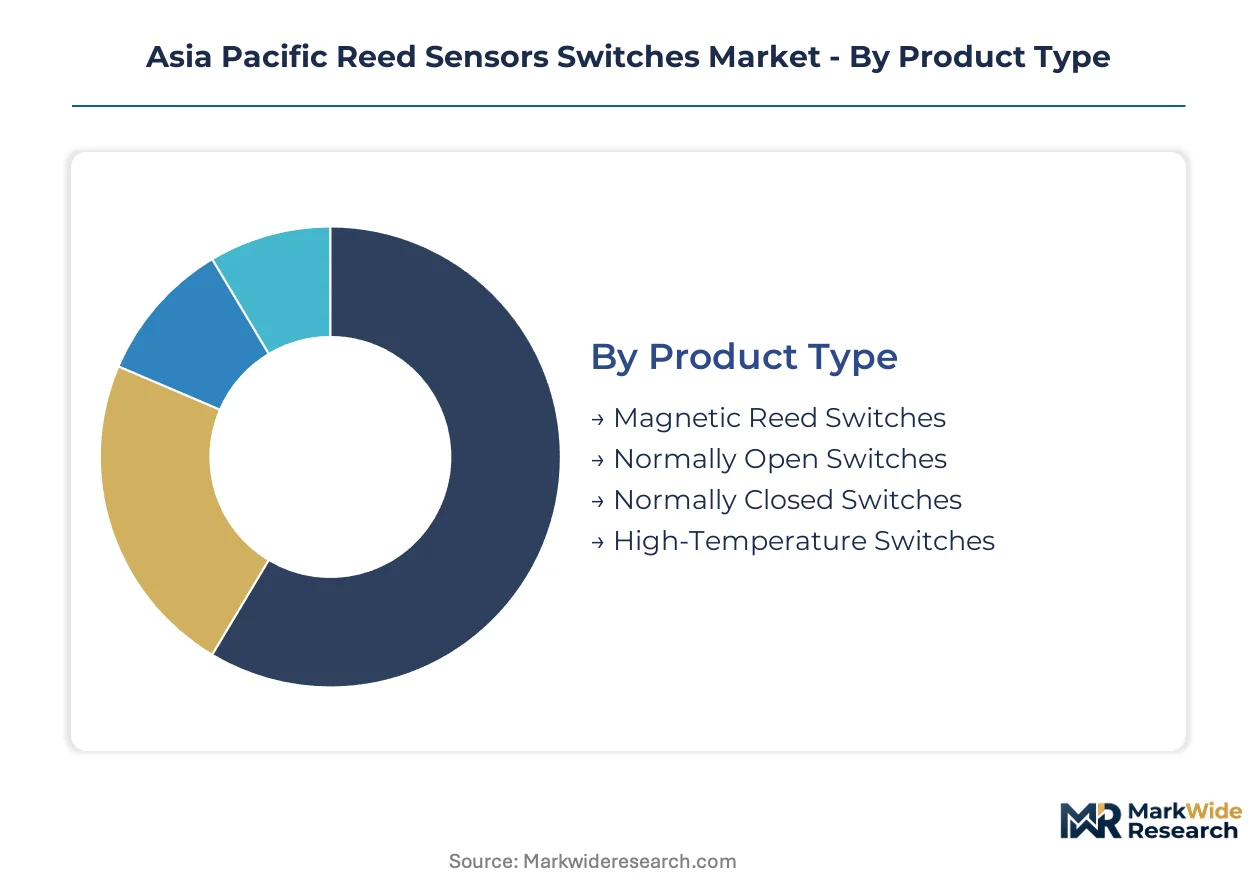
Reed switch procurement patterns diverge sharply across product architectures, end-use verticals, and interface technologies. Understanding these splits reveals where hermetic sealing premiums command pricing power versus where commodity substitution pressures dominate.
Product Type:
Upgrade cycles in industrial automation and automotive electrification are reshaping demand profiles across switch configurations, with thermal tolerance and default state characteristics driving replacement decisions.
- Magnetic Reed Switches:Ferromagnetic reeds encapsulated in inert gas-filled glass envelopes deliver contact resistance below 100 milliohms. Demand concentrates in Japanese and Korean automotive battery management systems where METI reliability mandates enforce sub-0.1 ppm failure rates.
- Normally Open Switches:Default-open circuits simplify installation in access control systems across Southeast Asian smart building corridors. Procurement from security OEMs in Singapore and Malaysia favors these configurations for reduced field service costs.
- Normally Closed Switches:Default-closed architectures serve fail-safe requirements in elevator safety circuits and emergency stop systems.
- High-Temperature Switches:Specialized glass-to-metal sealing extends thermal limits for Indian HVAC compressor controls where ambient operating conditions stress standard envelopes.
Volume placements concentrate in Magnetic Reed Switches; the faster expansion belongs to High-Temperature Switches.
End User:
Cost tier stratification separates premium hermetic specifications from standard-grade procurement, with certification burdens filtering supplier participation across government-tender-exposed verticals.
- Automotive:Battery management systems and motor position detection in Japanese and Korean EV programs demand traceable failure mode documentation under JIS C 0910. Tier-1 suppliers pre-qualify dual-source vendors to mitigate single-supplier audit risk from METI enforcement.
- Industrial Automation:China's MEE dual carbon goals are forcing replacement of electromechanical relays with zero-standby-power reed switches across manufacturing lines in Guangdong and Jiangsu provinces.
- Electronics:Consumer device manufacturers in Taiwan prioritize compact form factors for proximity detection in wearables and portable equipment.
- HVAC Systems:Indian residential and commercial cooling equipment creates white space for high-temperature variants as compressor duty cycles intensify.
Revenue pools are deepest in Automotive; Electronics is climbing the fastest as wearables proliferation accelerates.
Application:
Customer type fragmentation separates high-volume OEM contracts from fragmented maintenance-replacement demand, with channel concentration favoring distributor-managed procurement in regulated medical segments.
- Security Systems:Access control deployments across Southeast Asian smart building projects favor normally open configurations. Installation simplicity reduces field service costs in Bangkok, Jakarta, and Ho Chi Minh City metropolitan developments.
- Medical Devices:South Korean and Taiwanese diagnostic equipment manufacturers adopt wear-resistant magnetic reed switches to replace mechanical limit switches in high cycle-count applications. MFDS laser-etching mandates for component serialization pull suppliers into distributor-managed channels.
- Motor Control:Position feedback systems in industrial drives require precise actuation repeatability.
- Consumer Appliances:Door position and liquid level detection in white goods manufacturing lines.
Contract values are largest in Security Systems; Medical Devices is gaining share fastest on traceability premium capture.
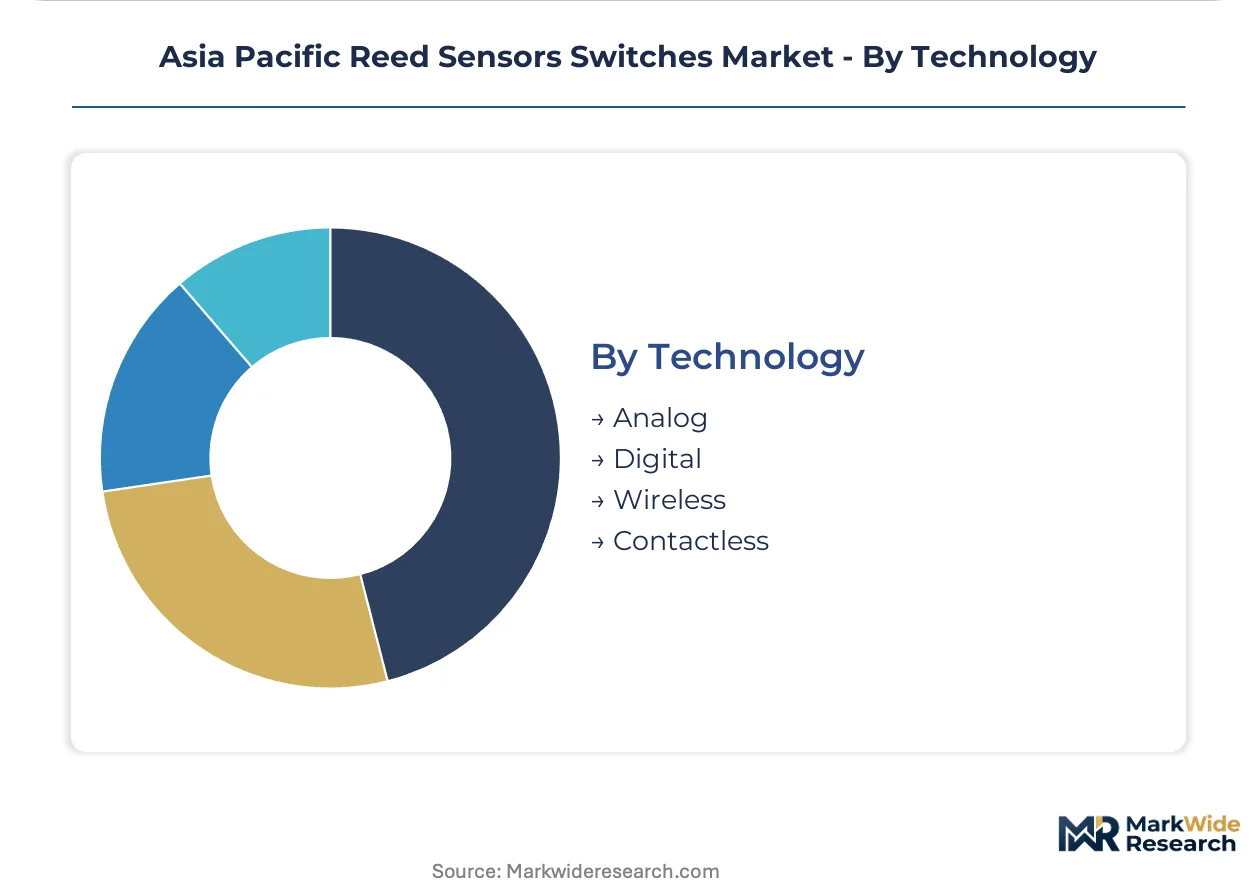
Technology:
Supply concentration in captive hermetic sealing expertise constrains new entrant scale-up, while semiconductor convergence pressures standalone reed switch positioning in configurable applications.
- Contactless:Magnetic field actuation eliminates mechanical wear, extending operational life in high-cycle diagnostic equipment. South Korean medical device OEMs pilot these variants to replace mechanical limit switches under MFDS durability requirements.
- Analog:Continuous signal output suits proportional position sensing in motor control applications across Japanese industrial automation lines.
- Digital:Binary state interfaces simplify integration with modern control systems.
- Wireless:RF-linked reed switches enable remote monitoring in distributed security sensor networks.
Shipment volumes skew toward Analog; Contactless shows the steepest expansion trajectory as wear resistance premiums command pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Tokyo industrial corridor anchors reed switch procurement for Japanese automotive electrification programs, while manufacturing clusters across East Asia concentrate hermetic sealing expertise and magnetic sensor production capacity.
China
Guangdong and Jiangsu provinces drive industrial automation retrofit demand as MEE dual carbon enforcement replaces electromechanical relays with zero-standby-power reed switches. The Yangtze River Delta manufacturing belt concentrates procurement for battery management systems and motor position detection in domestic EV programs.
Japan
Nagoya and Osaka metropolitan areas host captive hermetic sealing lines supplying domestic elevator and security OEMs. METI-backed JIS C 0910 reliability mandates compel suppliers to maintain sub-0.1 parts per million failure rate documentation for automotive safety circuits.
South Korea
Seoul Capital Area medical device manufacturers adopt wear-resistant magnetic reed switches under MFDS laser-etching mandates for component serialization. Busan-Ulsan automotive corridors expand hermetically sealed sensor procurement for battery management systems in domestic EV platforms.
India
Maharashtra and Gujarat industrial zones present white space for high-temperature switch variants in residential and commercial HVAC compressor controls. BIS certification mandates for electronics imports filter uncertified magnetic sensor vendors from government tender participation.
Taiwan
Taipei metropolitan diagnostic equipment manufacturers consolidate magnetic sensor procurement through designated component distributors. Wear-resistant reed switches replace mechanical limit switches in high cycle-count medical applications, with procurement channeling through distributor-managed serialization records.
Asia Pacific Reed Sensors Switches Market Competitive Environment
The competitive structure tilts toward specialized hermetic sealing expertise concentrated in legacy East Asian manufacturing lines. Supplier qualification timelines compress as procurement centralization and regulatory traceability mandates reshape channel relationships. Three archetypes dominate: integrated fuse-to-sensor platforms, captive glass-to-metal sealing specialists, and high-temperature variant developers. Competitive moves center on dual-source vendor pre-qualification and distributor channel consolidation for regulated medical segments.
Among Japan-based fabricators, OKI Sensor Device Corporation occupies a position within the captive hermetic sealing archetype, while Littelfuse Inc exemplifies the integrated platform model. Standex Electronics represents the high-temperature specialization vector. These three entities anchor the competitive landscape through distinct capability configurations rather than overlapping market coverage.
| Leading Market Players |
|---|
| Littelfuse Inc |
| OKI Sensor Device Corporation |
| PIC GmbH |
| Standex Electronics |
| Coto Technology |
| Comus International |
| Reed Switch Development Corporation |
| Hamlin Electronics |
| GE-Ding Information Inc |
| Others |
Value Chain & Pricing Dynamics
China's MEE dual carbon goals gate qualified supply for hermetically sealed reed switches, restricting premium-tier pricing access to vendors with documented zero-standby-power performance and alloy traceability. Buyers in Japanese automotive and Korean medical segments pay reliability premiums that commodity relay suppliers cannot access without JIS C 0910 certification investment.
Pricing Analysis
Value-based pricing anchors on operational uptime guarantees in elevator safety circuits and battery management systems where failure costs exceed component price by orders of magnitude. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified automotive grades from industrial automation specifications and uncertified spot-market units. Pricing pressure stems from MEMS magnetic sensor convergence in South Korean Tier-1 automotive programs. Security OEMs in Southeast Asia exhibit highest price sensitivity; Japanese EV platform engineers show lowest.
Supply Chain Analysis
Workforce-availability constraints in Nagoya and Osaka glass-to-metal sealing lines limit capacity expansion for hermetic envelope production. Supply concentrates in Japan, South Korea, and China, with specialty ferromagnetic alloys drawing from East Asian smelters in Aichi and Gyeonggi provinces. Single-source vulnerability runs through captive sealing expertise concentrated in legacy Japanese manufacturing lines. Distribution runs through designated component distributors in Taiwanese medical device corridors and direct OEM relationships in Japanese automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where captive hermetic sealing capacity props pricing power for incumbent specialists. New capacity cannot scale without multi-year workforce development in glass-to-metal bonding techniques.
For Market Incumbents: Deploy dual-source vendor pre-qualification programs to mitigate METI audit risk exposure in Japanese automotive supply chains. Lock in long-term alloy offtake agreements with Aichi and Gyeonggi smelters before raw material allocation tightens. Expand captive sealing line throughput in Nagoya metropolitan facilities to capture medical device traceability premiums under MFDS laser-etching mandates. For New Entrants and Emerging Players: Enter via high-temperature switch variants for Indian HVAC compressor controls where Standex Electronics holds limited manufacturing presence. Target Maharashtra and Gujarat industrial zones with BIS-certified product lines that filter uncertified competitors from government tender participation. Build distributor relationships in Taipei metropolitan medical device clusters rather than direct OEM sales approaches. For Investors and Strategic Acquirers: MFDS laser-etching mandate enforcement is the leading indicator that Korean medical device supply chains will consolidate around distributor-managed procurement channels. Five-to-ten year viability favors acquiring captive hermetic sealing specialists with documented JIS C 0910 compliance histories. Watch for MEMS-reed hybrid architecture pilot results from Busan-Ulsan automotive corridors as substitution threat signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Hermetic Sealing Capacity Expansion | OKI Sensor Device and legacy Japanese fabricators defend market position through in-house glass-to-metal bonding expertise. |
| JIS C 0910 Certification Investment | Suppliers gain access to METI-backed EV component localization programs requiring sub-0.1 ppm failure rate documentation. |
| Distributor Channel Consolidation | MFDS traceability rules in Seoul and Taipei favor designated component distributors over fragmented spot-buying patterns. |
| High-Temperature Variant Development | Specialized glass-to-metal sealing unlocks Indian HVAC compressor controls where ambient conditions stress standard envelopes. |
| Dual-Source Vendor Pre-Qualification | Korean Tier-1 suppliers mitigate single-supplier audit risk from METI reliability enforcement through qualified backup relationships. |
Study Parameters
Document review covered regulatory filings from METI, MFDS, and BIS, complemented by interviews with hermetic sealing equipment engineers, automotive Tier-1 procurement managers, medical device component distributors, and HVAC compressor controls specialists. Secondary sources included JIS C 0910 reliability standards, MEE dual carbon enforcement circulars, and East Asian ferromagnetic alloy trade data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Output modeling produced volume and value trajectories segmented by product architecture, end-use vertical, application interface, and technology type. CAGRs derived from regression analysis against automotive electrification capex cycles, industrial automation retrofit rates, and medical device production indices. Forecast inputs incorporated MEE enforcement timelines, METI localization subsidy schedules, and MFDS serialization mandate adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material allocation disruptions or MEMS sensor substitution acceleration. Projections reflect assumptions about hermetic sealing workforce availability and certification timeline adherence. Material deviation in alloy smelter consolidation or hybrid architecture pilot success warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Touchpad Market
Switches
North America Low Voltage Switchgear Market
Switches
Reed Switch Market
Switches
India Switchgear Market
Switches
Timer Switch Socket Market
Switches
Global Disconnector Switch Market
Switches
Global Light Control Switches Market
Switches
Global Float Level Switches Market
Switches
5G Electromechanical RF Switch Market
Switches
Asia-Pacific Low Voltage Switchgear Market
Switches
North America Push Buttons & Signaling Devices Market
Switches
ASEAN Switchgear Market
Switches
Membrane Switch Market
Switches
Global Smart Switch Panel Market
Switches
DC Switchgear Market
Switches
Electronic Shift-By-Wire Selector Modules Market