
 North America Coaxial Cable Market | 2026-2036
North America Coaxial Cable Market Size, Share, and Industry Trends Forecast 2026-2036
North America Coaxial Cable Market Insights
Project finance tied to municipal broadband bonds is rewriting competitive entry conditions across the North America coaxial cable landscape. Belden Inc. leverages its manufacturing scale to dominate industrial-grade twinaxial supply for factory automation networks. CommScope anchors its position through backward integration into copper cladding and dielectric extrusion. Prysmian Group competes on submarine and terrestrial hybrid coaxial systems linking coastal data centers.
Coaxial cable consists of a central copper conductor, dielectric insulator, metallic shield, and outer jacket engineered to transmit radio frequency signals with controlled impedance across defined frequency ranges. RF coaxial variants with foam polyethylene dielectrics and braided copper shields remain the workhorse for cable television distribution and cellular base station feeds. The application dimension shows data transmission outpacing television broadcasting as streaming infrastructure displaces legacy broadcast architectures. Residential end users still generate the largest volume base, though telecommunications providers concentrate margin pools in custom low-loss formulations for 5G small cell densification.
The FCC governs electromagnetic emissions and broadband subsidy eligibility, while the National Electrical Code through NFPA standards dictates fire-rated jacket requirements for commercial installations. Health Canada and PMRA oversee cable safety standards for cross-border infrastructure serving the Great Lakes manufacturing corridor. Stakeholders must track how EPA copper sourcing rules and state-level right-of-way policies reshape material costs and deployment timelines for underground coaxial runs.
Market Dynamics
Broadband infrastructure modernization is compressing replacement cycles across the North America coaxial cable market, as telecommunications carriers prioritize fiber-coaxial hybrid architectures over pure copper deployments.
Growth Catalysts
- FCC Broadband Equity Programs:Federal subsidy frameworks are accelerating municipal fiber-to-the-home expansions, generating bulk procurement of RF coaxial feeder cables for last-mile distribution nodes.
- Data Center Clustering:Texas and Virginia hyperscale campus construction is driving demand for low-loss coaxial assemblies in high-frequency interconnect applications.
- 5G Small Cell Densification:Cellular carriers are deploying hybrid fiber-coaxial backhaul to street-level radios, creating sustained volume pull for weatherproofed outdoor cable formulations.
Market Restraints
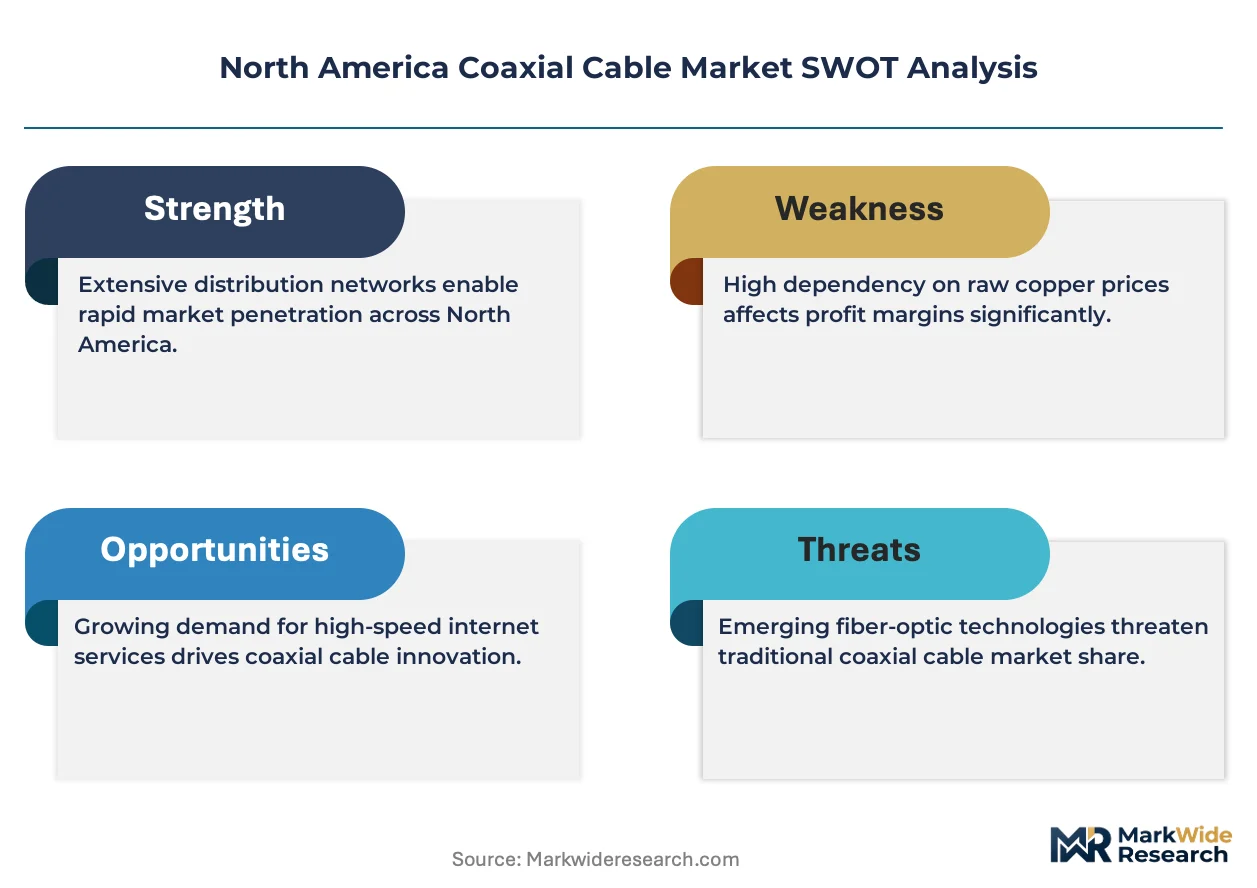
- Copper Price Volatility:LME copper futures swings directly compress margin stability for cable manufacturers without captive smelting capacity.
- Fiber Optic Substitution:Single-mode fiber deployments in greenfield residential developments are capturing bandwidth-intensive applications previously served by coaxial trunk lines.
- NFPA Fire-Rated Jacket Mandates:Commercial building code compliance adds material cost premiums of 15-25 percent for plenum-rated formulations versus standard PVC jackets.
Strategic Opportunities
- Industrial IoT Convergence:Factory automation networks combining Ethernet-over-coax with Power over Coax (PoC) are opening twinaxial demand in automotive and food processing plants.
- Canadian Arctic Infrastructure:Health Canada cold-climate certification requirements for telecommunications cable create a protected niche for specialized low-temperature dielectric formulations.
- Smart Grid AMI Backhaul:Electric utilities are repurposing existing coaxial plant for advanced metering infrastructure communications, extending asset utility beyond video distribution.
Industry Challenges
- Dielectric Extrusion Talent Scarcity:Foam polyethylene precision manufacturing requires skilled technicians in short supply across Midwest cable production corridors.
- Legacy Plant Integration:Hybrid fiber-coaxial network upgrades demand seamless interoperability with decades-old amplifier cascades and passive splitter architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Coaxial Cable Market |
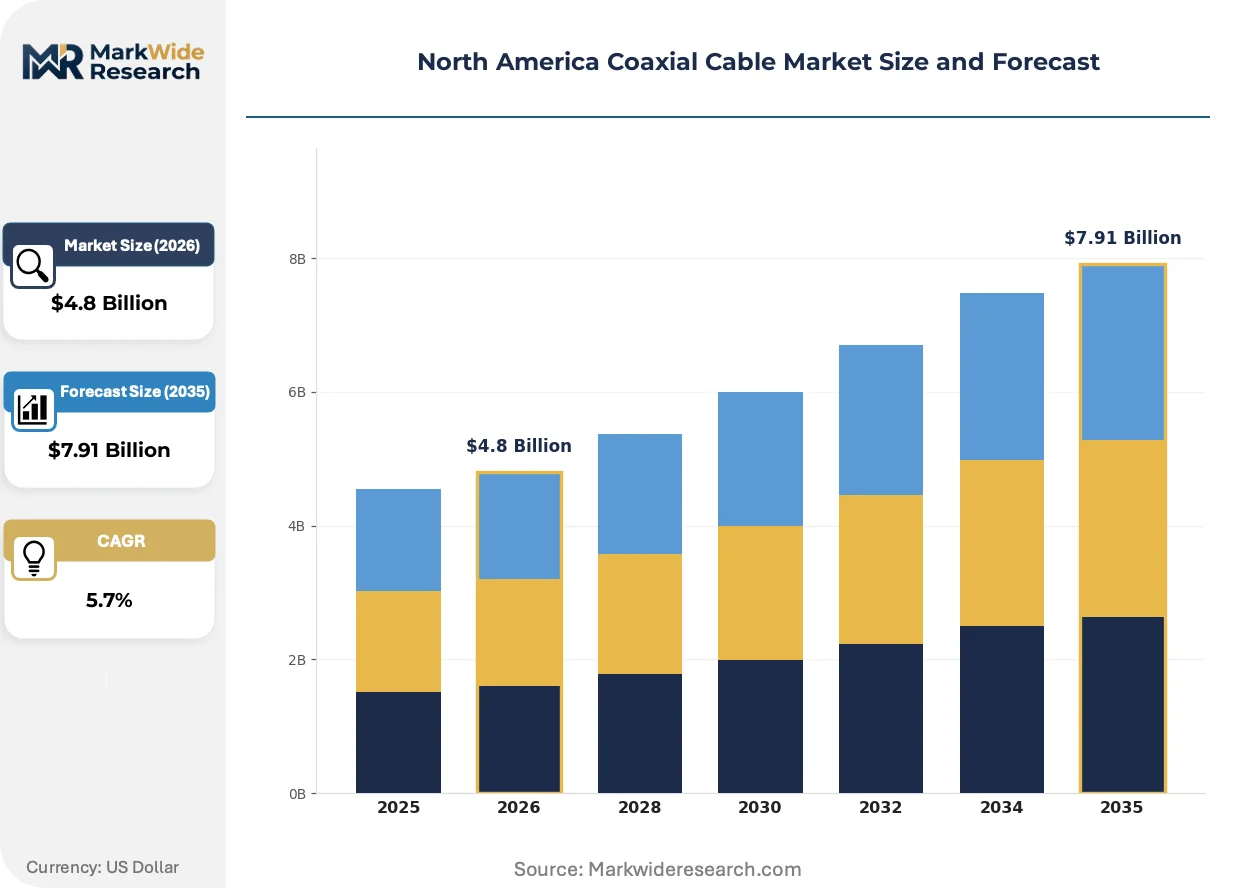
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RF Coaxial, Triaxial, Twinaxial, Hybrid Coaxial Application: Television Broadcasting, Data Transmission, Internet Services, Security Systems End User: Residential, Commercial, Industrial, Telecommunications Connectivity: Plug-in, Direct, Wireless, Ethernet |
| Companies Covered | Belden Inc., CommScope, TE Connectivity Ltd, Amphenol Corporation, Southwire Company, LLC, Prysmian Group, Nexans S.A., LS Cable & System Ltd., Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Coaxial Cable Market Trends and Innovations
Material science advances and procurement model compression are restructuring competitive advantage across the North America coaxial cable value chain. Three developments warrant particular attention.
Corrugated copper outer conductor designs with enhanced shielding effectiveness are rendering obsolete traditional braided-shield architectures in 5G fronthaul applications. Mobile network operators in California and Texas are specifying these formulations for millimeter-wave signal integrity. The shift is compressing supplier margins on legacy RG-series products while rewarding manufacturers with electron-beam welding capabilities.
The FCC's updated electromagnetic emissions testing protocols are forcing recertification of outdoor-rated coaxial assemblies deployed near aviation corridors. Cable OEMs serving the Great Lakes and Northeast corridors are reformulating jacket compounds to meet both FAA coordination requirements and NFPA 70 National Electrical Code flame spread limits. This dual compliance burden favors vertically integrated manufacturers with in-house compound development labs.
Telecommunications procurement teams are consolidating supplier relationships around single-source framework agreements with five-year volume commitments. Tier-one cable operators in the United States are replacing spot-market purchasing with integrated supply contracts covering copper cathode through finished cable. This concentration is marginalizing regional distributors and favoring manufacturers with captive copper cladding and polymer compounding operations.
North America Coaxial Cable Market Segmentation
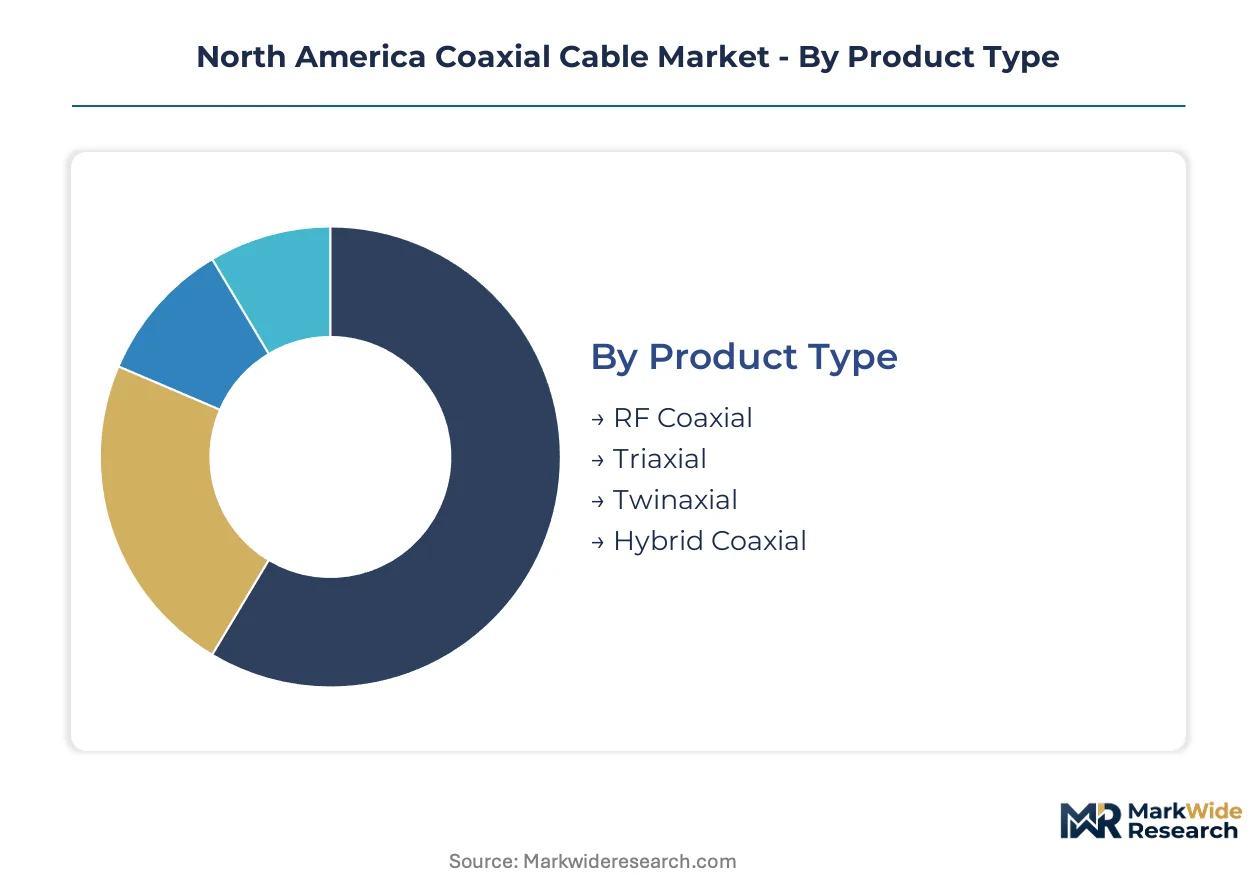
Coaxial cable segmentation in North America reflects divergent technical specifications across frequency bands, shielding architectures, and deployment environments. Product differentiation determines procurement patterns for telecommunications carriers versus industrial automation integrators. Application-based segmentation tracks the displacement of legacy broadcast infrastructure by streaming-centric data transmission networks.
Product Type:
Cost tier stratification separates commodity RF formulations from precision-engineered twinaxial and hybrid variants serving mission-critical interconnect applications.
- RF Coaxial:Foam polyethylene dielectric construction with braided copper shields dominates cable television distribution and cellular base station feeder lines. Municipal broadband expansions in Texas and Virginia are accelerating volume procurement of low-loss RG-series variants for last-mile hybrid fiber-coaxial nodes.
- Twinaxial:Paired inner conductors with shared dielectric and shielding enable balanced differential signaling for factory automation networks. Belden Inc. anchors industrial supply through backward integration into precision conductor drawing and jacket extrusion for automotive and food processing plant deployments.
- Triaxial:Additional outer shield layer provides enhanced electromagnetic interference protection for broadcast camera chains and medical imaging equipment.
- Hybrid Coaxial:Integrated fiber-optic elements within coaxial outer conductors support submarine and terrestrial data center links along coastal corridors.
RF Coaxial holds installed capacity. Twinaxial is rotating up the share rankings.
Application:
Volume concentration tracks bandwidth migration from one-way broadcast architectures to bidirectional data transmission infrastructure.
- Data Transmission:High-frequency coaxial assemblies with corrugated copper outer conductors serve hyperscale data center interconnects and 5G fronthaul applications. California and Texas mobile network operators specify these formulations for millimeter-wave signal integrity in small cell densification projects.
- Internet Services:Hybrid fiber-coaxial feeder cables bridge fiber termination points to residential drop connections. FCC broadband equity programs are compressing replacement cycles across municipal networks in the Great Lakes corridor.
- Television Broadcasting:Legacy trunk line deployments face fiber substitution in greenfield developments while maintaining upgrade revenue in existing plant.
- Security Systems:Plenum-rated jacket formulations satisfy NFPA 70 National Electrical Code requirements for commercial building video surveillance backhaul.
Internet Services holds installed capacity. Data Transmission is rotating up the share rankings.
End User:
Customer type determines margin structure, with telecommunications providers concentrating premium pricing on custom low-loss formulations versus standardized residential volume plays.
- Telecommunications:Carriers deploy weatherproofed outdoor cable formulations for 5G small cell backhaul and hybrid fiber-coaxial network modernization. Procurement consolidation around five-year framework agreements is marginalizing regional distributors.
- Residential:Bulk orders for standard RG-6 and RG-11 drop cables generate volume base despite compression from fiber-to-the-home substitution in bandwidth-intensive developments.
- Industrial:Ethernet-over-coax convergence with Power over Coax capabilities is opening factory automation demand in automotive assembly and food processing verticals.
- Commercial:Fire-rated jacket mandates add material cost premiums for plenum installations in multi-tenant office and hospitality properties.
Residential holds installed capacity. Telecommunications is rotating up the share rankings.
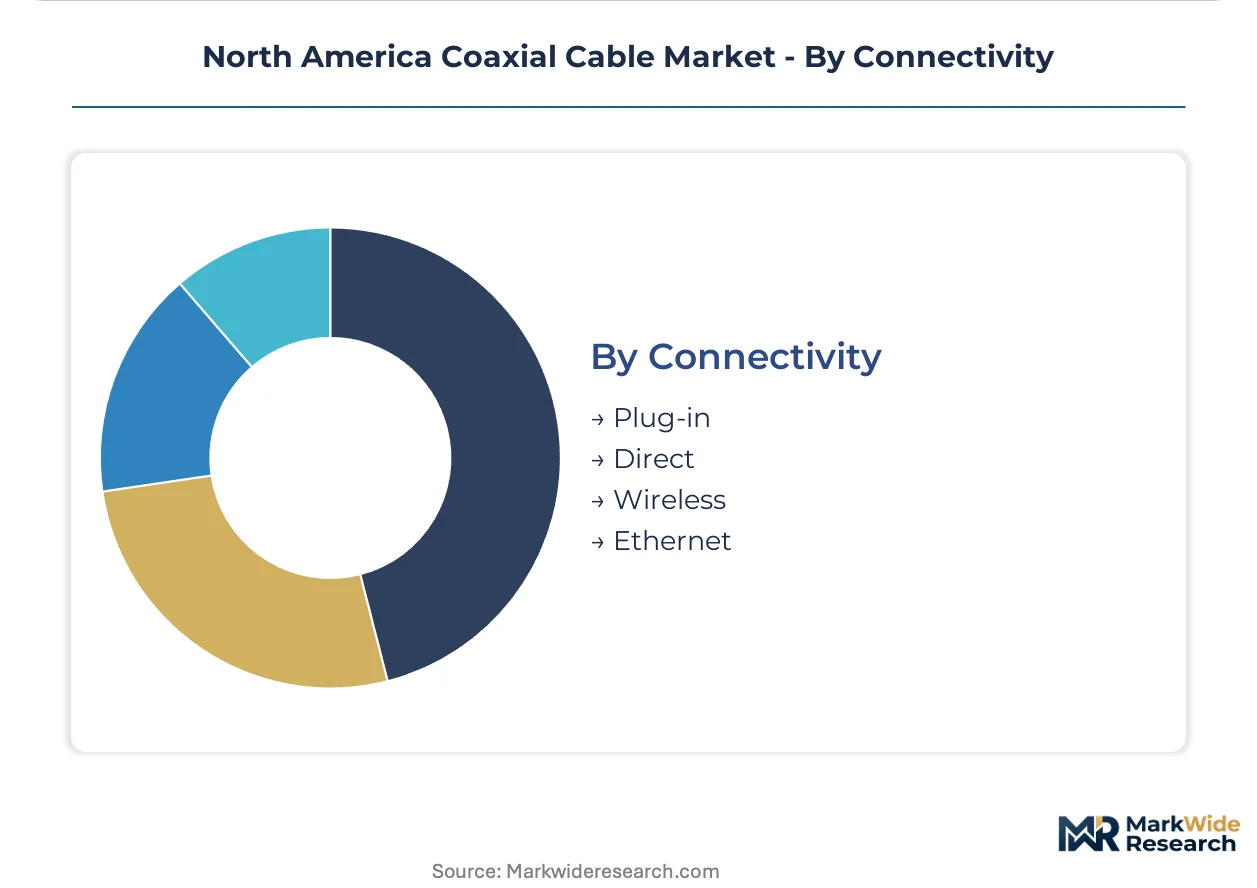
Connectivity:
Integration modality reflects installation labor economics and interoperability requirements with legacy amplifier cascades and passive splitter architectures.
- Direct:Hardwired termination dominates permanent infrastructure deployments in municipal broadband and electric utility smart grid AMI backhaul applications.
- Plug-in:Quick-connect interfaces accelerate field installation for 5G small cell deployments and temporary broadcast setups.
- Ethernet:Media converter integration enables coaxial cable reuse for IP-based surveillance and industrial IoT sensor networks.
- Wireless:Coaxial-to-antenna connections for distributed antenna systems in stadiums and transportation hubs.
Direct holds installed capacity. Ethernet is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC broadband equity programs and municipal bond financing are accelerating coaxial cable procurement across North American telecommunications infrastructure. State-level right-of-way policies and copper sourcing regulations are reshaping deployment economics for underground and aerial installations.
United States
Texas data center clusters in Dallas-Fort Worth and Austin drive bulk orders for low-loss RF coaxial assemblies in high-frequency interconnect applications. The FCC's BEAD program subsidizes hybrid fiber-coaxial last-mile expansions in underserved census tracts. California mobile network operators specify corrugated copper outer conductor designs for 5G small cell densification along Los Angeles-San Diego corridor.
Canada
Health Canada cold-climate certification requirements create protected demand for specialized low-temperature dielectric formulations in Arctic telecommunications infrastructure. The PMRA oversees cable safety standards for cross-border Great Lakes manufacturing corridor deployments. Ontario and Quebec municipal broadband expansions concentrate procurement volumes in Toronto-Ottawa-Montreal axis.
Mexico
Nearshoring manufacturing investments in Nuevo León and Baja California generate industrial-grade twinaxial demand for factory automation networks. Federal telecommunications reform frameworks accelerate backbone modernization programs. Mexico City metro area anchors residential coaxial deployment for cable television and internet service distribution.
North America Coaxial Cable Market Competitive Landscape
On the supply side, the industry is moderately consolidated with integrated cable manufacturers commanding premium positions in custom formulations while regional distributors face margin compression from procurement consolidation. Three archetypes dominate: vertically integrated copper-cladding specialists, precision dielectric extrusion houses, and hybrid fiber-coaxial system integrators. Competitive intensity centers on five-year framework agreement capture and captive raw material sourcing.
Among North American headquartered manufacturers, Belden Inc., CommScope, and Prysmian Group exemplify distinct strategic positioning within the supplier base. Belden represents the industrial automation specialist archetype with concentrated presence in factory network applications. CommScope anchors the telecommunications infrastructure tier through integrated supply capabilities spanning copper cathode to finished cable. Prysmian Group occupies the hybrid systems position linking submarine and terrestrial data center interconnect demand.
| Leading Market Players |
|---|
| Belden Inc. |
| CommScope |
| TE Connectivity Ltd |
| Amphenol Corporation |
| Southwire Company, LLC |
| Prysmian Group |
| Nexans S.A. |
| LS Cable & System Ltd. |
| Corning Incorporated |
| Others |
Pricing and Supply Chain Analysis
LME copper futures volatility compresses margin stability across the North America coaxial cable value chain, forcing simultaneous repricing of premium low-loss formulations and reconfiguration of cathode sourcing networks toward captive smelting arrangements.
Pricing Analysis
Certification level (FCC emissions compliance, NFPA 70 plenum rating, Health Canada cold-climate approval) creates the primary spread between commodity RG-series cable and precision-engineered outdoor assemblies. Three-tier pricing structure across premium, standard, and economy levels tracks shielding architecture and dielectric precision, with corrugated copper outer conductor designs commanding substantial premiums over braided-shield legacy products. Cost compression in standard residential drop cables is intensifying because fiber-to-the-home substitution erodes volume leverage. Municipal broadband procurement teams exhibit highest price sensitivity, while hyperscale data center operators prioritize signal integrity over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates raw material procurement risk for North American cable manufacturers without upstream copper cladding capacity. Primary manufacturing draws from the United States, Mexico, and Canada, with dielectric extrusion concentrated in Midwest production corridors and jacket compounding distributed across Texas and Ontario. The supply chain rests on copper cathode, foam polyethylene resin, and flame-retardant jacket compounds as critical inputs. Single-source vulnerability in electron-beam welding equipment for corrugated conductor fabrication threatens 5G fronthaul cable availability. Distribution runs through integrated supply contracts with tier-one telecommunications carriers, marginalizing regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America coaxial cable market sits at a platform-economics inflection where hybrid fiber-coaxial interoperability standards are consolidating procurement around framework agreements rather than spot-market purchasing.
For Market Incumbents: Pre-empt fiber substitution threats by deepening captive copper cladding capacity and securing five-year municipal broadband framework agreements before procurement consolidation hardens. Invest in electron-beam welding capabilities for corrugated outer conductor production to capture 5G small cell densification demand. Prioritize NFPA 70 and FAA dual-compliance certification for outdoor-rated assemblies serving aviation corridor deployments. For New Entrants and Emerging Players: Pursue industrial IoT convergence opportunities in factory automation networks, where Ethernet-over-coax with Power over Coax capabilities remains underpenetrated relative to telecommunications infrastructure. Target Canadian Arctic infrastructure deployments protected by Health Canada cold-climate certification requirements that create barrier-to-entry conditions. Lead with specialized low-temperature dielectric formulations and direct sales to electric utility smart grid AMI backhaul programs. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with in-house compound development labs and captive copper sourcing. Long-term viability hinges on positioning for hybrid fiber-coaxial network modernization cycles and industrial IoT sensor network expansion. Watch for FCC broadband equity program disbursement velocity as the signal indicating municipal procurement volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Cladding | CommScope and Belden anchor competitive positioning through captive cathode processing capacity. |
| Electron-Beam Welding Capability Expansion | Corrugated outer conductor fabrication for 5G millimeter-wave signal integrity commands premium positioning. |
| NFPA 70 Dual-Compliance Certification | FAA coordination requirements for aviation corridor deployments favor in-house compound development labs. |
| Five-Year Framework Agreement Capture | Tier-one carrier procurement consolidation marginalizes regional distributors and locks volume commitments. |
| Industrial IoT Sensor Network Partnership | Ethernet-over-coax convergence with Power over Coax opens factory automation white space. |
Research Methodology
A spread of perspectives from telecommunications procurement officers, cable manufacturing plant managers, municipal broadband program directors, and industrial automation integrators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through FCC broadband subsidy filings, NFPA standards documentation, Health Canada certification records, and SEC 10-K disclosures from listed cable manufacturers. Bottom-up volume modeling triangulated against top-down infrastructure investment forecasts across the analysis window.
Demand-supply balance modeling anchored projections, with segmentation across product type (RF coaxial, twinaxial, triaxial, hybrid), application (data transmission, internet services, television broadcasting, security systems), end user (telecommunications, residential, industrial, commercial), and connectivity modality. CAGRs derived from infrastructure investment trajectories, replacement cycle compression, and technology substitution elasticity. Industry-specific inputs included FCC BEAD program disbursement schedules, data center cluster construction pipelines, and 5G small cell densification targets.
Sensitivities concentrate around copper price volatility, fiber substitution velocity, and regulatory certification timeline shifts. Forecasts reflect documented assumptions about infrastructure investment continuity and technology migration patterns. Macroeconomic contraction, accelerated fiber-to-the-home deployment, or electromagnetic emissions protocol revision would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Lugs Market
Cables
Cable Material Market
Cables
Downhole Cables Market
Cables
Cable Market
Cables
Nuclear Multi-Conductor Cables Market
Cables
Submarine Cables Market
Cables
Cable Tray Market
Cables
UK Cables Market
Cables
Asia-Pacific Premise Cable Market
Cables
Europe HVAC Cables Market
Cables
XLPE Cables Market
Cables
US Medium Voltage Cable Accessories Market
Cables
Fiber Optic Cable Accessories Market
Cables
Magnetic Charging Cable Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
High Voltage Cable Termination Market