
 GCC Cable Accessories Market | 2026-2036
GCC Cable Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Cable Accessories Market Intelligence
The gap between utility-grade specifications and commodity building-wire accessories is expanding across the GCC. Nexans S.A. leverages its European R&D base to supply high-voltage terminations for Saudi grid interconnection projects. Prysmian Group anchors its regional position through localized production and direct utility relationships. Bahra Advanced Cable Manufacture Co. Ltd. competes on proximity, sustaining shorter lead times for Saudi construction contractors.
Cable accessories encompass termination kits, joints, connectors, and insulating components engineered to maintain electrical continuity, mechanical integrity, and environmental sealing across polymer or elastomeric cable interfaces, typically rated from 1 kV through 500 kV depending on grid tier. Their primary purpose is to prevent partial discharge, moisture ingress, and thermal runaway at cable system discontinuities. Terminations and connectors command the deepest margin pools where technical certification barriers limit supplier entry. Underground installation accessories are gaining share as Gulf cities bury distribution networks to accommodate densification and aesthetic requirements. Composite materials are displacing conventional metal housings in coastal environments where salt-fog corrosion accelerates degradation.
Saudi Standards, Metrology and Quality Organization (SASO) and the UAE's Emirates Authority for Standardization and Metrology (ESMA) enforce fire-performance and halogen-content specifications that reshape procurement criteria for commercial and residential projects. The Gulf Cooperation Council's unified customs framework and technical regulations create cross-border compliance obligations that favor suppliers with multi-country certification portfolios. Stakeholders must monitor how Saudi Power Procurement Company tender schedules and UAE EWEC capacity auctions translate into accessory procurement waves.
Market Dynamics
Saudi Arabia's NEOM and Red Sea gigaprojects are compressing procurement timelines for high-voltage accessories, forcing suppliers to pre-certify products under SASO fire-performance standards before tender submission windows open.
Growth Catalysts
- Grid Interconnection Standards:Saudi Power Procurement Company tender schedules mandate 400 kV+ terminations for cross-border transmission links. Utilities stockpile accessories ahead of award announcements.
- UAE Urban Undergrounding Mandates:Dubai Municipality and Abu Dhabi Distribution Company directives require buried medium-voltage networks in new districts. Cold-shrink joints displace heat-shrink in coastal substations.
- Halogen-Free Compound Adoption:ESMA's fire-resistance specifications for commercial towers in Dubai and Sharjah drive LSZH (low-smoke zero-halogen) insulation demand across termination kits.
Market Restraints
- Copper Price Volatility:Connector and lug manufacturers face margin compression when London Metal Exchange copper spikes, with limited pass-through clauses in Saudi EPC contracts.
- European R&D Concentration:High-voltage termination design IP resides with specialized German and French compound formulators, creating import dependency for 132 kV+ accessories.
- Cross-Border Certification Friction:SASO and ESMA maintain non-harmonized test protocols for fire-performance, forcing dual testing runs for suppliers serving both markets.
Strategic Opportunities
- Kuwait Distribution Rehabilitation:Ministry of Electricity and Water's 10-year grid upgrade plan lacks established accessory suppliers, opening first-mover positioning for certified terminations.
- Digital Condition Monitoring Integration:Partial discharge sensors embedded in 33 kV joints enable predictive maintenance contracts. This hardware-software bundle is converging with traditional accessory supply.
- Bahrain Industrial Zone Electrification:Alba Line 6 expansion and Askar aluminum smelter projects require heavy-current busbar connections, a segment underserved by regional distributors.
Industry Challenges
- Compound Formulation Expertise Gap:Regional manufacturers lack in-house silicone rubber R&D for 275 kV+ stress-control geometries, relying on licensed European masterbatch imports.
- Installation Certification Bottlenecks:Jointer training programs accredited by SASO and ESMA produce fewer than 200 certified technicians annually across the GCC, constraining project execution velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Cable Accessories Market |
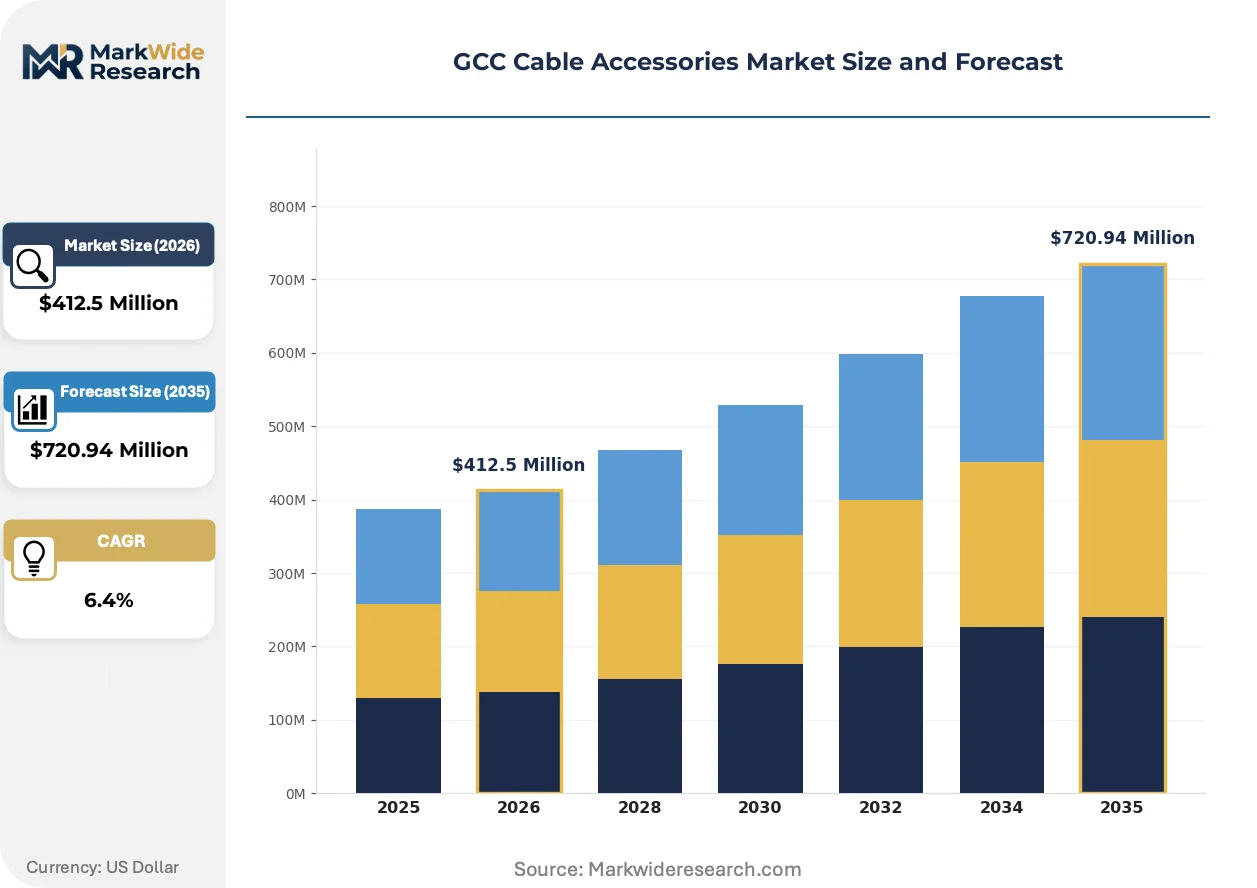
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Connectors, Junction Boxes, Terminations, Insulators Material: Plastic, Rubber, Metal, Composite Installation Type: Indoor, Outdoor, Underground, Overhead End User: Utilities, Construction, Industrial, Telecommunications |
| Companies Covered | Nexans S.A., Furukawa Electric Co., Ltd., ABB Ltd., NKT A/S, LS Cable & System Ltd., Dubai Cable Company, Prysmian Group, Bahra Advanced Cable Manufacture Co. Ltd., Elsewedy Electric, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Cable Accessories Market Strategic Shifts & Innovations
Material science advances and procurement digitization are restructuring how cable accessories are specified, tested, and delivered across Gulf utilities and EPC contractors.
Silicone rubber cold-shrink technology is displacing EPDM and heat-shrink alternatives in medium-voltage outdoor terminations. Saudi Aramco and ADNOC distribution affiliates specify cold-shrink for 11-33 kV offshore and desert applications where heat-gun installation proves impractical. This material shift is converging with robotic cable preparation systems that reduce field installation variability and warranty claim rates.
SASO's updated fire-performance testing protocols for building cable systems entered enforcement in 2024, extending halogen-content limits from high-rise residential towers to healthcare and education facilities. Manufacturers must submit compound formulations for third-party toxicity index testing before product registration. Saudi contractors now pre-qualify accessory suppliers based on SASO certificate validity windows, compressing vendor lists for Red Sea tourism projects.
Utility procurement departments are unbundling accessory supply from EPC installation contracts, creating direct manufacturer-to-utility purchasing channels. Saudi Electricity Company and Dubai Electricity and Water Authority now run separate tender lots for terminations versus jointing services, forcing distributors to reposition as technical advisors rather than bundled suppliers. This disintermediation is most advanced in Saudi Arabia's central region transmission projects.
GCC Cable Accessories Market Segmentation
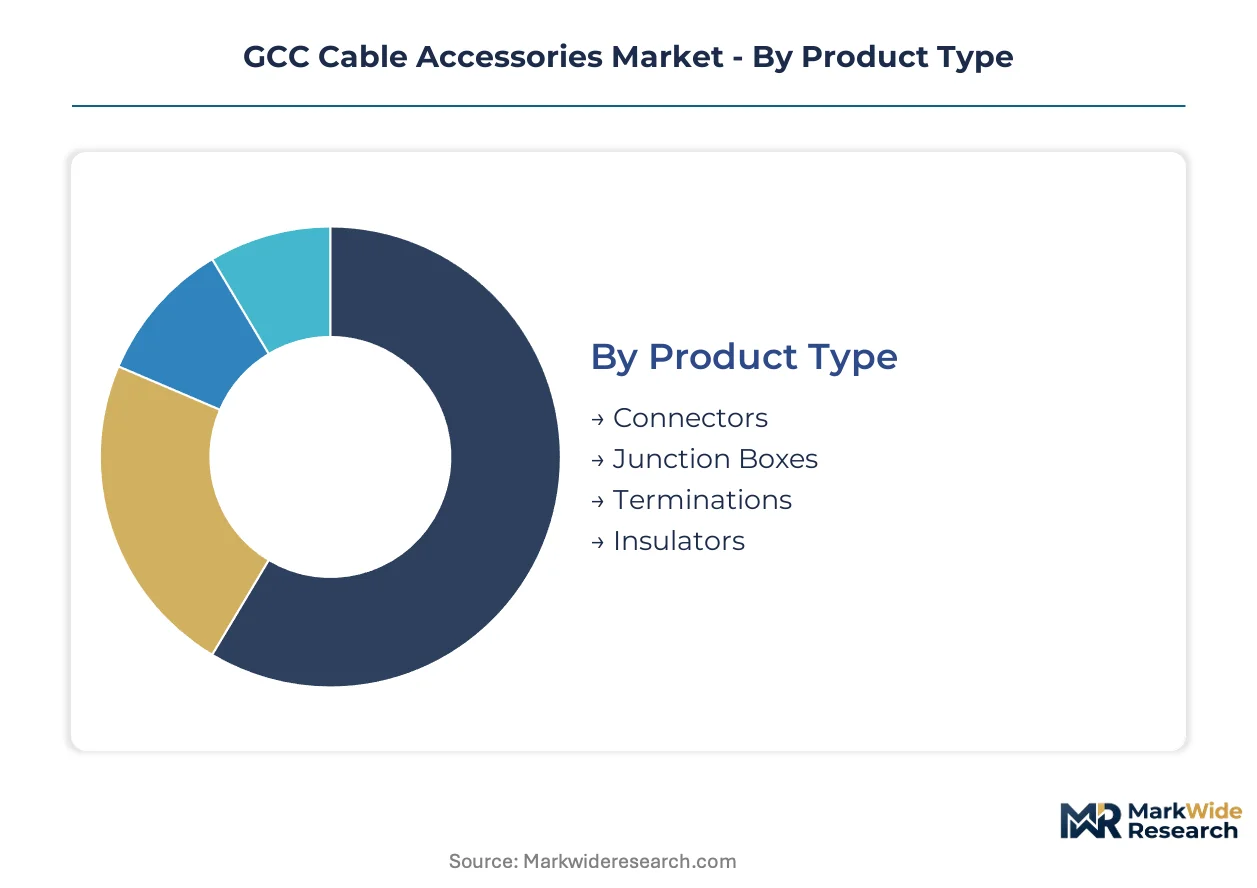
Cable accessory specifications diverge sharply across voltage tiers and environmental exposures in Gulf infrastructure. Procurement teams segment suppliers by certification depth rather than commodity availability.
Product Type:
Supply concentrates in termination and connector manufacturing where compound formulation IP limits regional production.
- Terminations:Cold-shrink silicone rubber assemblies dominate 11-33 kV outdoor specifications for Saudi Aramco and ADNOC distribution networks. NEOM and Red Sea gigaprojects are compressing SASO fire-certification timelines for 132 kV+ stress-control terminations.
- Connectors:Copper and aluminum compression lugs, mechanical bolted connectors, and GIS interface bushings maintain electrical continuity across substation equipment. Dubai Electricity and Water Authority now unbundle connector supply from EPC installation contracts.
- Junction Boxes:IP-rated enclosures house transition splices in UAE undergrounding mandates.
- Insulators:Polymeric housing assemblies displace porcelain in coastal 132 kV substations.
Today's leader: Terminations. Tomorrow's challenger: Connectors.
Material:
Cost tier stratification separates European-licensed compounds from regional commodity formulations.
- Rubber:Liquid silicone rubber and EPDM compounds form the dielectric backbone of cold-shrink joints and terminations. ESMA halogen-content specifications for Dubai commercial towers are reshaping procurement toward LSZH rubber masterbatches.
- Composite:Glass-reinforced polymer and epoxy resin housings displace metal in Bahrain and Qatar coastal installations where salt-fog corrosion accelerates degradation. Alba Line 6 expansion specifications favor composite busbar connections for aluminum smelter electrification.
- Plastic:Polyamide and polycarbonate junction box enclosures serve indoor commercial applications.
- Metal:Aluminum and brass connector bodies persist in utility-standard mechanical fittings.
Composite materials are climbing the fastest as coastal infrastructure expands.
Installation Type:
Application exposure determines warranty terms and supplier liability structures.
- Underground:Cold-shrink joints and waterproof transition chambers serve Dubai Municipality and Abu Dhabi Distribution Company buried network mandates. Robotic cable preparation systems are reducing field installation variability in Saudi central region transmission projects.
- Outdoor:Silicone rubber terminations with track-resistant housings withstand Gulf desert UV and thermal cycling. Kuwait Ministry of Electricity and Water rehabilitation tenders specify outdoor-rated 33 kV accessories for first-mover suppliers.
- Indoor:Heat-shrink and push-on terminations occupy switchgear and panelboard applications.
- Overhead:Dead-end assemblies and suspension clamps maintain aerial distribution in rural Saudi networks.
Underground installation commands premium positioning. Outdoor applications face jointer certification bottlenecks.
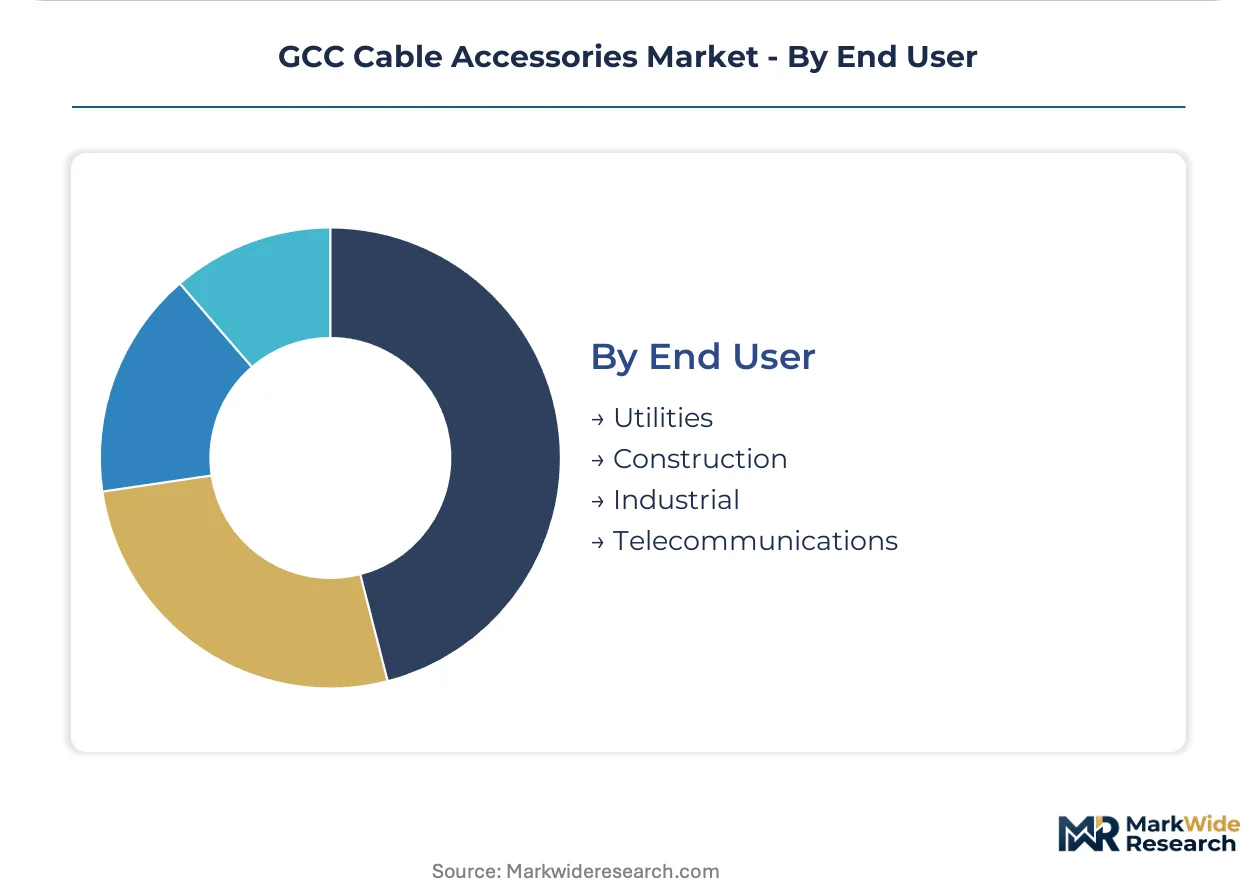
End User:
Customer type dictates technical documentation depth and payment security requirements.
- Utilities:Saudi Electricity Company and Dubai Electricity and Water Authority run direct manufacturer tender lots for 400 kV+ terminations, bypassing traditional distributor channels. Predictive maintenance contracts now bundle partial discharge sensors with 33 kV joint supply.
- Construction:Saudi contractors pre-qualify accessory suppliers based on SASO certificate validity windows for Red Sea tourism and NEOM residential clusters.
- Industrial:Bahrain Askar aluminum smelter and Qatar petrochemical expansions require heavy-current busbar connections underserved by regional distributors.
- Telecommunications:Fiber-optic cable sealing and grounding accessories serve data center electrification in Dubai and Riyadh.
Utility procurement represents the deepest margin pool. Construction volume offers scale exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands the largest procurement volumes for high-voltage accessories, while the UAE concentrates premium specification demand in Dubai's urban undergrounding mandates. Kuwait and Bahrain present first-mover openings as their grid rehabilitation programs accelerate.
Saudi Arabia
NEOM and Red Sea gigaprojects are compressing SASO fire-certification timelines for 132 kV+ terminations. Saudi Power Procurement Company tender schedules mandate 400 kV+ accessories for cross-border transmission links. Riyadh and the Eastern Province host concentrated utility procurement activity for central region transmission upgrades.
United Arab Emirates
Dubai Municipality and Abu Dhabi Distribution Company directives require buried medium-voltage networks in new districts. ESMA halogen-content specifications for commercial towers drive LSZH insulation demand across termination kits. Dubai's urban densification clusters concentrate cold-shrink joint procurement for coastal substations.
Kuwait
Ministry of Electricity and Water's 10-year grid upgrade plan lacks established accessory suppliers, creating entry openings for certified terminations. The country's national standards body enforces fire-performance testing protocols that mirror SASO frameworks. Kuwait City and surrounding industrial zones drive rehabilitation tender activity.
Bahrain
Alba Line 6 expansion and Askar aluminum smelter projects require heavy-current busbar connections underserved by regional distributors. The country's national regulator maintains electrical safety standards aligned with Gulf Cooperation Council technical regulations. Manama and the Southern Governorate concentrate industrial electrification demand.
Qatar
Petrochemical expansion projects and stadium legacy infrastructure sustain demand for medium-voltage outdoor terminations. The national standardization authority implements fire-resistance specifications for commercial and healthcare facilities. Doha and Ras Laffan Industrial City anchor procurement for coastal-rated composite housings.
GCC Cable Accessories Market Key Industry Players
Top-tier vendors anchor European-licensed compound supply, while regional fabricators compete on proximity and shortened lead times. The vendor base stratifies across three tiers: multinational cable system houses with integrated accessory divisions, specialized termination manufacturers licensing European masterbatch technology, and local distributors repositioning as technical advisors. Two dominant competitive moves are reshaping positioning: direct manufacturer-to-utility procurement channels bypassing traditional distribution, and predictive maintenance hardware-software bundles converging with traditional accessory supply.
Among European-anchored suppliers, Nexans S.A. and Prysmian Group exemplify the integrated multinational archetype, leveraging R&D concentration in German and French compound formulators to serve high-voltage transmission specifications. Bahra Advanced Cable Manufacture Co. Ltd. occupies a position within the regional proximity tier, sustaining shorter lead times for Saudi construction contractors through localized production relationships. These three anchors illustrate the competitive tension between technical certification depth and supply chain responsiveness across Gulf procurement channels.
| Leading Market Players |
|---|
| Nexans S.A. |
| Furukawa Electric Co., Ltd. |
| ABB Ltd. |
| NKT A/S |
| LS Cable & System Ltd. |
| Dubai Cable Company |
| Prysmian Group |
| Bahra Advanced Cable Manufacture Co. Ltd. |
| Elsewedy Electric |
| Others |
Cost & Logistics Intelligence
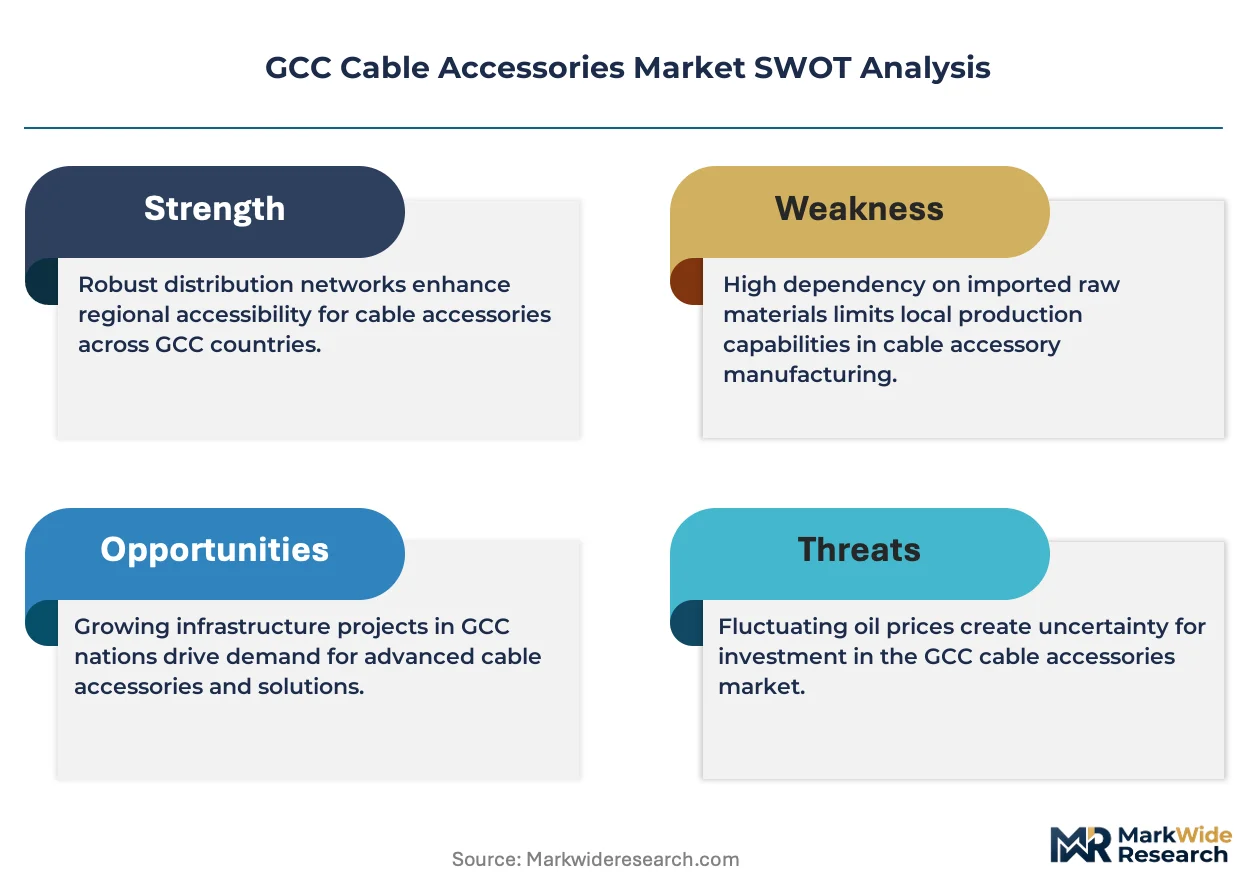
Saudi Electricity Company and Dubai Electricity and Water Authority direct procurement programs concentrate buying power among state-linked utilities, compressing margin pools for distributors and forcing manufacturers toward unbundled equipment-plus-service contract models.
Pricing Analysis
Unbundled accessory supply from installation services is reshaping contract structures across Gulf utilities. Three-tier pricing stratification separates SASO-certified premium terminations from standard commercial-grade connectors and economy mechanical fittings. Cost compression in copper-dependent connector segments intensifies when London Metal Exchange prices spike, with limited pass-through protection in Saudi EPC contracts. Construction contractors exhibit highest price sensitivity, while transmission utilities prioritize certification validity over unit cost.
Supply Chain Analysis
Certification gating through SASO and ESMA fire-performance protocols fragments supplier eligibility across Saudi Arabia and the United Arab Emirates. European-licensed silicone rubber compound formulators in Germany and France anchor high-voltage termination supply, while regional fabricators in Saudi Arabia and the UAE serve medium-voltage building-wire segments. Raw material dependencies on copper cathodes, liquid silicone masterbatches, and glass-reinforced polymer resins expose manufacturers to commodity volatility and import lead time variability. Single-source vulnerability concentrates in 275 kV+ stress-control geometry IP held by specialized European compound developers. Distribution runs through manufacturer-direct utility channels and repositioned technical-advisor distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where SASO's 2024 fire-performance protocol extension to healthcare and education facilities is accelerating replacement demand and compressing vendor qualification timelines.
For Market Incumbents: Extend certification coverage across both SASO and ESMA jurisdictions to capture cross-border procurement efficiencies. Deepen backward integration into silicone rubber masterbatch supply through licensed European partnerships, defending against emerging regional compound formulators. Prioritize jointer training program accreditation to alleviate installation certification bottlenecks constraining project velocity.
For New Entrants and Emerging Players: Kuwait Ministry of Electricity and Water rehabilitation tenders represent the most penetrable utility entry point, with established supplier relationships underdeveloped relative to Saudi Arabia and the UAE. Bahrain industrial electrification projects for aluminum smelter expansiation offer white-space positioning in heavy-current busbar connections. Lead with predictive maintenance hardware-software bundles to differentiate from commodity accessory suppliers.
For Investors and Strategic Acquirers: European cable system houses with integrated accessory divisions are the most active acquirer in this space, targeting specialized termination manufacturers with SASO pre-certification. Long-term viability hinges on compound formulation IP control and multi-country certification portfolios. Watch Saudi Power Procurement Company tender award announcements as inflection indicators for procurement wave timing.
| Strategic Initiative | Industry Significance |
|---|---|
| SASO Fire-Certification Pre-Qualification | Compresses vendor lists for NEOM and Red Sea gigaproject procurement windows. |
| Silicone Rubber Masterbatch Licensing | Secures compound IP access for 132 kV+ stress-control termination supply. |
| Jointer Training Program Accreditation | Alleviates installation certification bottlenecks constraining GCC project execution. |
| Predictive Maintenance Sensor Integration | Converges hardware-software bundles with traditional 33 kV joint supply contracts. |
| Direct Utility Procurement Channel Development | Bypasses distributor intermediation in Saudi central region transmission projects. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility procurement officers, EPC contract managers, compound formulator R&D directors, and cable jointer training program administrators with secondary validation through SASO technical regulation filings, ESMA product registration databases, GCC customs trade data, and SEC disclosures from listed cable system houses. Bottom-up project pipeline aggregation and top-down utility capex allocation analysis provided cross-verification.
Segment-weighting approaches modeled voltage tier, material compound type, installation environment exposure, and end-user procurement channel across the projection horizon. CAGRs derived from utility tender schedule analysis and gigaproject milestone tracking, with cross-border transmission interconnection timelines and urban undergrounding mandate implementation pace serving as demand-side forecast inputs.
Inputs from regulatory filing databases and utility procurement portals were available through the study window; gaps in real-time tender award pricing introduce uncertainty bands around volume-to-value conversion assumptions. Forecasts reflect documented assumptions regarding SASO certification timeline adherence and copper price trajectory stability. A model refresh is warranted upon material change in Saudi Power Procurement Company tender scheduling or ESMA halogen-content specification revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Ethernet Converters Market
Cables
Cable Testing and Certification Market
Cables
Global Low Voltage Cable Market
Cables
Global Cable Gland Market
Cables
Cable Market
Cables
Mexico Wires and Cables Market
Cables
Audio and Video Cables Market
Cables
Low-Temperature Cable Market
Cables
Cable Organisers Market
Cables
Medium Voltage Cables Market
Cables
EDM Wires Market
Cables
Latin America Wire and Cable Market
Cables
FFC/FPC Jumper Cables Market
Cables
Fiber Optic Cables for Military & Aerospace Market
Cables
Sensor Cable Market
Cables
Fiber Optic Cable Accessories Market