
 North America Patch Cable Market | 2026-2036
North America Patch Cable Market Size, Share, and Industry Trends Forecast 2026-2036
North America Patch Cable Market Insights
Pre-terminated cable bundling is shifting procurement patterns across enterprise and hyperscale buyers. Corning Incorporated leverages its optical-cable heritage to anchor credibility in copper patch segments. Belden Inc. differentiates through industrial-grade shielding architectures for manufacturing environments. Amphenol Corporation competes on connector density and modular breakouts for dense rack configurations.
North America patch cables are twisted-pair copper assemblies with RJ45, LC, SC, or ST terminations, engineered to TIA-568 performance benchmarks for structured cabling systems. Cat6a and Cat7 product types command premium positioning as 10GBase-T and 25GBase-T deployments expand in enterprise LAN refresh cycles. Shielded twisted pair configurations are gaining share in healthcare and financial verticals where electromagnetic interference mitigation carries compliance weight. Flat cable form factors occupy niche growth pockets under raised-floor and desk-edge routing scenarios where bend radius constraints limit round-cable deployment.
FCC equipment authorization rules and UL 444 flame-test certifications govern market access for patch cable assemblies sold in the United States. TIA and ISO/IEC cabling standards shape interoperability requirements that buyers embed in RFP specifications. Procurement teams must weigh copper-versus-optical transition timelines against stranded capital in existing Cat6 plant.
Market Dynamics
Hyperscaler data center construction timelines in Northern Virginia's Ashburn corridor are compressing procurement cycles for shielded copper assemblies, forcing cable vendors to pre-position inventory against 400G migration schedules.
Growth Catalysts
- 400G copper migration:Data center operators across the United States are scaling twisted-pair infrastructure to support 25GBase-T server connectivity. TIA-568.2-D performance benchmarks are tightening procurement specifications for Cat6a and Cat7 assemblies.
- Healthcare EMI compliance:Shielded twisted pair configurations are gaining mandatory status in hospital networks where FCC Part 15 electromagnetic interference limits intersect with HIPAA data integrity requirements.
- Ashburn corridor concentration:Northern Virginia's hyperscaler campus builds consume premium pre-terminated cable bundles, pulling assembly capacity toward mid-Atlantic distribution nodes.
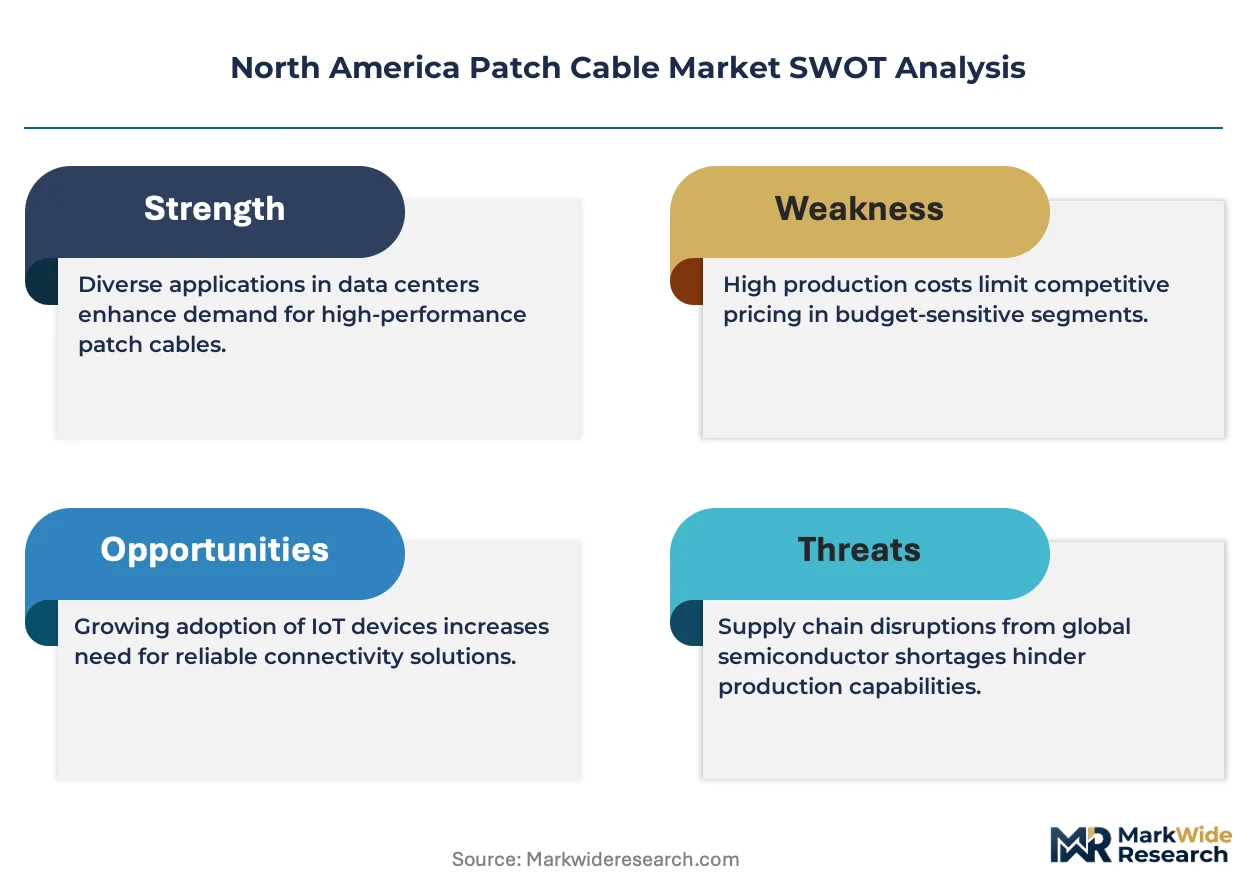
Market Restraints
- Copper raw material volatility:LME copper price swings directly compress margin structures for stranded conductor production. Cable assemblers lack pricing power to pass through commodity spikes to locked enterprise contracts.
- Optical substitution threat:Single-mode fiber transceiver cost curves are flattening below copper power-draw thresholds for runs exceeding 30 meters in hyperscale spine-leaf architectures.
- UL 444 certification bottlenecks:Third-party flame-test verification queues at Underwriters Laboratories are extending lead times for plenum-rated jacket materials, constraining rapid-response manufacturing.
Strategic Opportunities
- Canadian data center expansion:Montreal and Toronto hyperscaler builds are accelerating due to Quebec's hydroelectric power cost advantages, creating demand for shielded assemblies compliant with CSA C22.2 standards.
- Flat cable form factor penetration:Under-desk and raised-floor routing constraints in financial trading floors are opening niche demand for ultra-low-profile Cat6a constructions with 15mm bend radius specifications.
- Industrial IoT convergence:Manufacturing environments are merging Ethernet/IP control traffic with standard IT infrastructure, requiring Belden-style continuous-flex shielded cables that bridge operational technology and information technology domains.
Industry Challenges
- Certification timeline compression:TIA-568.2-D to TIA-568.5 standards evolution is forcing manufacturers to maintain parallel test lab accreditations while supporting legacy Cat5e plant in enterprise refresh cycles.
- Skill scarcity in precision termination:RJ45 connector crimp consistency for 28AWG stranded conductors requires technician training programs that outpace available workforce pipeline in Mexican maquiladora assembly operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Patch Cable Market |
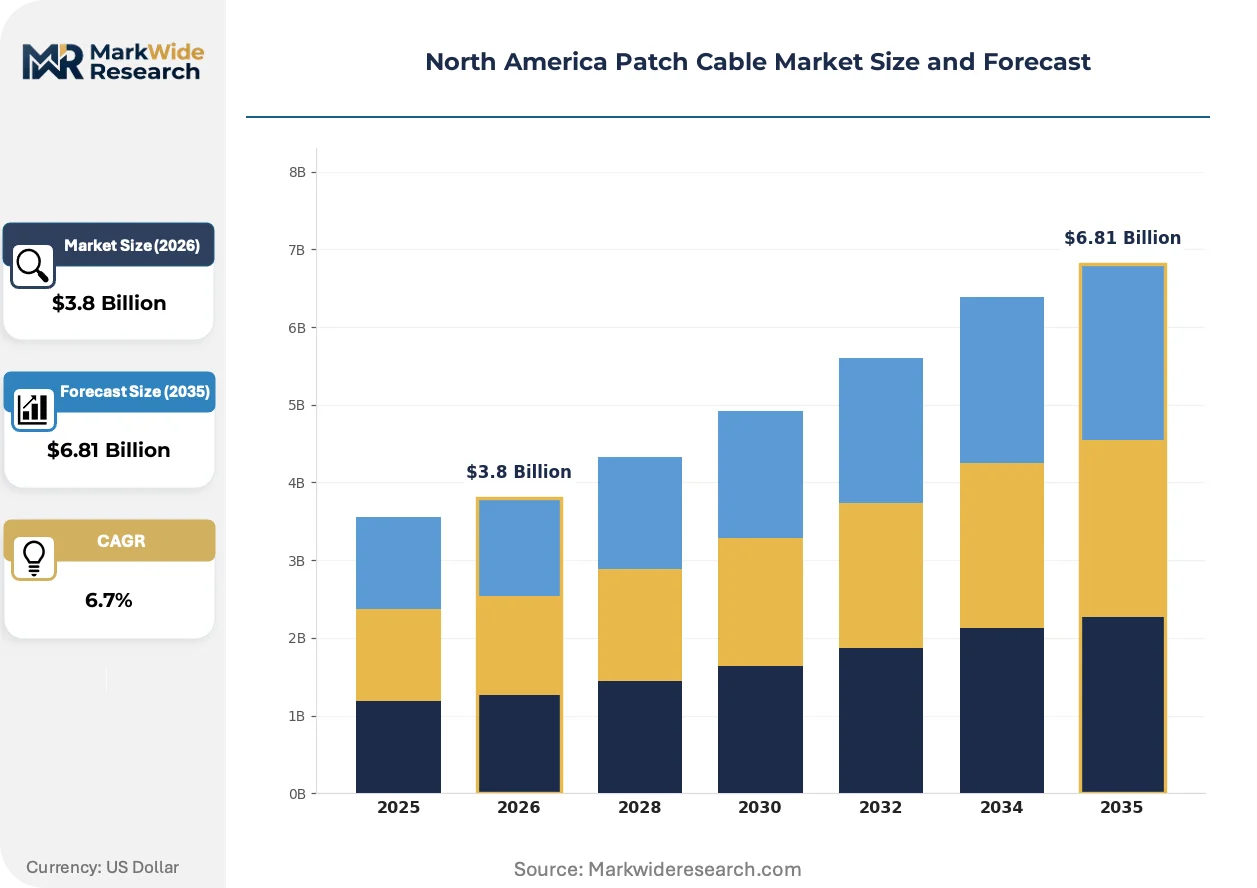
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cat5e, Cat6, Cat6a, Cat7 Form Factor: Patch Cable, Snagless Cable, Flat Cable, Round Cable Shielding Type: Unshielded Twisted Pair, Shielded Twisted Pair, Foiled Twisted Pair, Screened Twisted Pair Connector Type: RJ45, LC, SC, ST |
| Companies Covered | CommScope Holding Company Inc., Corning Incorporated, Belden Inc., Amphenol Corporation, CP Technologies, Panduit Corporation, Prysmian Group, TE Connectivity Corporation, Black Box Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Patch Cable Market Trends and Innovations
Pre-terminated cable bundling is restructuring procurement relationships between hyperscale buyers and assembly houses, compressing traditional distributor margins while elevating specification-engineering capabilities.
Modular breakout architectures are consolidating rack-level connectivity decisions. Hyperscale facility engineers are specifying factory-terminated MPO-to-RJ45 harnesses that reduce field installation labor by half. This consolidation is compressing demand for discrete patch cord SKUs in favor of configured assembly programs with locked bill-of-materials.
FCC equipment authorization rules are tightening electromagnetic compatibility verification for shielded cable assemblies. The Commission's 2023 enforcement memorandum on unintentional radiators is forcing manufacturers to submit revised test data for existing plenum-rated product lines. Healthcare and financial verticals in the United States are responding by embedding FCC compliance certificates directly into RFP technical specifications.
Enterprise buying committees are unbundling cable procurement from broader infrastructure contracts. Fortune 500 technology sourcing teams are establishing direct relationships with TIA-certified assembly houses, bypassing traditional electrical distribution channels. This disintermediation is most visible in Northern Virginia and Dallas-Fort Worth data center clusters where volume concentration justifies dedicated vendor-managed inventory programs.
North America Patch Cable Market Segmentation
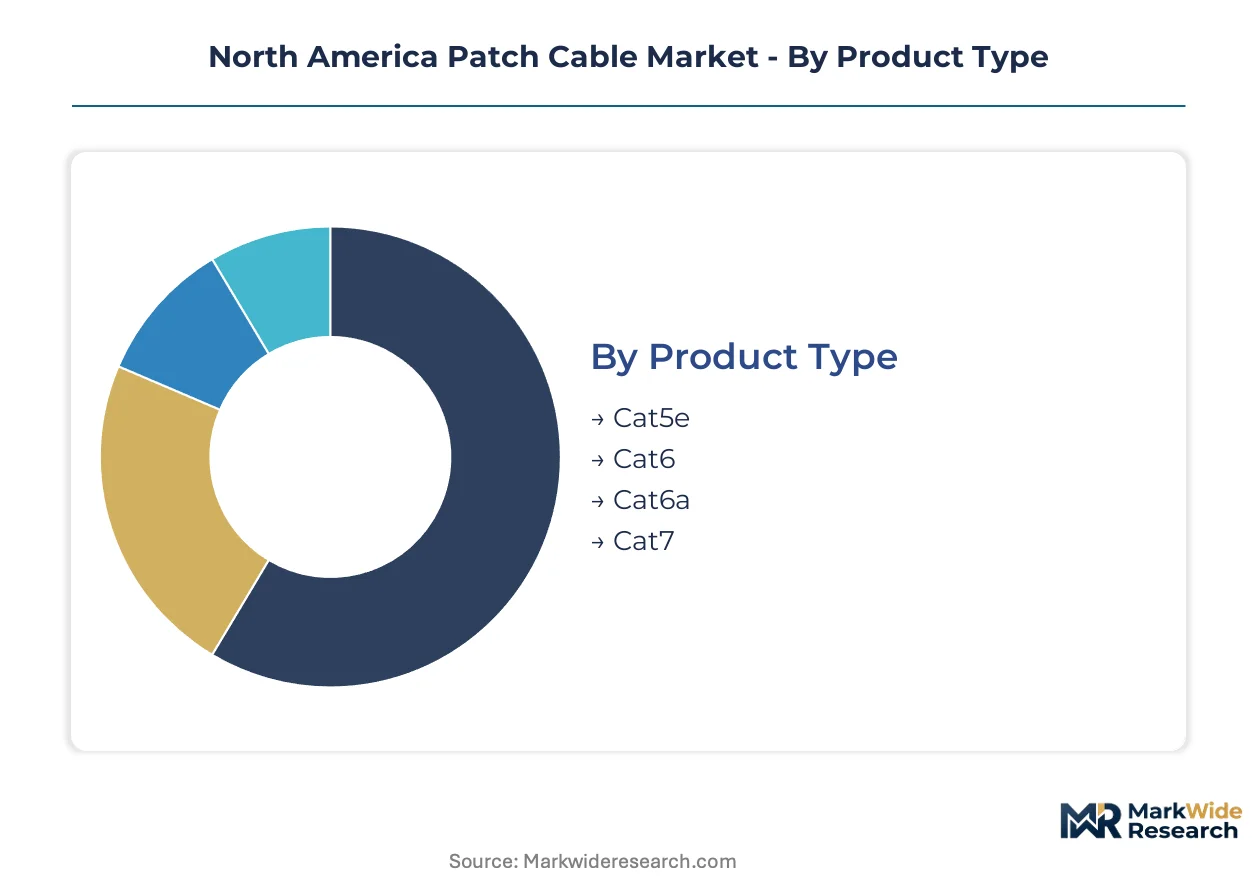
Patch cable procurement in North America hinges on performance tier decisions that balance stranded capital in legacy plant against 400G migration timelines. Buyers segment choices by bandwidth headroom, physical routing constraints, and electromagnetic interference exposure.
Product Type:
Enterprise technology sourcing teams anchor category decisions on TIA-568 performance benchmarks and server connectivity roadmaps.
- Cat5e:Legacy 100MHz-rated assemblies remain entrenched in enterprise refresh cycles where 1GBase-T suffices. Procurement teams in secondary US markets defer replacement to minimize stranded infrastructure.
- Cat6:250MHz bandwidth supports 10GBase-T runs up to 55 meters. Demand concentrates in Dallas-Fort Worth data center clusters where hyperscalers provision mid-tier server connectivity.
- Cat6a:Augmented 500MHz specifications enable 10GBase-T to 100 meters. Northern Virginia Ashburn corridor builds consume premium shielded variants for 25GBase-T server uplinks.
- Cat7:600MHz S/FTP constructions with individual pair shielding command positioning in financial trading floors where latency sensitivity intersects with EMI-heavy environments.
Cat6a leads on scale; Cat7 leads on momentum.
Form Factor:
Physical installation constraints dictate selection between standard and specialized constructions.
- Patch Cable:Standard round-profile assemblies with molded strain relief dominate rack-to-rack connectivity in data center spine-leaf architectures.
- Snagless Cable:Boot-protected RJ45 terminations prevent latch damage during dense patching. Hyperscale facility engineers specify these for rapid MAC work in live production environments.
- Flat Cable:Ultra-low-profile 15mm bend radius constructions penetrate financial trading floors and under-desk enterprise routing where raised-floor depth limits round-cable deployment.
- Round Cable:Conventional cylindrical geometry maintains structural integrity in vertical cable managers and overhead ladder tray runs.
Patch cable leads on scale; flat cable leads on momentum.
Shielding Type:
Electromagnetic environment assessment drives compliance-weighted procurement specifications.
- Unshielded Twisted Pair:Cost-optimized constructions without metallic shielding satisfy standard office LAN deployments where interference exposure remains minimal.
- Shielded Twisted Pair:Overall foil or braid coverage mitigates EMI in manufacturing environments and healthcare networks where FCC Part 15 limits intersect with HIPAA data integrity requirements.
- Foiled Twisted Pair:Individual pair foil wrapping delivers balanced protection against alien crosstalk in high-density patching fields.
- Screened Twisted Pair:Combination foil-and-braid architectures anchor Cat7 specifications for maximum electromagnetic immunity in critical infrastructure.
Unshielded twisted pair leads on scale; shielded twisted pair leads on momentum.
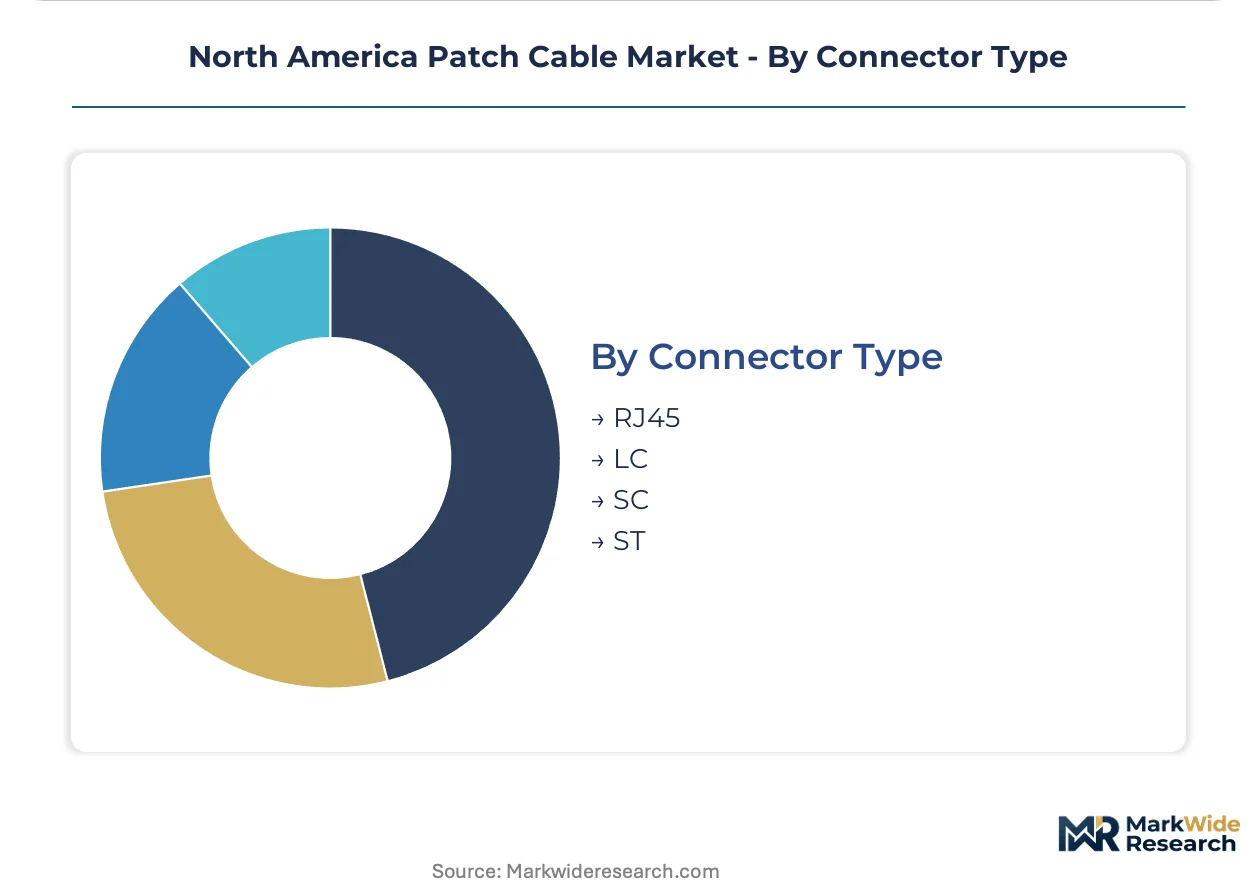
Connector Type:
Interface standardization determines interoperability with active equipment ports.
- RJ45:Eight-position modular connectors anchor twisted-pair Ethernet deployments across enterprise and data center environments.
- LC:Small-form-factor push-pull latching dominates fiber-to-the-copper transition points in hyperscale facilities.
- SC:Square push-pull connectors persist in legacy enterprise fiber plant and industrial control networks.
- ST:Bayonet-twist locking mechanism retains positioning in manufacturing floor deployments where vibration resistance carries priority.
RJ45 leads on scale; LC leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper cabling infrastructure first achieved industrial scale in the United States during the 1980s telecommunications deregulation era, with Bell System breakup spawning the structured cabling industry that now spans three North American economies.
United States
Ashburn's hyperscaler corridor in Northern Virginia consumes premium shielded Cat6a and Cat7 assemblies for 400G migration timelines. FCC equipment authorization rules and UL 444 flame-test certifications govern market access for plenum-rated jacket materials. Dallas-Fort Worth data center clusters provision mid-tier server connectivity, pulling assembly capacity toward Texas distribution nodes.
Canada
Montreal and Toronto hyperscaler builds accelerate due to Quebec's hydroelectric power cost advantages, creating demand for shielded assemblies. CSA C22.2 standards compliance distinguishes Canadian procurement specifications from US TIA benchmarks. Vancouver's Pacific gateway position anchors trans-Pacific cable landing connectivity, supporting west coast data center interconnection demand.
Mexico
Querétaro and Guadalajara electronics manufacturing clusters drive industrial-grade shielded cable consumption for factory automation networks. Mexican maquiladora assembly operations face technician training gaps for precision RJ45 termination of 28AWG stranded conductors. NOM-001-SCFI electrical safety standards intersect with USMCA trade provisions in cross-border supply chains.
North America Patch Cable Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and specification-engineering capabilities. The vendor base spans three structural tiers: integrated materials-to-assemblers controlling conductor and jacket supply, specialized termination houses focusing on pre-terminated bundling, and distributor-branded commodity players. Three strategic archetypes dominate: optical-cable heritage firms extending credibility into copper, industrial-grade shielding specialists, and connector-density engineers optimizing rack-level configurations. Competitive moves concentrate on vertical integration into raw conductor supply and strategic partnerships with hyperscale facility engineers for vendor-managed inventory programs.
Within the integrated-materials tier, Corning Incorporated leverages its optical-cable heritage to anchor credibility in copper patch segments. Belden Inc. exemplifies the industrial-grade shielding archetype through continuous-flex architectures. Amphenol Corporation occupies the connector-density position, competing on modular breakouts for dense rack configurations. These three represent distinct capability vectors rather than overlapping market positions.
| Leading Market Players |
|---|
| CommScope Holding Company Inc. |
| Corning Incorporated |
| Belden Inc. |
| Amphenol Corporation |
| CP Technologies |
| Panduit Corporation |
| Prysmian Group |
| TE Connectivity Corporation |
| Black Box Limited |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange copper price volatility cascades through stranded conductor production into three-tier pricing structures across premium, standard, and economy levels. Cable assemblers in Mexico and the United States absorb commodity spikes that locked enterprise contracts prevent passing through, compressing margin structures for mid-tier shielded assemblies while UL-certified premium variants retain pricing power.
Pricing Analysis
Contract-based long-term offtake agreements dominate hyperscale procurement, with price differentiation resting on UL 444 flame-test certification tier and volume scale commitments. Cost compression in standard-grade Cat6 assemblies is intensifying because Mexican maquiladora operations face technician training gaps for precision 28AWG termination. Enterprise buyers in secondary US markets exhibit highest price sensitivity, deferring Cat5e replacement to minimize stranded infrastructure investment.
Supply Chain Analysis
UL 444 certification queues at Underwriters Laboratories gate market access for plenum-rated jacket materials, extending lead times that favor pre-qualified assembly houses. Raw copper draws from Chilean mining operations and US scrap reclamation, while connector components hinge on Taiwanese precision manufacturing. Single-source vulnerability concentrates in FCC equipment authorization test labs. Distribution runs through electrical distribution channels that hyperscale buyers increasingly bypass for direct TIA-certified assembly house relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America patch cable market represents a late-cycle quality story as 400G migration timelines pull procurement toward shielded Cat6a and Cat7 specifications with stringent EMI compliance requirements.
For Market Incumbents: Anticipate optical substitution pressure in spine-leaf architectures exceeding 30 meters by deepening backward integration into raw conductor supply. Anchor vendor-managed inventory programs with Northern Virginia hyperscale facility engineers to lock specification-engineering relationships before single-mode fiber transceiver cost curves flatten further. For New Entrants and Emerging Players: Electrical distribution channel partners offer the most penetrable entry vector for CSA C22.2-compliant shielded assemblies targeting Montreal and Toronto hyperscaler builds. Flat cable form factors for financial trading floors present white-space opportunity with 15mm bend radius specifications that incumbent round-cable portfolios underserve. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized termination houses possessing TIA-568.2-D test lab accreditations and pre-terminated bundling capabilities. Long-term viability in this market requires certification depth rather than commodity scale. Watch for FCC enforcement memorandum expansion on unintentional radiators as signal of regulatory compliance premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Conductor Supply | Captive copper sourcing insulates margin structures from LME price volatility for stranded production. |
| UL 444 Certification Pre-Qualification Investment | Accelerated flame-test verification queues lock out rapid-response competitors from plenum-rated segments. |
| Vendor-Managed Inventory Programs | Dedicated stock positioning at Northern Virginia distribution nodes compresses procurement cycles for Ashburn corridor builds. |
| CSA C22.2 Standards Compliance Expansion | Montreal and Toronto hyperscaler demand requires Canadian electrical safety certification distinct from US TIA benchmarks. |
| Flat Cable Form Factor Development | Ultra-low-profile 15mm bend radius constructions penetrate financial trading floor routing constraints. |
Research Methodology
Bottom-up data center infrastructure modeling reconciled against top-down copper assembly capacity tracking forms the analytical core of this study. Primary interviews with hyperscale facility engineers, enterprise technology sourcing managers, TIA-certified assembly house operations directors, and electrical distribution channel partners combined with secondary validation from FCC equipment authorization databases, UL certification registries, SEC 10-K filings of listed cable manufacturers, and LME copper price series.
Input-output matrices map product type, form factor, shielding configuration, and connector interface dimensions against end-use vertical adoption patterns across the projection horizon. CAGRs derive from segment-level volume build-ups reconciled against aggregate market sizing. Forecast inputs include hyperscaler capex disclosure trajectories, TIA standards revision timelines, and raw material cost curve assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to optical transceiver cost curve flattening and FCC electromagnetic compatibility enforcement expansion. Forecasts reflect documented assumptions regarding 400G migration pacing and copper-versus-fiber transition thresholds. A model refresh is warranted upon material change in hyperscale server connectivity roadmaps or TIA-568 standards evolution timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Flexible Cables Market
Cables
Power Cable Accessories Market
Cables
XLPE Cables Market
Cables
Insulated Wire and Cable Market
Cables
Magnetic Charging Cable Market
Cables
Sensing Cable Market
Cables
Asia Pacific MV and HV Underground Cables and Accessories Market
Cables
Cable Organisers Market
Cables
Submarine Data Cables Market
Cables
Asia-Pacific Cable Joints Market
Cables
Cable Material Market
Cables
Low Voltage Cable Accessories Market
Cables
Shipboard Cable Market
Cables
Middle East Cable Market
Cables
Data Center Wire and Cable Market
Cables
USB Cable Market