
 Asia-Pacific Cable Joints Market | 2026-2036
Asia-Pacific Cable Joints Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cable Joints Market Insights
China's dual carbon goals and Japan's METI-led grid decarbonization roadmap are recalibrating procurement specifications across the Asia-Pacific cable joints landscape. Prysmian Group leverages its submarine cable heritage to dominate high-voltage offshore supply. TE Connectivity Ltd. anchors its position through R&D intensity in pre-terminated joint systems. LS Cable & System competes aggressively on manufacturing scale within South Korea's domestic utility market.
Asia-Pacific cable joints are engineered electromechanical assemblies that restore electrical continuity, mechanical integrity, and environmental sealing at cable terminations or repair points, typically rated from 1 kV through 500 kV depending on application. These components employ cross-linked polyethylene (XLPE) or ethylene-propylene rubber (EPR) insulation with metallic shielding continuity kits to maintain ampacity and fault-current paths in power distribution networks. Heat shrink joints retain the largest installed base across aging urban grids, while cold shrink technology captures the fastest growth trajectory due to reduced installation labor and elimination of open-flame work permits in confined underground vaults. Pre-terminated joints concentrate margin pools in data center and telecommunications applications where downtime costs dwarf material premiums.
China's SAMR enforces GB/T standards for cable accessory fire performance, while India's CEA mandates type-testing for 66 kV and above joints through central utility procurement rules. Japan's METI maintains JIS conformity assessment pathways that constrain market access for non-domestic suppliers. Stakeholders must monitor how Australia's TGA-equivalent electrical safety regulators and South Korea's KEPCO material qualification protocols evolve their reciprocity frameworks for cross-border certification.
Market Dynamics
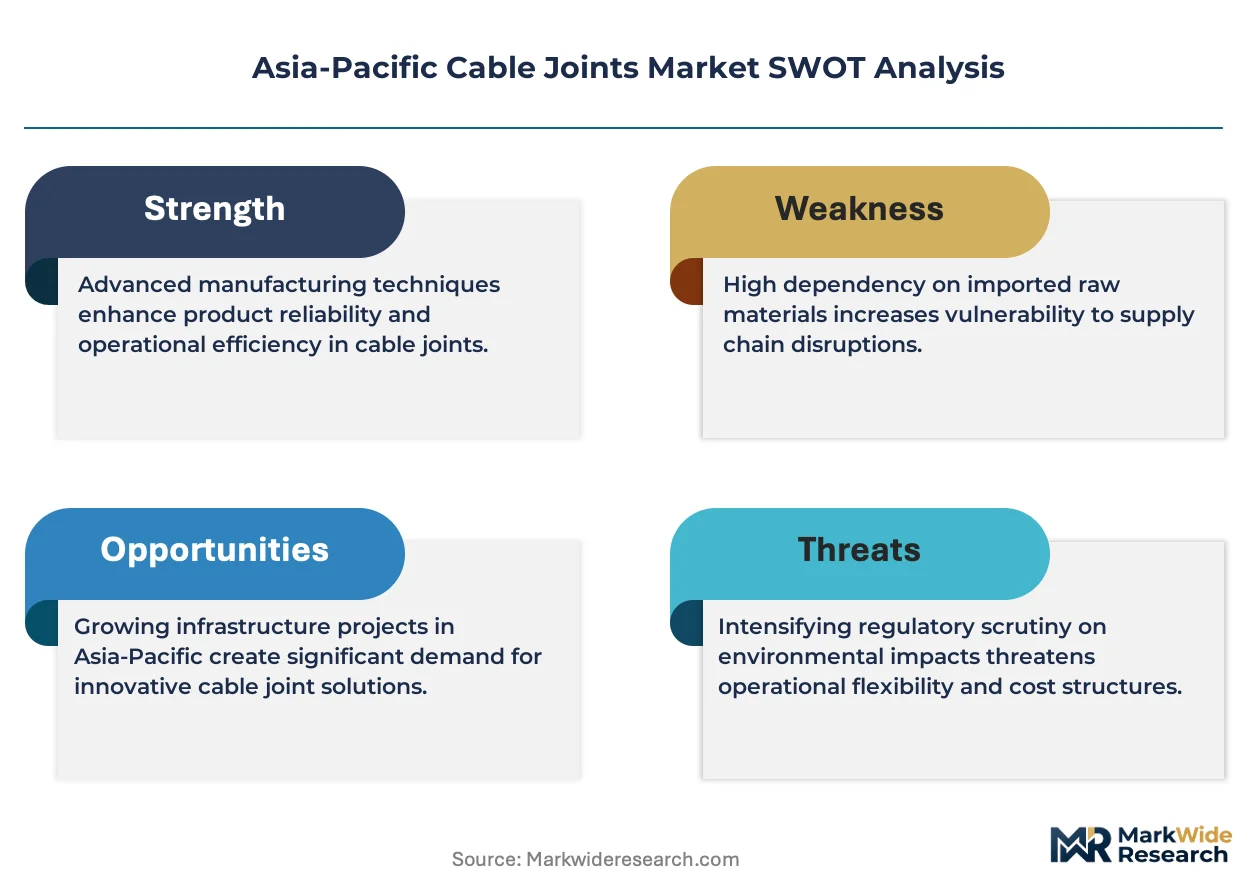
China's GB/T fire-resistance standards and Japan's METI grid decarbonization mandates are recalibrating procurement specifications across the Asia-Pacific cable joints landscape, compressing certification timelines while elevating technical barriers for non-domestic suppliers.
Growth Catalysts
- Offshore wind expansion:Array cable installations in Chinese and Japanese waters are accelerating medium-voltage joint procurement for subsea environments.
- India's state-grid modernization:CEA-mandated replacement cycles for 66 kV and above infrastructure are shortening asset lifecycles in transmission utilities.
- Fire-safety compliance tightening:SAMR enforcement of GB standards is upgrading product certification requirements and filtering marginal suppliers from regional tenders.
Market Restraints
- Copper and aluminum price volatility:Shielding continuity kits and metallic housings expose manufacturers to base metal cost swings without full pass-through mechanisms.
- JIS conformity assessment concentration:Japan's METI-maintained certification pathways constrain market access for suppliers lacking domestic testing infrastructure.
- Cold shrink material dependency:EPDM and silicone rubber formulations rely on specialized polymer supply chains concentrated in Northeast Asian chemical clusters.
Strategic Opportunities
- Southeast Asian grid buildout:Vietnam, Thailand, and Indonesia transmission expansion programs remain undersupplied with qualified 132 kV joint vendors.
- Data center pre-terminated systems:Hyperscale facility construction in Singapore and Sydney is creating premium-margin demand for plug-and-play joint assemblies.
- KEPCO material qualification reciprocity:South Korea's evolving mutual recognition frameworks may streamline cross-border certification for qualified regional suppliers.
Industry Challenges
- Skilled installer scarcity:Cold shrink and heat shrink joint installation requires certified technicians, with training pipelines lagging deployment schedules in India's utility sector.
- Legacy XLPE compatibility:New joint designs must interface with decades-old cable insulation systems without compromising sealing integrity or ampacity ratings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cable Joints Market |
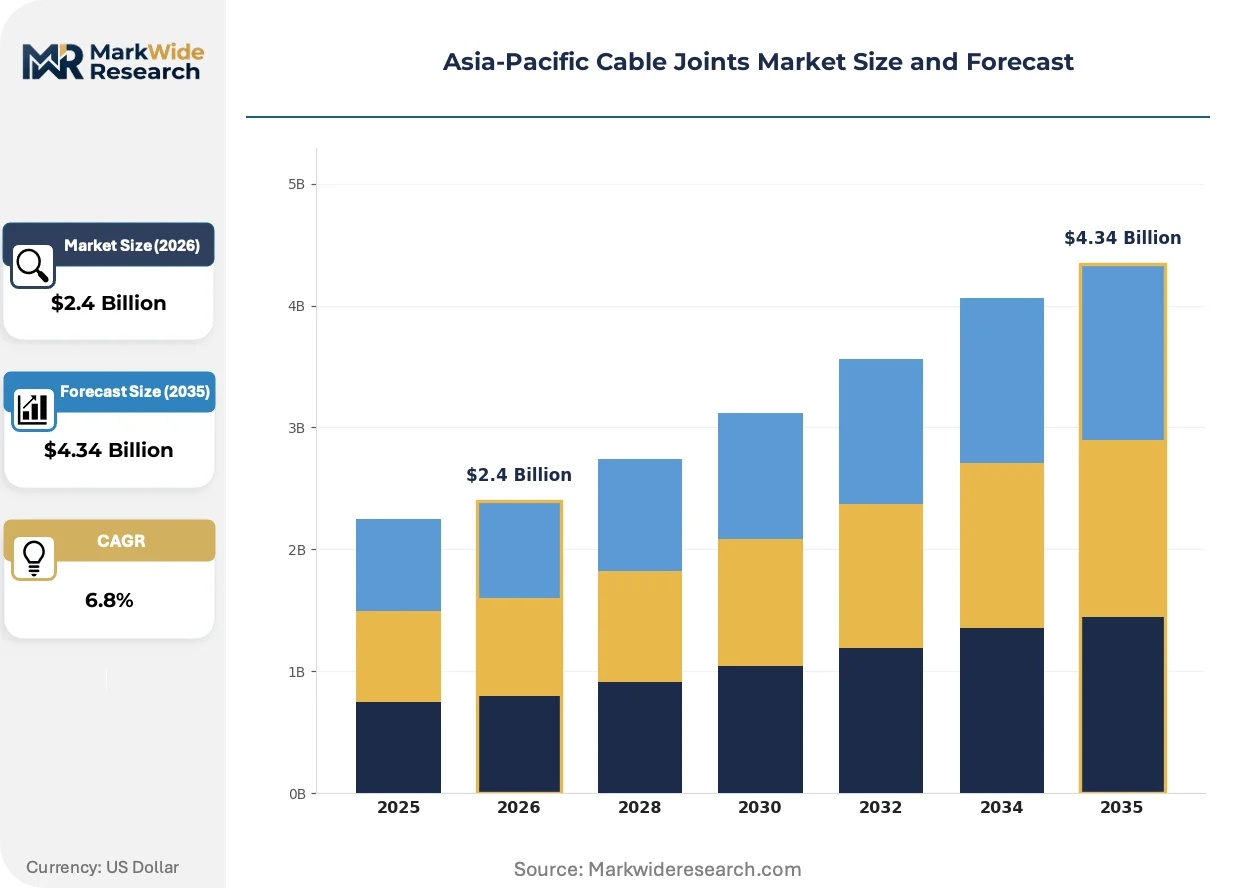
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Shrink, Pre-terminated, Cold Shrink, Insulating Installation Method: Indoor, Outdoor, Underground, Aerial End User: Telecommunications, Power Utilities, Renewable Energy, Industrial Capacity: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage |
| Companies Covered | Nexans S.A., Prysmian Group, TE Connectivity Ltd., Fujikura Ltd., Sumitomo Electric Industries, Furukawa Electric Co., Ltd., LS Cable & System, ABB Ltd., NKT A/S, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cable Joints Market Trends and Innovations
Material science advances and installation methodology shifts are compressing labor requirements while elevating performance specifications across voltage classes and environmental conditions.
Cold shrink joint technology is absorbing installation workflow efficiencies previously dependent on open-flame heat sources. Underground vault contractors in Tokyo and Seoul are adopting silicone rubber cold shrink systems to eliminate hot-work permits and reduce confined-space exposure. The technology is absorbing margin compression from labor cost inflation by shortening installation windows from hours to minutes.
Japan's METI has tightened JIS C 3605 conformity assessment for 66 kV cable accessories, mandating accelerated aging tests and partial discharge measurement protocols. Domestic manufacturers have absorbed compliance costs into product development cycles, while importers face extended type-test timelines at designated METI laboratories. High-voltage offshore segments are responding by consolidating supplier relationships with pre-qualified domestic entities.
Utility procurement officers are unbundling after-sales service contracts from hardware supply agreements. State transmission utilities in Maharashtra and Gujarat are separating joint installation supervision from material purchase orders, creating dedicated service procurement channels. This behavioral shift is most visible in India's central utility procurement rules, where CEA-mandated transparency is fragmenting single-source vendor relationships.
Asia-Pacific Cable Joints Market Segmentation
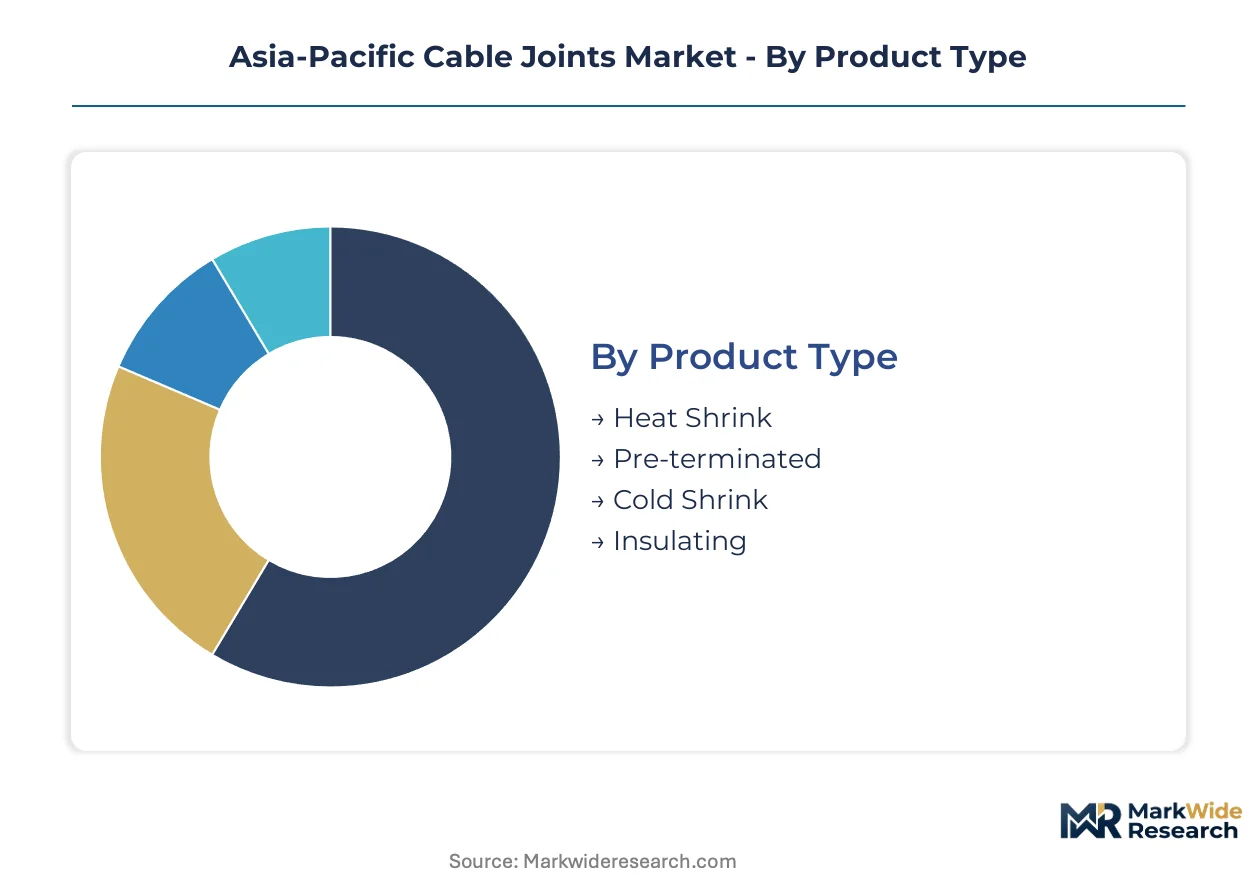
Cable joints in the Asia-Pacific region must satisfy divergent performance specifications across voltage classes, installation environments, and end-use sectors. Segmentation reveals where capital deployment concentrates and which technical standards filter supplier participation.
Product Type:
Capital intensity varies sharply by product category, with factory-terminated systems requiring the heaviest upfront tooling investment versus field-assembled alternatives.
- Heat Shrink:Polymeric sleeves with thermoplastic adhesive liners require propane torches for field installation. Aging urban grids in Japan and South Korea retain substantial installed base despite labor intensity and open-flame permitting requirements.
- Cold Shrink:Pre-expanded silicone or EPDM rubber tubes mounted on removable cores eliminate heat sources entirely. Tokyo and Seoul contractors are adopting these systems fastest to reduce confined-space exposure and accelerate installation windows.
- Pre-terminated:Factory-tested assemblies with integrated stress control and sealing systems command material premiums justified by near-zero failure rates in hyperscale data center applications across Singapore and Sydney.
- Insulating:Basic tape and resin-based solutions serve temporary repairs and low-voltage distribution extensions where capital constraints dominate procurement decisions in India's rural electrification programs.
Heat shrink joints absorb the bulk of installed capacity across legacy infrastructure; cold shrink technology is expanding most quickly through metropolitan underground networks.
Installation Method:
Environmental exposure severity dictates material specification tiers and warranty terms across deployment contexts.
- Indoor:Controlled-environment installations in substations and switchgear rooms permit simplified sealing requirements. India's state-grid modernization is accelerating replacement cycles for 66 kV indoor terminations.
- Outdoor:UV-stabilized housings and moisture-barrier designs withstand monsoon exposure and tropical humidity. Thailand and Vietnam transmission expansion programs are generating procurement volume for outdoor-rated 132 kV joints.
- Underground:Direct-buried and duct-bank installations demand watertight integrity and mechanical crush resistance. Chinese offshore wind developers are specifying subsea-rated underground joints for array cable connections.
- Aerial:Messenger-supported and self-supporting designs address right-of-way constraints in mountainous terrain and dense urban corridors. Japan's METI grid decarbonization roadmap is elevating technical specifications for aerial transmission refurbishment.
Underground installations command the highest material specification tiers; outdoor deployment is climbing the fastest as Southeast Asian transmission buildout accelerates.
End User:
Procurement sophistication and total-cost-of-ownership calculation maturity diverge substantially across customer categories.
- Power Utilities:Central and state transmission entities in India operate under CEA-mandated type-testing protocols that constrain vendor qualification. Replacement cycle compression is shortening asset lifecycles for 66 kV and above infrastructure.
- Renewable Energy:Offshore wind farm developers in China and Japan are expanding medium-voltage joint procurement for subsea array cables. Project finance requirements are elevating supplier track record and warranty duration expectations.
- Telecommunications:Fiber-optic and power-over-ethernet cable joint demand concentrates in data center construction across Singapore and Sydney. Downtime cost calculus justifies premium pricing for pre-terminated plug-and-play systems.
- Industrial:Manufacturing facility and port electrification projects in Indonesia and Vietnam prioritize availability over capital cost. Procurement officers favor established regional distributors with local inventory and technical service capability.
Power utilities absorb the bulk of procurement volume through centralized tender processes; renewable energy project demand is gaining share fastest as offshore wind pipelines mature.
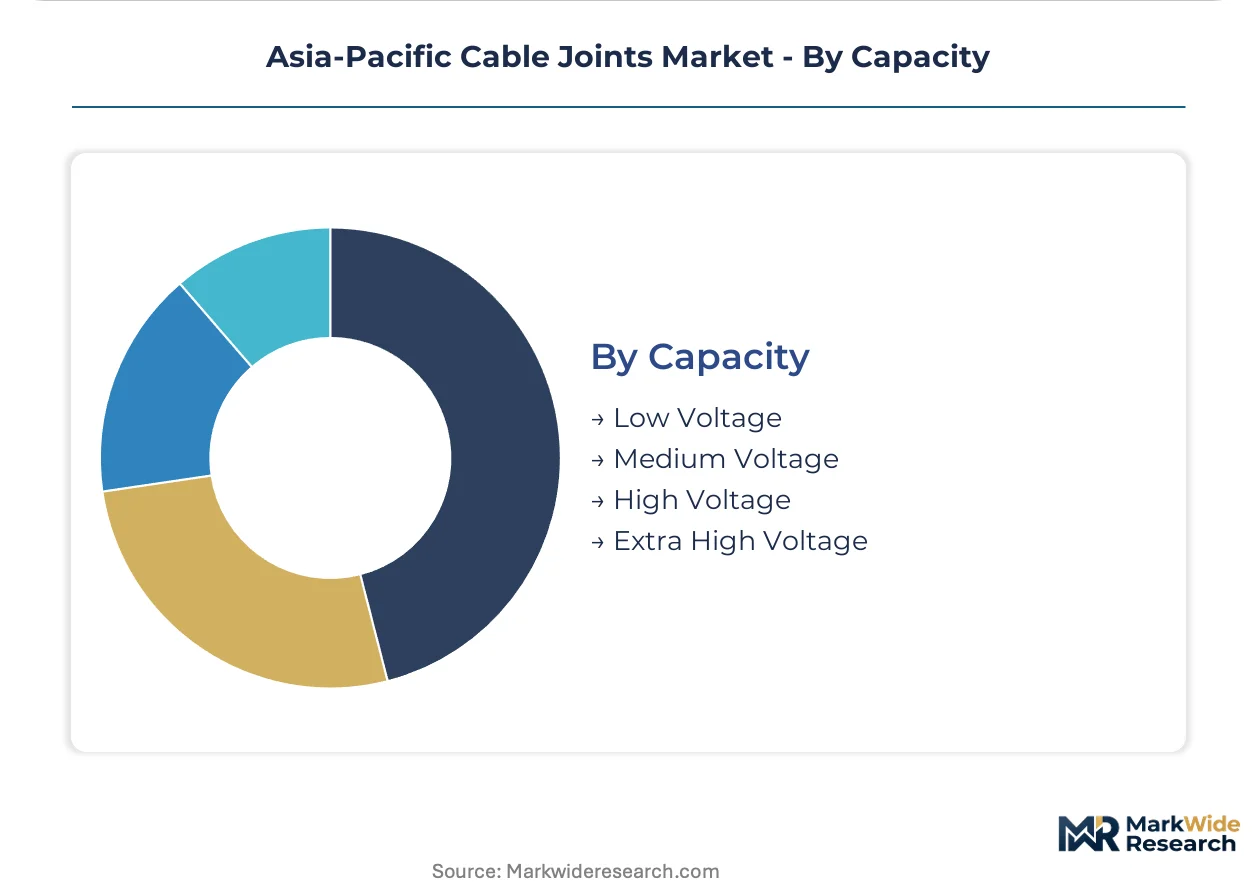
Capacity:
Voltage rating determines insulation thickness, shielding complexity, and regulatory scrutiny intensity across product tiers.
- Medium Voltage:1 kV through 35 kV ratings serve distribution networks and renewable energy collection systems. Chinese offshore wind array cables are concentrating demand in this tier.
- High Voltage:66 kV through 220 kV joints face India's CEA-mandated central utility procurement rules with extended type-test timelines. Maharashtra and Gujarat state utilities are unbundling installation supervision from hardware supply.
- Low Voltage:Sub-1 kV applications dominate unit volume through building wire and appliance connection markets. Margin compression is severe without differentiation through fire-resistance certification to China's GB/T standards.
- Extra High Voltage:330 kV and above ratings require specialized factory facilities and extended qualification protocols. Japan's METI JIS conformity assessment constrains market access to pre-qualified domestic entities.
Medium voltage absorbs the bulk of current deployment activity; extra high voltage is expanding most quickly as inter-regional transmission interconnectors advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates manufacturing scale for cable joint components across its eastern coastal provinces, while consumption spreads across utility modernization programs in India, offshore wind deployment in Japan, and data center buildouts in Singapore and Australia.
China
Offshore wind farm developers in Jiangsu and Fujian provinces are expanding procurement of medium-voltage joints for subsea array cables. SAMR enforcement of GB/T fire-resistance standards is upgrading product certification requirements and filtering marginal suppliers from regional tenders. Manufacturing clusters in Yangtze River Delta cities supply XLPE-insulated joint systems to domestic transmission utilities.
India
State-grid modernization in Maharashtra and Gujarat is accelerating replacement cycles for 66 kV and above infrastructure. CEA-mandated central utility procurement rules constrain vendor qualification through extended type-test timelines. Industrial corridors around Mumbai and Ahmedabad concentrate demand for high-voltage outdoor-rated joints in transmission expansion programs.
Japan
METI-led grid decarbonization roadmaps are elevating technical specifications for aerial transmission refurbishment across Kanto and Kansai regions. JIS C 3605 conformity assessment mandates accelerated aging tests and partial discharge measurement protocols at designated laboratories. Tokyo contractors are adopting silicone rubber cold shrink systems to eliminate hot-work permits in confined underground vaults.
South Korea
KEPCO material qualification protocols govern supplier access to domestic utility procurement channels. Seoul metropolitan underground networks are absorbing cold shrink joint installations fastest to reduce confined-space exposure. Busan-Ulsan industrial zones generate demand for high-availability joint systems in port electrification and heavy manufacturing facilities.
Australia
Hyperscale data center construction in Sydney and Melbourne is creating premium-margin demand for pre-terminated plug-and-play joint assemblies. State-level electrical safety regulators maintain reciprocity frameworks that constrain market access for non-domestic suppliers lacking local certification. Queensland transmission expansion programs are generating procurement volume for outdoor-rated 132 kV joints in tropical humidity conditions.
Asia-Pacific Cable Joints Market Competitive Landscape
The competitive structure tilts toward integrated cable manufacturers with submarine heritage and specialized joint system engineering capabilities. Market participation fragments across three tiers: global diversified electrotechnical conglomerates with full voltage-range portfolios, regional cable specialists leveraging manufacturing scale in domestic utility markets, and niche pre-terminated system providers targeting data center uptime premiums. Dominant competitive moves include vertical integration into polymer compounding for cold shrink formulations and strategic partnerships with offshore wind EPC contractors to secure array cable joint supply positions.
Among European-integrated electrotechnical groups, Nexans S.A. and Prysmian Group occupy positions spanning high-voltage offshore through medium-voltage distribution segments. TE Connectivity Ltd. represents the precision-engineering archetype with factory-terminated system specialization. Japanese industrial conglomerates including Fujikura Ltd., Sumitomo Electric Industries, and Furukawa Electric Co., Ltd. sit within the domestic-preferred supplier tier under METI qualification pathways. South Korea's LS Cable & System exemplifies scale-driven regional competition within KEPCO-governed procurement channels. ABB Ltd. and NKT A/S round out the multinational diversified tier with inter-regional transmission project exposure.
| Leading Market Players |
|---|
| Nexans S.A. |
| Prysmian Group |
| TE Connectivity Ltd. |
| Fujikura Ltd. |
| Sumitomo Electric Industries |
| Furukawa Electric Co., Ltd. |
| LS Cable & System |
| ABB Ltd. |
| NKT A/S |
| Others |
Pricing and Supply Chain Analysis
Central transmission utilities in India and KEPCO-governed procurement channels in South Korea concentrate buyer power sufficiently to enforce contract-based long-term offtake pricing with limited pass-through for base metal volatility. This procurement concentration compresses margin pools for joint manufacturers while elevating technical qualification barriers that filter non-compliant suppliers from tender participation.
Pricing Analysis
Margin tightening in medium-voltage tiers reflects copper and aluminum price volatility in shielding continuity kits without full cost recovery mechanisms in fixed-price utility contracts. Three-tier pricing structure across premium, standard, and economy levels separates pre-terminated data center systems from field-assembled utility grades. Price differentiation hinges on GB/T fire-resistance certification tiers and after-sales service bundling. Indian state-grid procurement officers exhibit highest price sensitivity; hyperscale data center operators in Singapore absorb material premiums for near-zero failure rates.
Supply Chain Analysis
Single-source vulnerability sits with specialized EPDM and silicone rubber formulations concentrated in Northeast Asian chemical clusters feeding cold shrink joint production. Manufacturing capacity clusters in China's Yangtze River Delta and South Korea's Busan-Ulsan corridor anchor regional supply. Raw material dependencies encompass XLPE insulation compounds, metallic shielding tapes, and pre-expanded rubber cores. Tariff exposure on polymer imports from Japan constrains cross-border sourcing flexibility. Distribution runs through authorized distributor networks with KEPCO and CEA-mandated installer certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific cable joints market sits in a technology-transition phase as cold shrink systems displace heat shrink installations across metropolitan underground networks.
For Market Incumbents: Hedge against silicone rubber supply concentration by securing captive polymer compounding capacity or multi-source qualification agreements with Northeast Asian chemical suppliers. Accelerate GB/T fire-resistance certification investment ahead of SAMR enforcement tightening to defend position in Chinese utility tenders. Prioritize backward integration into EPDM formulation to offset raw material cost volatility. For New Entrants and Emerging Players: Enter via Vietnam, Thailand, and Indonesia transmission expansion programs where qualified 132 kV joint vendors remain undersupplied relative to grid buildout schedules. Target pre-terminated system segments in Singapore and Sydney hyperscale data center construction where downtime cost calculus justifies premium positioning. Pursue KEPCO material qualification reciprocity pathways as South Korea evolves mutual recognition frameworks for regional suppliers. For Investors and Strategic Acquirers: The window for entry favors cold shrink technology specialists with proprietary silicone rubber formulation IP and established METI laboratory relationships. Long-term viability centers on manufacturers capable of spanning medium-voltage offshore wind through extra high voltage interconnector segments. Watch JIS C 3605 conformity assessment timeline extensions as inflection indicator for import-dependent supplier consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive EPDM/silicone supply secures margin control against Northeast Asian chemical cluster volatility. |
| GB/T Fire-Resistance Certification Investment | SAMR enforcement tightening filters non-compliant competitors from Chinese state-grid procurement channels. |
| Pre-Terminated System Product Line Expansion | Hyperscale data center demand in Singapore and Sydney commands material premiums for near-zero failure rates. |
| KEPCO Material Qualification Pursuit | South Korean reciprocity frameworks streamline cross-border certification for qualified regional suppliers. |
| Offshore Wind EPC Partnership Formation | Array cable joint supply positions in Chinese and Japanese waters secure medium-voltage volume commitments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with utility procurement officers, cable accessory plant managers, EPC contractors, and electrical safety regulator technical staff. SAMR GB/T standard documentation, CEA central utility procurement circulars, and METI JIS conformity assessment protocols provided regulatory validation. Bottom-up volume modeling across voltage tiers and installation methods triangulated against top-down macroeconomic indicators.
Granularity-level modeling deployed separate forecast frameworks for heat shrink, cold shrink, pre-terminated, and insulating product categories across indoor, outdoor, underground, and aerial installation environments. Segmentation dimensions included voltage capacity tiers, end-use sectors spanning power utilities through renewable energy developers, and country-level regulatory clusters. CAGRs derived from weighted average of historical replacement cycle compression rates and projected offshore wind deployment pipelines. Industry-specific inputs encompassed XLPE cable installation volumes and METI grid decarbonization roadmap transmission refurbishment schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price volatility spikes and JIS laboratory capacity constraints extending type-test timelines. Forecasts reflect documented assumptions regarding CEA procurement rule stability and KEPCO qualification reciprocity evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Fiber Optic Cable Accessories Market
Cables
Audio and Video Cables Market
Cables
Smartphone Type-C Charging and Data Cable Market
Cables
LED Cable Market
Cables
Multicore Cables Market
Cables
Power and Control Cable Market
Cables
US Medium Voltage Cable Accessories Market
Cables
Twisted Pair Cable Market
Cables
Submarine Cable System Market
Cables
Water Leak Sensing Cable Market
Cables
Europe Cable Accessories Market
Cables
North America Wire and Cable Market
Cables
Premise Cable Market
Cables
Solar Cable Market
Cables
Submarine Cables Market
Cables
LASER Light Cables Market